
Next Page Types of Cost Behavior Patterns Click
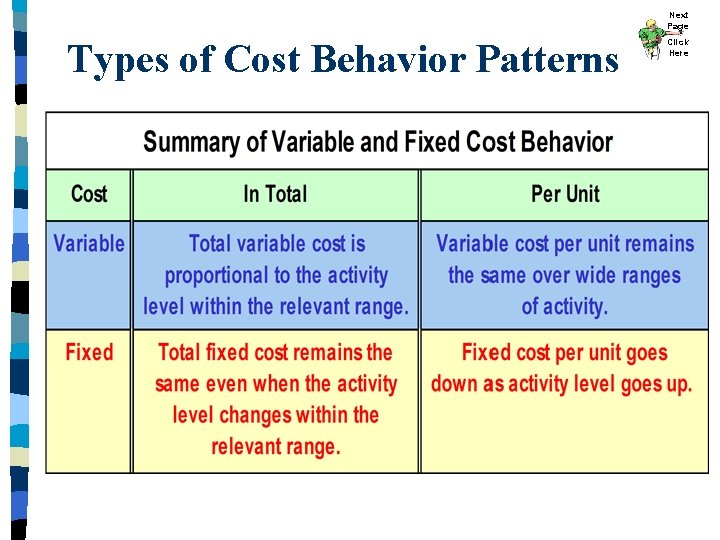
Next Page Types of Cost Behavior Patterns Click Here
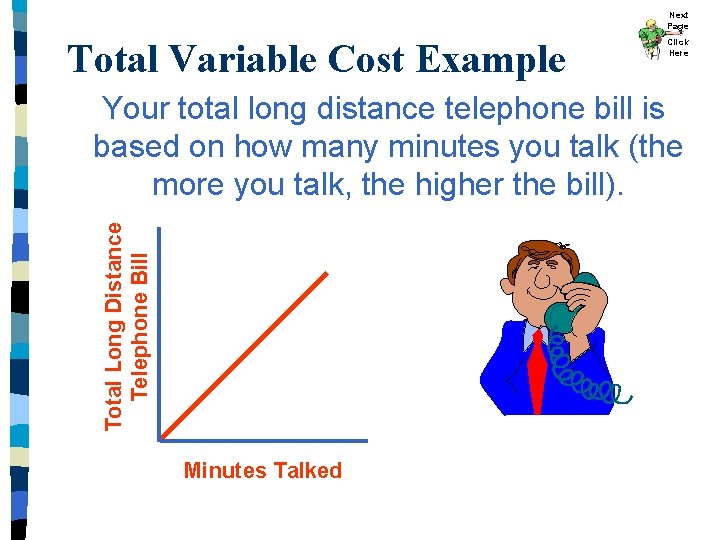
Next Page Total Variable Cost Example Click Here Total Long Distance Telephone Bill Your total long distance telephone bill is based on how many minutes you talk (the more you talk, the higher the bill). Minutes Talked
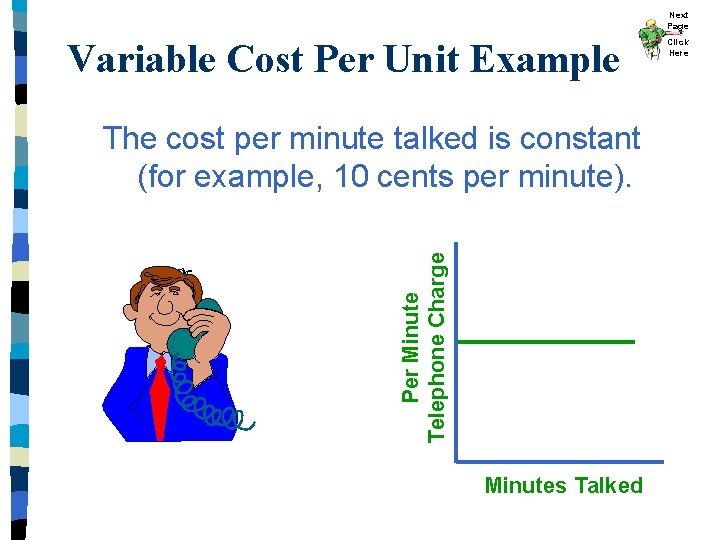
Next Page Variable Cost Per Unit Example Per Minute Telephone Charge The cost per minute talked is constant (for example, 10 cents per minute). Minutes Talked Click Here
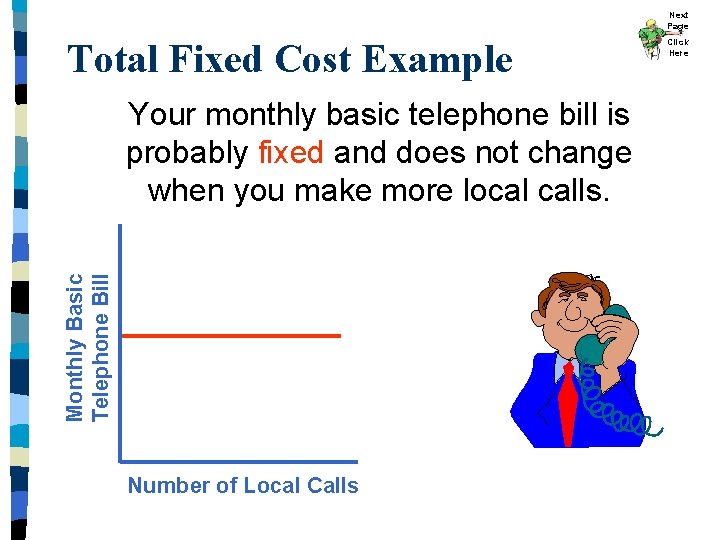
Next Page Total Fixed Cost Example Monthly Basic Telephone Bill Your monthly basic telephone bill is probably fixed and does not change when you make more local calls. Number of Local Calls Click Here
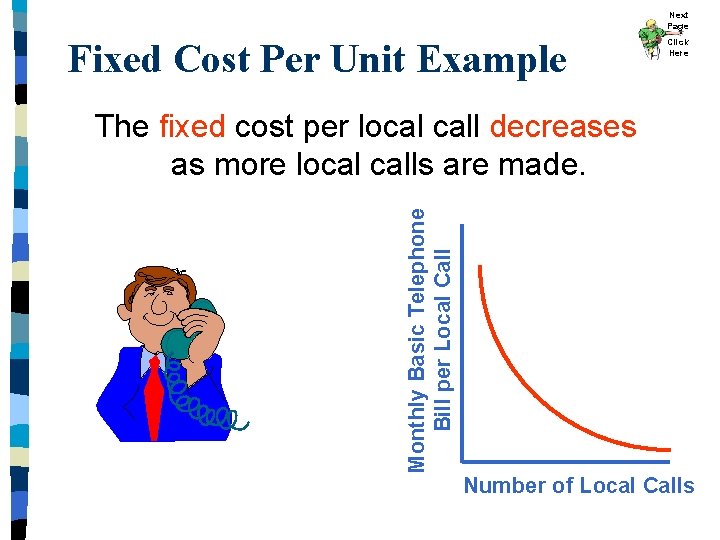
Next Page Fixed Cost Per Unit Example Click Here Monthly Basic Telephone Bill per Local Call The fixed cost per local call decreases as more local calls are made. Number of Local Calls
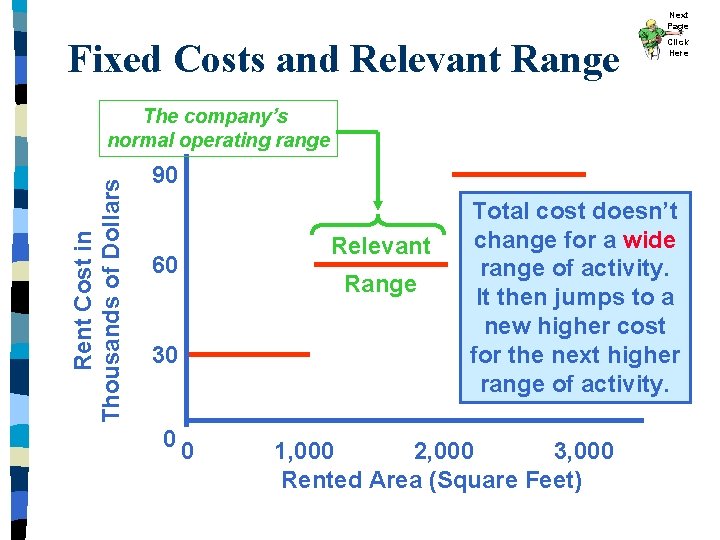
Next Page Fixed Costs and Relevant Range Click Here Rent Cost in Thousands of Dollars The company’s normal operating range 90 60 30 00 Relevant Range Total cost doesn’t change for a wide range of activity. It then jumps to a new higher cost for the next higher range of activity. 1, 000 2, 000 3, 000 Rented Area (Square Feet)
Fixed Costs and Step-Variable (or Step-Wise) Costs How does this type of fixed cost differ from a step-variable (or stepwise) cost? Next Page Click Here Step-variable (or step-wise) costs can be adjusted more quickly and. . . The width of the activity steps is much wider for the fixed cost.

Next Page Step-Variable (or Step-Wise) Costs Click Here Cost Total cost increases to a new higher cost for the next higher range of activity. Total cost remains constant within a narrow range of activity. Activity
Next Page Mixed Costs Click Here A mixed cost has both fixed and variable components. Consider the following electric utility example.
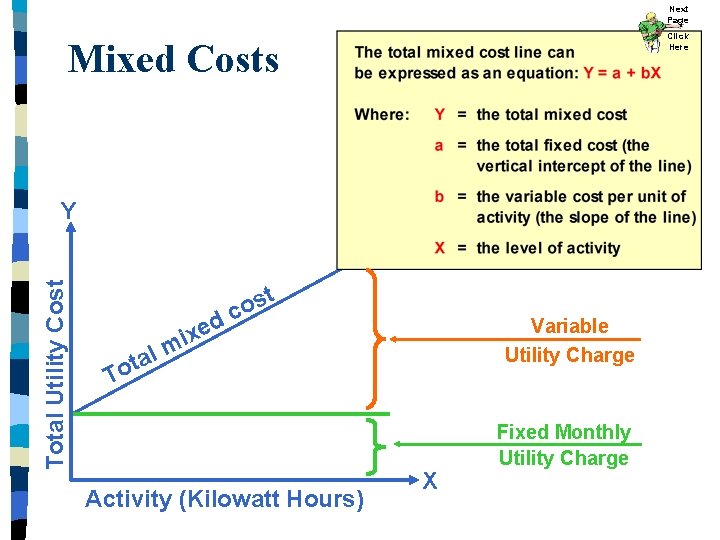
Next Page Click Here Mixed Costs Total Utility Cost Y t T l a t o d e x mi s co Activity (Kilowatt Hours) Variable Utility Charge X Fixed Monthly Utility Charge
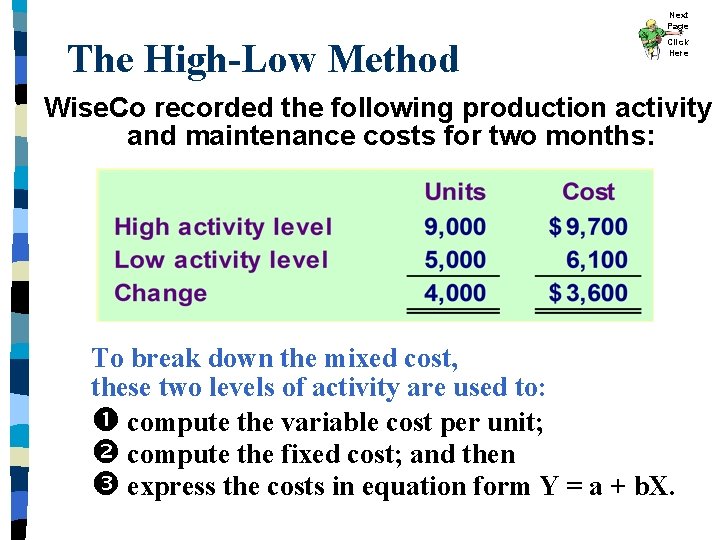
Next Page The High-Low Method Click Here Wise. Co recorded the following production activity and maintenance costs for two months: To break down the mixed cost, these two levels of activity are used to: compute the variable cost per unit; compute the fixed cost; and then express the costs in equation form Y = a + b. X.
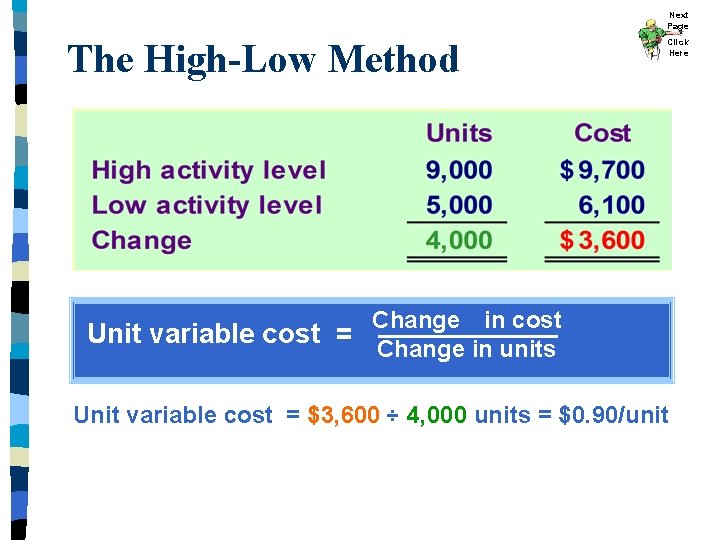
Next Page The High-Low Method Unit variable cost = Click Here Change in cost Change in units Unit variable cost = $3, 600 ÷ 4, 000 units = $0. 90/unit
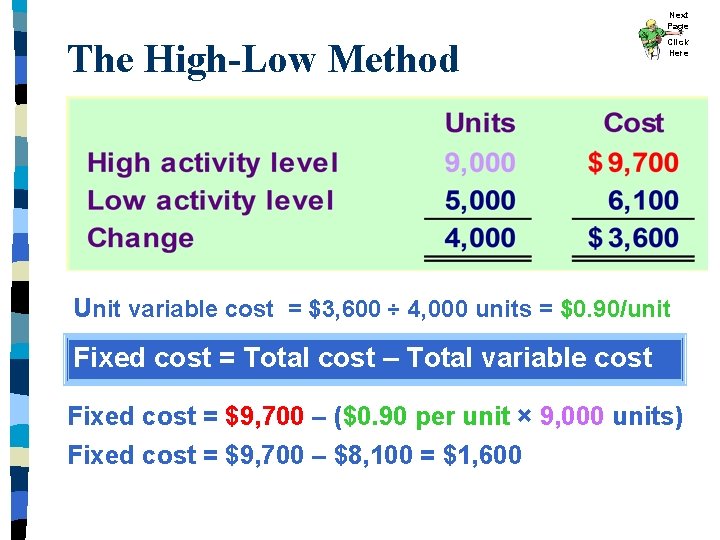
Next Page The High-Low Method Click Here Unit variable cost = $3, 600 ÷ 4, 000 units = $0. 90/unit Fixed cost = Total cost – Total variable cost Fixed cost = $9, 700 – ($0. 90 per unit × 9, 000 units) Fixed cost = $9, 700 – $8, 100 = $1, 600
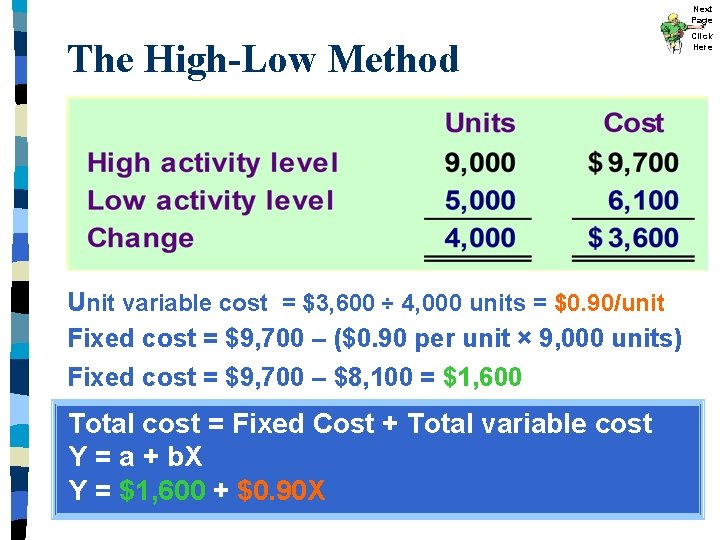
Next Page The High-Low Method Unit variable cost = $3, 600 ÷ 4, 000 units = $0. 90/unit Fixed cost = $9, 700 – ($0. 90 per unit × 9, 000 units) Fixed cost = $9, 700 – $8, 100 = $1, 600 Total cost = Fixed Cost + Total variable cost Y = a + b. X Y = $1, 600 + $0. 90 X Click Here
- Slides: 14