
New Russian CFC Rules and Cyprus Structures New


- Slides: 32
New Russian CFC Rules and Cyprus Structures
New Major RF Tax Rules q. Definition of Beneficiary for Application of DDT relief; q. New Rules on Russian Tax residency; q. New CFC Rules: taxation of undistributed profits of foreign companies/structures; q. Reporting Obligations of RF tax residents; q. Liability for failure to comply with new rules; q. History of CFC Rules; q. Taxation of sale of “real estate rich” companies; q. New reporting obligations of foreign companies and structures directly owning real estate in Russia.
Beneficiary (1) (p. 2 art. 7 and art. 312 RF Tax Code) Art. 7 RF Tax Code: new criteria for application of tax relief under relevant DTAs and treatment of qualifying beneficiary, i. e. the person who has the actual right for the relevant distributed proceeds (beneficiary). Qualifying Beneficiary ü is entitled to use independently and/or dispose proceeds by virtue of direct/indirect participation in a payercompany or by virtue of controlling of such payercompany or by virtue of other circumstances of control of the payer-company, ü or another person in whose interest the recipient of the proceeds can dispose of such proceeds.
Beneficiary (2) (p. 2 art. 7 and art. 312 RF Tax Code) Tax reliefs provided by the DTAs shall not apply if a foreign person is not considered to be a beneficiary of relevant proceeds. Non-qualifying beneficiary ü has limited powers in relation to disposing of income, ü exercises intermediate functions in the interest of the other person without exercising any other functions and undertaking any other risks, ü directly/indirectly pays such income (fully or in part) to such other person who would not have been entitled to applying such reliefs under the DTA if such income was received by the latter directly from sources in RF. Art. 312 para 1 RF Tax Code “Special Provisions” was amended to include the right of the Russian withholding agent to request from the foreign recipient of the proceeds confirmation that such foreign recipient has the actual right for relevant proceeds (beneficiary confirmation).
Russian Tax Residency (1) (art. 246. 2 RF Tax Code) A foreign company may be recognized as RF tax resident and treated equally to Russian companies for corporate profit tax purposes if Russia is place of its actual management, i. e. : § § § most of Board of directors’ meetings (or meetings of any other similar body, except for an executive body) are conducted in Russia, or executive bodies of the company regularly carry out it’s activities in RF, or CEOs of a foreign company primarily perform their functions in Russia §The foreign company can also be recognized RF tax resident if accounting (financial or management) or record keeping or operative staff management is carried out in Russia.
Russian Tax Residency (2) (art. 246. 2 RF Tax Code) A foreign company may voluntarily choose to be treated as RF tax resident if one of the following conditions is met: Ø foreign company has a permanent location in a country with which Russia has DTA, and is tax resident of a foreign country under provisions of DTA; Ø foreign companies participate in projects under production share, concession, license, service agreements or other similar agreements; Ø foreign company whose shareholder is a Russian controlling person holding share at least 50% during 365 calendar days if meets conditions specified in para 3 p. 6 art. 246. 2 RF Tax Code; Ø foreign company operates a new subsea field of petroleum commodities or is a shareholder of such company.
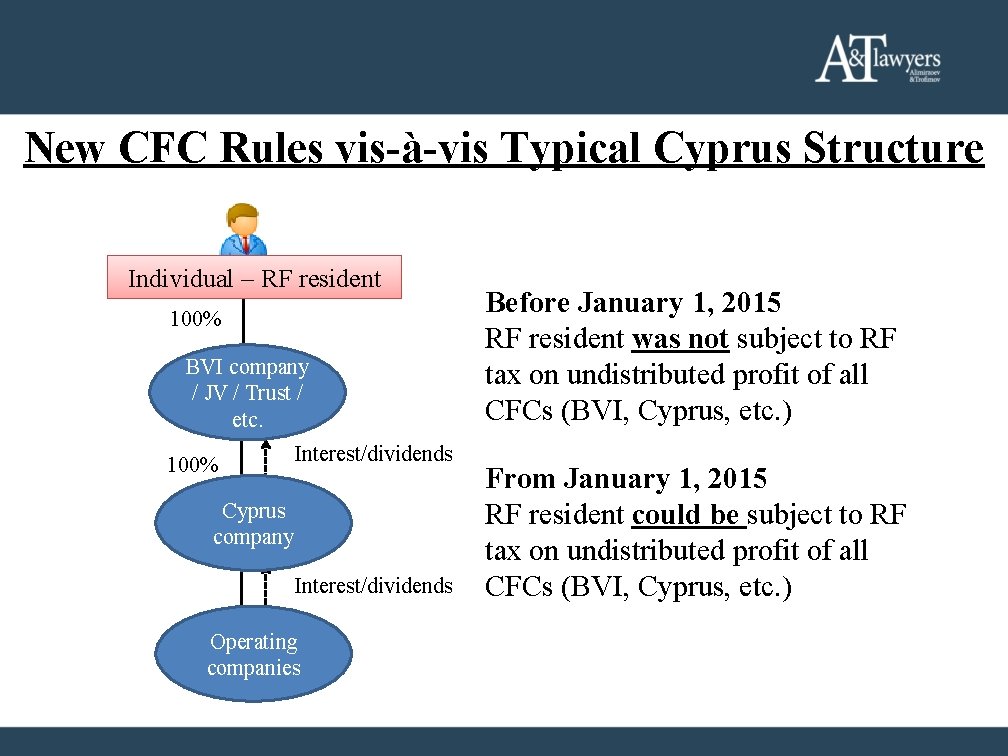
New CFC Rules vis-à-vis Typical Cyprus Structure Individual – RF resident 100% BVI company / JV / Trust / etc. 100% Interest/dividends Cyprus company Interest/dividends Operating companies Before January 1, 2015 RF resident was not subject to RF tax on undistributed profit of all CFCs (BVI, Cyprus, etc. ) From January 1, 2015 RF resident could be subject to RF tax on undistributed profit of all CFCs (BVI, Cyprus, etc. )
Main Tests and Criteria for Treatment of Structure as CFC
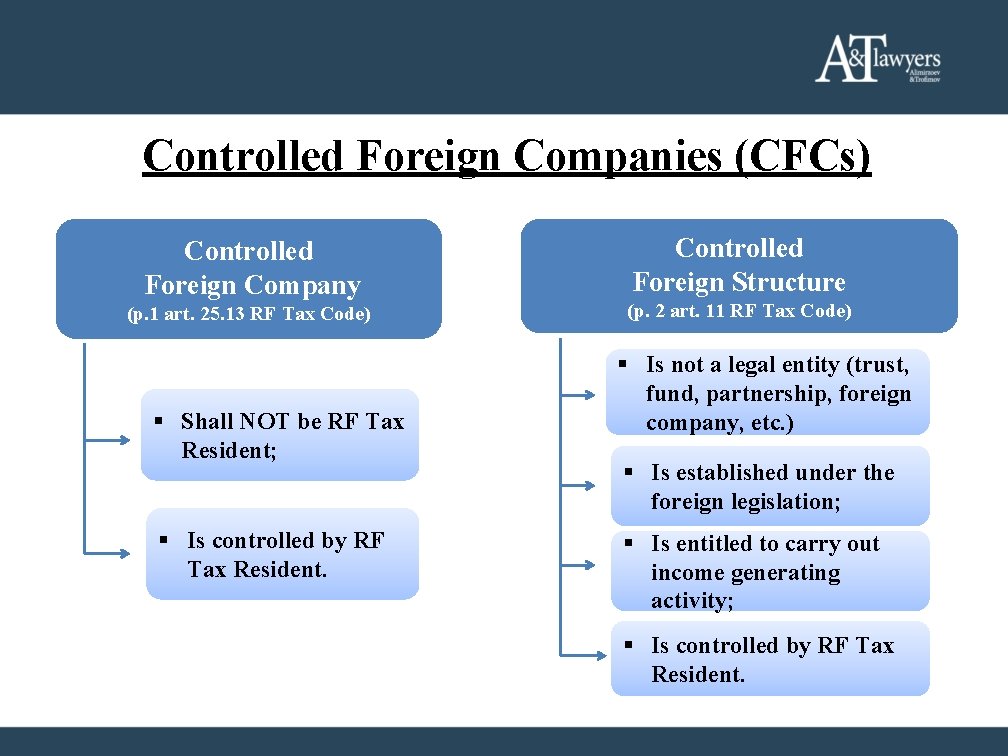
Controlled Foreign Companies (CFCs) Controlled Foreign Company (p. 1 art. 25. 13 RF Tax Code) § Shall NOT be RF Tax Resident; § Is controlled by RF Tax Resident. Controlled Foreign Structure (p. 2 art. 11 RF Tax Code) § Is not a legal entity (trust, fund, partnership, foreign company, etc. ) § Is established under the foreign legislation; § Is entitled to carry out income generating activity; § Is controlled by RF Tax Resident.
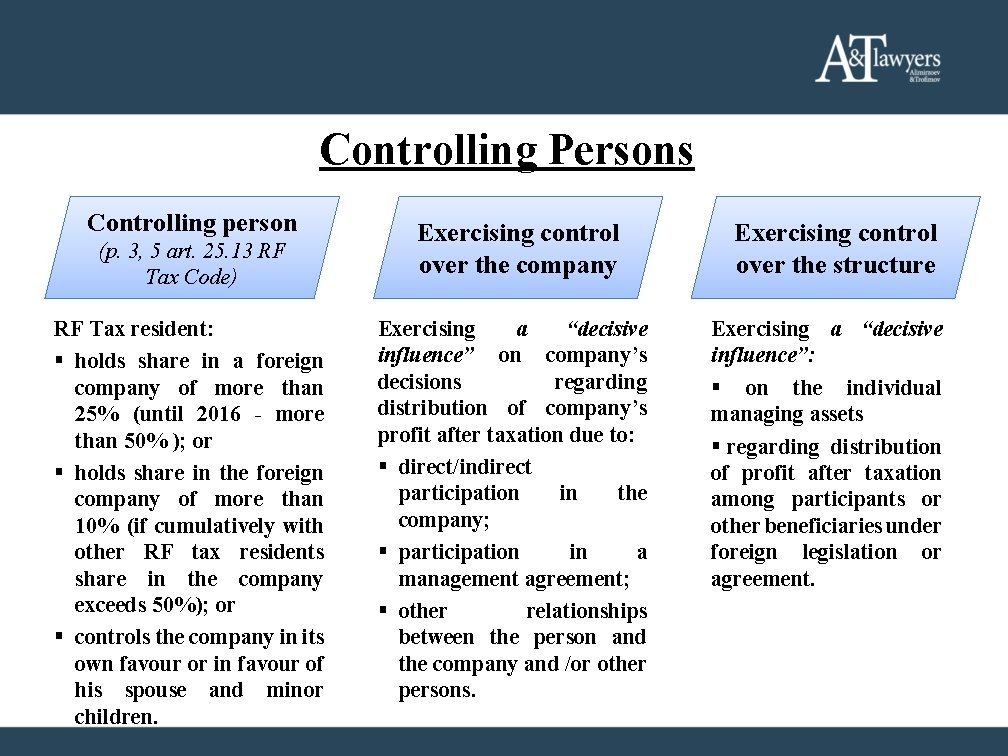
Controlling Persons Controlling person (p. 3, 5 art. 25. 13 RF Tax Code) RF Tax resident: § holds share in a foreign company of more than 25% (until 2016 - more than 50% ); or § holds share in the foreign company of more than 10% (if cumulatively with other RF tax residents share in the company exceeds 50%); or § controls the company in its own favour or in favour of his spouse and minor children. Exercising control over the company Exercising a “decisive influence” on company’s decisions regarding distribution of company’s profit after taxation due to: § direct/indirect participation in the company; § participation in a management agreement; § other relationships between the person and the company and /or other persons. Exercising control over the structure Exercising a “decisive influence”: § on the individual managing assets § regarding distribution of profit after taxation among participants or other beneficiaries under foreign legislation or agreement.
Exempted Foreign Companies’ Income from CFC Taxation
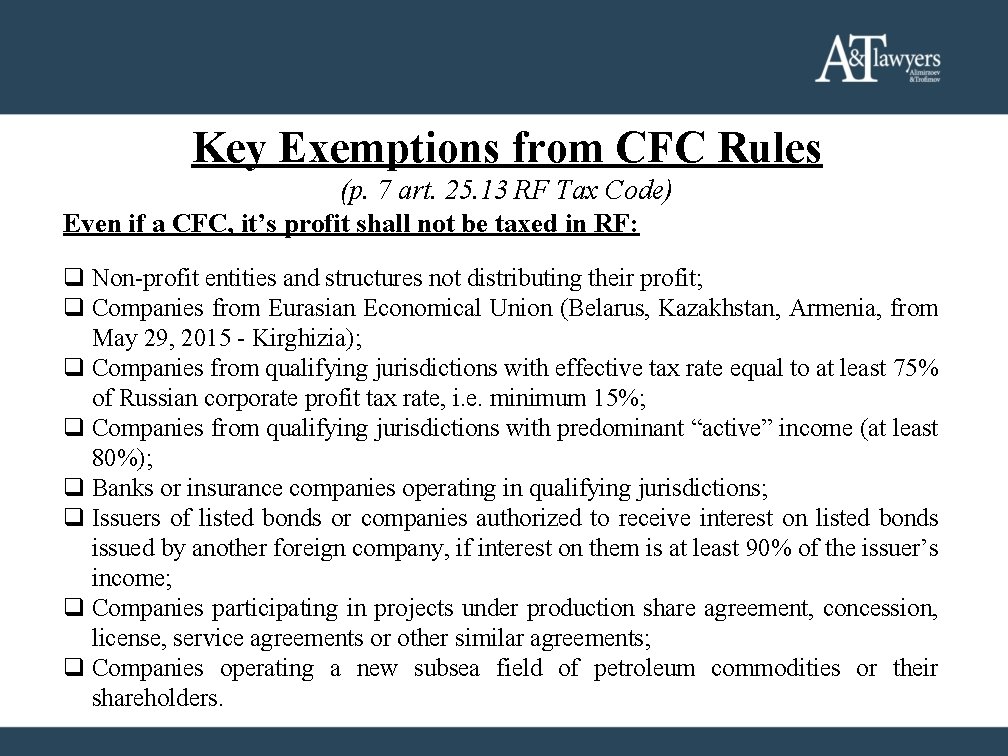
Key Exemptions from CFC Rules (p. 7 art. 25. 13 RF Tax Code) Even if a CFC, it’s profit shall not be taxed in RF: q Non-profit entities and structures not distributing their profit; q Companies from Eurasian Economical Union (Belarus, Kazakhstan, Armenia, from May 29, 2015 - Kirghizia); q Companies from qualifying jurisdictions with effective tax rate equal to at least 75% of Russian corporate profit tax rate, i. e. minimum 15%; q Companies from qualifying jurisdictions with predominant “active” income (at least 80%); q Banks or insurance companies operating in qualifying jurisdictions; q Issuers of listed bonds or companies authorized to receive interest on listed bonds issued by another foreign company, if interest on them is at least 90% of the issuer’s income; q Companies participating in projects under production share agreement, concession, license, service agreements or other similar agreements; q Companies operating a new subsea field of petroleum commodities or their shareholders.
Whether Cyprus International Trusts Would Qualify as CFCs
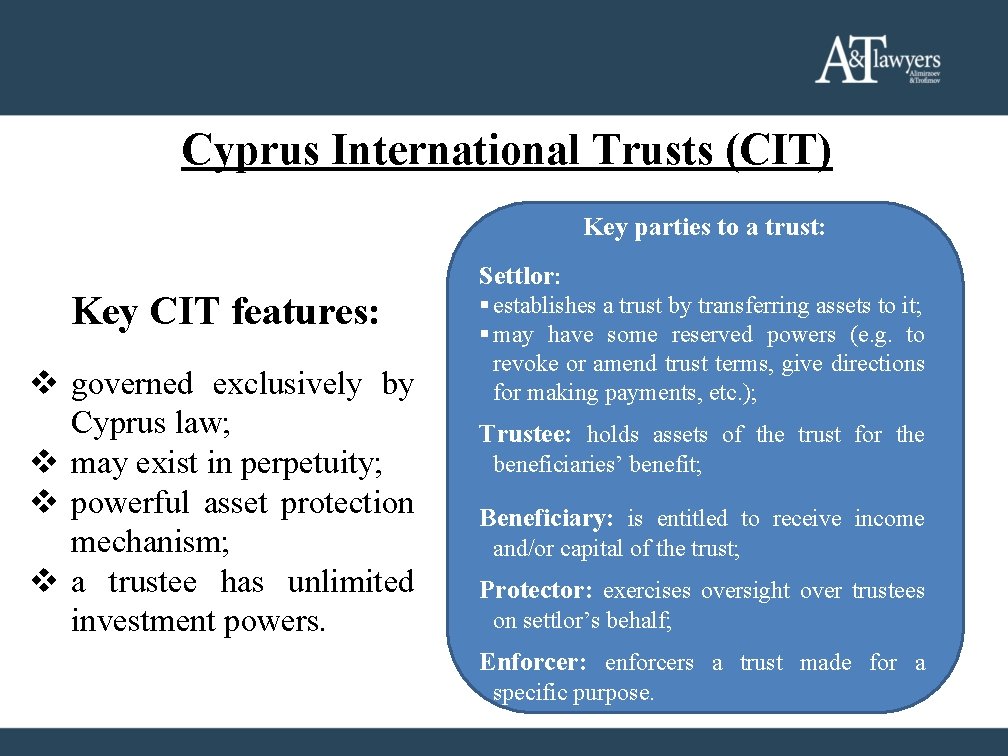
Cyprus International Trusts (CIT) Key parties to a trust: Key CIT features: v governed exclusively by Cyprus law; v may exist in perpetuity; v powerful asset protection mechanism; v a trustee has unlimited investment powers. Settlor: § establishes a trust by transferring assets to it; § may have some reserved powers (e. g. to revoke or amend trust terms, give directions for making payments, etc. ); Trustee: holds assets of the trust for the beneficiaries’ benefit; Beneficiary: is entitled to receive income and/or capital of the trust; Protector: exercises oversight over trustees on settlor’s behalf; Enforcer: enforcers a trust made for a specific purpose.
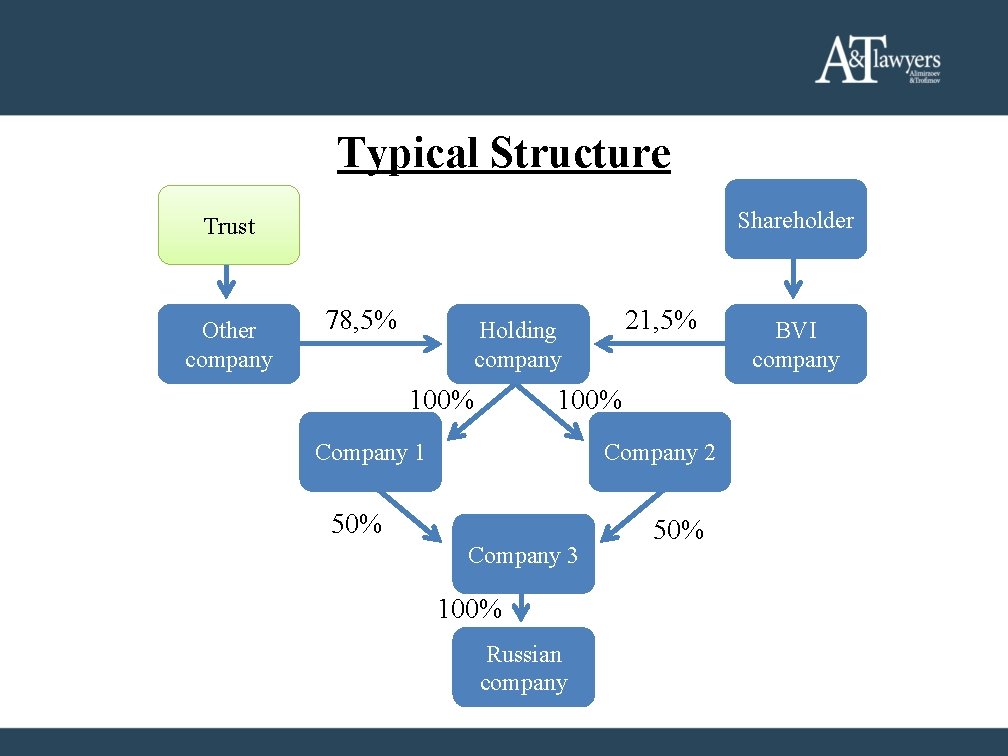
Typical Structure Shareholder Trust Other company 78, 5% 21, 5% Holding company 100% Company 1 Company 2 50% Company 3 100% Russian company 50% BVI company
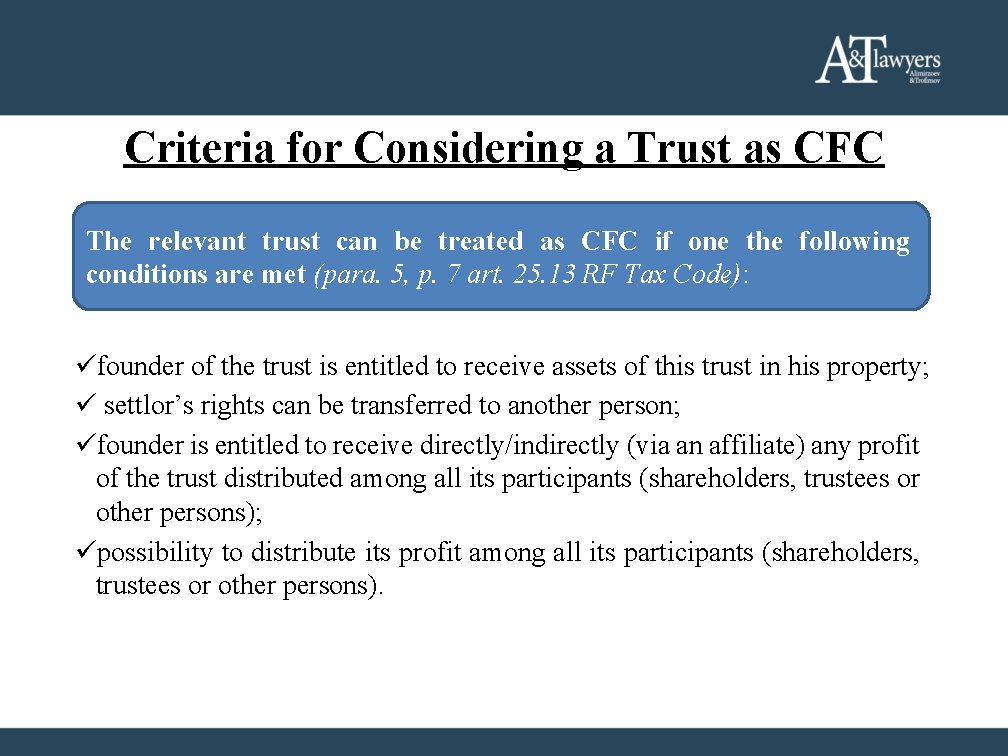
Criteria for Considering a Trust as CFC The relevant trust can be treated as CFC if one the following conditions are met (para. 5, p. 7 art. 25. 13 RF Tax Code): üfounder of the trust is entitled to receive assets of this trust in his property; ü settlor’s rights can be transferred to another person; üfounder is entitled to receive directly/indirectly (via an affiliate) any profit of the trust distributed among all its participants (shareholders, trustees or other persons); üpossibility to distribute its profit among all its participants (shareholders, trustees or other persons).
Use of Foundations, Investment Funds, Insurance Wrappers
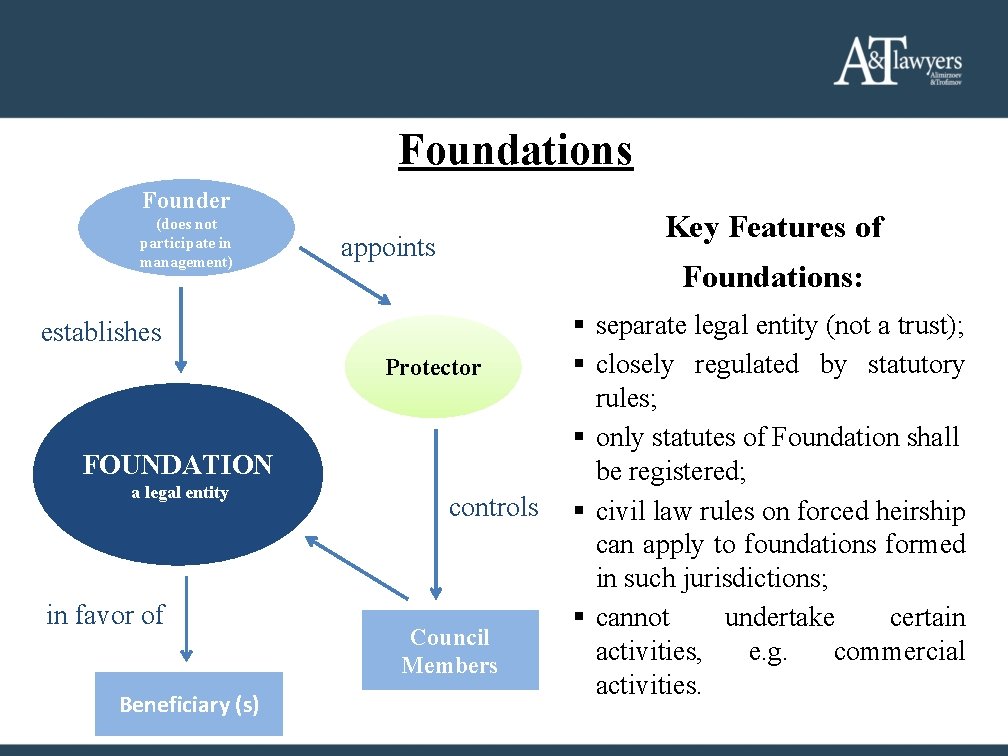
Foundations Founder (does not participate in management) Key Features of appoints Foundations: establishes Protector FOUNDATION a legal entity in favor of Beneficiary (s) controls Council Members § separate legal entity (not a trust); § closely regulated by statutory rules; § only statutes of Foundation shall be registered; § civil law rules on forced heirship can apply to foundations formed in such jurisdictions; § cannot undertake certain activities, e. g. commercial activities.
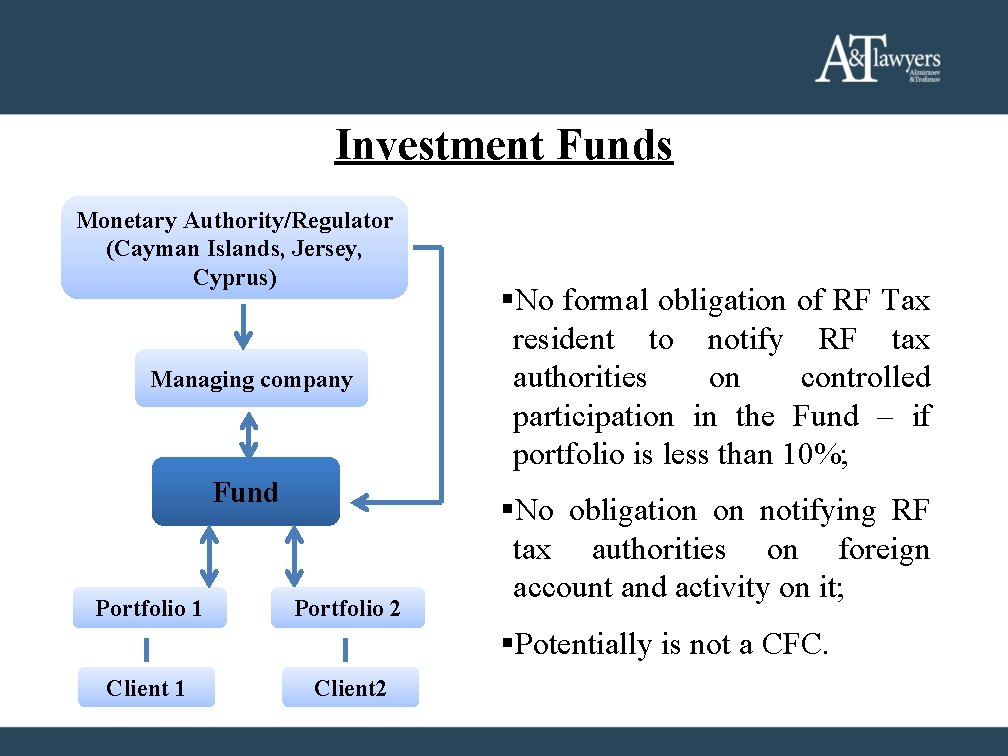
Investment Funds Monetary Authority/Regulator (Cayman Islands, Jersey, Cyprus) Managing company Fund Portfolio 1 Portfolio 2 §No formal obligation of RF Tax resident to notify RF tax authorities on controlled participation in the Fund – if portfolio is less than 10%; §No obligation on notifying RF tax authorities on foreign account and activity on it; §Potentially is not a CFC. Client 1 Client 2
Insurance Wrappers (1) Policy holder (non-Russian person/entity) nominates Life policy Life insurance company SPV Beneficiary (non. Russian person/entity) Life assured person (RF tax resident) appoints Investment Manager manages assets
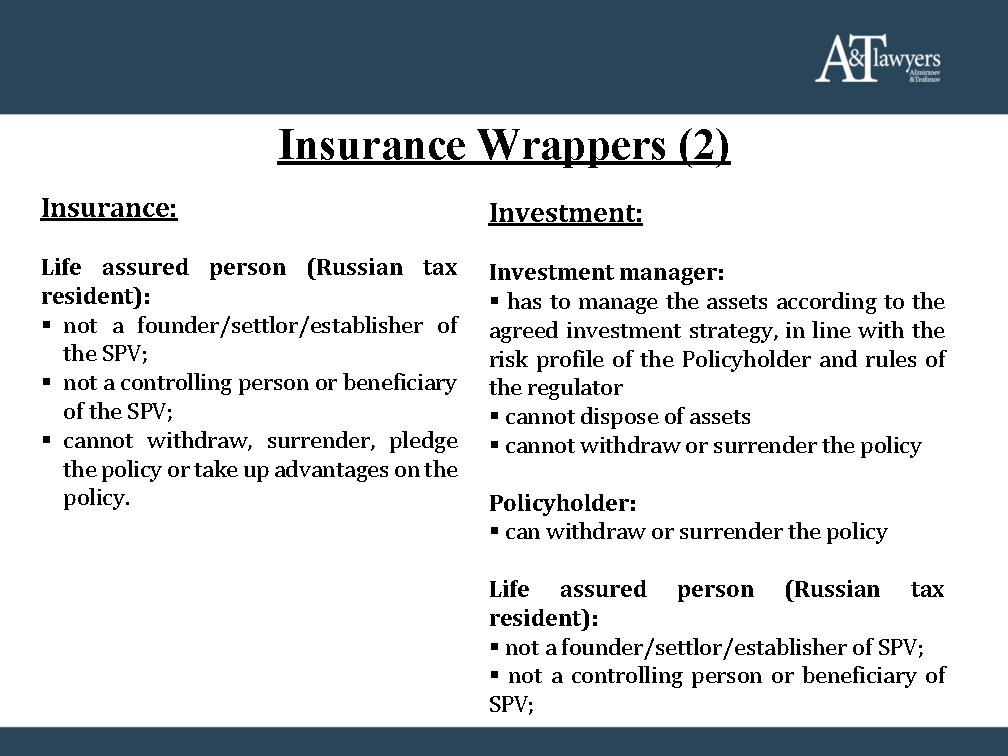
Insurance Wrappers (2) Insurance: Investment: Life assured person (Russian tax resident): § not a founder/settlor/establisher of the SPV; § not a controlling person or beneficiary of the SPV; § cannot withdraw, surrender, pledge the policy or take up advantages on the policy. Investment manager: § has to manage the assets according to the agreed investment strategy, in line with the risk profile of the Policyholder and rules of the regulator § cannot dispose of assets § cannot withdraw or surrender the policy Policyholder: § can withdraw or surrender the policy Life assured person (Russian tax resident): § not a founder/settlor/establisher of SPV; § not a controlling person or beneficiary of SPV;
Reporting Obligations of Controlling Person on CFC
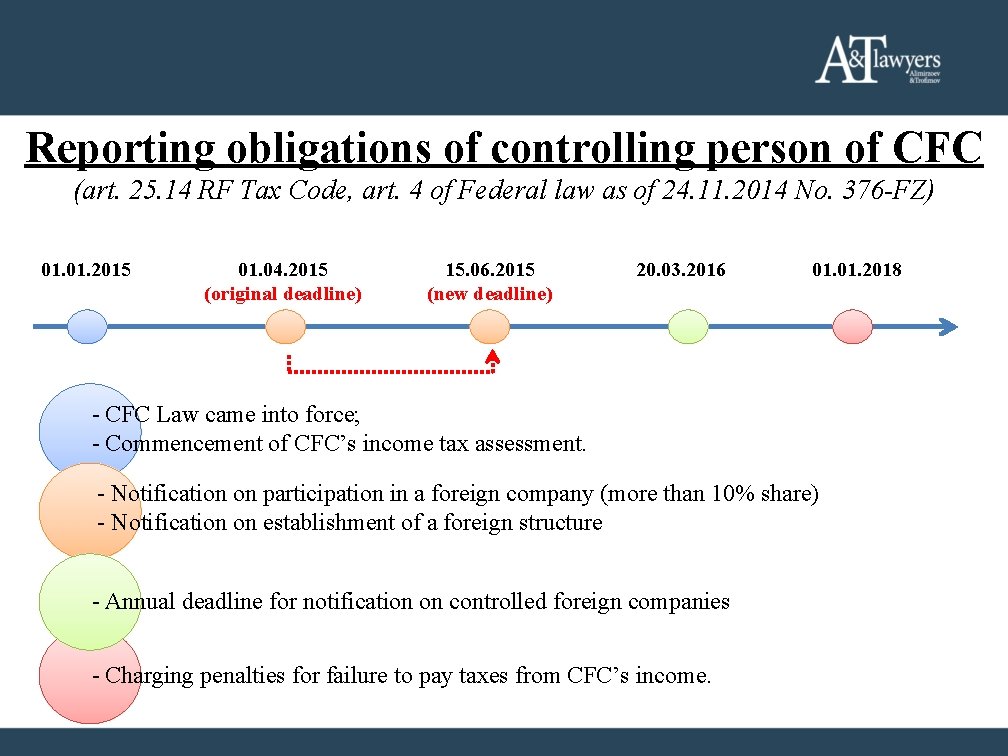
Reporting obligations of controlling person of CFC (art. 25. 14 RF Tax Code, art. 4 of Federal law as of 24. 11. 2014 No. 376 -FZ) 01. 2015 01. 04. 2015 (original deadline) 15. 06. 2015 (new deadline) 20. 03. 2016 01. 2018 - СFC Law came into force; - Commencement of CFC’s income tax assessment. - Notification on participation in a foreign company (more than 10% share) - Notification on establishment of a foreign structure - Annual deadline for notification on controlled foreign companies - Charging penalties for failure to pay taxes from CFC’s income.
Risks and Liabilities for Non-disclosure and Non-payment of CFC Tax
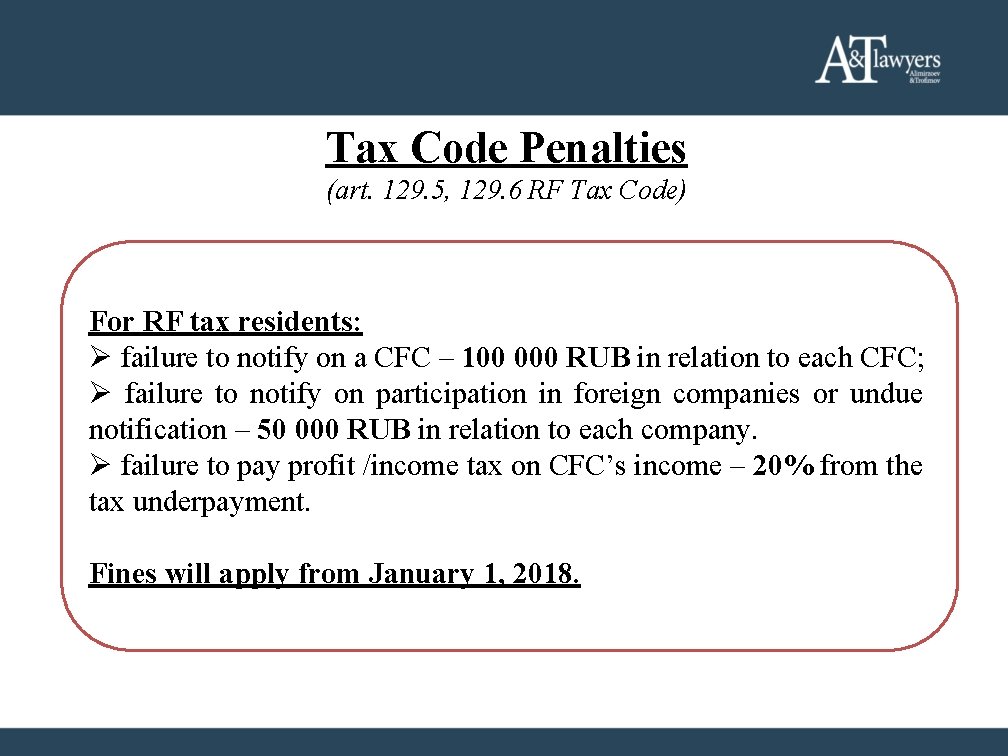
Tax Code Penalties (art. 129. 5, 129. 6 RF Tax Code) For RF tax residents: Ø failure to notify on a CFC – 100 000 RUB in relation to each CFC; Ø failure to notify on participation in foreign companies or undue notification – 50 000 RUB in relation to each company. Ø failure to pay profit /income tax on CFC’s income – 20% from the tax underpayment. Fines will apply from January 1, 2018.
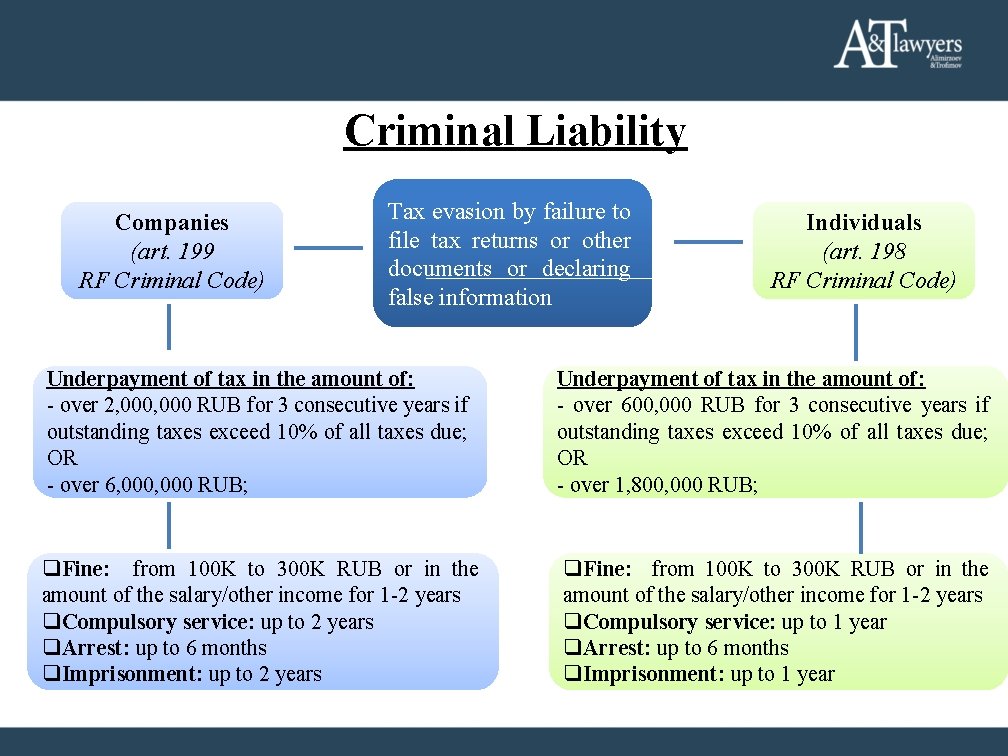
Criminal Liability Companies (art. 199 RF Criminal Code) Tax evasion by failure to file tax returns or other documents or declaring false information Individuals (art. 198 RF Criminal Code) Underpayment of tax in the amount of: - over 2, 000 RUB for 3 consecutive years if outstanding taxes exceed 10% of all taxes due; OR - over 6, 000 RUB; Underpayment of tax in the amount of: - over 600, 000 RUB for 3 consecutive years if outstanding taxes exceed 10% of all taxes due; OR - over 1, 800, 000 RUB; q. Fine: from 100 K to 300 K RUB or in the amount of the salary/other income for 1 -2 years q. Compulsory service: up to 2 years q. Arrest: up to 6 months q. Imprisonment: up to 2 years q. Fine: from 100 K to 300 K RUB or in the amount of the salary/other income for 1 -2 years q. Compulsory service: up to 1 year q. Arrest: up to 6 months q. Imprisonment: up to 1 year
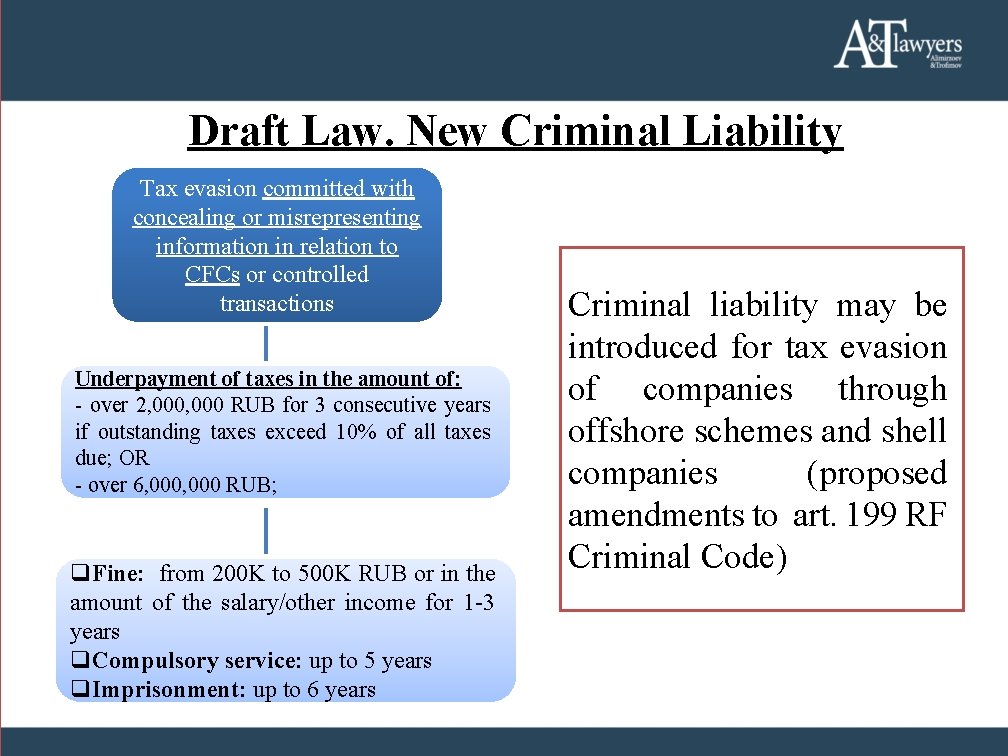
Draft Law. New Criminal Liability Tax evasion committed with concealing or misrepresenting information in relation to CFCs or controlled transactions Underpayment of taxes in the amount of: - over 2, 000 RUB for 3 consecutive years if outstanding taxes exceed 10% of all taxes due; OR - over 6, 000 RUB; q. Fine: from 200 K to 500 K RUB or in the amount of the salary/other income for 1 -3 years q. Compulsory service: up to 5 years q. Imprisonment: up to 6 years Criminal liability may be introduced for tax evasion of companies through offshore schemes and shell companies (proposed amendments to art. 199 RF Criminal Code)
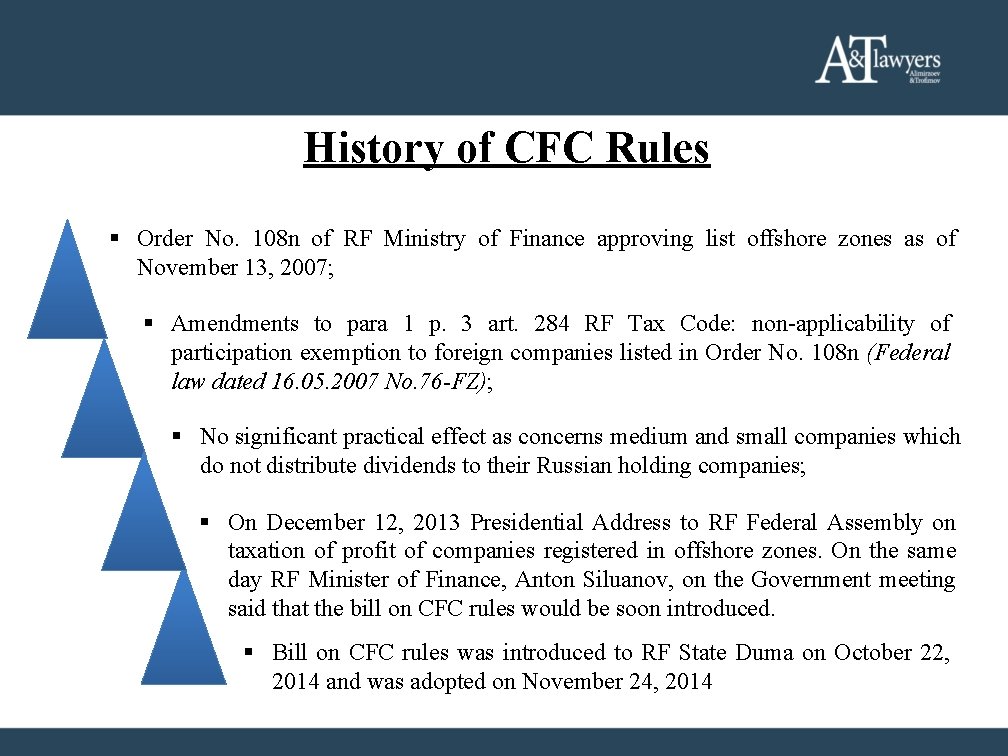
History of CFC Rules § Order No. 108 n of RF Ministry of Finance approving list offshore zones as of November 13, 2007; § Amendments to para 1 p. 3 art. 284 RF Tax Code: non-applicability of participation exemption to foreign companies listed in Order No. 108 n (Federal law dated 16. 05. 2007 No. 76 -FZ); § No significant practical effect as concerns medium and small companies which do not distribute dividends to their Russian holding companies; § On December 12, 2013 Presidential Address to RF Federal Assembly on taxation of profit of companies registered in offshore zones. On the same day RF Minister of Finance, Anton Siluanov, on the Government meeting said that the bill on CFC rules would be soon introduced. § Bill on CFC rules was introduced to RF State Duma on October 22, 2014 and was adopted on November 24, 2014
Real Estate Rich companies (1) q New provisions on taxation of sale shares in “real estate rich” companies; q As of January 1, 2015 amended version of para 5. p. 1 art 309 RF Tax Code: ü “Real Estate Rich” Company – any company in any jurisdiction more than 50% assets of which directly or indirectly consists of real estate in Russia; before only Russian companies were mentioned; ü Taxable Base: Proceeds from sale of shares (participations) or derivative financial instruments in qualifying “Real Estate Rich Companies”; ü Exceptions: shares in listed real estate companies; Specific exclusion from Tax Code of withholding agent’s obligation upon payment of proceeds from the sale of shares in “real estate rich” companies (p. 1. 1. art. 309 RF Tax Code);
Real Estate Rich companies (2) As of January 1, 2015 the Seller of shares in “real estate rich” company shall be responsible for payment of Russian tax: ü Tax rate: for non-resident legal entities – 20%, for non-resident individuals – 30% (p. 2 art. 284, p. 3 art. 224 RF Tax Code); ü Enforcement procedures: for legal entities - seizure of funds in the accounts in RF, for individuals – seizure of property under the court decision, including funds in the account and cash; Tax authority is entitled to apply provisional measures, ex: prohibition to sell (pledge) property without its consent or suspension of operations on bank accounts (p. 1 art. 46, p. 1 art. 48, p. 10 art. 101 RF Tax Code); ü Consequences for non-payment of Russian tax: fine from 20 to 40% from outstanding tax amount, late penalty (art. 75, p. 1, 3 art. 122 RF Tax Code).
Reporting on UBOs of Foreign Companies Owning Russian Real Estate v v Who is required to report: a foreign company (structure) directly owning Real Estate in RF including rep-offices (p. 3. 2. art. 23 RF Tax Code) When: upon presentation of relevant tax returns: until March 30, 2016 (for the 2015 tax period), until March 30, 2017 (for the 2016 tax period), etc. (p. 3 art. 386 RF Tax Code); Extent of information to be provided: tax returns as well as information on participants of a foreign company (founders of a foreign structure) as of December 31, 2015, including disclosure of indirect participation (if any) of an individual or a public company if the share of their direct and/or indirect participation in the foreign company (structure) exceeds 5% (p. 3 art. 386 RF Tax Code). Failure to comply: a fine in the amount of 100% from the immovable property tax amount, in proportion to the share in the member, information on which was not provided, or to the number of participants (p. 2. 1. art. 129. 1. RF Tax Code).
Thank You For Attention!