New Developments in Insurance Supervision Solvency II and
- Slides: 12
New Developments in Insurance Supervision Solvency II and Insurance Distribution Directive (IDD) Steffi Illegems Ph. D Candidate Antwerp Liability Law and Insurance Chair Antwerp, 26 April 2018
Overview I. III. IV. V. VII. 2 Scope and structure Types of requirements Proportionality principle In the shadow of banking supervision Similar objectives, yet conflicting results? Review v. implementation Food for thought…
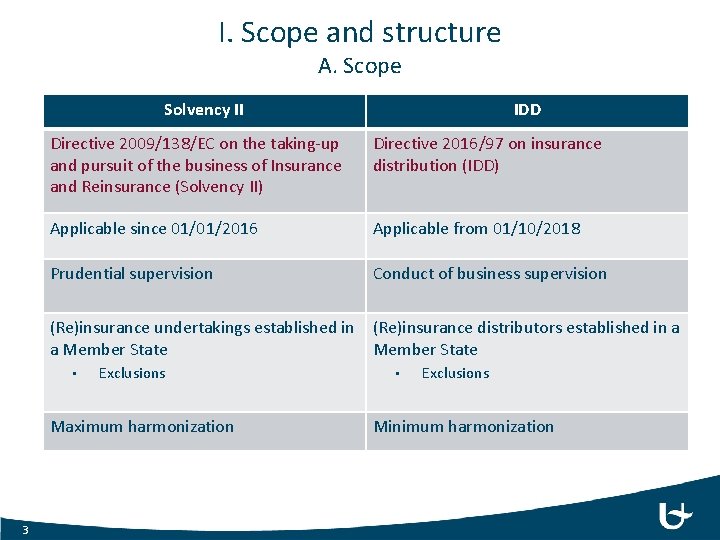
I. Scope and structure A. Scope Solvency II Directive 2009/138/EC on the taking-up and pursuit of the business of Insurance and Reinsurance (Solvency II) Directive 2016/97 on insurance distribution (IDD) Applicable since 01/01/2016 Applicable from 01/10/2018 Prudential supervision Conduct of business supervision (Re)insurance undertakings established in a Member State (Re)insurance distributors established in a Member State • Exclusions Maximum harmonization 3 IDD • Exclusions Minimum harmonization
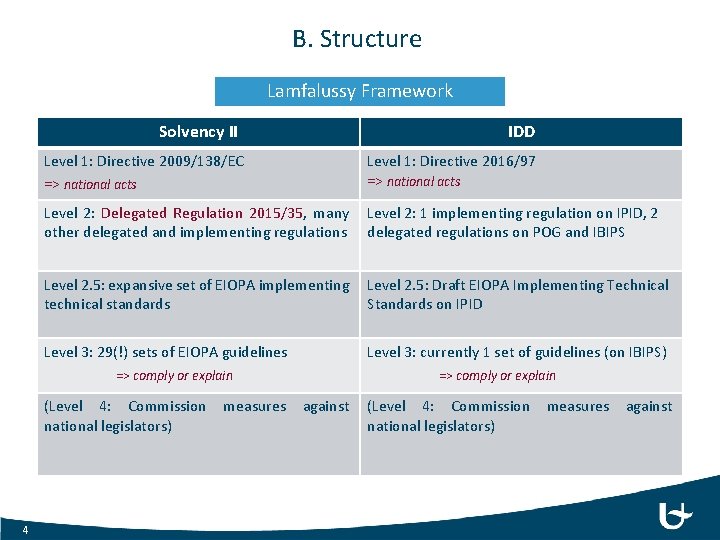
B. Structure Lamfalussy Framework Solvency II IDD Level 1: Directive 2009/138/EC => national acts Level 1: Directive 2016/97 => national acts Level 2: Delegated Regulation 2015/35, many other delegated and implementing regulations Level 2: 1 implementing regulation on IPID, 2 delegated regulations on POG and IBIPS Level 2. 5: expansive set of EIOPA implementing technical standards Level 2. 5: Draft EIOPA Implementing Technical Standards on IPID Level 3: 29(!) sets of EIOPA guidelines Level 3: currently 1 set of guidelines (on IBIPS) => comply or explain (Level 4: Commission national legislators) 4 measures => comply or explain against (Level 4: Commission national legislators) measures against
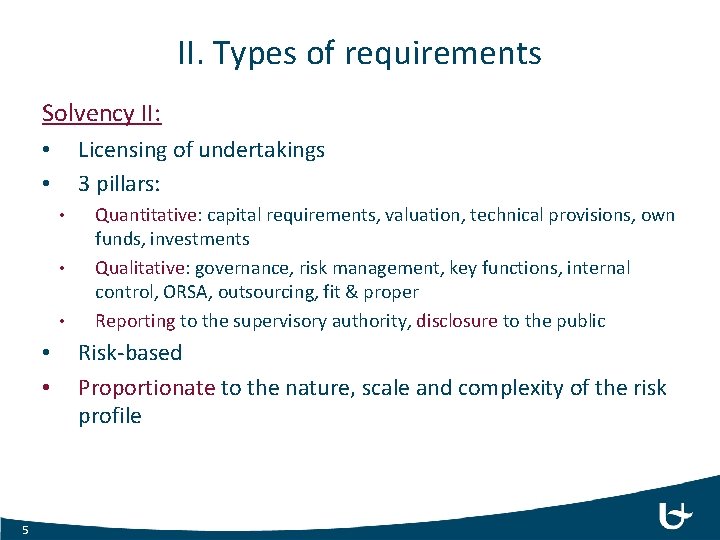
II. Types of requirements Solvency II: Licensing of undertakings 3 pillars: • • 5 Quantitative: capital requirements, valuation, technical provisions, own funds, investments Qualitative: governance, risk management, key functions, internal control, ORSA, outsourcing, fit & proper Reporting to the supervisory authority, disclosure to the public Risk-based Proportionate to the nature, scale and complexity of the risk profile
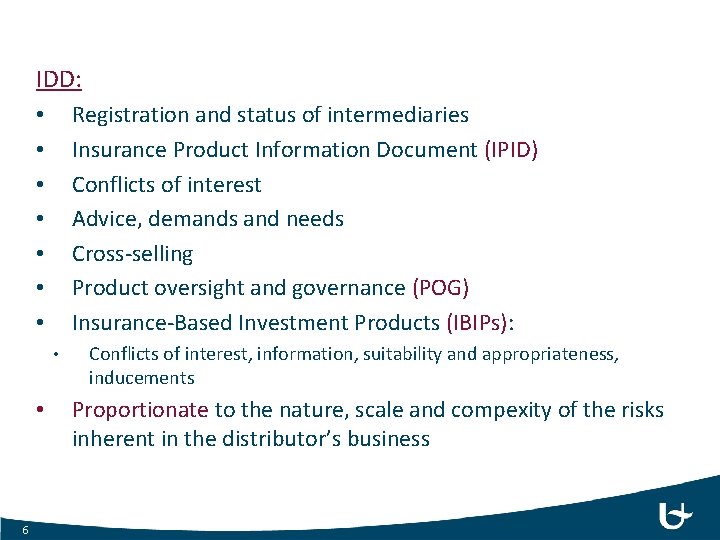
IDD: Registration and status of intermediaries Insurance Product Information Document (IPID) Conflicts of interest Advice, demands and needs Cross-selling Product oversight and governance (POG) Insurance-Based Investment Products (IBIPs): • • • 6 Conflicts of interest, information, suitability and appropriateness, inducements Proportionate to the nature, scale and compexity of the risks inherent in the distributor’s business
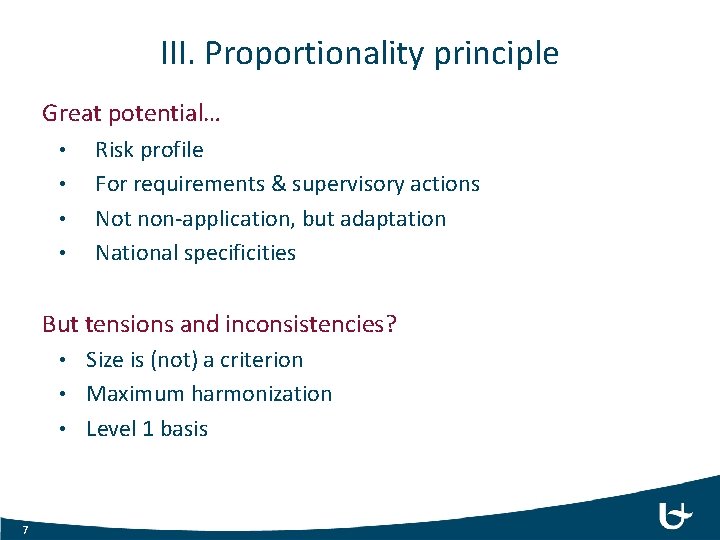
III. Proportionality principle Great potential… • • Risk profile For requirements & supervisory actions Not non-application, but adaptation National specificities But tensions and inconsistencies? • Size is (not) a criterion • Maximum harmonization • Level 1 basis 7
IV. In the shadow of banking supervision Solvency II v. CRD IV/CRR: • • • 3 pillars Risk-based capital requirements Own funds in tiers Independent control functions/key functions (BE) … IDD v. Mi. FID II: • • • 8 Key information document (IPID) Execution only Suitability & appropriateness POG …
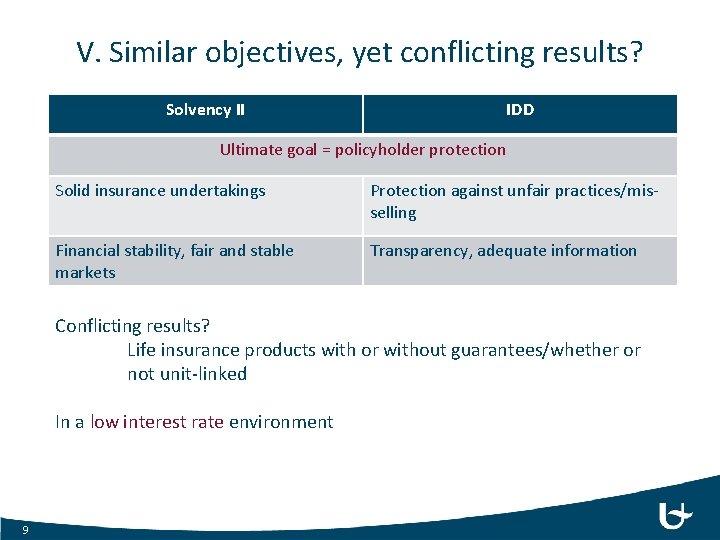
V. Similar objectives, yet conflicting results? Solvency II IDD Ultimate goal = policyholder protection Solid insurance undertakings Protection against unfair practices/misselling Financial stability, fair and stable markets Transparency, adequate information Conflicting results? Life insurance products with or without guarantees/whether or not unit-linked In a low interest rate environment 9
VI. Review v. implementation Solvency II: • • Review stage Delegated Regulation 2015/35 – SCR review 2018 • • • Technical advice by EIOPA Actual review by Commission Solvency II Directive – Review 2021 IDD: • • Implementation stage Directive 2018/411 – Quick Fix • • • 10 Transposition date: July 1 st, 2018 Application date: October 1 st, 2018 National transpositions + Levels 2 and 3 to be completed
VII. Food for thought… Technical aspects: • More insurance-tailored approach needed? • How to deal with national specificities? • Proportionality principle New developments: • Brexit • Fin. Tech, Insur. Tech • International Capital Standard, IFRS 11
Thank you steffi. illegems@uantwerpen. be