
NBED Title in sentence case UBS TMT Conference
NBED Title in sentence case UBS TMT Conference September 2015 The global M 2 M and Io. T market: forecasts and key trends Michele Mackenzie analysysmason. com © Analysys Mason Limited 2015
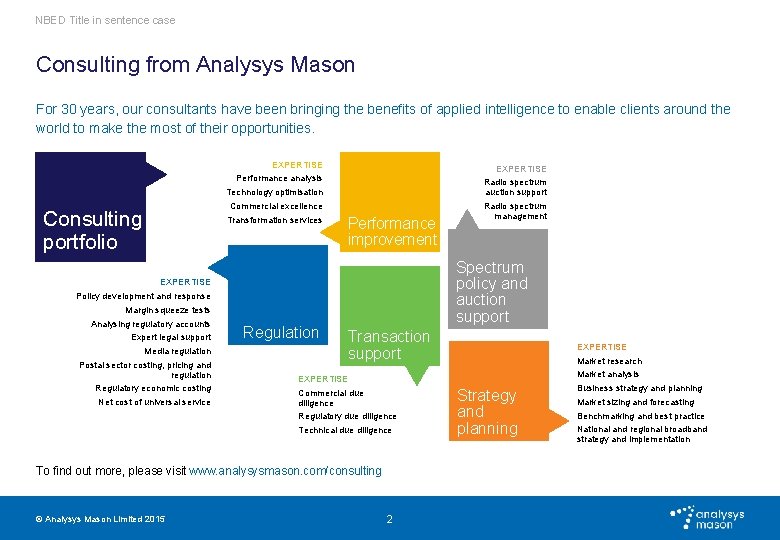
NBED Title in sentence case Consulting from Analysys Mason For 30 years, our consultants have been bringing the benefits of applied intelligence to enable clients around the world to make the most of their opportunities. EXPERTISE Performance analysis Radio spectrum auction support Technology optimisation Commercial excellence Consulting portfolio Transformation services Performance improvement Spectrum policy and auction support EXPERTISE Policy development and response Margin squeeze tests Analysing regulatory accounts Expert legal support Media regulation Postal sector costing, pricing and regulation Regulatory economic costing Net cost of universal service Regulation Transaction support EXPERTISE Market research Market analysis EXPERTISE Commercial due diligence Regulatory due diligence Technical due diligence To find out more, please visit www. analysysmason. com/consulting © Analysys Mason Limited 2015 Radio spectrum management 2 Strategy and planning Business strategy and planning Market sizing and forecasting Benchmarking and best practice National and regional broadband strategy and implementation
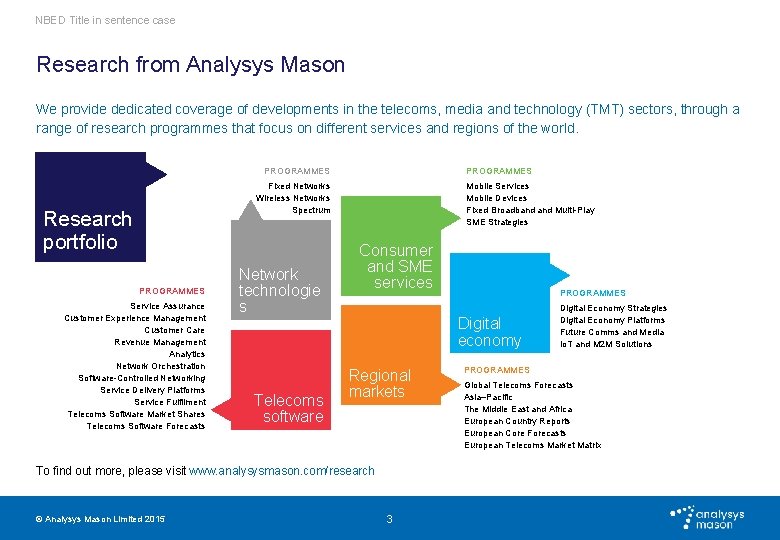
NBED Title in sentence case Research from Analysys Mason We provide dedicated coverage of developments in the telecoms, media and technology (TMT) sectors, through a range of research programmes that focus on different services and regions of the world. PROGRAMMES Fixed Networks Wireless Networks Spectrum Research portfolio PROGRAMMES Service Assurance Customer Experience Management Customer Care Revenue Management Analytics Network Orchestration Software-Controlled Networking Service Delivery Platforms Service Fulfilment Telecoms Software Market Shares Telecoms Software Forecasts Network technologie s Telecoms software Mobile Services Mobile Devices Fixed Broadband Multi-Play SME Strategies Consumer and SME services Digital economy Regional markets To find out more, please visit www. analysysmason. com/research © Analysys Mason Limited 2015 PROGRAMMES 3 Digital Economy Strategies Digital Economy Platforms Future Comms and Media Io. T and M 2 M Solutions PROGRAMMES Global Telecoms Forecasts Asia–Pacific The Middle East and Africa European Country Reports European Core Forecasts European Telecoms Market Matrix
NBED Title in sentence case 4 Io. T and M 2 M Solutions Programme: In 2014, our Io. T and M 2 M research was largely vertically focused Examples of vertical focused research reports Connected Car Digital Signage © Analysys Mason Limited 2015 Security Fleet Management Smart Cities Industrial Internet Smart Metering
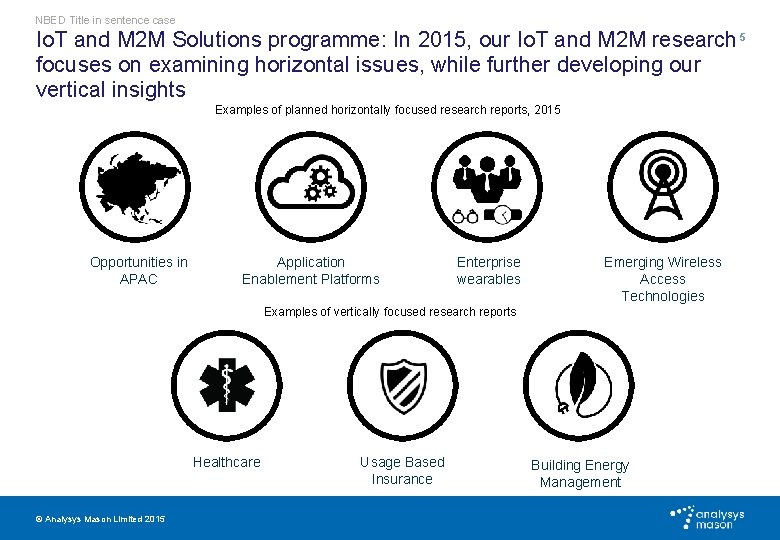
NBED Title in sentence case Io. T and M 2 M Solutions programme: In 2015, our Io. T and M 2 M research 5 focuses on examining horizontal issues, while further developing our vertical insights Examples of planned horizontally focused research reports, 2015 Opportunities in APAC Application Enablement Platforms Enterprise wearables Emerging Wireless Access Technologies Examples of vertically focused research reports Healthcare © Analysys Mason Limited 2015 Usage Based Insurance Building Energy Management
NBED Title in sentence case CONTENTS INTRODUCTION TO ANALYSYS MASON DEMAND SUPPLY SIDE DRIVERS OUTLOOK FOR M 2 M/Io. T KEY TRENDS ABOUT THE AUTHOR © Analysys Mason Limited 2015 6
NBED Title in sentence case Definition: M 2 M versus Io. T • • © Analysys Mason Limited 2015 M 2 M and Io. T continue to be used interchangeably on both the demand supply side of the industry. M 2 M typically refers to the connectivity that enables two or more machines or things to communicate with each other. The Io. T industry is nascent and its boundaries and structures are still evolving – and, as a result, so is its definition. Io. T is often closely associated with the consumer market and consumer devices, and Io. T certainly takes into account the human interaction with the data generated by devices in a connected environment. However, Io. T is just as relevant, if not more so, in the enterprise domain as it is in the consumer environment. 7
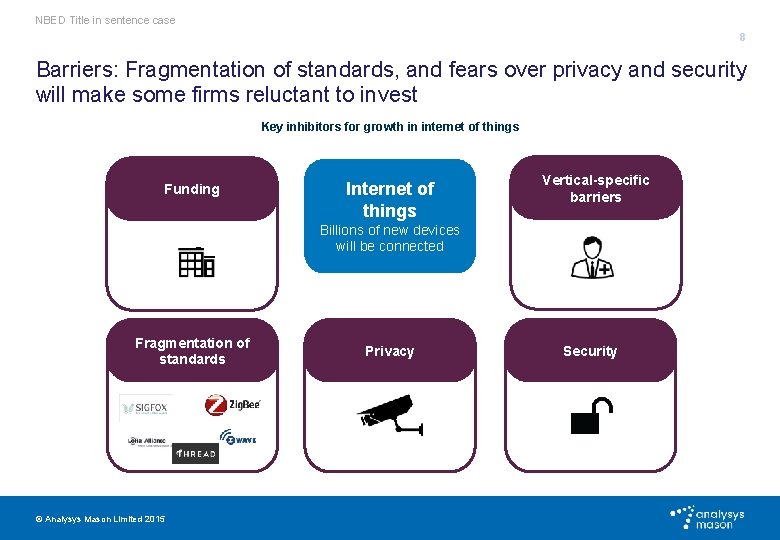
NBED Title in sentence case 8 Barriers: Fragmentation of standards, and fears over privacy and security will make some firms reluctant to invest Key inhibitors for growth in internet of things Funding New providers The lowering cost of service provision has led to hundreds of new start ups Fragmentation of standards New providers The lowering cost of service provision has led to hundreds of new start ups © Analysys Mason Limited 2015 Internet of things Billions of new devices will be connected Privacy New providers The lowering cost of service provision has led to hundreds of new start ups Vertical-specific Newbarriers providers The lowering cost of service provision has led to hundreds of new start ups Security New providers The lowering cost of service provision has led to hundreds of new start ups
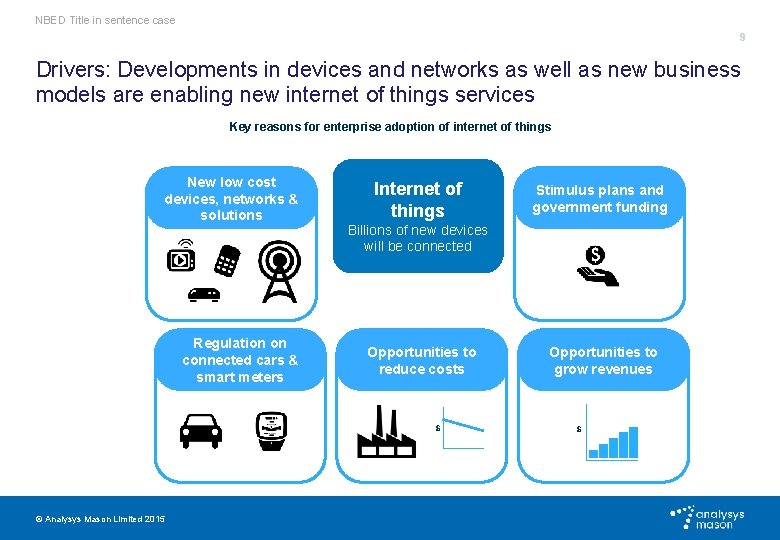
NBED Title in sentence case 9 Drivers: Developments in devices and networks as well as new business models are enabling new internet of things services Key reasons for enterprise adoption of internet of things New low cost devices, networks & New providers solutions The lowering cost of service provision has led to hundreds of new start ups Billions of new devices will be connected Stimulus plans and government funding New providers The lowering cost of service provision has led to hundreds of new start ups Regulation on connected cars & New providers smart meters The lowering cost of service provision has led to hundreds of new start ups Opportunities to reduce costs New providers The lowering cost of service provision has led to hundreds $ of new start ups Opportunities to grow revenues New providers The lowering cost of service provision has led to hundreds $ of new start ups © Analysys Mason Limited 2015 Internet of things
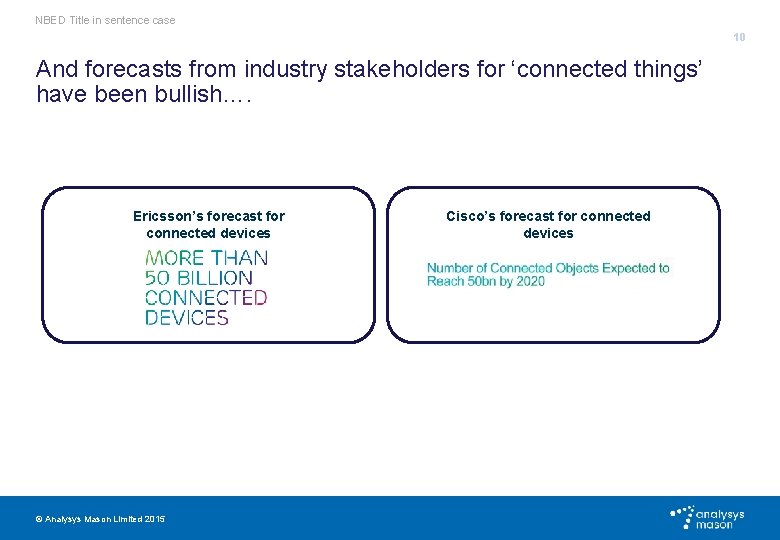
NBED Title in sentence case 10 And forecasts from industry stakeholders for ‘connected things’ have been bullish…. Ericsson’s forecast for connected devices © Analysys Mason Limited 2015 Cisco’s forecast for connected devices
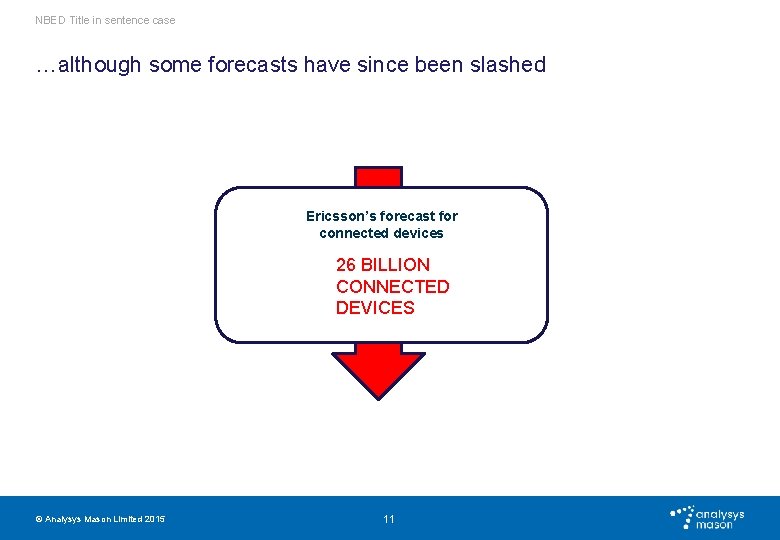
NBED Title in sentence case …although some forecasts have since been slashed Ericsson’s forecast for connected devices 26 BILLION CONNECTED DEVICES © Analysys Mason Limited 2015 11
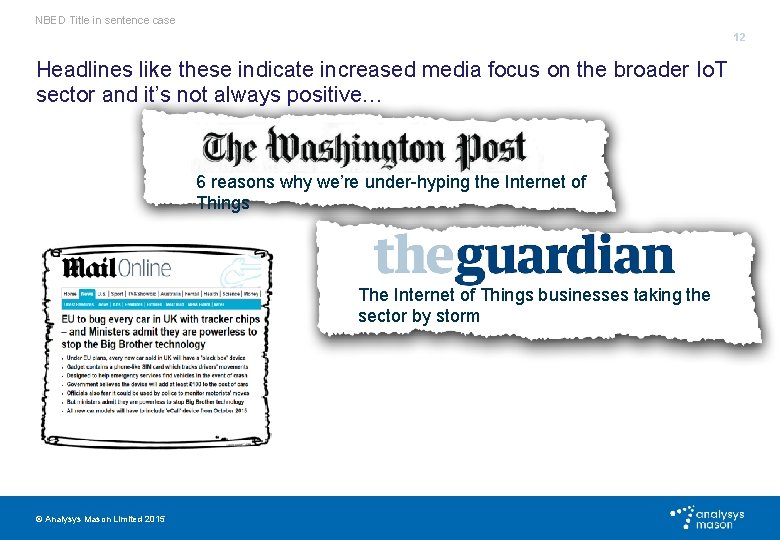
NBED Title in sentence case 12 Headlines like these indicate increased media focus on the broader Io. T sector and it’s not always positive… 6 reasons why we’re under-hyping the Internet of Things The Internet of Things businesses taking the sector by storm © Analysys Mason Limited 2015
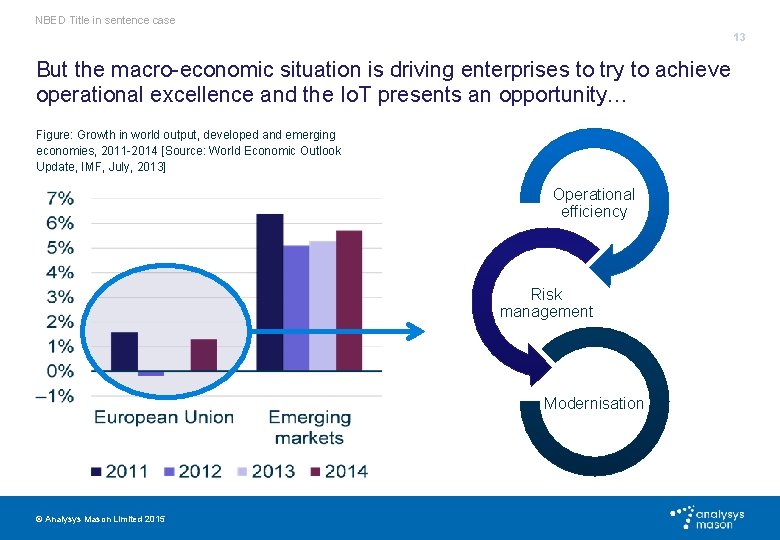
NBED Title in sentence case 13 But the macro-economic situation is driving enterprises to try to achieve operational excellence and the Io. T presents an opportunity… Figure: Growth in world output, developed and emerging economies, 2011 -2014 [Source: World Economic Outlook Update, IMF, July, 2013] Operational efficiency Risk management Modernisation © Analysys Mason Limited 2015
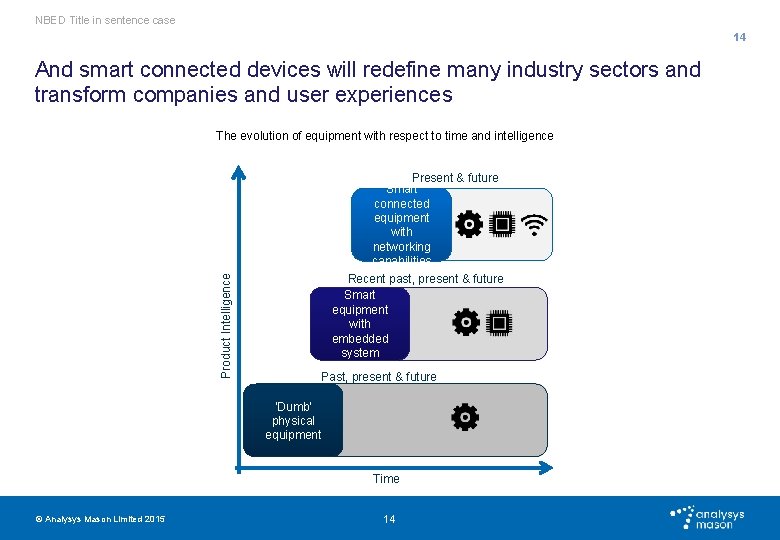
NBED Title in sentence case 14 And smart connected devices will redefine many industry sectors and transform companies and user experiences Product Intelligence The evolution of equipment with respect to time and intelligence Present & future Smart connected equipment with networking capabilities Recent past, present & future Smart equipment with embedded system Past, present & future ‘Dumb’ physical equipment Time © Analysys Mason Limited 2015 14
NBED Title in sentence case CONTENTS INTRODUCTION TO ANALYSYS MASON DEMAND SUPPLY SIDE DRIVERS OUTLOOK FOR M 2 M/Io. T KEY TRENDS ABOUT THE AUTHOR © Analysys Mason Limited 2015 15
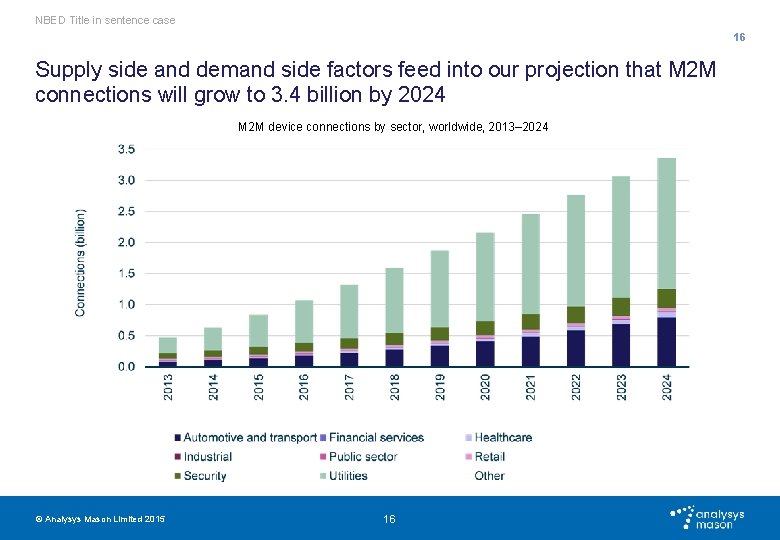
NBED Title in sentence case 16 Supply side and demand side factors feed into our projection that M 2 M connections will grow to 3. 4 billion by 2024 M 2 M device connections by sector, worldwide, 2013– 2024 © Analysys Mason Limited 2015 16
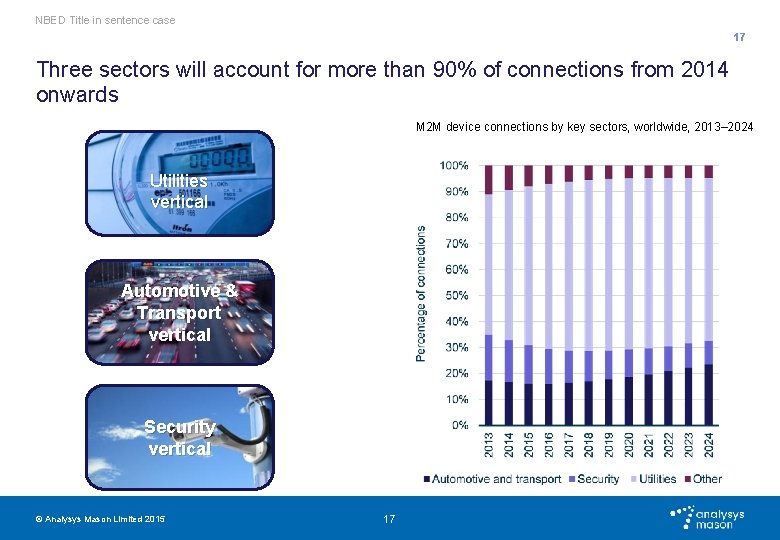
NBED Title in sentence case 17 Three sectors will account for more than 90% of connections from 2014 onwards M 2 M device connections by key sectors, worldwide, 2013– 2024 Utilities vertical Automotive & Transport vertical Security vertical © Analysys Mason Limited 2015 17
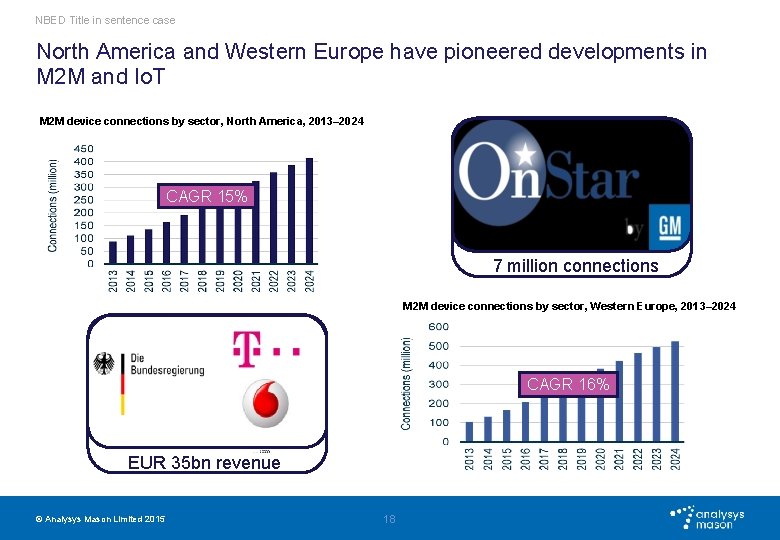
NBED Title in sentence case North America and Western Europe have pioneered developments in M 2 M and Io. T M 2 M device connections by sector, North America, 2013– 2024 CAGR 15% 7 million connections M 2 M device connections by sector, Western Europe, 2013– 2024 CAGR 16% EUR 35 bn revenue © Analysys Mason Limited 2015 18
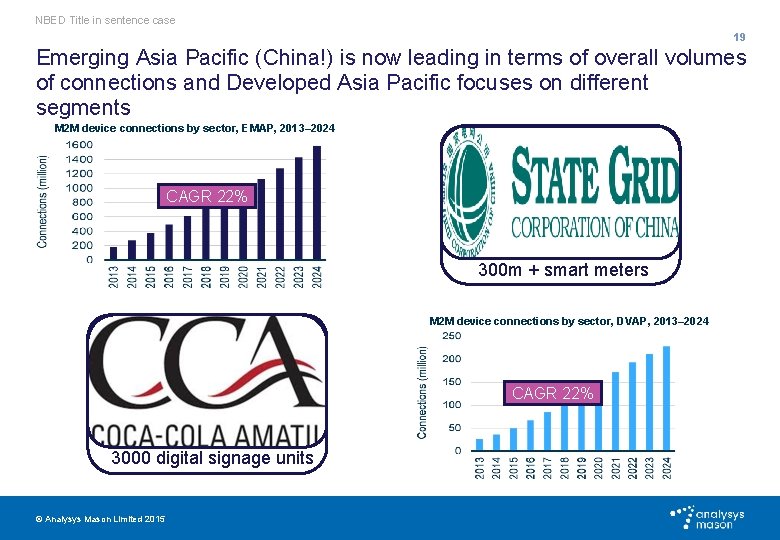
NBED Title in sentence case 19 Emerging Asia Pacific (China!) is now leading in terms of overall volumes of connections and Developed Asia Pacific focuses on different segments M 2 M device connections by sector, EMAP, 2013– 2024 CAGR 22% 300 m + smart meters M 2 M device connections by sector, DVAP, 2013– 2024 CAGR 22% 3000 digital signage units © Analysys Mason Limited 2015
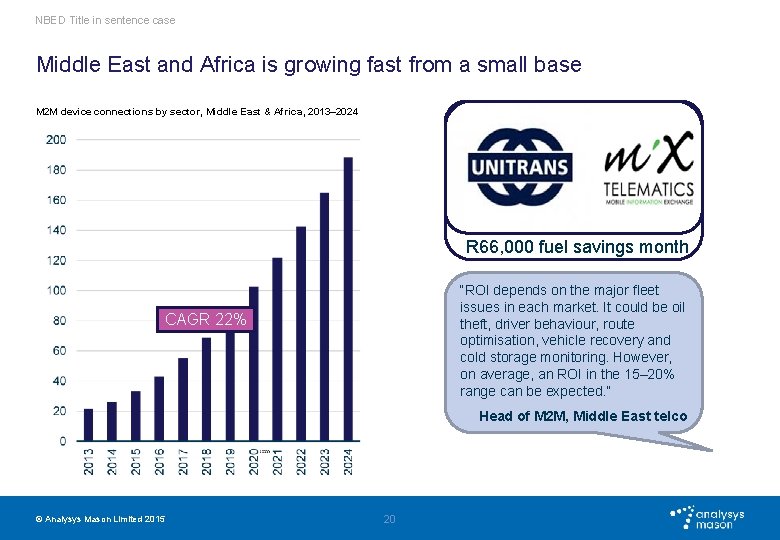
NBED Title in sentence case Middle East and Africa is growing fast from a small base M 2 M device connections by sector, Middle East & Africa, 2013– 2024 R 66, 000 fuel savings month “ROI depends on the major fleet issues in each market. It could be oil theft, driver behaviour, route optimisation, vehicle recovery and cold storage monitoring. However, on average, an ROI in the 15– 20% range can be expected. ” CAGR 22% Head of M 2 M, Middle East telco © Analysys Mason Limited 2015 20
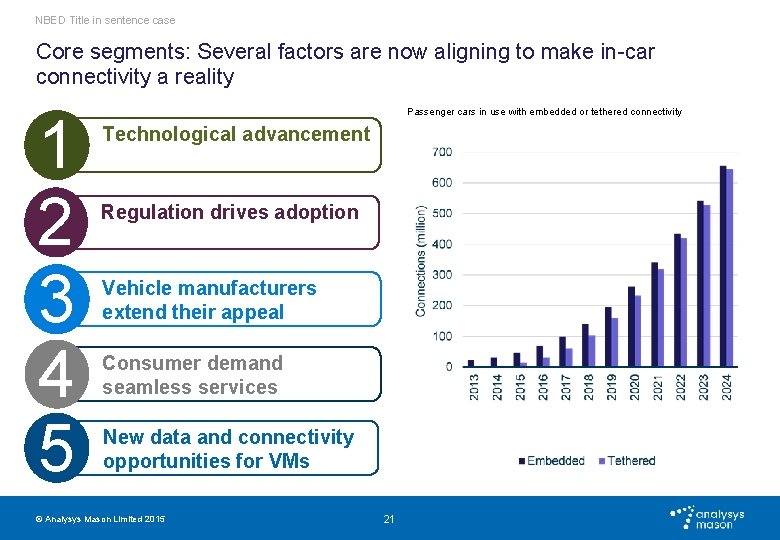
NBED Title in sentence case Core segments: Several factors are now aligning to make in-car connectivity a reality 1 2 3 4 5 Passenger cars in use with embedded or tethered connectivity Technological advancement Regulation drives adoption Vehicle manufacturers extend their appeal Consumer demand seamless services New data and connectivity opportunities for VMs © Analysys Mason Limited 2015 21
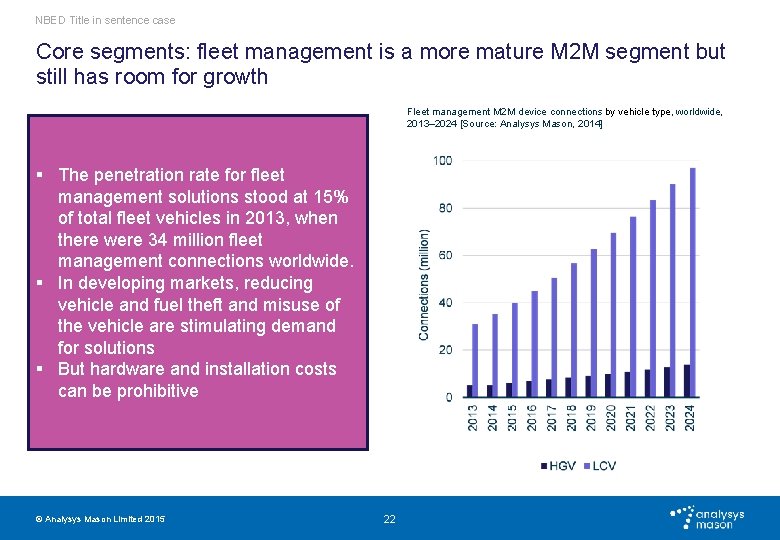
NBED Title in sentence case Core segments: fleet management is a more mature M 2 M segment but still has room for growth Fleet management M 2 M device connections by vehicle type, worldwide, 2013– 2024 [Source: Analysys Mason, 2014] § The penetration rate for fleet management solutions stood at 15% of total fleet vehicles in 2013, when there were 34 million fleet management connections worldwide. § In developing markets, reducing vehicle and fuel theft and misuse of the vehicle are stimulating demand for solutions § But hardware and installation costs can be prohibitive © Analysys Mason Limited 2015 22
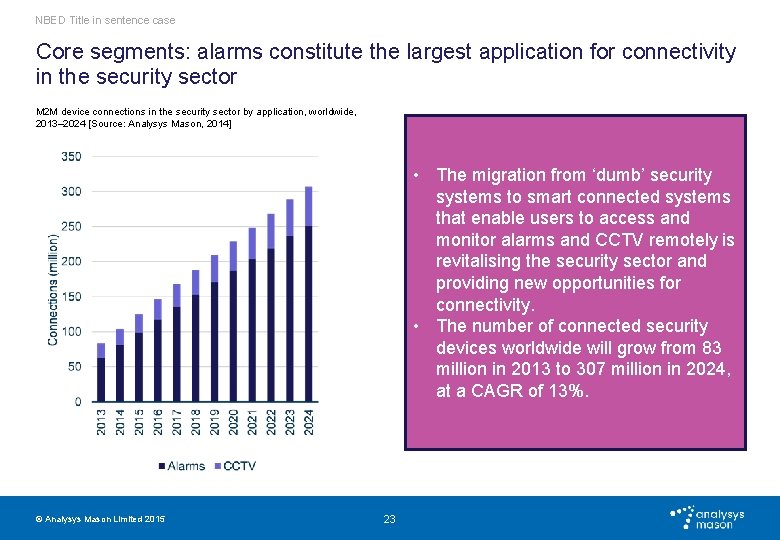
NBED Title in sentence case Core segments: alarms constitute the largest application for connectivity in the security sector M 2 M device connections in the security sector by application, worldwide, 2013– 2024 [Source: Analysys Mason, 2014] • The migration from ‘dumb’ security systems to smart connected systems that enable users to access and monitor alarms and CCTV remotely is revitalising the security sector and providing new opportunities for connectivity. • The number of connected security devices worldwide will grow from 83 million in 2013 to 307 million in 2024, at a CAGR of 13%. © Analysys Mason Limited 2015 23
NBED Title in sentence case CONTENTS INTRODUCTION TO ANALYSYS MASON DEMAND SUPPLY SIDE DRIVERS OUTLOOK FOR M 2 M/Io. T KEY TRENDS ABOUT THE AUTHOR © Analysys Mason Limited 2015 24
NBED Title in sentence case Key trends in the M 2 M/Io. T market Players are positioning to take advantage of the M 2 M/Io. T market LPWA: optimised networks will drive future growth © Analysys Mason Limited 2015 25 M 2 M and Io. T merger and acquisition activity continues to shape the industry
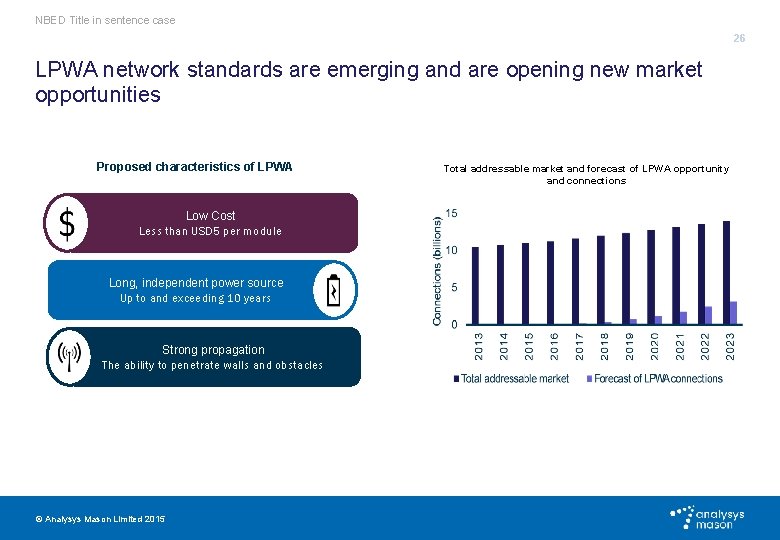
NBED Title in sentence case 26 LPWA network standards are emerging and are opening new market opportunities Proposed characteristics of LPWA Low Cost Less than USD 5 per module Long, independent power source Up to and exceeding 10 years Strong propagation The ability to penetrate walls and obstacles © Analysys Mason Limited 2015 Total addressable market and forecast of LPWA opportunity and connections
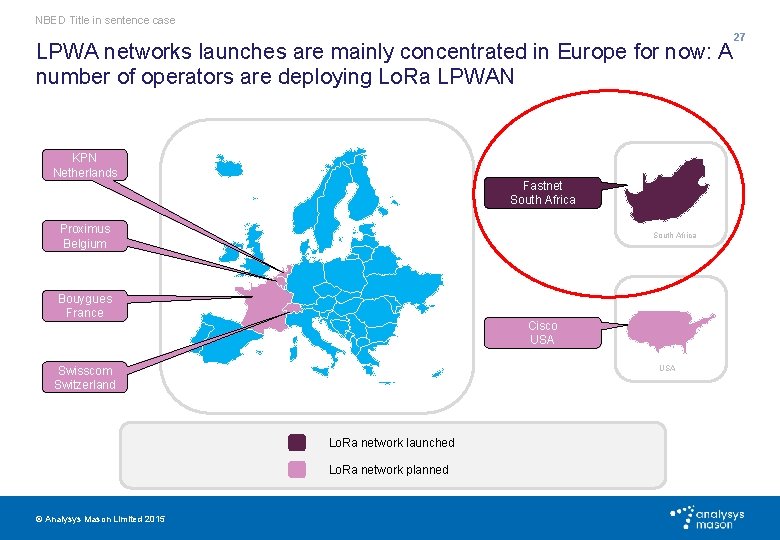
NBED Title in sentence case 27 LPWA networks launches are mainly concentrated in Europe for now: A number of operators are deploying Lo. Ra LPWAN KPN Netherlands Fastnet South Africa Proximus Belgium South Africa Bouygues France Cisco USA Swisscom Switzerland Lo. Ra network launched Lo. Ra network planned © Analysys Mason Limited 2015
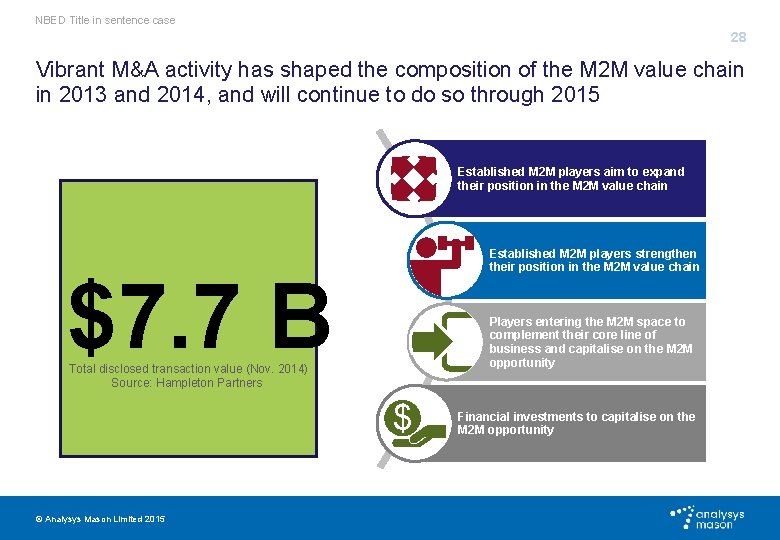
NBED Title in sentence case 28 Vibrant M&A activity has shaped the composition of the M 2 M value chain in 2013 and 2014, and will continue to do so through 2015 Established M 2 M players aim to expand their position in the M 2 M value chain Established M 2 M players strengthen their position in the M 2 M value chain $7. 7 B Players entering the M 2 M space to complement their core line of business and capitalise on the M 2 M opportunity Total disclosed transaction value (Nov. 2014) Source: Hampleton Partners $ © Analysys Mason Limited 2015 Financial investments to capitalise on the M 2 M opportunity
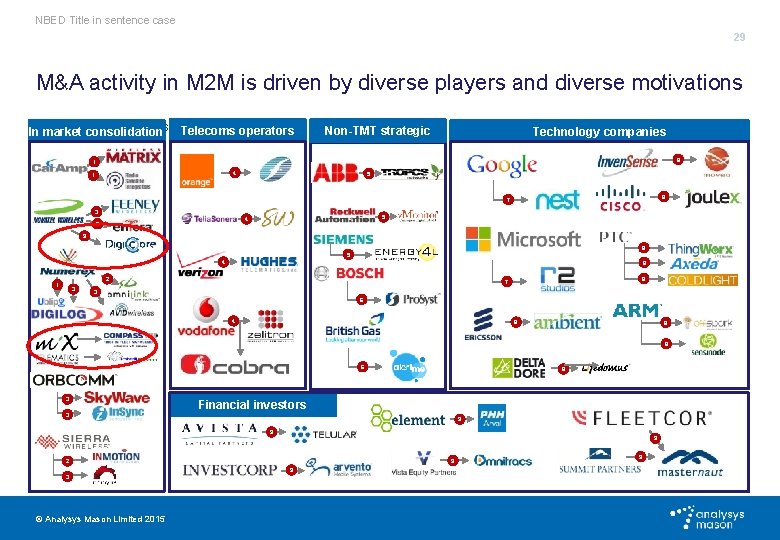
NBED Title in sentence case 29 M&A activity in M 2 M is driven by diverse players and diverse motivations Source: Analysys Mason, Public sources In▪ market consolidation Telecoms operators Non-TMT strategic Technology companies 8 1 4 1 5 8 7 3 5 4 2 9 8 5 4 8 2 1 3 8 7 3 6 4 8 8 8 6 3 3 8 Financial investors 9 9 2 3 © Analysys Mason Limited 2015 9 9
NBED Title in sentence case Key takeaways 1 2 3 Demand supply side drivers are aligning to drive growth in the M 2 M/Io. T market • But the market is immature and dynamic and forecasts have already been adjusted • The Io. T is however expected to deliver a new wave of economic growth Regional and vertical variations will persist § Developing markets are beginning to deploy M 2 M/Io. T more rapidly § Fleet management, connected car, security and utilities have grown quickly but other verticals are attracting interest. Io. T optimised networks are emerging and M&A activity is increasing § LPWA affords a significant opportunity to connect new application groups § M&A activity is significant as players position to capture the value of the Io. T © Analysys Mason Limited 2015 30
- Slides: 30