
Microfinance Regulation Arnaud Ventura Cofounder Vice President Founder
- Slides: 29
Microfinance Regulation Arnaud Ventura Co-founder, Vice President Founder, President & CEO 10/6/2020 Pla. Net Finance Micro. Cred
Content I. An Introduction to Pla. Net Finance II. An Introduction to Micro. Cred III. A few concrete cases: Regulation & microfinance investments 1. 2. 3. 4. 5. 2 Mexico Madagascar China Senegal Algeria
Introduction to Pla. Net Finance 3
I. Introduction to Pla. Net Finance Group Pla. Net Finance is an International Non Profit Organization that contributes to the improvement of human condition by ensuring each person’s dignity through the development of microfinance worldwide. Pla. Net Finance focuses on – Strengthening the capacity of the microfinance sector (Microfinance Institutions, Governments, Banks & Financial Institutions, etc. ) – Increasing the transparency of the microfinance sector – Increasing the funding available to Microfinance Institutions 4
I. Introduction to Pla. Net Finance Group I. 1. Services 1. Consulting, Technical Assistance & Training services to : • • • Microfinance Institutions (NGOs, Cooperatives, Regulated financial institutions), National Microfinance Network Governments (defining strategies, setting up regulations) Banks interested in downscaling or supporting the sector Microentrepreneurs (Business Development Services) 2. Investment Management & Advisory Services for microfinance investors: • • Pla. Net Micro. Fund a 1 M€ fund managed by Pla. Net Finance respons. Ability Global & respons. Ability Leader Fund: 2 funds with cumulated assets of 200 M€ advised by Pla. Net Finance 3. Rating Services to MFIs through an independant affiliate 4. Equity Investment through Micro. Cred, a Microfinance Holding Company 5
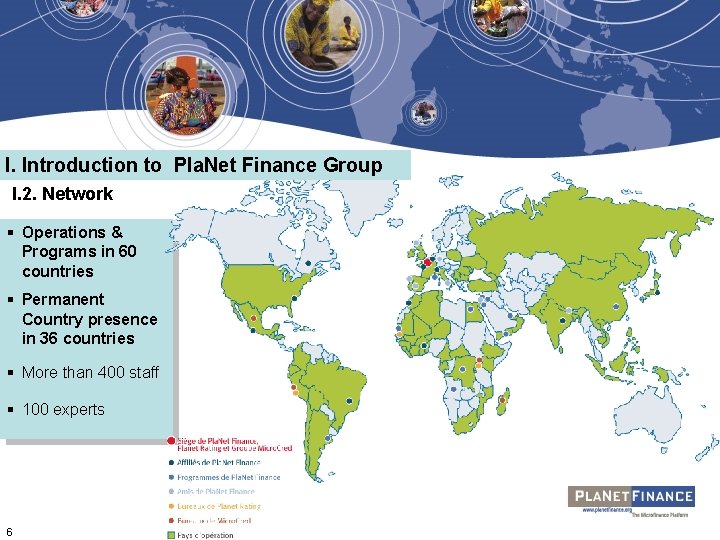
I. Introduction to Pla. Net Finance Group I. 2. Network § Operations & Programs in 60 countries § Permanent Country presence in 36 countries § More than 400 staff § 100 experts 6
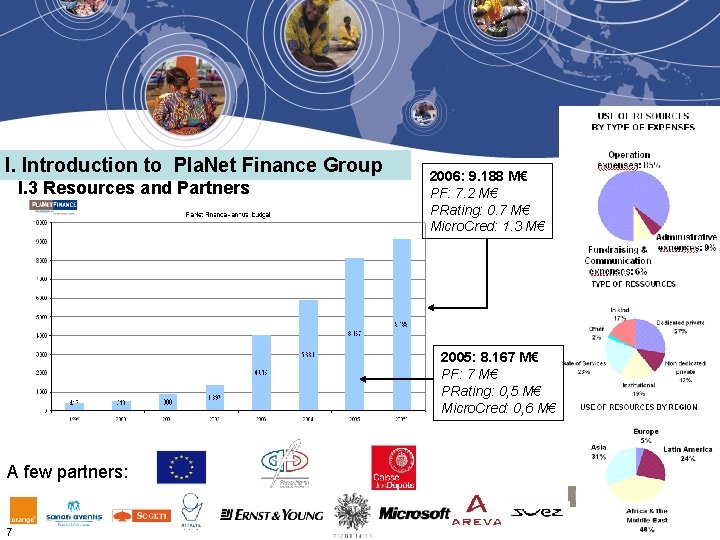
I. Introduction to Pla. Net Finance Group I. 3 Resources and Partners 2006: 9. 188 M€ PF: 7. 2 M€ PRating: 0. 7 M€ Micro. Cred: 1. 3 M€ 2005: 8. 167 M€ PF: 7 M€ PRating: 0, 5 M€ Micro. Cred: 0, 6 M€ A few partners: 7
Introduction to Micro. Cred 8
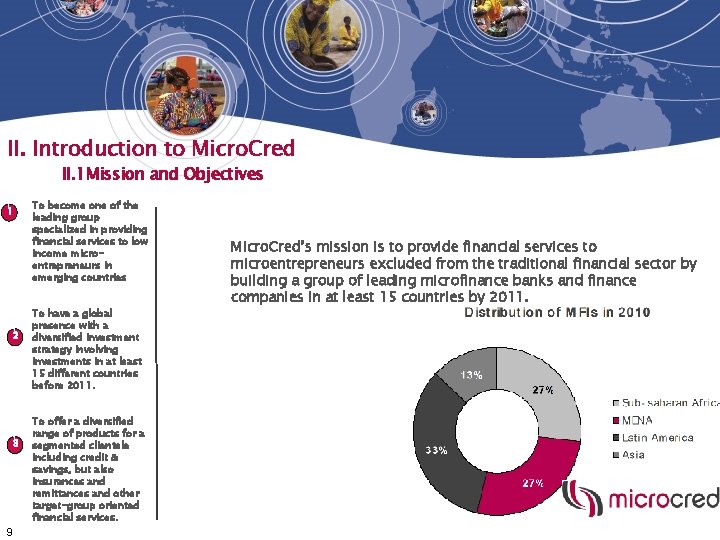
II. Introduction to Micro. Cred II. 1 Mission and Objectives 1 1 1 2 1 3 9 To become one of the leading group specialized in providing financial services to low income microentrepreneurs in emerging countries To have a global presence with a diversified investment strategy involving investments in at least 15 different countries before 2011. To offer a diversified range of products for a segmented clientele including credit & savings, but also insurances and remittances and other target-group oriented financial services. Micro. Cred’s mission is to provide financial services to microentrepreneurs excluded from the traditional financial sector by building a group of leading microfinance banks and finance companies in at least 15 countries by 2011.
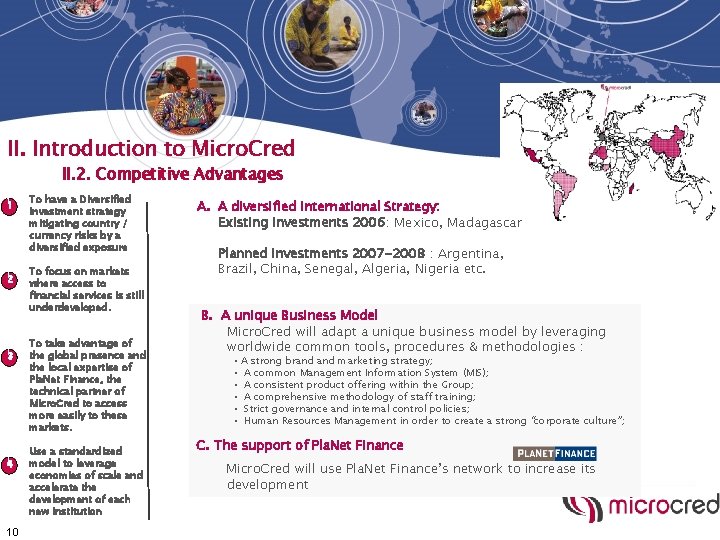
II. Introduction to Micro. Cred II. 2. Competitive Advantages 1 1 1 2 1 3 1 4 10 To have a Diversified investment strategy mitigating country / currency risks by a diversified exposure To focus on markets where access to financial services is still underdeveloped. To take advantage of the global presence and the local expertise of Pla. Net Finance, the technical partner of Micro. Cred to access more easily to these markets. Use a standardized model to leverage economies of scale and accelerate the development of each new institution A. A diversified International Strategy: Existing Investments 2006: Mexico, Madagascar Planned Investments 2007 -2008 : Argentina, Brazil, China, Senegal, Algeria, Nigeria etc. B. A unique Business Model Micro. Cred will adapt a unique business model by leveraging worldwide common tools, procedures & methodologies : • A strong brand marketing strategy; • A common Management Information System (MIS); • A consistent product offering within the Group; • A comprehensive methodology of staff training; • Strict governance and internal control policies; • Human Resources Management in order to create a strong “corporate culture”; C. The support of Pla. Net Finance Micro. Cred will use Pla. Net Finance’s network to increase its development
II. Introduction to Micro. Cred II. 3. Shareholders An initial capital of 25 Millions USD with strong shareholders support : 11
A few Concrete Cases: Mexico Madagascar China Sénégal Algeria 12
MEXICO 13
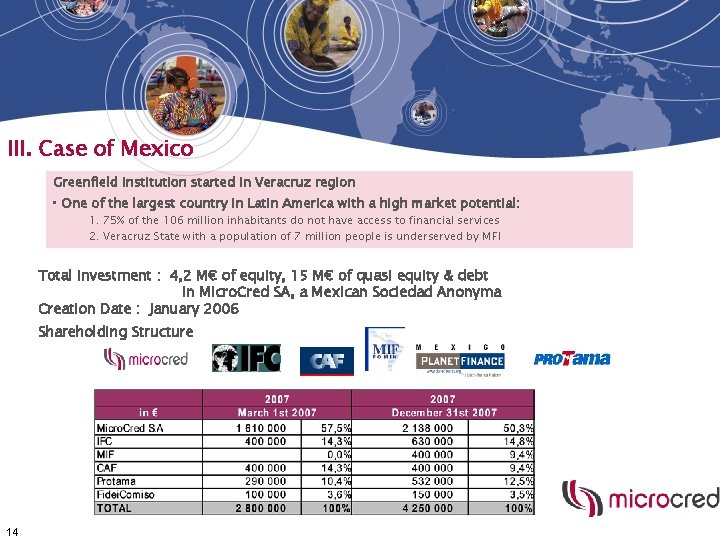
III. Case of Mexico Greenfield institution started in Veracruz region • One of the largest country in Latin America with a high market potential: 1. 75% of the 106 million inhabitants do not have access to financial services 2. Veracruz State with a population of 7 million people is underserved by MFI Total Investment : 4, 2 M€ of equity, 15 M€ of quasi equity & debt in Micro. Cred SA, a Mexican Sociedad Anonyma Creation Date : January 2006 Shareholding Structure 14
III. Case of Mexico No specific regulation for microfinance in Mexico but regulation concerning financial institutions & Credit & Saving Cooperatives applying to the target group of microfinance. “Ley de Institutiociones de Credito” for banks & financial institutions & “Ley de Credito y Ahorro Popular” published on June 4 th 2001 regulating credit & savings cooperatives. Some issues linked to this regulatory framework: 1. 2. designed considering the need of cooperatives structures no specific considerations for other type of structures : NGOs, Private Company Consequences: As a Private company operating in Microfinance in Mexico Micro. Cred can not benefit from the advantages of the ley de credito y ahorro popular, specifically it can not offer savings services 15
MADAGASCAR 16
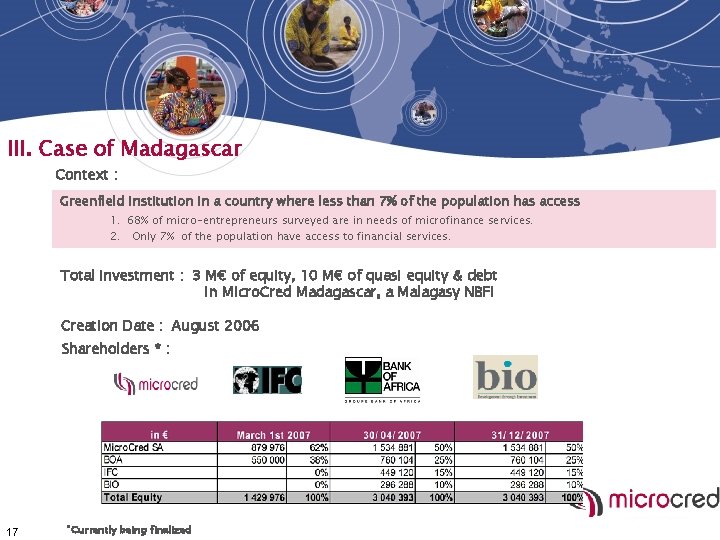
III. Case of Madagascar Context : Greenfield institution in a country where less than 7% of the population has access 1. 68% of micro-entrepreneurs surveyed are in needs of microfinance services. 2. Only 7% of the population have access to financial services. Total Investment : 3 M€ of equity, 10 M€ of quasi equity & debt in Micro. Cred Madagascar, a Malagasy NBFI Creation Date : August 2006 Shareholders * : 17 * Currently being finalized
III. Case of Madagascar, has issues a specific microfinance law “loi n°- 2005 - 016 du 29 septembre 2005 “ in 2005. but at the date, no implementation rules have been adopted. The law mentions 3 types of MFI : Category 1, 2 and 3 including both cooperatives and non cooperatives institutions. Some issues linked to this regulatory framework: 1. not finalized yet (no “decret d’application” yet) Consequences: As a Private company operating in Microfinance in Madagascar Micro. Cred was started as Non bank financial institution and is now considering transforming into a full fledge bank 18
CHINA 19
III. Case of China Context: • Extremely promising market • Underdevelopped financial and microfinance sector • One of the four first licenses for commercials Micro. Finance being offered in China • Nanchong Municipality: more than 108, 000 MPME among 94, 000 individual enterprises. • Support of Local Authorities in the creation of a Commercial Institution. Total Investment : 5 M€ of equity, 20 M€ of quasi equity & debt in Micro. Cred China, a Chinese WFOE Creation Date : April 2007 Shareholders : The following investors have agreed to take an equity participation into Micro. Cred China: 20
III. Case of China A specific microfinance framework has been issued under PBOC initiative, the microfinance pilot framework allows for private investors to invest in the development of microfinance companies serving the rural areas and offering credit services. No specific law but rather a loose regulation issued by PBOC Some issues linked to this regulatory framework: 1. 2. 3. a pilot program, so the sustainability is not yet clear Very limited scope of activities allowed Limitation of financing sources (the approved companies can not mobilize savings neither can they access bank loans)… Consequences: 21 As a Private company operating in Microfinance in China Micro. Cred is starting in a very unsecured position, but trust that the regulation will be formalized in the coming years.
SENEGAL 22
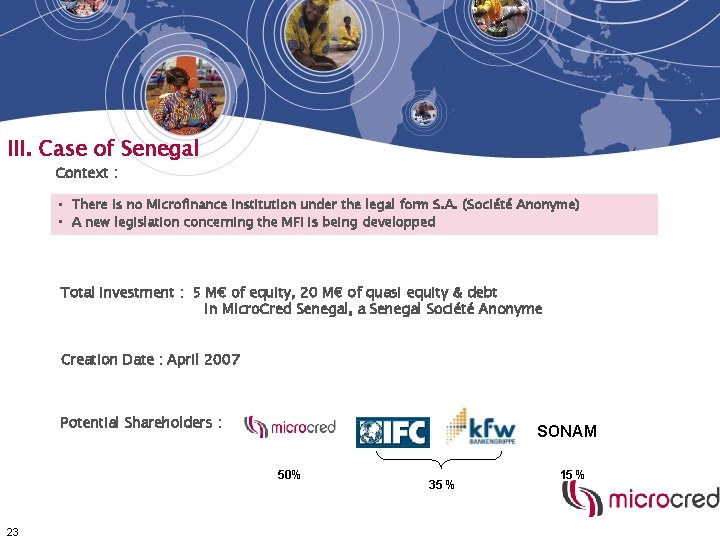
III. Case of Senegal Context : • There is no Microfinance institution under the legal form S. A. (Société Anonyme) • A new legislation concerning the MFI is being developped Total Investment : 5 M€ of equity, 20 M€ of quasi equity & debt in Micro. Cred Senegal, a Senegal Société Anonyme Creation Date : April 2007 Potential Shareholders : SONAM 50% 23 35 % 15 %
III. Case of Senegal A specific regulation for microfinance exist in West Africa under the CBWAS (Central Bank of West African States) Senegal “ Loi PARMEC”. The regulation has been designed for Cooperatives rather than for microfinance institutions. The regulation is currently being revised. Some issues linked to this regulatory framework: 1. Designed for Cooperatives structures, does not facilitate NGOs, nor private company 2. Different fiscal treatment for each legal form 3. Specific approval with 5 years license for Private Companies Consequences: 24 As a Private company operating in Microfinance in Sénégal Micro. Cred is starting in a very unsecured position, but trust that the regulation will be formalized in the coming months.
ALGERIA 25
III. Case of Algeria • Strong economic growth (7% growth of GDP in 2005) • Lowest banking coverage rate in the Arab world • No microfinance sector developed in Algeria • Strong potential market (73% of interviewed microentrepreneurs interested in a loan) Total Investment : 5 M€ of equity, 20 M€ of quasi equity & debt in Micro. Cred Algeria, a Non Bank Financial Institution Creation Date : 2007 /2008, depending on the aproval process Potential Shareholders : 26
III. Case of Algeria No specific regulation for microfinance exist in Algeria. Only a very strict banking regulation allowing for Banks & NBFI (minimum equity for NBFI 6 M€) Some issues linked to this regulatory framework: 1. 2. 3. 4. Minimum equity to create a Microfinance Company very high 6 M€ as NBFI Limited scope of services (credit only) Long and very difficult approval process Approval to be sought for each branch opening. Consequences: 27 As a Private company operating in Microfinance in Algeria Micro. Cred is making a huge investment only to fill the un-adpated conditions of the “Banque d’Algérie”. Micro. Cred is treated as a bank and not as a Microfinance Institution.
CONCLUSIONS 28
Conclusions Bad Regulatory Framework can limit Microfinance development. Main obstacles are : 1. No regulation for Microfinance (Algeria, China) 2. Regulation targeting a limited legal form of MFIs (Mexico, West Africa) 3. Regulations not allowing deposit taking MFI (China, Mexico) 4. Bureaucratic Obstacles : long approval process, etc. . (Algeria) Solution : In the same way the financial & banking sector is adopting international regulations (Basle I, Basle II) to improve efficiency, Microfinance development could be foster with international regulations or at least international guidelines helping local regulatory body facilitate the development of microfinance. 29