Marginal Costing with emphasis on its uses and
- Slides: 15
Marginal Costing with emphasis on its uses and applications in business Simon Lee Co-Director, Integrated BBA Program Senior Lecturer, School of Accountancy CUHK Business School Simon Lee 李兆波 1
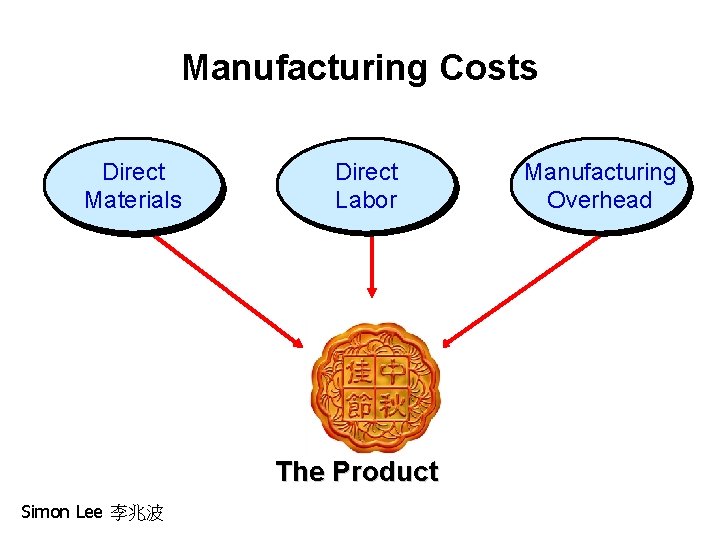
Manufacturing Costs Direct Materials Direct Labor The Product Simon Lee 李兆波 Manufacturing Overhead
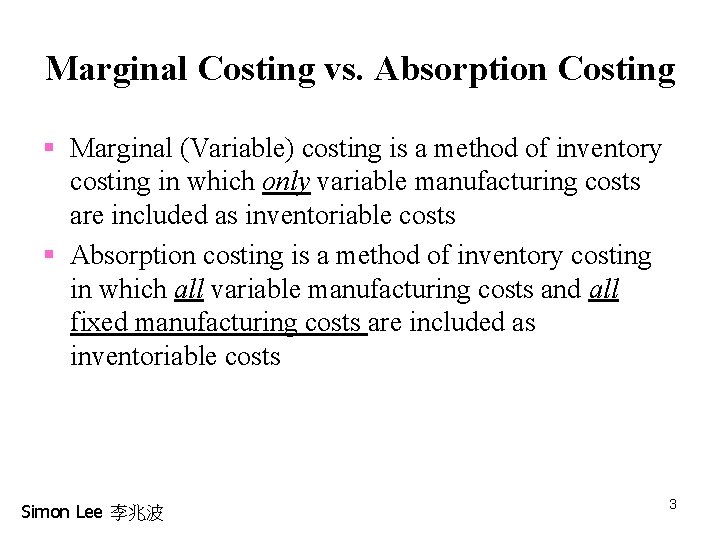
Marginal Costing vs. Absorption Costing § Marginal (Variable) costing is a method of inventory costing in which only variable manufacturing costs are included as inventoriable costs § Absorption costing is a method of inventory costing in which all variable manufacturing costs and all fixed manufacturing costs are included as inventoriable costs Simon Lee 李兆波 3
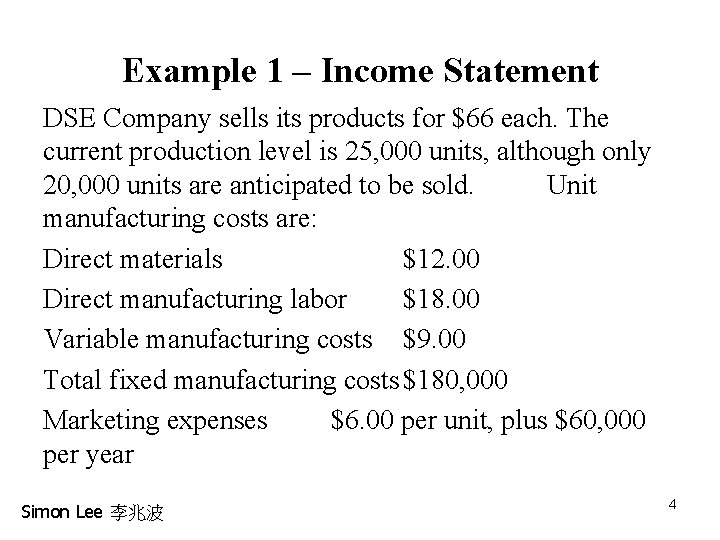
Example 1 – Income Statement DSE Company sells its products for $66 each. The current production level is 25, 000 units, although only 20, 000 units are anticipated to be sold. Unit manufacturing costs are: Direct materials $12. 00 Direct manufacturing labor $18. 00 Variable manufacturing costs $9. 00 Total fixed manufacturing costs $180, 000 Marketing expenses $6. 00 per unit, plus $60, 000 per year Simon Lee 李兆波 4
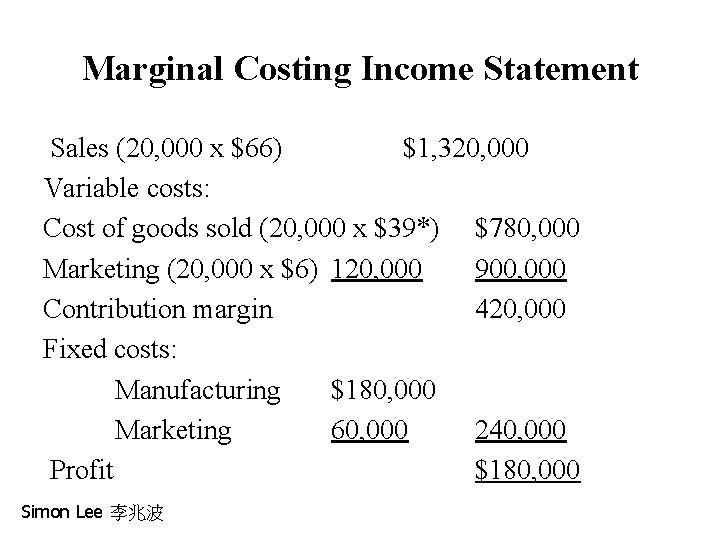
Marginal Costing Income Statement Sales (20, 000 x $66) $1, 320, 000 Variable costs: Cost of goods sold (20, 000 x $39*) $780, 000 Marketing (20, 000 x $6) 120, 000 900, 000 Contribution margin 420, 000 Fixed costs: Manufacturing $180, 000 Marketing 60, 000 240, 000 Profit $180, 000 Simon Lee 李兆波
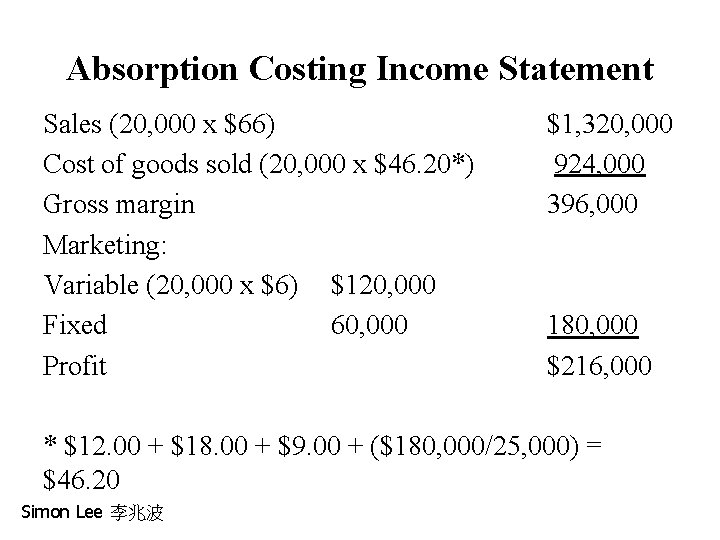
Absorption Costing Income Statement Sales (20, 000 x $66) Cost of goods sold (20, 000 x $46. 20*) Gross margin Marketing: Variable (20, 000 x $6) $120, 000 Fixed 60, 000 Profit $1, 320, 000 924, 000 396, 000 180, 000 $216, 000 * $12. 00 + $18. 00 + $9. 00 + ($180, 000/25, 000) = $46. 20 Simon Lee 李兆波
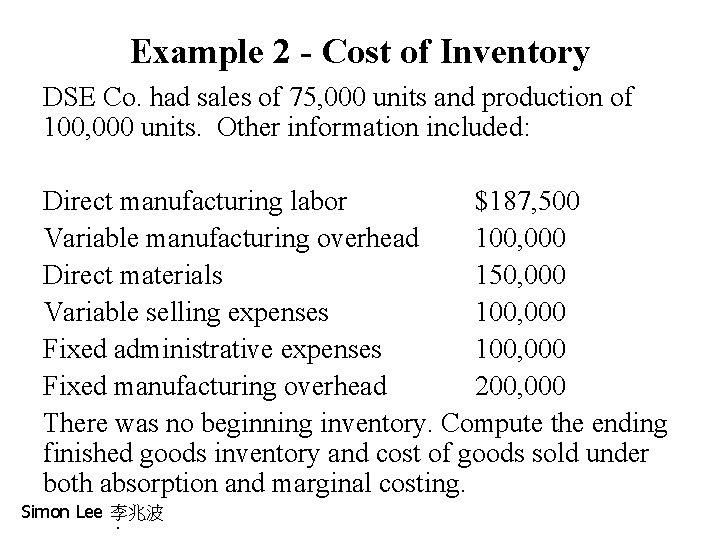
Example 2 - Cost of Inventory DSE Co. had sales of 75, 000 units and production of 100, 000 units. Other information included: Direct manufacturing labor $187, 500 Variable manufacturing overhead 100, 000 Direct materials 150, 000 Variable selling expenses 100, 000 Fixed administrative expenses 100, 000 Fixed manufacturing overhead 200, 000 There was no beginning inventory. Compute the ending finished goods inventory and cost of goods sold under both absorption and marginal costing. Simon Lee 李兆波.
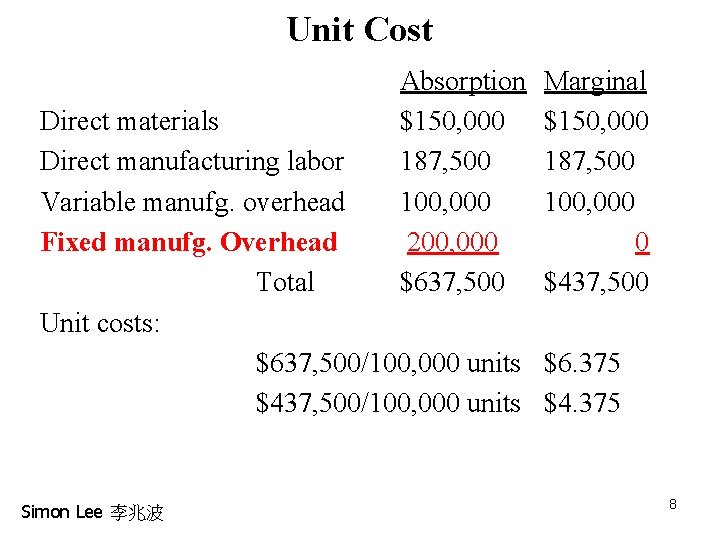
Unit Cost Absorption $150, 000 187, 500 100, 000 200, 000 $637, 500 Marginal $150, 000 187, 500 100, 000 0 $437, 500 Direct materials Direct manufacturing labor Variable manufg. overhead Fixed manufg. Overhead Total Unit costs: $637, 500/100, 000 units $6. 375 $437, 500/100, 000 units $4. 375 Simon Lee 李兆波 8
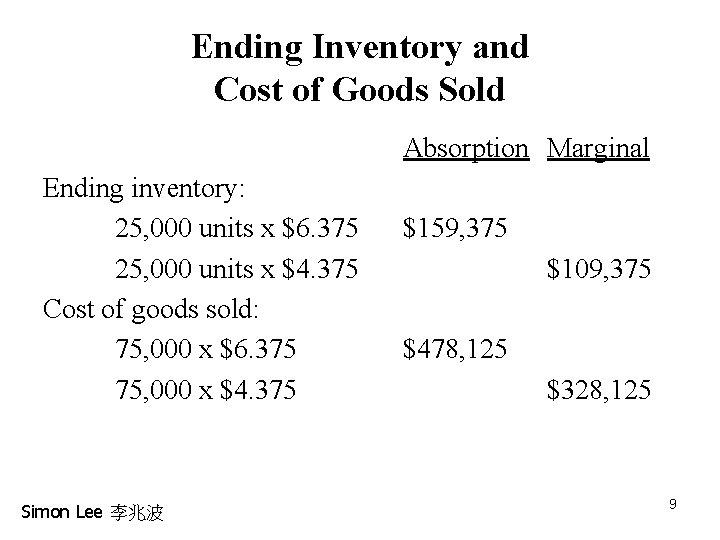
Ending Inventory and Cost of Goods Sold Absorption Marginal Ending inventory: 25, 000 units x $6. 375 25, 000 units x $4. 375 Cost of goods sold: 75, 000 x $6. 375 75, 000 x $4. 375 Simon Lee 李兆波 $159, 375 $109, 375 $478, 125 $328, 125 9
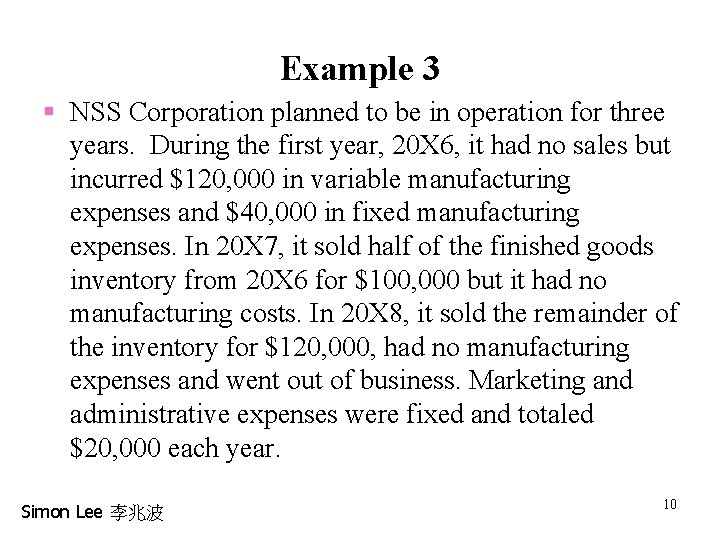
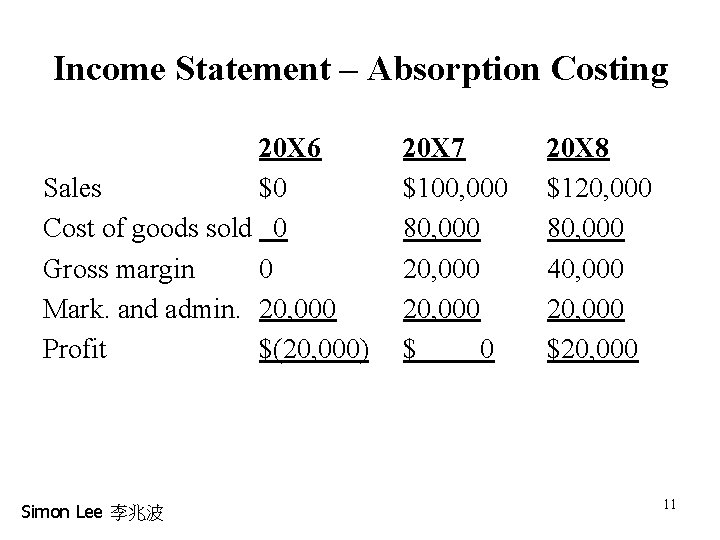
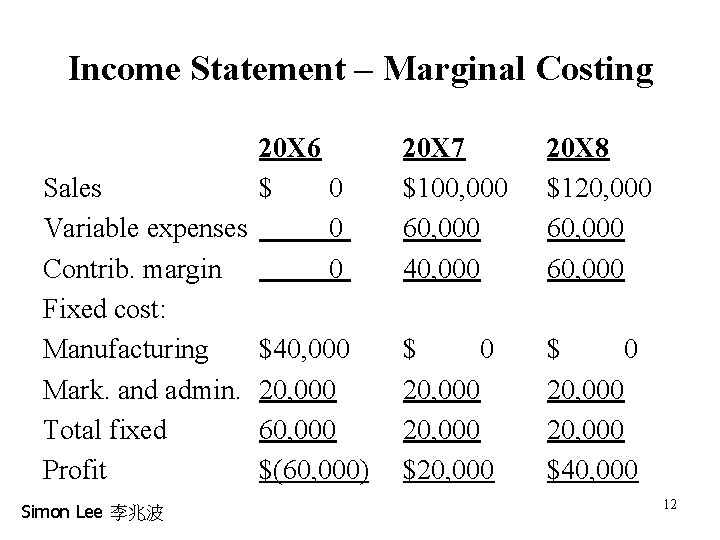
Example 3 § NSS Corporation planned to be in operation for three years. During the first year, 20 X 6, it had no sales but incurred $120, 000 in variable manufacturing expenses and $40, 000 in fixed manufacturing expenses. In 20 X 7, it sold half of the finished goods inventory from 20 X 6 for $100, 000 but it had no manufacturing costs. In 20 X 8, it sold the remainder of the inventory for $120, 000, had no manufacturing expenses and went out of business. Marketing and administrative expenses were fixed and totaled $20, 000 each year. Simon Lee 李兆波 10
Income Statement – Absorption Costing 20 X 6 Sales $0 Cost of goods sold 0 Gross margin 0 Mark. and admin. 20, 000 Profit $(20, 000) Simon Lee 李兆波 20 X 7 $100, 000 80, 000 20, 000 $ 0 20 X 8 $120, 000 80, 000 40, 000 20, 000 $20, 000 11
Income Statement – Marginal Costing 20 X 6 Sales $ 0 Variable expenses 0 Contrib. margin 0 Fixed cost: Manufacturing $40, 000 Mark. and admin. 20, 000 Total fixed 60, 000 Profit $(60, 000) Simon Lee 李兆波 20 X 7 $100, 000 60, 000 40, 000 20 X 8 $120, 000 60, 000 $ 0 20, 000 $20, 000 $ 0 20, 000 $40, 000 12
Simon Lee 李兆波 13
Simon Lee 李兆波 14
Source: Amazon. com Simon Lee 李兆波 15