
Mandatory Disclosure DAC 6 A Polish experience Amsterdam
- Slides: 30
Mandatory Disclosure (DAC 6) A Polish experience Amsterdam, the Netherlands 16 December 2019 12 Świętokrzyska St. 00 -916 Warsaw tel. : +48 22 123 45 67 fax : +48 22 123 45 67 gov. pl/finanse
DAC 6 – the next step in administrative cooperation DAC 5 DAC 1 DAC 3 DAC 2 DAC 6 DAC 4
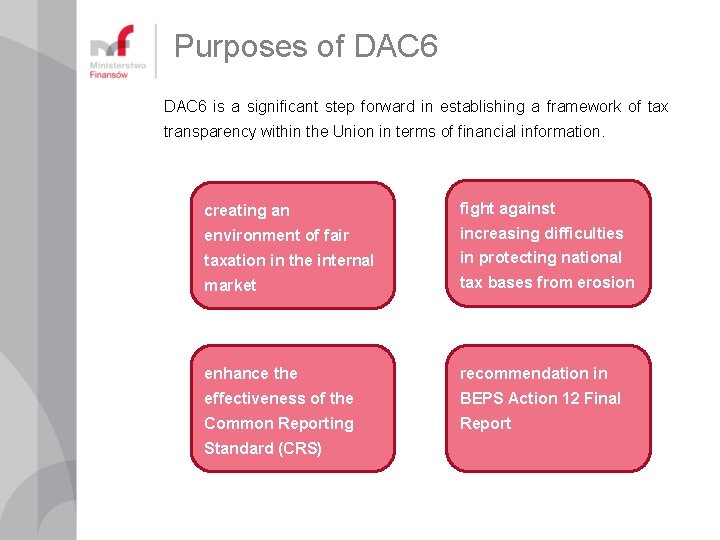
Purposes of DAC 6 is a significant step forward in establishing a framework of tax transparency within the Union in terms of financial information. creating an fight against environment of fair increasing difficulties taxation in the internal in protecting national market tax bases from erosion enhance the recommendation in effectiveness of the BEPS Action 12 Final Common Reporting Report Standard (CRS)
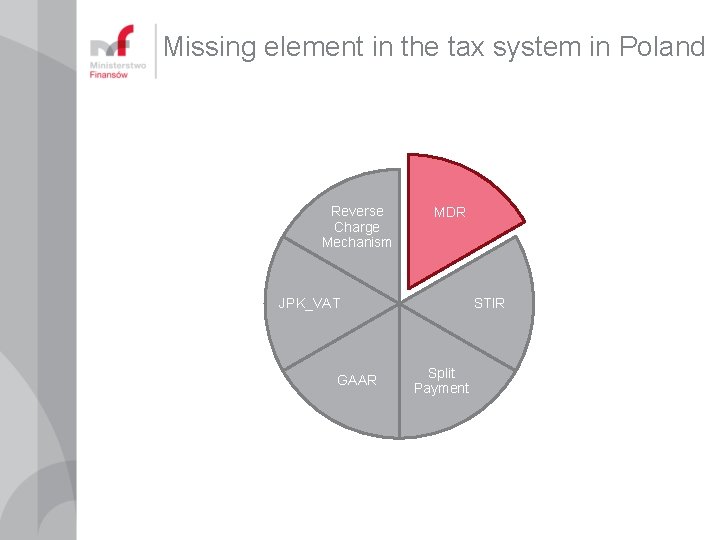
Missing element in the tax system in Poland Reverse Charge Mechanism MDR JPK_VAT GAAR STIR Split Payment
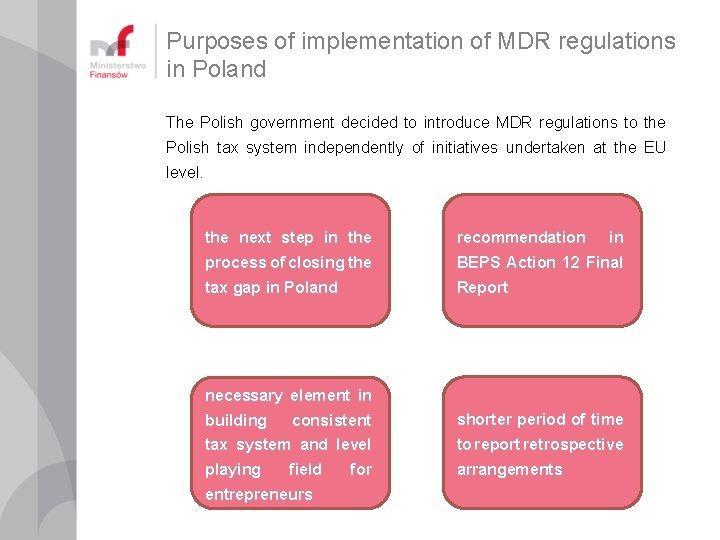
Purposes of implementation of MDR regulations in Poland The Polish government decided to introduce MDR regulations to the Polish tax system independently of initiatives undertaken at the EU level. the next step in the recommendation process of closing the BEPS Action 12 Final tax gap in Poland Report in necessary element in consistent shorter period of time tax system and level to report retrospective playing arrangements building field entrepreneurs for
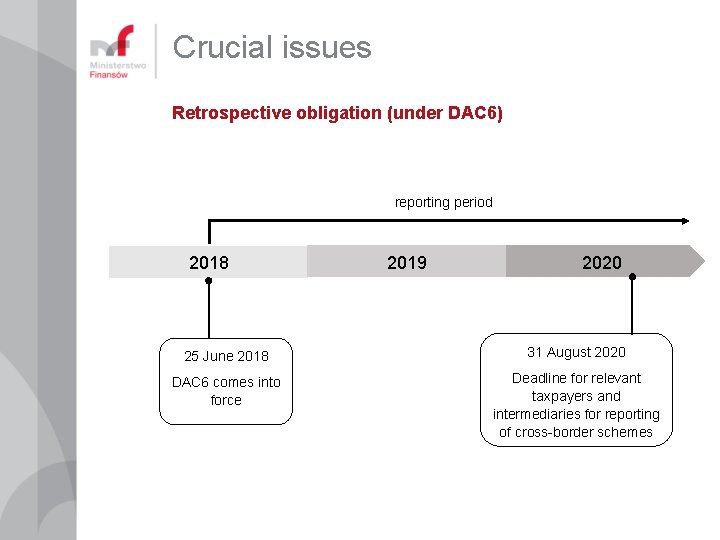
Crucial issues Retrospective obligation (under DAC 6) reporting period 2018 2019 2020 25 June 2018 31 August 2020 DAC 6 comes into force Deadline for relevant taxpayers and intermediaries for reporting of cross-border schemes
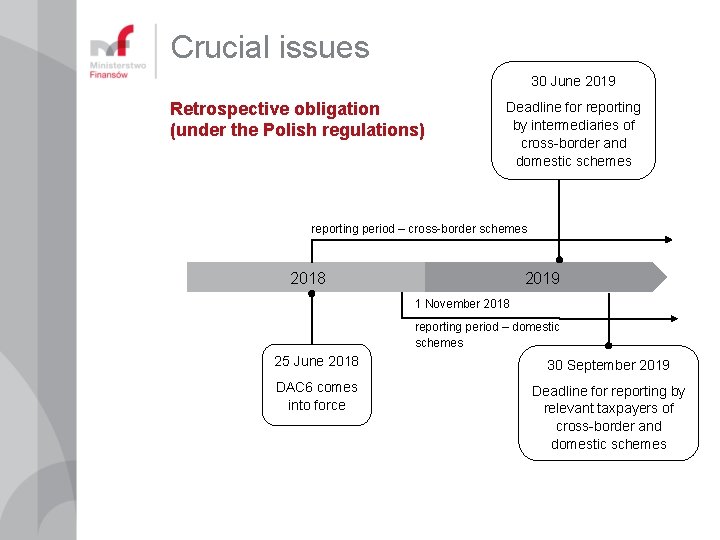
Crucial issues 30 June 2019 Retrospective obligation (under the Polish regulations) Deadline for reporting by intermediaries of cross-border and domestic schemes reporting period – cross-border schemes 2018 2019 1 November 2018 reporting period – domestic schemes 25 June 2018 30 September 2019 DAC 6 comes into force Deadline for reporting by relevant taxpayers of cross-border and domestic schemes
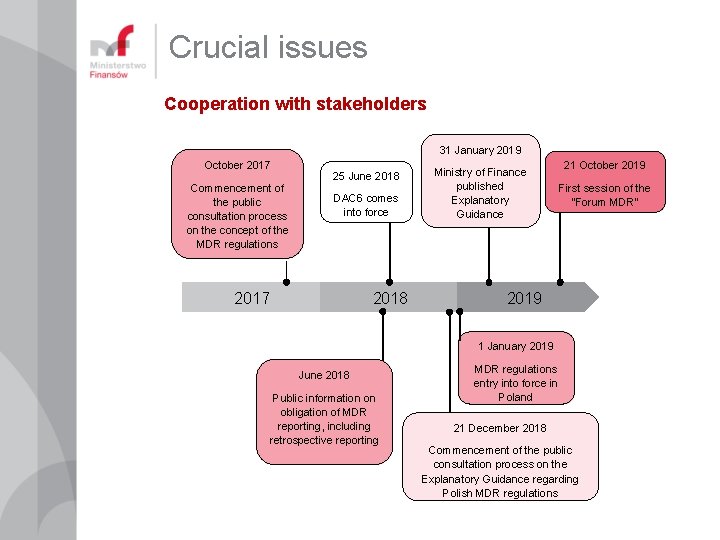
Crucial issues Cooperation with stakeholders The process of implementation of the MDR regulations in Poland – openness for discussion: • multi-stage public consultation on the concepts of the Polish MDR regulations and legislative projects in this respect, • issuance of the Explanatory Guidance of the Minister of Finance dated on January 31, 2019, • commencement of the „Forum MDR” initiative in October 2019.
Crucial issues Cooperation with stakeholders 31 January 2019 October 2017 Commencement of the public consultation process on the concept of the MDR regulations 25 June 2018 DAC 6 comes into force Ministry of Finance published Explanatory Guidance 2018 2017 21 October 2019 First session of the "Forum MDR” 2019 1 January 2019 June 2018 Public information on obligation of MDR reporting, including retrospective reporting MDR regulations entry into force in Poland 21 December 2018 Commencement of the public consultation process on the Explanatory Guidance regarding Polish MDR regulations
Crucial issues Cooperation with stakeholders Explanatory Guidance of The Minister of Finance clarifies various interpretation issues which may potentially arise within the proces of MDR reporting, eg. : • supporter (service provider) does not have an investigative duty – is not obliged to purchase data he does not possess, • intermediaries do not need to file an information on the tax schemes if another intermediary has already filed that information - provided that they received the NTS (NSP) number or, with respect to cross-border arrangements, they are able to prove that reporting obligation was fulfilled in the other member state, • if there is no commercial motive, there is no standarised (marketable) arrangement (i. e. publication of an article on an arrangement in the professional magazine by the professor)
Crucial issues Cooperation with stakeholders „Forum MDR” • iniciative of the Polish Ministry of Finance launched in October 2019, • involves ca. 200 representatives of commercial chambers, proffessional chambers, tax advisers, legal advisers, banks and other financial institutions, taxpayers, representatives of the local governmental units, • the tasks of the „Forum MDR” include developing and presenting to the Minister of Finance opinions, analyses, petitions and proposals regarding the improvement and sealing of the tax system in the scope of provisions relating to information on tax schemes, • there are 4 working groups established, which are referring to: • key definitions set out in the Polish MDR regulations, • the obligations of entities obliged to inform about tax schemes, • the impact of MDR regulations on the financial sector, • the subject of which will be the impact of MDR regulations on local governmental units.
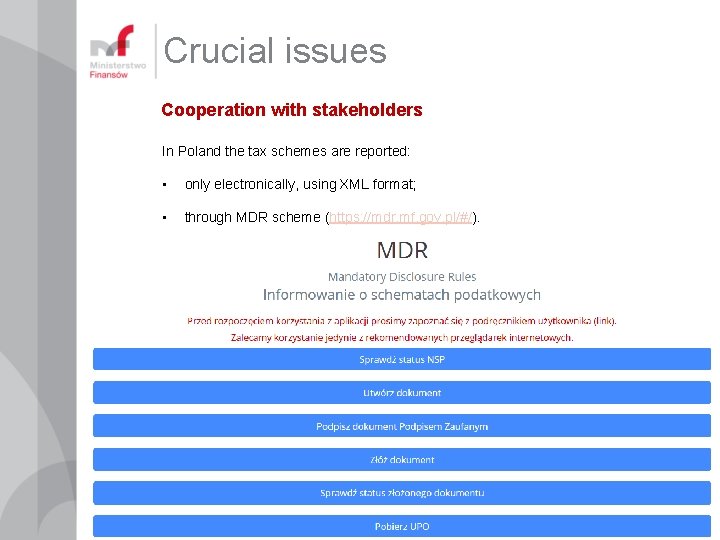
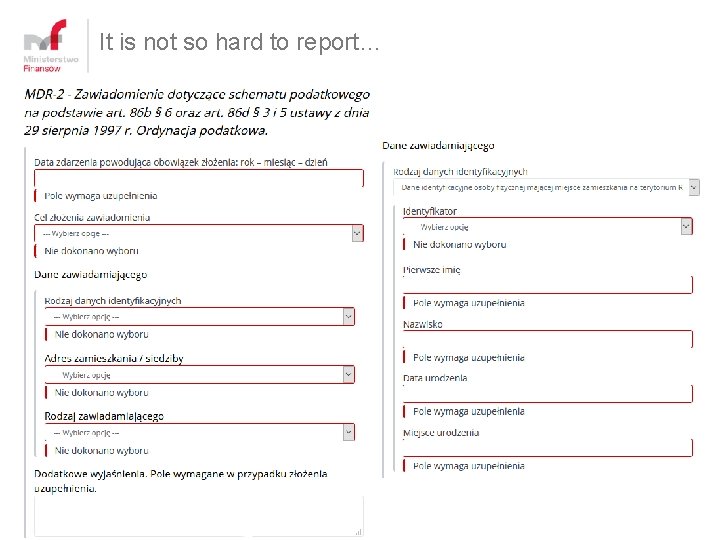
Crucial issues Cooperation with stakeholders In Poland the tax schemes are reported: • only electronically, using XML format; • through MDR scheme (https: //mdr. mf. gov. pl/#/).
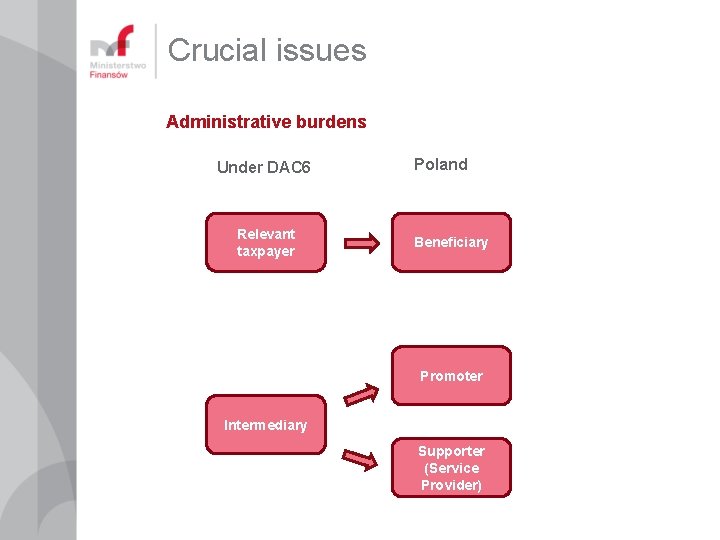
Crucial issues Administrative burdens Under DAC 6 Relevant taxpayer Poland Beneficiary Promoter Intermediary Supporter (Service Provider)
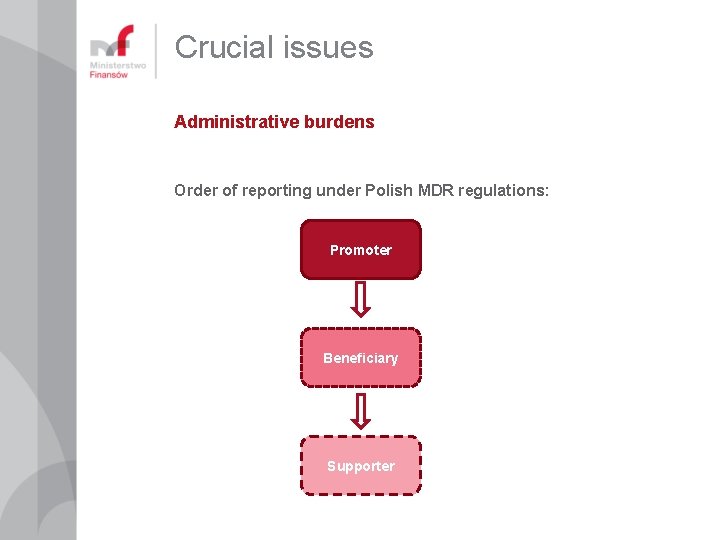
Crucial issues Administrative burdens Order of reporting under Polish MDR regulations: Promoter Beneficiary Supporter
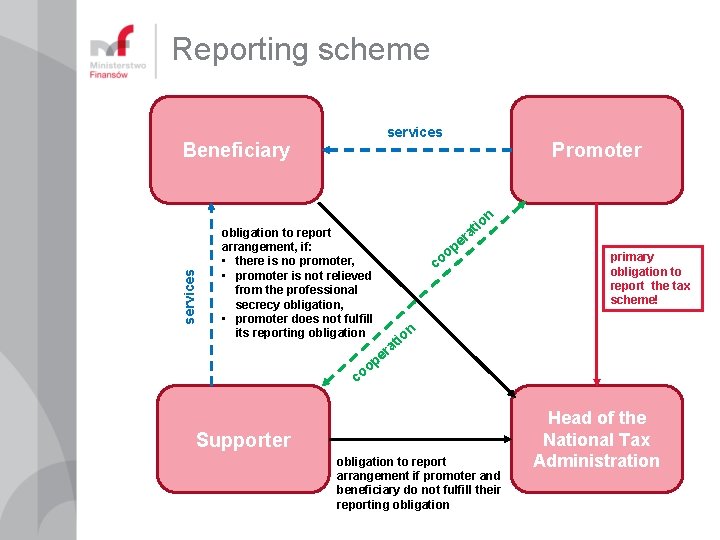
Reporting scheme services Beneficiary Promoter services n obligation to report arrangement, if: • there is no promoter, • promoter is not relieved from the professional secrecy obligation, • promoter does not fulfill its reporting obligation io at co co er p o primary obligation to report the tax scheme! n io at er p o Supporter obligation to report arrangement if promoter and beneficiary do not fulfill their reporting obligation Head of the National Tax Administration
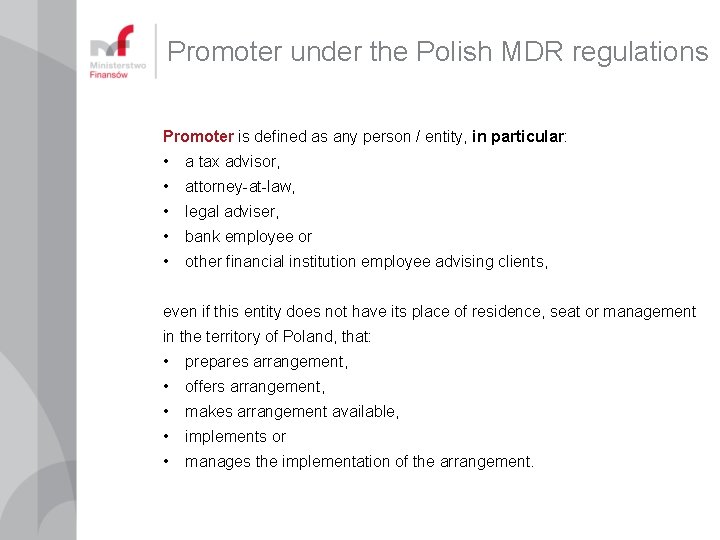
Promoter under the Polish MDR regulations Promoter is defined as any person / entity, in particular: • a tax advisor, • attorney-at-law, • legal adviser, • bank employee or • other financial institution employee advising clients, even if this entity does not have its place of residence, seat or management in the territory of Poland, that: • prepares arrangement, • offers arrangement, • makes arrangement available, • implements or • manages the implementation of the arrangement.
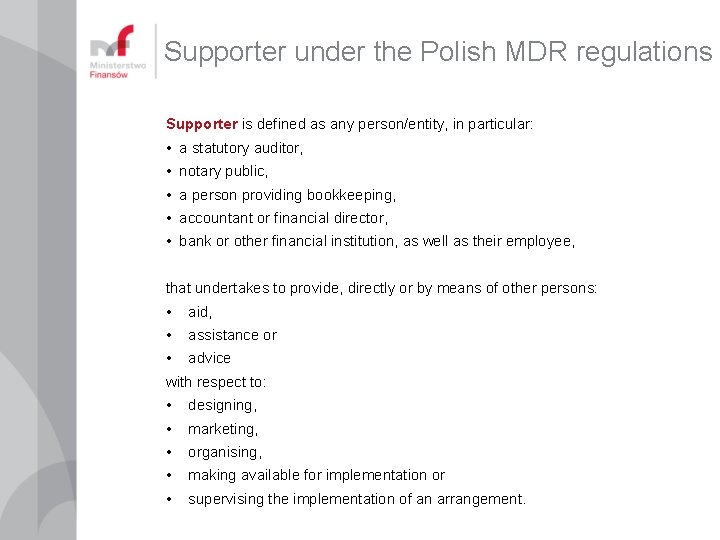
Supporter under the Polish MDR regulations Supporter is defined as any person/entity, in particular: • a statutory auditor, • notary public, • a person providing bookkeeping, • accountant or financial director, • bank or other financial institution, as well as their employee, that undertakes to provide, directly or by means of other persons: • aid, • assistance or • advice with respect to: • designing, • marketing, • organising, • making available for implementation or • supervising the implementation of an arrangement.
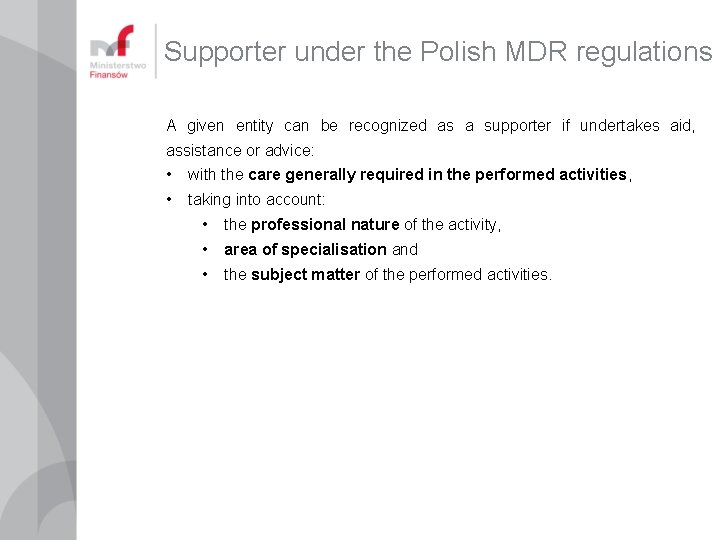
Supporter under the Polish MDR regulations A given entity can be recognized as a supporter if undertakes aid, assistance or advice: • with the care generally required in the performed activities, • taking into account: • the professional nature of the activity, • area of specialisation and • the subject matter of the performed activities.
It is not so hard to report…
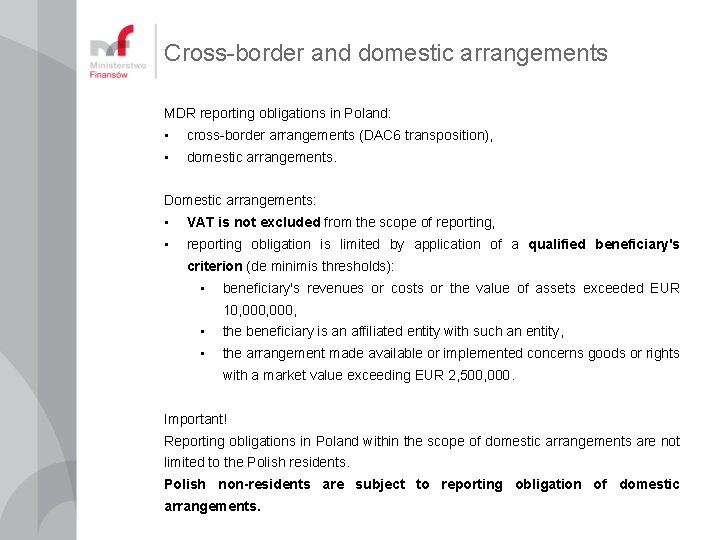
Cross-border and domestic arrangements MDR reporting obligations in Poland: • cross-border arrangements (DAC 6 transposition), • domestic arrangements. Domestic arrangements: • VAT is not excluded from the scope of reporting, • reporting obligation is limited by application of a qualified beneficiary's criterion (de minimis thresholds): • beneficiary's revenues or costs or the value of assets exceeded EUR 10, 000, • the beneficiary is an affiliated entity with such an entity, • the arrangement made available or implemented concerns goods or rights with a market value exceeding EUR 2, 500, 000. Important! Reporting obligations in Poland within the scope of domestic arrangements are not limited to the Polish residents. Polish non-residents are subject to reporting obligation of domestic arrangements.
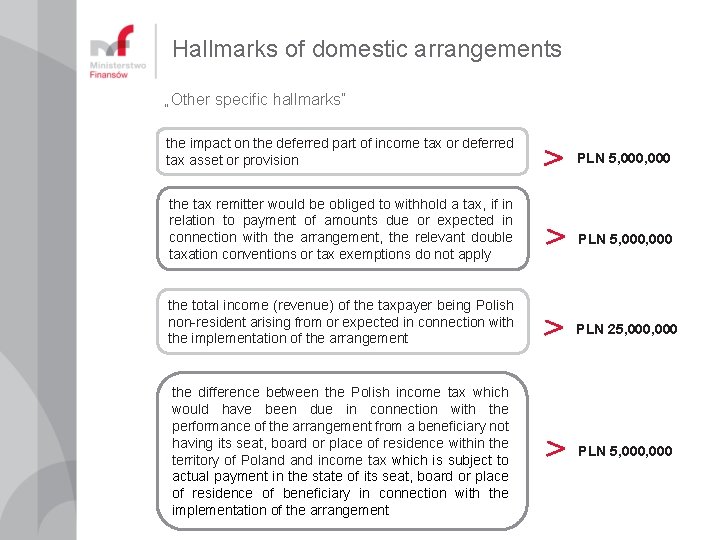
Hallmarks of domestic arrangements „Other specific hallmarks” the impact on the deferred part of income tax or deferred tax asset or provision the tax remitter would be obliged to withhold a tax, if in relation to payment of amounts due or expected in connection with the arrangement, the relevant double taxation conventions or tax exemptions do not apply the total income (revenue) of the taxpayer being Polish non-resident arising from or expected in connection with the implementation of the arrangement the difference between the Polish income tax which would have been due in connection with the performance of the arrangement from a beneficiary not having its seat, board or place of residence within the territory of Poland income tax which is subject to actual payment in the state of its seat, board or place of residence of beneficiary in connection with the implementation of the arrangement PLN 5, 000, 000 PLN 25, 000 PLN 5, 000
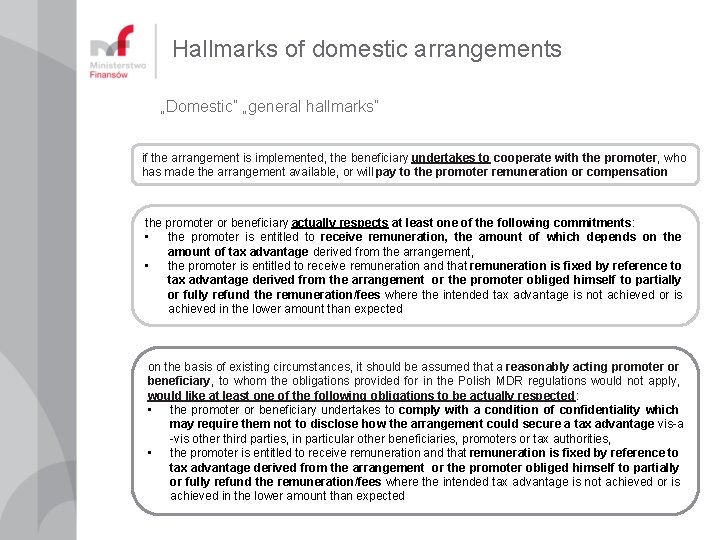
Hallmarks of domestic arrangements „Domestic” „general hallmarks” if the arrangement is implemented, the beneficiary undertakes to cooperate with the promoter, who has made the arrangement available, or will pay to the promoter remuneration or compensation the promoter or beneficiary actually respects at least one of the following commitments: • the promoter is entitled to receive remuneration, the amount of which depends on the amount of tax advantage derived from the arrangement, • the promoter is entitled to receive remuneration and that remuneration is fixed by reference to tax advantage derived from the arrangement or the promoter obliged himself to partially or fully refund the remuneration/fees where the intended tax advantage is not achieved or is achieved in the lower amount than expected on the basis of existing circumstances, it should be assumed that a reasonably acting promoter or beneficiary, to whom the obligations provided for in the Polish MDR regulations would not apply, would like at least one of the following obligations to be actually respected: • the promoter or beneficiary undertakes to comply with a condition of confidentiality which may require them not to disclose how the arrangement could secure a tax advantage vis-a -vis other third parties, in particular other beneficiaries, promoters or tax authorities, • the promoter is entitled to receive remuneration and that remuneration is fixed by reference to tax advantage derived from the arrangement or the promoter obliged himself to partially or fully refund the remuneration/fees where the intended tax advantage is not achieved or is achieved in the lower amount than expected
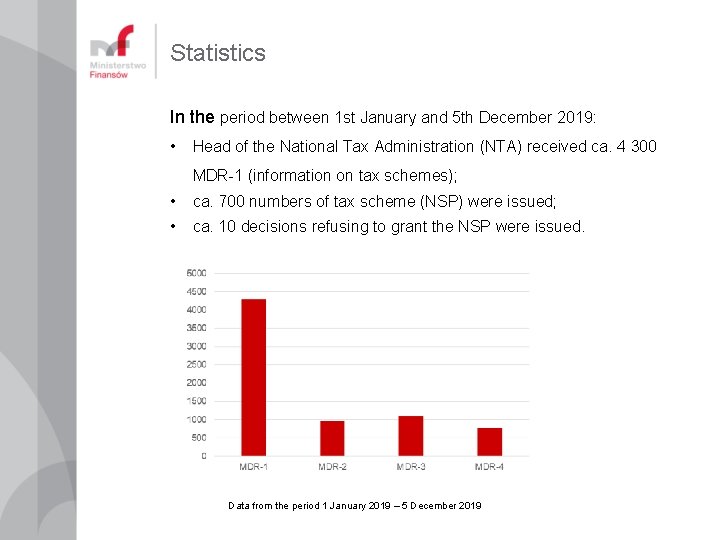
Statistics In the period between 1 st January and 5 th December 2019: • Head of the National Tax Administration (NTA) received ca. 4 300 MDR-1 (information on tax schemes); • ca. 700 numbers of tax scheme (NSP) were issued; • ca. 10 decisions refusing to grant the NSP were issued. Data from the period 1 January 2019 – 5 December 2019
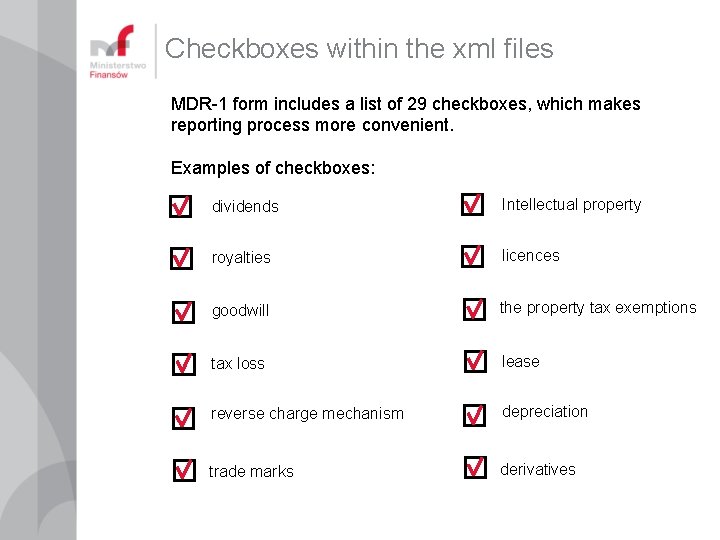
Checkboxes within the xml files MDR-1 form includes a list of 29 checkboxes, which makes reporting process more convenient. Examples of checkboxes: dividends Intellectual property royalties licences goodwill the property tax exemptions tax loss lease reverse charge mechanism depreciation trade marks derivatives
Crucial issues Professional secrecy Under DAC 6 The reporting obligation of is not enforceable upon the taxpayer who benefits an intermediary due to a from the arrangement legal professional privilege
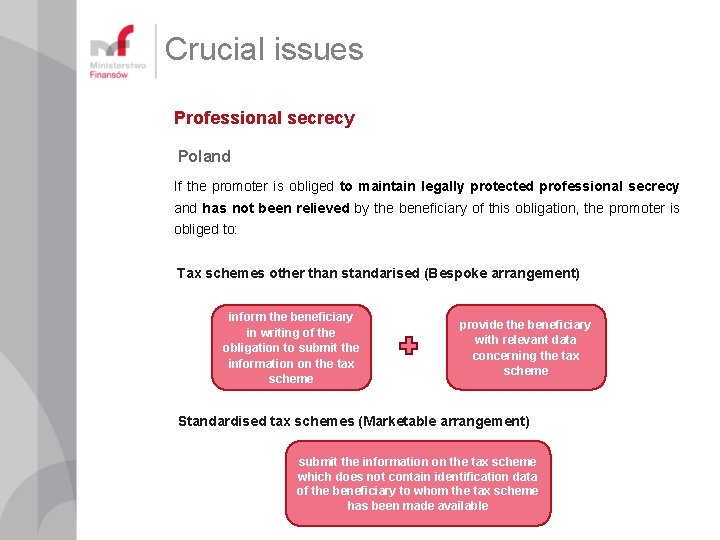
Crucial issues Professional secrecy Poland If the promoter is obliged to maintain legally protected professional secrecy and has not been relieved by the beneficiary of this obligation, the promoter is obliged to: Tax schemes other than standarised (Bespoke arrangement) inform the beneficiary in writing of the obligation to submit the information on the tax scheme provide the beneficiary with relevant data concerning the tax scheme Standardised tax schemes (Marketable arrangement) submit the information on the tax scheme which does not contain identification data of the beneficiary to whom the tax scheme has been made available
Crucial issues Penalties Under DAC 6 In order to improve the prospects for the effectiveness of the Directive, Member States should lay down penalties against the violation of national rules that implement Directive. Penalties should be: • effective, • proportionate and • dissuasive.
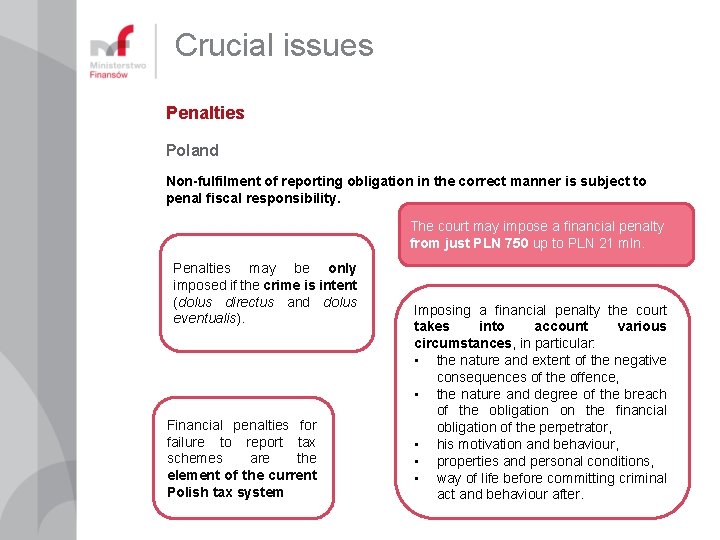
Crucial issues Penalties Poland Non-fulfilment of reporting obligation in the correct manner is subject to penal fiscal responsibility. The court may impose a financial penalty from just PLN 750 up to PLN 21 mln. Penalties may be only imposed if the crime is intent (dolus directus and dolus eventualis). Financial penalties for failure to report tax schemes are the element of the current Polish tax system Imposing a financial penalty the court takes into account various circumstances, in particular: • the nature and extent of the negative consequences of the offence, • the nature and degree of the breach of the obligation on the financial obligation of the perpetrator, • his motivation and behaviour, • properties and personal conditions, • way of life before committing criminal act and behaviour after.
Crucial issues An individual acting on behalf on intermediary (promoter, supporter) or beneficiary may be independently recognized as an intermediary. Responsibility for fulfilling the MDR reporting obligations lays on the entity being intermediary (promoter, supporter) or beneficiary as well as individual functionally responsible for the advisory service, „project” etc. In that case, there will be more than one entity responsible for MDR reporting. However, intermediaries do not need to file an information on the tax schemes if another intermediary has already filed that information on the tax scheme (provided that further formal conditions are met).
Contact details Konrad Kurpiewski Head of Division Information on Tax Schemes Division Tax System Department Ministry of Finance tel. : +48 22 694 5108 e-mail : konrad. kurpiewski@mf. gov. pl