
Maintaining Financial Records FA 2 B Amrith Thilan
Maintaining Financial Records FA 2 B Amrith Thilan B. B. A, ACCA Passed Finalist
ACCA - Maintaining Financial Records (FA 2) Non Current Assets • Non Current Assets refers to items such as machinery, equipment, premises and motor vehicles. • These assets lasts for several accounting periods • Non Current Assets are not frequently bought and sold. • These assets are used by the business to carry on it’s operations • Non Current Assets are of two types ; Tangible and Intangible
ACCA - Maintaining Financial Records (FA 2) Capital and Revenue Expenditure Capital Expenditure • Capital Expenditure is the purchase on noncurrent asset or expenditure to enhance their earning ability. • Capital Expenditure results in non-current assets and these will appear in the statement of financial position. • Examples of Capital Expenditure include purchase of a computer, purchase of factory machinery, upgrading a computer by adding a larger hard disk.
ACCA - Maintaining Financial Records (FA 2) Capital and Revenue Expenditure • Revenue expenditure is expenditure incurred for the purpose of the trade of the business or for maintaining the earning ability of non-current assets. • Revenue expenditure is another term for business expenses and will appear on income statement. • Examples of Revenue Expenditure include wages , rent, electricity, interest and electricity.
ACCA - Maintaining Financial Records (FA 2) Depreciation • Although Non current Assets last for several accounting periods, most wear out. • All tangible assets (except for land) wear out and will be eventually be scrapped our sold for a second hand value. • The term given to loss of value of tangibles assets is depreciation. • Depreciation is an accounting method of allocating the cost of a tangible asset over it’s useful life. • Business depreciate long term assets for both tax and accounting purposes. • For leases, the term amortisation is used instead of depreciation.
ACCA - Maintaining Financial Records (FA 2) Test Your Understanding Which of the following item is an example of Intangible Asset ? A. B. C. D. Motor Vehicle Copyright Machinery Power Plant
ACCA - Maintaining Financial Records (FA 2) Test Your Understanding Which of the following item is an example of Capital Expenditure ? A. B. C. D. Motor Vehicle Rent Wages Electricity. Z
ACCA - Maintaining Financial Records (FA 2) Test Your Understanding The term given to the ‘‘process of tangible assets losing it’s value as it gets older’’ is : A. B. C. D. Amortisation Goodwill Depreciation Value for Money
ACCA - Maintaining Financial Records (FA 2) Methods of Depreciation There are two main types of depreciation used in financial statements : Straight Line Method • Straight line method charges cost evenly throughout the useful life of a fixed asset. • This depreciation method is appropriate where economic benefits from an asset are expected to be realized evenly over it’s useful life. • Formula : • Depreciation per annum = (Cost – Residual Value) / Useful Life • Depreciation per annum = (Cost – Residual Value) / Rate of Depreciation
ACCA - Maintaining Financial Records (FA 2) Methods of Depreciation Reducing Balance Method • Reducing Balance method charges depreciation at a higher rate in the earlier years of an asset. The amount of depreciation reduces as the life of the asset progresses. • Depreciation under this method can be calculated as follows : • Depreciation Per annum = (Net Book Value – Residual Value) x Rate % • Under reducing balance method depreciation for the last year of the asset’s useful life is the difference between net book value at the start of the period and the estimated residual value.
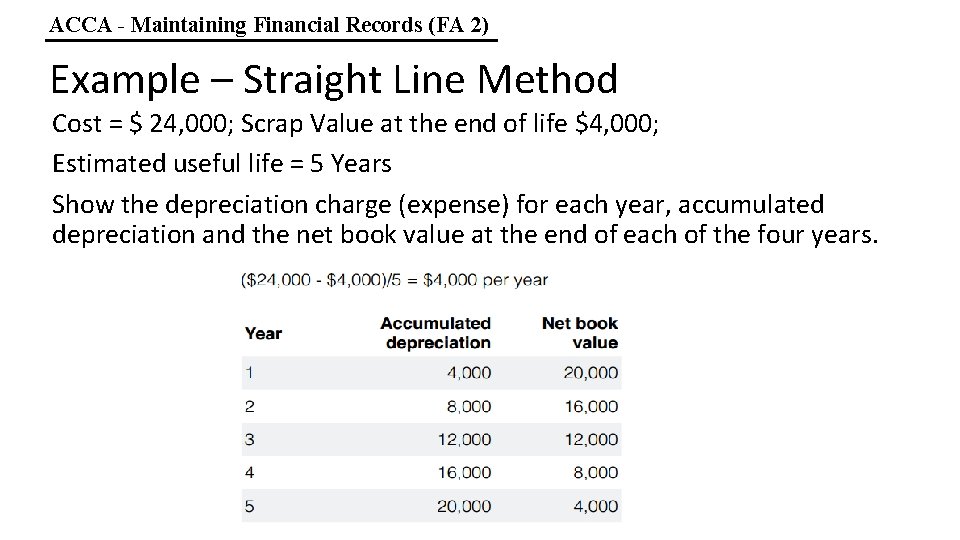
ACCA - Maintaining Financial Records (FA 2) Example – Straight Line Method Cost = $ 24, 000; Scrap Value at the end of life $4, 000; Estimated useful life = 5 Years Show the depreciation charge (expense) for each year, accumulated depreciation and the net book value at the end of each of the four years.
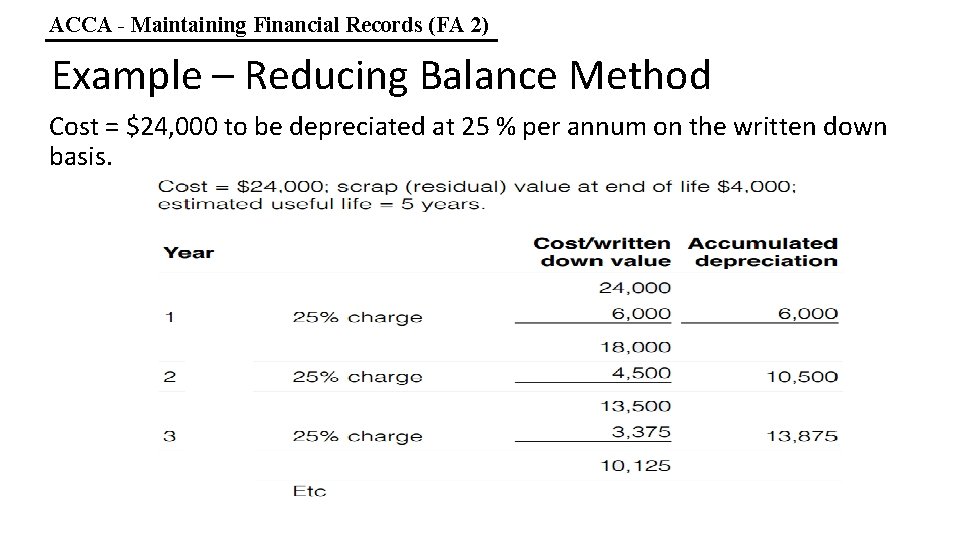
ACCA - Maintaining Financial Records (FA 2) Example – Reducing Balance Method Cost = $24, 000 to be depreciated at 25 % per annum on the written down basis.
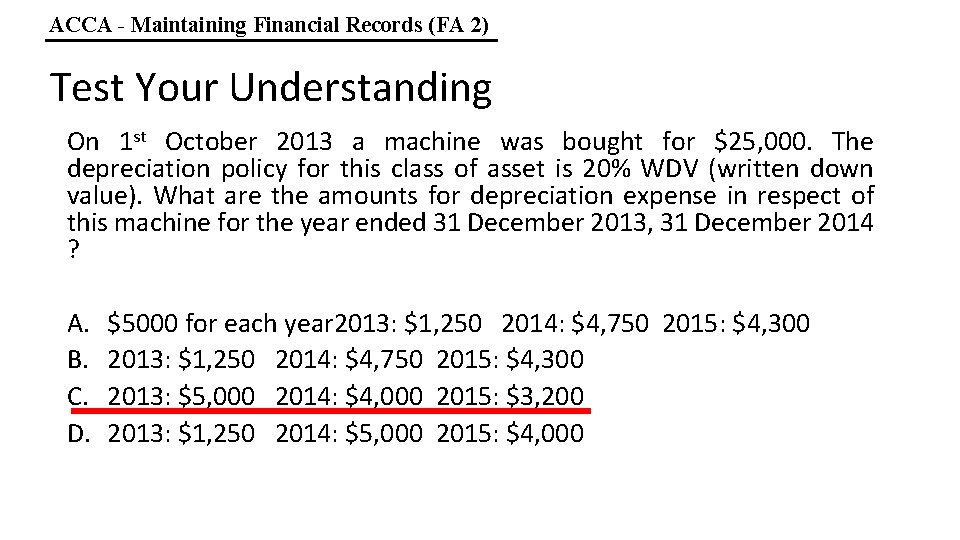
ACCA - Maintaining Financial Records (FA 2) Test Your Understanding On 1 st October 2013 a machine was bought for $25, 000. The depreciation policy for this class of asset is 20% WDV (written down value). What are the amounts for depreciation expense in respect of this machine for the year ended 31 December 2013, 31 December 2014 ? A. B. C. D. $5000 for each year 2013: $1, 250 2014: $4, 750 2015: $4, 300 2013: $5, 000 2014: $4, 000 2015: $3, 200 2013: $1, 250 2014: $5, 000 2015: $4, 000
Maintaining Financial Records FA 2 B Amrith Thilan B. B. A, ACCA Passed Finalist
- Slides: 14