
Maintaining Financial Records FA 2 B Amrith Thilan
Maintaining Financial Records FA 2 B Amrith Thilan B. B. A, ACCA Passed Finalist
ACCA - Maintaining Financial Records (FA 2) Accruals and Prepayments Financial statements are prepared under the Accruals Basis of accounting which requires that income and expense must be recognized in the accounting periods to which they relate rather than on cash basis.
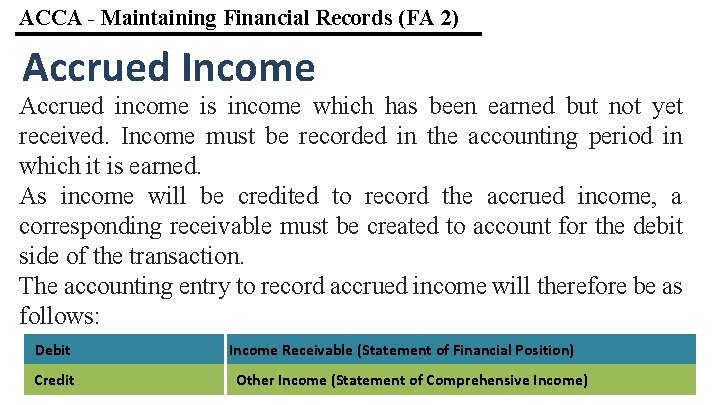
ACCA - Maintaining Financial Records (FA 2) Accrued Income Accrued income is income which has been earned but not yet received. Income must be recorded in the accounting period in which it is earned. As income will be credited to record the accrued income, a corresponding receivable must be created to account for the debit side of the transaction. The accounting entry to record accrued income will therefore be as follows: Debit Credit Income Receivable (Statement of Financial Position) Other Income (Statement of Comprehensive Income)
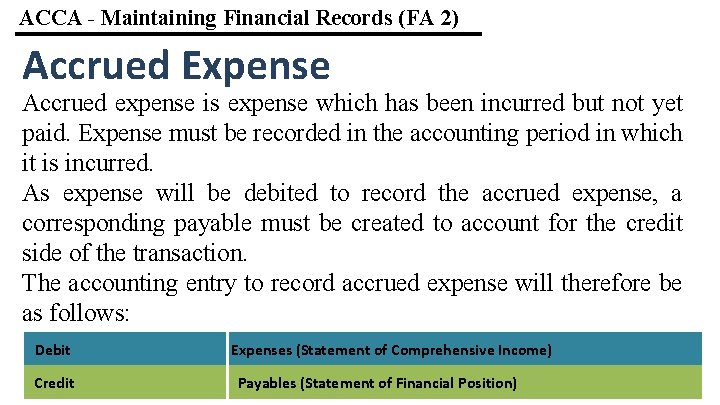
ACCA - Maintaining Financial Records (FA 2) Accrued Expense Accrued expense is expense which has been incurred but not yet paid. Expense must be recorded in the accounting period in which it is incurred. As expense will be debited to record the accrued expense, a corresponding payable must be created to account for the credit side of the transaction. The accounting entry to record accrued expense will therefore be as follows: Debit Credit Expenses (Statement of Comprehensive Income) Payables (Statement of Financial Position)
ACCA - Maintaining Financial Records (FA 2) Prepaid Income Prepaid income is revenue received in advance but which is not yet earned. Income must be recorded in the accounting period in which it is earned. Entity should therefore recognize a liability in respect of income it has received in advance until such time as the obligations or services that are due on its part in relation to the prepaid income have been performed. Following accounting entry is required to account for the prepaid income: Debit Cash/Bank (Statement of Financial Position) Credit Prepaid Income (Liability in Statement of Financial Position)
ACCA - Maintaining Financial Records (FA 2) Prepaid Expense Prepaid expense is expense paid in advance but which has not yet been incurred. Expense must be recorded in the accounting period in which it is incurred. Entity should therefore recognize an asset in respect of expense it has paid in advance until such time as the services that are due in relation to the prepaid expense have been performed by the suppliers/contractors. Following accounting entry is required to account for the prepaid expense: Debit Credit Prepaid Expense (Current Asset in Statement of Financial Position) Cash/Bank (Statement of Financial Position)
ACCA - Maintaining Financial Records (FA 2) Test Your Understanding An prepayment is an expense relating to the current accounting period. True or false? A. True B. False
ACCA - Maintaining Financial Records (FA 2) Test Your Understanding An accrual is an expense not yet paid for. True or false? A. True B. False
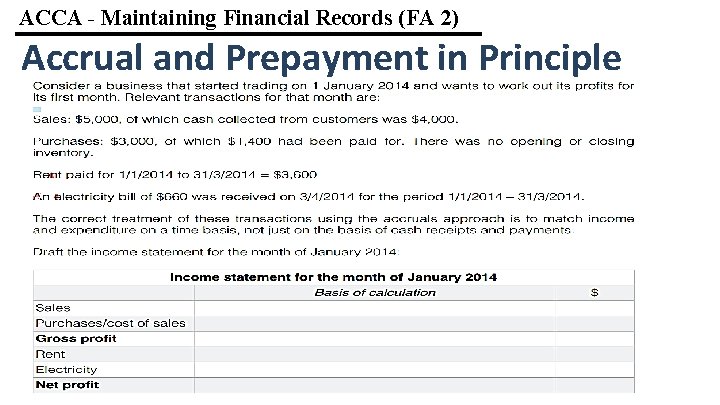
ACCA - Maintaining Financial Records (FA 2) Accrual and Prepayment in Principle
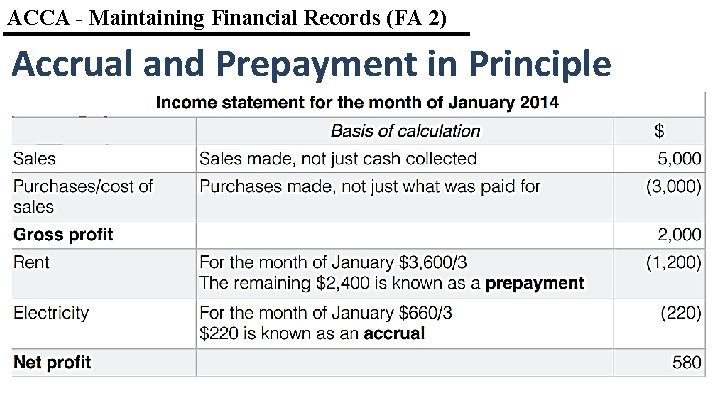
ACCA - Maintaining Financial Records (FA 2) Accrual and Prepayment in Principle
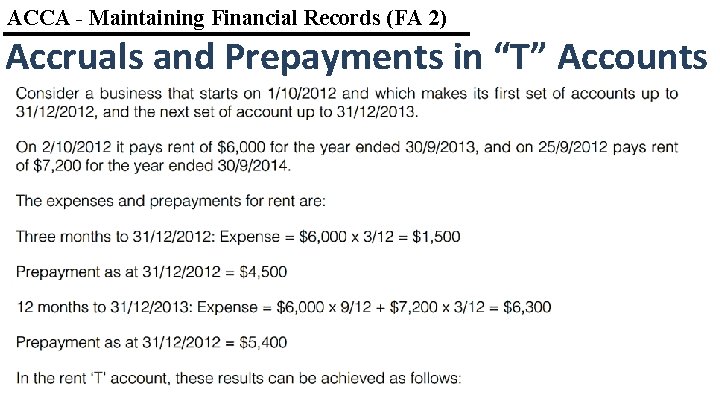
ACCA - Maintaining Financial Records (FA 2) Accruals and Prepayments in “T” Accounts
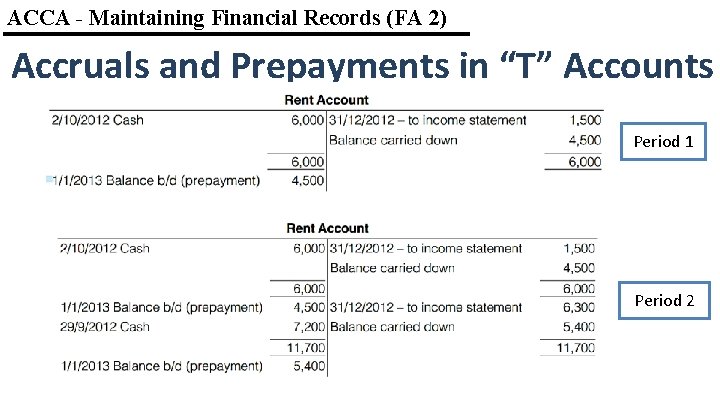
ACCA - Maintaining Financial Records (FA 2) Accruals and Prepayments in “T” Accounts Period 1 Period 2
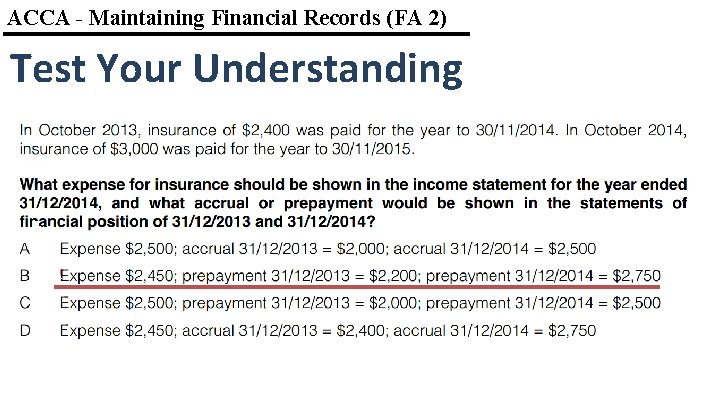
ACCA - Maintaining Financial Records (FA 2) Test Your Understanding
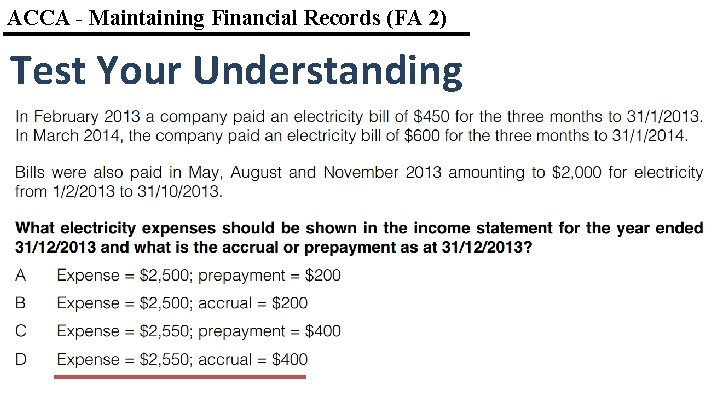
ACCA - Maintaining Financial Records (FA 2) Test Your Understanding
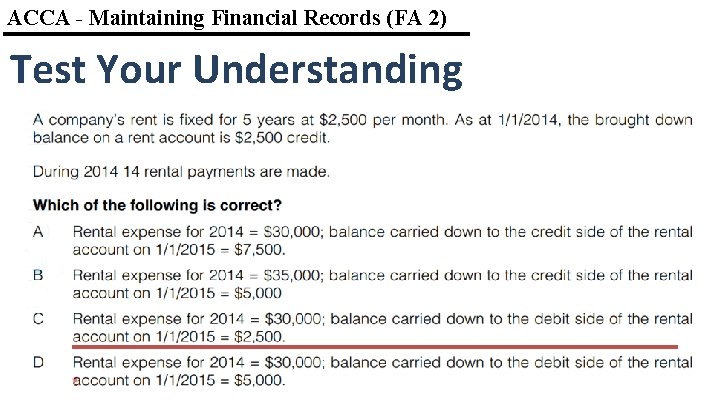
ACCA - Maintaining Financial Records (FA 2) Test Your Understanding
Maintaining Financial Records FA 2 B Amrith Thilan B. B. A, ACCA Passed Finalist
- Slides: 16