
LOUISIANA DEPT OF REVENUE FIELD AUDIT DIVISION 2015
- Slides: 42
LOUISIANA DEPT OF REVENUE “FIELD AUDIT DIVISION” 2015 LDR/TAX PRACTIONERS WORKSHOP Joseph Vaughn, Asst. Secretary, Group III Debbie Jenkins, Group III Executive Assistant Cynthia Pugh, Director – Audit Intelligence Team Darlene Allen, Director – FA Sales Tax Division Kevin Richard, Director – FA Income Tax Division Clarence Lymon, Director – FA Excise Tax Division Jay Frost, Director – Audit Review & Appeals Division
WHAT WE WILL DISCUSS TODAY • Field Audit case, production and collection stats; • Staff Count, locations • Use of Contract Auditors – stats • Voluntary Disclosure Program
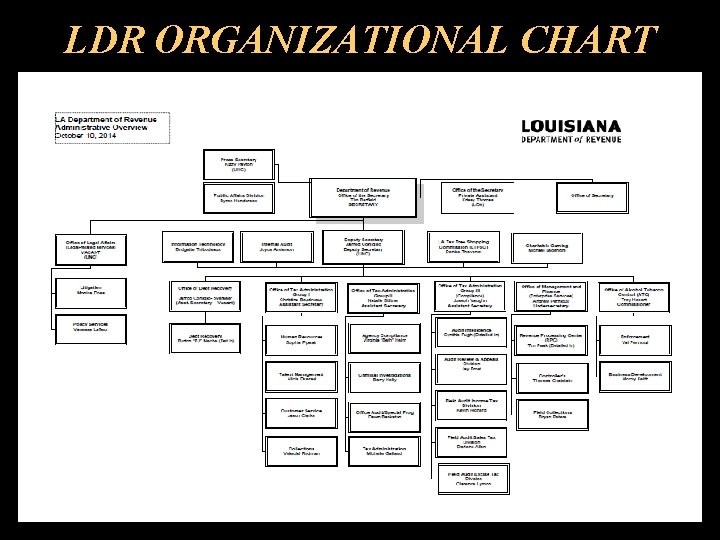
LDR ORGANIZATIONAL CHART
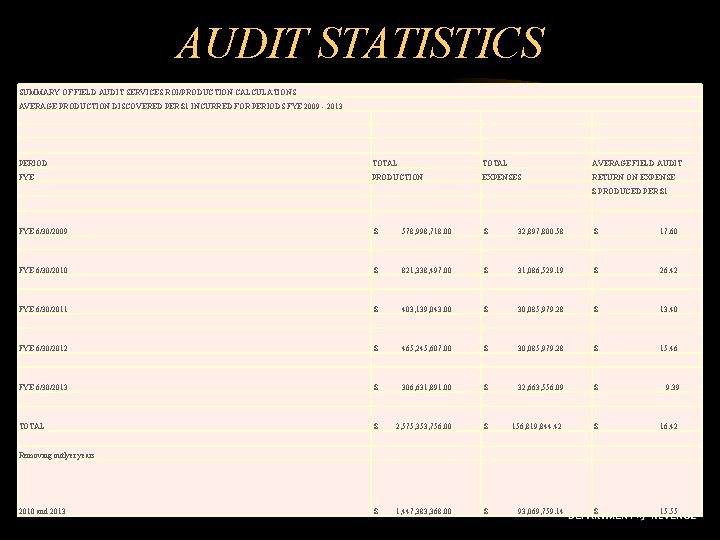
AUDIT STATISTICS SUMMARY OF FIELD AUDIT SERVICES ROI/PRODUCTION CALCULATIONS AVERAGE PRODUCTION DISCOVERED PER $1 INCURRED FOR PERIODS FYE 2009 - 2013 PERIOD TOTAL AVERAGE FIELD AUDIT FYE PRODUCTION EXPENSES RETURN ON EXPENSE $ PRODUCED PER $1 FYE 6/30/2009 $ 578, 998, 718. 00 $ 32, 897, 800. 58 $ 17. 60 FYE 6/30/2010 $ 821, 338, 497. 00 $ 31, 086, 529. 19 $ 26. 42 FYE 6/30/2011 $ 403, 139, 043. 00 $ 30, 085, 979. 28 $ 13. 40 FYE 6/30/2012 $ 465, 245, 607. 00 $ 30, 085, 979. 28 $ 15. 46 FYE 6/30/2013 $ 306, 631, 891. 00 $ 32, 663, 556. 09 $ 9. 39 TOTAL $ 2, 575, 353, 756. 00 $ 156, 819, 844. 42 $ 16. 42 Removing outlyer years 2010 and 2013 $ 1, 447, 383, 368. 00 $ 93, 069, 759. 14 $ 15. 55
AUDIT STATISTICS CONT.
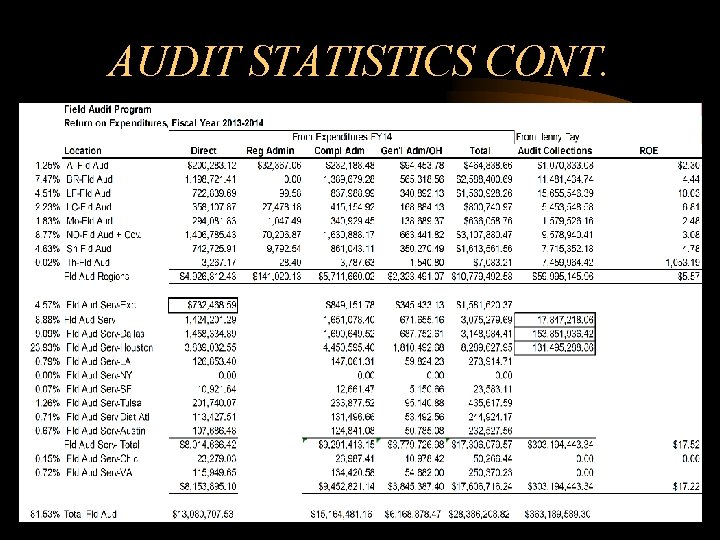
AUDIT STATISTICS CONT. The last five (2009 – 2013) years of Field Audit compliance activity has generated the following findings: – FIELD AUDIT • Number of field audits performed = 11, 270; • Total Collections = $1, 210, 897, 442. 33 • ROE = $7. 72 collected for each $1 spent. • FYE 2014: – Audit discoveries = $435, 178, 610. 02 – Audit Collections = $363, 189, 599. 30
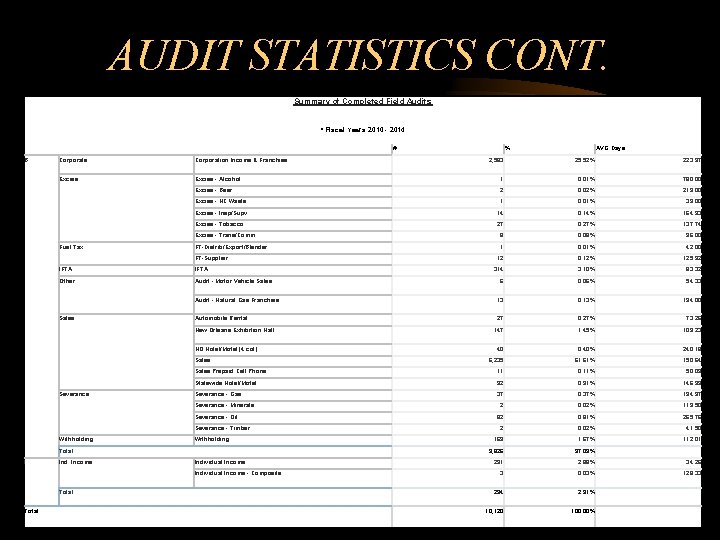
AUDIT STATISTICS CONT. Summary of Completed Field Audits * Fiscal Years 2010 - 2014 B # Corporate Corporation Income & Franchise Excise Fuel Tax 223. 97 Excise - Alcohol 1 0. 01% 780. 00 Excise - Beer 2 0. 02% 219. 00 Excise - HZ Waste 1 0. 01% 39. 00 Excise - Insp/Supv 14 0. 14% 164. 93 Excise - Tobacco 27 0. 27% 137. 74 Excise - Trans/Comm 8 0. 08% 96. 00 FT-Distrib/Export/Blender 1 0. 01% 42. 00 12 0. 12% 125. 92 314 3. 10% 83. 32 6 0. 06% 54. 33 13 0. 13% 194. 00 27 0. 27% 73. 26 147 1. 45% 109. 23 IFTA Other Audit - Motor Vehicle Sales Audit - Natural Gas Franchise Automobile Rental New Orleans Exhibition Hall NO Hotel/Motel (4 col) 40 0. 40% 240. 18 6, 235 61. 61% 150. 64 Sales Prepaid Cell Phone 11 0. 11% 50. 09 Statewide Hotel/Motel 92 0. 91% 146. 99 Severance - Gas 37 0. 37% 194. 97 2 0. 02% 119. 50 82 0. 81% 265. 76 2 0. 02% 41. 50 169 1. 67% 112. 01 9, 826 97. 09% 291 2. 88% 34. 26 3 0. 03% 128. 33 294 2. 91% 10, 120 100. 00% Sales Severance - Minerals Severance - Oil Severance - Timber Withholding Total I Ind. Income Individual Income - Composite Total AVG Days 25. 52% FT-Supplier Sales % 2, 583
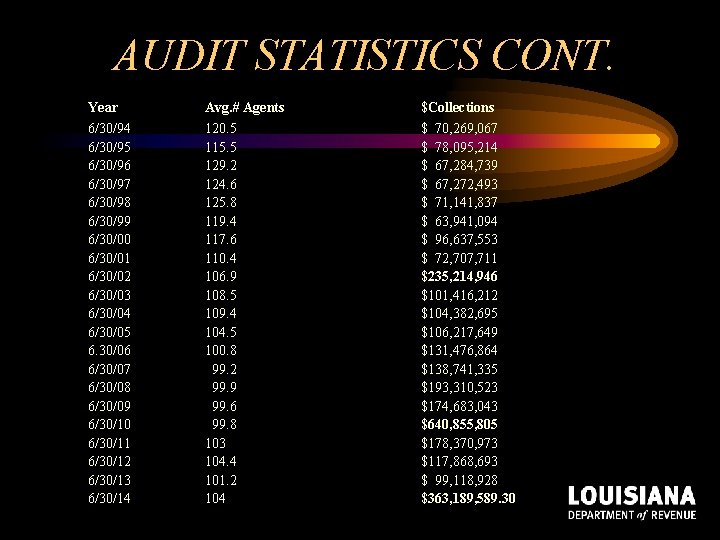
AUDIT STATISTICS CONT. Year Avg. # Agents $Collections 6/30/94 6/30/95 6/30/96 6/30/97 6/30/98 6/30/99 6/30/00 6/30/01 6/30/02 6/30/03 6/30/04 6/30/05 6. 30/06 6/30/07 6/30/08 6/30/09 6/30/10 6/30/11 6/30/12 6/30/13 6/30/14 120. 5 115. 5 129. 2 124. 6 125. 8 119. 4 117. 6 110. 4 106. 9 108. 5 109. 4 104. 5 100. 8 99. 2 99. 9 99. 6 99. 8 103 104. 4 101. 2 104 $ 70, 269, 067 $ 78, 095, 214 $ 67, 284, 739 $ 67, 272, 493 $ 71, 141, 837 $ 63, 941, 094 $ 96, 637, 553 $ 72, 707, 711 $235, 214, 946 $101, 416, 212 $104, 382, 695 $106, 217, 649 $131, 476, 864 $138, 741, 335 $193, 310, 523 $174, 683, 043 $640, 855, 805 $178, 370, 973 $117, 868, 693 $ 99, 118, 928 $363, 189, 589. 30
AUDIT STATISTICS CONCLUSION • FY Ending 6/30/15 – YTD thru 12/31/2014 – Audits Completed: 817. 0 – Audit Production: $154, 385, 219. 57 – Audit Collections: $80, 877, 096. 89
FIELD AUDIT DIVISION REORGANIZATION • Field Audit Operations were generally managed by one Director level manager; – Managed all headquarters and district field audit operations, as well as Audit Review and administrative staff. • Field Audit Operations were structured by geographic areas – Each geographic area was managed by an Audit Manager and Supervisors
FIELD AUDIT DIVISION PREREORGANIZATIONS CONT. • Field Auditors covered these geographic areas, and approached audits in “audit the taxpayer and not just the tax”. – Auditors are cross trained to have at least a minimum amount of training experience in all tax types.
FIELD AUDIT DIVISION PREREORGANIZATIONS CONT. • The result of this structure was: – One Director level manager responsible for the activities of 120 FAS staff; – Audit Management and staff that had to stretch their activities across all tax types; – A very narrow and deep structure that stretched our Field Audit staff that may be beyond their level of expertise. – A “reactive” more than a “proactive” audit program.
COMPLIANCE DIVISION REORGANIZATIONS CONT. • The Decision was made by the LDR Executive Team to reorganize both Divisions by “tax type”.
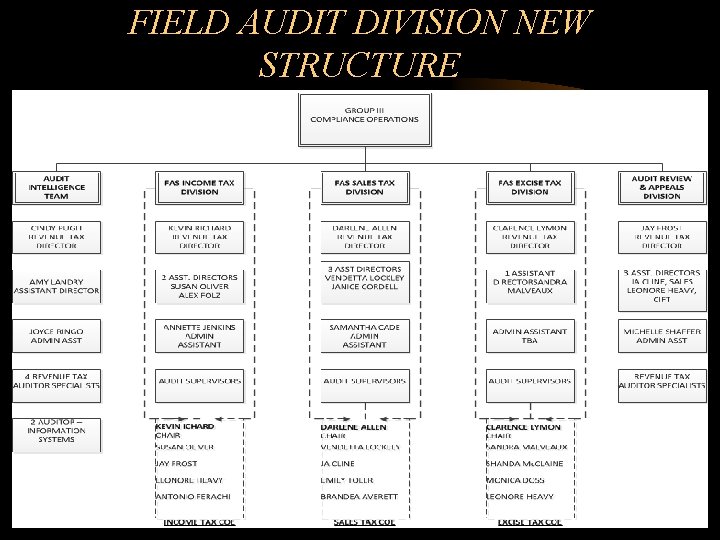
FIELD AUDIT DIVISION NEW STRUCTURE
FIELD AUDIT DIVISION POSTREORGANIZATION CONT. • Expected Results: – Director level emphasis on audit operations by specific tax type; – Flatter organizational structure; – Will allow Directors, Supervisors and managers to concentrate on one or two specific tax types resulting in subject matter experts with a deeper understanding of tax law and theory;
INCREASING COMPLIANCE STAFF • Approximately 48 positions have been added to the Compliance Divisions of LDR including – Field Auditors, Field Audit Supervisors, and Revenue tax Auditor Specialists; – Compliance staff will be added in-state in areas of perceived need, based on current staffing levels and areas of dense business activities; – Compliance staff will be added to out of state metropolitan areas where the Department has historically sent multiple Field Audit trips.
INCREASING COMPLIANCE STAFF • For a total cost of about $90 K, it is estimated that for each new revenue auditor position created and filled the Department would see an increase collections, on average, by $200, 000 in the first full year of employment, $450, 000 in the second year of employment and $750, 000 in the third year of employment. – Does not take into consideration collections from the resulting voluntary compliance.
INCREASING COMPLIANCE STAFF • We have a perpetual posting on the Civil Service website nor for these auditor positions. • We feel that the practioner community has many qualified candidates for these positions available. • If you or any of your colleagues are interested, please contact us. COME TO THE DARK SIDE!
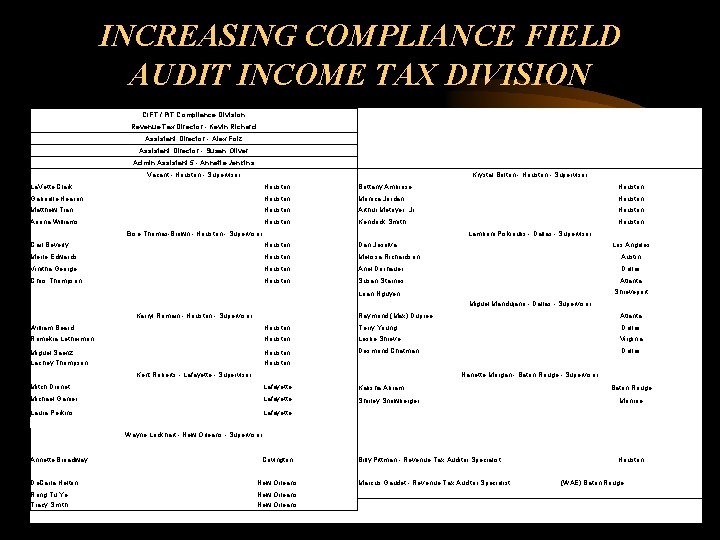
INCREASING COMPLIANCE FIELD AUDIT INCOME TAX DIVISION CIFT / PIT Compliance Division Revenue Tax Director - Kevin Richard Assistant Director - Alex Folz Assistant Director - Susan Oliver Admin Assistant 5 - Annette Jenkins Vacant - Houston - Supervisor Krystal Bolton - Houston - Supervisor La. Vette Clark Houston Brittany Ambrose Houston Gabrielle Hearon Houston Monica Jordan Houston Matthew Tran Houston Arthur Metoyer, Jr. Houston Ariona Williams Houston Kendrick Smith Houston Elise Thomas-Brown - Houston - Supervisor Lambrini Piskioulis - Dallas - Supervisor Carl Beverly Houston Dan Jesolva Los Angeles Merle Edwards Houston Melissa Richardson Austin Vinitha George Houston Anel Dorhauer Dallas Chris Thompson Houston Susan Starnes Atlanta Shreveport Karryl Romain - Houston - Supervisor Loan Nguyen Miguel Mandujano - Dallas - Supervisor Raymond (Max) Dupree William Beard Houston Terry Young Dallas Romekia Lethermon Houston Leslie Shreve Virginia Miguel Saenz Lachey Thompson Houston Desmond Chatman Dallas Kent Roberts - Lafayette - Supervisor Atlanta Nanette Morgan - Baton Rouge - Supervisor Mitch Dronet Lafayette Kalisha Abram Baton Rouge Michael Ganier Lafayette Shirley Snowberger Monroe Laura Perkins Lafayette Wayne Lockhart - New Orleans - Supervisor Annette Broadway Covington De. Carla Helton New Orleans Marcus Gaudet - Revenue Tax Auditor Specialist Rong Tu Ye Tracy Smith New Orleans Billy Pittman - Revenue Tax Auditor Specialist Houston (WAE) Baton Rouge
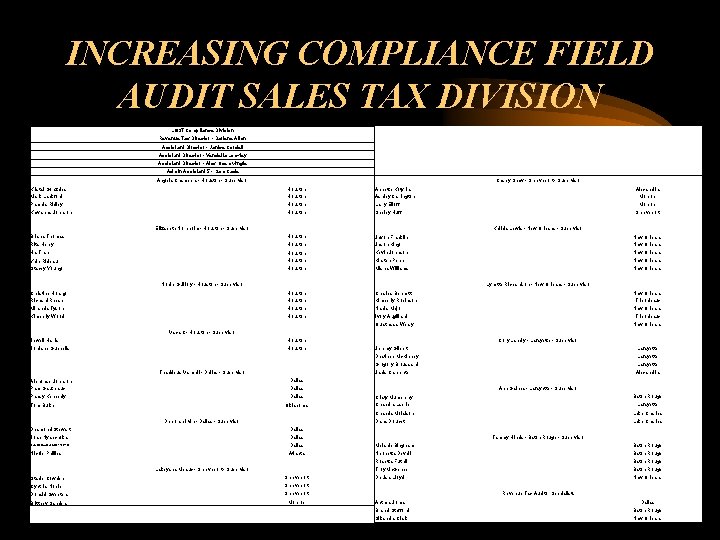
INCREASING COMPLIANCE FIELD AUDIT SALES TAX DIVISION LGST Compliance Division Revenue Tax Director - Darlene Allen Assistant Director - Janice Cordell Assistant Director - Vendetta Lockley Assistant Director - Alex Osemwingie Admin Assistant 5 - Sam Cade Casey Shaw - Shreveport - Supervisor Angela Chambers - Houston - Supervisor Kristal Gonzales Mark Lankford Houston Annette Kotynia Ashley Carrington Pamela Ridley Houston Larry Elioff Monroe Kewanna Johnson Houston Shelby Huff Shreveport Elizabeth Nornholm - Houston - Supervisor Kelicia Lewis - New Orleans - Supervisor Briana Thomas Houston Rita Henry Houston Ha Tran Yale Rideau Stacey Young Alexandria Monroe Javon Franklin Jason King New Orleans Houston Kevin Johnson New Orleans Kirsten Penn New Orleans Houston Misha Williams New Orleans Noble Guillory - Houston - Supervisor Lynette Richardson - New Orleans - Supervisor Christine Hoang Richard Reese Houston Charles Bennett Kimberly Robinson New Orleans Thibodeaux Miranda Tyson Houston Nadia Major New Orleans Kimberly Wood Houston Ivory Augillard Vacant - Houston - Supervisor Quatressa Weary Houston Thibodeaux New Orleans Jewell Harris Jordane Gunnells Jeremy Gilbert Lafayette Destinee Mc. Kinney Lafayette Grogory Broussard Lafayette Janis Carpenter Alexandria Houston Thaddeus Varmall - Dallas - Supervisor Dallas Alphonse Johnson Pam Gautreaux Pansy Kennedy Dallas Tom Burke Oklahoma Dallas Deborah Irvin - Dallas - Supervisor Desmond Stewart Cory Landry - Lafayette - Supervisor Dallas Ann Gaines - Lafayette - Supervisor Baton Rouge Cristy Mumphrey Chandra Labrie Lafayette Chanda Molaison Lake Charles Dana Doucet Lake Charles Tammy Hinds - Baton Rouge - Supervisor Joan Nyanchoka Marcus Davis (starts 1/20/15) Dallas Melanie Bingham Baton Rouge Nicole Phillips Atlanta Neonetta Devall Baton Rouge Rosetta Futrell Baton Rouge Dallas Lakeysha Meaux - Shreveport - Supervisor Troy Mc. Gehee Baton Rouge Stacie Cowden Shreveport De. Lisa Lloyd New Orleans Cynthia Noble Shreveport Donald Sweeters Shreveport Brittney Sanders Monroe Revenue Tax Auditor Specialists Anthea Jones Dallas Brandi Stafford Baton Rouge Sikandra Clark New Orleans
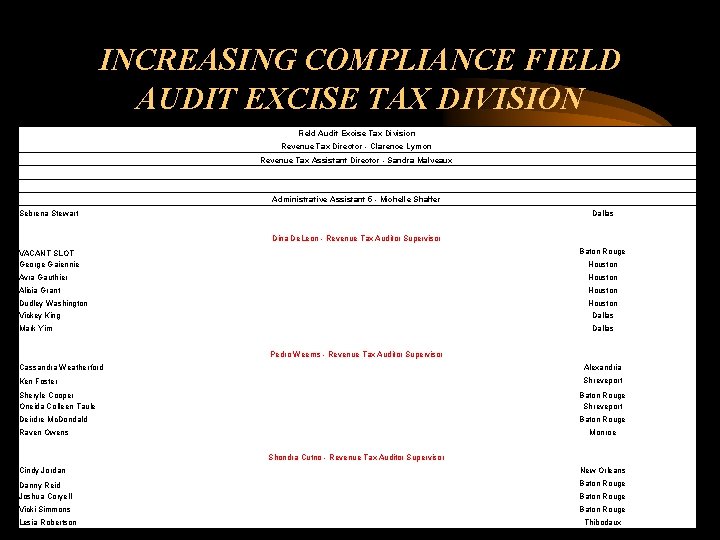
INCREASING COMPLIANCE FIELD AUDIT EXCISE TAX DIVISION Field Audit Excise Tax Division Revenue Tax Director - Clarence Lymon Revenue Tax Assistant Director - Sandra Malveaux Administrative Assistant 5 - Michelle Shaffer Sebrena Stewart Dallas Dina De. Leon - Revenue Tax Auditor Supervisor VACANT SLOT George Gaiennie Baton Rouge Houston Avra Gauthier Houston Alicia Grant Houston Dudley Washington Houston Vickey King Dallas Mark Yim Dallas Pedro Weems - Revenue Tax Auditor Supervisor Cassandra Weatherford Alexandria Ken Foster Shreveport Sheryle Cooper Oneida Colleen Taule Baton Rouge Shreveport Deirdre Mc. Dondald Baton Rouge Raven Owens Monroe Shondra Cutno - Revenue Tax Auditor Supervisor Cindy Jordan New Orleans Danny Reid Joshua Coryell Baton Rouge Vicki Simmons Baton Rouge Lesia Robertson Thibodaux
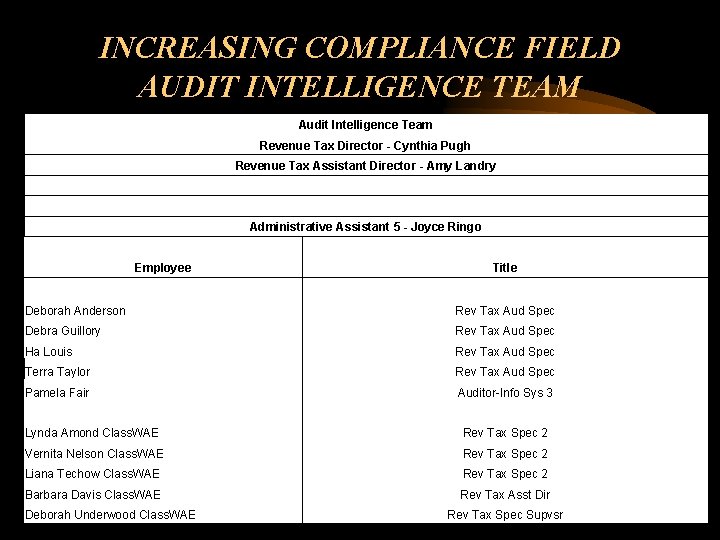
INCREASING COMPLIANCE FIELD AUDIT INTELLIGENCE TEAM Audit Intelligence Team Revenue Tax Director - Cynthia Pugh Revenue Tax Assistant Director - Amy Landry Administrative Assistant 5 - Joyce Ringo Employee Title Deborah Anderson Rev Tax Aud Spec Debra Guillory Rev Tax Aud Spec Ha Louis Rev Tax Aud Spec Terra Taylor Rev Tax Aud Spec Pamela Fair Auditor-Info Sys 3 Lynda Amond Class. WAE Rev Tax Spec 2 Vernita Nelson Class. WAE Rev Tax Spec 2 Liana Techow Class. WAE Rev Tax Spec 2 Barbara Davis Class. WAE Rev Tax Asst Dir Deborah Underwood Class. WAE Rev Tax Spec Supvsr
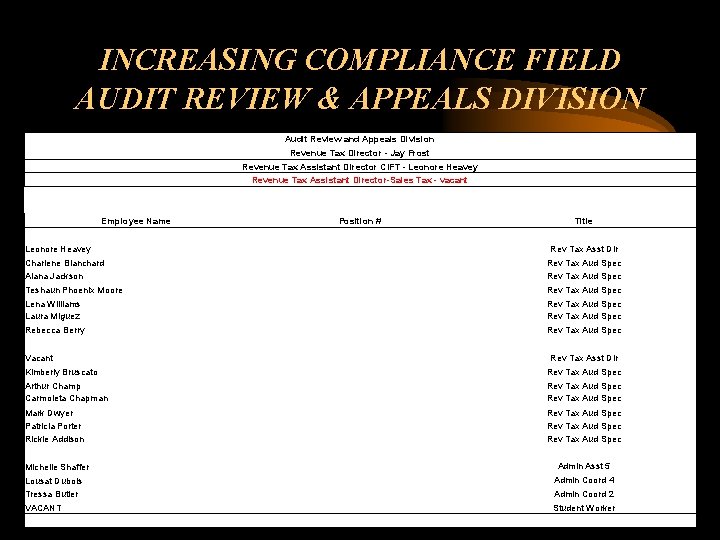
INCREASING COMPLIANCE FIELD AUDIT REVIEW & APPEALS DIVISION Audit Review and Appeals Division Revenue Tax Director - Jay Frost Revenue Tax Assistant Director CIFT - Leonore Heavey Revenue Tax Assistant Director-Sales Tax - vacant Employee Name Position # Title Leonore Heavey Rev Tax Asst Dir Charlene Blanchard Alana Jackson Rev Tax Aud Spec Teshaun Phoenix Moore Rev Tax Aud Spec Lena Williams Laura Miguez Rev Tax Aud Spec Rebecca Berry Rev Tax Aud Spec Vacant Rev Tax Asst Dir Kimberly Bruscato Rev Tax Aud Spec Arthur Champ Carmoleta Chapman Rev Tax Aud Spec Mark Dwyer Rev Tax Aud Spec Patricia Porter Rickie Addison Rev Tax Aud Spec Michelle Shaffer Admin Asst 5 Lousat Dubois Admin Coord 4 Tressa Butler Admin Coord 2 VACANT Student Worker
CONTRACT AUDIT INITIATIVES • LDR audits. 4% of all registered taxpayers in Louisiana. • Last year the Louisiana Department of Revenue engaged with the Rapides Parish Sales and Use Tax Office in a multi year joint endeavor for that agency to perform audits on behalf of LDR. • The theory was that one auditor/agency could complete both audits with minimum disruption to the taxpayers operation.
CONTRACT AUDIT INITIATIVES CONT. • Rapides Parish Sales Tax Office has eight auditors for one parish audit operation; the Alexandria Regional Office has two auditors to cover the ten parishes around Alexandria. (More auditors are about to be added to that area). • LDR keeps complete control over what audits are performed, but it is generally taxpayers they are also auditing.
CONTRACT AUDIT INITIATIVES CONT. • LDR is in the process of also signing agreements with St. Charles Parish and St. Mary parish. • LDR also engaged two contract audit firms to perform Louisiana sales tax audits, in conjunction with local audits they are performing. – BPA Associates, and Revenue Recovery Group
CONTRACT AUDIT INITIATIVES CONT. • All entities contracted to perform audits paid by the hours of audit services performed (no contingency agreements); • All auditing entities provides a list to LDR of taxpayers they are requesting to audit; • LDR retains complete control over which taxpayers are selected for audit; • LDR performs all reviews of audits and assessments of liabilities.
CONTRACT AUDIT INITIATIVES CONT. • Productive? Efficient? • The three contracts have resulted in 97 audits performed; • $485, 158. 08 in liabilities discovered and collection in progress; • Total Audit Fees paid = $52, 521. 52 • $9. 24 collected for every $1 spent.
VOLUNTARY DISCLOSURE AGREEMENT • Voluntary disclosure is the process of reporting undisclosed liabilities for any tax administered by the Louisiana Department of Revenue. Taxpayers may anonymously enter into agreements and voluntarily pay their taxes with a reduced or no penalty. • In most cases, taxpayers enjoy a limited “look-back” period. • The voluntary disclosure program helps coordinate the registration and payment process and provides general responses to tax related questions.
VOLUNTARY DISCLODURE AGREEMENT CONT. • Louisiana Department of Revenue has a voluntary disclosure program for all of the taxes it administers, including (but not limited to): – – – Individual Income Tax Sales and Use Tax Corporation Income and Franchise Tax Severance Taxes, including Oil and Gas Severance Tax Excise Taxes
VOLUNTARY DISCLODURE AGREEMENT • Any taxpayer who has a filing requirement for a tax administered by the Louisiana Department of Revenue, – is not currently registered with the Department for the same tax, and – has not been previously contacted by the Department concerning their filing requirement • is eligible for consideration of a voluntary disclosure agreement.
VOLUNTARY DISCLODURE AGREEMENT CONT. • A company that is currently registered with the Department may request a voluntary disclosure agreement for an entity it has acquired by purchase or merger provided the acquired company would have qualified under the conditions listed above. – Only the undisclosed taxes of the acquired company for taxes due prior to the acquisition or merger would be eligible for a voluntary disclosure agreement.
VOLUNTARY DISCLOSURE AGREEMENT CONT. • A taxpayer who is registered but failed to file returns or who submitted returns, extensions, or payments for any tax for which the voluntary disclosure agreement (VDA) is requested is not eligible for consideration. • These taxpayers must file the appropriate original or amended return(s) and pay the tax, interest, and delinquent penalty due.
VOLUNTARY DISCLOSURE AGREEMENT CONT. • A taxpayer who has been contacted by the Department of Revenue concerning a liability or potential liability of tax for which a VDA is requested generally does not qualify. – This includes any contact made for the purpose of performing an audit of the taxpayer’s records. – Disclosures relating to delinquencies or deficiencies that are obvious and would routinely generate a billing if not otherwise self-disclosed are not eligible for consideration. – Disclosures related to the non-filing affiliates of a taxpayer who has been contacted for audit are not eligible for consideration.
VOLUNTARY DISCLOSURE AGREEMENT CONT. • After the tax and interest liabilities have been paid for the look-back period, delinquent penalties will be waived unless the tax being disclosed has been collected but not remitted. • The look-back period is the period for which prescription would not have run had returns been filed timely.
VOLUNTARY DISCLOSURE AGREEMENT CONT. • Generally, this includes returns due during the current calendar year and the three immediately preceding calendar years. • The look-back period is established when the application is received by the Department. • In the case of taxes collected but not remitted, the look-back period will include all taxable periods for which there were collected but unremitted taxes.
VOLUNTARY DISCLOSURE AGREEMENT CONT. • You may apply anonymously by completing form R-60010 (Application to Request Voluntary Disclosure Agreement), which can be found on the Department’s website. • If it is determined that you would qualify to participate in the program based upon your responses in the application, the Department of Revenue will mail a blank Voluntary Disclosure Agreement to you or your representative.
VOLUNTARY DISCLOSURE AGREEMENT CONT. • You may remain anonymous until after the agreement is signed by both parties. • If you choose to forego anonymity and include your payment along with the voluntary disclosure application, please include your FEIN or SSN (as applicable) on your check and • an application for account number (CR-1, R 16019) to assist in properly applying the payment. • Make your check payable to the Louisiana Department of Revenue.
VOLUNTARY DISCLOSURE AGREEMENT CONT. • Mail the voluntary disclosure application to: • Louisiana Department of Revenue Voluntary Disclosure Program – Field Audit Services Division PO Box 4936 Baton Rouge, Louisiana 70821 -4936
VOLUNTARY DISCLOSURE AGREEMENT CONT. • Or deliver it to: • Louisiana Department of Revenue La. Salle Building Voluntary Disclosure Program – Field Audit Services Division 617 North Third St, Room 562 Baton Rouge, Louisiana 70821 -5431 • Applications may also be faxed to 225 -219 -2740 or e-mailed to vda. ldr@la. gov.
AUDIT INITIATIVES - CONCLUSION • Secretary Barfield: “Closing the “Tax Gap”, which is the difference between what taxpayers should be paying under the law and what they are paying in practice”
QUESTIONS?