
Longevity 15 Fifteenth International Longevity Risk and Capital
- Slides: 16
Longevity 15: Fifteenth International Longevity Risk and Capital Market Solutions Conference Professor David Blake Director Pensions Institute Cass Business School d. blake@city. ac. uk September 2019 1
Previous conferences § Longevity 1: London 2005 § Longevity 8: Waterloo 2012 § Longevity 2: Chicago 2006 § Longevity 9: Beijing 2013 § Longevity 3: Taipei 2007 § Longevity 10: Santiago 2014 § Longevity 4: Amsterdam 2008 § Longevity 11: Lyon 2015 § Longevity 5: New York 2009 § Longevity 12: Chicago 2016 § Longevity 6: Sydney 2010 § Longevity 13: Taipei 2017 § Longevity 7: Frankfurt 2011 § Longevity 14: Amsterdam 2018 2
Developments in 2018 § £ 24 bn buy-outs + buy-ins in UK pension funds in 2018 § § § Main players: § § Legal & General, Pension Insurance Corp (PIC), Aviva, Scottish Widows, Just £ 120 bn since 2006 £ 7 bn of longevity swaps in 2018 § § £ 9. 7 bn buy-outs versus £ 14. 5 billion of buy-ins Up from £ 12 bn in 2017 £ 70 bn since 2007 Solvency II raised cost of buyout by 5 -7% US buy-outs + buy-ins since 2012 § 2, 170 deals valued at $139 bn (only 15 buy-ins) 3
Developments in 2018 § § Average UK pension fund now 100% funded, making de-risking deals more affordable Prudential Retirement executed $2. 6 bn longevity reinsurance contract in UK covering 16, 000 pensioners § § § $60 bn since 2011 L&G executed a £ 4. 4 bn buy-in with British Airways L&G executed a £ 2. 4 bn buy-out with Nortel PIC executed a £ 1. 5 bn buy-out with Rentokil PIC executed a £ 1. 3 bn buy-in with Siemens Phoenix Life purchased insurance arm of Standard Life Aberdeen, including around £ 5 bn of annuity liabilities 4
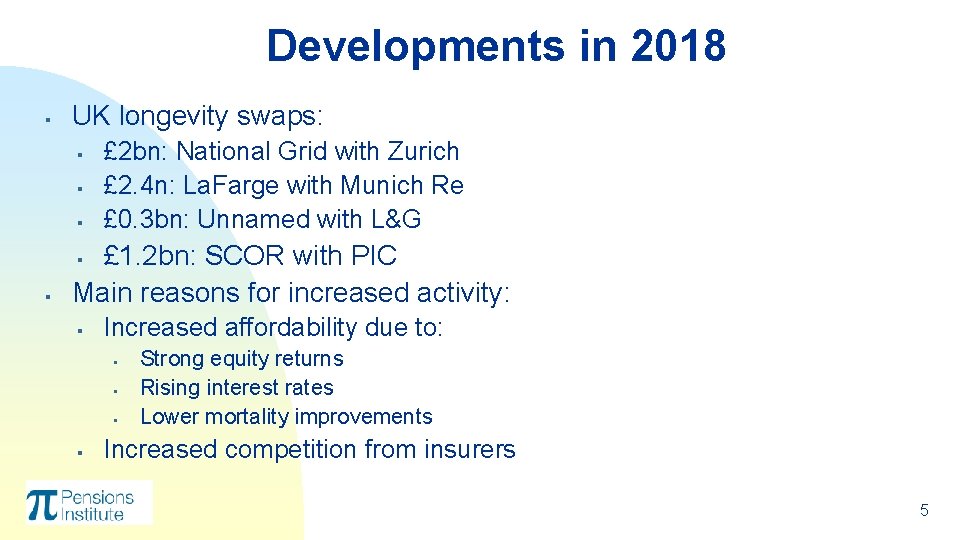
Developments in 2018 § UK longevity swaps: § § § £ 2 bn: National Grid with Zurich £ 2. 4 n: La. Farge with Munich Re £ 0. 3 bn: Unnamed with L&G £ 1. 2 bn: SCOR with PIC Main reasons for increased activity: § § § Increased affordability due to: § § Strong equity returns Rising interest rates Lower mortality improvements Increased competition from insurers 5
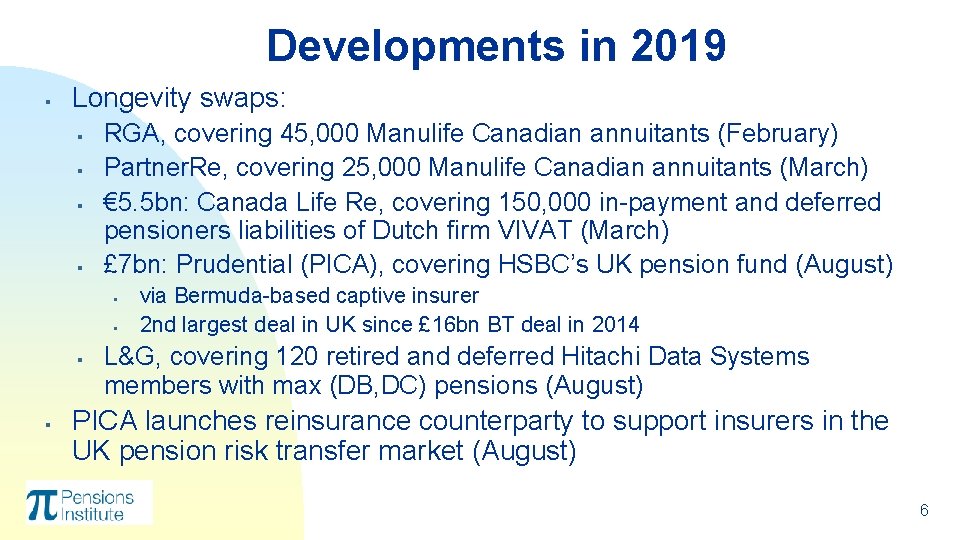
Developments in 2019 § Longevity swaps: § § RGA, covering 45, 000 Manulife Canadian annuitants (February) Partner. Re, covering 25, 000 Manulife Canadian annuitants (March) € 5. 5 bn: Canada Life Re, covering 150, 000 in-payment and deferred pensioners liabilities of Dutch firm VIVAT (March) £ 7 bn: Prudential (PICA), covering HSBC’s UK pension fund (August) § § via Bermuda-based captive insurer 2 nd largest deal in UK since £ 16 bn BT deal in 2014 L&G, covering 120 retired and deferred Hitachi Data Systems members with max (DB, DC) pensions (August) PICA launches reinsurance counterparty to support insurers in the UK pension risk transfer market (August) 6
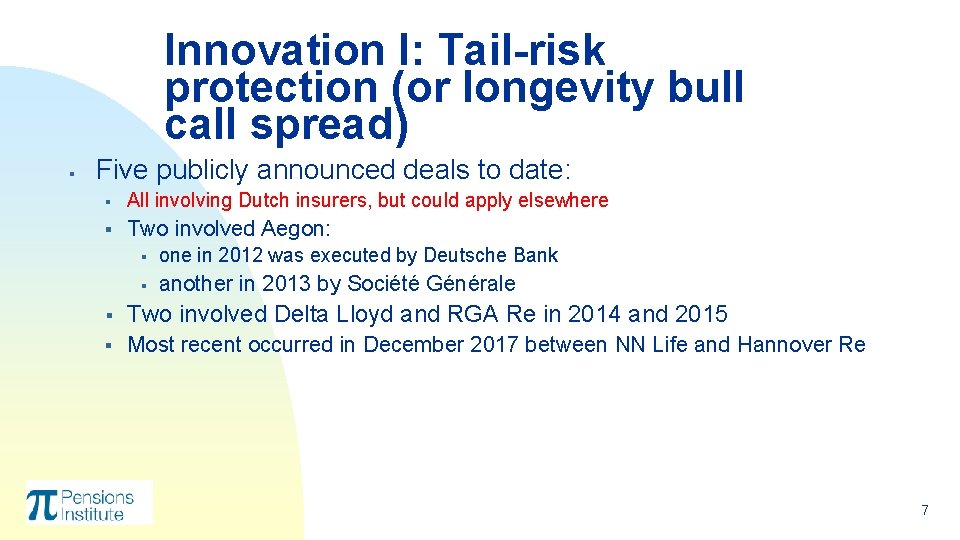
Innovation I: Tail-risk protection (or longevity bull call spread) § Five publicly announced deals to date: § All involving Dutch insurers, but could apply elsewhere § Two involved Aegon: § one in 2012 was executed by Deutsche Bank § another in 2013 by Société Générale § Two involved Delta Lloyd and RGA Re in 2014 and 2015 § Most recent occurred in December 2017 between NN Life and Hannover Re 7
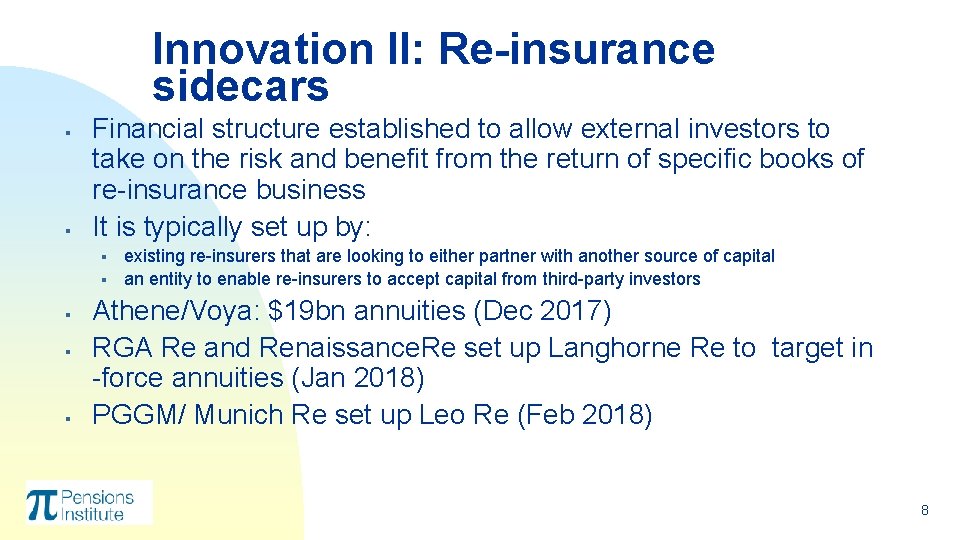
Innovation II: Re-insurance sidecars § § Financial structure established to allow external investors to take on the risk and benefit from the return of specific books of re-insurance business It is typically set up by: § § § existing re-insurers that are looking to either partner with another source of capital an entity to enable re-insurers to accept capital from third-party investors Athene/Voya: $19 bn annuities (Dec 2017) RGA Re and Renaissance. Re set up Langhorne Re to target in -force annuities (Jan 2018) PGGM/ Munich Re set up Leo Re (Feb 2018) 8
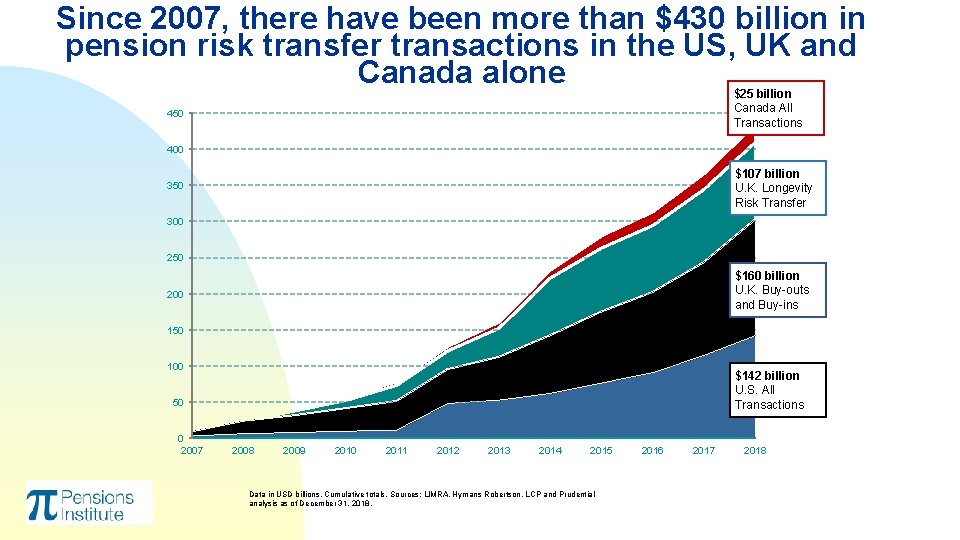
Since 2007, there have been more than $430 billion in pension risk transfer transactions in the US, UK and Canada alone $25 billion Canada All Transactions 450 400 $107 billion U. K. Longevity Risk Transfer 350 300 250 $160 billion U. K. Buy-outs and Buy-ins 200 150 100 $142 billion U. S. All Transactions 50 0 2007 2008 2009 2010 2011 2012 2013 2014 2015 Data in USD billions. Cumulative totals. Sources: LIMRA, Hymans Robertson, LCP and Prudential analysis as of December 31, 2018. 2016 2017 2018
Looking ahead § UK forecasts for 2019 (WTW): § £ 25 bn+ in buy-in/outs (£ 17 bn in H 1) § § § £ 700 bn over next 15 years £ 10 bn in longevity swaps Kessler (Prudential): Longevity risk transfer demand shows no signs of slowing Club Vita: Capital markets can plug any gaps in longevity reinsurance or risk transfer capacity, with index-based longevity hedging likely to become the focus But capacity constraints: § § Human resources, e. g. , skilled lawyers Limited availability of illiquid assets to back the liabilities § e. g. , ground rents, education loans and infrastructure assets 10
Individuals do not understand longevity risk § Introduction of ‘freedom and choice’ in UK in April 2015 § § § £ 16 bn withdrawn since 2015 § § Often held in bank accounts, depressing interest rates Every quarter, 200, 000 retirees are withdrawing a total of £ 1. 5 bn per quarter § § retirees with DC pots no longer need to annuitise Retirees with DB pots can switch to DC and take lump sum ‘No sign of slowing’ 60% of retirees with guaranteed annuity rates have surrendered them in order to access the lump sum § Losing 40 -80% 11
What needs to happen at L 15 § § § Continuing with our strategy of bringing together practitioners, academics, regulators and policy makers from a variety of relevant disciplines Extending our community to include pension plan sponsors with significant longevity risk asset exposure from different countries Also raising awareness of longevity risk generally 12
§ What needs to happen at L 15 Key themes of Longevity 15: § § § n mortality trends and forecasts longevity risk and inequalities longevity hedging solutions sustainability of pension systems financial wellbeing life settlements Special issue of Insurance: Mathematics & Economics 13
Longevity 15 The Fifteenth International Longevity Risk and Capital Markets Solutions Conference, Washington DC, 12 -13 September 2019 SPONSORS Platinum Gold Silver https: //www. cass. city. ac. uk/faculties-and-research/centres/pensionsinstitute/events/longevity-15/sponsors 14
Hosts Many thanks to Mike Fasano’s team, Katrina Mbaye and Marilyn Parris-Bell & Sharmila Harris 15
Longevity 16 The Sixteenth International Longevity Risk and Capital Markets Solutions Conference, Singapore, 10 -11 September 2020 Special issue of Journal of Demographic Economics 16