
KoreaIran Economic cooperation Petrochemical sector I Global Petrochemical
Korea-Iran Economic cooperation -Petrochemical sector. I. Global Petrochemical Industry II. Iran Petrochemical Industry III. Petrochemical Cooperation with Korea-Iran NH Investment & Securities Global Credit Strategist: Hwan Jong (Louis) Shin tel 02) 768 -7590 │e-mail louis. shin@nhqv. com
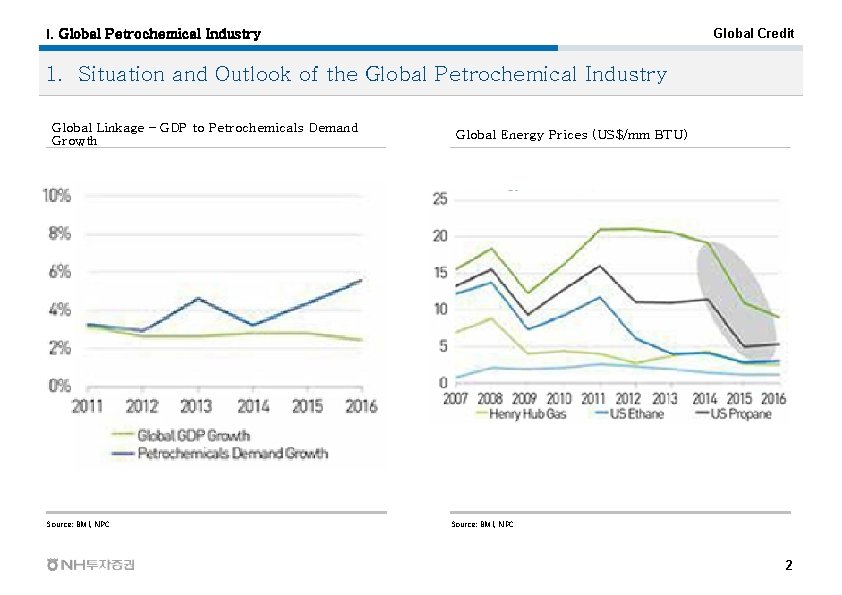
I. Global Petrochemical Industry Global Credit 1. Situation and Outlook of the Global Petrochemical Industry Global Linkage – GDP to Petrochemicals Demand Growth Source: BMI, NPC Global Energy Prices (US$/mm BTU) Source: BMI, NPC 2
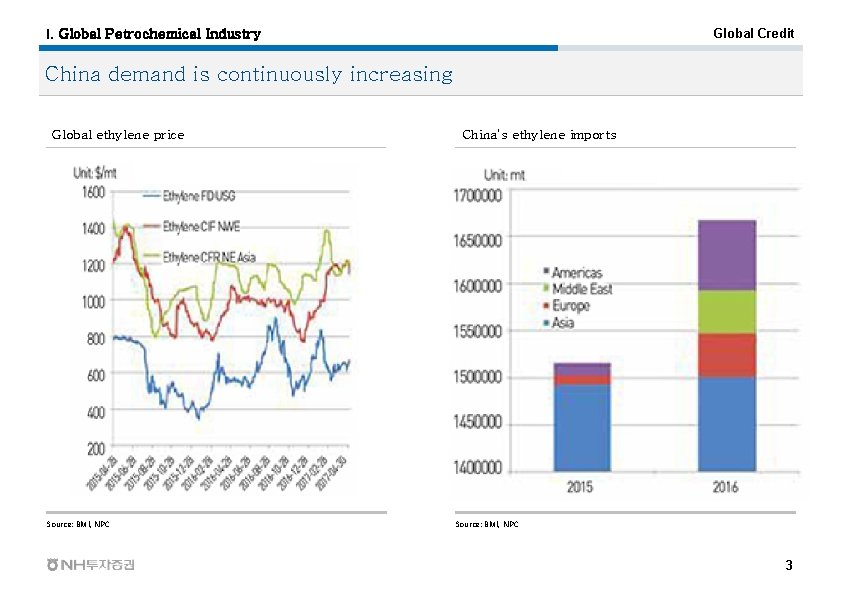
I. Global Petrochemical Industry Global Credit China demand is continuously increasing Global ethylene price Source: BMI, NPC China’s ethylene imports Source: BMI, NPC 3
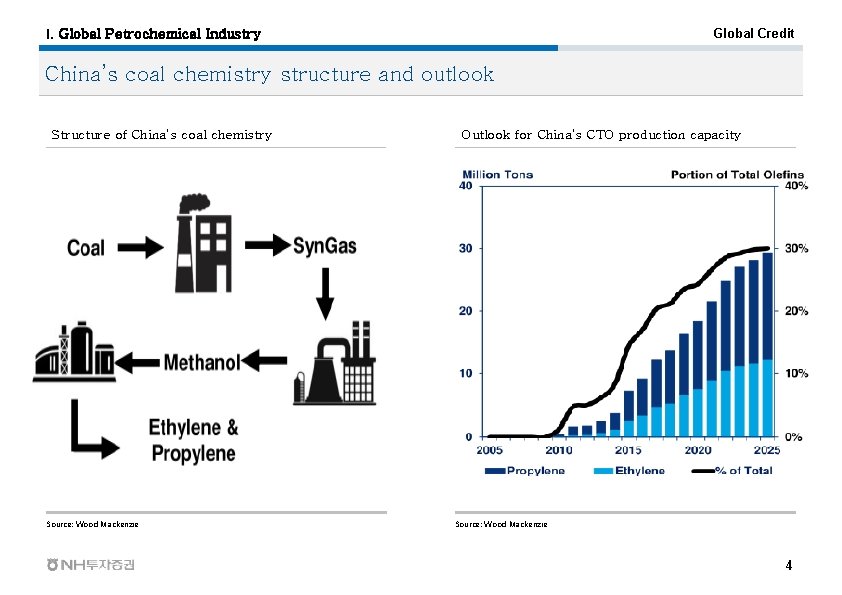
I. Global Petrochemical Industry Global Credit China’s coal chemistry structure and outlook Structure of China’s coal chemistry Source: Wood Mackenzie Outlook for China’s CTO production capacity Source: Wood Mackenzie 4
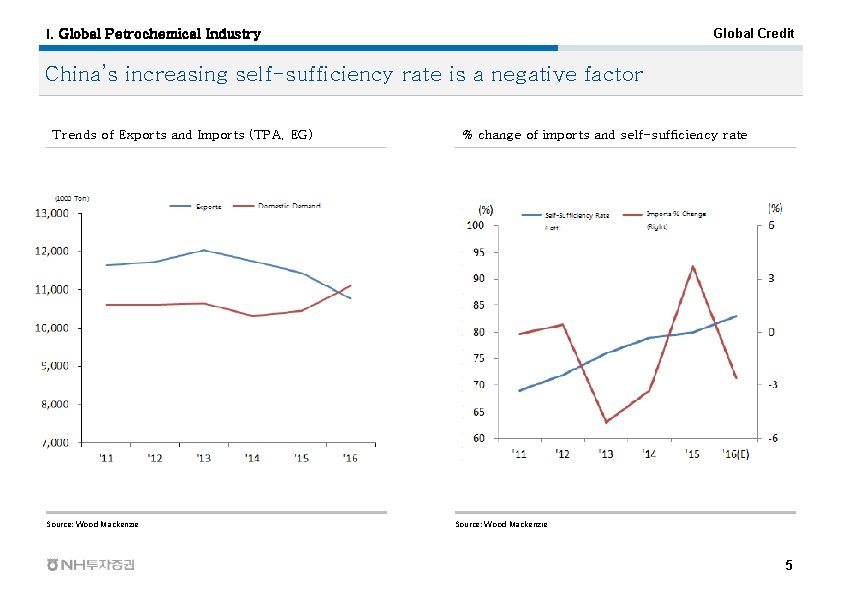
I. Global Petrochemical Industry Global Credit China’s increasing self-sufficiency rate is a negative factor Trends of Exports and Imports (TPA, EG) Source: Wood Mackenzie % change of imports and self-sufficiency rate Source: Wood Mackenzie 5
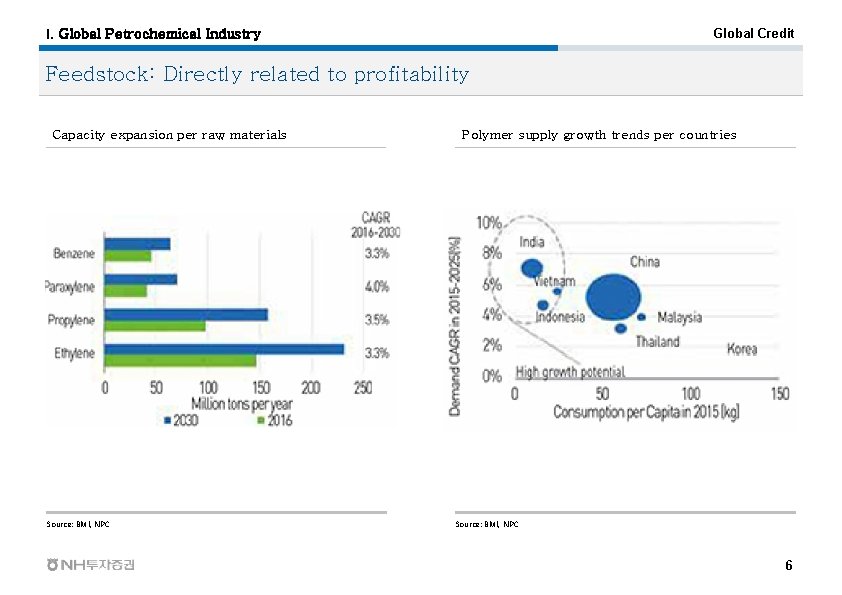
I. Global Petrochemical Industry Global Credit Feedstock: Directly related to profitability Capacity expansion per raw materials Source: BMI, NPC Polymer supply growth trends per countries Source: BMI, NPC 6
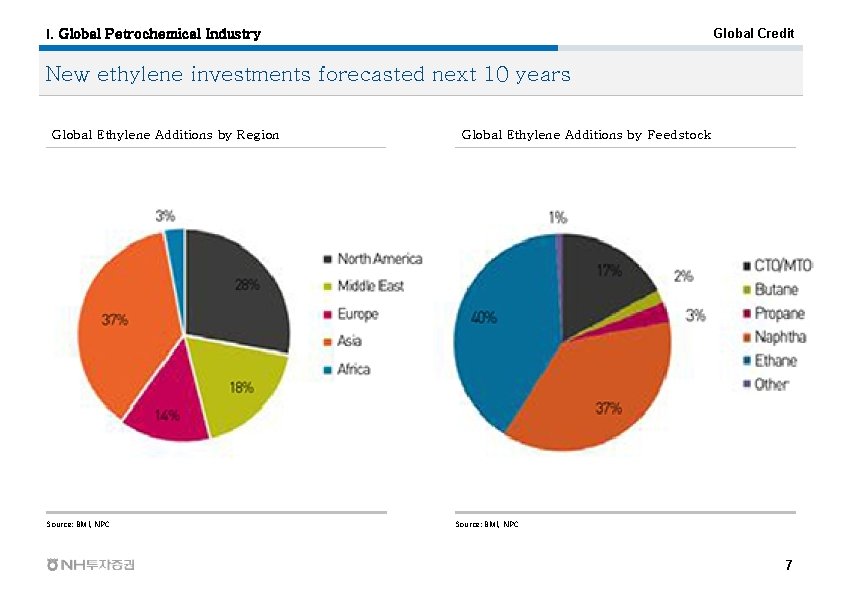
I. Global Petrochemical Industry Global Credit New ethylene investments forecasted next 10 years Global Ethylene Additions by Region Source: BMI, NPC Global Ethylene Additions by Feedstock Source: BMI, NPC 7
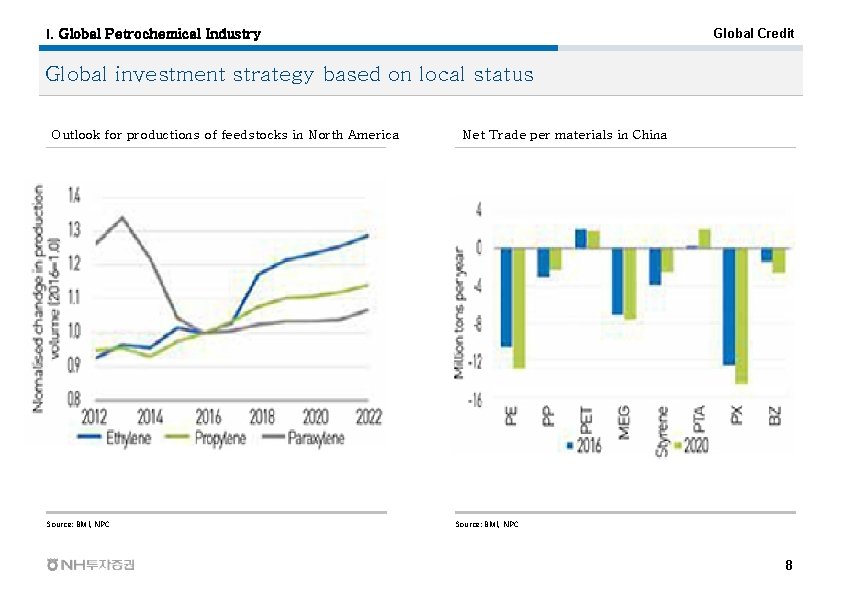
I. Global Petrochemical Industry Global Credit Global investment strategy based on local status Outlook for productions of feedstocks in North America Source: BMI, NPC Net Trade per materials in China Source: BMI, NPC 8
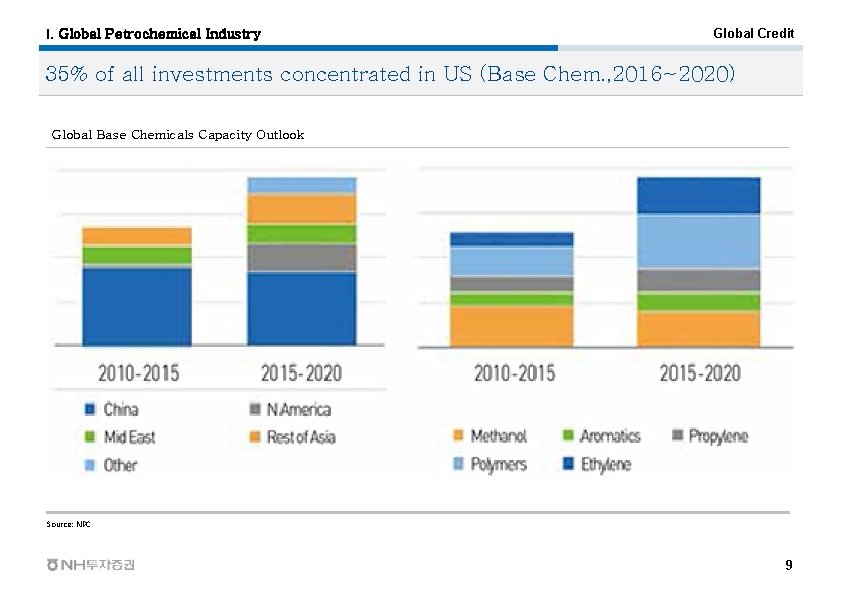
I. Global Petrochemical Industry Global Credit 35% of all investments concentrated in US (Base Chem. , 2016~2020) Global Base Chemicals Capacity Outlook Source: NPC 9
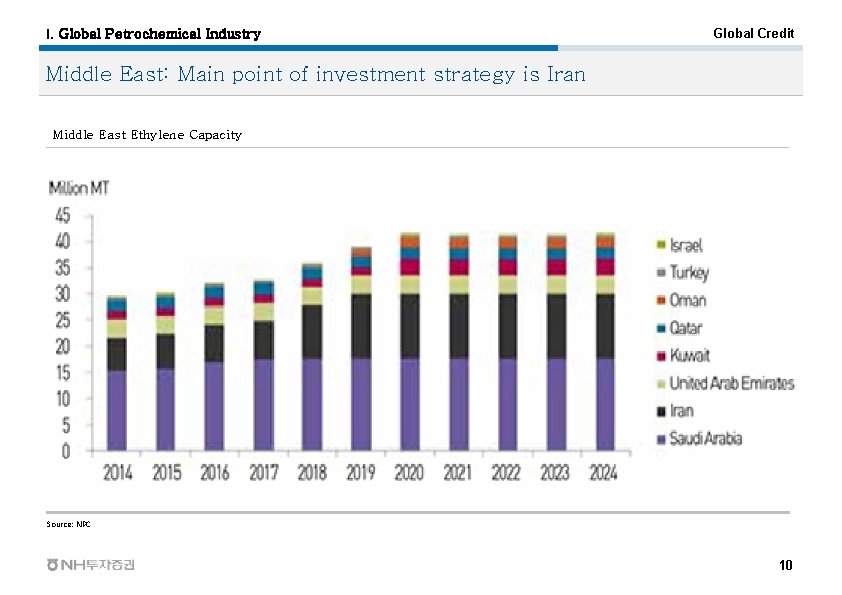
I. Global Petrochemical Industry Global Credit Middle East: Main point of investment strategy is Iran Middle East Ethylene Capacity Source: NPC 10
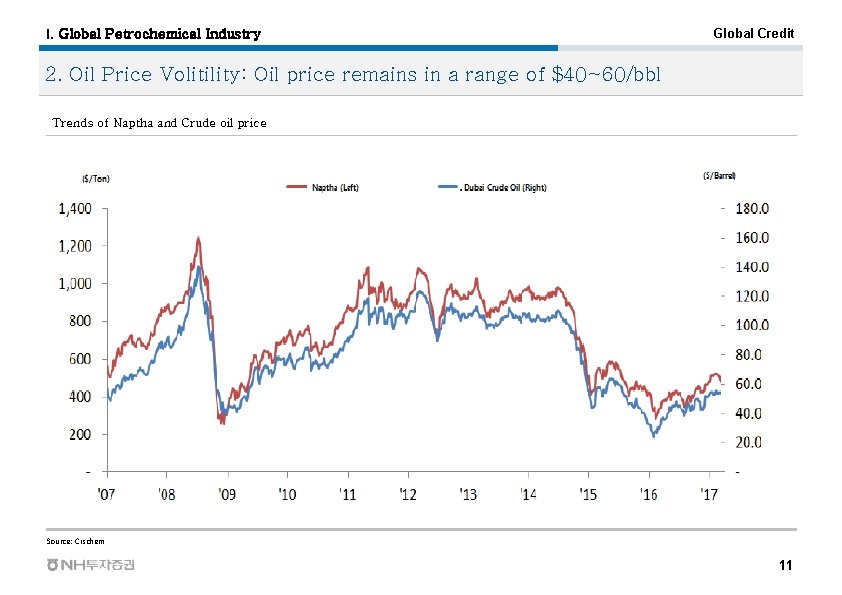
I. Global Petrochemical Industry Global Credit 2. Oil Price Volitility: Oil price remains in a range of $40~60/bbl Trends of Naptha and Crude oil price Source: Cischem 11
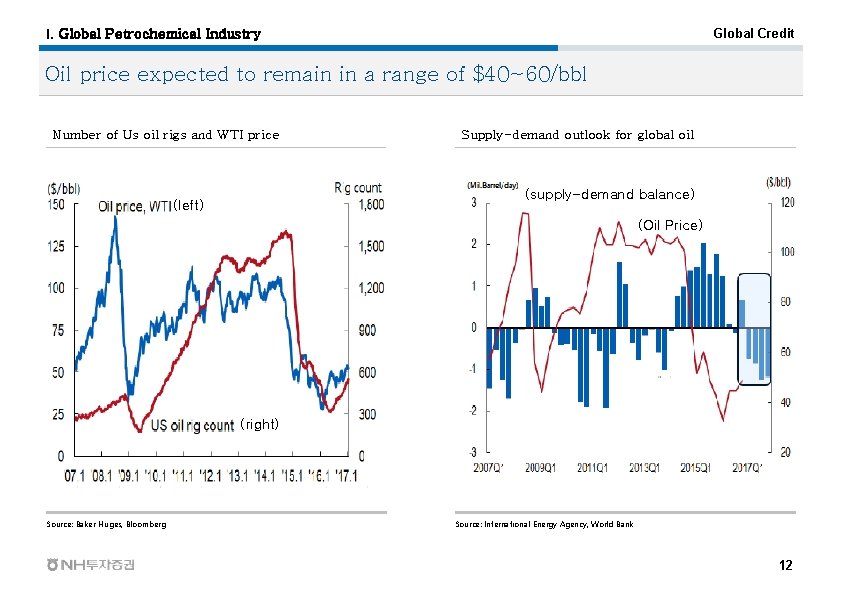
I. Global Petrochemical Industry Global Credit Oil price expected to remain in a range of $40~60/bbl Number of Us oil rigs and WTI price Supply-demand outlook for global oil (supply-demand balance) (left) (Oil Price) (right) Source: Baker Huges, Bloomberg Source: International Energy Agency, World Bank 12
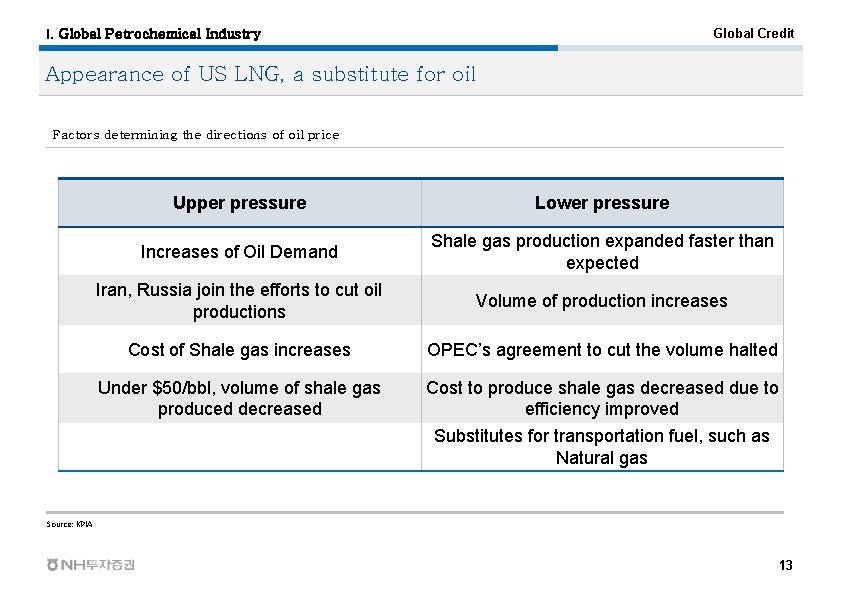
I. Global Petrochemical Industry Global Credit Appearance of US LNG, a substitute for oil Factors determining the directions of oil price Upper pressure Lower pressure Increases of Oil Demand Shale gas production expanded faster than expected Iran, Russia join the efforts to cut oil productions Volume of production increases Cost of Shale gas increases OPEC’s agreement to cut the volume halted Under $50/bbl, volume of shale gas produced decreased Cost to produce shale gas decreased due to efficiency improved Substitutes for transportation fuel, such as Natural gas Source: KPIA 13
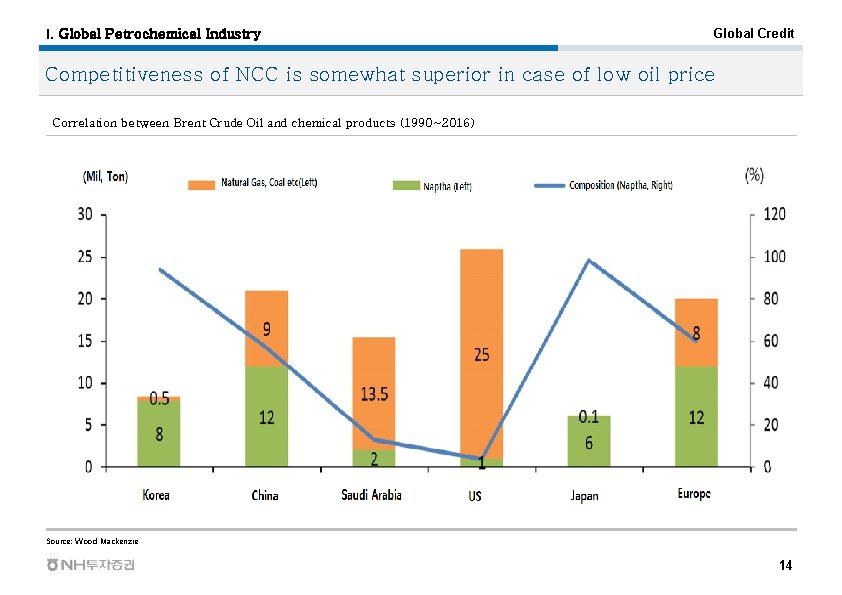
I. Global Petrochemical Industry Global Credit Competitiveness of NCC is somewhat superior in case of low oil price Correlation between Brent Crude Oil and chemical products (1990~2016) Source: Wood Mackenzie 14
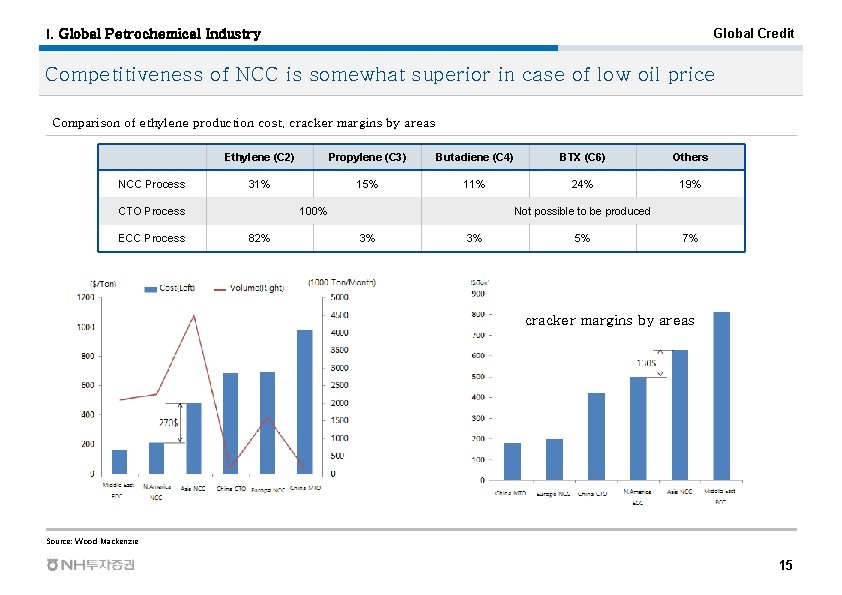
I. Global Petrochemical Industry Global Credit Competitiveness of NCC is somewhat superior in case of low oil price Comparison of ethylene production cost, cracker margins by areas NCC Process Ethylene (C 2) Propylene (C 3) Butadiene (C 4) BTX (C 6) Others 31% 15% 11% 24% 19% CTO Process ECC Process 100% 82% Not possible to be produced 3% 3% 5% 7% cracker margins by areas Source: Wood Mackenzie 15
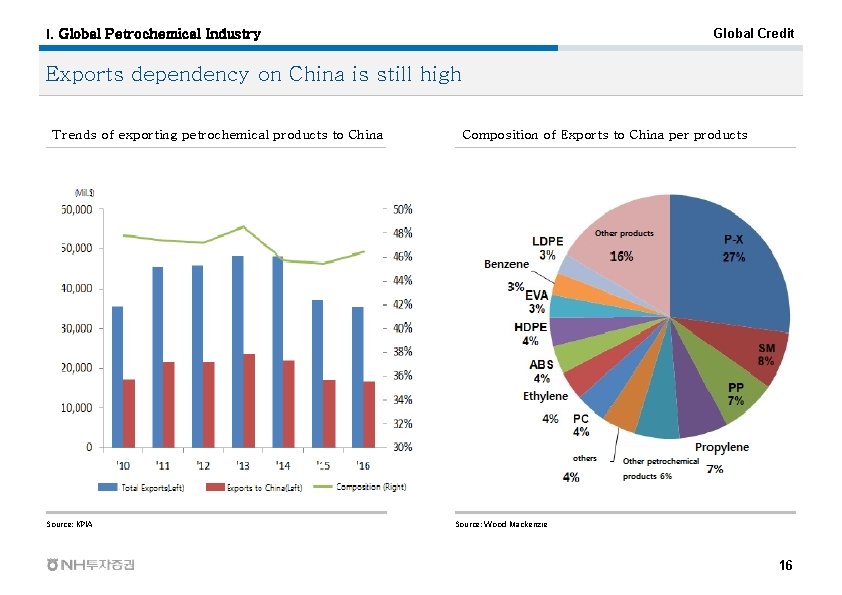
I. Global Petrochemical Industry Global Credit Exports dependency on China is still high Trends of exporting petrochemical products to China Source: KPIA Composition of Exports to China per products Source: Wood Mackenzie 16
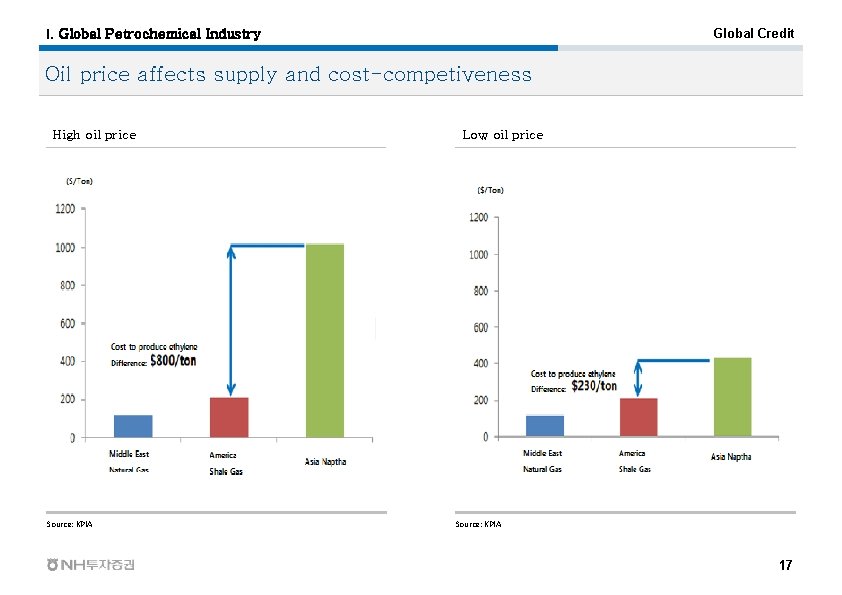
I. Global Petrochemical Industry Global Credit Oil price affects supply and cost-competiveness High oil price Source: KPIA Low oil price Source: KPIA 17
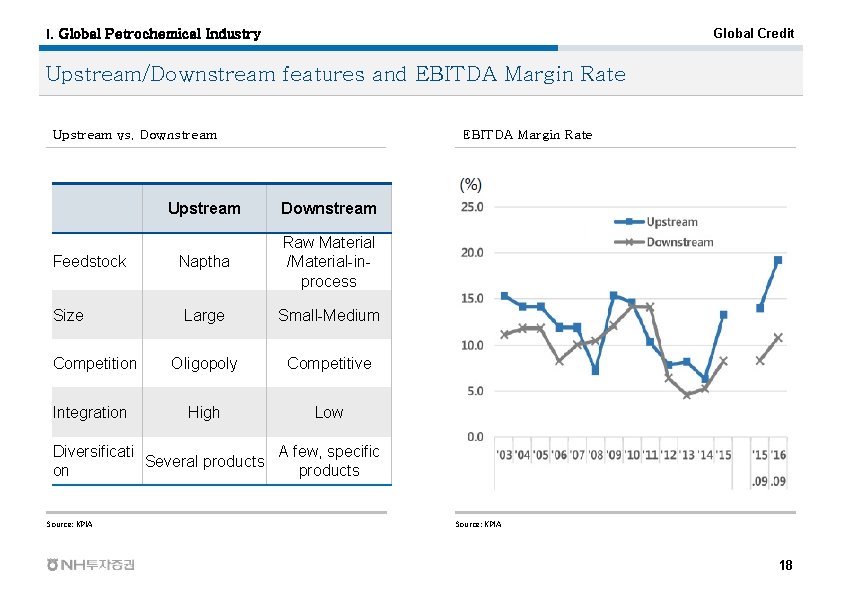
I. Global Petrochemical Industry Global Credit Upstream/Downstream features and EBITDA Margin Rate Upstream vs. Downstream Feedstock Size Competition Integration EBITDA Margin Rate Upstream Downstream Naptha Raw Material /Material-inprocess Large Small-Medium Oligopoly Competitive High Low Diversificati A few, specific Several products on products Source: KPIA 18
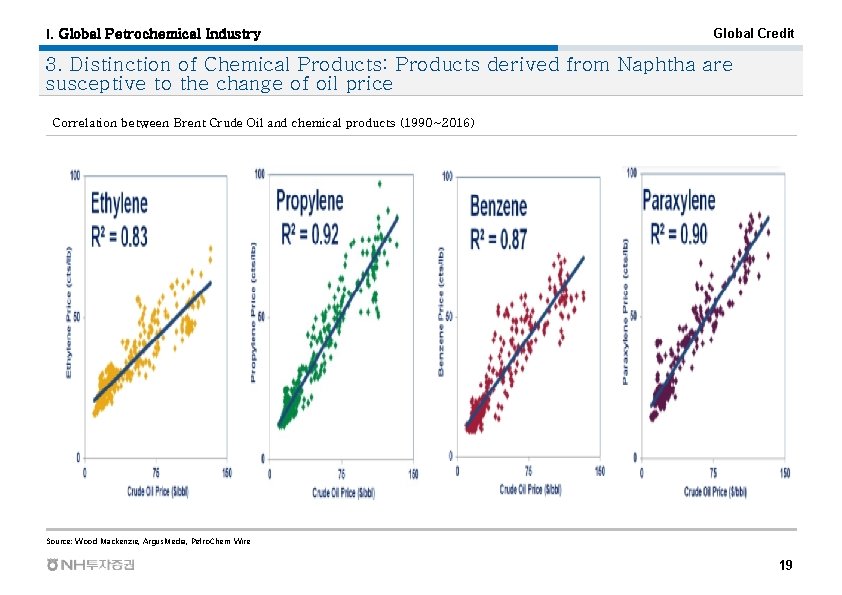
I. Global Petrochemical Industry Global Credit 3. Distinction of Chemical Products: Products derived from Naphtha are susceptive to the change of oil price Correlation between Brent Crude Oil and chemical products (1990~2016) Source: Wood Mackenzie, Argus. Media, Petro. Chem Wire 19
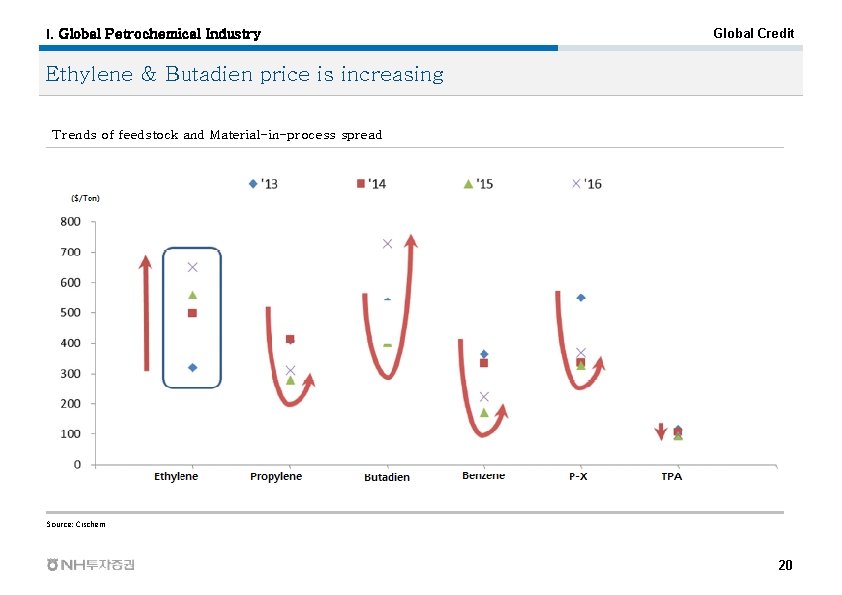
I. Global Petrochemical Industry Global Credit Ethylene & Butadien price is increasing Trends of feedstock and Material-in-process spread Source: Cischem 20
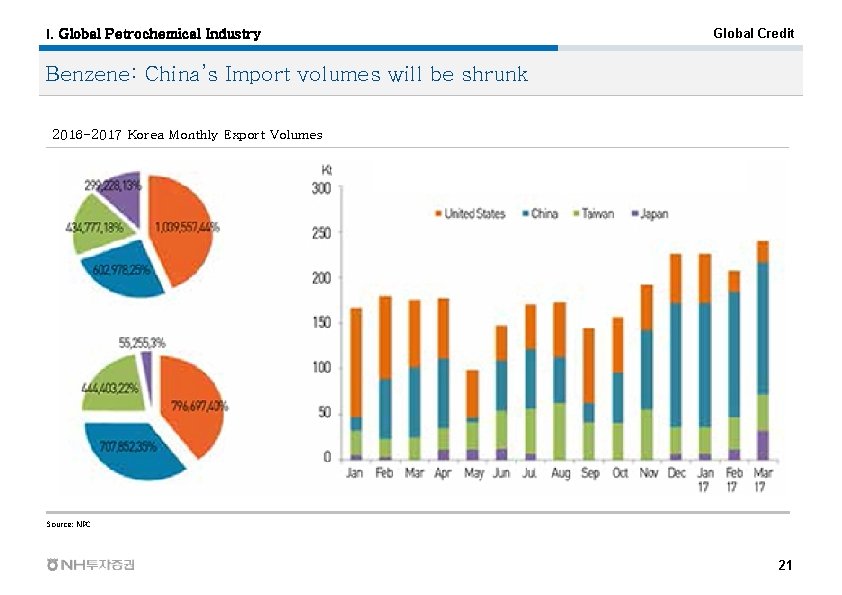
I. Global Petrochemical Industry Global Credit Benzene: China’s Import volumes will be shrunk 2016 -2017 Korea Monthly Export Volumes Source: NPC 21
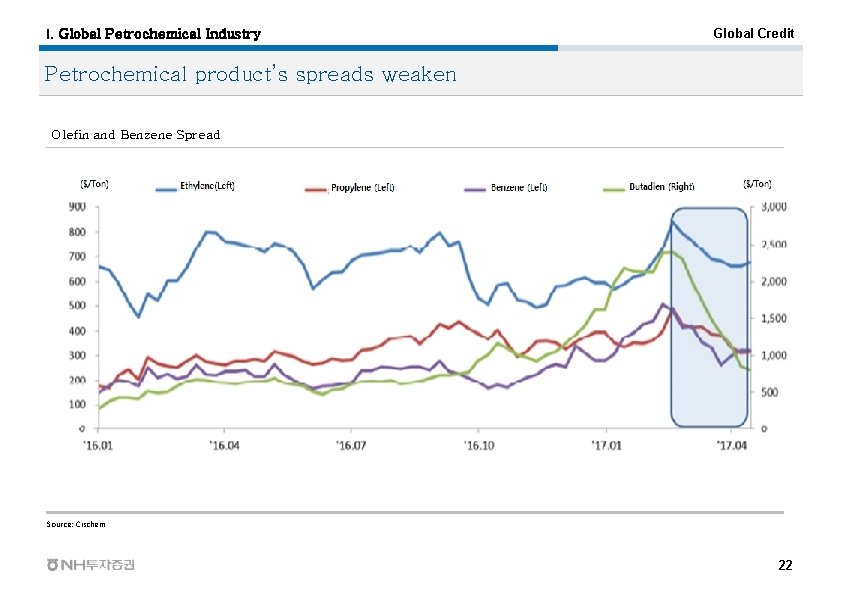
I. Global Petrochemical Industry Global Credit Petrochemical product’s spreads weaken Olefin and Benzene Spread Source: Cischem 22
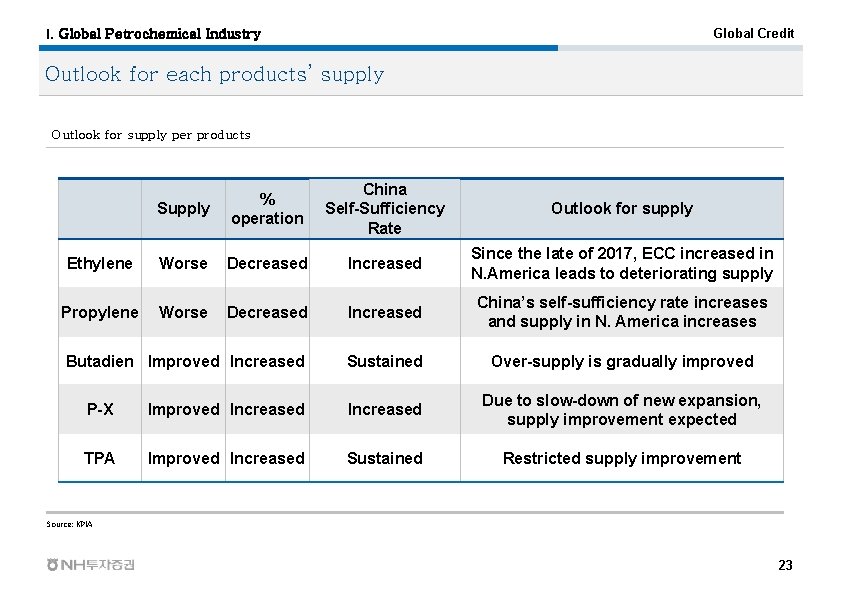
I. Global Petrochemical Industry Global Credit Outlook for each products’ supply Outlook for supply per products Supply % operation China Self-Sufficiency Rate Outlook for supply Ethylene Worse Decreased Increased Since the late of 2017, ECC increased in N. America leads to deteriorating supply Propylene Worse Decreased Increased China’s self-sufficiency rate increases and supply in N. America increases Butadien Improved Increased Sustained Over-supply is gradually improved P-X Improved Increased Due to slow-down of new expansion, supply improvement expected TPA Improved Increased Sustained Restricted supply improvement Source: KPIA 23
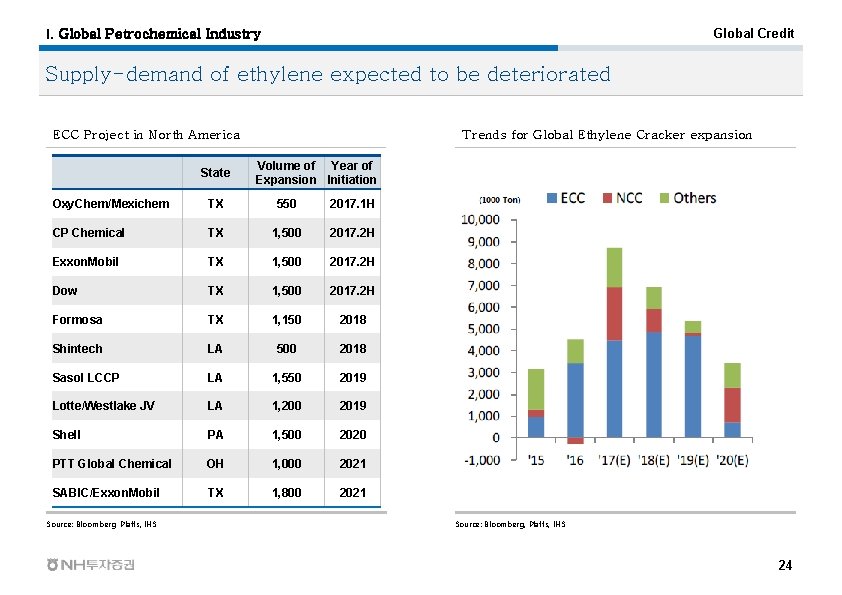
I. Global Petrochemical Industry Global Credit Supply-demand of ethylene expected to be deteriorated ECC Project in North America State Trends for Global Ethylene Cracker expansion Volume of Year of Expansion Initiation Oxy. Chem/Mexichem TX 550 2017. 1 H CP Chemical TX 1, 500 2017. 2 H Exxon. Mobil TX 1, 500 2017. 2 H Dow TX 1, 500 2017. 2 H Formosa TX 1, 150 2018 Shintech LA 500 2018 Sasol LCCP LA 1, 550 2019 Lotte/Westlake JV LA 1, 200 2019 Shell PA 1, 500 2020 PTT Global Chemical OH 1, 000 2021 SABIC/Exxon. Mobil TX 1, 800 2021 Source: Bloomberg, Platts, IHS 24
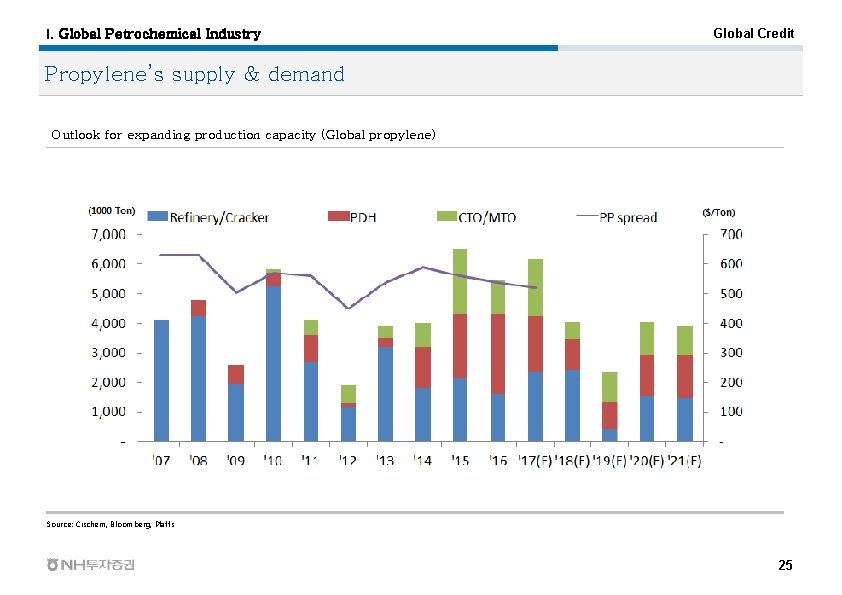
I. Global Petrochemical Industry Global Credit Propylene’s supply & demand Outlook for expanding production capacity (Global propylene) Source: Cischem, Bloomberg, Platts 25
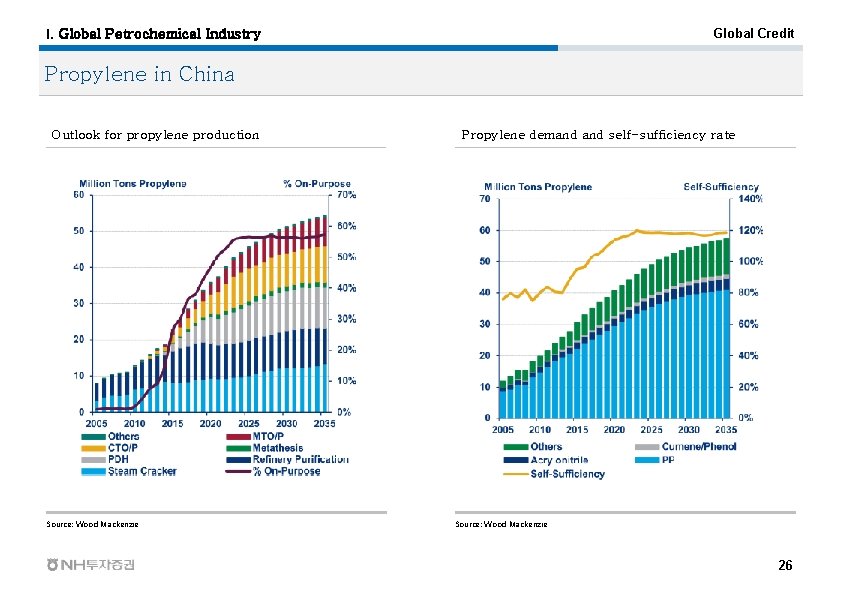
I. Global Petrochemical Industry Global Credit Propylene in China Outlook for propylene production Source: Wood Mackenzie Propylene demand self-sufficiency rate Source: Wood Mackenzie 26
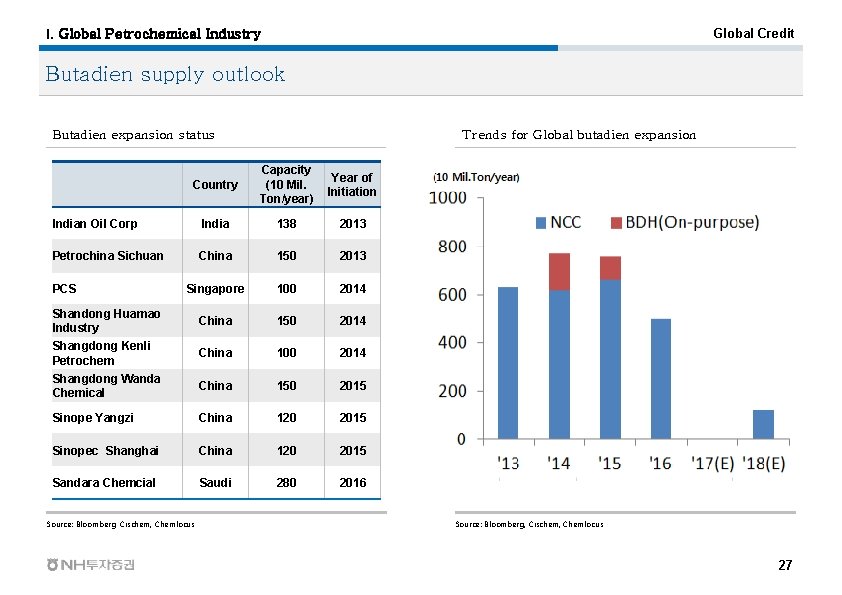
I. Global Petrochemical Industry Global Credit Butadien supply outlook Butadien expansion status Trends for Global butadien expansion Country Capacity (10 Mil. Ton/year) Year of Initiation Indian Oil Corp India 138 2013 Petrochina Sichuan China 150 2013 Singapore 100 2014 China 150 2014 China 100 2014 China 150 2015 Sinope Yangzi China 120 2015 Sinopec Shanghai China 120 2015 Sandara Chemcial Saudi 280 2016 PCS Shandong Huamao Industry Shangdong Kenli Petrochem Shangdong Wanda Chemical Source: Bloomberg, Cischem, Chemlocus 27
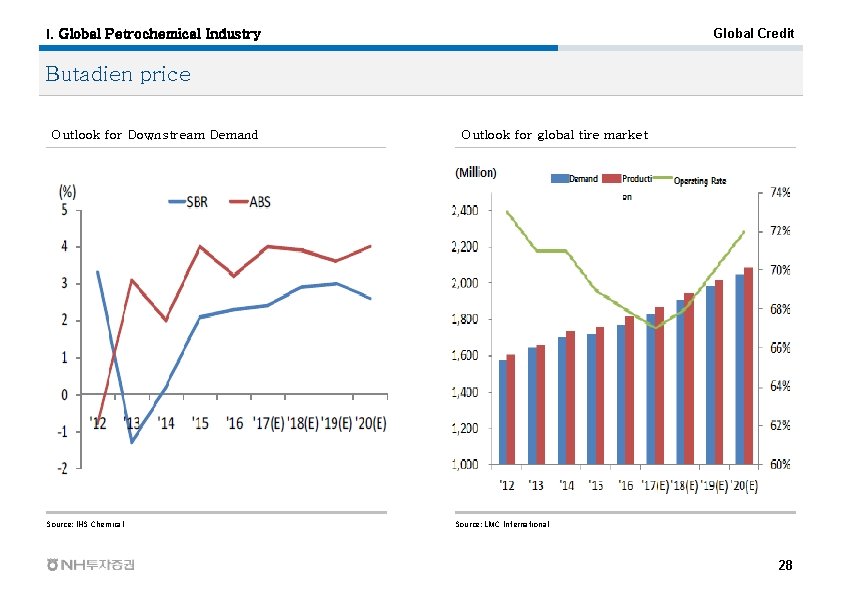
I. Global Petrochemical Industry Global Credit Butadien price Outlook for Downstream Demand Source: IHS Chemical Outlook for global tire market Source: LMC International 28
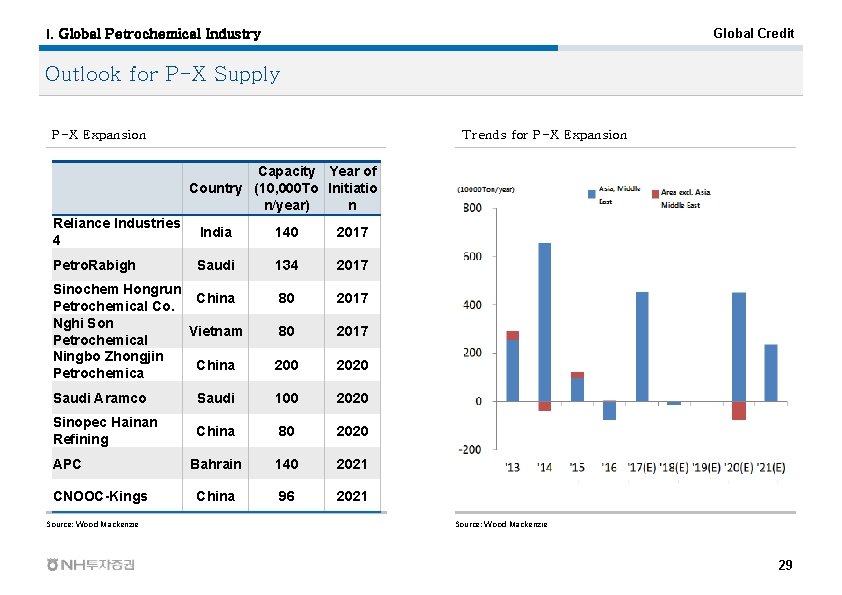
I. Global Petrochemical Industry Global Credit Outlook for P-X Supply P-X Expansion Trends for P-X Expansion Capacity Year of Country (10, 000 To Initiatio n/year) n Reliance Industries 4 India 140 2017 Petro. Rabigh Saudi 134 2017 80 2017 200 2020 Sinochem Hongrun China Petrochemical Co. Nghi Son Vietnam Petrochemical Ningbo Zhongjin China Petrochemica Saudi Aramco Saudi 100 2020 Sinopec Hainan Refining China 80 2020 Bahrain 140 2021 China 96 2021 APC CNOOC-Kings Source: Wood Mackenzie 29
Korea-Iran Economic cooperation -Petrochemical sector. I. Global Petrochemical Industry II. Iran Petrochemical Industry III. Petrochemical Cooperation with Korea-Iran NH Investment & Securities Global Credit Strategist: Hwan Jong (Louis) Shin tel 02) 768 -7590 │e-mail louis. shin@nhqv. com
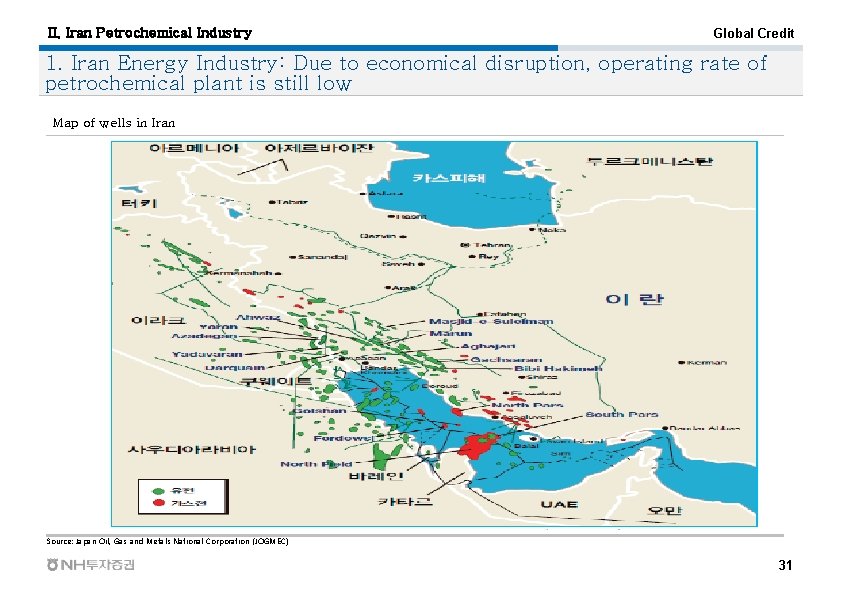
II. Iran Petrochemical Industry Global Credit 1. Iran Energy Industry: Due to economical disruption, operating rate of petrochemical plant is still low Map of wells in Iran Source: Japan Oil, Gas and Metals National Corporation (JOGMEC) 31
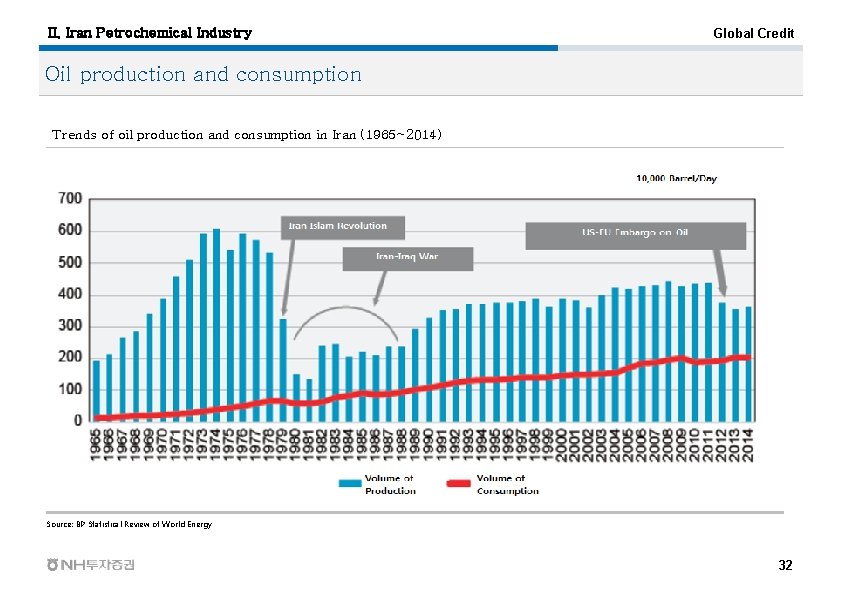
II. Iran Petrochemical Industry Global Credit Oil production and consumption Trends of oil production and consumption in Iran (1965~2014) Source: BP Statistical Review of World Energy 32
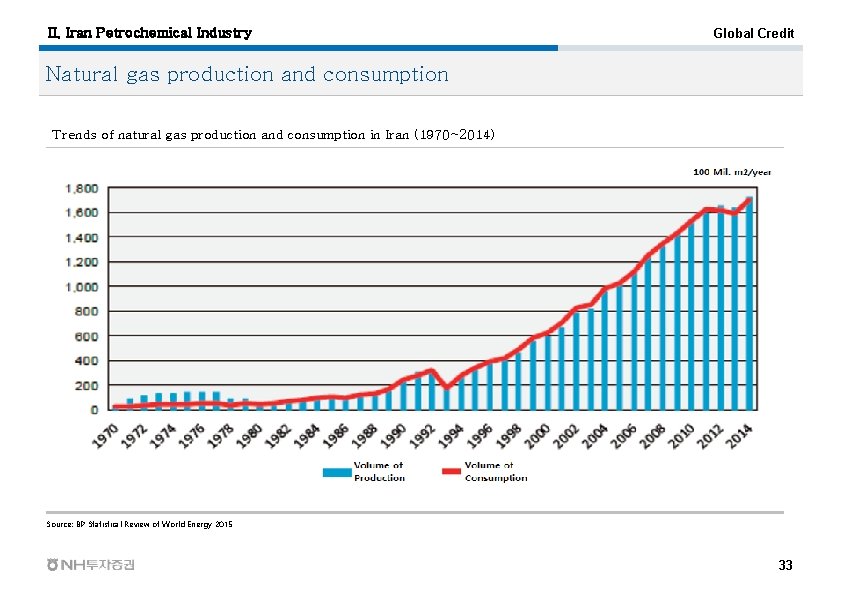
II. Iran Petrochemical Industry Global Credit Natural gas production and consumption Trends of natural gas production and consumption in Iran (1970~2014) Source: BP Statistical Review of World Energy 2015 33
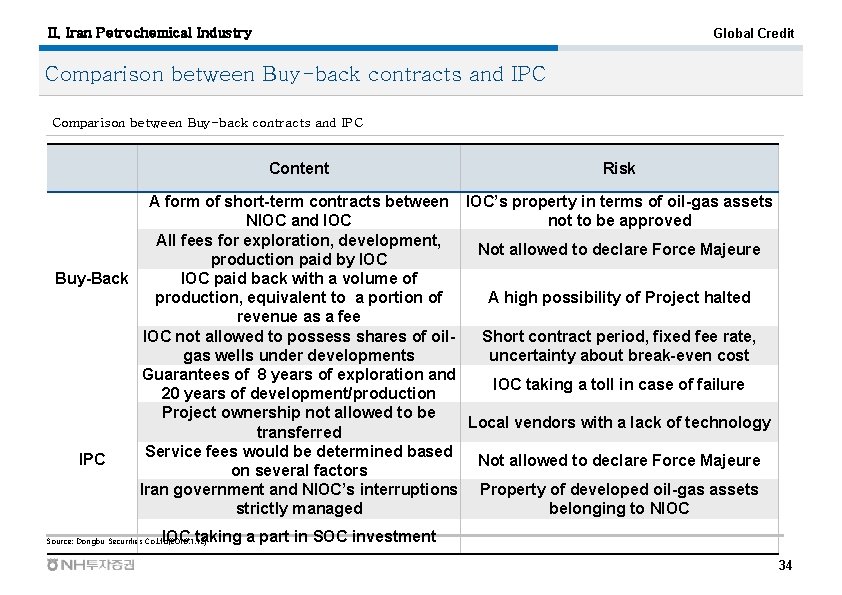
II. Iran Petrochemical Industry Global Credit Comparison between Buy-back contracts and IPC Content Risk A form of short-term contracts between IOC’s property in terms of oil-gas assets NIOC and IOC not to be approved All fees for exploration, development, Not allowed to declare Force Majeure production paid by IOC paid back with a volume of Buy-Back production, equivalent to a portion of A high possibility of Project halted revenue as a fee IOC not allowed to possess shares of oil. Short contract period, fixed fee rate, gas wells under developments uncertainty about break-even cost Guarantees of 8 years of exploration and IOC taking a toll in case of failure 20 years of development/production Project ownership not allowed to be Local vendors with a lack of technology transferred Service fees would be determined based IPC Not allowed to declare Force Majeure on several factors Iran government and NIOC’s interruptions Property of developed oil-gas assets strictly managed belonging to NIOC taking a part in SOC investment Source: Dongbu Securities Co. Ltd(2016. 1. 12) 34
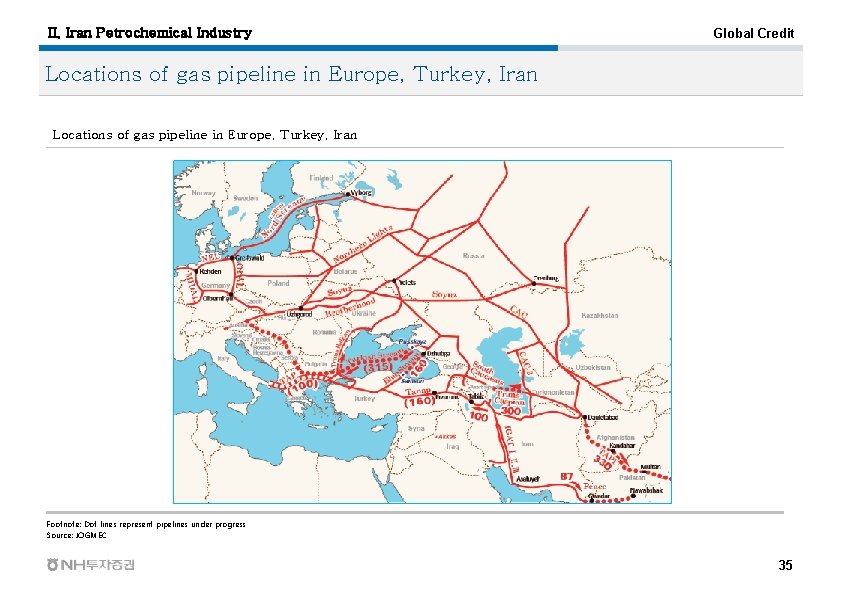
II. Iran Petrochemical Industry Global Credit Locations of gas pipeline in Europe, Turkey, Iran Footnote: Dot lines represent pipelines under progress Source: JOGMEC 35
II. Iran Petrochemical Industry Global Credit 2. Status of Petrochemical Industry in Iran 1) Status of Industry -Operating rate of petrochemical plant is still low due to economical disruption -Feedstock is Ethane -Olefin is the most productive feedstock -Petrochemcial hurbs are Mahshahr PETZone and Assaluyeh PSEEZ -Interruption by government is the factor lagging the development of petrochemical industry 2) Structure of Industry - NPC is a monopoly in Iran - Branches of NPC are under process of privatization 3) Current Issues -5 Petrochemical complex would be arranged as five-year term development plan - In Mahshahr PETZone, 7 plants are being constructed - In Assaluyeh PSEEZ, 22 plants are being constructed -Otehrs: Olefin, Polyethylene producing-facility expansion -West Ethylene pipeline construction project -Central Ethane-Ethylene pipeline construction project 36
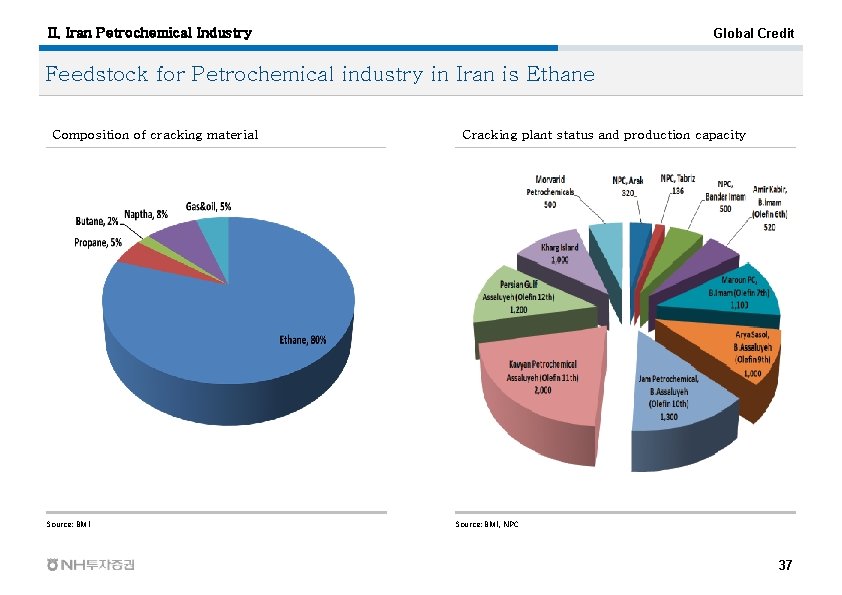
II. Iran Petrochemical Industry Global Credit Feedstock for Petrochemical industry in Iran is Ethane Composition of cracking material Source: BMI Cracking plant status and production capacity Source: BMI, NPC 37
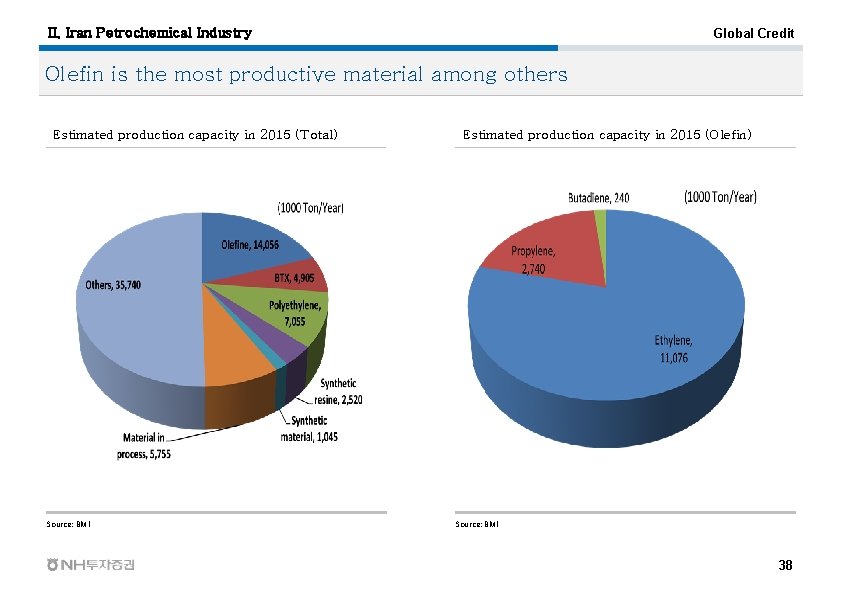
II. Iran Petrochemical Industry Global Credit Olefin is the most productive material among others Estimated production capacity in 2015 (Total) Source: BMI Estimated production capacity in 2015 (Olefin) Source: BMI 38
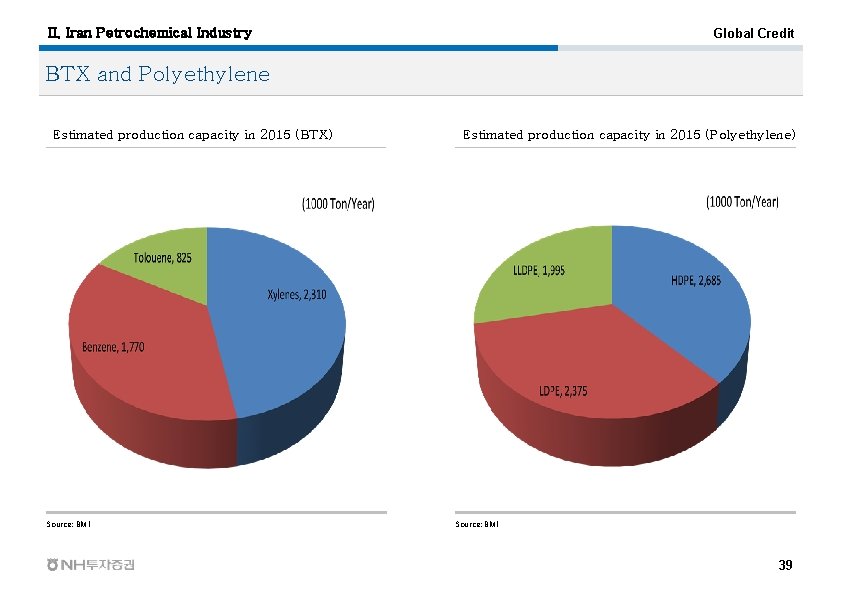
II. Iran Petrochemical Industry Global Credit BTX and Polyethylene Estimated production capacity in 2015 (BTX) Source: BMI Estimated production capacity in 2015 (Polyethylene) Source: BMI 39
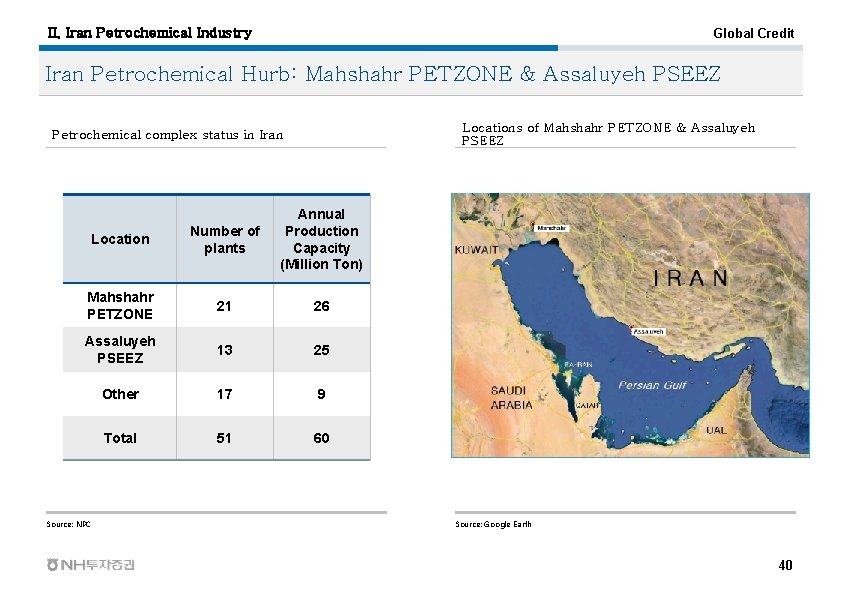
II. Iran Petrochemical Industry Global Credit Iran Petrochemical Hurb: Mahshahr PETZONE & Assaluyeh PSEEZ Locations of Mahshahr PETZONE & Assaluyeh PSEEZ Petrochemical complex status in Iran Location Number of plants Annual Production Capacity (Million Ton) Mahshahr PETZONE 21 26 Assaluyeh PSEEZ 13 25 Other 17 9 Total 51 60 Source: NPC Source: Google Earth 40
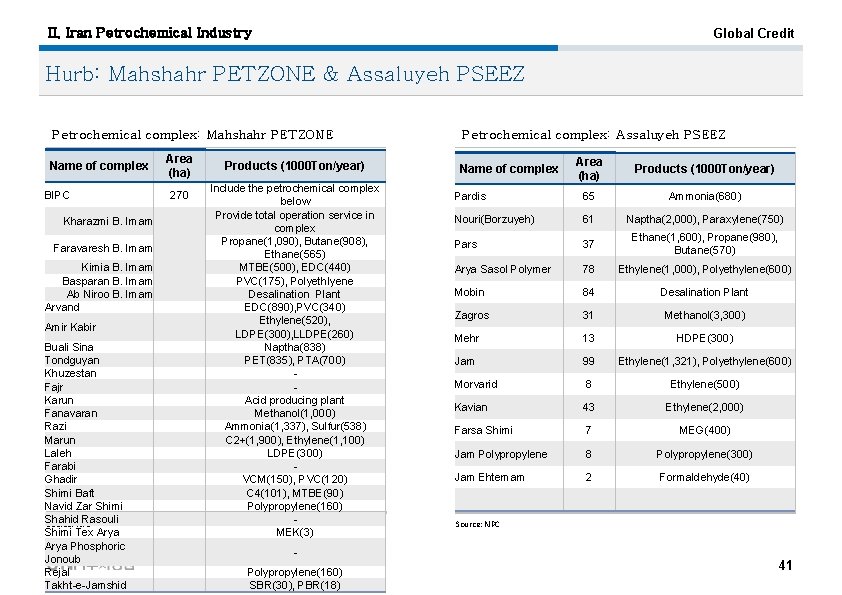
II. Iran Petrochemical Industry Global Credit Hurb: Mahshahr PETZONE & Assaluyeh PSEEZ Petrochemical complex: Mahshahr PETZONE Name of complex BIPC Kharazmi B. Imam Faravaresh B. Imam Kimia B. Imam Basparan B. Imam Ab Niroo B. Imam Arvand Amir Kabir Buali Sina Tondguyan Khuzestan Fajr Karun Fanavaran Razi Marun Laleh Farabi Ghadir Shimi Baft Navid Zar Shimi Shahid Rasouli Source: NPC Shimi Tex Arya Phosphoric Jonoub Rejal Takht-e-Jamshid Area (ha) 270 Products (1000 Ton/year) Include the petrochemical complex below Provide total operation service in complex Propane(1, 090), Butane(908), Ethane(565) MTBE(500), EDC(440) PVC(175), Polyethlyene Desalination Plant EDC(890), PVC(340) Ethylene(520), LDPE(300), LLDPE(260) Naptha(838) PET(835), PTA(700) Acid producing plant Methanol(1, 000) Ammonia(1, 337), Sulfur(538) C 2+(1, 900), Ethylene(1, 100) LDPE(300) VCM(150), PVC(120) C 4(101), MTBE(90) Polypropylene(160) MEK(3) Polypropylene(160) SBR(30), PBR(18) Petrochemical complex: Assaluyeh PSEEZ Area (ha) Products (1000 Ton/year) Pardis 65 Ammonia(680) Nouri(Borzuyeh) 61 Naptha(2, 000), Paraxylene(750) Pars 37 Ethane(1, 600), Propane(980), Butane(570) Arya Sasol Polymer 78 Ethylene(1, 000), Polyethylene(600) Mobin 84 Desalination Plant Zagros 31 Methanol(3, 300) Mehr 13 HDPE(300) Jam 99 Ethylene(1, 321), Polyethylene(600) Morvarid 8 Ethylene(500) Kavian 43 Ethylene(2, 000) Farsa Shimi 7 MEG(400) Jam Polypropylene 8 Polypropylene(300) Jam Ehtemam 2 Formaldehyde(40) Name of complex Source: NPC 41
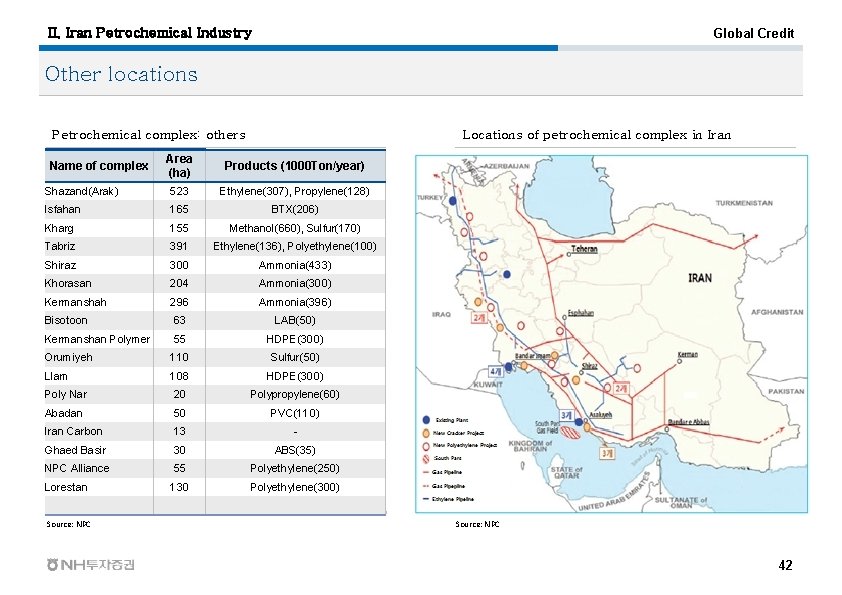
II. Iran Petrochemical Industry Global Credit Other locations Petrochemical complex: others Locations of petrochemical complex in Iran Area (ha) Products (1000 Ton/year) Shazand(Arak) 523 Ethylene(307), Propylene(128) Isfahan 165 BTX(206) Kharg 155 Methanol(660), Sulfur(170) Tabriz 391 Ethylene(136), Polyethylene(100) Shiraz 300 Ammonia(433) Khorasan 204 Ammonia(300) Kermanshah 296 Ammonia(396) Bisotoon 63 LAB(50) Kermanshan Polymer 55 HDPE(300) Orumiyeh 110 Sulfur(50) Llam 108 HDPE(300) Poly Nar 20 Polypropylene(60) Abadan 50 PVC(110) Iran Carbon 13 - Ghaed Basir 30 ABS(35) NPC Alliance 55 Polyethylene(250) Lorestan 130 Polyethylene(300) Name of complex Source: NPC 42
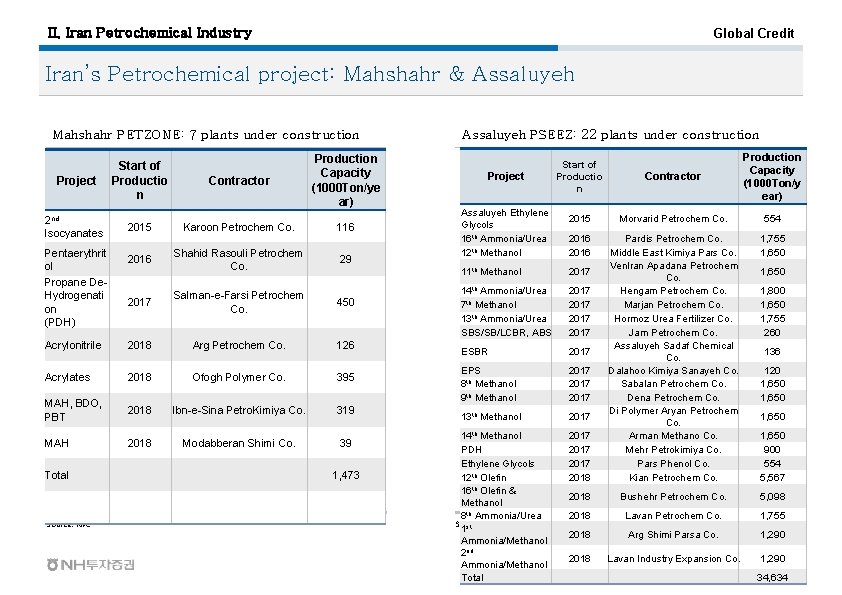
II. Iran Petrochemical Industry Global Credit Iran’s Petrochemical project: Mahshahr & Assaluyeh Mahshahr PETZONE: 7 plants under construction Project 2 nd Isocyanates Pentaerythrit ol Propane De. Hydrogenati on (PDH) Start of Productio n 2015 2016 Contractor Karoon Petrochem Co. Shahid Rasouli Petrochem Co. Production Capacity (1000 Ton/ye ar) 116 29 2017 Salman-e-Farsi Petrochem Co. 450 Acrylonitrile 2018 Arg Petrochem Co. 126 Acrylates 2018 Ofogh Polymer Co. 395 MAH, BDO, PBT 2018 Ibn-e-Sina Petro. Kimiya Co. 319 MAH 2018 Modabberan Shimi Co. 39 Total Source: NPC 1, 473 Assaluyeh PSEEZ: 22 plants under construction Project Assaluyeh Ethylene Glycols 16 th Ammonia/Urea 12 th Methanol Start of Productio n Contractor Production Capacity (1000 Ton/y ear) 2015 Morvarid Petrochem Co. 554 2016 1, 755 1, 650 2017 2018 Pardis Petrochem Co. Middle East Kimiya Pars Co. Venlran Apadana Petrochem Co. Hengam Petrochem Co. Marjan Petrochem Co. Hormoz Urea Fertilizer Co. Jam Petrochem Co. Assaluyeh Sadaf Chemical Co. Dalahoo Kimiya Sanayeh Co. Sabalan Petrochem Co. Dena Petrochem Co. Di Polymer Aryan Petrochem Co. Arman Methano Co. Mehr Petrokimiya Co. Pars Phenol Co. Kian Petrochem Co. 2018 Bushehr Petrochem Co. 5, 098 2018 Lavan Petrochem Co. 1, 755 2018 Arg Shimi Parsa Co. 1, 290 2018 Lavan Industry Expansion Co. 1, 290 11 th Methanol 2017 14 th Ammonia/Urea 7 th Methanol 13 th Ammonia/Urea SBS/SB/LCBR, ABS 2017 ESBR 2017 EPS 8 th Methanol 9 th Methanol 2017 13 th Methanol 2017 14 th Methanol PDH Ethylene Glycols 12 th Olefin 16 th Olefin & Methanol 8 th Ammonia/Urea Source: 1 st NPC Ammonia/Methanol 2 nd Ammonia/Methanol Total 1, 650 1, 800 1, 650 1, 755 260 136 120 1, 650 900 554 5, 567 43 34, 634
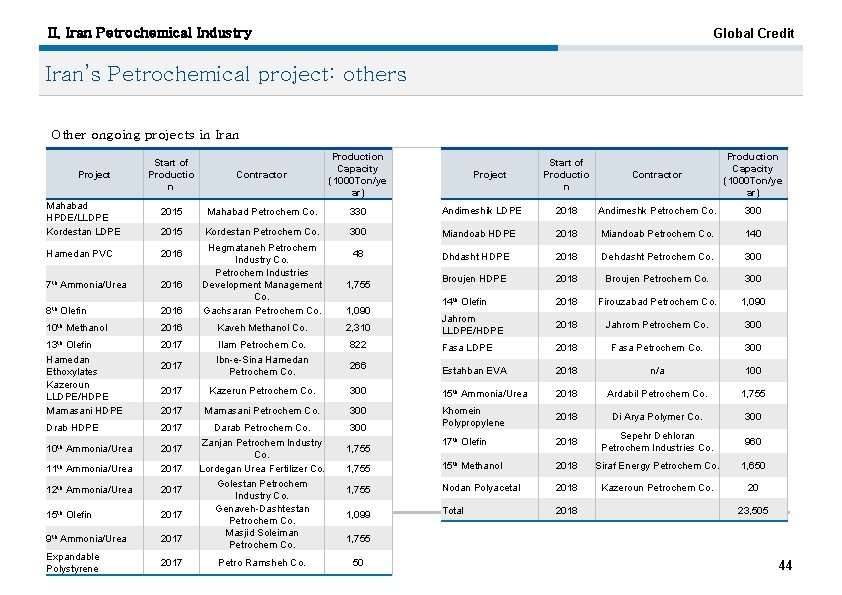
II. Iran Petrochemical Industry Global Credit Iran’s Petrochemical project: others Other ongoing projects in Iran Project Mahabad HPDE/LLDPE Kordestan LDPE Start of Productio n Contractor Production Capacity (1000 Ton/ye ar) 2015 Mahabad Petrochem Co. 330 2015 Kordestan Petrochem Co. Start of Productio n Contractor Production Capacity (1000 Ton/ye ar) Andimeshik LDPE 2018 Andimeshk Petrochem Co. 300 Miandoab HDPE 2018 Miandoab Petrochem Co. 140 48 Dhdasht HDPE 2018 Dehdasht Petrochem Co. 300 Broujen HDPE 2018 Broujen Petrochem Co. 300 14 th Olefin 2018 Firouzabad Petrochem Co. 1, 090 Jahrom LLDPE/HDPE 2018 Jahrom Petrochem Co. 300 Project Hamedan PVC 2016 7 th Ammonia/Urea 2016 8 th Olefin 2016 Hegmataneh Petrochem Industry Co. Petrochem Industries Development Management Co. Gachsaran Petrochem Co. 10 th Methanol 2016 Kaveh Methanol Co. 2, 310 13 th Olefin 2017 Ilam Petrochem Co. 822 Fasa LDPE 2018 Fasa Petrochem Co. 300 2017 Ibn-e-Sina Hamedan Petrochem Co. 266 Estahban EVA 2018 n/a 100 2017 Kazerun Petrochem Co. 300 15 th Ammonia/Urea 2018 Ardabil Petrochem Co. 1, 755 2017 Mamasani Petrochem Co. 300 2018 Di Arya Polymer Co. 300 2017 Darab Petrochem Co. Zanjan Petrochem Industry Co. Lordegan Urea Fertilizer Co. Golestan Petrochem Industry Co. Genaveh-Dashtestan Petrochem Co. Masjid Soleiman Petrochem Co. 300 Khomein Polypropylene 17 th Olefin 2018 Sepehr Dehloran Petrochem Industries Co. 960 1, 755 15 th Methanol 2018 Siraf Energy Petrochem Co. 1, 650 1, 755 Nodan Polyacetal 2018 Kazeroun Petrochem Co. 20 1, 099 Total 2018 Hamedan Ethoxylates Kazeroun LLDPE/HDPE Mamasani HDPE Drab HDPE 10 th Ammonia/Urea 2017 11 th Ammonia/Urea 2017 12 th Ammonia/Urea 2017 15 th Olefin 2017 9 th Ammonia/Urea 2017 Expandable Polystyrene 2017 Source: NPC Petro Ramsheh Co. 1, 755 1, 090 1, 755 23, 505 1, 755 50 44
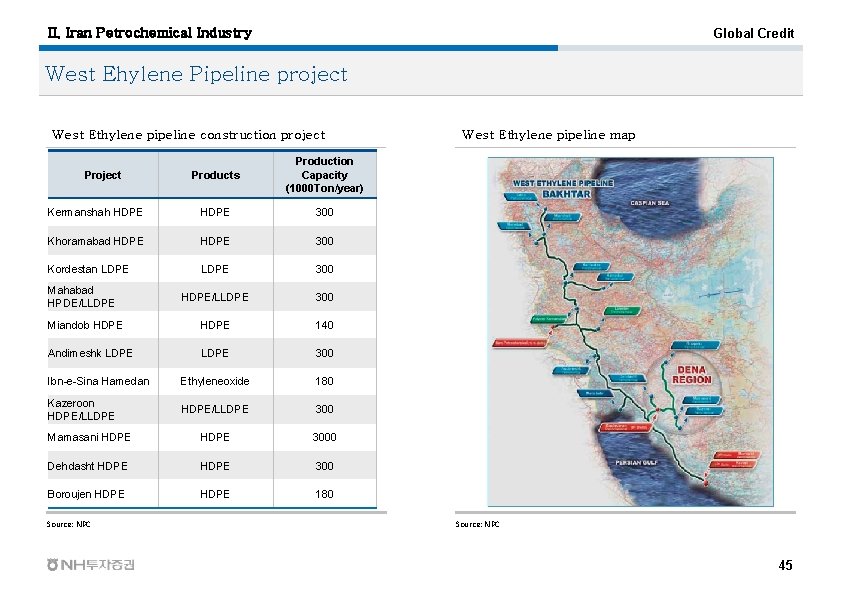
II. Iran Petrochemical Industry Global Credit West Ehylene Pipeline project West Ethylene pipeline construction project Products Production Capacity (1000 Ton/year) Kermanshah HDPE 300 Khoramabad HDPE 300 Kordestan LDPE 300 HDPE/LLDPE 300 Miandob HDPE 140 Andimeshk LDPE 300 Ibn-e-Sina Hamedan Ethyleneoxide 180 Kazeroon HDPE/LLDPE 300 Mamasani HDPE 3000 Dehdasht HDPE 300 Boroujen HDPE 180 Project Mahabad HPDE/LLDPE Source: NPC West Ethylene pipeline map Source: NPC 45
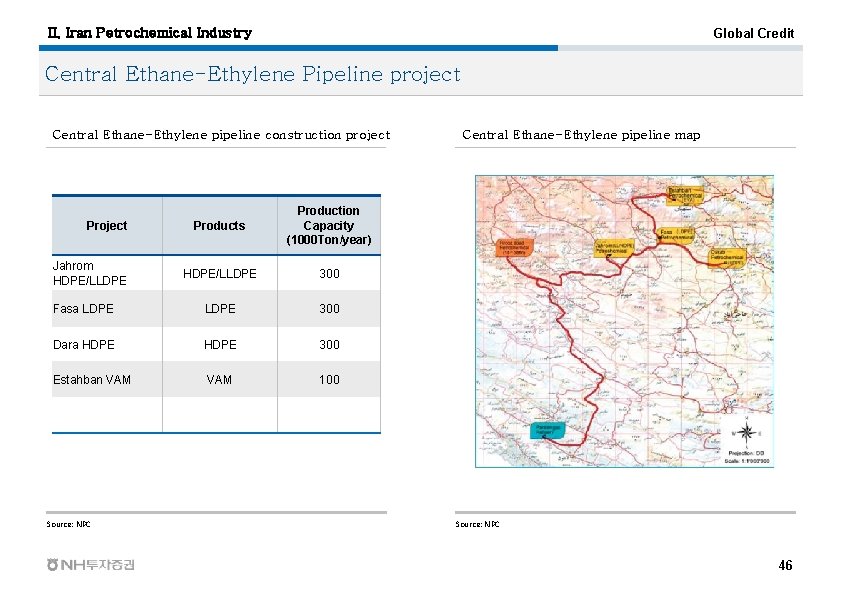
II. Iran Petrochemical Industry Global Credit Central Ethane-Ethylene Pipeline project Central Ethane-Ethylene pipeline construction project Products Production Capacity (1000 Ton/year) HDPE/LLDPE 300 Fasa LDPE 300 Dara HDPE 300 VAM 100 Project Jahrom HDPE/LLDPE Estahban VAM Source: NPC Central Ethane-Ethylene pipeline map Source: NPC 46
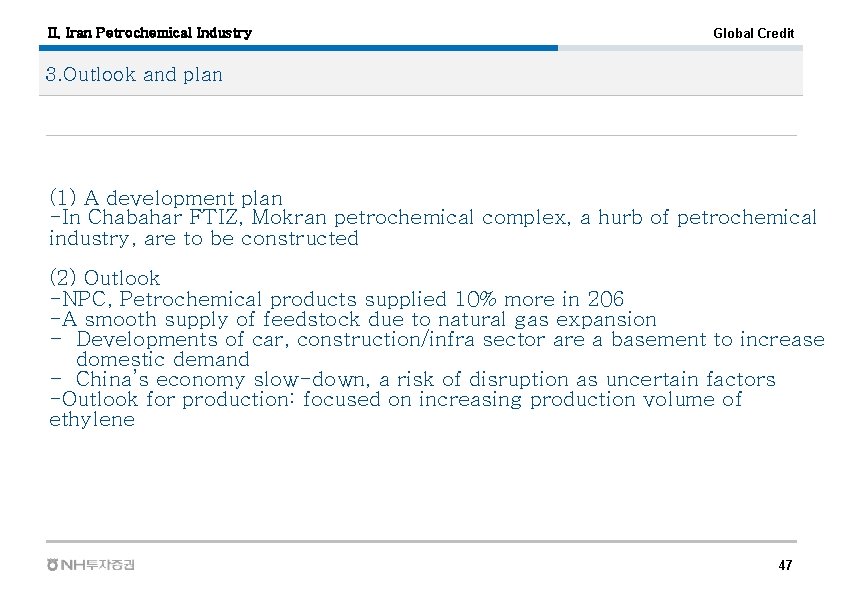
II. Iran Petrochemical Industry Global Credit 3. Outlook and plan (1) A development plan -In Chabahar FTIZ, Mokran petrochemical complex, a hurb of petrochemical industry, are to be constructed (2) Outlook -NPC, Petrochemical products supplied 10% more in 206 -A smooth supply of feedstock due to natural gas expansion - Developments of car, construction/infra sector are a basement to increase domestic demand - China’s economy slow-down, a risk of disruption as uncertain factors -Outlook for production: focused on increasing production volume of ethylene 47
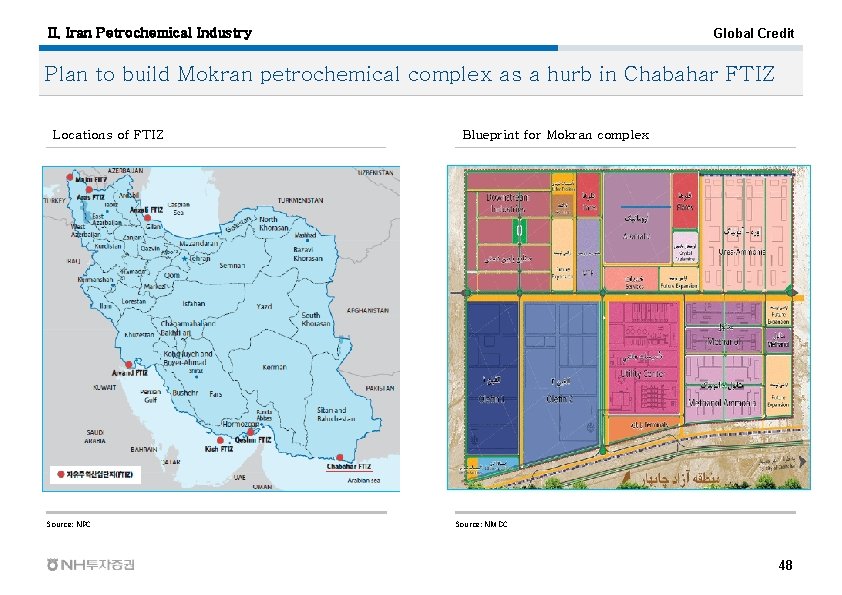
II. Iran Petrochemical Industry Global Credit Plan to build Mokran petrochemical complex as a hurb in Chabahar FTIZ Locations of FTIZ Source: NPC Blueprint for Mokran complex Source: NMDC 48
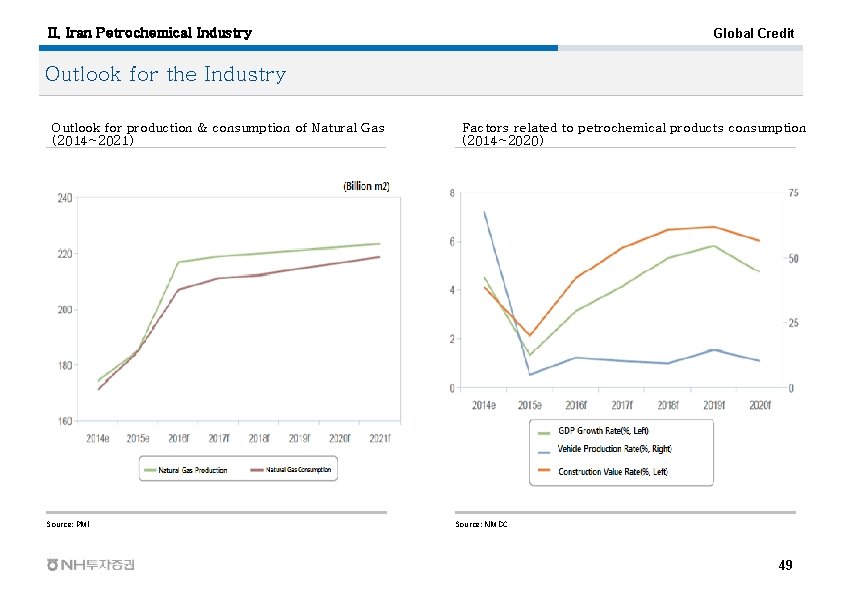
II. Iran Petrochemical Industry Global Credit Outlook for the Industry Outlook for production & consumption of Natural Gas (2014~2021) Source: PMI Factors related to petrochemical products consumption (2014~2020) Source: NMDC 49
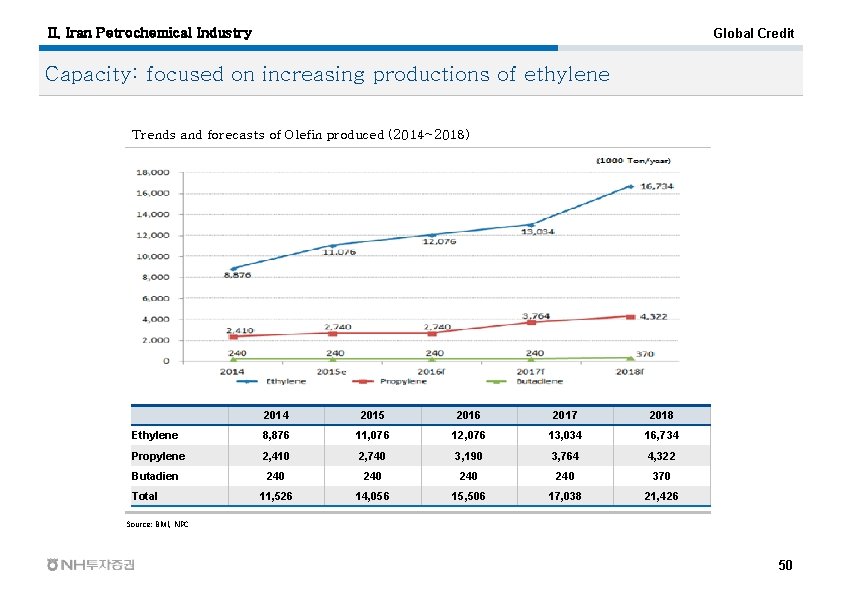
II. Iran Petrochemical Industry Global Credit Capacity: focused on increasing productions of ethylene Trends and forecasts of Olefin produced (2014~2018) 2014 2015 2016 2017 2018 Ethylene 8, 876 11, 076 12, 076 13, 034 16, 734 Propylene 2, 410 2, 740 3, 190 3, 764 4, 322 Butadien 240 240 370 11, 526 14, 056 15, 506 17, 038 21, 426 Total Source: BMI, NPC 50
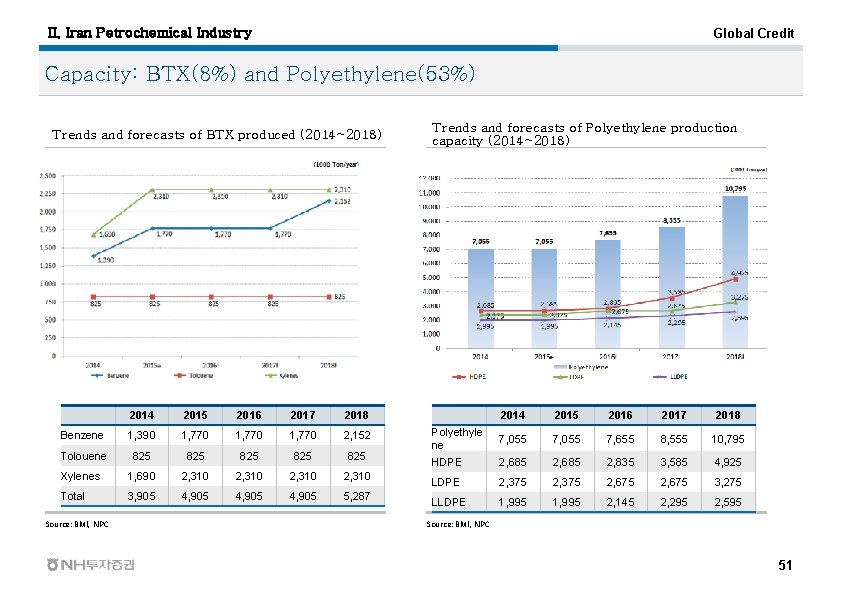
II. Iran Petrochemical Industry Global Credit Capacity: BTX(8%) and Polyethylene(53%) Trends and forecasts of BTX produced (2014~2018) 2014 2015 2016 2017 2018 Benzene 1, 390 1, 770 2, 152 Tolouene 825 825 825 Xylenes 1, 690 2, 310 Total 3, 905 4, 905 5, 287 Source: BMI, NPC Trends and forecasts of Polyethylene production capacity (2014~2018) 2014 2015 2016 2017 2018 Polyethyle ne 7, 055 7, 655 8, 555 10, 795 HDPE 2, 685 2, 835 3, 585 4, 925 LDPE 2, 375 2, 675 3, 275 LLDPE 1, 995 2, 145 2, 295 2, 595 Source: BMI, NPC 51
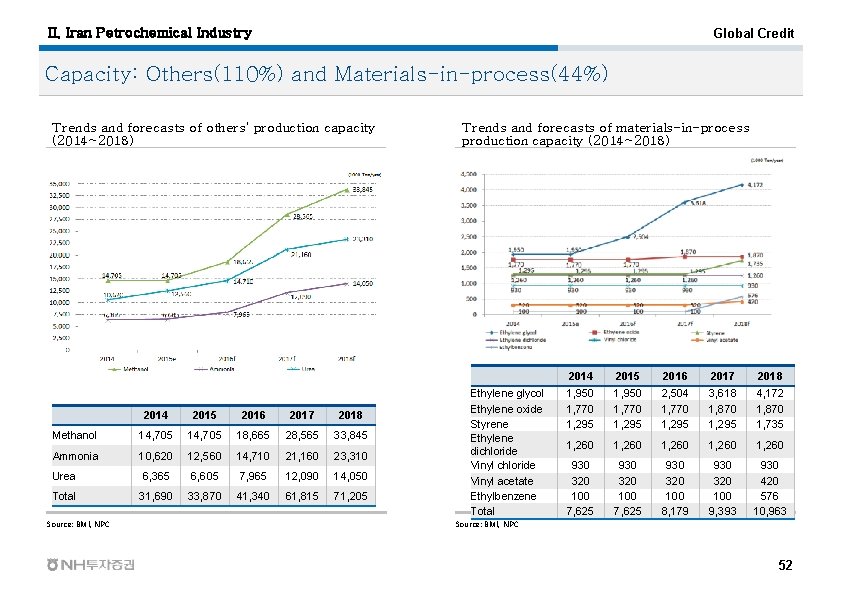
II. Iran Petrochemical Industry Global Credit Capacity: Others(110%) and Materials-in-process(44%) Trends and forecasts of others’ production capacity (2014~2018) 2014 2015 2016 2017 2018 Methanol 14, 705 18, 665 28, 565 33, 845 Ammonia 10, 620 12, 560 14, 710 21, 160 23, 310 Urea 6, 365 6, 605 7, 965 12, 090 14, 050 Total 31, 690 33, 870 41, 340 61, 815 71, 205 Source: BMI, NPC Trends and forecasts of materials-in-process production capacity (2014~2018) Ethylene glycol Ethylene oxide Styrene Ethylene dichloride Vinyl acetate Ethylbenzene Total 2014 2015 2016 2017 2018 1, 950 1, 770 1, 295 2, 504 1, 770 1, 295 3, 618 1, 870 1, 295 4, 172 1, 870 1, 735 1, 260 1, 260 930 320 100 7, 625 930 320 100 8, 179 930 320 100 9, 393 930 420 576 10, 963 Source: BMI, NPC 52
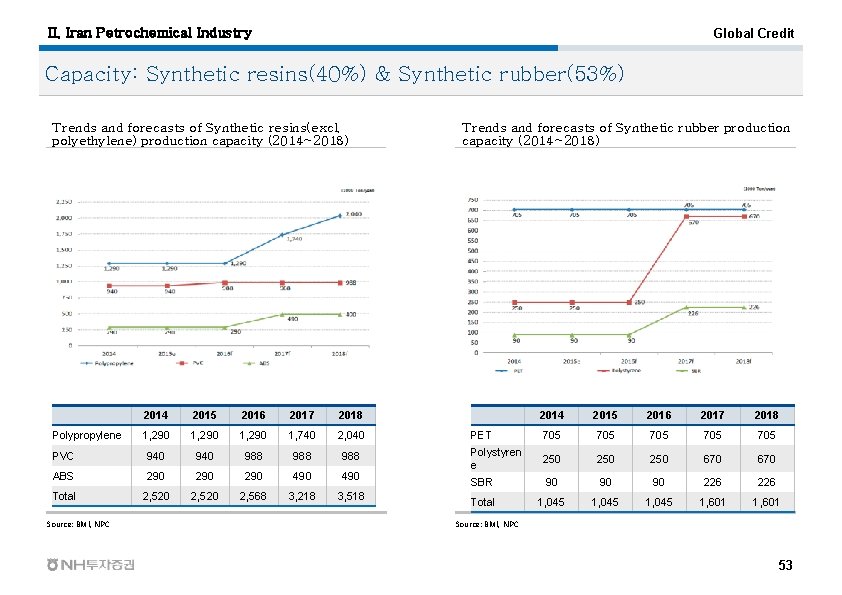
II. Iran Petrochemical Industry Global Credit Capacity: Synthetic resins(40%) & Synthetic rubber(53%) Trends and forecasts of Synthetic resins(excl. polyethylene) production capacity (2014~2018) 2014 2015 2016 2017 2018 1, 290 1, 740 2, 040 PVC 940 988 988 ABS 290 290 490 Total 2, 520 2, 568 3, 218 3, 518 Polypropylene Source: BMI, NPC Trends and forecasts of Synthetic rubber production capacity (2014~2018) 2014 2015 2016 2017 2018 PET 705 705 705 Polystyren e 250 250 670 SBR 90 90 90 226 Total 1, 045 1, 601 Source: BMI, NPC 53
Korea-Iran Economic cooperation -Petrochemical sector. I. Global Petrochemical Industry II. Iran Petrochemical Industry III. Petrochemical Cooperation with Korea-Iran NH Investment & Securities Global Credit Strategist: Hwan Jong (Louis) Shin tel 02) 768 -7590 │e-mail louis. shin@nhqv. com
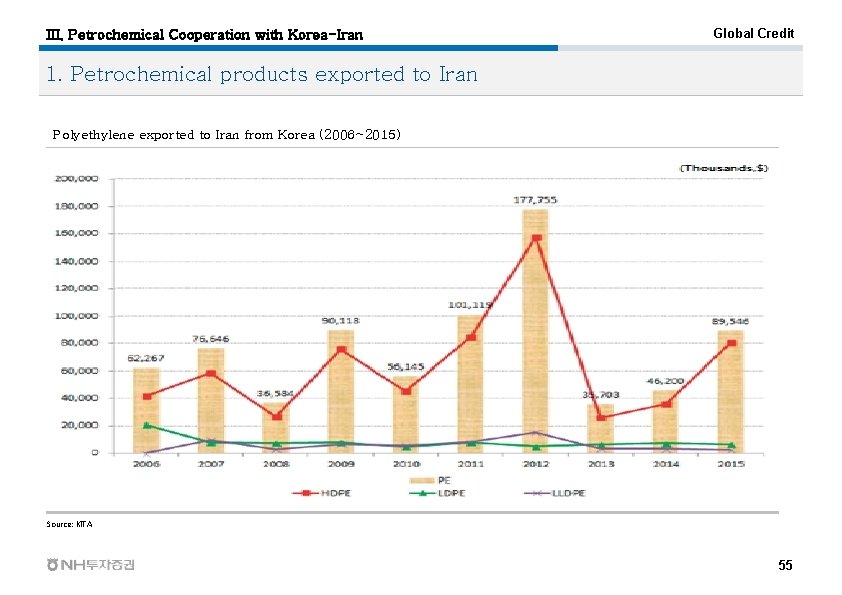
III. Petrochemical Cooperation with Korea-Iran Global Credit 1. Petrochemical products exported to Iran Polyethylene exported to Iran from Korea (2006~2015) Source: KITA 55
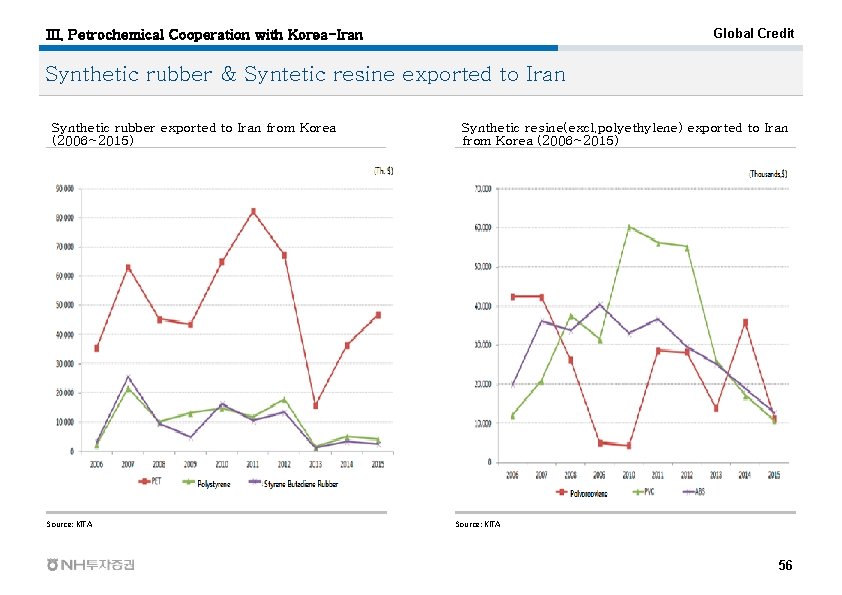
Global Credit III. Petrochemical Cooperation with Korea-Iran Synthetic rubber & Syntetic resine exported to Iran Synthetic rubber exported to Iran from Korea (2006~2015) Source: KITA Synthetic resine(excl. polyethylene) exported to Iran from Korea (2006~2015) Source: KITA 56
III. Petrochemical Cooperation with Korea-Iran Global Credit 2. Petrochemical cooperation with Korea and Iran ① Utilized as diverse ways of procuring Feedstocks such as Naptha, Condensate, Butadien ② In the previous 10 years (2006~2016), exports to Iran from Koreas are polyethylene, synthesis resin, synthesis rubber. Further competition expected to be intensified ③ Need to pay attention to exporting facilities in a response to Iran’s expanding investment in petrochemical industry ④ Possibility for JV investment in case of exporting to Iran and Europe - Global petrochemical companies(Dow, Total, etc) promote the expansion of petrochemical complex by coordination with companies in middle east(SABIC, QP, etc). Stable supply, low transportation cost would be anticipated - Review on going into polypropylene business with Hyosung’s NPC. Looking for the opportunity and optimization by going into local business - Risk: possibility of Snapback as per changes of geopolitical circumstances. Lack of policy of securing probable investment 57
- Slides: 57