
JJ Mois Anne SMILOVICE Jan Necka Dana Chromkov

- Slides: 15
JJ Mois Année SMILOVICE Jan Neckař Dana Chromíková
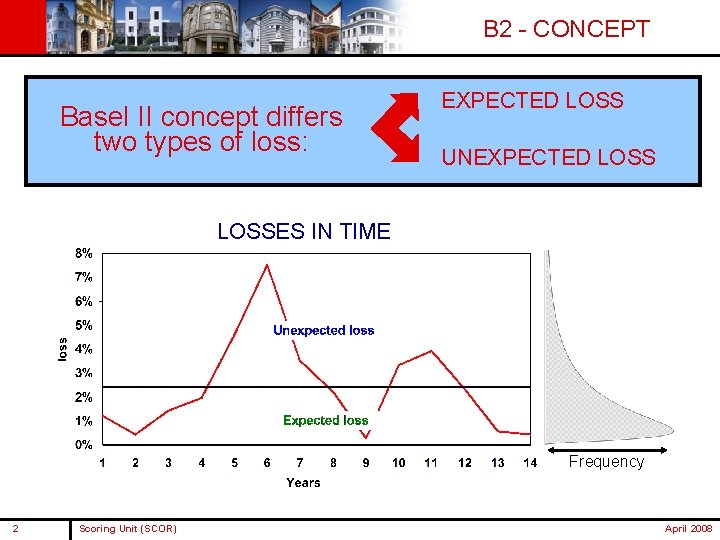
B 2 - CONCEPT Basel II concept differs two types of loss: EXPECTED LOSS UNEXPECTED LOSSES IN TIME Frequency 2 Scoring Unit (SCOR) April 2008
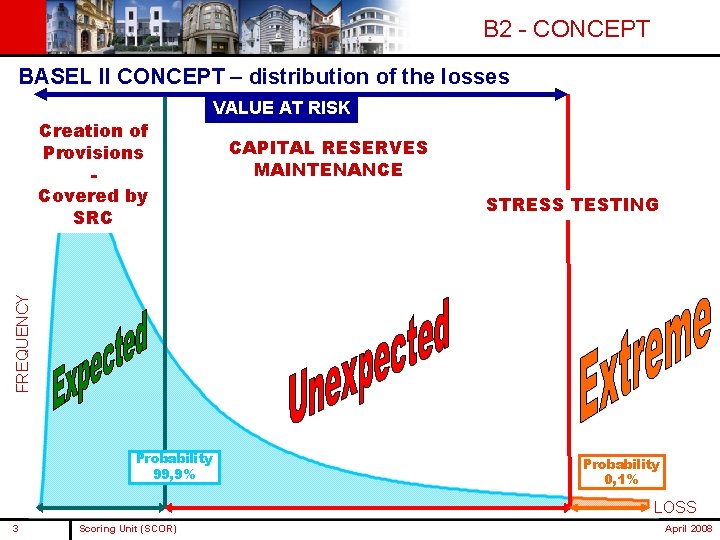
B 2 - CONCEPT BASEL II CONCEPT – distribution of the losses CAPITAL RESERVES MAINTENANCE STRESS TESTING FREQUENCY Creation of Provisions Covered by SRC VALUE AT RISK Probability 99, 9% Probability 0, 1% LOSS 3 Scoring Unit (SCOR) April 2008
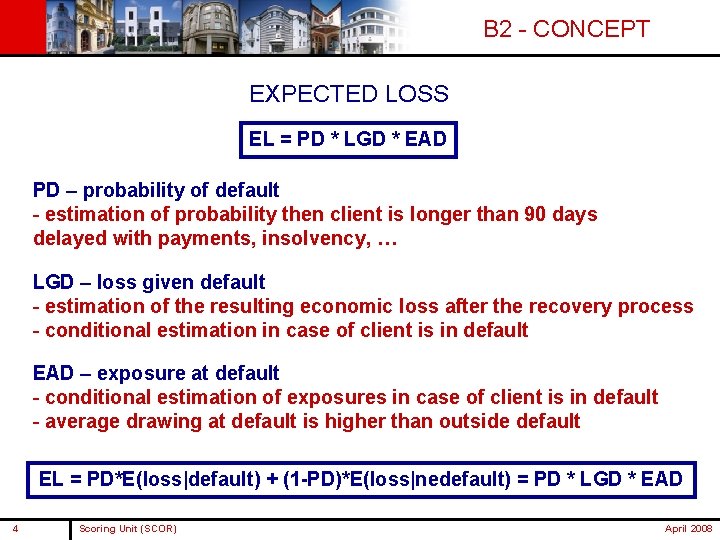
B 2 - CONCEPT EXPECTED LOSS EL = PD * LGD * EAD PD – probability of default - estimation of probability then client is longer than 90 days delayed with payments, insolvency, … LGD – loss given default - estimation of the resulting economic loss after the recovery process - conditional estimation in case of client is in default EAD – exposure at default - conditional estimation of exposures in case of client is in default - average drawing at default is higher than outside default EL = PD*E(loss|default) + (1 -PD)*E(loss|nedefault) = PD * LGD * EAD 4 Scoring Unit (SCOR) April 2008
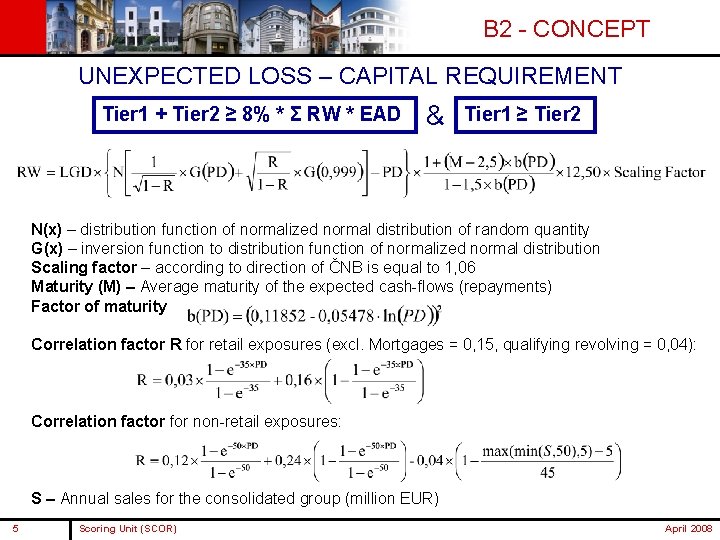
B 2 - CONCEPT UNEXPECTED LOSS – CAPITAL REQUIREMENT Tier 1 + Tier 2 ≥ 8% * Σ RW * EAD & Tier 1 ≥ Tier 2 N(x) – distribution function of normalized normal distribution of random quantity G(x) – inversion function to distribution function of normalized normal distribution Scaling factor – according to direction of ČNB is equal to 1, 06 Maturity (M) – Average maturity of the expected cash-flows (repayments) Factor of maturity Correlation factor R for retail exposures (excl. Mortgages = 0, 15, qualifying revolving = 0, 04): Correlation factor for non-retail exposures: S – Annual sales for the consolidated group (million EUR) 5 Scoring Unit (SCOR) April 2008
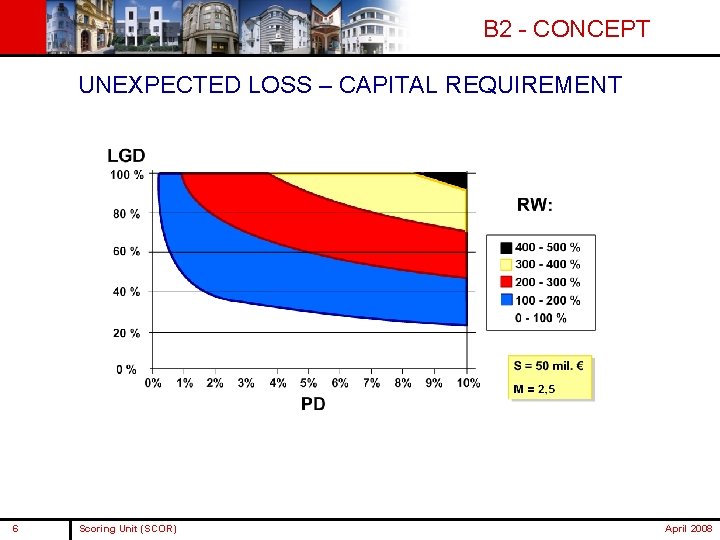
B 2 - CONCEPT UNEXPECTED LOSS – CAPITAL REQUIREMENT 6 Scoring Unit (SCOR) April 2008
STRESS-TESTING Behavior under stress is not easy to predict 7 Scoring Unit (SCOR) April 2008
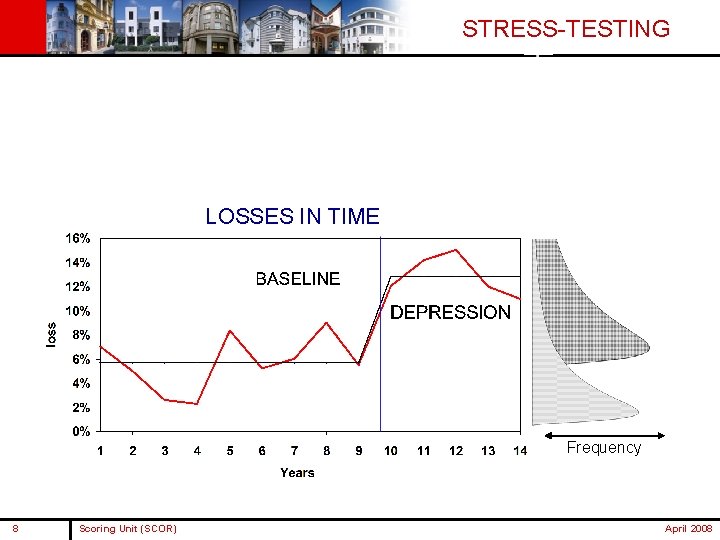
STRESS-TESTING LOSSES IN TIME Frequency 8 Scoring Unit (SCOR) April 2008
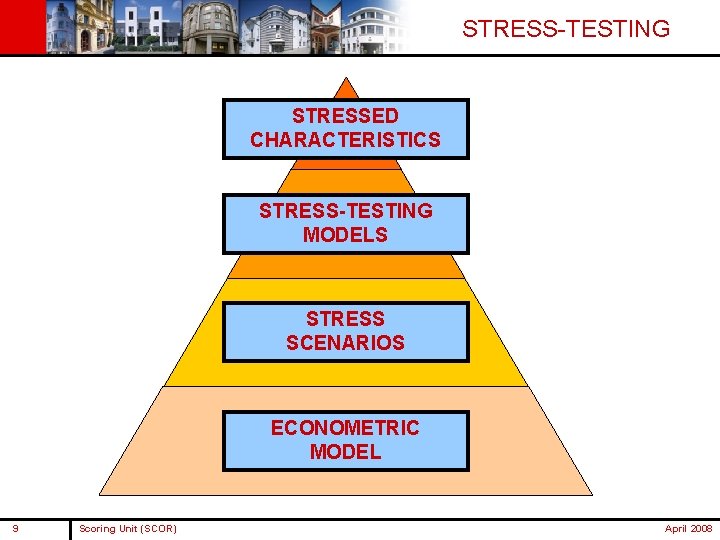
STRESS-TESTING STRESSED CHARACTERISTICS STRESS-TESTING MODELS STRESS SCENARIOS ECONOMETRIC MODEL 9 Scoring Unit (SCOR) April 2008
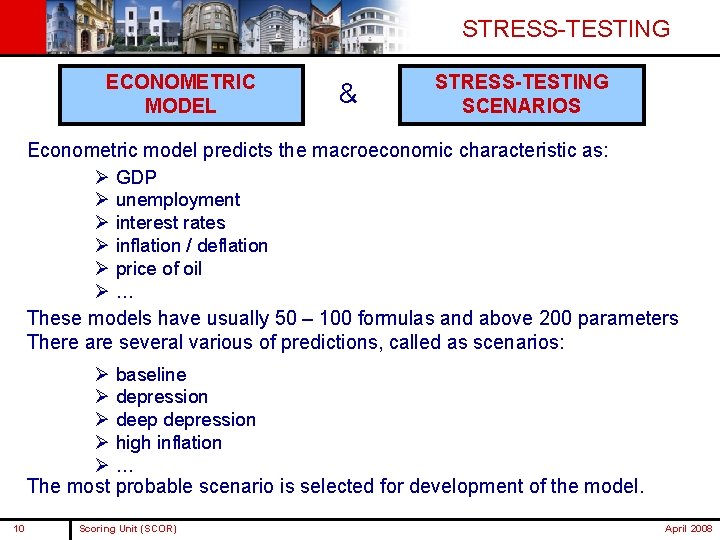
STRESS-TESTING ECONOMETRIC MODEL & STRESS-TESTING SCENARIOS Econometric model predicts the macroeconomic characteristic as: Ø GDP Ø unemployment Ø interest rates Ø inflation / deflation Ø price of oil Ø… These models have usually 50 – 100 formulas and above 200 parameters There are several various of predictions, called as scenarios: Ø baseline Ø depression Ø deep depression Ø high inflation Ø… The most probable scenario is selected for development of the model. 10 Scoring Unit (SCOR) April 2008
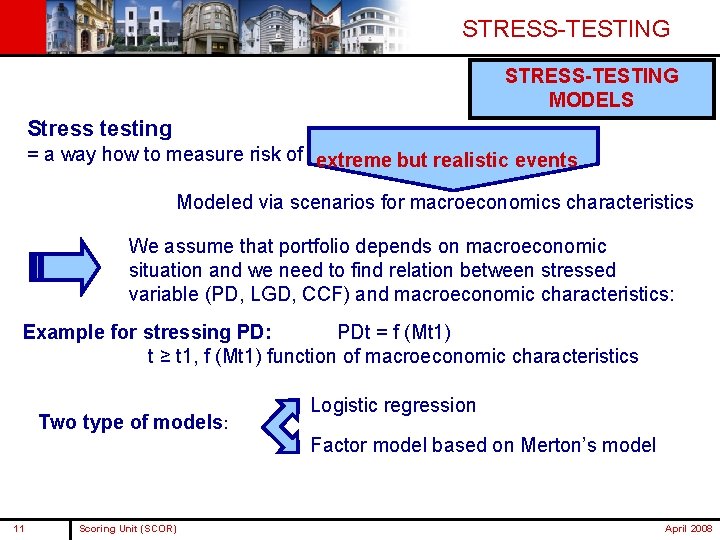
STRESS-TESTING MODELS Stress testing = a way how to measure risk of extreme but realistic events Modeled via scenarios for macroeconomics characteristics We assume that portfolio depends on macroeconomic situation and we need to find relation between stressed variable (PD, LGD, CCF) and macroeconomic characteristics: Example for stressing PD: PDt = f (Mt 1) t ≥ t 1, f (Mt 1) function of macroeconomic characteristics Two type of models: Logistic regression Factor model based on Merton’s model 11 Scoring Unit (SCOR) April 2008
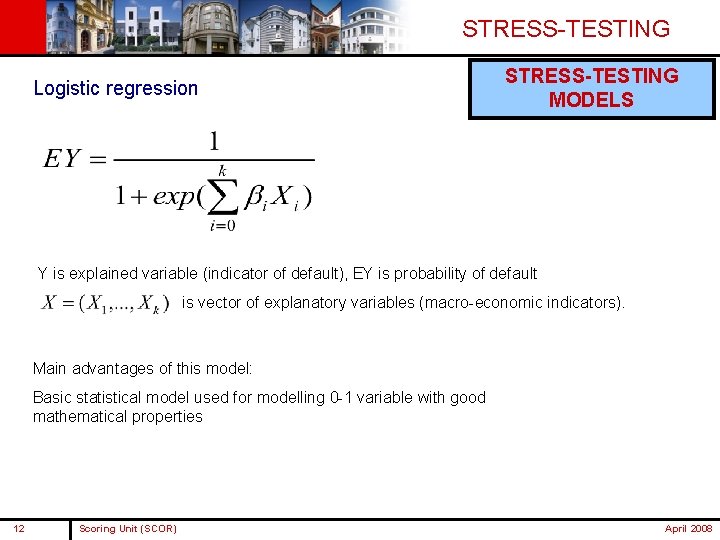
STRESS-TESTING Logistic regression STRESS-TESTING MODELS Y is explained variable (indicator of default), EY is probability of default is vector of explanatory variables (macro-economic indicators). Main advantages of this model: Basic statistical model used for modelling 0 -1 variable with good mathematical properties 12 Scoring Unit (SCOR) April 2008
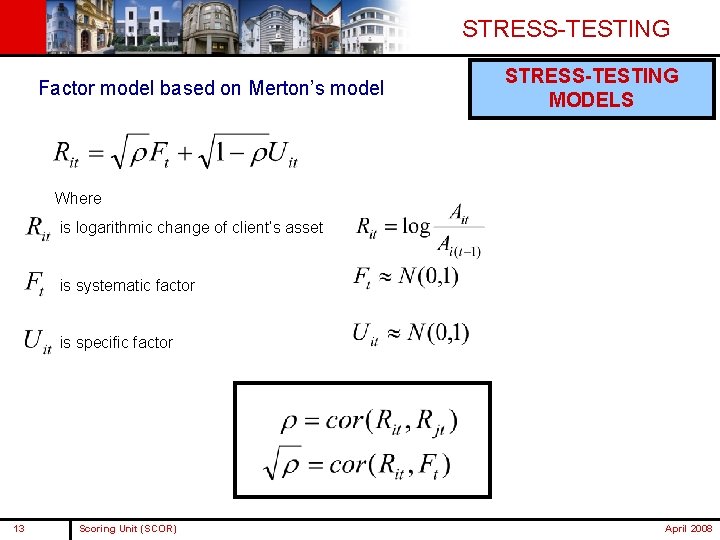
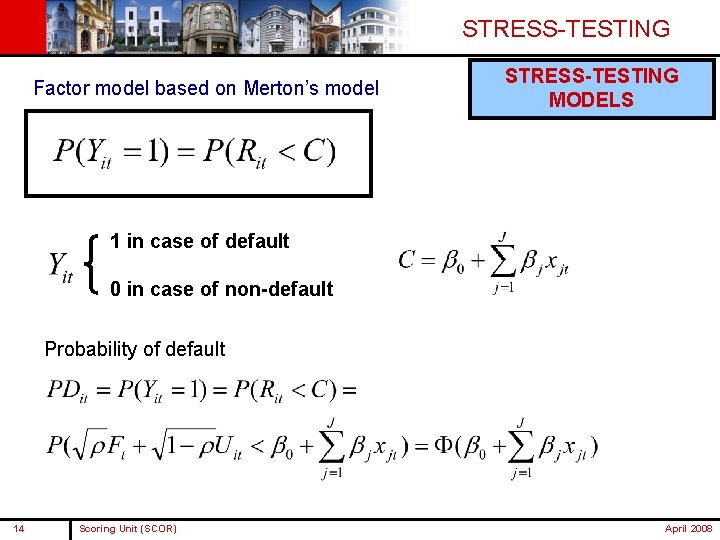
STRESS-TESTING Factor model based on Merton’s model STRESS-TESTING MODELS Where is logarithmic change of client’s asset is systematic factor is specific factor 13 Scoring Unit (SCOR) April 2008
STRESS-TESTING Factor model based on Merton’s model STRESS-TESTING MODELS 1 in case of default 0 in case of non-default Probability of default 14 Scoring Unit (SCOR) April 2008
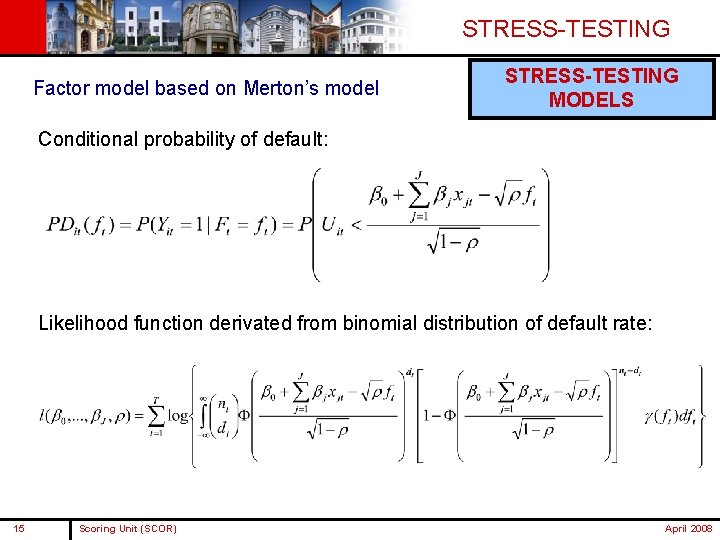
STRESS-TESTING Factor model based on Merton’s model STRESS-TESTING MODELS Conditional probability of default: Likelihood function derivated from binomial distribution of default rate: 15 Scoring Unit (SCOR) April 2008