
Jan Snel Baker Mc Kenzie Amsterdam N V
Jan Snel Baker & Mc. Kenzie Amsterdam N. V. is een vennootschap van Baker & Mc. Kenzie Internationaal, een Zwitserse Verein waarvan vennootschappen over de gehele wereld lid zijn. In overeenstemming met de in de professionele dienstverlening gebruikelijke terminologie wordt met de term "partner" bedoeld personen die partner zijn van een dergelijke vennootschap of een daaraan gelijkwaardige functie bekleden. De term "kantoor" wordt gebruikt om te verwijzen naar een vestiging van een dergelijke vennootschap. © 2014 Baker & Mc. Kenzie Amsterdam N. V.
VAT / Customs (I) – Import VAT reverse charge license (Art 23 code license) – Contributes Cash Flow Advantage The Netherlands allows for “VAT free” importation of products into the European Union. With an import VAT reverse charge license the levy of Dutch import VAT is shifted to the periodical VAT return instead of payment upon importation. As such, importation of products is VAT free since the import VAT due can be reclaimed in the same VAT return (i. e. , no cash flow disadvantage). – Rulings – Contributes Advanced Certainty Dutch customs accepts the need for legal certainty for the importer. Therefore, Dutch customs is very cooperative in this respect. It is standard practice to issue rulings with respect to customs classification, (non-) preferential origin and valuation on an expedient and transparent basis. 2 © 2014 Baker & Mc. Kenzie Amsterdam N. V.
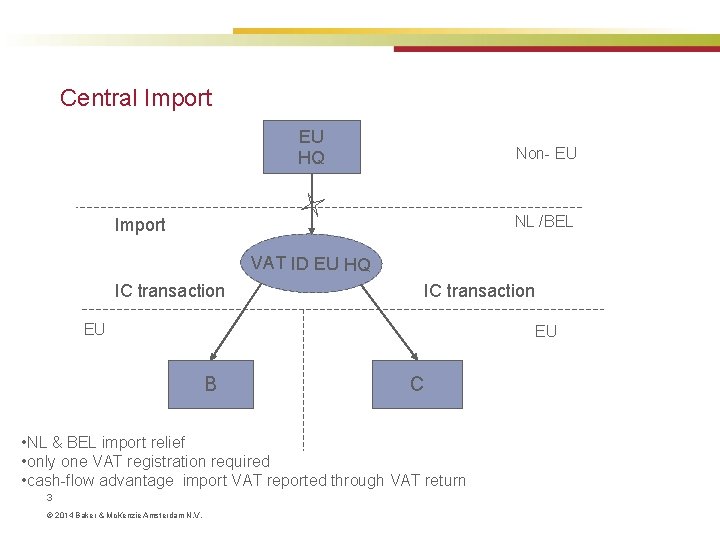
Central Import EU HQ Non- EU NL /BEL Import VAT ID EU HQ IC transaction EU EU B C • NL & BEL import relief • only one VAT registration required • cash-flow advantage import VAT reported through VAT return 3 © 2014 Baker & Mc. Kenzie Amsterdam N. V.
VAT / Customs (II) Dutch customs classification and European VAT – – – Upon request of BV (Netherlands) the Dutch customs authorities can issue Binding Tariff Information (“BTI”). For customs purposes, these BTI’s are valid throughout the European Union, regardless of the Member State which issued it. The main customs benefit to the holder of BTI’s is legal certainty with regard to customs tariff classification. This is important as such customs tariff classification is the basis for determining customs duties, export refunds and the application of other related legal provisions (e. g. import/export certificates), but can also be leading for the VAT qualification. For the application of the (super) reduced VAT rates, EU Member States qualify products into product categories: e. g. pharmaceutical products, medical equipment for disabled persons, medical/dental care, etc. BTI’s could be benificial to support the VAT qualification in EU Member States, especially to categorise products into categories that benefit from the (super) reduced VAT rates. Dutch customs authorities are known for their cooperative and pragmatic approach towards issuing BTI’s and as such are often used to obtain beneficial BTI’s that are used throughout the EU for applying the (super) reduced VAT rate. 4 © 2014 Baker & Mc. Kenzie Amsterdam N. V.
Are Pringles potato chips (crisps)? ‒ Proctor & Gamble – No (0%) § Mouth melt taste… uniform color… regular shape not found in nature…” ‒ HMRC/VAT Tribunal – Yes (17. 5%) ‒ High Court – No (0%) § Insufficient potato content in the potato chip ‒ Court of Appeal – Yes (17. 5%) © 2014 Baker & Mc. Kenzie Amsterdam N. V.
VAT / Customs (III) Dutch customs classification and European VAT – Contributes to Margins and/or Competitive Position EXAMPLE*: *) The purpose of this example is an explanation of the system; further detailed analyses of Medline’s HS codes is required in this respect. – – – HS Code 3005(9031): wadding, gauze, bandages, prepared dressings, poultices, similar articles. For this HS Code, BV (Netherlands) obtains with Dutch customs authorities the BTI classification “pharmaceutical product”. Throughout Europe, EU Member States apply the (super) reduced rate on pharmaceutical products: Category: BE BG CZ DK DE EE EL ES Pharmaceutical products 6 (21) 20 14 25 19 9 6. 5 (13, 23) 4 (18) – 6 FR IE 2, 1 (7, 19. 6) 0 (23) IT CY LV LT LU HU MT NL AT PL PT RO SI SK FI SE UK 10 (21) 5 12 5 3 (15) 5 (27) 0 6 (19) 10 8 6 (23) 9 8. 5 10 9 25 (0) 0 (20) Local tax authorities of EU Member States rely on Dutch BTI customs classification as pharmaceutical product for the application of the (super) reduced VAT rate instead of indepth reviewing whether the underlying product can be qualified as “pharmaceutical product” for VAT purposes. © 2014 Baker & Mc. Kenzie Amsterdam N. V.
Corporate Income Tax From a Corporate Income Tax (“CIT”) perspective the following issues can be of importance: § § § § Nominal CIT rate Rulings to come to a lower effective CIT rate Incentives for IP income Exemption of branch profits Participation exemption Dividend Withholding Tax on distribution Treaty Network © 2014 Baker & Mc. Kenzie Amsterdam N. V.
- Slides: 7