
Ivan Martin CEO Misys Banking Division Agenda Misys
Ivan Martin CEO Misys Banking Division
Agenda Misys Banking Division Strategy Ivan Martin Business Drivers Steve Gowers Product Management Jerry Luckett Break Three Great Stories Summit. FT Georges Bory Midas. Plus Andrew White Equation. Plus Andrew Derrer Summary Ivan Martin Questions and Answers All
Key messages 1. Banking is a large and growing software market 2. Misys is well positioned to benefit from this growth 3. Misys leads in functionality and technology 4. Misys is growing its market share in key markets 5. Retail is key growth sector going forward
Where we? What did we do? Where are we now?
Where we? What did we do? Where are we now?
What did we see in 2002? In 2002 you told me … “Products are old legacy back office systems” “Losing market share to competitors” “We see no product roadmap for the future” “There is a risk the business will not benefit from a recovery in spending”
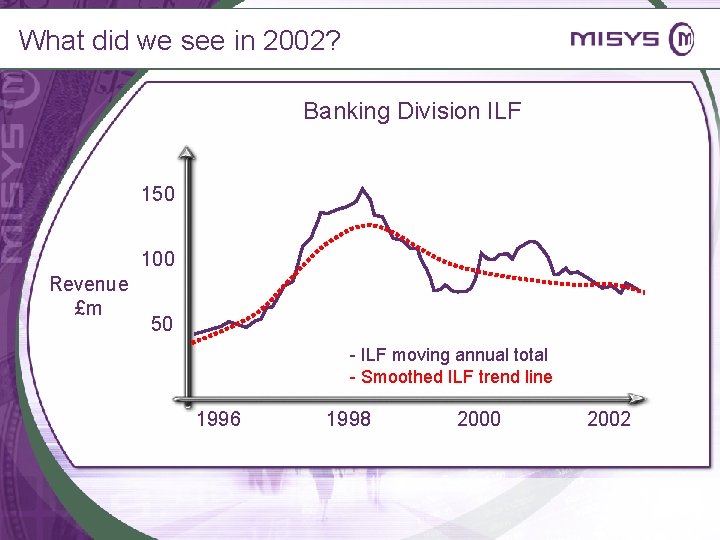
What did we see in 2002? Banking Division ILF 150 100 Revenue £m 50 - ILF moving annual total - Smoothed ILF trend line 1996 1998 2000 2002
Where we? What did we do? Where are we now?
What did we do? Columbus Product Management Portfolio Management Services Talent Management R&D investment
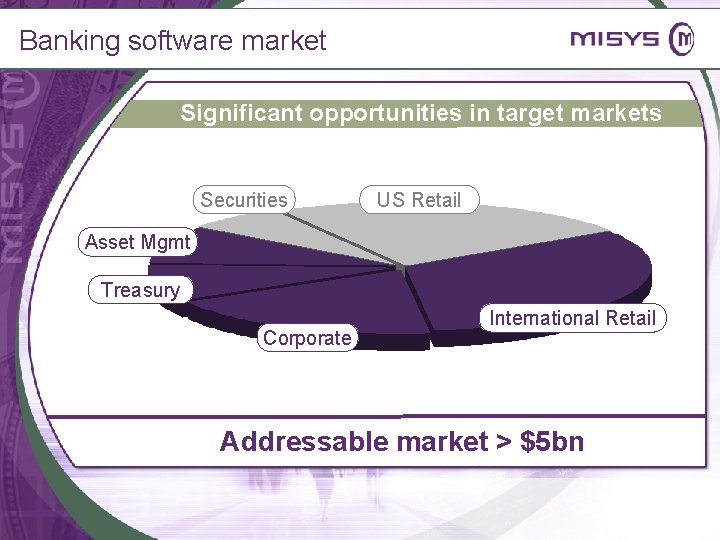
Banking software market Significant opportunities in target markets Securities US Retail Asset Mgmt Treasury Corporate International Retail Addressable market > $5 bn
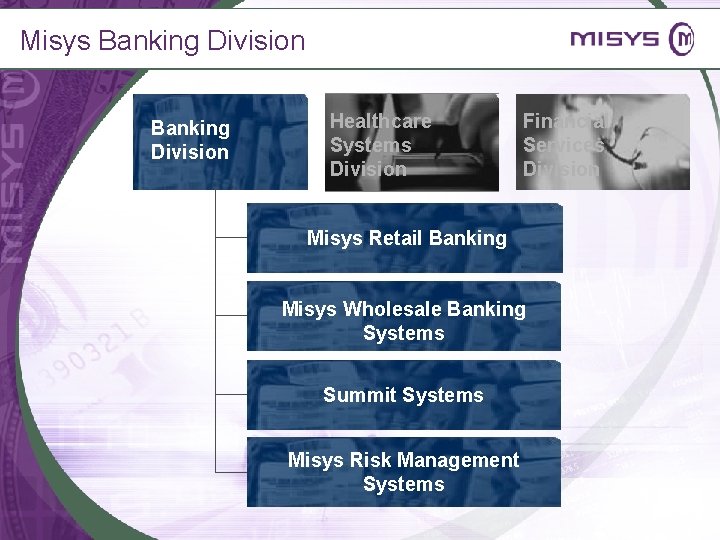
Misys Banking Division Healthcare Systems Division Financial Services Division Misys Retail Banking Misys Wholesale Banking Systems Summit Systems Misys Risk Management Systems
What did we do? Columbus Product Management Portfolio Management Services Talent Management R&D investment
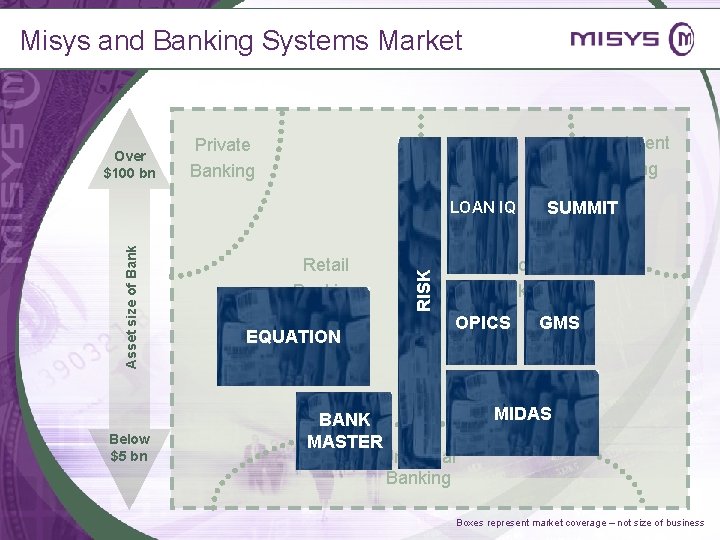
Misys and Banking Systems Market Over $100 bn Investment Banking Private Banking Below $5 bn Retail Banking EQUATION SUMMIT Corporate Banking RISK Asset size of Bank LOAN IQ OPICS BANK MASTER Universal Banking GMS MIDAS Boxes represent market coverage – not size of business
What did we do? Columbus Product Management Portfolio Management Services Talent Management R&D investment
What did we do? Columbus Product Management Portfolio Management Services Talent Management R&D investment
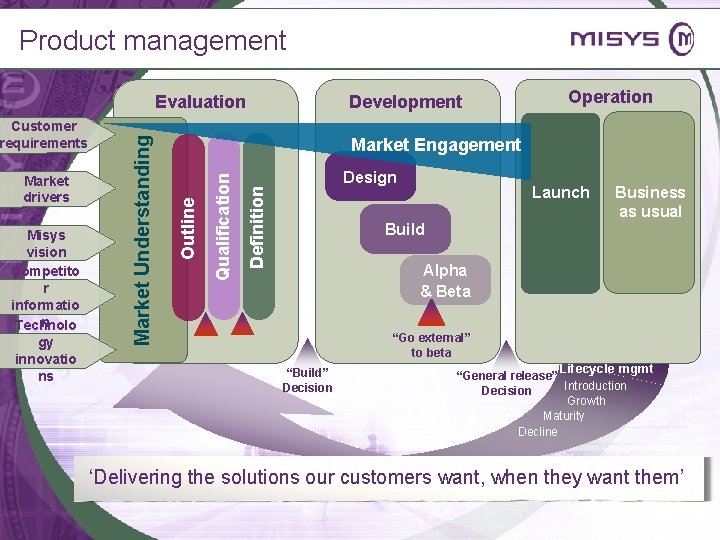
Product management Design Definition Misys vision Competito r informatio n Technolo gy innovatio ns Qualification Market drivers Development Operation Market Engagement Outline Customer requirements Market Understanding Evaluation Launch Business as usual Build Alpha & Beta “Go external” to beta “Build” Decision Lifecycle mgmt “General release” Introduction Decision Growth Maturity Decline ‘Delivering the solutions our customers want, when they want them’
What did we do? Columbus Product Management Portfolio Management Services Talent Management R&D investment
What did we do? Columbus Product Management Portfolio Management Services Talent Management R&D investment
R&D Man Days (, 000) 140 Front-office 100 + 55% 60 Technology 20 Back-office 0 2003/4 2006/7 Increasing offshore capacity
Where we? What did we do? Where are we now?
Banking market conditions • Banking software markets are generally improving • Conditions vary significantly between sectors – Retail banking continues to show sustained growth – Wholesale banking and capital markets have stabilised – Marked regional differences; activity in emerging markets • Underlying market drivers still apply – Cost containment – Regulation – Rising consumer expectations • Long term trends continue – Move away from in-house software to third party packages
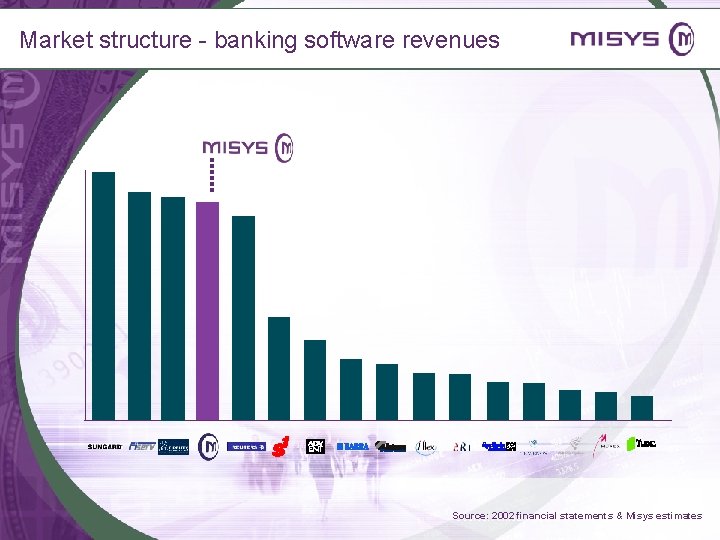
Market structure - banking software revenues Source: 2002 financial statements & Misys estimates Source: Annual Reports and Private Company estimates.
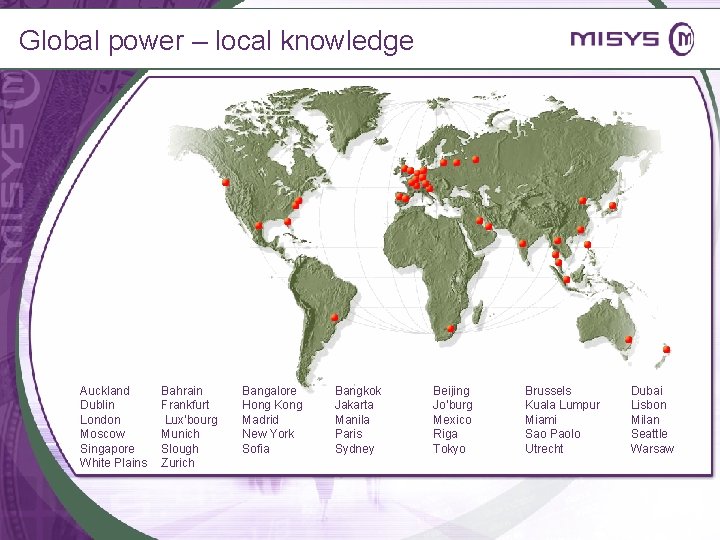
Global power – local knowledge Auckland Dublin London Moscow Singapore White Plains Bahrain Frankfurt Lux’bourg Munich Slough Zurich Bangalore Hong Kong Madrid New York Sofia Bangkok Jakarta Manila Paris Sydney Beijing Jo’burg Mexico Riga Tokyo Brussels Kuala Lumpur Miami Sao Paolo Utrecht Dubai Lisbon Milan Seattle Warsaw
Achievements in 2004 Portfolio moved to new areas of growth Increased investment in R&D Retail benefiting from market facing structure Increased Treasury & Capital Markets market share Strong evidence of traction in our installed base
Achievements in 2004 Best increase in H 2 order intake in 3 years Closing order book up strongly Maintenance revenues stable H 2 professional services grew by 20% Professional Services backlog grew by greater than 70%
Business Drivers Steve Gowers Business Development Director Misys Banking Division
Misys focus • Misys is focused on providing business critical systems in specialist vertical markets • Characteristics of vertical markets: – – – Depth of industry knowledge Depth of software IPR Specialist skills able to rapidly deliver solutions Demand for mature and proven systems Long lead times • Different drivers from ‘horizontal’ markets (e. g. ERP)
How do vendors compete in vertical markets? What drives growth in vertical markets?
How do vendors compete in vertical markets? What drives growth in vertical markets?
Competitive dynamics in vertical markets 1. Breadth of product portfolio 2. Depth of IPR 3. Size & quality of development capability 4. Breadth and depth of geographic network 5. Ability to sell into installed base
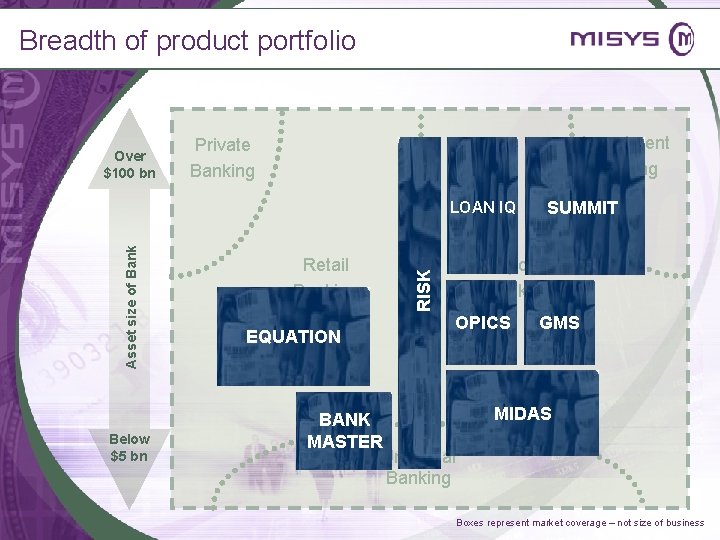
Breadth of product portfolio Over $100 bn Investment Banking Private Banking Below $5 bn Retail Banking EQUATION SUMMIT Corporate Banking RISK Asset size of Bank LOAN IQ OPICS BANK MASTER Universal Banking GMS MIDAS Boxes represent market coverage – not size of business
Depth of IPR Midas. Plus • Midas represents 14 million lines of code in total, with 168 functional modules • Midas. Plus release was 3 years in the making, delivering 3 million lines of new software • IAS Compliance was 50 man years of investment Summit. FT • Summit represents 6 million lines of code in total • Summit. FT release was 3 years in the making • Summit. FT and MUST alone represent an investment of over 75 man years
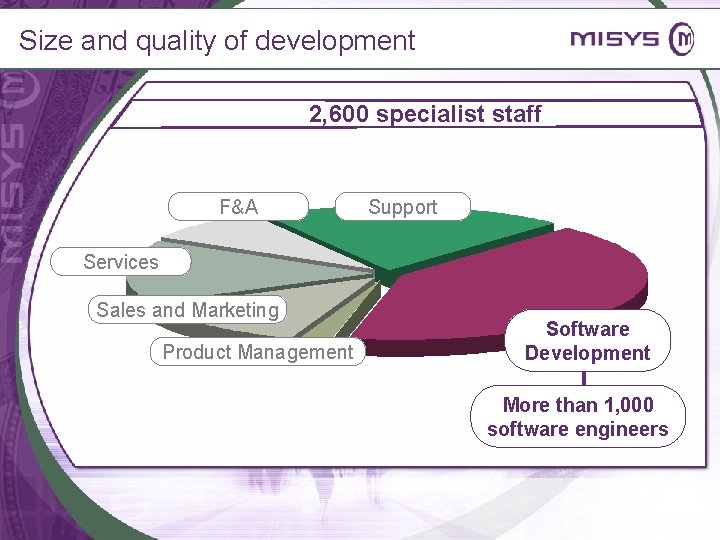
Size and quality of development 2, 600 specialist staff F&A Support Services Sales and Marketing Product Management Software Development More than 1, 000 software engineers
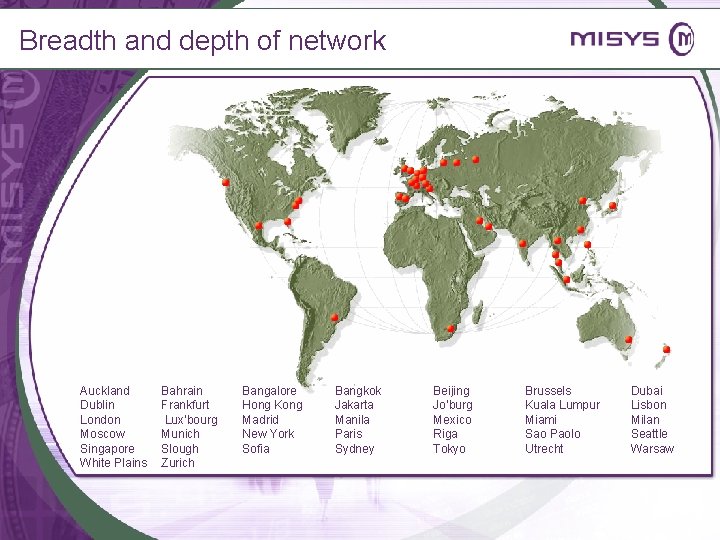
Breadth and depth of network Auckland Dublin London Moscow Singapore White Plains Bahrain Frankfurt Lux’bourg Munich Slough Zurich Bangalore Hong Kong Madrid New York Sofia Bangkok Jakarta Manila Paris Sydney Beijing Jo’burg Mexico Riga Tokyo Brussels Kuala Lumpur Miami Sao Paolo Utrecht Dubai Lisbon Milan Seattle Warsaw
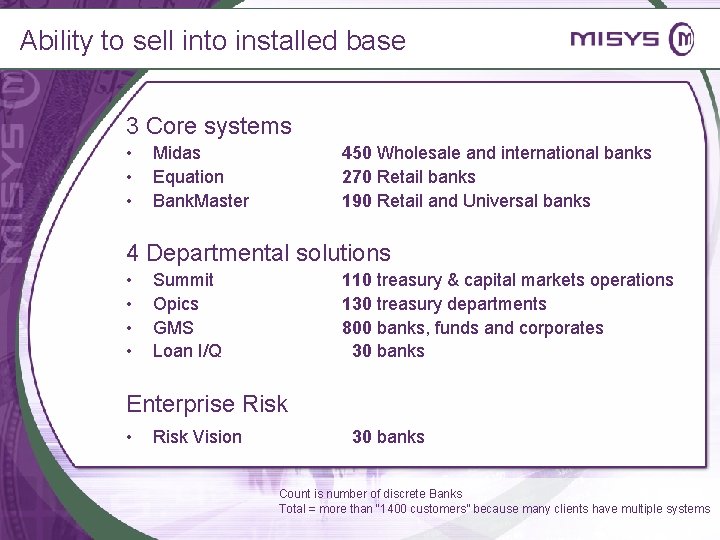
Ability to sell into installed base 3 Core systems • • • Midas Equation Bank. Master 450 Wholesale and international banks 270 Retail banks 190 Retail and Universal banks 4 Departmental solutions • • Summit Opics GMS Loan I/Q 110 treasury & capital markets operations 130 treasury departments 800 banks, funds and corporates 30 banks Enterprise Risk • Risk Vision 30 banks Count is number of discrete Banks Total = more than “ 1400 customers” because many clients have multiple systems
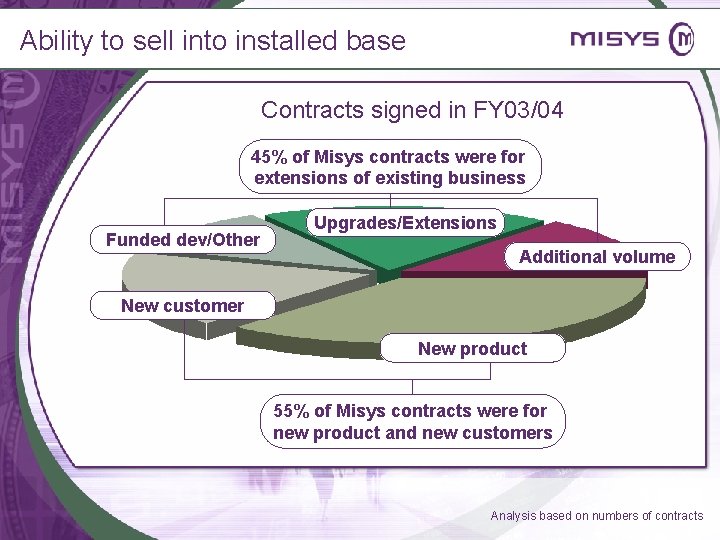
Ability to sell into installed base Contracts signed in FY 03/04 45% of Misys contracts were for extensions of existing business Funded dev/Other Upgrades/Extensions Additional volume New customer New product 55% of Misys contracts were for new product and new customers Analysis based on numbers of contracts
How do vendors compete in vertical markets? What drives growth in vertical markets?
Drivers of growth in vertical markets 1. New technology cycles 2. Growth in underlying business volumes 3. Increasing burden of regulation/reporting 4. A return to IT spending for competitive advantage 5. Trend to use of third-party vendors
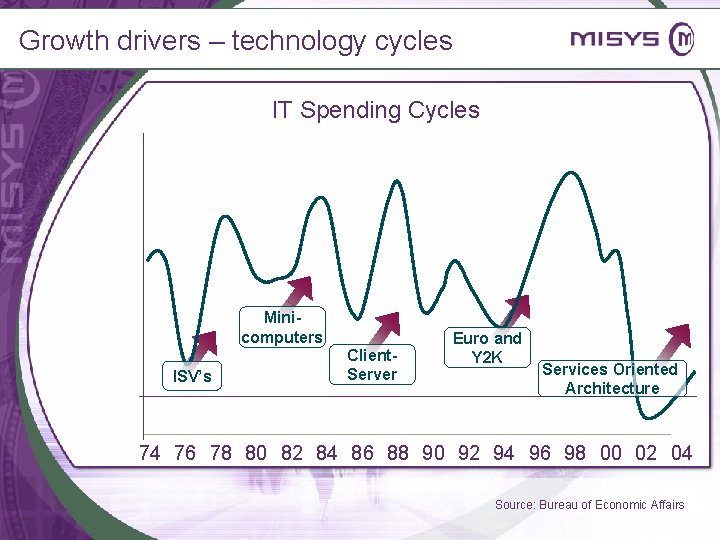
Growth drivers – technology cycles IT Spending Cycles Minicomputers ISV’s Client. Server Euro and Y 2 K Services Oriented Architecture 74 76 78 80 82 84 86 88 90 92 94 96 98 00 02 04 Source: Bureau of Economic Affairs
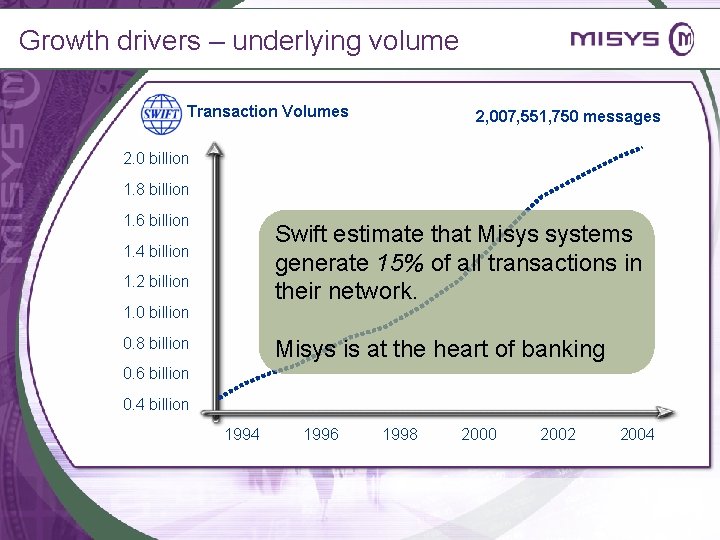
Growth drivers – underlying volume Transaction Volumes 2, 007, 551, 750 messages 2. 0 billion 1. 8 billion 1. 6 billion Swift estimate that Misys systems generate 15% of all transactions in their network. 1. 4 billion 1. 2 billion 1. 0 billion 0. 8 billion Misys is at the heart of banking 0. 6 billion 0. 4 billion 1994 1996 1998 2000 2002 2004
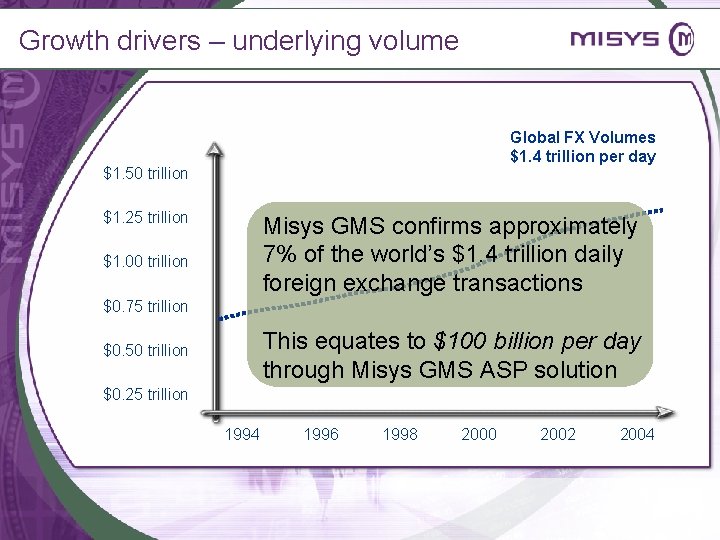
Growth drivers – underlying volume Global FX Volumes $1. 4 trillion per day $1. 50 trillion $1. 25 trillion Misys GMS confirms approximately 7% of the world’s $1. 4 trillion daily foreign exchange transactions $1. 00 trillion $0. 75 trillion This equates to $100 billion per day through Misys GMS ASP solution $0. 50 trillion $0. 25 trillion 1994 1996 1998 2000 2002 2004
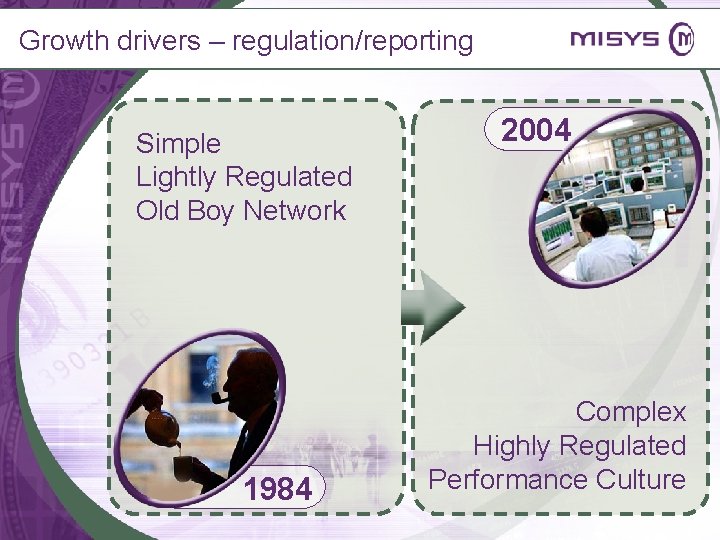
Growth drivers – regulation/reporting Simple Lightly Regulated Old Boy Network 1984 2004 Complex Highly Regulated Performance Culture
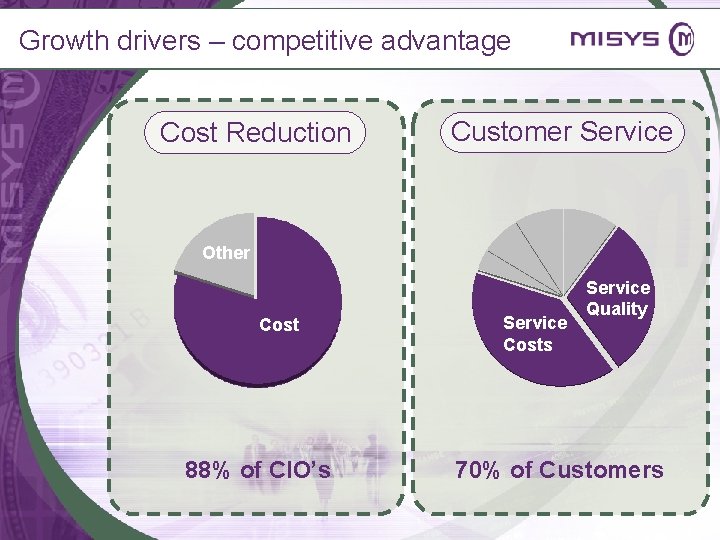
Growth drivers – competitive advantage Cost Reduction Customer Service Other Cost 88% of CIO’s Service Costs Service Quality 70% of Customers
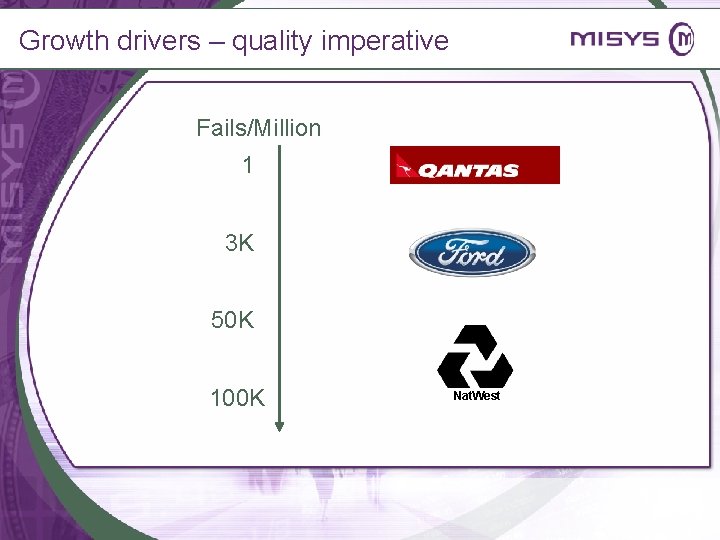
Growth drivers – quality imperative Fails/Million 1 3 K 50 K 100 K Nat. West
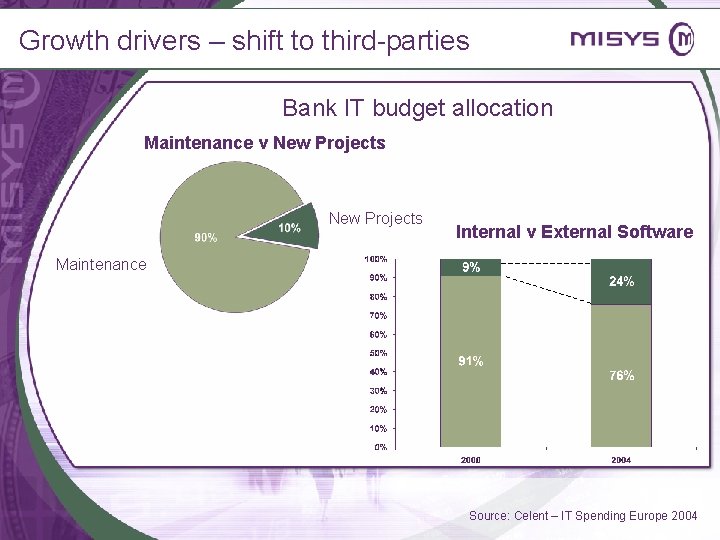
Growth drivers – shift to third-parties Fails/ Million Bank IT budget allocation Maintenance v New Projects Internal v External Software Maintenance Source: Celent – IT Spending Europe 2004
The new era and Misys Functionally rich Component based Engineered on Java &. NET With compliance built in ‘Delivering the solutions our customers want, when they want them’
Product Management and Development Process Jerry Luckett Product and Strategy Director Misys Wholesale Banking Systems
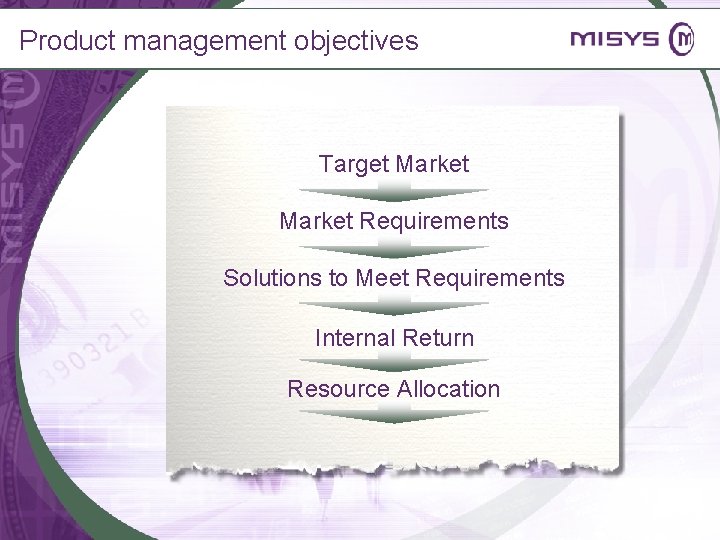
Product management objectives Target Market Requirements Solutions to Meet Requirements Internal Return Resource Allocation
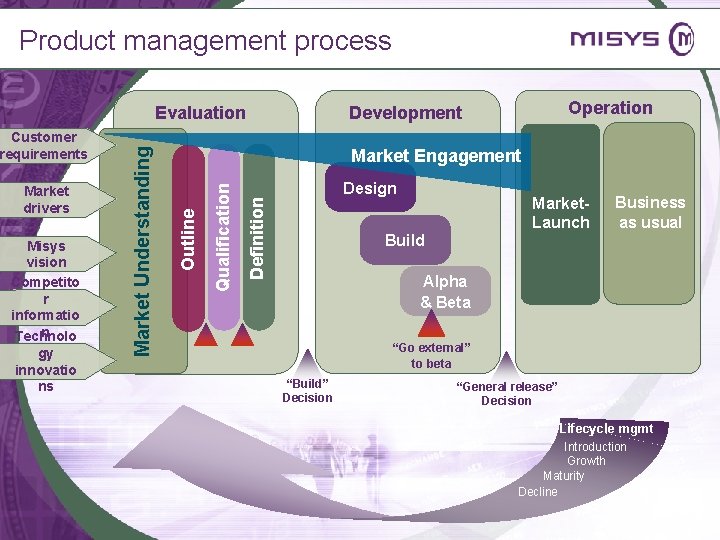
Product management process Design Definition Misys vision Competito r informatio n Technolo gy innovatio ns Qualification Market drivers Operation Development Market Engagement Outline Customer requirements Market Understanding Evaluation Market- Launch Business as usual Build Alpha & Beta “Go external” to beta “Build” Decision “General release” Decision Lifecycle mgmt Introduction Growth Maturity Decline
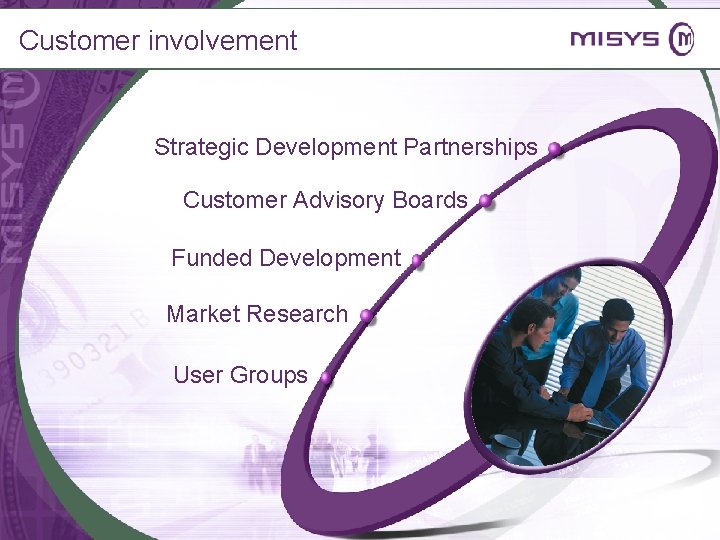
Customer involvement Strategic Development Partnerships Customer Advisory Boards Funded Development Market Research User Groups
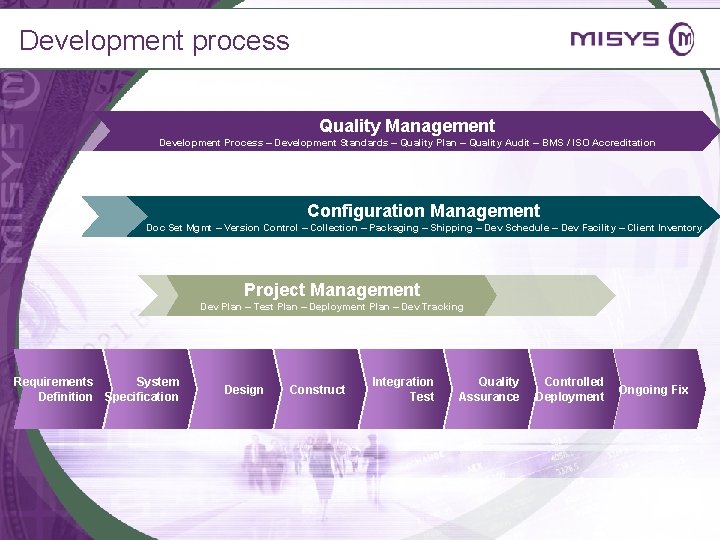
Development process Quality Management Development Process – Development Standards – Quality Plan – Quality Audit – BMS / ISO Accreditation Configuration Management Doc Set Mgmt – Version Control – Collection – Packaging – Shipping – Dev Schedule – Dev Facility – Client Inventory Project Management Dev Plan – Test Plan – Deployment Plan – Dev Tracking Requirements System Definition Specification Design Construct Integration Test Quality Assurance Controlled Deployment Ongoing Fix
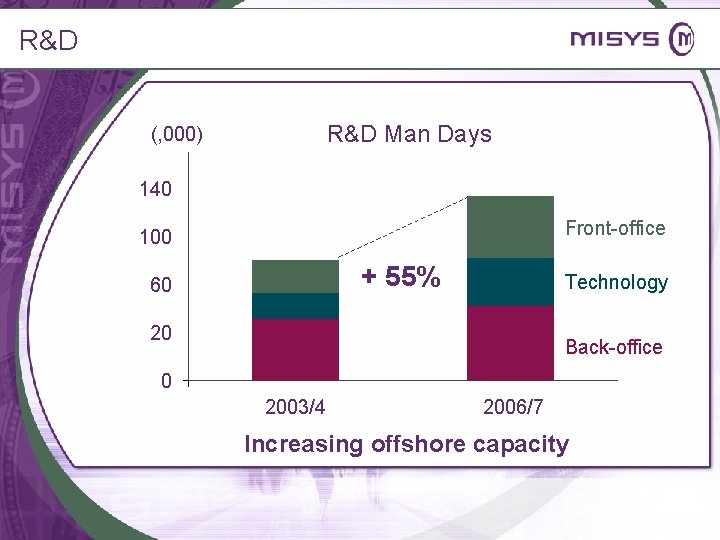
The move to offshore and outsourcing • Misys has been creating offshore capacity for more than a decade • What we gain from offshoring: – – – Lower unit costs Increased capacity 24 hour development capability Access to wider skill pool Significant local market presence • In addition outsourcing also provides a variable cost model
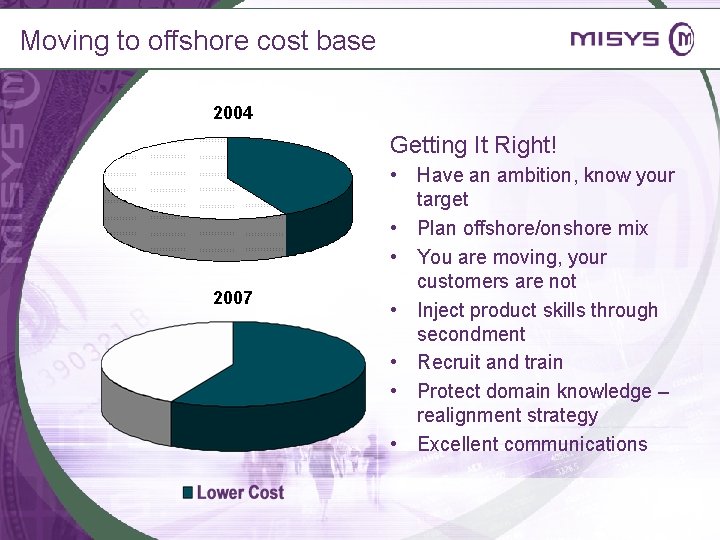
Moving to offshore cost base 2004 Getting It Right! 2007 • Have an ambition, know your target • Plan offshore/onshore mix • You are moving, your customers are not • Inject product skills through secondment • Recruit and train • Protect domain knowledge – realignment strategy • Excellent communications
Summary • Know what you want to build • Get the software factory working effectively and efficiently • Result – Focus on growth products and new markets – Output that meets and exceeds industry quality standards • Increase development capacity without increasing the R&D to revenue ratio
Summit. FT Georges Bory Managing Director Summit Systems
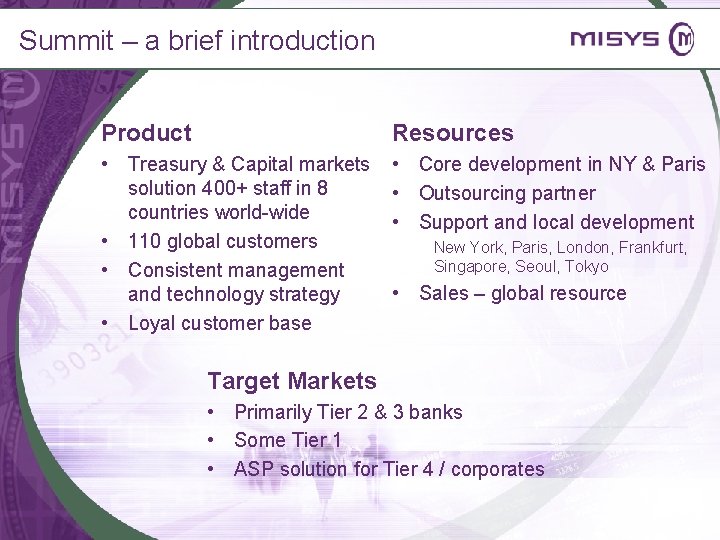
Summit – a brief introduction Product Resources • Treasury & Capital markets solution 400+ staff in 8 countries world-wide • 110 global customers • Consistent management and technology strategy • Loyal customer base • Core development in NY & Paris • Outsourcing partner • Support and local development New York, Paris, London, Frankfurt, Singapore, Seoul, Tokyo • Sales – global resource Target Markets • Primarily Tier 2 & 3 banks • Some Tier 1 • ASP solution for Tier 4 / corporates
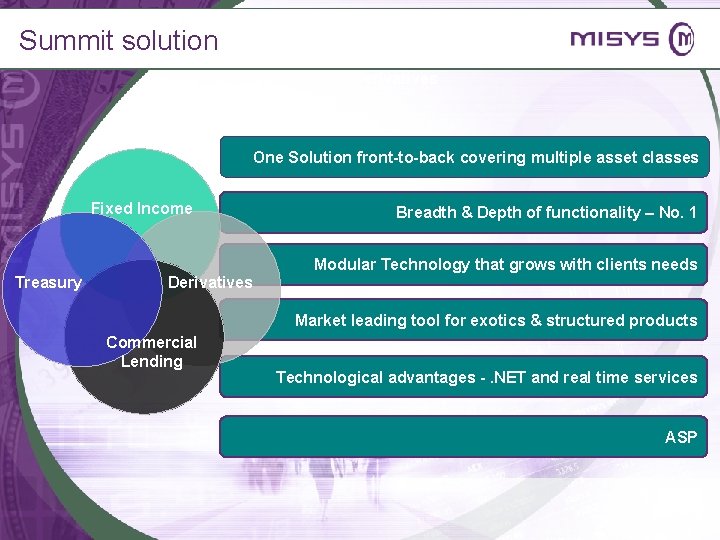
Summit solution Derivatives One Solution front-to-back covering multiple asset classes Fixed Income Treasury Derivatives Breadth & Depth of functionality – No. 1 Modular Technology that grows with clients needs Market leading tool for exotics & structured products Commercial Lending Technological advantages -. NET and real time services ASP
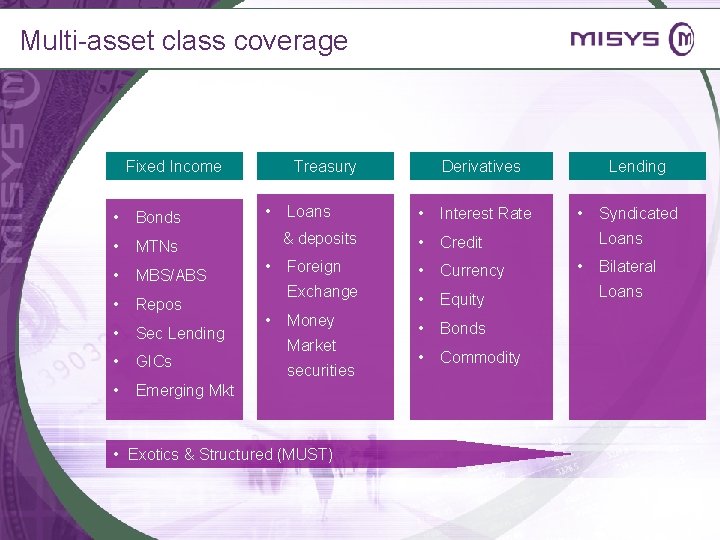
Multi-asset class coverage Fixed Income • Bonds • MTNs • MBS/ABS • Repos • Sec Lending • GICs • Emerging Mkt Treasury • • • Derivatives Loans • Interest Rate & deposits • Credit Foreign • Currency Exchange • Equity Money • Bonds • Commodity Market securities • Exotics & Structured (MUST) Lending • Syndicated Loans • Bilateral Loans
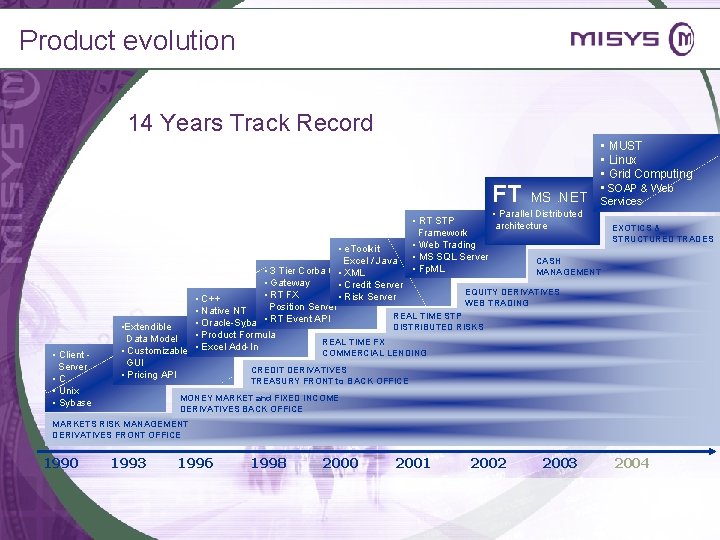
Product evolution 14 Years Track Record FT MS. NET • MUST • Linux • Grid Computing • SOAP & Web Services • Parallel Distributed • RT STP architecture Framework • Web Trading • MS SQL Server CASH • Fp. ML MANAGEMENT • e. Toolkit Excel / Java • 3 Tier Corba Orbix • XML • Gateway • Credit Server EQUITY DERIVATIVES • RT FX • Risk Server • C++ WEB TRADING Position Server • Native NT REAL TIME STP • Oracle-Sybase • RT Event API • Client Server • C • Unix • Sybase EXOTICS & STRUCTURED TRADES • Extendible DISTRIBUTED RISKS • Product Formula Data Model REAL TIME FX • Customizable • Excel Add-In COMMERCIAL LENDING GUI CREDIT DERIVATIVES • Pricing API TREASURY FRONT to BACK OFFICE MONEY MARKET and FIXED INCOME DERIVATIVES BACK OFFICE MARKETS RISK MANAGEMENT DERIVATIVES FRONT OFFICE 1990 1993 1996 1998 2000 2001 2002 2003 2004
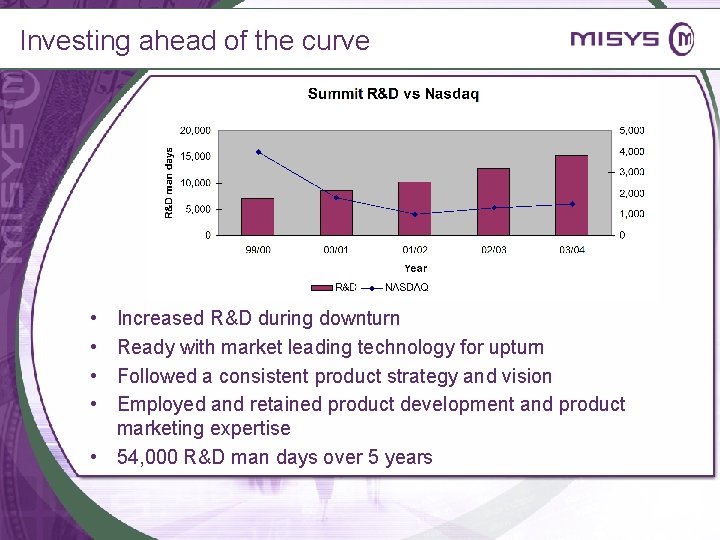
Investing ahead of the curve • • Increased R&D during downturn Ready with market leading technology for upturn Followed a consistent product strategy and vision Employed and retained product development and product marketing expertise • 54, 000 R&D man days over 5 years
Client examples Global Investment Banks International Wholesale Banks Regional & Large Local Banks Hedge Funds/Corporates
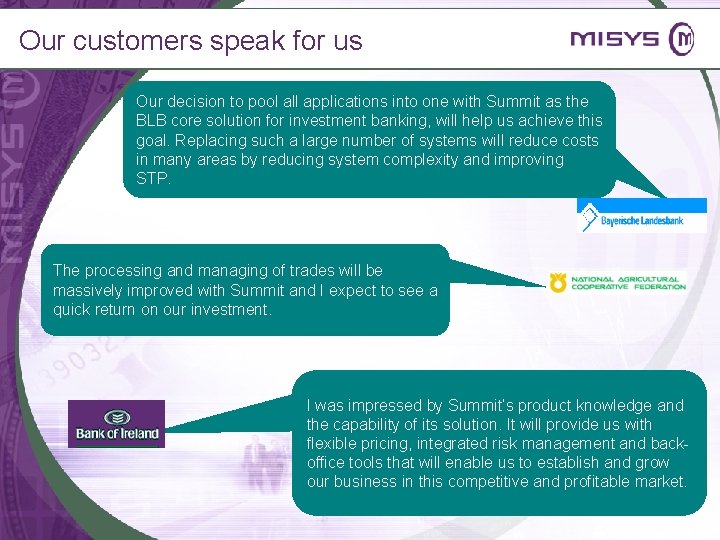
Our customers speak for us Our decision to pool all applications into one with Summit as the BLB core solution for investment banking, will help us achieve this goal. Replacing such a large number of systems will reduce costs in many areas by reducing system complexity and improving STP. The processing and managing of trades will be massively improved with Summit and I expect to see a quick return on our investment. I was impressed by Summit’s product knowledge and the capability of its solution. It will provide us with flexible pricing, integrated risk management and backoffice tools that will enable us to establish and grow our business in this competitive and profitable market.
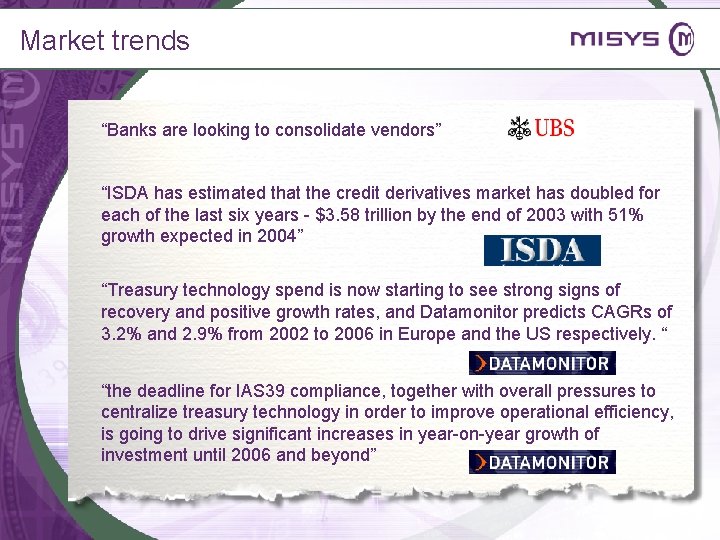
Market trends “Banks are looking to consolidate vendors” “ISDA has estimated that the credit derivatives market has doubled for each of the last six years - $3. 58 trillion by the end of 2003 with 51% growth expected in 2004” “Treasury technology spend is now starting to see strong signs of recovery and positive growth rates, and Datamonitor predicts CAGRs of 3. 2% and 2. 9% from 2002 to 2006 in Europe and the US respectively. “ “the deadline for IAS 39 compliance, together with overall pressures to centralize treasury technology in order to improve operational efficiency, is going to drive significant increases in year-on-year growth of investment until 2006 and beyond”
The Summit advantage Breadth and depth Technological advantage Summit MUST Regulatory compliance Corporate strength Business specialists Worldwide customer base 14 years experience 33 banks of the top 100 Banks use Summit
Midas. Plus Andrew White CEO Misys Wholesale Banking Systems
This is Midas! Most successful banking software package ever International branches and regional banks Unmatched corporate banking capabilities Global product, local features, local support Loyal customer base – TRUST
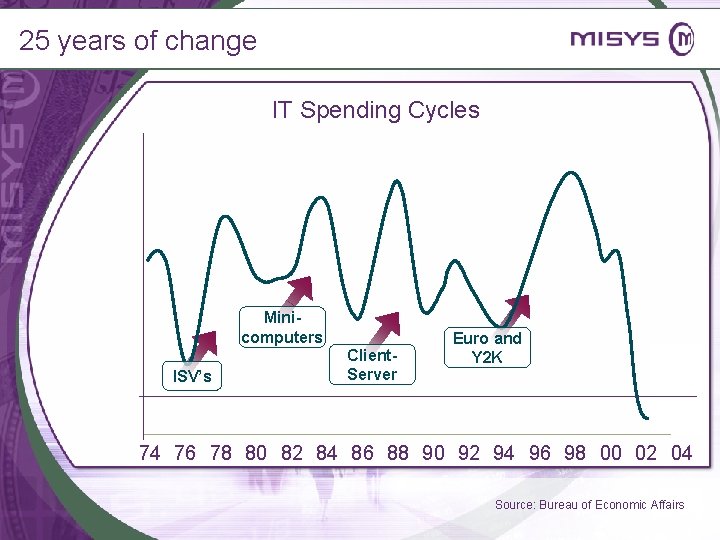
25 years of change IT Spending Cycles Minicomputers ISV’s Client. Server Euro and Y 2 K 74 76 78 80 82 84 86 88 90 92 94 96 98 00 02 04 Source: Bureau of Economic Affairs
Change again. Banks are under pressure. Competition: markets, products, price Risk Regulation Manual operations Rocketing customer expectations
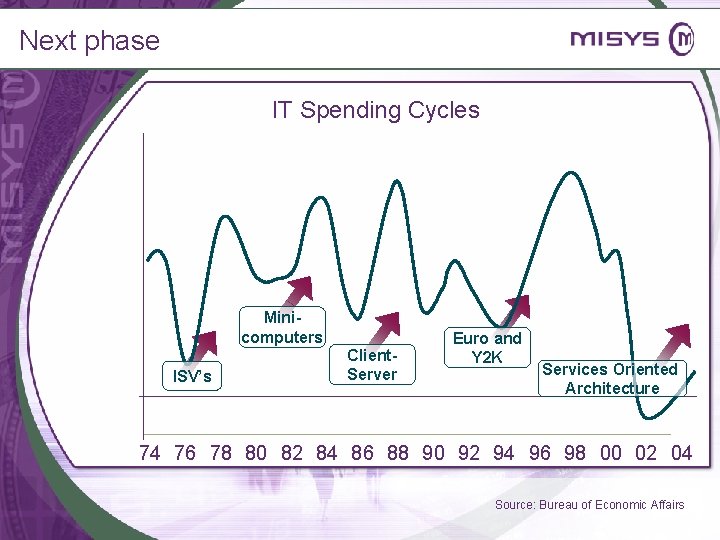
Next phase IT Spending Cycles Minicomputers ISV’s Client. Server Euro and Y 2 K Services Oriented Architecture 74 76 78 80 82 84 86 88 90 92 94 96 98 00 02 04 Source: Bureau of Economic Affairs
This is Midas. Plus! Open architecture Global processing Straight Through Processing (STP) Head office solution Multi-channel e. Services platform
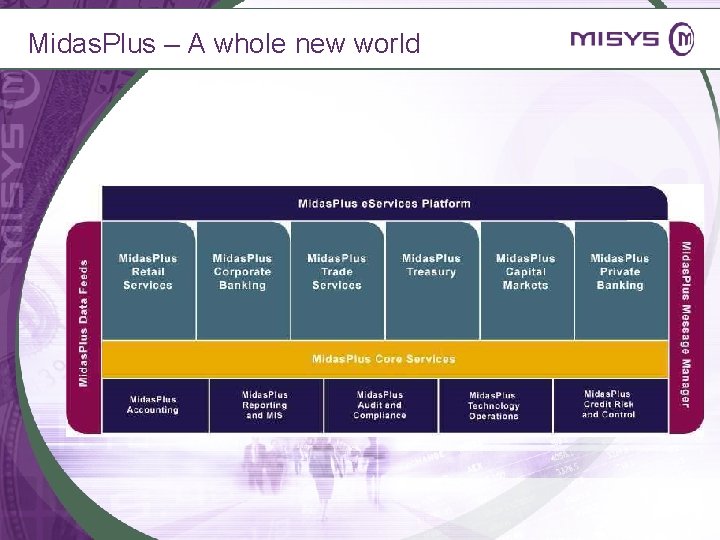
Midas. Plus – A whole new world
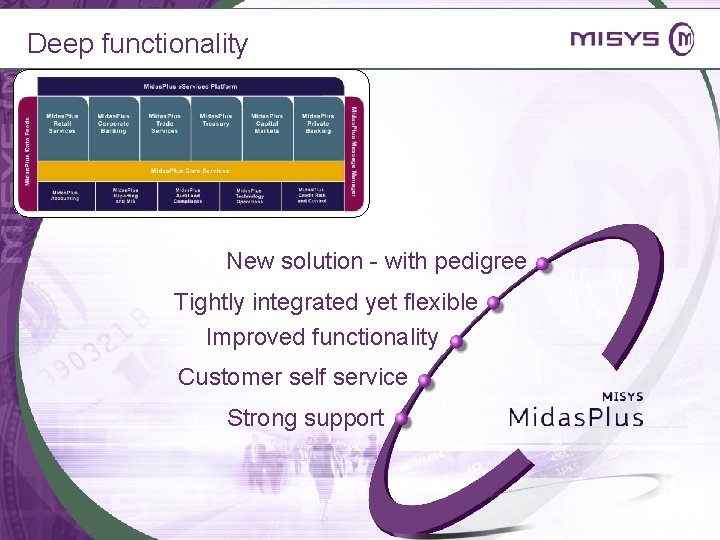
Deep functionality New solution - with pedigree Tightly integrated yet flexible Improved functionality Customer self service Strong support
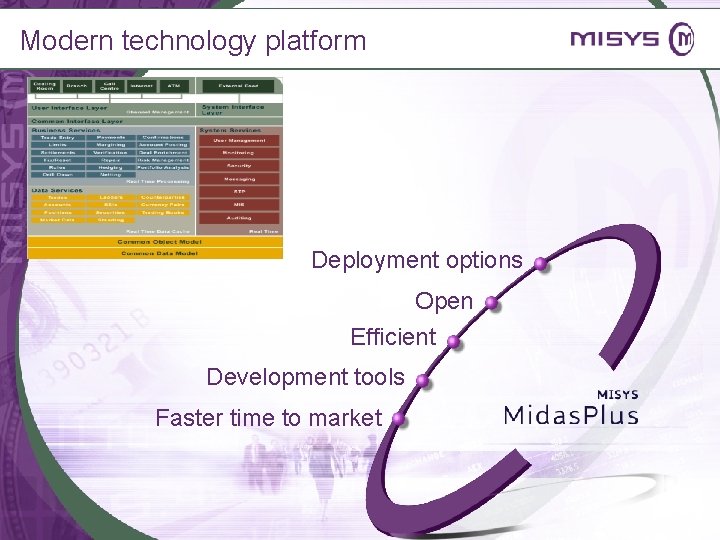
Modern technology platform Deployment options Open Efficient Development tools Faster time to market
Delivering global processing solutions The Power of One Improved customer service Cost and credit control Reduced risk Agility Cross-selling opportunities
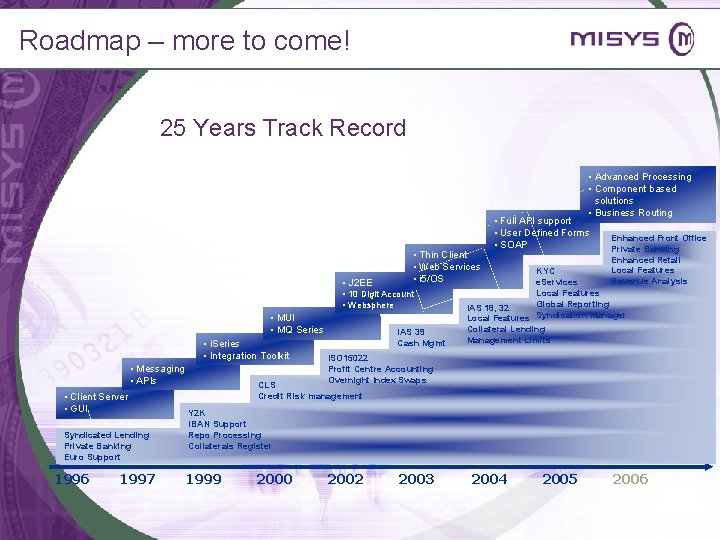
Roadmap – more to come! 25 Years Track Record • Advanced Processing • Component based solutions • Business Routing • J 2 EE • Thin Client • Web Services • i 5/OS • 10 Digit Account • Websphere • MUI • MQ Series • i. Series • Integration Toolkit • Messaging • APIs • Client Server • GUI Syndicated Lending Private Banking Euro Support 1996 1997 IAS 39 Cash Mgmt • Full API support • User Defined Forms • SOAP Enhanced Front Office Private Banking Enhanced Retail Local Features Revenue Analysis KYC e. Services Local Features Global Reporting IAS 18, 32 Local Features Syndication Manager Collateral Lending Management Limits ISO 15022 Profit Centre Accounting Overnight Index Swaps CLS Credit Risk management Y 2 K IBAN Support Repo Processing Collaterals Register 1999 2000 2002 2003 2004 2005 2006
The Midas. Plus effect Single biggest investment in Midas, ever Three years in the making Delivered on schedule 15 deliveries the day Midas. Plus was launched First two customers in production before Dec
The global processing effect Banks will each select a single vendor solution All back offices in a bank will converge All Midas customers will upgrade over time Local features and local reporting are musts Misys is market leader and has first mover advantage
Why Misys and Why Midas. Plus? Trust and expertise Integrated Global processing Best functionality Corporate strength Best local support Best technology 25 years experience
Equation. Plus Andrew Derrer CEO Misys Retail Banking
Brand new technology Market leading foundation More than just a product Elevates the entire market Wider opportunity Equation Plus
Market dynamics • The largest market with the largest growth: – Retail Banking to Bank Retailing – Packages will be the norm – Compliance deadlines – Islamic Banking
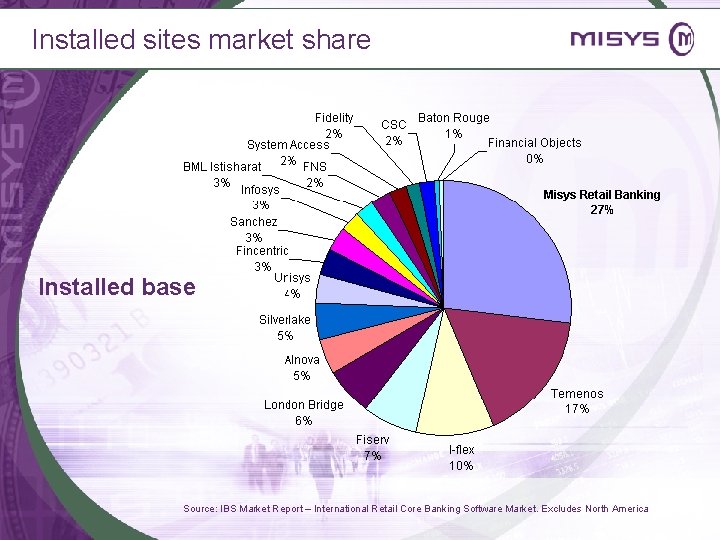
Installed sites market share Installed base Source: IBS Market Report – International Retail Core Banking Software Market. Excludes North America
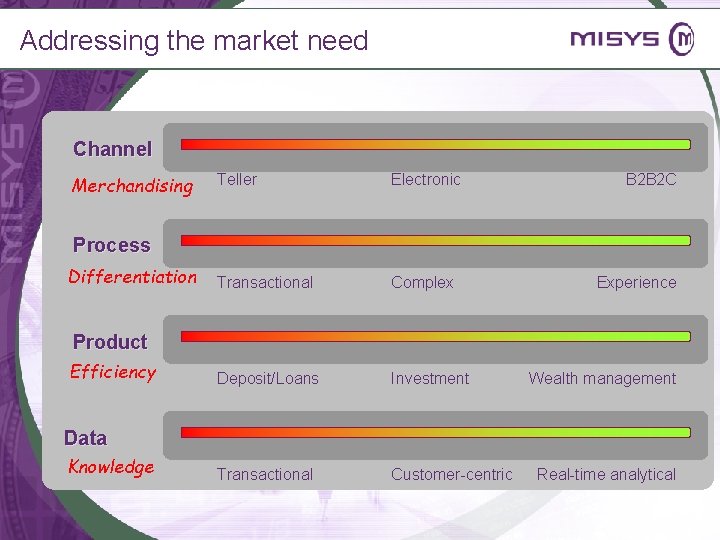
Addressing the market need Channel Merchandising Teller Electronic Transactional Complex Deposit/Loans Investment Transactional Customer-centric B 2 B 2 C Process Differentiation Experience Product Efficiency Wealth management Data Knowledge Real-time analytical
The challenge • Delivering packaged software and related services to help financial institutions: – Improve customer service – Comply with regulatory requirements – Reduce IT costs
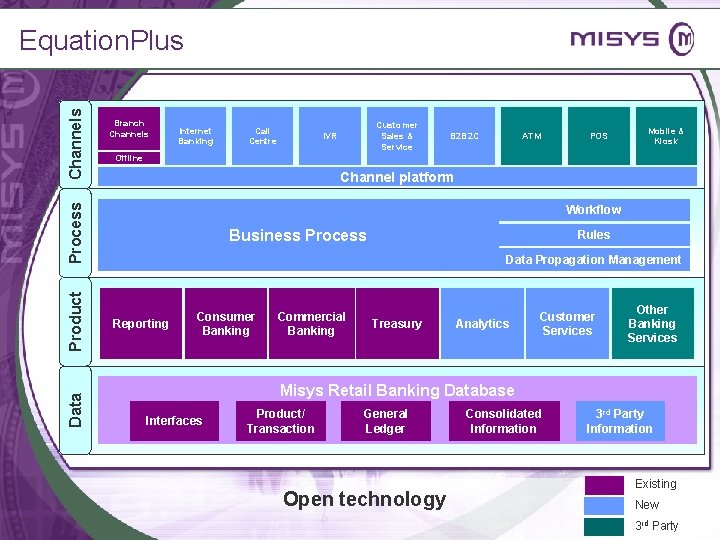
Branch Channels Internet Banking Product Data Call Centre Customer Sales & Service IVR B 2 B 2 C ATM POS Mobile & Kiosk Offline Channel platform Process Channels Equation. Plus Workflow Business Process Rules Data Propagation Management Reporting Consumer Banking Commercial Banking Treasury Analytics Customer Services Other Banking Services Misys Retail Banking Database Interfaces Product/ Transaction General Ledger Open technology Consolidated Information 3 rd Party Information Existing New 3 rd Party
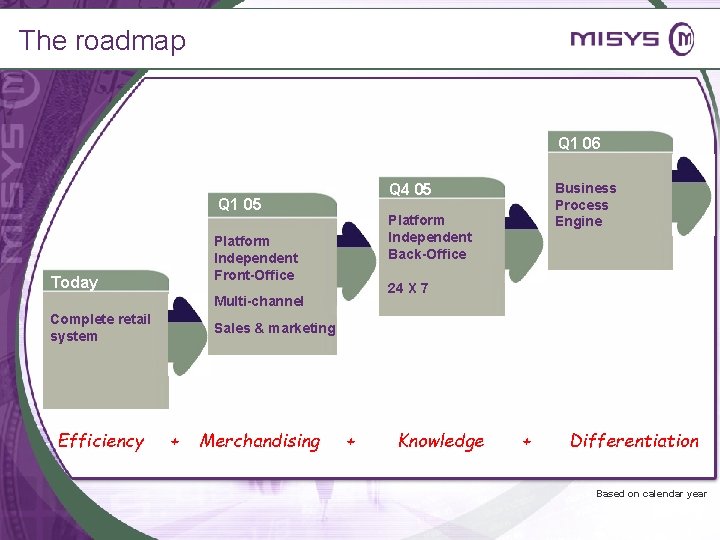
The roadmap Q 1 06 Q 1 05 Platform Independent Back-Office Platform Independent Front-Office Today 24 X 7 Multi-channel Complete retail system Efficiency Business Process Engine Q 4 05 Sales & marketing + Merchandising + Knowledge + Differentiation Based on calendar year
The execution • What convinces us that we can execute on the milestones? – Experience - Midas. Plus – Partnerships – Unique tools and utilities – Talent
Founding principles for customers • Bring every customer with us – An attractive future for every Misys Retail Banking customer – Easy, worthwhile upgrades – Support commitment • Technologies that meet the aspiration of banks, both large and small • The right architecture – Inclusive, not silo-based – Right platforms
What the market thinks In migrating to Equation Plus, Misys has unveiled an expansive vision to combine the best elements of proven retail banking functionality, with the capabilities of leading edge architectures. Equation Plus, a complete new-generation, richly functional, highly-advanced retail banking system, will in our assessment, transform the fragmented retail banking market and competitive landscape. If Misys can deliver on this plan, it will mark a real renaissance for the Equation brand
Why we will be best in the market? Single customer view First truly open system Process automation leader CRM leader Functional leader Single point of accountability Company strength 20 years of experience
Summary Ivan Martin CEO Misys Banking Division
Growth opportunities 1. Summit. FT • • • Market leading Treasury & Capital Markets solution World class functionality and technology Consistent growth up to and including last 3 years 2. Midas. Plus • • • Most successful banking application ever Unmatched depth of corporate banking functionality Significant 3 year investment in new technology platform 3. Equation. Plus • • • World class Retail functionality Clear leader in international markets First truly open front-to-back Retail solution
Customer satisfaction … today our customers tell us … “Very impressed by the improvement in Equation Support over the last six months. ” “If the Customer Satisfaction Survey were to be repeated now, Misys would see a dramatic improvement in feedback from its customers. ” “A most impressive display of solid technical expertise and great support. Best wishes from a satisfied customer. “
Market feedback “Our survey indicates that Misys’ customers are planning fewer system replacements than users of other systems Morgan Stanley/IBS Survey on behalf of Association of Foreign Banks April 2004 The solutions rated more favourably than other vendors on flexibility and instrument coverage Misys’ product position versus the market remains strong. . . with products perceived as offering above-average support for banks’ future needs”
Key messages 1. Banking is a large and growing software market 2. Misys is well positioned to benefit from this growth 3. Misys leads in functionality and technology 4. Misys is growing its market share in key markets 5. Retail is key growth sector going forward
Making things that really matter, work better
- Slides: 98