
IPO trends worldwide and experiences from the Warsaw
- Slides: 21
IPO trends worldwide and experiences from the Warsaw Stock Exchange Tomasz Konieczny 2 July 2010 Pw. C
Agenda Recent IPO trends Experiences from Warsaw Privatisation through the WSE Pricewaterhouse. Coopers Pw. C Page 2
Agenda Recent IPO trends Experiences from Warsaw Privatisation through the WSE Pricewaterhouse. Coopers Pw. C Page 3
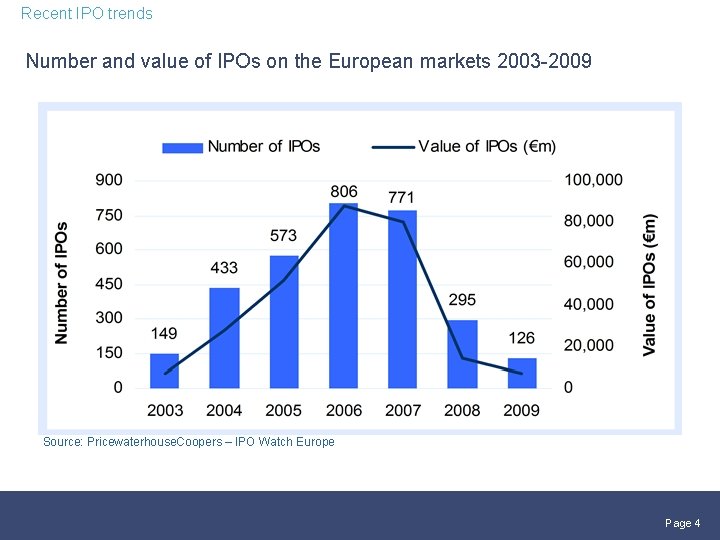
Recent IPO trends Number and value of IPOs on the European markets 2003 -2009 Source: Pricewaterhouse. Coopers – IPO Watch Europe Pricewaterhouse. Coopers Page 4
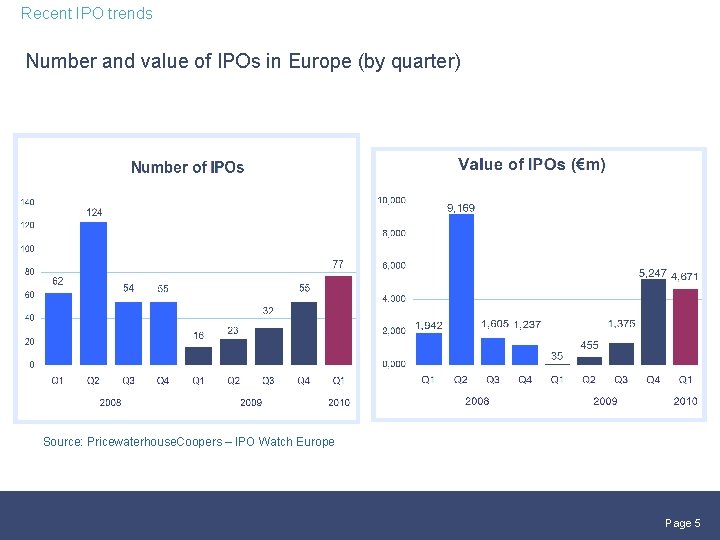
Recent IPO trends Number and value of IPOs in Europe (by quarter) Source: Pricewaterhouse. Coopers – IPO Watch Europe Pricewaterhouse. Coopers Page 5
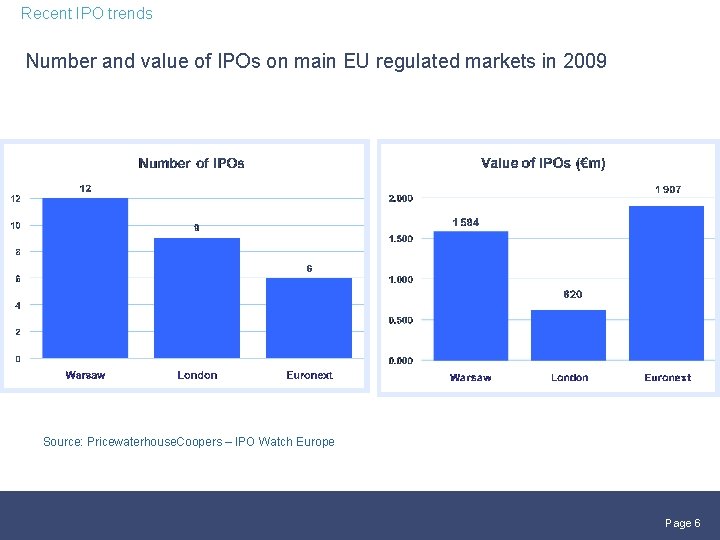
Recent IPO trends Number and value of IPOs on main EU regulated markets in 2009 Source: Pricewaterhouse. Coopers – IPO Watch Europe Pricewaterhouse. Coopers Page 6
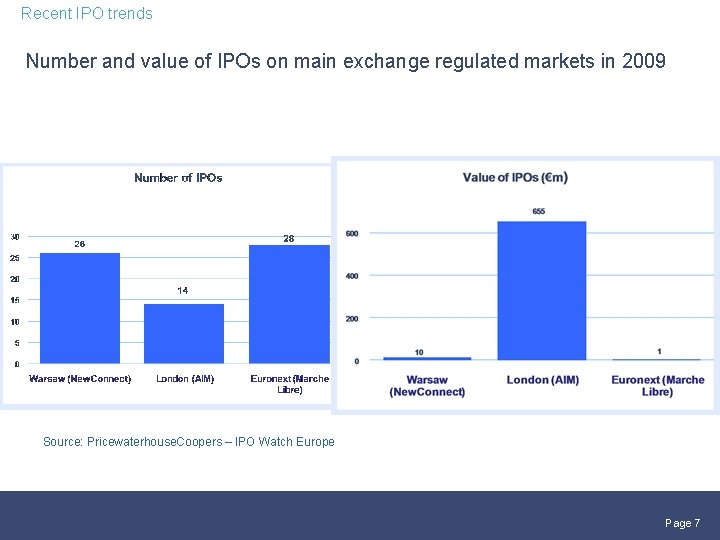
Recent IPO trends Number and value of IPOs on main exchange regulated markets in 2009 Source: Pricewaterhouse. Coopers – IPO Watch Europe Pricewaterhouse. Coopers Page 7
Agenda Recent IPO trends Experiences from Warsaw Privatisation through the WSE Pricewaterhouse. Coopers Pw. C Page 8
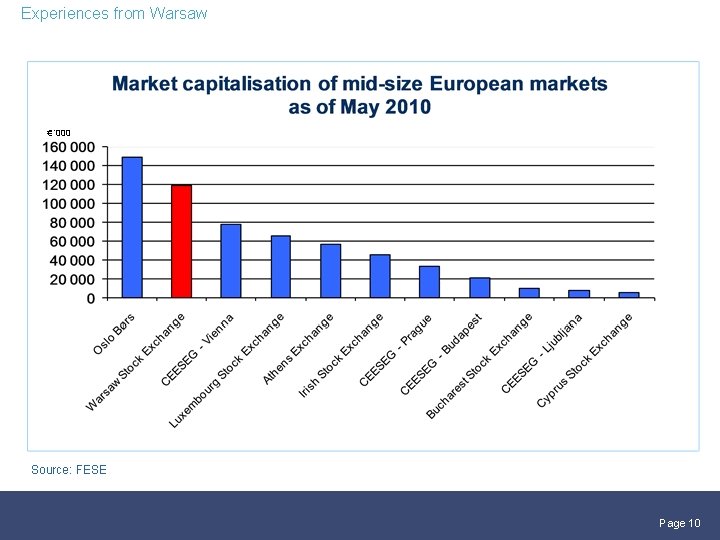
Experiences from Warsaw Stock Exchange (WSE) • WSE runs several markets: - Main Market – EU regulated - alternative markets (New Connect for equities, Catalyst for debt) – exchange regulated • According to FESE data, WSE market capitalisation at the end of May 2010 was EUR 118, 224 million • As of 18 June 2010 there were: - 381 companies listed on the WSE Main Market, 23 of which were non-domestic (including two Estonian entities) - 135 companies listed on the New. Connect market, 2 of which were non-domestic Pricewaterhouse. Coopers Page 9
Experiences from Warsaw € ‘ 000 Source: FESE Pricewaterhouse. Coopers Page 10
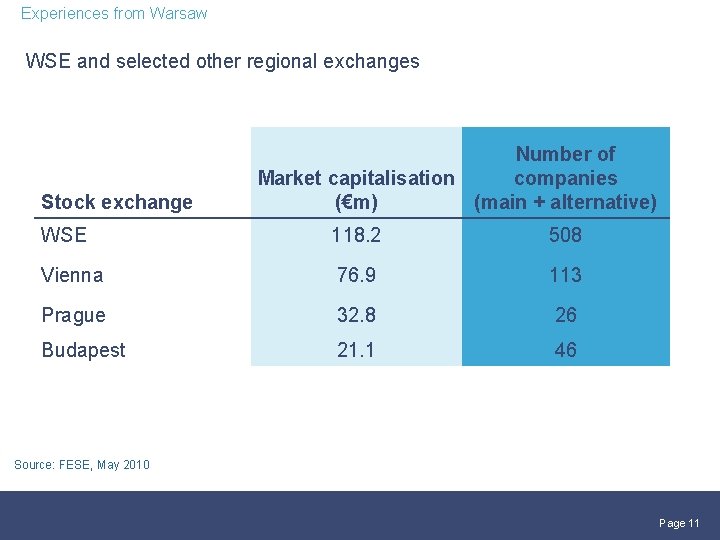
Experiences from Warsaw WSE and selected other regional exchanges Stock exchange Number of Market capitalisation companies (€m) (main + alternative) WSE 118. 2 508 Vienna 76. 9 113 Prague 32. 8 26 Budapest 21. 1 46 Source: FESE, May 2010 Pricewaterhouse. Coopers Page 11
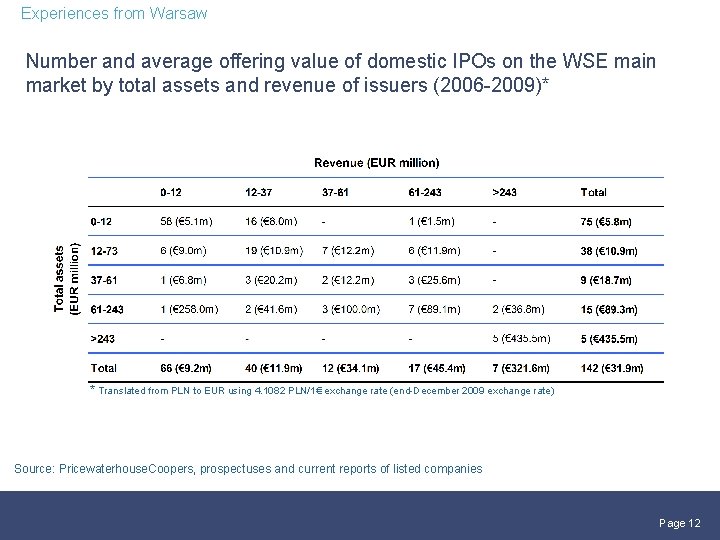
Experiences from Warsaw Number and average offering value of domestic IPOs on the WSE main market by total assets and revenue of issuers (2006 -2009)* * Translated from PLN to EUR using 4. 1082 PLN/1€ exchange rate (end-December 2009 exchange rate) Source: Pricewaterhouse. Coopers, prospectuses and current reports of listed companies Pricewaterhouse. Coopers Page 12
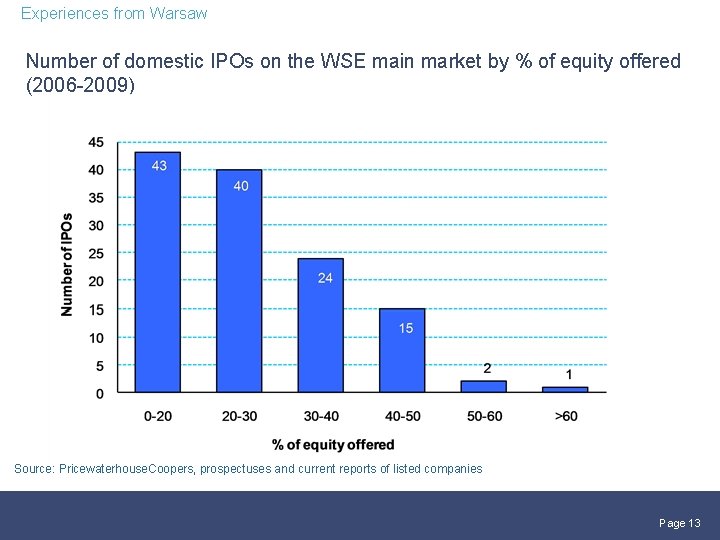
Experiences from Warsaw Number of domestic IPOs on the WSE main market by % of equity offered (2006 -2009) Source: Pricewaterhouse. Coopers, prospectuses and current reports of listed companies Pricewaterhouse. Coopers Page 13
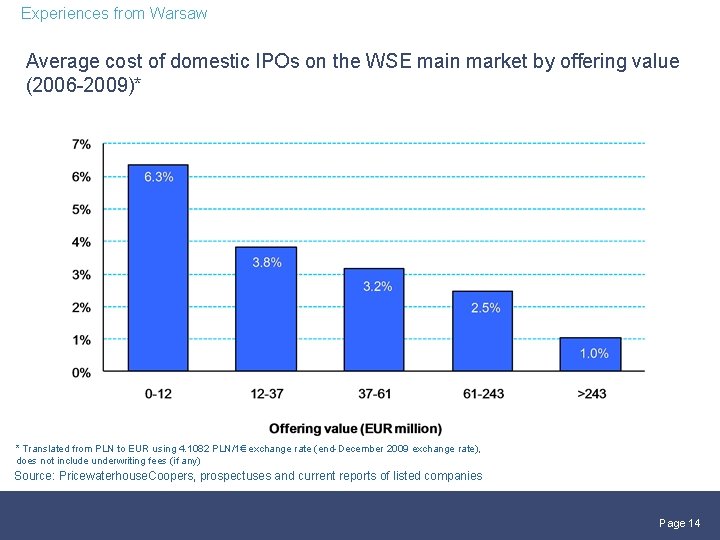
Experiences from Warsaw Average cost of domestic IPOs on the WSE main market by offering value (2006 -2009)* * Translated from PLN to EUR using 4. 1082 PLN/1€ exchange rate (end-December 2009 exchange rate), does not include underwriting fees (if any) Source: Pricewaterhouse. Coopers, prospectuses and current reports of listed companies Pricewaterhouse. Coopers Page 14
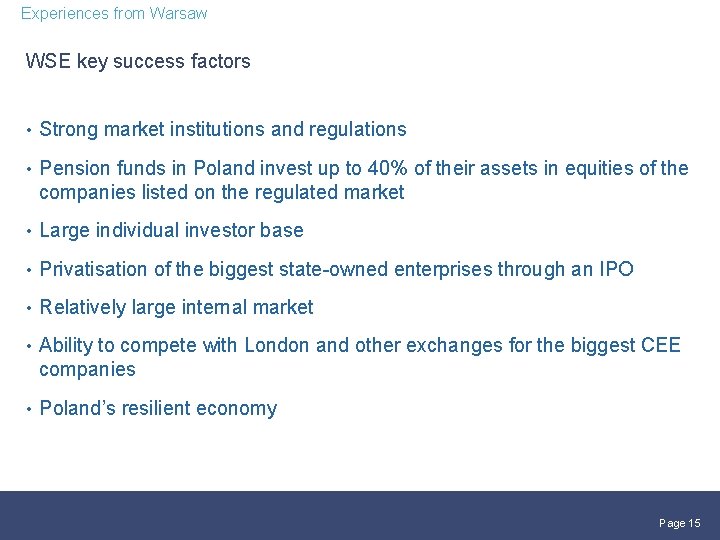
Experiences from Warsaw WSE key success factors • Strong market institutions and regulations • Pension funds in Poland invest up to 40% of their assets in equities of the companies listed on the regulated market • Large individual investor base • Privatisation of the biggest state-owned enterprises through an IPO • Relatively large internal market • Ability to compete with London and other exchanges for the biggest CEE companies • Poland’s resilient economy Pricewaterhouse. Coopers Page 15
Agenda Recent IPO trends Experiences from Warsaw Privatisation through the WSE Pricewaterhouse. Coopers Pw. C Page 16
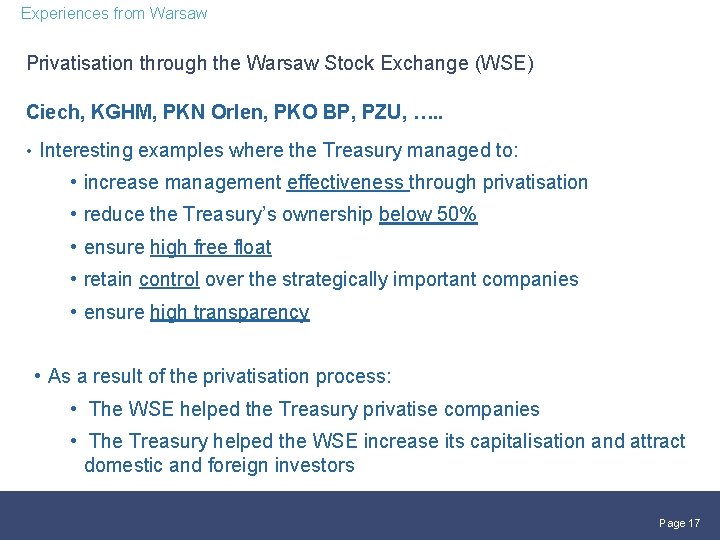
Experiences from Warsaw Privatisation through the Warsaw Stock Exchange (WSE) Ciech, KGHM, PKN Orlen, PKO BP, PZU, …. . • Interesting examples where the Treasury managed to: • increase management effectiveness through privatisation • reduce the Treasury’s ownership below 50% • ensure high free float • retain control over the strategically important companies • ensure high transparency • As a result of the privatisation process: • The WSE helped the Treasury privatise companies • The Treasury helped the WSE increase its capitalisation and attract domestic and foreign investors Pricewaterhouse. Coopers Page 17
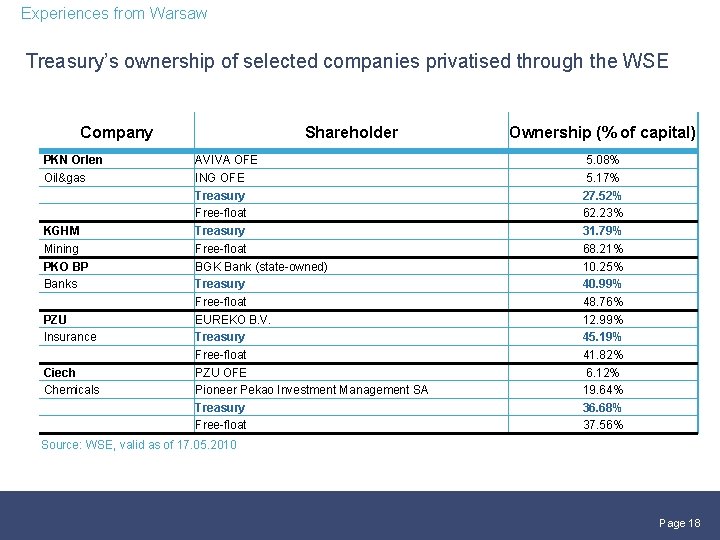
Experiences from Warsaw Treasury’s ownership of selected companies privatised through the WSE Company PKN Orlen Oil&gas KGHM Mining PKO BP Banks PZU Insurance Ciech Chemicals Shareholder AVIVA OFE ING OFE Treasury Free-float BGK Bank (state-owned) Treasury Free-float EUREKO B. V. Treasury Free-float PZU OFE Pioneer Pekao Investment Management SA Treasury Free-float Ownership (% of capital) 5. 08% 5. 17% 27. 52% 62. 23% 31. 79% 68. 21% 10. 25% 40. 99% 48. 76% 12. 99% 45. 19% 41. 82% 6. 12% 19. 64% 36. 68% 37. 56% Source: WSE, valid as of 17. 05. 2010 Pricewaterhouse. Coopers Page 18
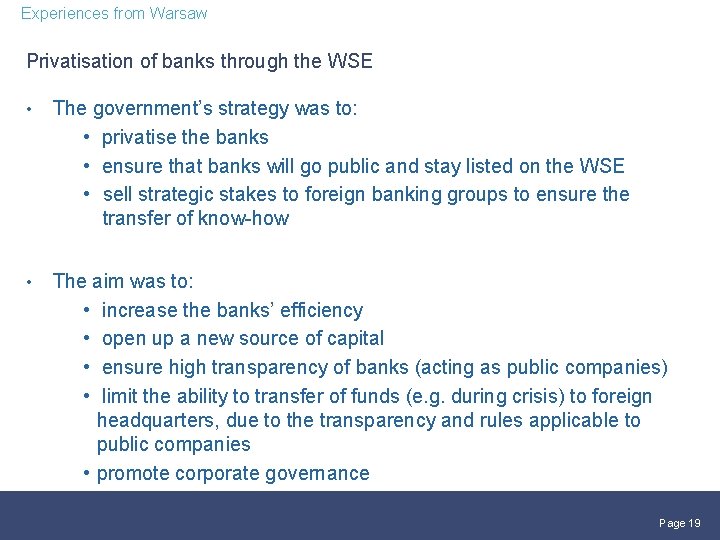
Experiences from Warsaw Privatisation of banks through the WSE • The government’s strategy was to: • privatise the banks • ensure that banks will go public and stay listed on the WSE • sell strategic stakes to foreign banking groups to ensure the transfer of know-how • The aim was to: • increase the banks’ efficiency • open up a new source of capital • ensure high transparency of banks (acting as public companies) • limit the ability to transfer of funds (e. g. during crisis) to foreign headquarters, due to the transparency and rules applicable to public companies • promote corporate governance Pricewaterhouse. Coopers Page 19
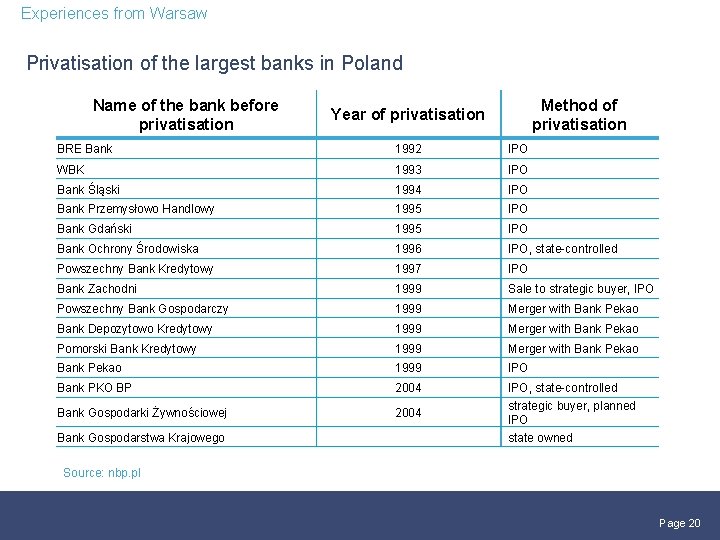
Experiences from Warsaw Privatisation of the largest banks in Poland Name of the bank before privatisation Method of privatisation Year of privatisation BRE Bank 1992 IPO WBK 1993 IPO Bank Śląski 1994 IPO Bank Przemysłowo Handlowy 1995 IPO Bank Gdański 1995 IPO Bank Ochrony Środowiska 1996 IPO, state-controlled Powszechny Bank Kredytowy 1997 IPO Bank Zachodni 1999 Sale to strategic buyer, IPO Powszechny Bank Gospodarczy 1999 Merger with Bank Pekao Bank Depozytowo Kredytowy 1999 Merger with Bank Pekao Pomorski Bank Kredytowy 1999 Merger with Bank Pekao 1999 IPO Bank PKO BP 2004 Bank Gospodarki Żywnościowej 2004 IPO, state-controlled strategic buyer, planned IPO state owned Bank Gospodarstwa Krajowego Source: nbp. pl Pricewaterhouse. Coopers Page 20
Thank you! Tomasz Konieczny Partner tomasz. konieczny@pl. pwc. com +48 502 18 42 85 +48 22 523 42 85 © 2010 Pricewaterhouse. Coopers. All rights reserved. “Pricewaterhouse. Coopers” refers to the network of member firms of Pricewaterhouse. Coopers International Limited, each of which is a separate and independent legal entity. *connectedthinking is a trademark of Pricewaterhouse. Coopers LLP (US). Pw. C