
International Aspects Of Tax Cuts and Jobs Act
International Aspects Of Tax Cuts and Jobs Act (2017) -- Working With The GILTI Maria Soledad Otero, Esq. Karlin & Peebles, LLP Tel: 323 -648 -4648 Email: motero@karlinpeebles. com Date: August 19, 2019 19 cWorking with the GILTI. pptx Thomas M. Giordano-Lascari, Esq. Karlin & Peebles, LLP Tel: 323 -648 -4649 Email: tgiordano@karlinpeebles. com -- William K. Norman. Esq. Ord & Norman West Los Angeles Tel: 310 -473 -8067 Email: ontaxla@yahoo. com 1
Global Intangible Low-Taxed Income Basic Questions 19 cWorking with the GILTI. pptx 2
Global Intangible Low-Taxed Income (GILTI) When Is GILTI Effective? GILTI is effective for TYs of a foreign corp. beginning after 12/31/17 and the TY of U. S. Shareholder in which or with which the TY of the foreign corp. ends. § 951 A P. L. 115 -97, § 14201(a) 19 cWorking with the GILTI. pptx 3
Global Intangible Low-Taxed Income (GILTI) What does GILTI Do? Broadly speaking, GILTI eliminates U. S. income tax deferral with respect to foreign earnings of controlled foreign corporations in excess of a fixed return (10%) on depreciable tangible assets. 19 cWorking with the GILTI. pptx 4
GILTI (Cont) What is the appropriate characterization of the outbound provisions of the Tax Cuts and Jobs Act that include GILTI? Three possible characterizations are plausible: - The provisions establish a quasi-territorial system with a minimum tax rate; - The provisions establish a minimum tax rate on foreign earnings in excess of a reasonable return on fixed assets; or - The provisions establish a multi-rate world-wide system. - The provisions are a closely integrated set of rules that collectively operate as a comprehensive framework for the taxation of earnings of foreign corporations with a specified level of U. S. ownership. 19 cWorking with the GILTI. pptx 5
GILTI (Cont) What are the core policy rationales for the GILTI provisions? • Current inclusion is necessary to protect against profit shifting under the territorial system to low tax jurisdictions. • Low effective tax rate of 10. 5 percent at the U. S. corporate Shareholder level is necessary for U. S. multinational corporations to remain competitive vis-àvis foreign MNCs. • Formulaic determinations are needed to minimize administrative burdens for the IRS. 19 cWorking with the GILTI. pptx 6

GILTI (Cont) U. S. Federal Income Taxation of Domestic C Corporations and Their Foreign Branches and Subsidiaries Domestic Earnings: Flat Rate 21. 0% After FDII deduction 13. 125% Foreign Earnings Post 1986 deferred earnings of DFICs through measurement date Related to cash position 15. 5% * Excess over cash position 8. 0% * Foreign branches 21. 0% * Subpart F income 21. 0% * GILTI inclusion 10. 5% * High taxed (>18. 9%) Subpart F income 0 Fixed return on tangible assets 0 Foreign Subsidiaries (CFC): Ten-Fifty Foreign Corporations Dividends 0 * Foreign tax credit available subject to limitations 19 cWorking with the GILTI. pptx 7
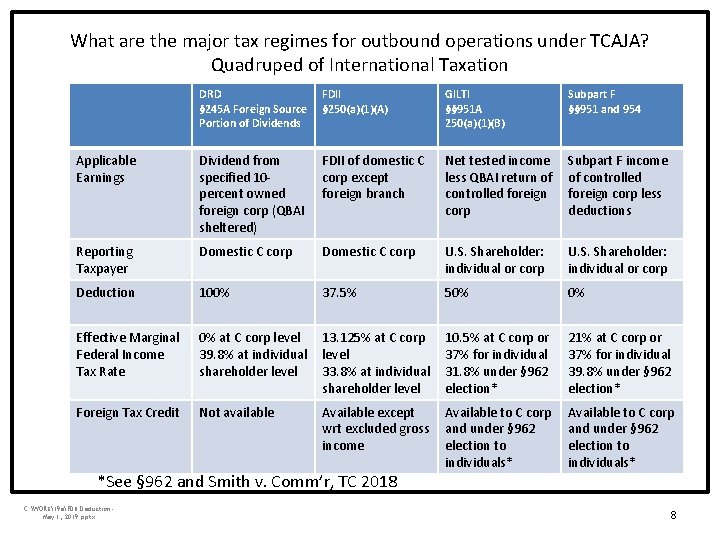
What are the major tax regimes for outbound operations under TCAJA? Quadruped of International Taxation DRD § 245 A Foreign Source Portion of Dividends FDII § 250(a)(1)(A) GILTI §§ 951 A 250(a)(1)(B) Subpart F §§ 951 and 954 Applicable Earnings Dividend from specified 10 percent owned foreign corp (QBAI sheltered) FDII of domestic C corp except foreign branch Net tested income less QBAI return of controlled foreign corp Subpart F income of controlled foreign corp less deductions Reporting Taxpayer Domestic C corp U. S. Shareholder: individual or corp Deduction 100% 37. 5% 50% 0% Effective Marginal Federal Income Tax Rate 0% at C corp level 13. 125% at C corp 39. 8% at individual level shareholder level 33. 8% at individual shareholder level 10. 5% at C corp or 37% for individual 31. 8% under § 962 election* 21% at C corp or 37% for individual 39. 8% under § 962 election* Foreign Tax Credit Not available Available except Available to C corp wrt excluded gross and under § 962 income election to individuals* *See § 962 and Smith v. Comm’r, TC 2018 C: WORK19 aFDII Deduction. May 1, 2019. pptx 8
GILTI (Cont) GILTI in a Nutshell: “U. S. Shareholder” of any “Controlled Foreign Corporation” (CFC) that owns stock of one or more CFCs directly or indirectly through a foreign entity (“Section 958(a) Stock”) includes in its gross income the shareholder’s “GILTI Inclusion Amount” for the “U. S. Shareholder Inclusion Year. ” “Section 958(a) Stock” is stock of a CFC owned directly or indirectly through foreign entities by a U. S. Shareholder. § 951 A(a), § 1. 951 A-1(b) 19 cWorking with the GILTI. pptx 9
GILTI (Cont) CFC is any foreign corporation where more than 50% of the vote or value of its shares is owned directly, indirectly or constructively by one or more “U. S. Shareholders” on any day of the taxable year of the corporation. §§ 957 and 958 § 951 A(e)(3) 19 cWorking with the GILTI. pptx 10
GILTI (Cont) • “U. S. Shareholder Inclusion Year” is the taxable year of a U. S. Shareholder that includes a “CFC Inclusion Date” of the CFC of the Shareholder. • “CFC Inclusion Date” is the last day of “CFC Inclusion Year” on which the foreign corporation is a CFC. • “CFC Inclusion Year” is any taxable year of a foreign corporation beginning after December 31, 2017 at time during which the corporation is a CFC. § 1. 951 A-1(e) 19 cWorking with the GILTI. pptx 11
GILTI (Cont) A “U. S. Shareholder” of a CFC is a U. S. Person” that owns (w/in meaning of § 958(a) i. e. , directly or indirectly through one or more foreign entities) 10% or more of the vote or value of stock in the foreign corp. on the last day in the taxable year of the foreign corp. on which it is a CFC. § 951 A(e)(2) § 951(b) 19 cWorking with the GILTI. pptx 12
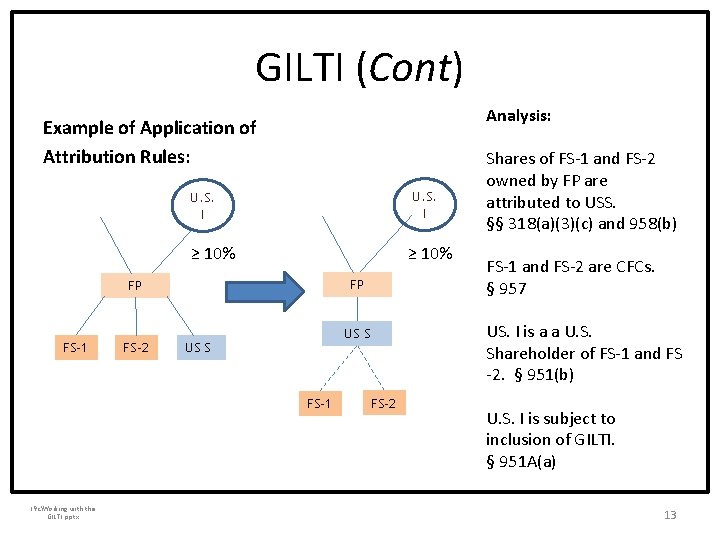
GILTI (Cont) Analysis: Example of Application of Attribution Rules: U. S. I ≥ 10% FP FP FS-1 FS-2 FS-1 19 cWorking with the GILTI. pptx FS-1 and FS-2 are CFCs. § 957 US. I is a a U. S. Shareholder of FS-1 and FS -2. § 951(b) US S Shares of FS-1 and FS-2 owned by FP are attributed to USS. §§ 318(a)(3)(c) and 958(b) FS-2 U. S. I is subject to inclusion of GILTI. § 951 A(a) 13
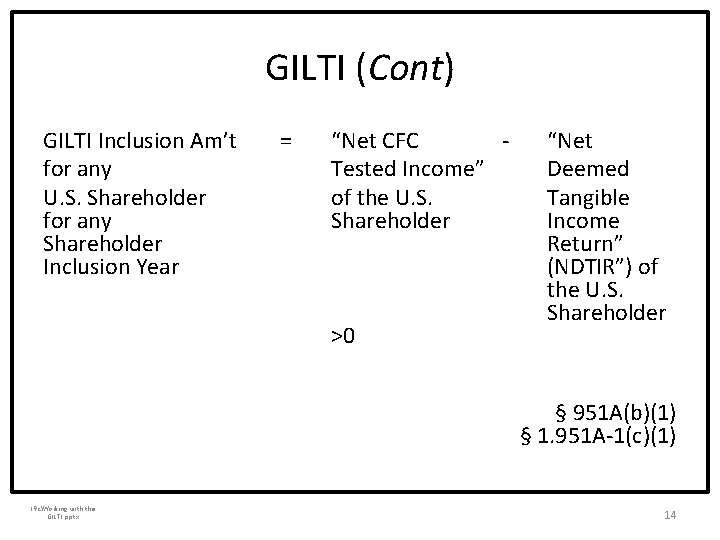
GILTI (Cont) GILTI Inclusion Am’t = for any U. S. Shareholder for any Shareholder Inclusion Year “Net CFC Tested Income” of the U. S. Shareholder >0 “Net Deemed Tangible Income Return” (NDTIR”) of the U. S. Shareholder § 951 A(b)(1) § 1. 951 A-1(c)(1) 19 cWorking with the GILTI. pptx 14
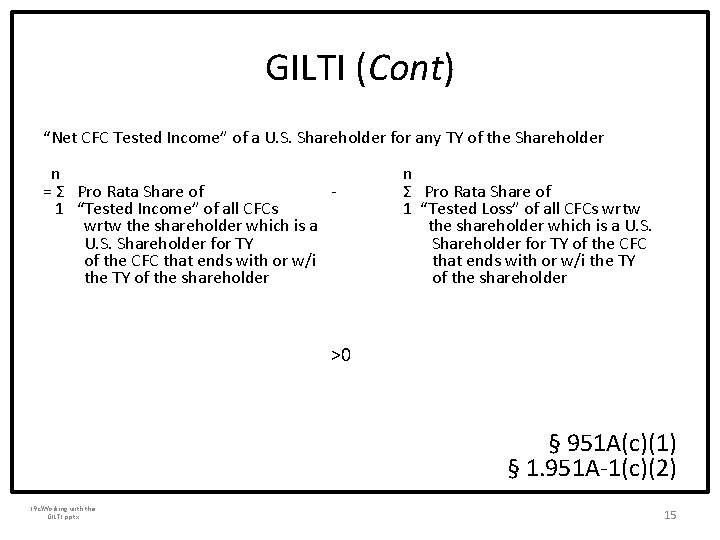
GILTI (Cont) “Net CFC Tested Income” of a U. S. Shareholder for any TY of the Shareholder n n = Ʃ Pro Rata Share of 1 “Tested Income” of all CFCs 1 “Tested Loss” of all CFCs wrtw the shareholder which is a the shareholder which is a U. S. Shareholder for TY of the CFC of the CFC that ends with or w/i the TY of the shareholder >0 § 951 A(c)(1) § 1. 951 A-1(c)(2) 19 cWorking with the GILTI. pptx 15
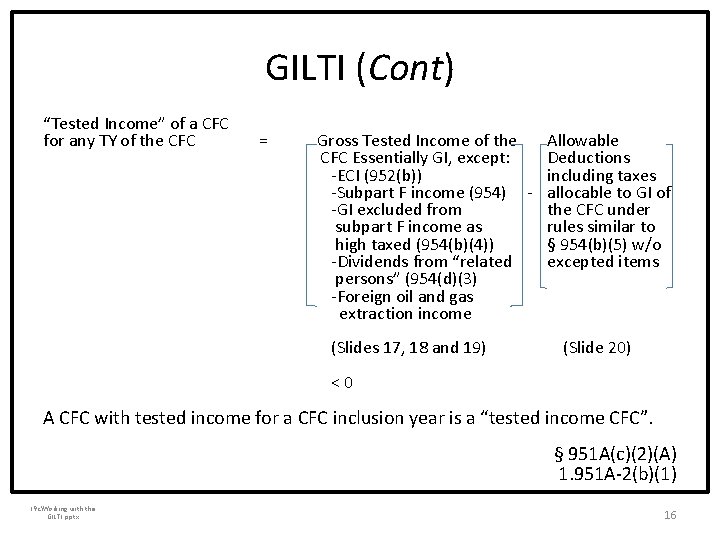
GILTI (Cont) “Tested Income” of a CFC for any TY of the CFC = Gross Tested Income of the CFC Essentially GI, except: -ECI (952(b)) -Subpart F income (954) -GI excluded from subpart F income as high taxed (954(b)(4)) -Dividends from “related persons” (954(d)(3) -Foreign oil and gas extraction income (Slides 17, 18 and 19) Allowable Deductions including taxes allocable to GI of the CFC under rules similar to § 954(b)(5) w/o excepted items (Slide 20) < 0 A CFC with tested income for a CFC inclusion year is a “tested income CFC”. § 951 A(c)(2)(A) 1. 951 A-2(b)(1) 19 cWorking with the GILTI. pptx 16
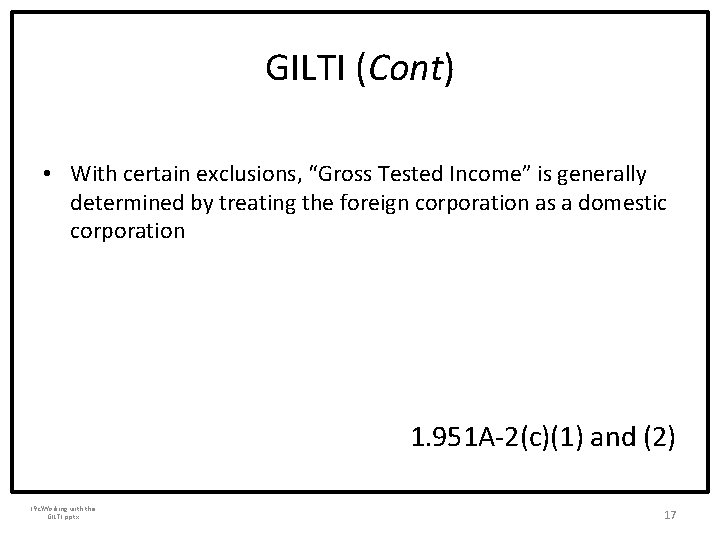
GILTI (Cont) • With certain exclusions, “Gross Tested Income” is generally determined by treating the foreign corporation as a domestic corporation 1. 951 A-2(c)(1) and (2) 19 cWorking with the GILTI. pptx 17
GILTI (Cont) • Exclusions from gross tested income are: – Gross income effectively connected, with the conduct a U. S. trade of business – Gross income treated as Subpart F income – Gross income excluded from Subpart F income solely by reason of high tax rate election 1. 951 A-2(c)(1) 19 cWorking with the GILTI. pptx 18
GILTI (Cont) – Dividend received by related foreign corporation organized in same foreign country and has a substantial part of its assets used in the same country. – Foreign oil and gas extraction income 1. 951 A-2(c)(1) 19 cWorking with the GILTI. pptx 19
GILTI (Cont) • Coordination with Subpart F: – Net tested income is the gross income of the corporation determined without regard to “any gross income taken into account in determining the subpart F income of such corporation. • So what does this mean? Final regulation 1. 951 A 2(c)(4) provides coordination rules between GILTI and subpart F. 19 cWorking with the GILTI. pptx 20
GILTI (Cont) • Coordination with Subpart F (cont): – Excludable subpart F includes: • • Insurance income Foreign base company income International boycott income Illegal bribes, kickbacks, or other payments – Excludable subpart F also includes gross income described above but that is excluded from subpart F income due to the E&P limitation under section 952(c)(1) 19 cWorking with the GILTI. pptx 21
GILTI (Cont) • Coordination with Subpart F (cont): – Excludable subpart F includes: • • Insurance income Foreign base company income International boycott income Illegal bribes, kickbacks, or other payments – Excludable subpart F also includes gross income described above but that is excluded from subpart F income due to the E&P limitation under section 952(c)(1) (see 1. 951 A 2(c)(4)(iii)(A)). • Recall, if a CFC has subpart F income in a given year, but no E&P, there is no subpart F inclusion. The subpart F income that should have been inclusion is deferred until there is E&P and then it is subject to recapture. • Thus, even if the subpart F income is not included in the US Shareholder’s income because of the E&P limitation, it is still not counted toward net tested income for GILTI purposes. 19 cWorking with the GILTI. pptx 22
GILTI (Cont) • Coordination with Subpart F (cont): – Excludable subpart F does not include gross income that is recaptured due under 952(c)(2) • Thus, net tested income will include gross income that is also recaptured and recharacterized as subpart F income; this has the potential to result in the same E&P being taxed twice in the year of inclusion. 19 cWorking with the GILTI. pptx 23
GILTI (Cont) • Allowable deductions allowed against gross tested income are allocated by treating gross tested income as a single item of gross income in a single separate category using “the principles of Sections 861, 864 and 904(d). ” 1. 951 A-2(c)(2) and (3) 1. 952 -2 1. 954 -1(c) 19 cWorking with the GILTI. pptx 24
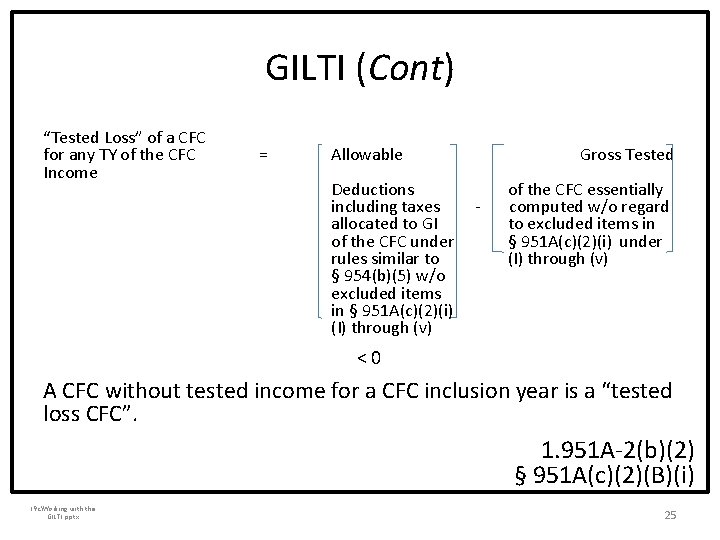
GILTI (Cont) “Tested Loss” of a CFC for any TY of the CFC Income = Allowable Deductions including taxes allocated to GI of the CFC under rules similar to § 954(b)(5) w/o excluded items in § 951 A(c)(2)(i) (I) through (v) Gross Tested of the CFC essentially - computed w/o regard to excluded items in § 951 A(c)(2)(i) under (I) through (v) < 0 A CFC without tested income for a CFC inclusion year is a “tested loss CFC”. 1. 951 A-2(b)(2) § 951 A(c)(2)(B)(i) 19 cWorking with the GILTI. pptx 25
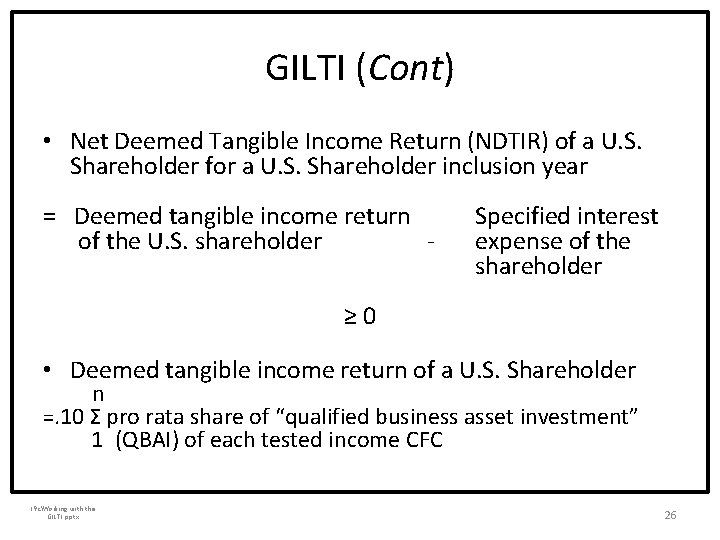
GILTI (Cont) • Net Deemed Tangible Income Return (NDTIR) of a U. S. Shareholder for a U. S. Shareholder inclusion year = Deemed tangible income return of the U. S. shareholder - Specified interest expense of the shareholder ≥ 0 • Deemed tangible income return of a U. S. Shareholder n =. 10 Ʃ pro rata share of “qualified business asset investment” 1 (QBAI) of each tested income CFC 19 cWorking with the GILTI. pptx 26
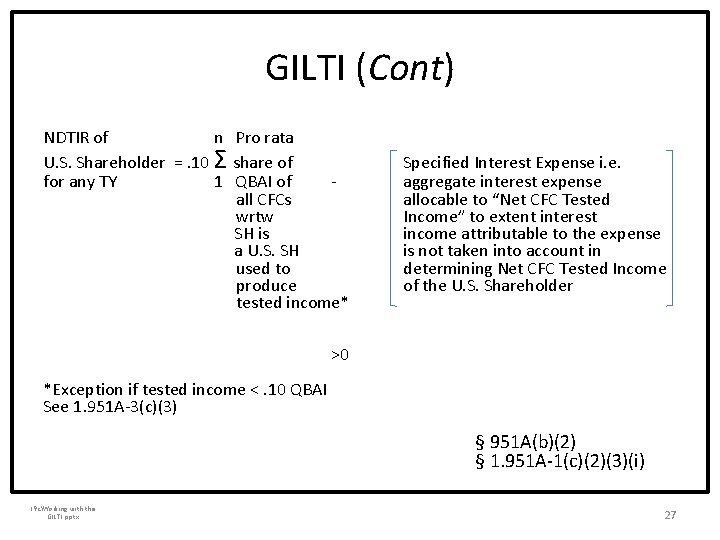
GILTI (Cont) NDTIR of n Pro rata U. S. Shareholder =. 10 Ʃ share of for any TY 1 QBAI of all CFCs wrtw SH is a U. S. SH used to produce tested income* Specified Interest Expense i. e. aggregate interest expense allocable to “Net CFC Tested Income” to extent interest income attributable to the expense is not taken into account in determining Net CFC Tested Income of the U. S. Shareholder >0 *Exception if tested income <. 10 QBAI See 1. 951 A-3(c)(3) § 951 A(b)(2) § 1. 951 A-1(c)(2)(3)(i) 19 cWorking with the GILTI. pptx 27
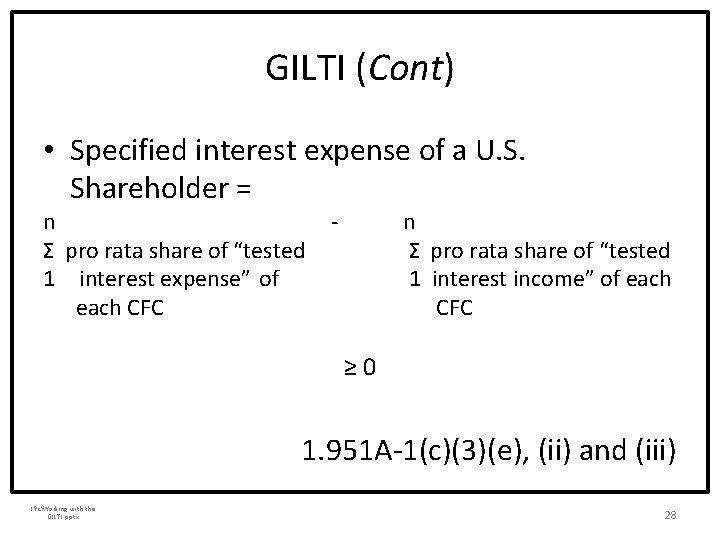
GILTI (Cont) • Specified interest expense of a U. S. Shareholder = n Ʃ pro rata share of “tested 1 interest expense” of each CFC - n Ʃ pro rata share of “tested 1 interest income” of each CFC ≥ 0 1. 951 A-1(c)(3)(e), (ii) and (iii) 19 cWorking with the GILTI. pptx 28
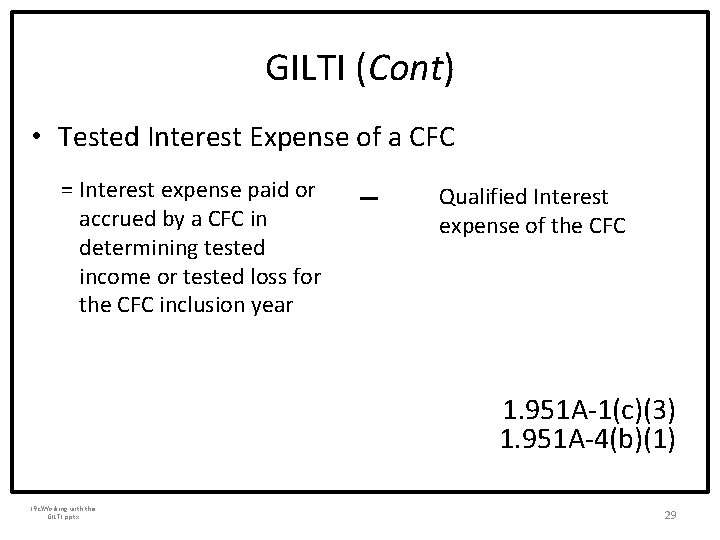
GILTI (Cont) • Tested Interest Expense of a CFC = Interest expense paid or accrued by a CFC in determining tested income or tested loss for the CFC inclusion year Qualified Interest expense of the CFC 1. 951 A-1(c)(3) 1. 951 A-4(b)(1) 19 cWorking with the GILTI. pptx 29
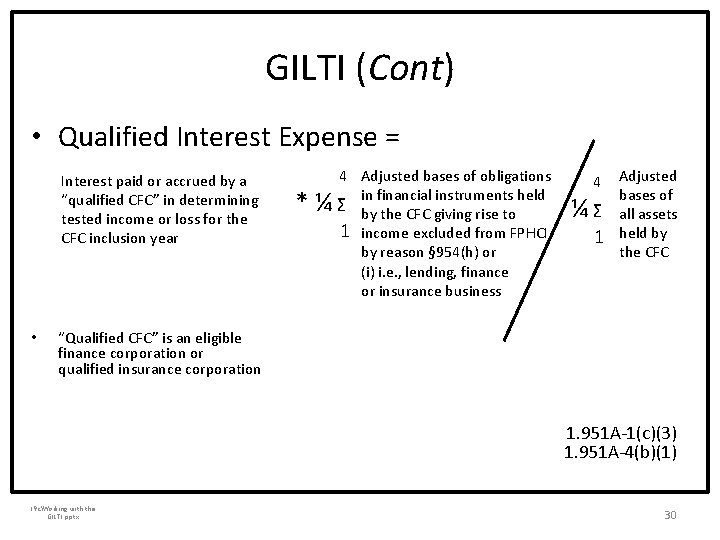
GILTI (Cont) • Qualified Interest Expense = Interest paid or accrued by a “qualified CFC” in determining tested income or loss for the CFC inclusion year • 4 Adjusted bases of obligations in financial instruments held Ʃ by the CFC giving rise to 1 income excluded from FPHCI by reason § 954(h) or (i) i. e. , lending, finance or insurance business * ¼ 4 ¼ Ʃ 1 Adjusted bases of all assets held by the CFC “Qualified CFC” is an eligible finance corporation or qualified insurance corporation 1. 951 A-1(c)(3) 1. 951 A-4(b)(1) 19 cWorking with the GILTI. pptx 30
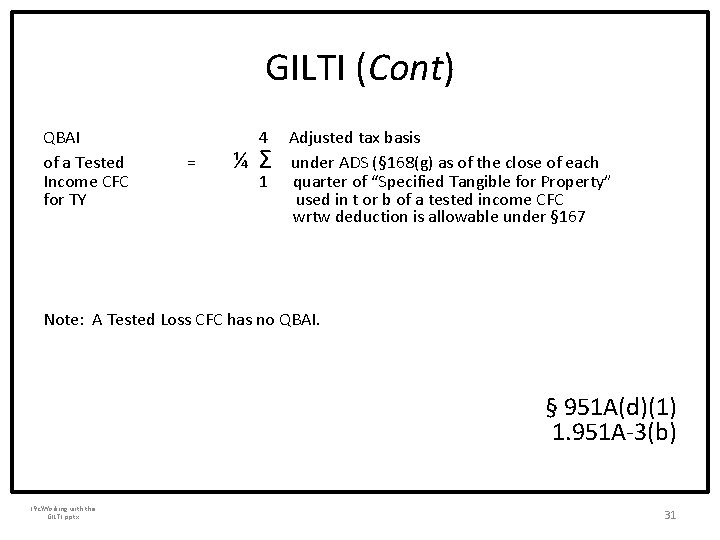
GILTI (Cont) QBAI 4 Adjusted tax basis of a Tested = ¼ Ʃ under ADS (§ 168(g) as of the close of each Income CFC 1 quarter of “Specified Tangible for Property” for TY used in t or b of a tested income CFC wrtw deduction is allowable under § 167 Note: A Tested Loss CFC has no QBAI. § 951 A(d)(1) 1. 951 A-3(b) 19 cWorking with the GILTI. pptx 31
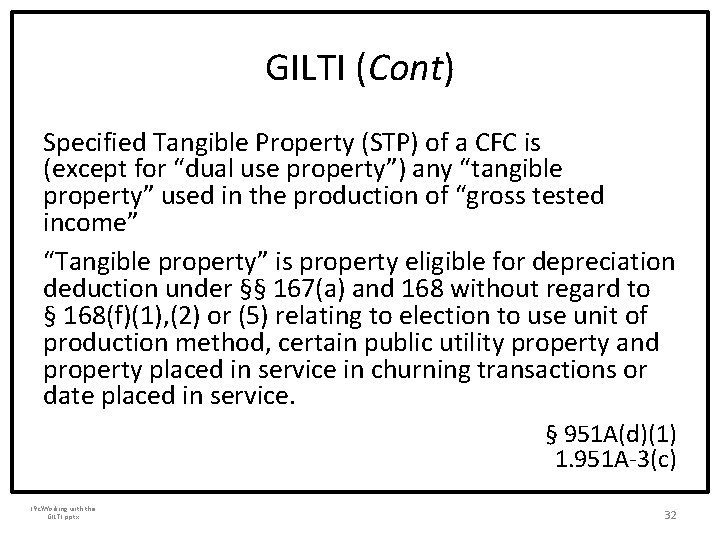
GILTI (Cont) Specified Tangible Property (STP) of a CFC is (except for “dual use property”) any “tangible property” used in the production of “gross tested income” “Tangible property” is property eligible for depreciation deduction under §§ 167(a) and 168 without regard to § 168(f)(1), (2) or (5) relating to election to use unit of production method, certain public utility property and property placed in service in churning transactions or date placed in service. § 951 A(d)(1) 1. 951 A-3(c) 19 cWorking with the GILTI. pptx 32
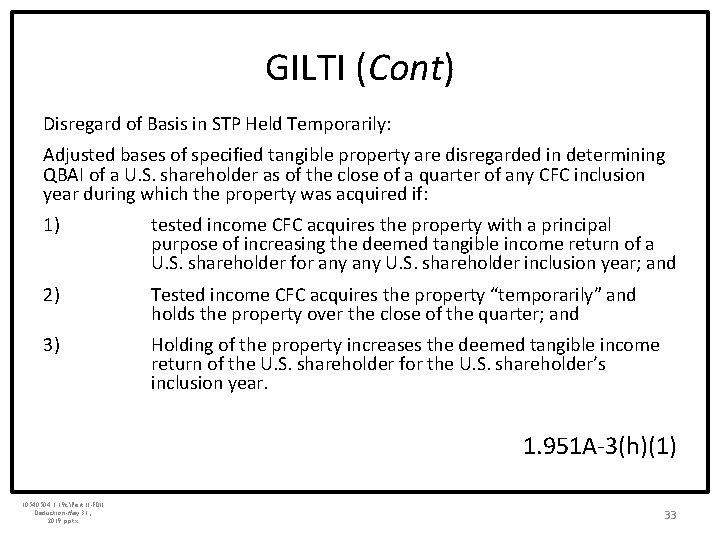
GILTI (Cont) Disregard of Basis in STP Held Temporarily: Adjusted bases of specified tangible property are disregarded in determining QBAI of a U. S. shareholder as of the close of a quarter of any CFC inclusion year during which the property was acquired if: 1) tested income CFC acquires the property with a principal purpose of increasing the deemed tangible income return of a U. S. shareholder for any U. S. shareholder inclusion year; and 2) Tested income CFC acquires the property “temporarily” and holds the property over the close of the quarter; and 3) Holding of the property increases the deemed tangible income return of the U. S. shareholder for the U. S. shareholder’s inclusion year. 1. 951 A-3(h)(1) 10540504. 1 19 cPart II-FDII Deduction-May 31, 2019. pptx 33
GILTI (Cont) Certain holdings of STP at the close of a quarter are not treated as increasing the deemed tangible income return of the U. S. shareholder if four conditions specified in the regulations are satisfied. 1. 951 A-3(h)(iii) 10540504. 1 19 cPart II-FDII Deduction-May 31, 2019. pptx 34
GILTI (Cont) Disqualified Basis in Specified Tangible Property Acquired in Disqualified Transfer in Disqualified Period Disqualified Basis of specified tangible property (STP) is not taken in account in determining the QBAI of a tested income CFC for a CFC inclusion year. 1. 951 A-3(h)(2) 10540504. 1 19 cPart II-FDII Deduction-May 31, 2019. pptx 35
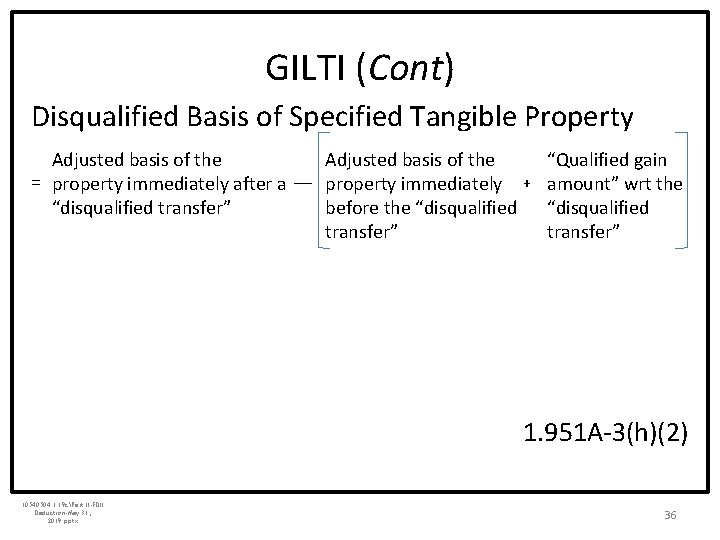
GILTI (Cont) Disqualified Basis of Specified Tangible Property Adjusted basis of the = property immediately after a property immediately + “disqualified transfer” before the “disqualified transfer” “Qualified gain amount” wrt the “disqualified transfer” 1. 951 A-3(h)(2) 10540504. 1 19 cPart II-FDII Deduction-May 31, 2019. pptx 36
GILTI (Cont) “Disqualified transfer” is a transfer of STP (including certain indirect transfers) during the “disqualified period” by the CFC to a “related person” in which gain was recognized in whole or in part. “Disqualified period” means, wrt the transferred CFC, the period beginning on January 1, 2018 and ending as of the close of the last taxable year of the CFC that is not a CFC inclusion year except for a CFC that has a CFC inclusion year beginning January 1, 2018 has no “disqualified period. ” “Related person” is a person treated as related to the CFC immediately before and immediately after under § 267(b) or § 707(b). 1. 951 A-3(h)(2) 10540504. 1 19 cPart II-FDII Deduction-May 31, 2019. pptx 37
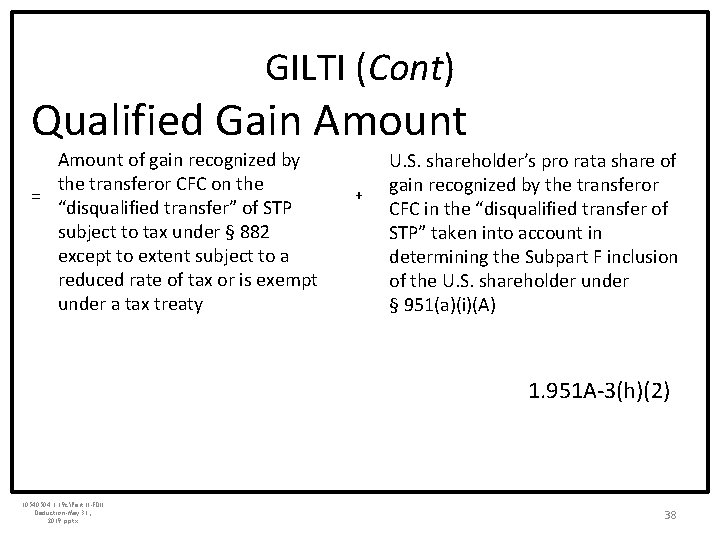
GILTI (Cont) Qualified Gain Amount of gain recognized by the transferor CFC on the = “disqualified transfer” of STP subject to tax under § 882 except to extent subject to a reduced rate of tax or is exempt under a tax treaty 10540504. 1 19 cPart II-FDII Deduction-May 31, 2019. pptx + U. S. shareholder’s pro rata share of gain recognized by the transferor CFC in the “disqualified transfer of STP” taken into account in determining the Subpart F inclusion of the U. S. shareholder under § 951(a)(i)(A) 1. 951 A-3(h)(2) 38
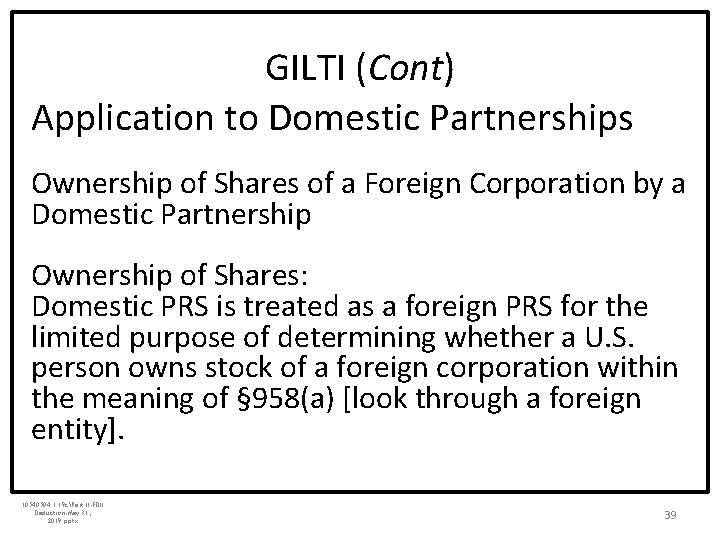
GILTI (Cont) Application to Domestic Partnerships Ownership of Shares of a Foreign Corporation by a Domestic Partnership Ownership of Shares: Domestic PRS is treated as a foreign PRS for the limited purpose of determining whether a U. S. person owns stock of a foreign corporation within the meaning of § 958(a) [look through a foreign entity]. 10540504. 1 19 cPart II-FDII Deduction-May 31, 2019. pptx 39
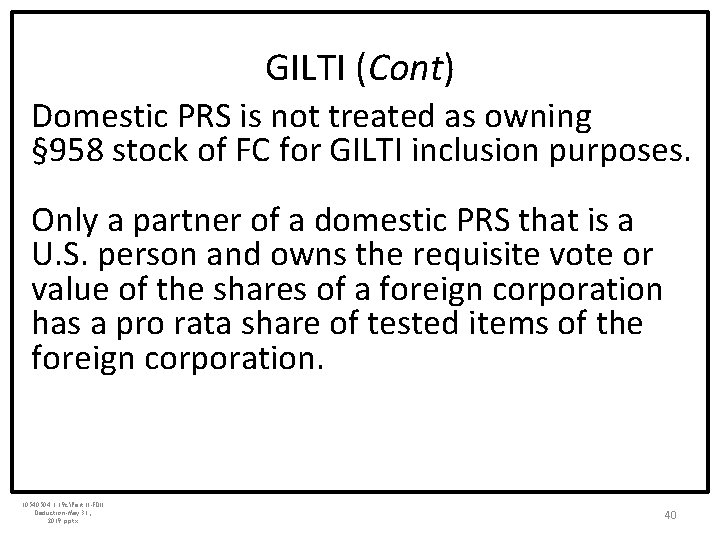
GILTI (Cont) Domestic PRS is not treated as owning § 958 stock of FC for GILTI inclusion purposes. Only a partner of a domestic PRS that is a U. S. person and owns the requisite vote or value of the shares of a foreign corporation has a pro rata share of tested items of the foreign corporation. 10540504. 1 19 cPart II-FDII Deduction-May 31, 2019. pptx 40
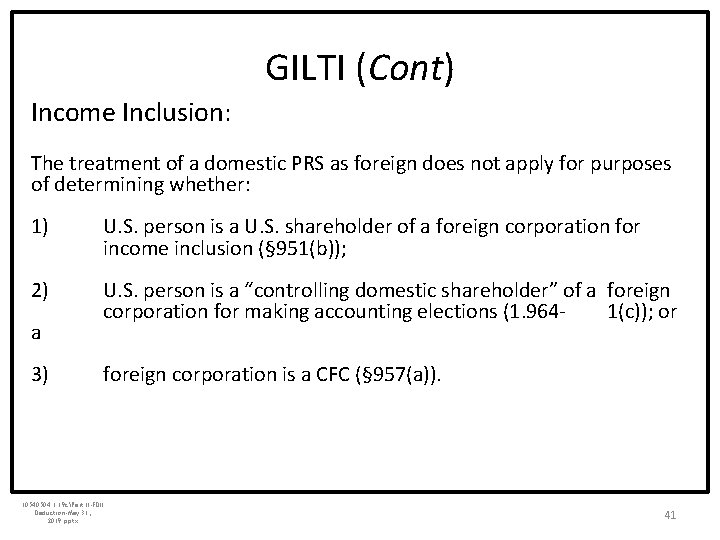
GILTI (Cont) Income Inclusion: The treatment of a domestic PRS as foreign does not apply for purposes of determining whether: 1) U. S. person is a U. S. shareholder of a foreign corporation for income inclusion (§ 951(b)); 2) U. S. person is a “controlling domestic shareholder” of a foreign corporation for making accounting elections (1. 9641(c)); or a 3) foreign corporation is a CFC (§ 957(a)). 10540504. 1 19 cPart II-FDII Deduction-May 31, 2019. pptx 41
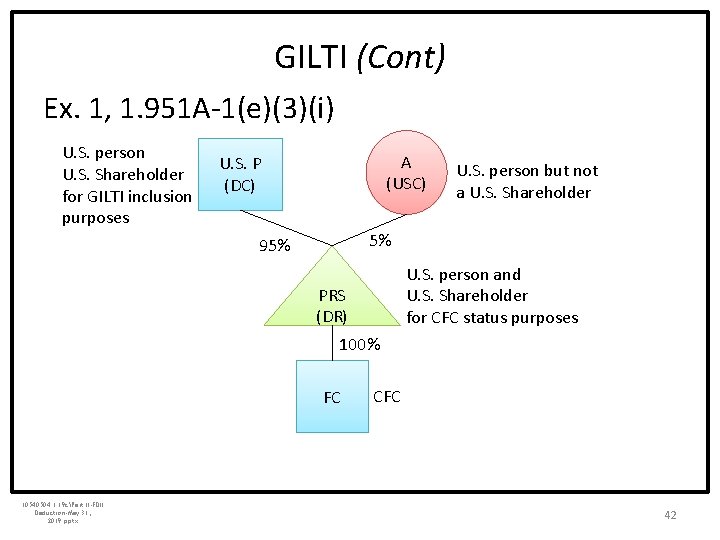
GILTI (Cont) Ex. 1, 1. 951 A-1(e)(3)(i) U. S. person U. S. Shareholder for GILTI inclusion purposes A (USC) U. S. P (DC) U. S. person but not a U. S. Shareholder 5% 95% U. S. person and U. S. Shareholder for CFC status purposes PRS (DR) 100% FC 10540504. 1 19 cPart II-FDII Deduction-May 31, 2019. pptx CFC 42
GILTI (Cont) 1) Analysis for U. S. shareholder and CFC determinations: PRS treated as foreign partnership for purposes of determining whether PRS, USP or A are U. S. shareholders of FC and whether FC is a CFC. PRS is a U. S. person. RS owns 95% FC under § 958(a). Hence, PRS is a U. S. shareholder of FC under § 951(b). FC is a CFC under § 957(a). A owns 5% of FC under §§ 958(b) and 318(a)(2)(ii). Hence A is not a U. S. shareholder under § 958(b). 10540504. 1 19 cPart II-FDII Deduction-May 31, 2019. pptx 43
GILTI (Cont) 2) Analysis for GILTI inclusion (Section 951 A) purposes: PRS is not treated as a foreign partnership. Hence, USP and A are treated as owning 95% and 5% respectively of FC; A is not a U. S. shareholder of FC. A does not report any pro rata share of any tested items of FC. 10540504. 1 19 cPart II-FDII Deduction-May 31, 2019. pptx 44
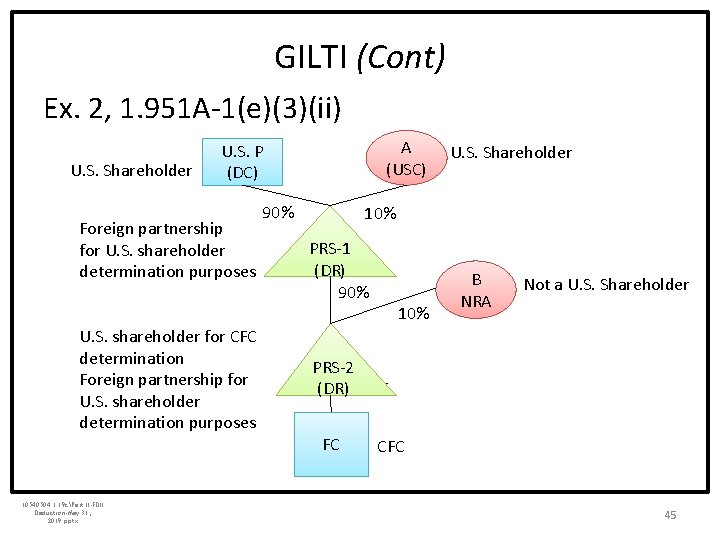
GILTI (Cont) Ex. 2, 1. 951 A-1(e)(3)(ii) U. S. Shareholder Foreign partnership for U. S. shareholder determination purposes U. S. shareholder for CFC determination Foreign partnership for U. S. shareholder determination purposes 10540504. 1 19 cPart II-FDII Deduction-May 31, 2019. pptx A (USC) U. S. P (DC) 90% U. S. Shareholder 10% PRS-1 (DR) 90% 10% B NRA Not a U. S. Shareholder PRS-2 (DR)100% FC CFC 45
GILTI (Cont) 1) Analysis for U. S. shareholder and CFC determinations: PRS-2 is treated as a domestic partnership for purposes of determining whether it is a U. S. shareholder of FC and whether FC is a CFC. PRS-2 owns 100% of stock of FC. Hence, PRS-2 is a U. S. shareholder under § 951(b) and FC is a CFC under § 957(a). 10540504. 1 19 cPart II-FDII Deduction-May 31, 2019. pptx 46
GILTI (Cont) 2) Analysis for GILTI inclusion purposes: PRS-2 is treated as a foreign partnership for purposes of determining the ownership of FC by PRS-1 is treated as a foreign partnership for purpose of determining the ownership of stock of FC by USP and A. U. S. P-1 is treated as owning 100% of the stock owned by PRS-2 for purposes of determining the amount of stock of FC owned by USP and A under §§ 318(a)(2) as modified by 958(b)(2). 10540504. 1 19 cPart II-FDII Deduction-May 31, 2019. pptx 47
GILTI (Cont) 2) Analysis for GILTI inclusion purposes (cont): Therefore USP is treated as owning 90% of stock of FC (100% * 90%) and is a U. S. shareholder under § 951(b). A is treated as owning 10% of FC stock (100% *10%) and is a U. S. shareholder under § 951(b). 10540504. 1 19 cPart II-FDII Deduction-May 31, 2019. pptx 48
GILTI (Cont) 2) Analysis for GILTI inclusion purposes (cont): For purpose of determining the GILTI inclusion, PRS-1 and PRS-2 are treated in the same manner as foreign partnerships. Therefore for GILTI inclusion purposes US P is a U. S. shareholder and is treated as owning 81% of stock of FC under § 958(a) (100% * 90%). The pro rata share of U. S. P is determined on basis of § 958(a) tested items of ownership. 10540504. 1 19 cPart II-FDII Deduction-May 31, 2019. pptx 49
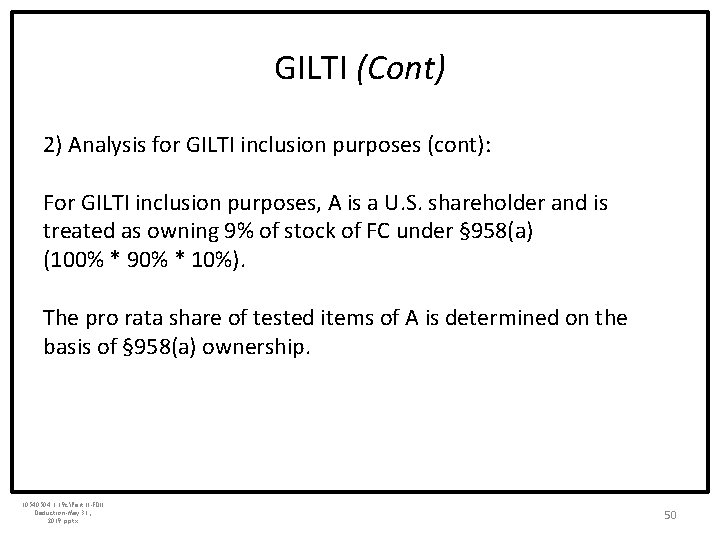
GILTI (Cont) 2) Analysis for GILTI inclusion purposes (cont): For GILTI inclusion purposes, A is a U. S. shareholder and is treated as owning 9% of stock of FC under § 958(a) (100% * 90% * 10%). The pro rata share of tested items of A is determined on the basis of § 958(a) ownership. 10540504. 1 19 cPart II-FDII Deduction-May 31, 2019. pptx 50
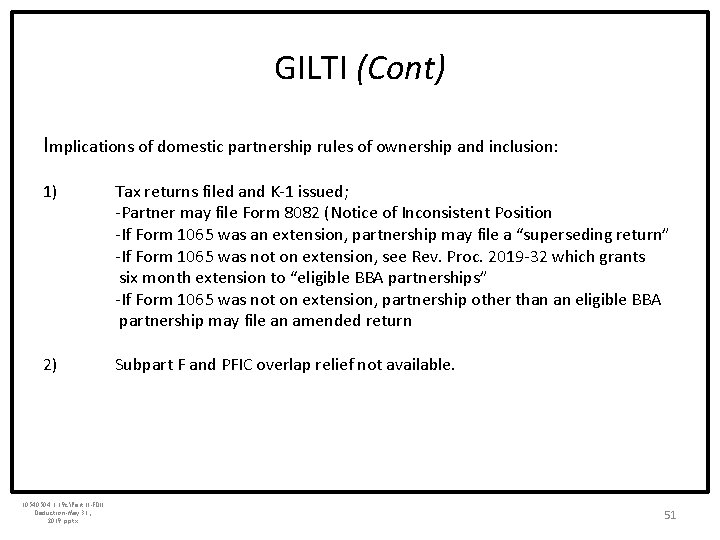
GILTI (Cont) Implications of domestic partnership rules of ownership and inclusion: 1) Tax returns filed and K-1 issued; -Partner may file Form 8082 (Notice of Inconsistent Position -If Form 1065 was an extension, partnership may file a “superseding return” -If Form 1065 was not on extension, see Rev. Proc. 2019 -32 which grants six month extension to “eligible BBA partnerships” -If Form 1065 was not on extension, partnership other than an eligible BBA partnership may file an amended return 2) Subpart F and PFIC overlap relief not available. 10540504. 1 19 cPart II-FDII Deduction-May 31, 2019. pptx 51
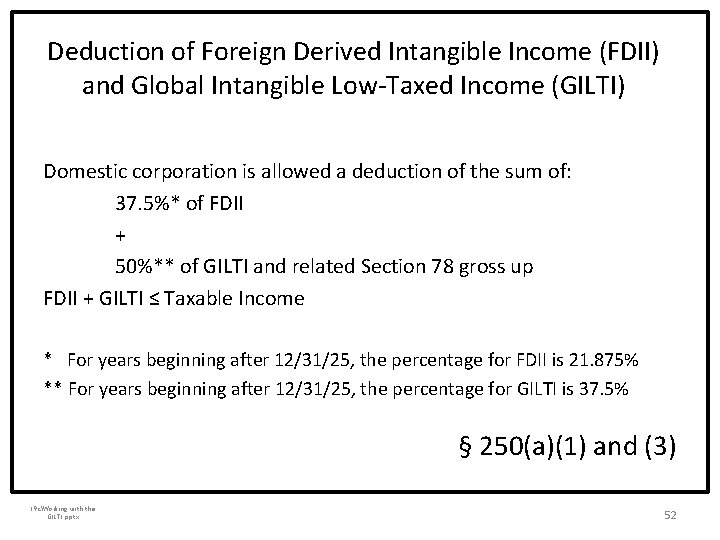
Deduction of Foreign Derived Intangible Income (FDII) and Global Intangible Low-Taxed Income (GILTI) Domestic corporation is allowed a deduction of the sum of: 37. 5%* of FDII + 50%** of GILTI and related Section 78 gross up FDII + GILTI ≤ Taxable Income * For years beginning after 12/31/25, the percentage for FDII is 21. 875% ** For years beginning after 12/31/25, the percentage for GILTI is 37. 5% § 250(a)(1) and (3) 19 cWorking with the GILTI. pptx 52
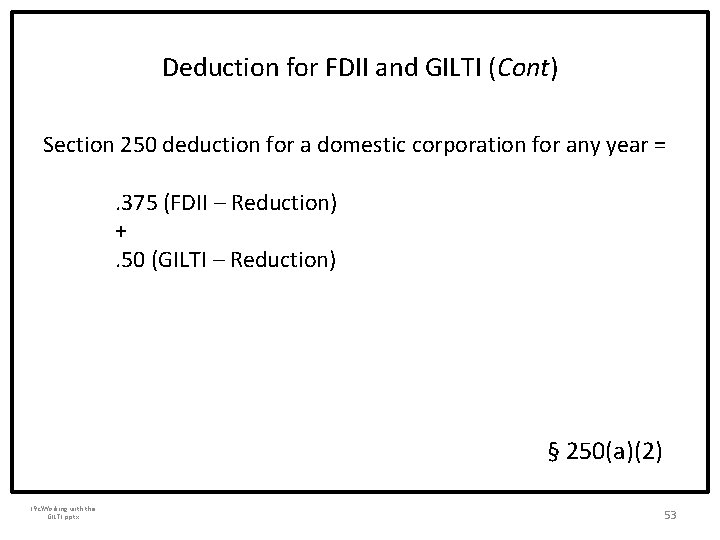
Deduction for FDII and GILTI (Cont) Section 250 deduction for a domestic corporation for any year =. 375 (FDII – Reduction) +. 50 (GILTI – Reduction) § 250(a)(2) 19 cWorking with the GILTI. pptx 53
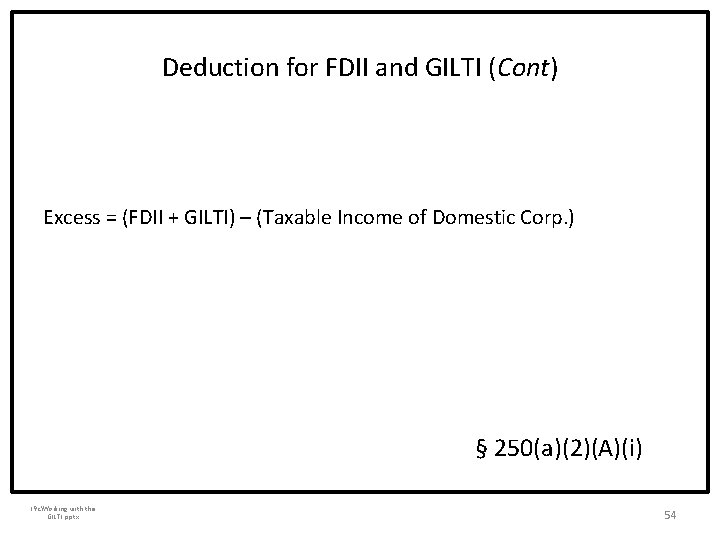
Deduction for FDII and GILTI (Cont) Excess = (FDII + GILTI) – (Taxable Income of Domestic Corp. ) § 250(a)(2)(A)(i) 19 cWorking with the GILTI. pptx 54
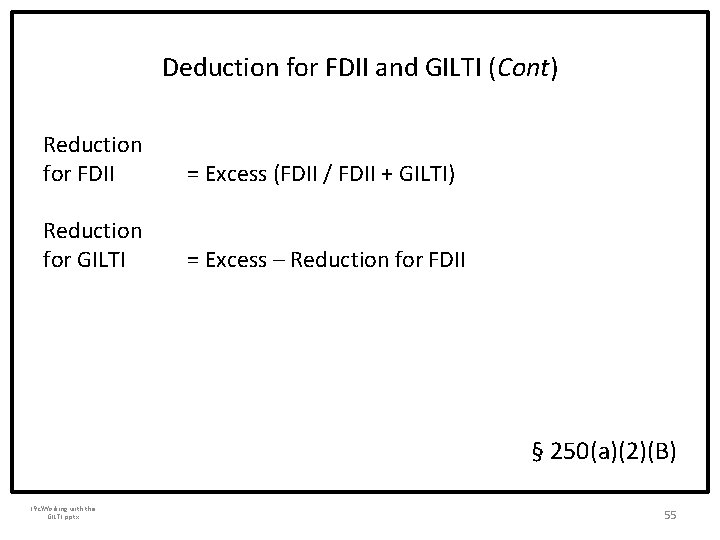
Deduction for FDII and GILTI (Cont) Reduction for FDII = Excess (FDII / FDII + GILTI) Reduction for GILTI = Excess – Reduction for FDII § 250(a)(2)(B) 19 cWorking with the GILTI. pptx 55
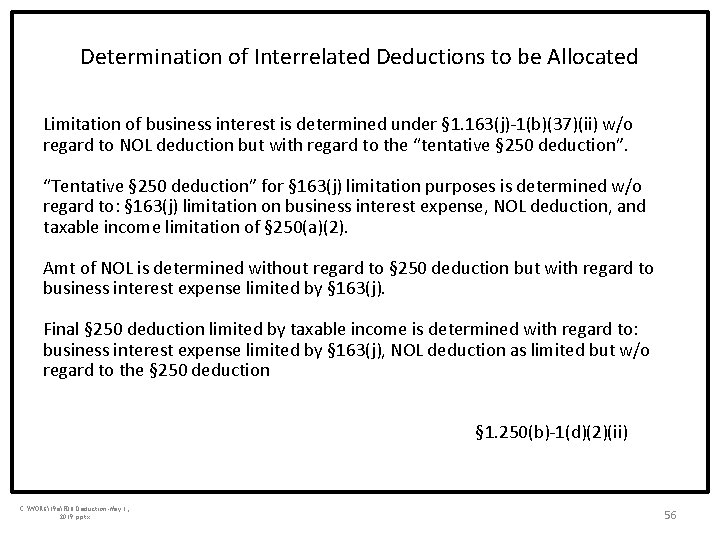
Determination of Interrelated Deductions to be Allocated Limitation of business interest is determined under § 1. 163(j)-1(b)(37)(ii) w/o regard to NOL deduction but with regard to the “tentative § 250 deduction”. “Tentative § 250 deduction” for § 163(j) limitation purposes is determined w/o regard to: § 163(j) limitation on business interest expense, NOL deduction, and taxable income limitation of § 250(a)(2). Amt of NOL is determined without regard to § 250 deduction but with regard to business interest expense limited by § 163(j). Final § 250 deduction limited by taxable income is determined with regard to: business interest expense limited by § 163(j), NOL deduction as limited but w/o regard to the § 250 deduction § 1. 250(b)-1(d)(2)(ii) C: WORK19 aFDII Deduction-May 1, 2019. pptx 56
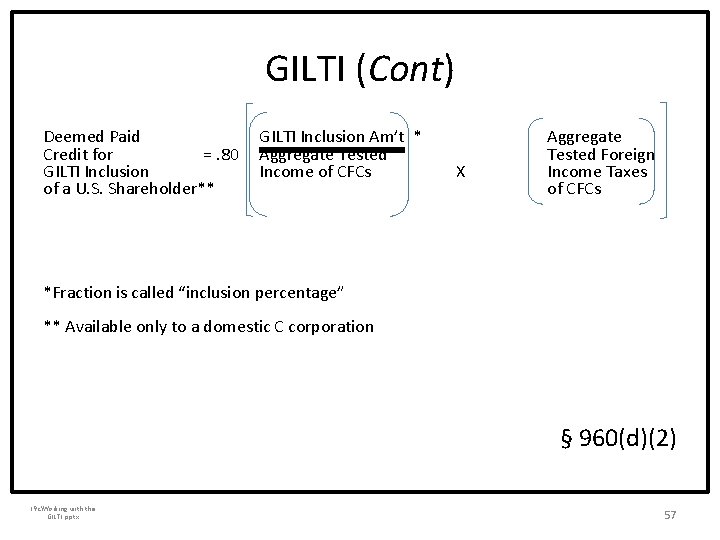
GILTI (Cont) Deemed Paid Credit for =. 80 GILTI Inclusion of a U. S. Shareholder** GILTI Inclusion Am’t * Aggregate Tested Income of CFCs X Aggregate Tested Foreign Income Taxes of CFCs *Fraction is called “inclusion percentage” ** Available only to a domestic C corporation § 960(d)(2) 19 cWorking with the GILTI. pptx 57
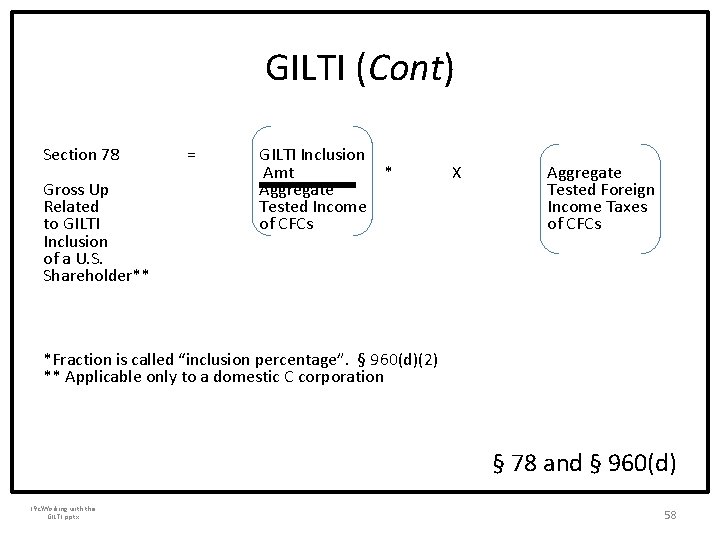
GILTI (Cont) Section 78 = Gross Up Related to GILTI Inclusion of a U. S. Shareholder** GILTI Inclusion Amt * X Aggregate Tested Income of CFCs Aggregate Tested Foreign Income Taxes of CFCs *Fraction is called “inclusion percentage”. § 960(d)(2) ** Applicable only to a domestic C corporation § 78 and § 960(d) 19 cWorking with the GILTI. pptx 58
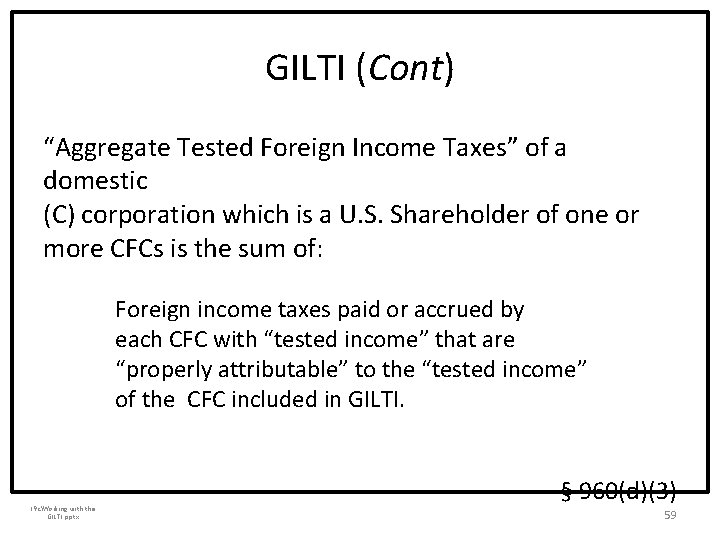
GILTI (Cont) “Aggregate Tested Foreign Income Taxes” of a domestic (C) corporation which is a U. S. Shareholder of one or more CFCs is the sum of: Foreign income taxes paid or accrued by each CFC with “tested income” that are “properly attributable” to the “tested income” of the CFC included in GILTI. 19 cWorking with the GILTI. pptx § 960(d)(3) 59
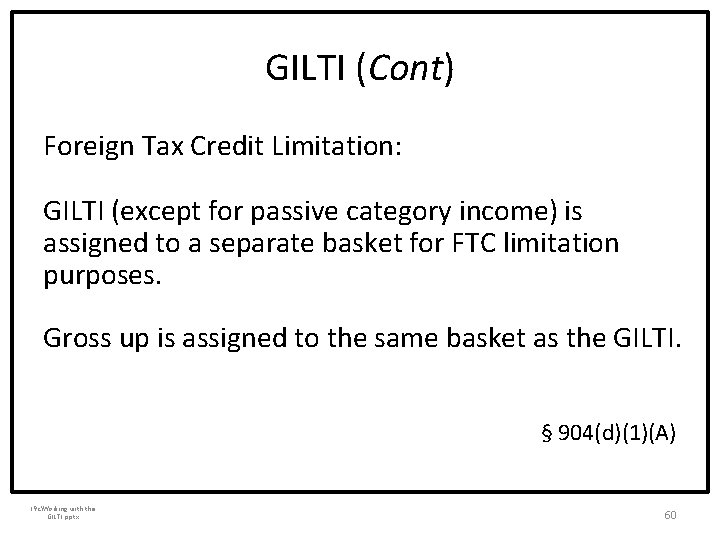
GILTI (Cont) Foreign Tax Credit Limitation: GILTI (except for passive category income) is assigned to a separate basket for FTC limitation purposes. Gross up is assigned to the same basket as the GILTI. § 904(d)(1)(A) 19 cWorking with the GILTI. pptx 60
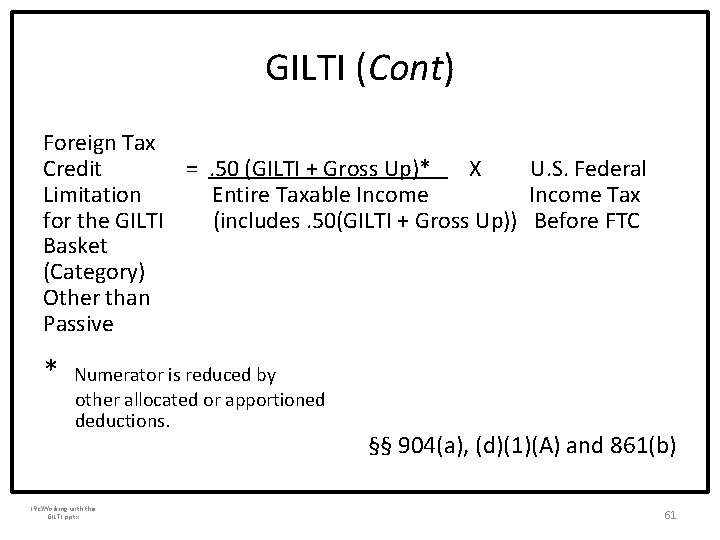
GILTI (Cont) Foreign Tax Credit = . 50 (GILTI + Gross Up)* X U. S. Federal Limitation Entire Taxable Income Tax for the GILTI (includes. 50(GILTI + Gross Up)) Before FTC Basket (Category) Other than Passive * Numerator is reduced by other allocated or apportioned deductions. 19 cWorking with the GILTI. pptx §§ 904(a), (d)(1)(A) and 861(b) 61
Summary of GILTI Determinations 19 cWorking with the GILTI. pptx 62
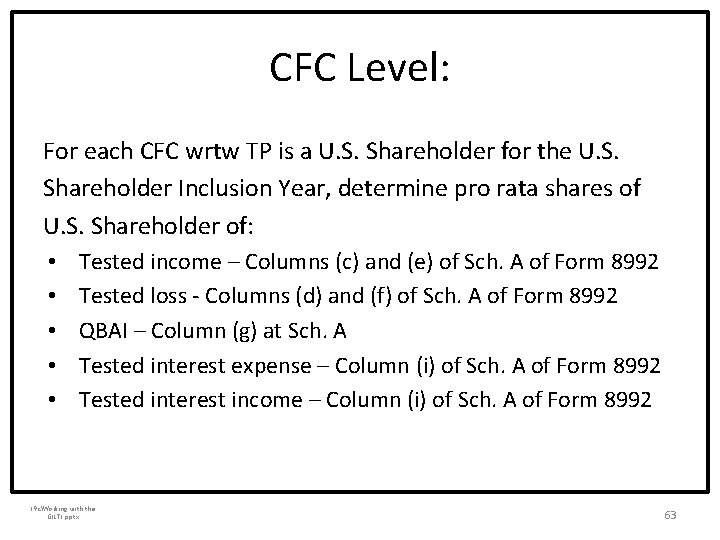
CFC Level: For each CFC wrtw TP is a U. S. Shareholder for the U. S. Shareholder Inclusion Year, determine pro rata shares of U. S. Shareholder of: • • • Tested income – Columns (c) and (e) of Sch. A of Form 8992 Tested loss - Columns (d) and (f) of Sch. A of Form 8992 QBAI – Column (g) at Sch. A Tested interest expense – Column (i) of Sch. A of Form 8992 Tested interest income – Column (i) of Sch. A of Form 8992 19 cWorking with the GILTI. pptx 63
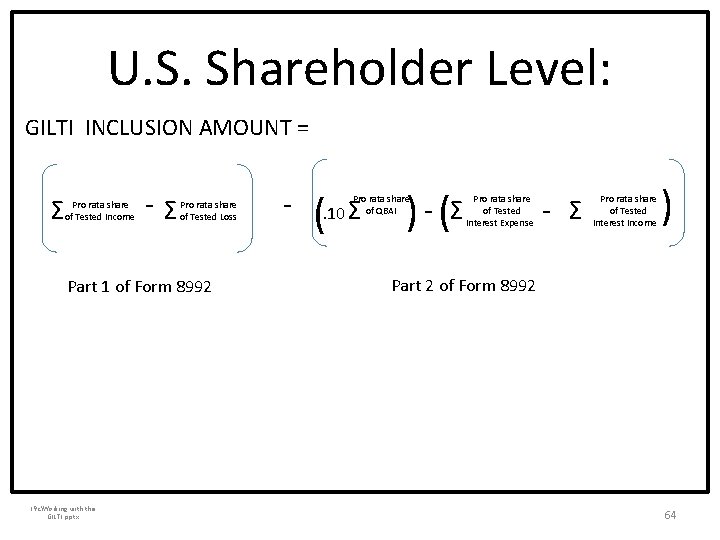
U. S. Shareholder Level: GILTI INCLUSION AMOUNT = Ʃ Pro rata share of Tested Income -Ʃ Pro rata share of Tested Loss Part 1 of Form 8992 19 cWorking with the GILTI. pptx - (. 10 Ʃ ) - (Ʃ Pro rata share of QBAI Pro rata share of Tested Interest Expense - Ʃ Pro rata share of Tested Interest Income ) Part 2 of Form 8992 64
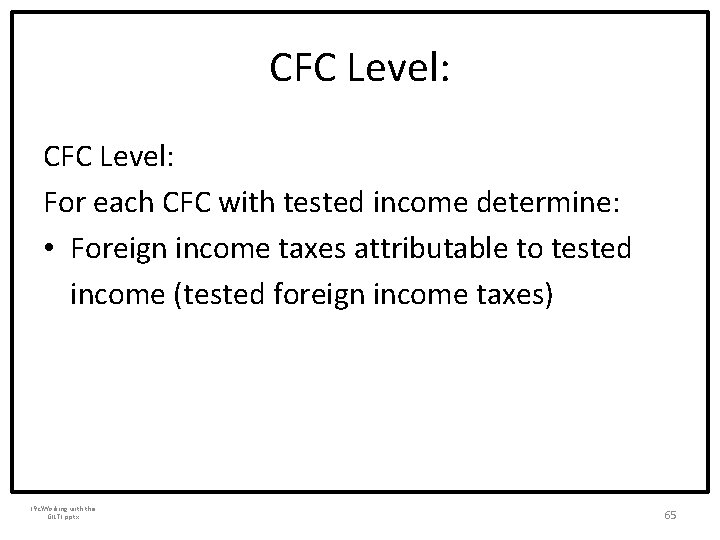
CFC Level: For each CFC with tested income determine: • Foreign income taxes attributable to tested income (tested foreign income taxes) 19 cWorking with the GILTI. pptx 65
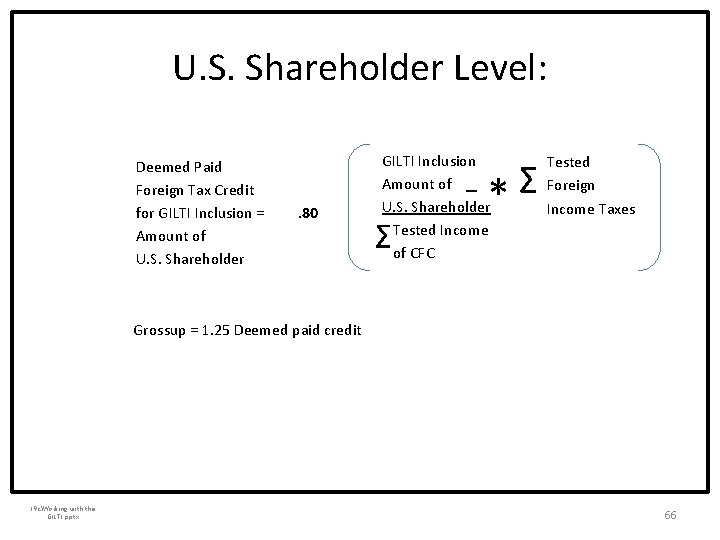
U. S. Shareholder Level: Deemed Paid Foreign Tax Credit for GILTI Inclusion = . 80 Amount of U. S. Shareholder GILTI Inclusion Amount of U. S. Shareholder Tested Income of CFC Ʃ Ʃ * Tested Foreign Income Taxes Grossup = 1. 25 Deemed paid credit 19 cWorking with the GILTI. pptx 66
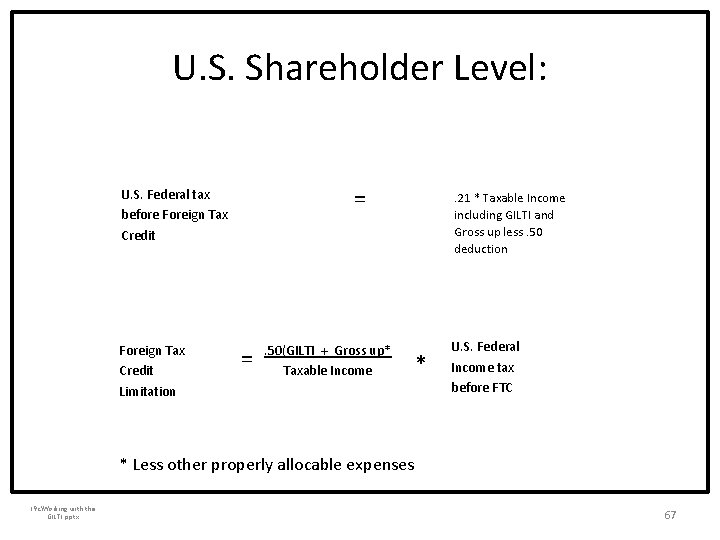
U. S. Shareholder Level: = U. S. Federal tax before Foreign Tax Credit Limitation = . 50(GILTI + Gross up* Taxable Income . 21 * Taxable Income including GILTI and Gross up less. 50 deduction * U. S. Federal Income tax before FTC * Less other properly allocable expenses 19 cWorking with the GILTI. pptx 67
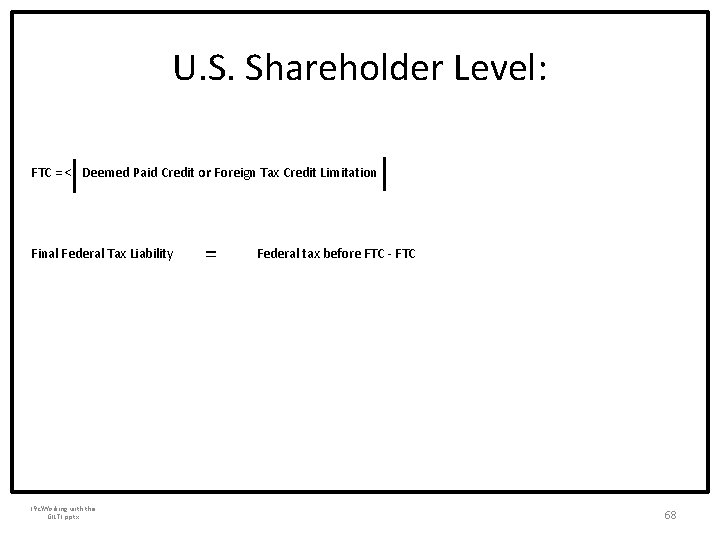
U. S. Shareholder Level: FTC = < Deemed Paid Credit or Foreign Tax Credit Limitation Final Federal Tax Liability 19 cWorking with the GILTI. pptx = Federal tax before FTC - FTC 68
Proposed GILTI High-Tax Exception • As mentioned, previously, net tested income excludes foreign base company income or foreign insurance income that is excluded from subpart F under the high-tax exception of section 954(b)(4). – The October 2018 proposed regulations and the June 2019 final regulations confirm this treatment and do not otherwise extend the high-tax exception of non FBCI or FII. – However, simultaneously with the release of the June 19 final regulations, new proposed regulations were also issued that potentially extend the high-tax exception to GILTI. 19 cWorking with the GILTI. pptx 69
Proposed GILTI High-Tax Exception (cont) • Proposed Regulation 1. 951 A-2(c)(6) provides: – An election may be made for a CFC to exclude from gross tested income, gross income subject to foreign income tax at an effective rate that is greater than 90% of the rate that would apply if the income were subject to the maximum rate of tax under section 11 (e. g. 18. 9% based on the current corporate of 21%). – The election is made by the CFC’s controlling domestic shareholders with respect to the CFC for a CFC inclusion year. – The election is binding on future years unless revoked. If revoked, a new election cannot be made for 5 years. If a new election is made, that election cannot be revoked for 5 years. – If a CFC is a member of a controlling domestic shareholder group, the election applies with respect to each member of the controlling domestic shareholder group. • 2 or more CFCs if more than 50% of the stock (by vote) of each CFC is woned by the same controlling domestic shareholder. 19 cWorking with the GILTI. pptx 70
Proposed GILTI High-Tax Exception (cont) • Proposed Regulation 1. 951 A-2(c)(6) provides: – The relevant items of income for purposes of the election are all items of gross tested income attributed to a qualified business unit (“QBU”) • Look to books and records of the QBU to determine if an item of gross income is attributable to the QBU. – Principals of section 960 apply to allocate foreign taxes to each item of gross income of a QBU to measure the effective tax rate. Those items of gross income that meet the required effective tax rate can be excluded under the GILTI high-tax exception. 19 cWorking with the GILTI. pptx 71
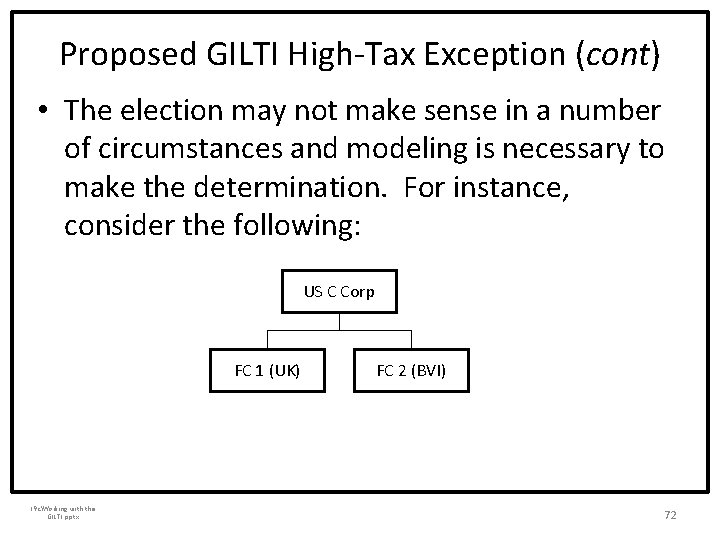
Proposed GILTI High-Tax Exception (cont) • The election may not make sense in a number of circumstances and modeling is necessary to make the determination. For instance, consider the following: US C Corp FC 1 (UK) 19 cWorking with the GILTI. pptx FC 2 (BVI) 72
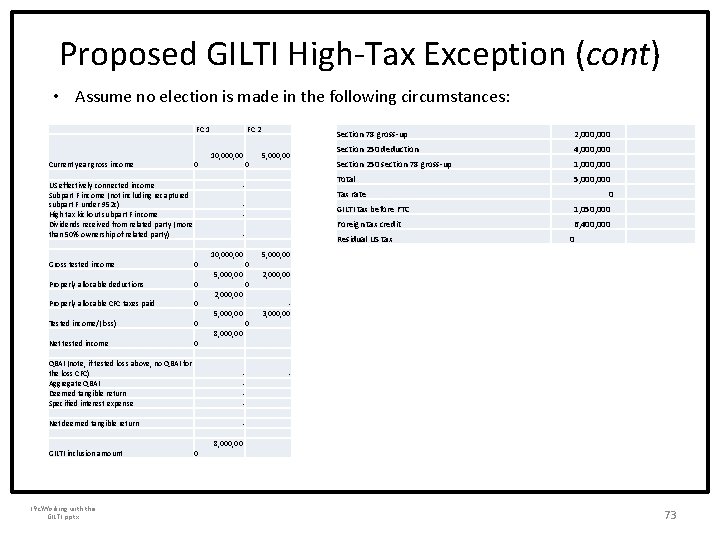
Proposed GILTI High-Tax Exception (cont) • Assume no election is made in the following circumstances: FC 1 Current year gross income FC 2 10, 00 5, 000, 00 0 0 US effectively connected income - Subpart F income (not including recaptured subpart F under 952 c) - High tax kickout subpart F income - Dividends received from related party (more than 50% ownership of related party) - Gross tested income Properly allocable deductions Properly allocable CFC taxes paid Tested income/(loss) Net tested income Section 78 gross-up 2, 000 Section 250 deduction 4, 000 Section 250 section 78 gross-up 1, 000 Total 5, 000 Tax rate 0 GILTI tax before FTC 1, 050, 000 Foreign tax credit 6, 400, 000 Residual US tax 0 10, 00 5, 000, 00 0 0 5, 000, 00 2, 000, 00 0 - 5, 000, 00 3, 000, 00 0 0 8, 000, 00 0 QBAI (note, if tested loss above, no QBAI for the loss CFC) - Aggregate QBAI - Deemed tangible return - Specified interest expense - Net deemed tangible return - GILTI inclusion amount 8, 000, 00 0 19 cWorking with the GILTI. pptx 73
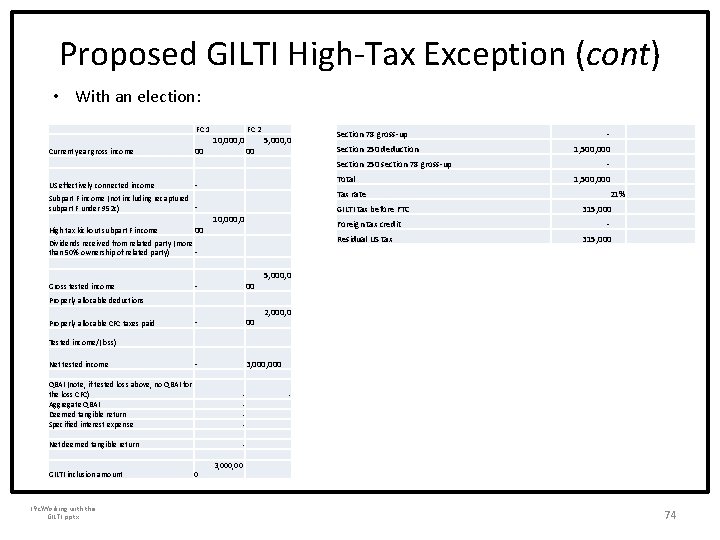
Proposed GILTI High-Tax Exception (cont) • With an election: FC 1 Current year gross income FC 2 10, 000, 0 5, 000, 0 00 00 - US effectively connected income Subpart F income (not including recaptured - subpart F under 952 c) 10, 000, 0 00 High tax kickout subpart F income Dividends received from related party (more - than 50% ownership of related party) Gross tested income Section 78 gross-up - Section 250 deduction 1, 500, 000 Section 250 section 78 gross-up - Total 1, 500, 000 Tax rate 21% GILTI tax before FTC 315, 000 Foreign tax credit - Residual US tax 315, 000 5, 000, 0 - 00 Properly allocable deductions Properly allocable CFC taxes paid 2, 000, 0 - 00 Tested income/(loss) Net tested income - 3, 000 QBAI (note, if tested loss above, no QBAI for the loss CFC) - Aggregate QBAI - Deemed tangible return - Specified interest expense - Net deemed tangible return - GILTI inclusion amount 3, 000, 00 0 19 cWorking with the GILTI. pptx 74
Proposed GILTI High-Tax Exception (cont) • Effective upon publication of final regulations; thus, no GILTI high-tax exception retroactively. 19 cWorking with the GILTI. pptx 75
ILLUSTRATION OF BASIC GILTI PROVISIONS 19 cWorking with the GILTI. pptx 76
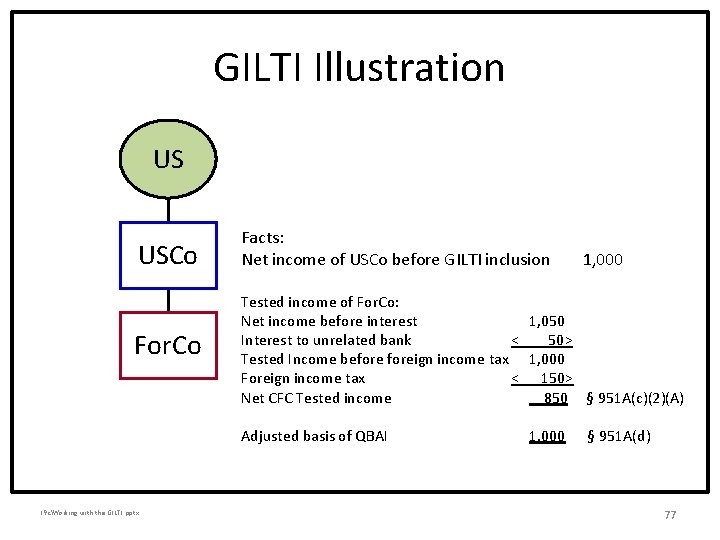
GILTI Illustration US USCo Facts: Net income of USCo before GILTI inclusion 1, 000 For. Co Tested income of For. Co: Net income before interest 1, 050 Interest to unrelated bank < 50> Tested Income beforeign income tax 1, 000 Foreign income tax < 150> Net CFC Tested income 850 § 951 A(c)(2)(A) Adjusted basis of QBAI 19 cWorking with the GILTI. pptx 1, 000 § 951 A(d) 77
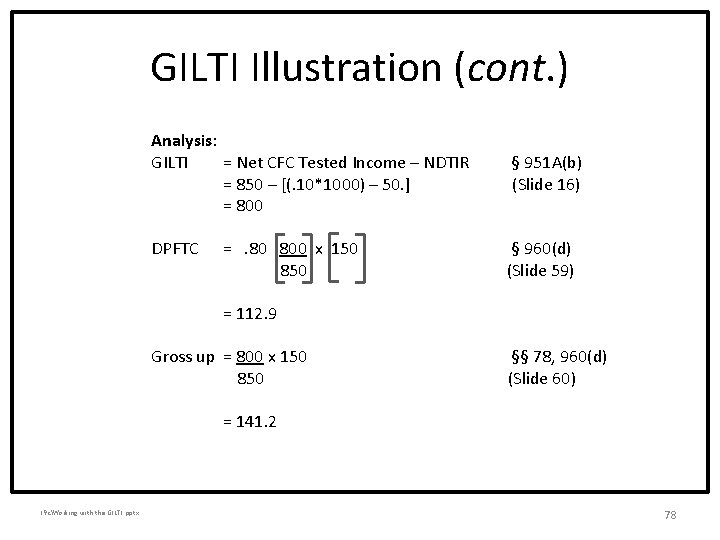
GILTI Illustration (cont. ) Analysis: GILTI = Net CFC Tested Income – NDTIR § 951 A(b) = 850 – [(. 10*1000) – 50. ] (Slide 16) = 800 DPFTC = . 80 800 x 150 § 960(d) 850 (Slide 59) = 112. 9 Gross up = 800 x 150 §§ 78, 960(d) 850 (Slide 60) = 141. 2 19 cWorking with the GILTI. pptx 78
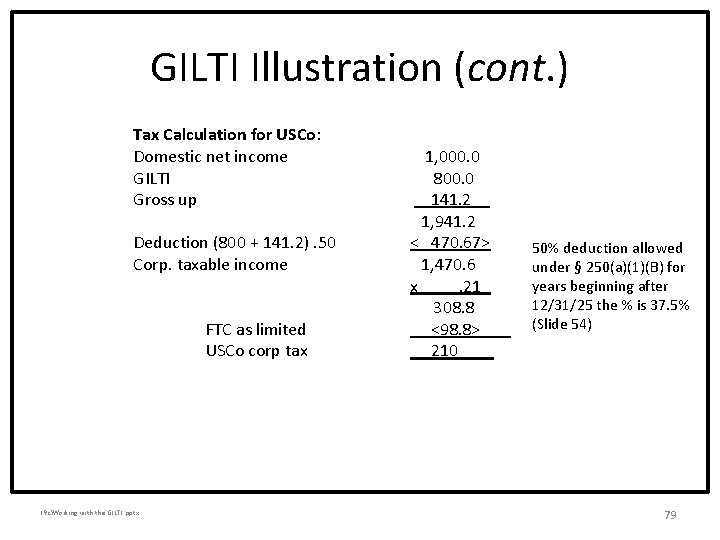
GILTI Illustration (cont. ) Tax Calculation for USCo: Domestic net income GILTI Gross up 1, 000. 0 800. 0 141. 2__ 1, 941. 2 Deduction (800 + 141. 2). 50 < 470. 67> Corp. taxable income 1, 470. 6 x . 21_ 308. 8 FTC as limited <98. 8>__ USCo corp tax 210 19 cWorking with the GILTI. pptx 50% deduction allowed under § 250(a)(1)(B) for years beginning after 12/31/25 the % is 37. 5% (Slide 54) 79
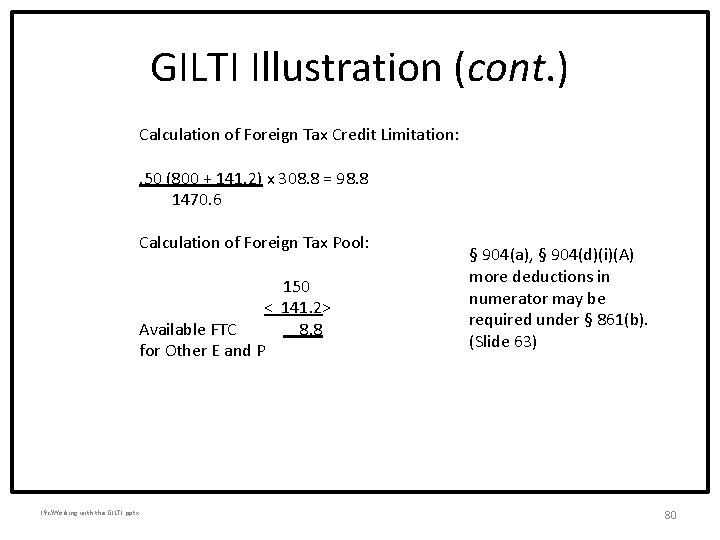
GILTI Illustration (cont. ) Calculation of Foreign Tax Credit Limitation: . 50 (800 + 141. 2) x 308. 8 = 98. 8 1470. 6 Calculation of Foreign Tax Pool: 150 < 141. 2> Available FTC 8. 8 for Other E and P 19 cWorking with the GILTI. pptx § 904(a), § 904(d)(i)(A) more deductions in numerator may be required under § 861(b). (Slide 63) 80
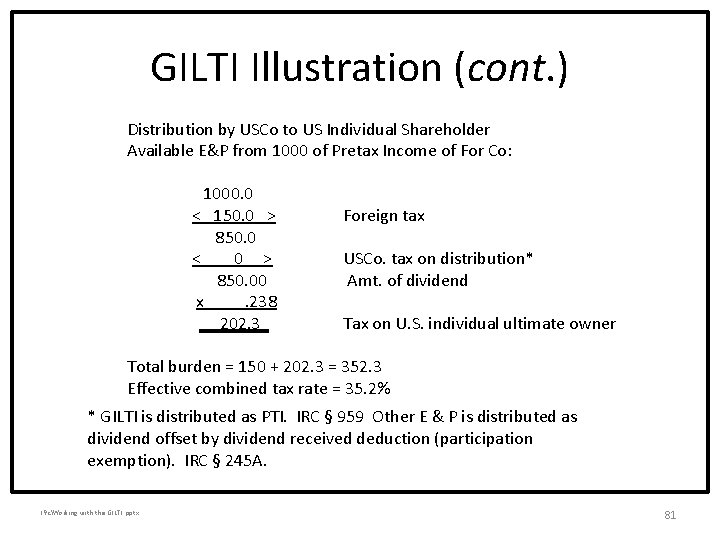
GILTI Illustration (cont. ) Distribution by USCo to US Individual Shareholder Available E&P from 1000 of Pretax Income of For Co: 1000. 0 < 150. 0 > 850. 0 < 0 > 850. 00 x . 238 202. 3 Foreign tax USCo. tax on distribution* Amt. of dividend Tax on U. S. individual ultimate owner Total burden = 150 + 202. 3 = 352. 3 Effective combined tax rate = 35. 2% * GILTI is distributed as PTI. IRC § 959 Other E & P is distributed as dividend offset by dividend received deduction (participation exemption). IRC § 245 A. 19 cWorking with the GILTI. pptx 81
Illustration of FDII, GILTI Subpart F Income and Interrelated Deductions C: WORK19 aFDII Deduction-May 1, 2019. pptx 82
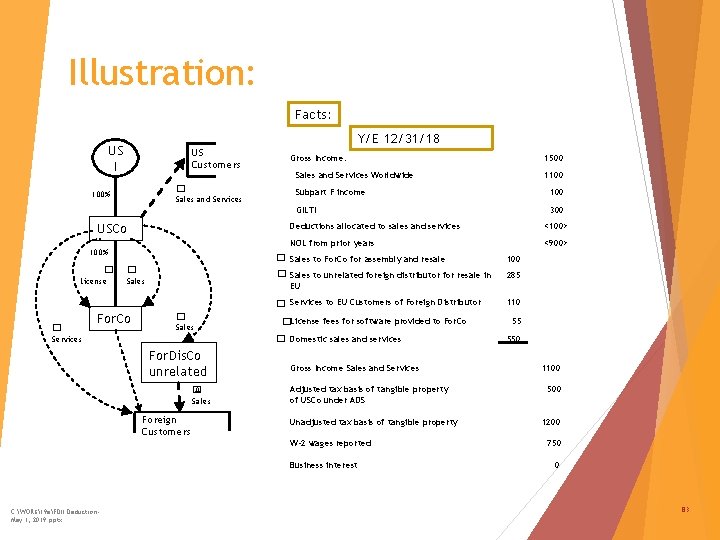
Illustration: Facts: US I US Customers � 100% Sales and Services USCo 100% � License Y/E 12/31/18 Gross Income: Sales and Services Worldwide Sales 100 GILTI 300 Deductions allocated to sales and services <100> NOL from prior years <900> For. Co � Sales �License fees for software provided to For. Co � Domestic sales and services Services For. Dis. Co unrelated � A Sales Foreign Customers Gross Income Sales and Services Adjusted tax basis of tangible property of USCo under ADS Unadjusted tax basis of tangible property W-2 wages reported Business interest C: WORK19 aFDII Deduction. May 1, 2019. pptx 100 285 EU � Services to EU Customers of Foreign Distributor � 1100 Subpart F income � Sales to For. Co for assembly and resale � Sales to unrelated foreign distributor for resale in � 1500 110 55 550 1100 500 1200 750 0 83
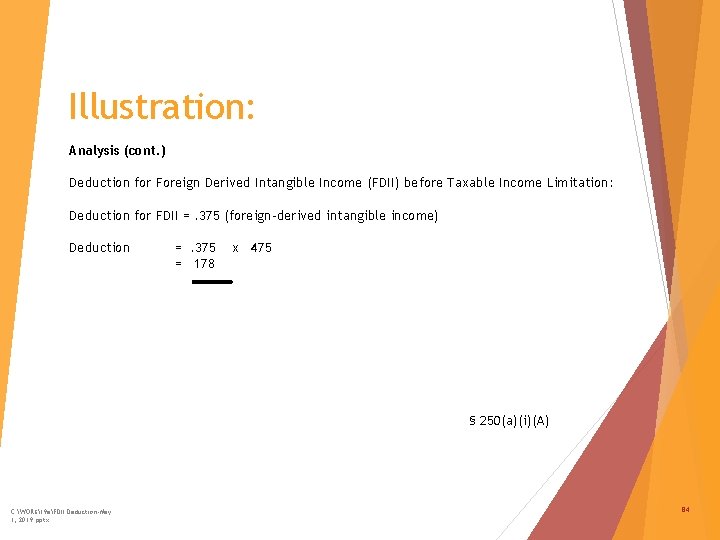
Illustration: Analysis (cont. ) Deduction for Foreign Derived Intangible Income (FDII) before Taxable Income Limitation: Deduction for FDII =. 375 (foreign-derived intangible income) Deduction =. 375 = 178 x 475 § 250(a)(i)(A) C: WORK19 aFDII Deduction-May 1, 2019. pptx 84
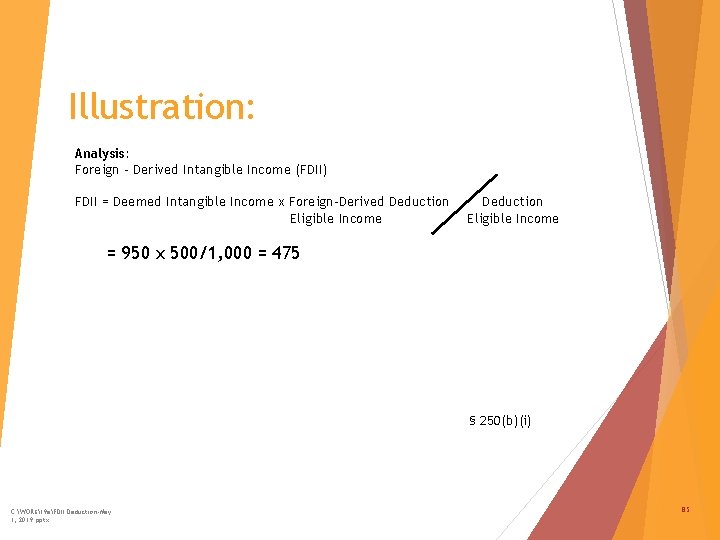
Illustration: Analysis: Foreign – Derived Intangible Income (FDII) FDII = Deemed Intangible Income x Foreign-Derived Deduction Eligible Income = 950 x 500/1, 000 = 475 § 250(b)(i) C: WORK19 aFDII Deduction-May 1, 2019. pptx 85
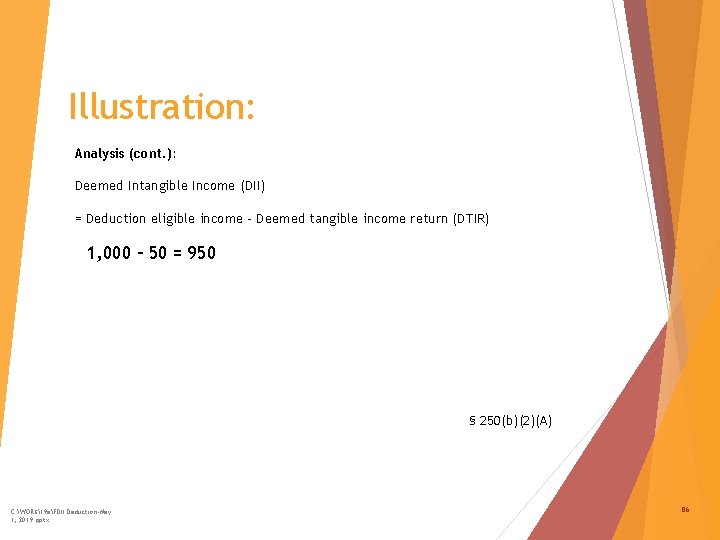
Illustration: Analysis (cont. ): Deemed Intangible Income (DII) = Deduction eligible income – Deemed tangible income return (DTIR) 1, 000 – 50 = 950 § 250(b)(2)(A) C: WORK19 aFDII Deduction-May 1, 2019. pptx 86
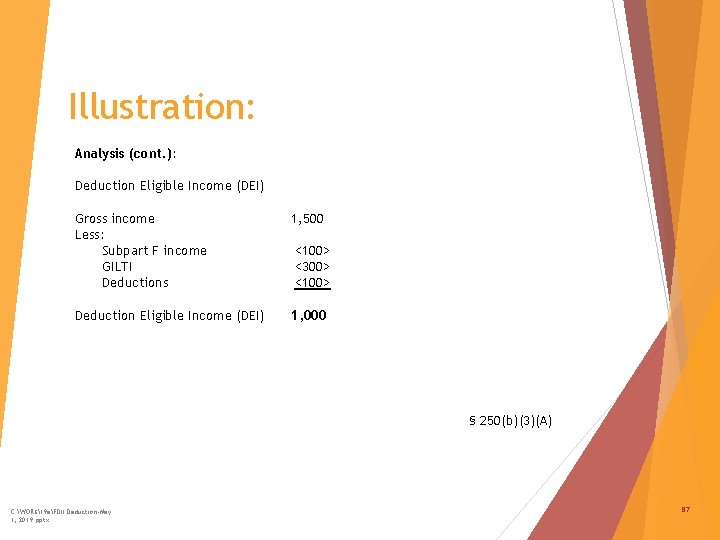
Illustration: Analysis (cont. ): Deduction Eligible Income (DEI) Gross income Less: Subpart F income GILTI Deductions 1, 500 Deduction Eligible Income (DEI) 1, 000 <100> <300> <100> § 250(b)(3)(A) C: WORK19 aFDII Deduction-May 1, 2019. pptx 87
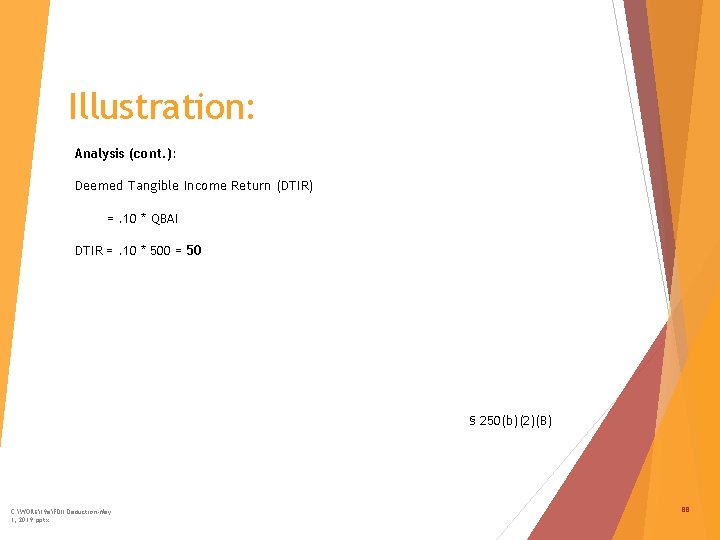
Illustration: Analysis (cont. ): Deemed Tangible Income Return (DTIR) =. 10 * QBAI DTIR =. 10 * 500 = 50 § 250(b)(2)(B) C: WORK19 aFDII Deduction-May 1, 2019. pptx 88
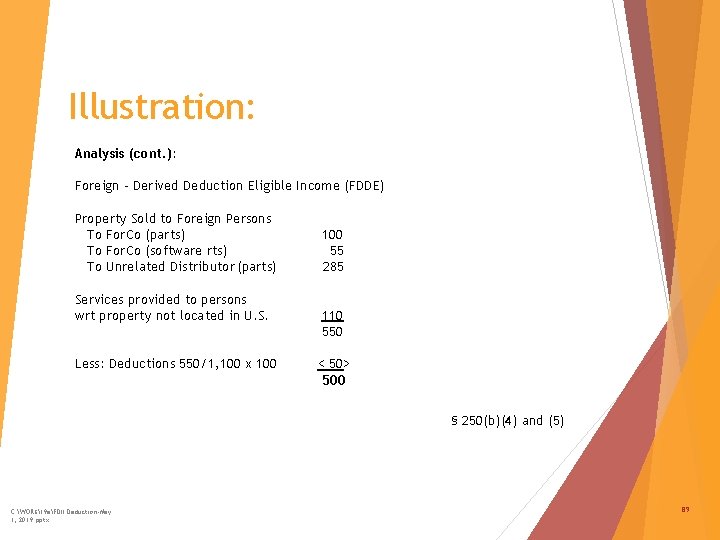
Illustration: Analysis (cont. ): Foreign – Derived Deduction Eligible Income (FDDE) Property Sold to Foreign Persons To For. Co (parts) To For. Co (software rts) To Unrelated Distributor (parts) Services provided to persons wrt property not located in U. S. Less: Deductions 550/1, 100 x 100 55 285 110 550 < 50> 500 § 250(b)(4) and (5) C: WORK19 aFDII Deduction-May 1, 2019. pptx 89
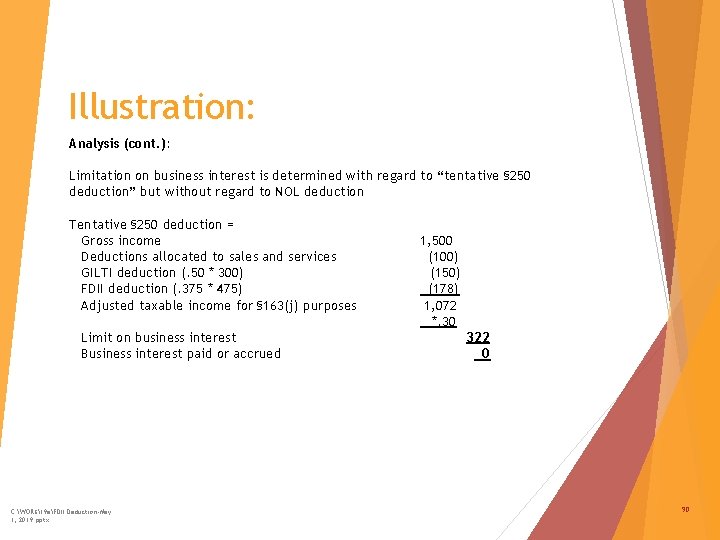
Illustration: Analysis (cont. ): Limitation on business interest is determined with regard to “tentative § 250 deduction” but without regard to NOL deduction Tentative § 250 deduction = Gross income Deductions allocated to sales and services GILTI deduction (. 50 * 300) FDII deduction (. 375 * 475) Adjusted taxable income for § 163(j) purposes Limit on business interest Business interest paid or accrued C: WORK19 aFDII Deduction-May 1, 2019. pptx 1, 500 (100) (150) (178) 1, 072 *. 30 322 0 90
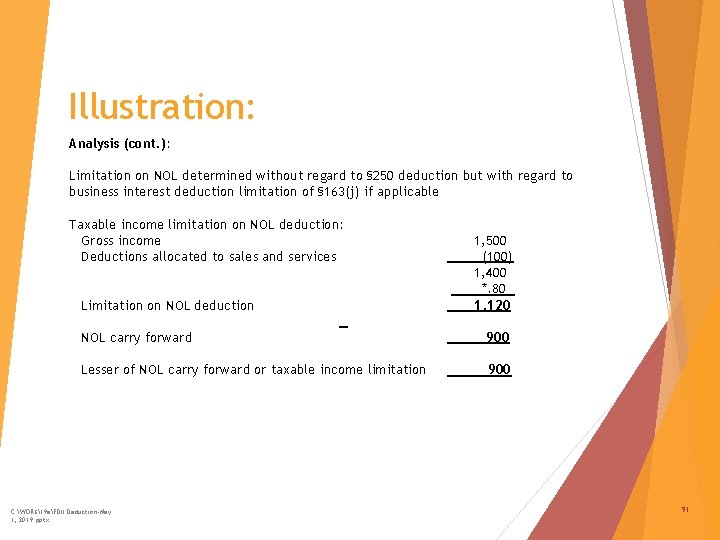
Illustration: Analysis (cont. ): Limitation on NOL determined without regard to § 250 deduction but with regard to business interest deduction limitation of § 163(j) if applicable Taxable income limitation on NOL deduction: Gross income Deductions allocated to sales and services Limitation on NOL deduction 1, 500 (100) 1, 400 *. 80 1, 120 NOL carry forward 900 Lesser of NOL carry forward or taxable income limitation 900 C: WORK19 aFDII Deduction-May 1, 2019. pptx 91
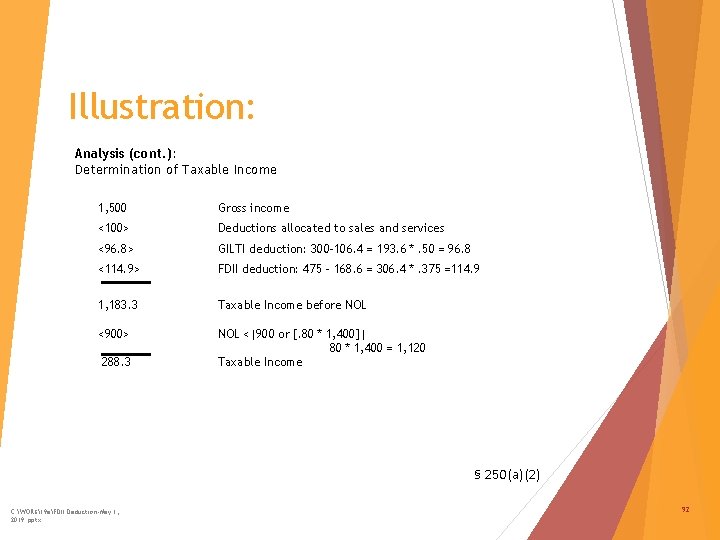
Illustration: Analysis (cont. ): Determination of Taxable Income 1, 500 Gross income <100> Deductions allocated to sales and services <96. 8> GILTI deduction: 300 -106. 4 = 193. 6 *. 50 = 96. 8 <114. 9> FDII deduction: 475 – 168. 6 = 306. 4 *. 375 =114. 9 1, 183. 3 Taxable Income before NOL <900> NOL <|900 or [. 80 * 1, 400]| 80 * 1, 400 = 1, 120 Taxable Income 288. 3 § 250(a)(2) C: WORK19 aFDII Deduction-May 1, 2019. pptx 92
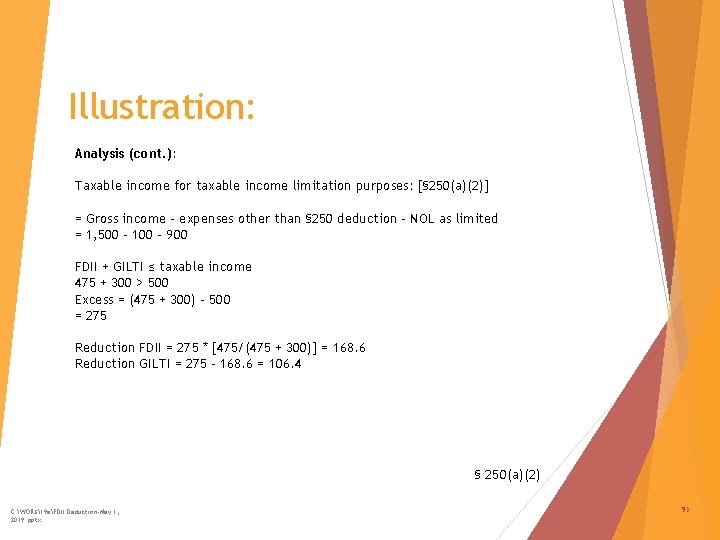
Illustration: Analysis (cont. ): Taxable income for taxable income limitation purposes: [§ 250(a)(2)] = Gross income – expenses other than § 250 deduction – NOL as limited = 1, 500 - 100 – 900 FDII + GILTI ≤ taxable income 475 + 300 > 500 Excess = (475 + 300) – 500 = 275 Reduction FDII = 275 * [475/(475 + 300)] = 168. 6 Reduction GILTI = 275 – 168. 6 = 106. 4 § 250(a)(2) C: WORK19 aFDII Deduction-May 1, 2019. pptx 93
Practical Tax Planning Under the 2017 ACT: Impact of International Provisions Illustrated by Simple Examples of Business Structures 19 cWorking with the GILTI. pptx 94
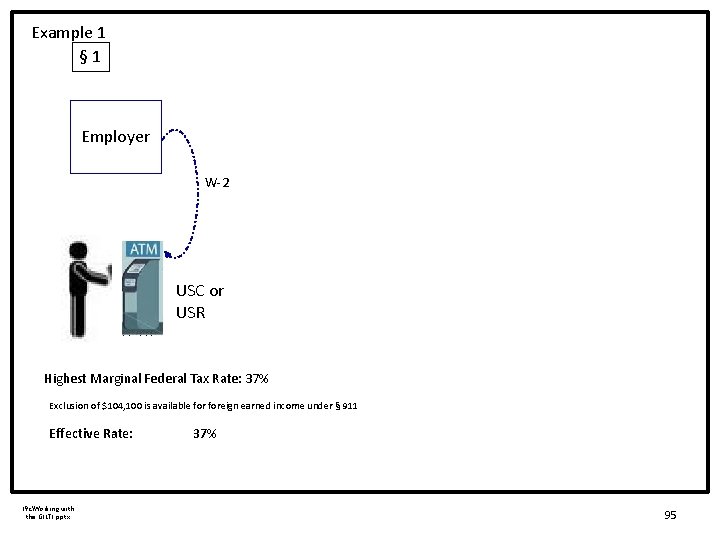
Example 1 § 1 Employer W-2 USC or USR Highest Marginal Federal Tax Rate: 37% Exclusion of $104, 100 is available foreign earned income under § 911 Effective Rate: 19 cWorking with the GILTI. pptx 37% 95
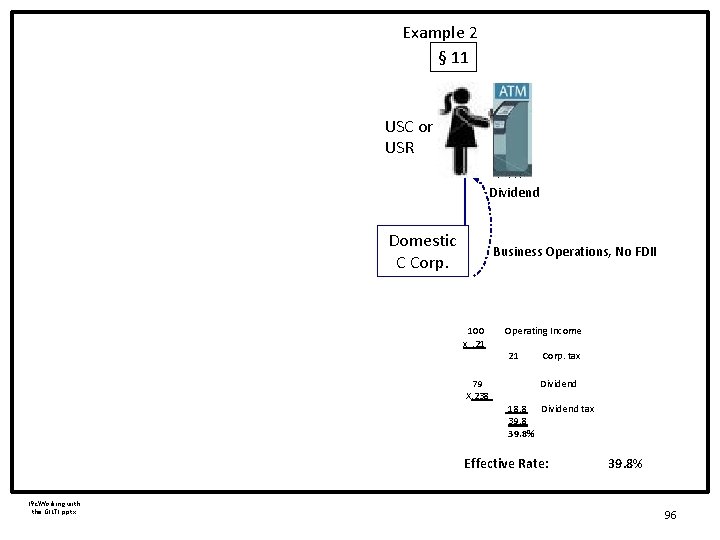
Example 2 § 11 USC or USR Dividend Domestic C Corp. Business Operations, No FDII 100 Operating Income x . 21 Corp. tax 79 Dividend X. 238 18. 8 Dividend tax 39. 8% Effective Rate: 19 cWorking with the GILTI. pptx 39. 8% 96
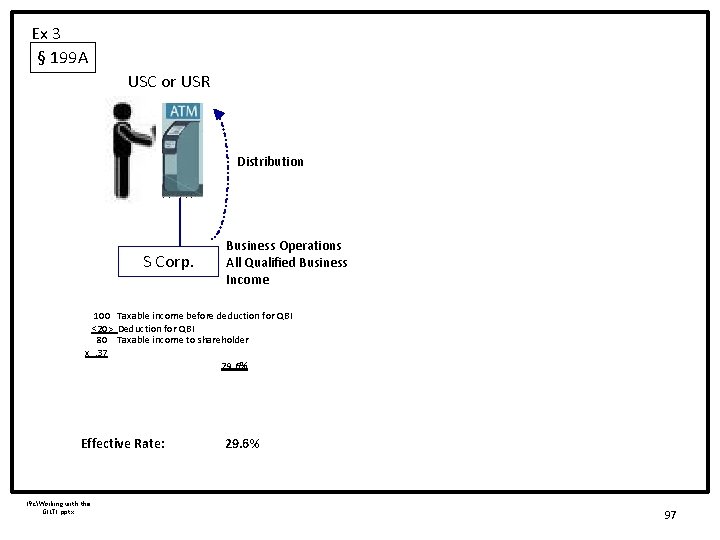
Ex 3 § 199 A USC or USR Distribution S Corp. Business Operations All Qualified Business Income 100 Taxable income before deduction for QBI <20> Deduction for QBI 80 Taxable income to shareholder x . 37 29. 6% Effective Rate: 19 cWorking with the GILTI. pptx 29. 6% 97
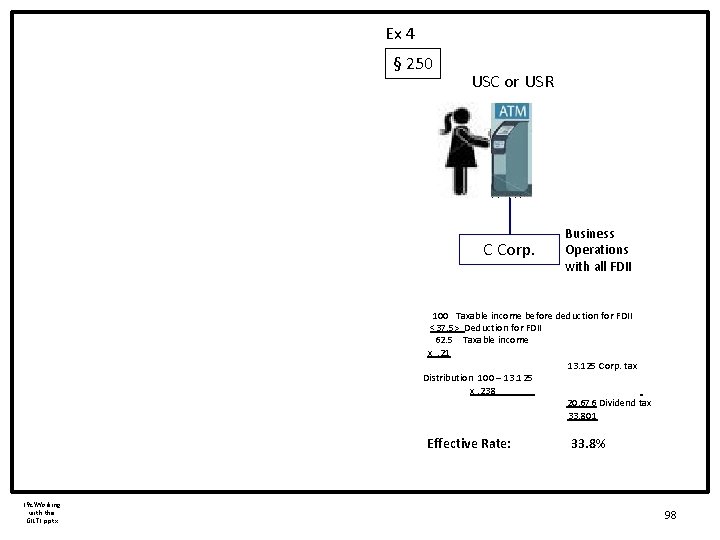
Ex 4 § 250 USC or USR C Corp. Business Operations with all FDII 100 Taxable income before deduction for FDII <37. 5> Deduction for FDII 62. 5 Taxable income x . 21 13. 125 Corp. tax Distribution 100 – 13. 125 x. 238 20. 676 Dividend tax 33. 801 Effective Rate: 19 cWorking with the GILTI. pptx 33. 8% 98
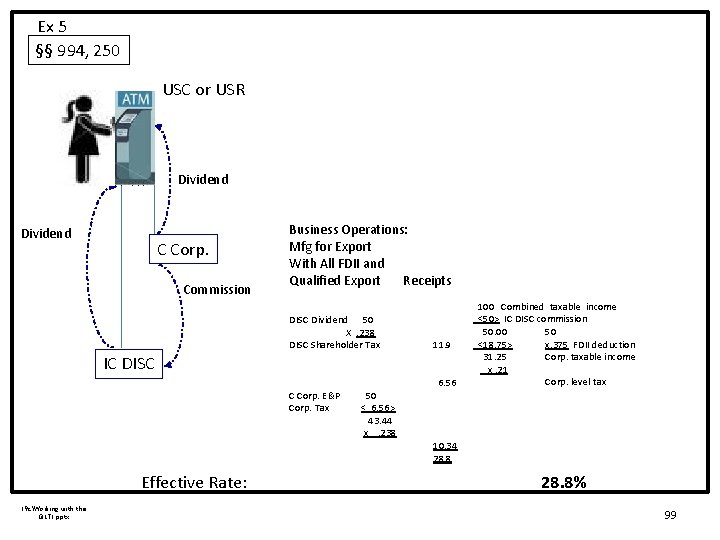
Ex 5 §§ 994, 250 USC or USR Dividend C Corp. Commission Business Operations: Mfg for Export With All FDII and Qualified Export Receipts DISC Dividend 50 X . 238 DISC Shareholder Tax 11. 9 IC DISC C Corp. E&P Corp. Tax Effective Rate: 19 cWorking with the GILTI. pptx 50 < 6. 56> 43. 44 x . 238 6. 56 100 Combined taxable income <50> IC DISC commission 50. 00 50 <18. 75> x. 375 FDII deduction 31. 25 Corp. taxable income x. 21 Corp. level tax 10. 34 28. 8% 99
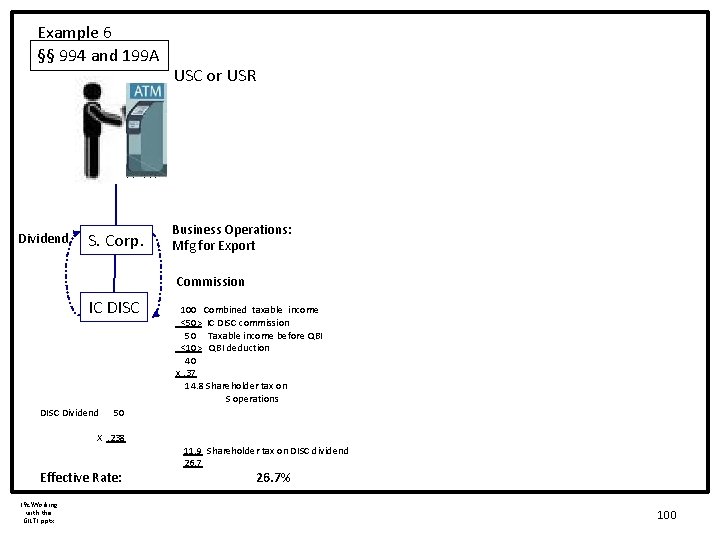
Example 6 §§ 994 and 199 A Dividend S. Corp. USC or USR Business Operations: Mfg for Export Commission IC DISC 100 Combined taxable income <50> IC DISC commission 50 Taxable income before QBI <10> QBI deduction 40 x. 37 14. 8 Shareholder tax on S operations DISC Dividend 50 X . 238 Effective Rate: 19 cWorking with the GILTI. pptx 11. 9 Shareholder tax on DISC dividend 26. 7% 100
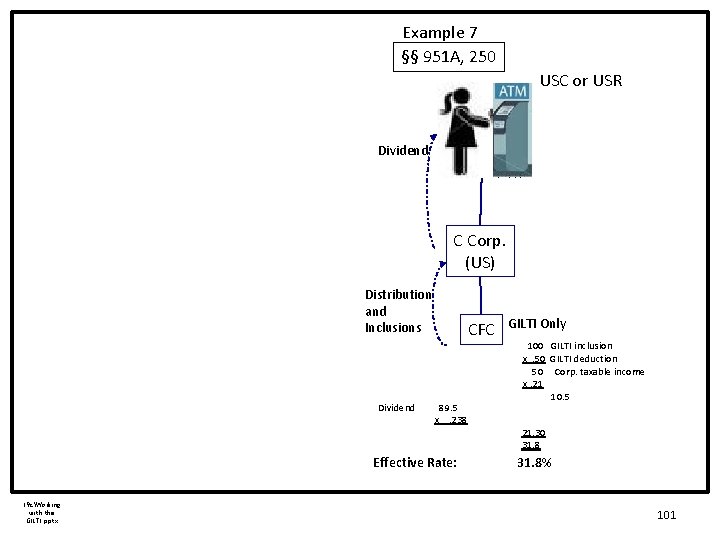
Example 7 §§ 951 A, 250 USC or USR Dividend C Corp. (US) Distribution and Inclusions Dividend 89. 5 x . 238 Effective Rate: 19 cWorking with the GILTI. pptx CFC GILTI Only 100 GILTI inclusion x . 50 GILTI deduction 50 Corp. taxable income x. 21 10. 5 21. 30 31. 8% 101
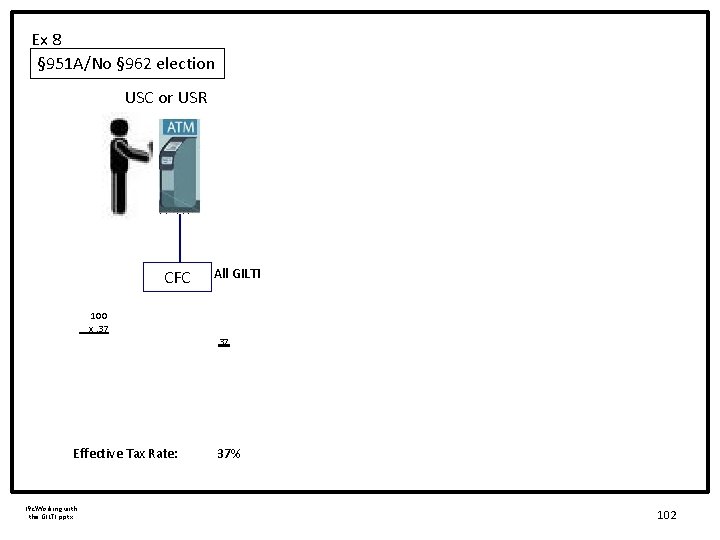
Ex 8 § 951 A/No § 962 election USC or USR CFC 100 x. 37 All GILTI 37 Effective Tax Rate: 19 cWorking with the GILTI. pptx 37% 102
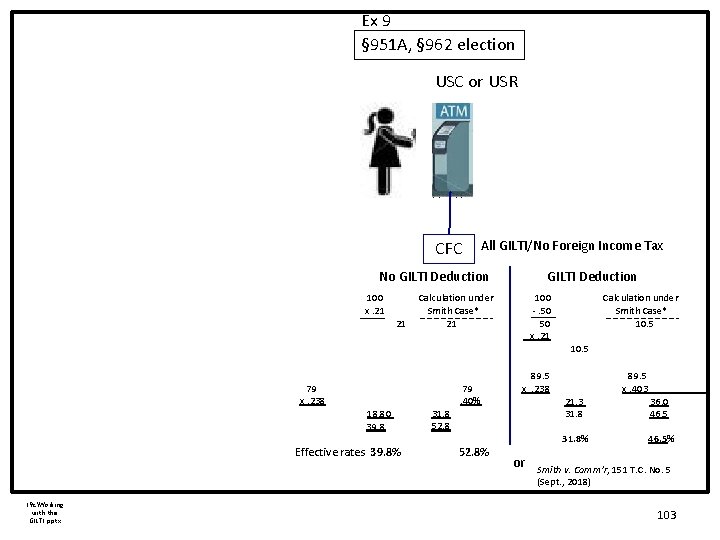
Ex 9 § 951 A, § 962 election USC or USR CFC All GILTI/No Foreign Income Tax No GILTI Deduction 100 Calculation under x. 21 Smith Case* 21 79 x. 238 79 . 40% 31. 8 18. 80 52. 8 39. 8 Effective rates 39. 8% 19 cWorking with the GILTI. pptx 52. 8% GILTI Deduction 100 Calculation under -. 50 Smith Case* 50 10. 5 x. 21 10. 5 89. 5 89. 5 x . 238 x. 403 21. 3 36. 0 31. 8 46. 5 31. 8% or 46. 5% Smith v. Comm’r, 151 T. C. No. 5 (Sept. , 2018) 103
Section 962 Election for GILTI 19 cWorking with the GILTI. pptx 104
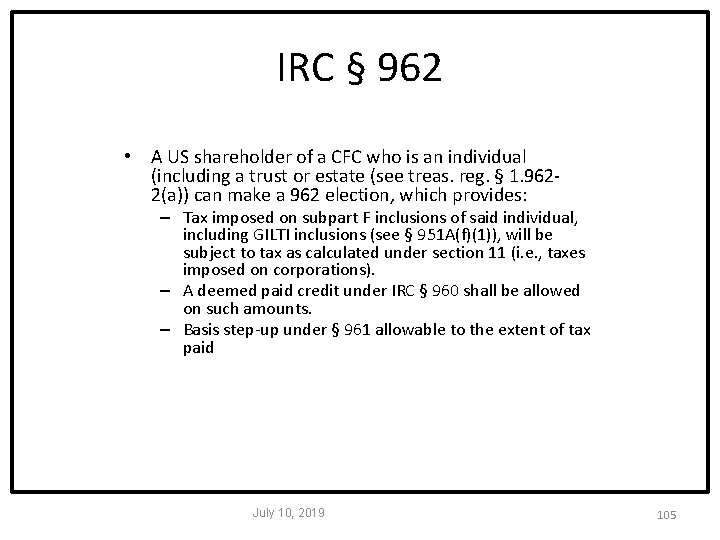
IRC § 962 • A US shareholder of a CFC who is an individual (including a trust or estate (see treas. reg. § 1. 9622(a)) can make a 962 election, which provides: – Tax imposed on subpart F inclusions of said individual, including GILTI inclusions (see § 951 A(f)(1)), will be subject to tax as calculated under section 11 (i. e. , taxes imposed on corporations). – A deemed paid credit under IRC § 960 shall be allowed on such amounts. – Basis step-up under § 961 allowable to the extent of tax paid July 10, 2019 105
IRC § 962 – Legislative History (S. Rep. No. 1881, 87 th Cong. , 2 d Sess. (1962)) • “The purpose of this provision is to avoid what might otherwise be a hardship in taxing a U. S. individual at high bracket rates with respect to earnings in a foreign corporation which he does not receive. This provision gives such individuals assurance that their tax burdens, with respect to these undistributed foreign earnings, will be no heavier than they would have been had they invested in an American corporation doing business abroad. ” July 10, 2019 106
IRC § 962 – Application • Application of section 11 for inclusions subject to a 962 election (treas. reg. § 1. 962 -1(b)(1)): – Section 11 is limited under 962 and the above cited regulation. Specifically, for 962 purposes, “taxable income” means the sum of: • The amounts required to be included in gross income as traditional subpart F income and GILTI; plus • The section 78 “gross-up” with respect to those amounts. – “such sum shall not be reduced by any deduction of the United States shareholder even if such shareholder’s deductions exceed his gross income” • “Taxable Income” under Section 11 refers to section 63, which provides taxable income means gross income minus allowable deductions July 10, 2019 107
IRC § 962 – Foreign Tax Credit (Treas. Reg. § 1. 962 -1(b)(2) • Allowance of foreign tax credit: – There shall be allowed a foreign tax credit under § 960(a)(1) for amounts which are the subject of a § 962 election (subject to the applicable limitation of § 904) • To the extent the foreign tax credit exceeds the § 904 limitation, the excess can be carried back or carried forward, except can only offset other income for which a 962 election is in place July 10, 2019 108
IRC § 962 – Treatment of Actual Distributions (IRC § 962(d); Treas. Reg. § 1. 962 -3 • § 962 E&P less Excludable § 962 E&P are included in gross income – § 962 E&P = the E&P of a foreign corporation that were included in the gross income of a the taxpayer under § 951(a) in a prior year and for which a § 962 election is in effect; includes Excludable § 962 E&P and Taxable § 962 E&P – Excludable § 962 E&P = the amount of income tax paid by the taxpayer with respect to the § 962 election in the prior year – Taxable § 962 E&P = the excess over Excludable § 962 E&P. • Source of distributions: – § 962 E&P generally is distributed after regular PTI • Excludable § 962 E&P is distributed first and then Taxable § 962 E&P July 10, 2019 109
IRC § 962 – Procedure (Treas. Reg. § 1. 962 -2) • • Only individuals, trusts or estates may make the election. Election made by filing a statement with taxpayer’s return: – Name, address, and taxable year of each CFC with respect to which the electing shareholder is a US shareholder and all other corporations, partnerships, trusts, or estates in any applicable chain of ownership described in § 958(a) – The amounts, on a corporation-by-corporation basis, which are included in such shareholder’s gross income for his taxable year under § 951(a) – Taxpayer’s pro rata share of E&P of such CFC with respect to which the taxpayer as an inclusion under § 951(a) and the foreign taxes with respect to such E&P – The amount of distributions received by the taxpayer from each CFC which are (1) excludable § 962 E&P; (2) taxable § 962 E&P; and (3) E&P other than § 962 E&P, showing the source of such amounts by taxable year • Effect of election – A § 962 election when made is applicable to all CFCs owned by the taxpayer and is binding for the taxable year for which the election is made – An election may be revoked with the approval of the Commissioner. Approval will not be granted unless a material and substantial change in circumstances occurs which could not have been anticipated. July 10, 2019 110
IRC § 962 – Recent Developments • Can individuals who own CFC through an S corporation or partnership make a § 962 election? • Availability of § 250 Deduction for GILTI Inclusions • Are subsequent distributions qualified dividends if distributed from a foreign corporation not located in a treaty jurisdiction? July 10, 2019 111
Availability of Section 250 Deduction • Prop. Reg. § 1. 962 -1(b)(1)(i)(B)(3) provides that individuals making § 962 election eligible for § 250 deduction. Allowable deductions include: – (3) The portion of the deduction under section 250 and § 1. 250(a)-1 that would be allowed to a domestic corporation equal to the percentage applicable to global intangible low-taxed income for the taxable year under section 250(a)(1)(B) (including as modified by section 250(a)(3)(B)) multiplied by the sum of the amount described in paragraph (b)(1)(i)(A)(2) of this section and the amount described in paragraph (b)(1)(i)(A)(3) of this section that is attributable to the amount described in paragraph (b)(1)(i)(A)(2) of this section. July 10, 2019 112
ILLUSTRATION WITH TREATY COUNTRY 19 cWorking with the GILTI. pptx 113
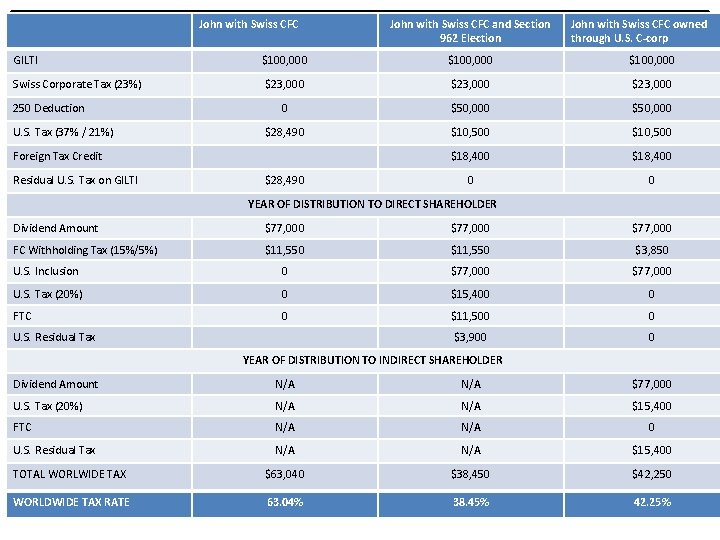
John with Swiss CFC and Section 962 Election John with Swiss CFC owned through U. S. C-corp GILTI $100, 000 Swiss Corporate Tax (23%) $23, 000 0 $50, 000 $28, 490 $10, 500 $18, 400 $28, 490 0 0 250 Deduction U. S. Tax (37% / 21%) Foreign Tax Credit Residual U. S. Tax on GILTI YEAR OF DISTRIBUTION TO DIRECT SHAREHOLDER Dividend Amount $77, 000 FC Withholding Tax (15%/5%) $11, 550 $3, 850 U. S. Inclusion 0 $77, 000 U. S. Tax (20%) 0 $15, 400 0 FTC 0 $11, 500 0 $3, 900 0 U. S. Residual Tax YEAR OF DISTRIBUTION TO INDIRECT SHAREHOLDER Dividend Amount N/A $77, 000 U. S. Tax (20%) N/A $15, 400 FTC N/A 0 U. S. Residual Tax N/A $15, 400 TOTAL WORLWIDE TAX $63, 040 $38, 450 $42, 250 WORLDWIDE TAX RATE 63. 04% 38. 45% 42. 25% 114 19 cWorking with the GILTI. pptx
ILLUSTRATION WITH NON TREATY COUNTRY 19 cWorking with the GILTI. pptx 115
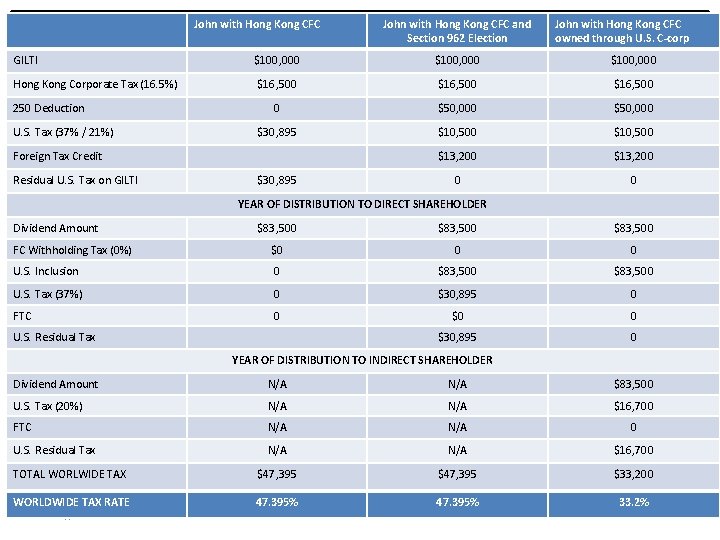
John with Hong Kong CFC and Section 962 Election John with Hong Kong CFC owned through U. S. C-corp GILTI $100, 000 Hong Kong Corporate Tax (16. 5%) $16, 500 0 $50, 000 $30, 895 $10, 500 $13, 200 $30, 895 0 0 250 Deduction U. S. Tax (37% / 21%) Foreign Tax Credit Residual U. S. Tax on GILTI YEAR OF DISTRIBUTION TO DIRECT SHAREHOLDER Dividend Amount $83, 500 FC Withholding Tax (0%) $0 0 0 U. S. Inclusion 0 $83, 500 U. S. Tax (37%) 0 $30, 895 0 FTC 0 $0 0 $30, 895 0 U. S. Residual Tax YEAR OF DISTRIBUTION TO INDIRECT SHAREHOLDER Dividend Amount N/A $83, 500 U. S. Tax (20%) N/A $16, 700 FTC N/A 0 U. S. Residual Tax N/A $16, 700 TOTAL WORLWIDE TAX $47, 395 $33, 200 WORLDWIDE TAX RATE 19 cWorking with the 47. 395% 33. 2% GILTI. pptx 116
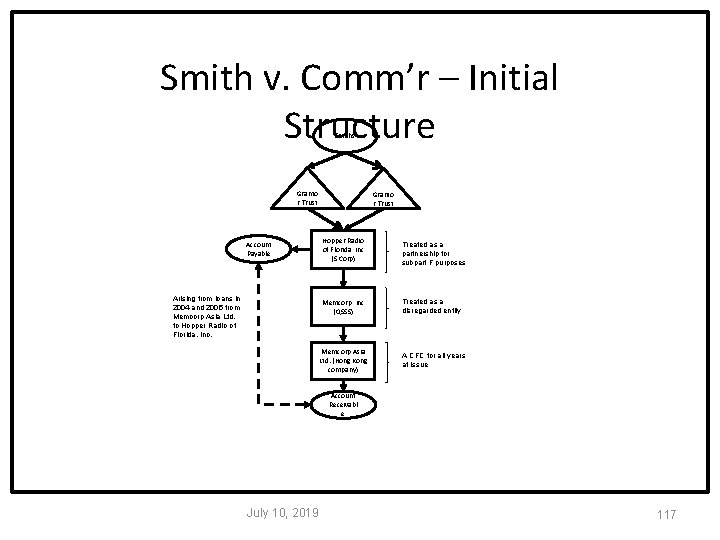
Smith v. Comm’r – Initial Structure Smiths Granto r Trust Account Payable Arising from loans in 2004 and 2005 from Memcorp Asia Ltd. to Hopper Radio of Florida, Inc. Granto r Trust Hopper Radio of Florida, Inc (S Corp) Memcorp, Inc (QSSS) Memcorp Asia Ltd. (Hong Kong company) Treated as a partnership for subpart F purposes Treated as a disregarded entity A CFC for all years at issue Account Receivabl e July 10, 2019 117
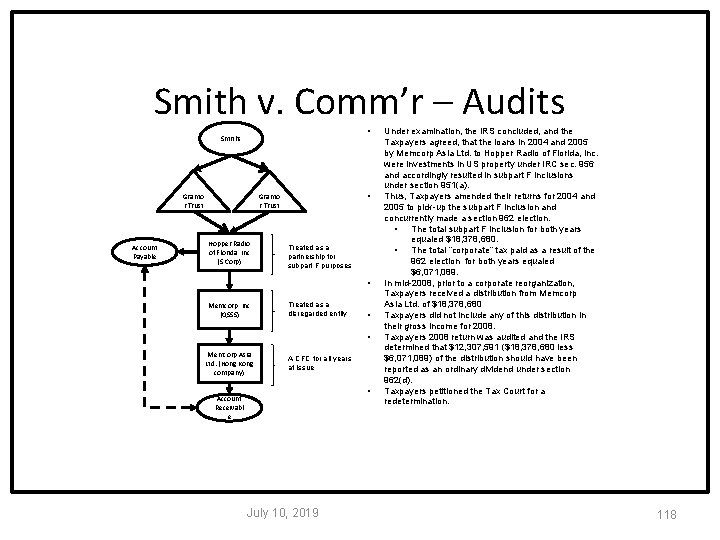
Smith v. Comm’r – Audits • Smiths Granto r Trust Account Payable • Granto r Trust Hopper Radio of Florida, Inc (S Corp) Treated as a partnership for subpart F purposes • Memcorp, Inc (QSSS) Treated as a disregarded entity • • Memcorp Asia Ltd. (Hong Kong company) A CFC for all years at issue • Account Receivabl e July 10, 2019 Under examination, the IRS concluded, and the Taxpayers agreed, that the loans in 2004 and 2005 by Memcorp Asia Ltd. to Hopper Radio of Florida, Inc. were investments in US property under IRC sec. 956 and accordingly resulted in subpart F inclusions under section 951(a). Thus, Taxpayers amended their returns for 2004 and 2005 to pick-up the subpart F inclusion and concurrently made a section 962 election. • The total subpart F inclusion for both years equaled $18, 378, 680. • The total “corporate” tax paid as a result of the 962 election for both years equaled $6, 071, 089. In mid-2008, prior to a corporate reorganization, Taxpayers received a distribution from Memcorp Asia Ltd. of $18, 378, 680 Taxpayers did not include any of this distribution in their gross income for 2008. Taxpayers 2008 return was audited and the IRS determined that $12, 307, 591 ($18, 378, 680 less $6, 071, 089) of the distribution should have been reported as an ordinary dividend under section 962(d). Taxpayers petitioned the Tax Court for a redetermination. 118
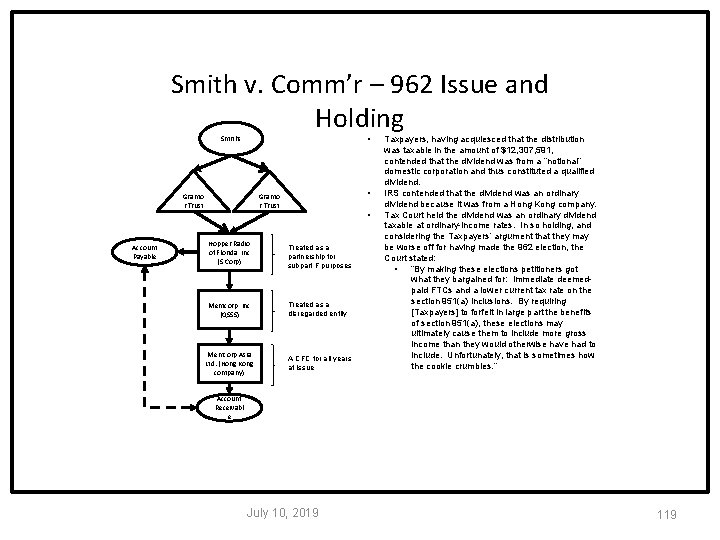
Smith v. Comm’r – 962 Issue and Holding • Smiths Granto r Trust Account Payable • Granto r Trust Hopper Radio of Florida, Inc (S Corp) Memcorp, Inc (QSSS) Memcorp Asia Ltd. (Hong Kong company) • Treated as a partnership for subpart F purposes Treated as a disregarded entity A CFC for all years at issue Taxpayers, having acquiesced that the distribution was taxable in the amount of $12, 307, 591, contended that the dividend was from a “notional” domestic corporation and thus constituted a qualified dividend. IRS contended that the dividend was an ordinary dividend because it was from a Hong Kong company. Tax Court held the dividend was an ordinary dividend taxable at ordinary-income rates. In so holding, and considering the Taxpayers’ argument that they may be worse off for having made the 962 election, the Court stated: • “By making these elections petitioners got what they bargained for: immediate deemedpaid FTCs and a lower current tax rate on the section 951(a) inclusions. By requiring [Taxpayers] to forfeit in large part the benefits of section 951(a), these elections may ultimately cause them to include more gross income than they would otherwise have had to include. Unfortunately, that is sometimes how the cookie crumbles. ” Account Receivabl e July 10, 2019 119
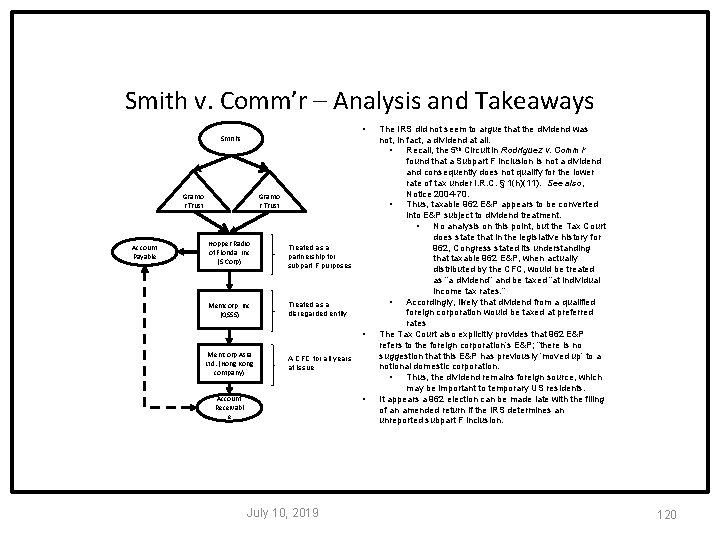
Smith v. Comm’r – Analysis and Takeaways • Smiths Granto r Trust Account Payable Granto r Trust Hopper Radio of Florida, Inc (S Corp) Memcorp, Inc (QSSS) Treated as a partnership for subpart F purposes Treated as a disregarded entity • Memcorp Asia Ltd. (Hong Kong company) A CFC for all years at issue • Account Receivabl e July 10, 2019 The IRS did not seem to argue that the dividend was not, in fact, a dividend at all. • Recall, the 5 th Circuit in Rodriguez v. Comm’r found that a Subpart F inclusion is not a dividend and consequently does not qualify for the lower rate of tax under I. R. C. § 1(h)(11). See also, Notice 2004 -70. • Thus, taxable 962 E&P appears to be converted into E&P subject to dividend treatment. • No analysis on this point, but the Tax Court does state that in the legislative history for 962, Congress stated its understanding that taxable 962 E&P, when actually distributed by the CFC, would be treated as “a dividend” and be taxed “at individual income tax rates. ” • Accordingly, likely that dividend from a qualified foreign corporation would be taxed at preferred rates The Tax Court also explicitly provides that 962 E&P refers to the foreign corporation’s E&P; “there is no suggestion that this E&P has previously ‘moved up’ to a notional domestic corporation. • Thus, the dividend remains foreign source, which may be important to temporary US residents. It appears a 962 election can be made late with the filing of an amended return if the IRS determines an unreported subpart F inclusion. 120
- Slides: 120