
INTERNAL AUDIT OF CONSTRUCTION INDUSTRY K K RAO
- Slides: 29
INTERNAL AUDIT OF CONSTRUCTION INDUSTRY K. K RAO M. Com, LLB. , FCMA, MIMA, FCS
v Building and Other Construction Workers Act, 1996 - Applicable if 10 or more construction workers, or Construction cost exceeds 10 lakhs (Excluding land cost) v Contract Labour Act , 1970 - Applicable if Establishment /Contractor employs 20 or more labours v Employees Compensation Act , 1923 v Employees Provident Funds and Misc. provisions Act, 1952 v Fatal Accidents Act, 1855 v Minimum Wages Act, 1948 v Employees Liability Act, 1938 v Payment of Bonus Act, 1965 v Public Liability Insurance Act , 1991 K. K. RAO & ASSOCIATES
LEGAL & REGULATORY FRAMEWORK: v Unorganized Workers Social Security Act, 2008 v Equal remuneration Act, 1976 -Payment of Equal pay for equal work for both man and woman v Maternity benefit Act, 1961 - Regulates employment of woman before and after the child birth v Child labour (Prohibition and Regulation) Act, 1986 v Environment (Protection) Act, 1986 v Trade Unions Act, 1926 v Stamp duty and Registration K. K. RAO & ASSOCIATES
INTERNAL AUDIT v Internal Audit is continuous and systematic Process of examining and reporting the operation and records of a concern by its employees or external agencies specially assigned for this purpose v Internal audit is to provide independent assurance that an organisation's risk management, governance and internal control processes are operating effectively v To provide reasonable assurance to the relevant audit committee K. K. RAO & ASSOCIATES
Internal Auditor has to look at : v Assessing the management of risk v Assisting management in the improvement of internal controls v Activities of Internal Audit v Evaluating controls and advising managers at all levels v Working with other assurance providers v Analyzing operations and Confirm Information v Evaluating risks K. K. RAO & ASSOCIATES
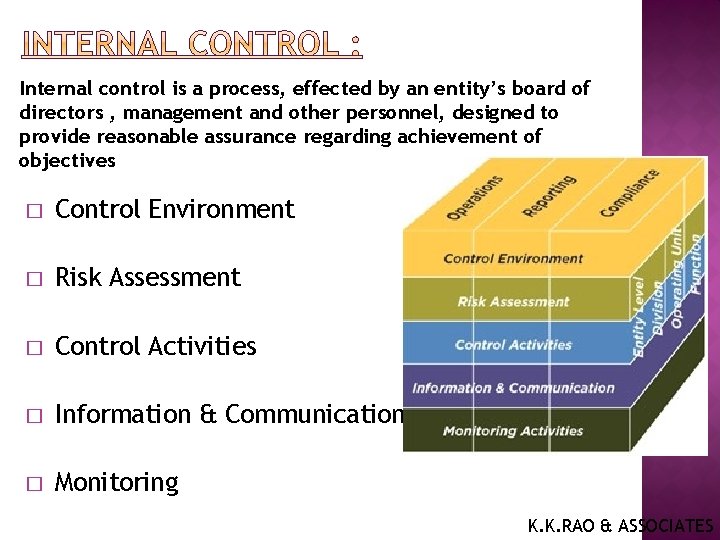
Internal control is a process, effected by an entity’s board of directors , management and other personnel, designed to provide reasonable assurance regarding achievement of objectives � Control Environment � Risk Assessment � Control Activities � Information & Communication � Monitoring K. K. RAO & ASSOCIATES
Risk Assessment : Risk Assessment is a process by which an auditor Identifies and evaluates the Quantity of the Organization risk and Quality of its controls over those risks v Assessment typically analyze INHERENT RISK of business/process v Assessment should reflect changes to the system of Internal Control v Considering thematic control issues, risk tolerance v Qualitative & Quantitative factors of event occurring v Inclusion of overall auditable entity score v Supported with written analysis of risks v summary risk assessment provided to audit committee K. K. RAO & ASSOCIATES
Value addition to Organization ü Multi-disciplinary skill set ü Organizational alignment ü Data supported insight & analysis ü Improve management processes the effectiveness risk , control and governance K. K. RAO & ASSOCIATES
Scope of Internal Audit : Verification of fixed asset register and periodic updation Purchase of materials & equipment in terms of a) Invitation of quotations b) Evaluation of quotations c) Selection of vendors d) Receipt of goods & issue procedures Payment process including handling, safe custody of cash & cheques in terms of a) Physical verification of cash b) Safe custody of cash & blank cheques c) Verification of vouchers & their approvals d) Review of Advances e) Review of bank reconciliation statements K. K. RAO & ASSOCIATES
Scope of Internal Audit (Contd): q Evaluation of procedures adopted for awarding contracts a) Invitation of Tenders b) Evaluation of Tenders received c) Selection of the contractor q Reporting on compliance of provisions of Companies Act, 2013 in respect of a) Authorised , Subscribed & Paid-up capital b) Unsecured loans c) Loans & advances d) Board meetings & resolutions e) Filing returns as per legal provisions q Scrutiny of statutory compliances like TDS, Advance tax, Service tax, VAT, Works contract tax. K. K. RAO & ASSOCIATES
Scope of Internal Audit (Contd): q Scrutiny of internal control procedures at project site in respect of a) Record maintenance for receipt & issue of materials b) Storing arrangements for unutilized inventory c) Proper utilization & safe guarding of Assets d) Certification of project work in progress e) Accounting procedures & reporting to head office f) Proper accounting payments including classification q Verification of Interest during construction q Accounting of loan transactions q. Maintaining reasonableness of internal financial controls K. K. RAO & ASSOCIATES
Accounting standards v AS – 7 (Construction contracts) v AS – 9 (Revenue recognition) K. K. RAO & ASSOCIATES
Accounting standards : AS- 7 � Rendering of services directly related to construction of asset � Cost and revenue is recognized only when outcome of contract is measured reliably � AS-9 � Recognition of revenue arising in the course of ordinary activities � Incase of uncertainty recognition is postponed. Expected losses should recognize as an expense for the contract K. K. RAO & ASSOCIATES
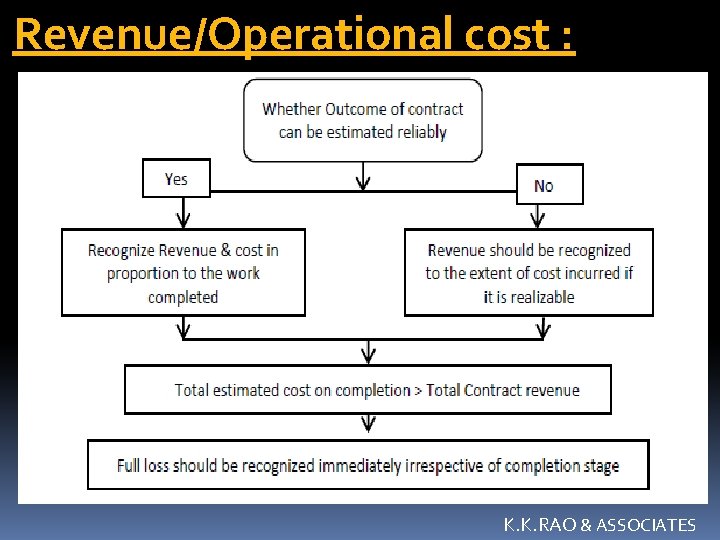
Revenue/Operational cost : K. K. RAO & ASSOCIATES
OPERATING REVENUE : Ø Revenue from land, plots and constructed properties. Ø Revenue from development charges. Ø Revenue from development rights (net). Ø Revenue from power generation. Ø Rental income. Ø Maintenance or other Service receipts. Ø Amount forfeited on properties. Ø Revenue from other activities of the Company. K. K. RAO & ASSOCIATES
REASONS OF UNEXPECTED COST : �Design development changes. �Schedule adjustments. �General administration changes (such as wage rates). �Differing site conditions for those expected. �Third party requirements imposed during construction. � Natural Calamities K. K. RAO & ASSOCIATES
Project cost allocation : Specific identification method Relative value method Common Expenses i) Value of cost completed to date. ii) Management discretion. iii) Incremental cost during the year. iv) Capital employed for each project (for interest). Or a combination of above. K. K. RAO & ASSOCIATES
Application of percentage completion method: Where to apply � The duration of such project is beyond 12 months. � Most features of the projects are common to the construction contract. � The construction activities form a significant proportion of the project activity. Conditions to Apply � Total project revenue can be estimated reliably. � The probable economic benefits associated with the project will flow to the enterprises. � The cost to complete the project and cost up to stage of completion at the reporting date can be estimated reliably. � The project cost attributable to the project can be identified and measured reliably for the purpose of comparison with prior estimates. � All the approvals required for commencement of the project activity have been obtained. K. K. RAO & ASSOCIATES
Construction project 1) Public Private Partnership (PPP) models : Model 2) Real Estate Development Model 3) EPC Contracting Model PPP Projects Operation on the basis of v BOO ‐ Build Own Operate v BOLT ‐ Build Own Lease Transfer v BOOST ‐ Build Own Operate Share Transfer v BOT‐ Build, Operate and Transfer v BOOT‐ Build, Own, Operate and Transfer v BOLT ‐ Build Own Lease Transfer v BLOT‐ Build, Lease, Operate and Transfer v DBFO ‐ Design Build Finance Operate v DBFOT‐ Design, Build, Finance, Operate and Transfer v OMT ‐ Operate Maintain Transfer K. K. RAO & ASSOCIAT
Construction project models (Contd) : Real Estate Development Model : This Includes development of land construction/ development of everything that is permanently attached to the land & It also Covers i) Green field development (Traditional model) ii) Redevelopment model EPC Model : EPC model is Engineering, Procurement and Construction Contracts finalized based on Technical and Commercial bidding process. It covers i) LSTK‐ Lump Sum Turnkey contracts ii) Cost plus contracts iii) Item Rate Contract iv) A Combination of above K. K. RAO & ASSOCIAT
POTENTIAL CAUSES OF INEFFICIENCIES : ü Poor quality of planning and engineering design ü Inappropriate contracts in use ü Pre-tendering approval process is slow and centralized ü Land acquisition problems ü Weak dispute resolution practices ü Weak performance management ü Non-availability or paucity of skilled and semi-skilled workers ü Weak risk management skills ü Lack of best-in-class procurement practices ü Low prevalence of lean construction principles K. K. RAO & ASSOCIATES
Overcoming Inefficiencies : q Board Of Directors and Senior management Oversight q Risk Identification and Assessment q Role Accountability and Responsibility q Improvising Policies and Procedures q Internal controls q Self monitoring and Remediation q Internal Audits framework q Proper Utilization of resources K. K. RAO & ASSOCIATES
Compliance means ensuring conformity and adherence to regulatory acts, rules, procedures, laws , regulations Standard on Internal Audit 17 relating to “Consideration of Laws and Regulations in an Internal Audit” K. K. RAO & ASSOCIATES
� ü ü ü To Industry Reduction in penalties Increase in Internal control Reduction of frauds & losses ü Increase in efficiency ü Customer satisfaction ü To Stakeholders Ensures risk containment & safe market place ü Better Investor Confidence ü Uniform practices ü Better Image hence better value for Investor � K. K. RAO & ASSOCIATES
� cost over run � Time over run � Technological � Environmental � Political � Social changes & Legal changes K. K. RAO & ASSOCIATES
INTERNAL AUDIT RELATED ISSUES Not getting land with in stipulated time Paying heavy Compensation to land owner Religious & Sentimental matters relating to localstemple, masjid, church Purchase of materials without invoices/unauthorized sellers Not paying royalty- sand/bricks Not adhering to standards of construction K. K. RAO & ASSOCIATES
INTERNAL AUDIT RELATED ISSUES(CONTD) v. Illegal payments to Government and tax authorities v. Political contributions v. Disaster management v Risk assessment , management and mitigation plans v Non servicing of Interest to the lenders and deposit holders v Detection of fraud v Diversion of funds v Over statement of inventory v Default in contractors payment v Insurance v Legal cases v Expiry of warranty , lease and Insurance K. K. RAO & ASSOCIAT
Questions K. K. RAO & ASSOCIATES
-K. K RAO & ASSOCIATES 2 -B, SAMRAT RESIDENTIAL COMPLEX SAIFABAD, HYDERABAD Ph: 9849269020 Website: www. kkraoassociates. com E-mail: kkrao. associates@gmail. com kkrao 2008@gmail. com