
Intermediate Financial Accounting Statement of Cash Flows by
Intermediate Financial Accounting Statement of Cash Flows by Professor Hsieh
Objectives of this Chapter I. Identify business activities which can generate or use cash and differentiate between income flows and cash flows from operating activities. II. Introduce the content and the usefulness of the statement of cash flows. Statement of Cash Flows 2
Objectives of this Chapter (contd. ) III. Understand cash flows of operating, investing and financing activities. IV. Learn how to prepare the statement of cash flows. V. Learn the two alternatives (direct and indirect methods) in preparing net cash flows from operating activities. Statement of Cash Flows 3
I. Activities which can either generate cash or use cash for a business entity A. Operating activities. B. Investing activities. C. Financing activities. Statement of Cash Flows 4
A. Operating Activities (i. e. , sales revenue, expenses) n n All these activities are reported in the I/S (income statement). However, I/S only provides the net income amount which very often is not the change in cash. Therefore, we need to adjust from net income flows to cash flows in order to report the net cash provided by (or used in) operating activities. Statement of Cash Flows 5
A. Operating Activities (contd. ) n There are two approaches to reconcile net income to net cash provided by (or used in) operating activities: 1. Indirect Method ==> Lump-Sum Adjustment 2. Direct Method ==> Individual Account Adjustment Statement of Cash Flows 6
1. Indirect Method n Adjust net income (the lump sum amount of all revenues and expenses) for all differences between income flows and cash flows. Statement of Cash Flows 7
2. Direct Method n Adjust each revenue account to cash collection and adjust each expense account to cash payment. Subtract total cash payments from total cash collections to derive net cash flows of the operation activities. Statement of Cash Flows 8
Activities which can either generate cash or use cash for a business entity A. Operating activities. B. Investing activities. C. Financing activities. Statement of Cash Flows 9
B. Investing Activities n n In addition to generate cash from or use cash in the operating activities, companies can also generate cash from (or use cash in) investing activities. i. e. , Acquiring (cash outflow) or selling (cash inflow): u PPE u Investments (current or noncurrent) u N/R (current or noncurrent) Statement of Cash Flows 10
Activities which can either generate cash or use cash for a business entity A. Operating activities. B. Investing activities. C. Financing activities. Statement of Cash Flows 11
C. Financing Activities n Companies can also generate cash or use cash through financing activities: Statement of Cash Flows 12
1. Cash Inflows Financing Activities u Issue B/P. u Issue common stock. u Issue N/P. Statement of Cash Flows 13
Financing Activities 2. Cash Outflows u Retirement of B/P. u Retirement of common stock. u Retirement of N/P. u Payments of dividends. Statement of Cash Flows 14
II. The Content and the Usefulness of the Statement of Cash Flows n In order to show cash flows of a company, cash flows of all three activities should be reported. In doing so, investors can also obtain all the information of operating, investing, and financing activities of a company. Moreover, the following questions can also be answered: Statement of Cash Flows 15
The Content and the Usefulness of the Statement of Cash Flows (contd. ) 1. What is the relationship between net income and cash provided by operations? 2. Why did cash decreased when net income increased? 3. What expansion (investment) activities took place and how were they financed? Statement of Cash Flows 16
The Content and the Usefulness of the Statement of Cash Flows (contd. ) 4. How much is the cash provided by operating activities? 5. What happened to the proceeds received from issuance of bonds or common stock? All of these cannot be answered from either the income statement or the balance sheet statement. Statement of Cash Flows 17
APB Opinion No. 19 n In 1971 APB Opinion No. 19, “Reporting Changes in Financial Position”, requires a statement of changes in financial position be presented in a company’s set of financial statements. Statement of Cash Flows 18
APB Opinion No. 19 (contd. ) n n APB No. 19 allowed flexibility in defining the financial position(i. e. , Working capital or cash). Disadvantage: lose the comparability among firms when firms adopted different financial position in preparing the statement. Statement of Cash Flows 19
SFAS No. 95 n To improve the comparability, SFAS No. 95, “Statement of Cash Flows, ” requires companies present the statement of cash flows using a specific format. Statement of Cash Flows 20
SFAS No. 95 (contd. ) n Following SFAS No. 95, the statement of cash flows should have three sections: 1. Cash flows from operating activities. 2. Cash flows from investing activities. 3. Cash flows from financing activities. Statement of Cash Flows 21
III. Understand Cash Flows from Operating, Investing, and Financing Activities Cash flows from operating activities: n Cash Inflows: 1. Collections from customers including cash received from sales (or services) and collections of A/R. 2. Cash receipts of interests or dividends. 3. Collections of other operating receipts (i. e. , unearned revenue, rent revenue). Statement of Cash Flows 22
Cash Flows from Operating Activities (contd. ) n Cash Outflows: 1. Payments to suppliers. 2. Payments to employees. 3. Payments for interest expense. 4. Payments for income taxes. 5. Payments for other expenses(i. e. , Prepaid expenses; rent expenses). Statement of Cash Flows 23
Cash Flows from Investing Activities n Transactions involving acquiring ( Investing (Cash outflows)) and selling ( Disinvesting (Cash inflows)) : a. Property, Plant and Equipment. b. Investments (current and non-current). c. Notes Receivable (current and noncurrent). Statement of Cash Flows 24
Notes Receivable n Notes Receivable (current and noncurrent), including: u u u Lending money (N/R , cash outflow); Collecting of loan (N/R , cash inflow); Selling of N/R (N/R , discounting N/R, cash inflow) Statement of Cash Flows 25
Cash Flows from Financing Activities n n Obtaining resources from owners and creditors (cash inflows) and repaying the amount borrowed (cash outflows). Cash inflows: Cash received from issuance of common stock. u Cash received from issuance of bonds. u Cash received from issuance of N/P (short-term or long term). u Statement of Cash Flows 26
Cash Flows from Financing Activities (contd. ) n Cash Outflows: u Retirement of bonds. u Retirement of stock. u Payments of N/P. u Payments of dividends. Statement of Cash Flows 27
IV. Procedures for Preparation of the Statement of Cash Flows 1. Operating Cash Flows (indirect method). 2. Investing Cash Flows. 3. Financing Cash Flows. Statement of Cash Flows 28
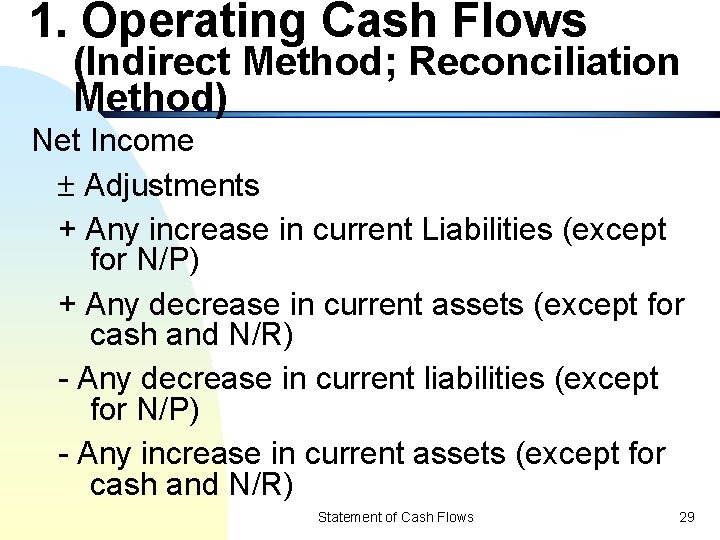
1. Operating Cash Flows (Indirect Method; Reconciliation Method) Net Income Adjustments + Any increase in current Liabilities (except for N/P) + Any decrease in current assets (except for cash and N/R) - Any decrease in current liabilities (except for N/P) - Any increase in current assets (except for cash and N/R) Statement of Cash Flows 29
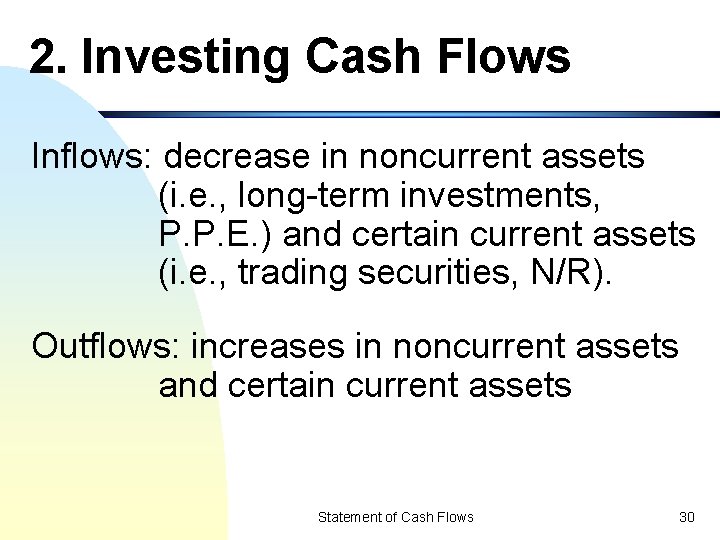
2. Investing Cash Flows Inflows: decrease in noncurrent assets (i. e. , long-term investments, P. P. E. ) and certain current assets (i. e. , trading securities, N/R). Outflows: increases in noncurrent assets and certain current assets Statement of Cash Flows 30
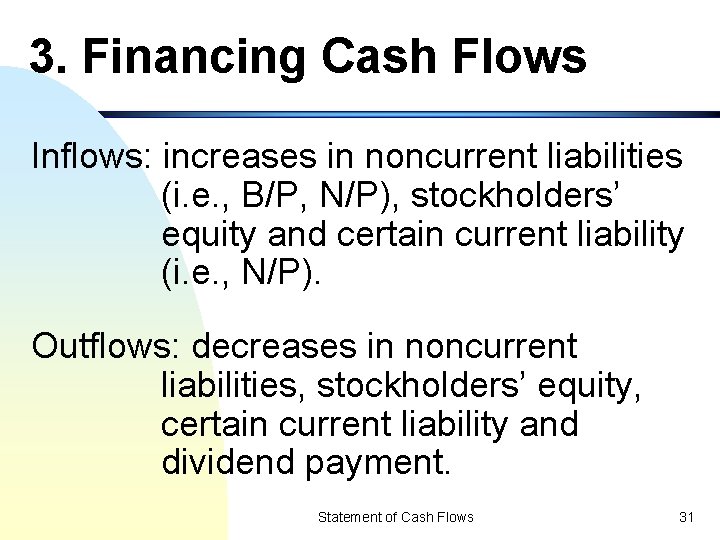
3. Financing Cash Flows Inflows: increases in noncurrent liabilities (i. e. , B/P, N/P), stockholders’ equity and certain current liability (i. e. , N/P). Outflows: decreases in noncurrent liabilities, stockholders’ equity, certain current liability and dividend payment. Statement of Cash Flows 31
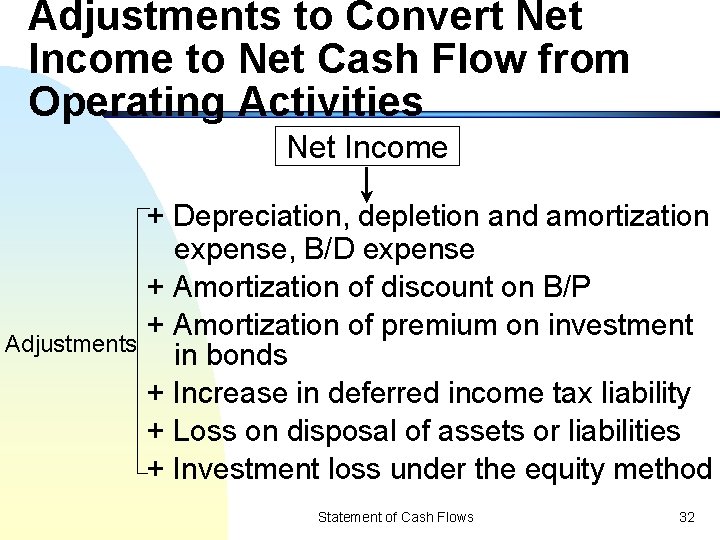
Adjustments to Convert Net Income to Net Cash Flow from Operating Activities Net Income Adjustments + Depreciation, depletion and amortization expense, B/D expense + Amortization of discount on B/P + Amortization of premium on investment in bonds + Increase in deferred income tax liability + Loss on disposal of assets or liabilities + Investment loss under the equity method Statement of Cash Flows 32
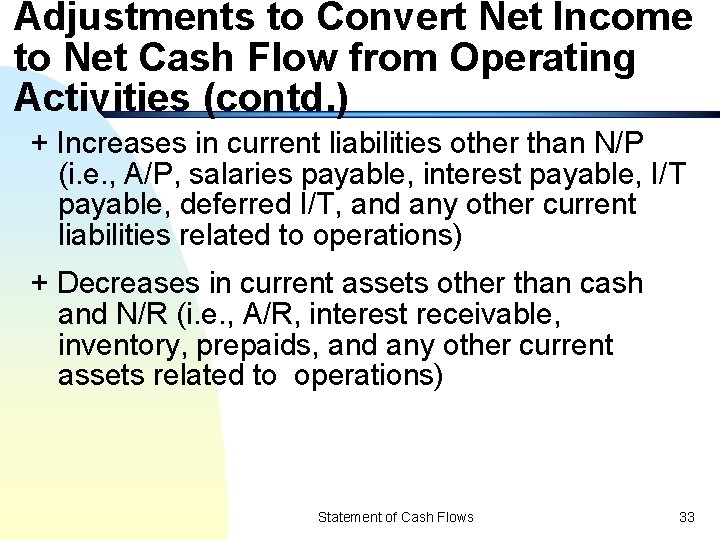
Adjustments to Convert Net Income to Net Cash Flow from Operating Activities (contd. ) + Increases in current liabilities other than N/P (i. e. , A/P, salaries payable, interest payable, I/T payable, deferred I/T, and any other current liabilities related to operations) + Decreases in current assets other than cash and N/R (i. e. , A/R, interest receivable, inventory, prepaids, and any other current assets related to operations) Statement of Cash Flows 33
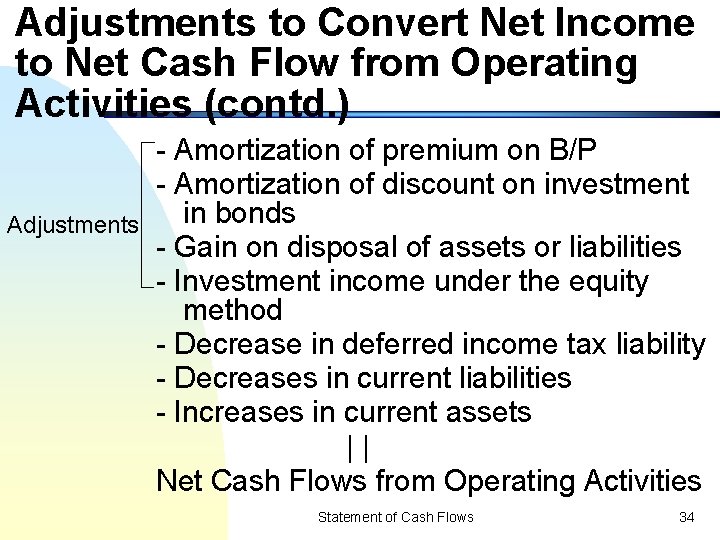
Adjustments to Convert Net Income to Net Cash Flow from Operating Activities (contd. ) Adjustments - Amortization of premium on B/P - Amortization of discount on investment in bonds - Gain on disposal of assets or liabilities - Investment income under the equity method - Decrease in deferred income tax liability - Decreases in current liabilities - Increases in current assets || Net Cash Flows from Operating Activities Statement of Cash Flows 34
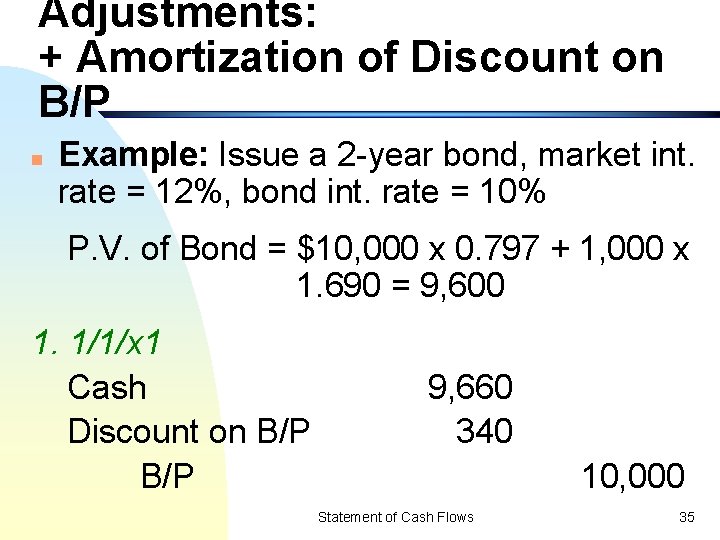
Adjustments: + Amortization of Discount on B/P n Example: Issue a 2 -year bond, market int. rate = 12%, bond int. rate = 10% P. V. of Bond = $10, 000 x 0. 797 + 1, 000 x 1. 690 = 9, 600 1. 1/1/x 1 Cash Discount on B/P 9, 660 340 10, 000 Statement of Cash Flows 35
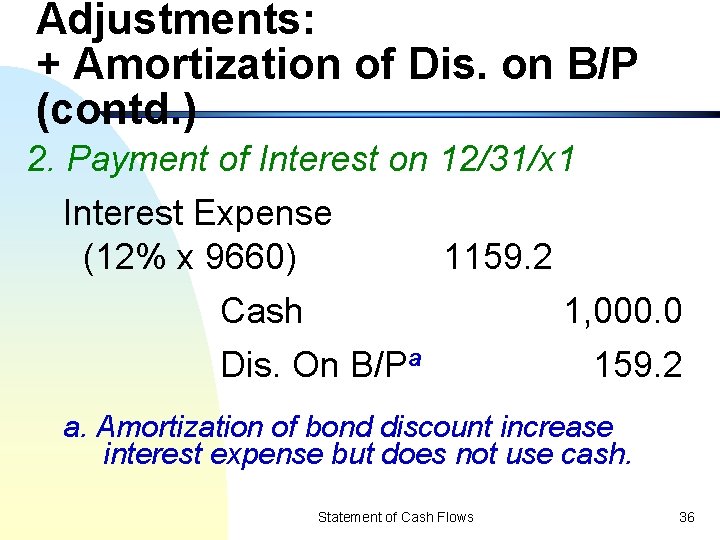
Adjustments: + Amortization of Dis. on B/P (contd. ) 2. Payment of Interest on 12/31/x 1 Interest Expense (12% x 9660) 1159. 2 Cash 1, 000. 0 Dis. On B/Pa 159. 2 a. Amortization of bond discount increase interest expense but does not use cash. Statement of Cash Flows 36
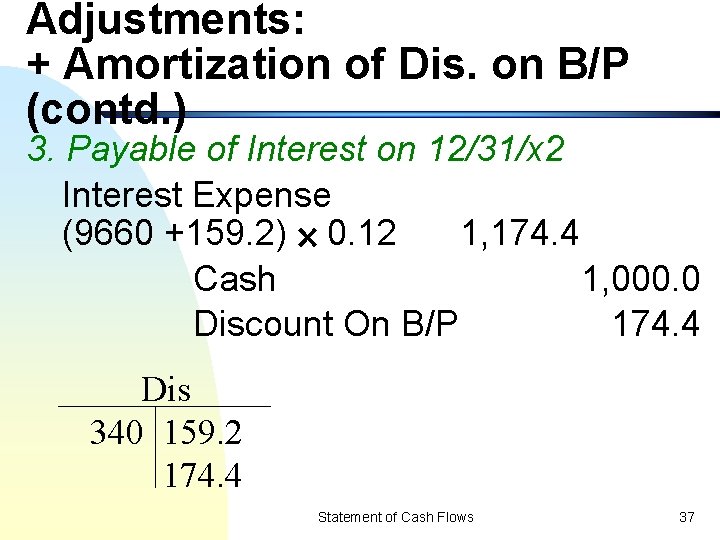
Adjustments: + Amortization of Dis. on B/P (contd. ) 3. Payable of Interest on 12/31/x 2 Interest Expense (9660 +159. 2) 0. 12 1, 174. 4 Cash 1, 000. 0 Discount On B/P 174. 4 Dis 340 159. 2 174. 4 Statement of Cash Flows 37
Adjustments: + Amortization of Premium on Investment in Bonds n Example: GEO Corp. purchased $100, 000, 10% 5 -year bonds on 1/1/x 2, with interest payable on 7/1 and 1/1. The bonds sell for $108, 111 which results in bond premium of $8, 111 and an effective interest rate of 8%. Statement of Cash Flows 38
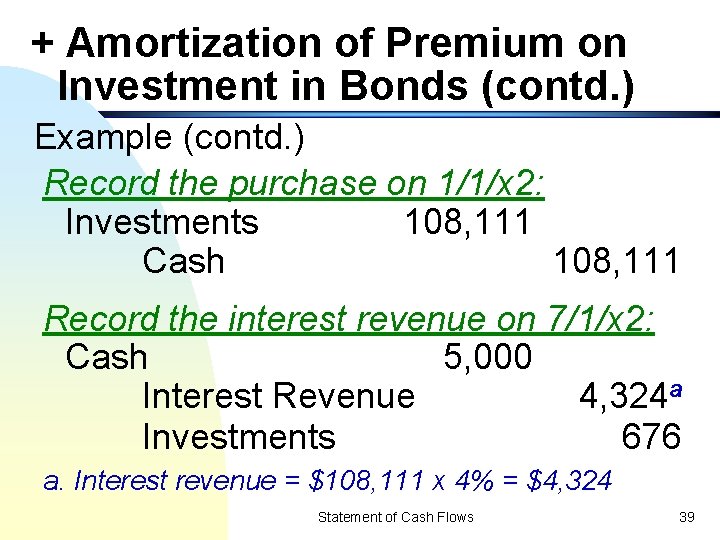
+ Amortization of Premium on Investment in Bonds (contd. ) Example (contd. ) Record the purchase on 1/1/x 2: Investments 108, 111 Cash 108, 111 Record the interest revenue on 7/1/x 2: Cash 5, 000 Interest Revenue 4, 324 a Investments 676 a. Interest revenue = $108, 111 x 4% = $4, 324 Statement of Cash Flows 39
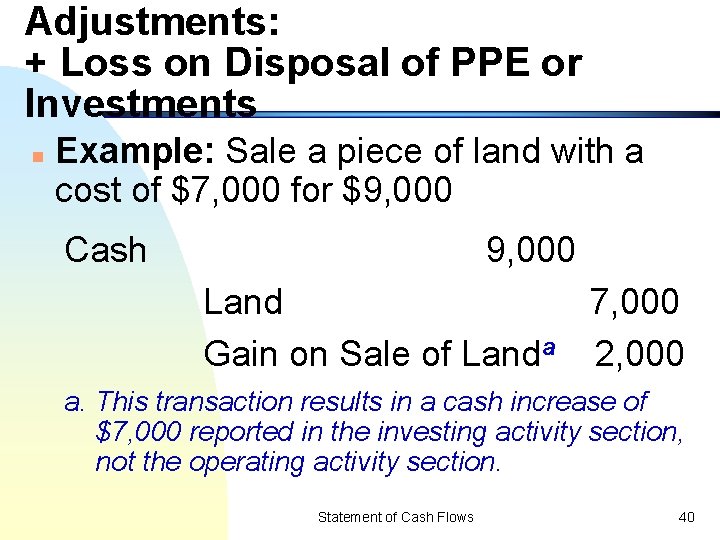
Adjustments: + Loss on Disposal of PPE or Investments n Example: Sale a piece of land with a cost of $7, 000 for $9, 000 Cash 9, 000 Land 7, 000 Gain on Sale of Landa 2, 000 a. This transaction results in a cash increase of $7, 000 reported in the investing activity section, not the operating activity section. Statement of Cash Flows 40
Adjustments: + Investment Loss under equity method n n Equity method must be used to account for return on investment in stock when gaining ownership of 20% ~ 50% with significant influence. Example: Obtain 30% of ownership with significant influence on investment in stock of Green Corp. for $40, 000 Statement of Cash Flows 41
+ Investment Loss under equity method (contd. ) 2/4/x 2 Investment in Stock Cash 40, 000 12/31/x 2 Green’s Loss of Year x 2 = 100, 000 Loss in Investment 30, 000 Investment in Stock 30, 000 Statement of Cash Flows 42
Data needed to prepare statement of cash flows 1. Comparative balance sheet statements. 2. The income statement. 3. The retained earnings statement. 4. Other supplemental information concerning the reasons for the changes in the B/S accounts (other than cash). Statement of Cash Flows 43
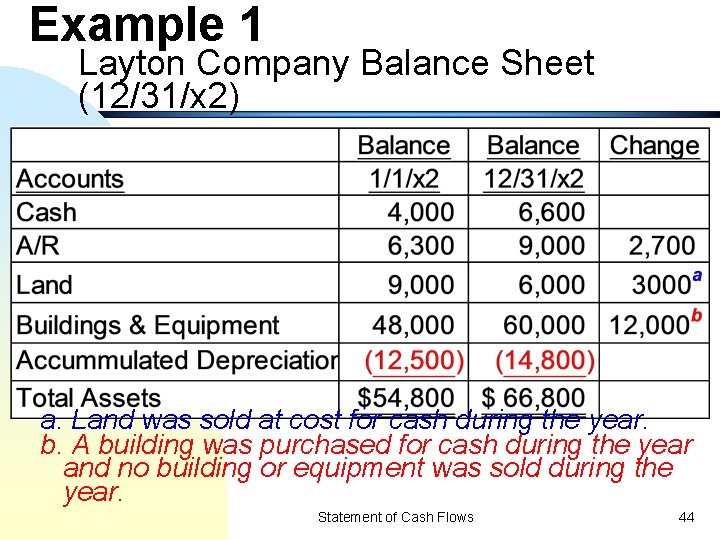
Example 1 Layton Company Balance Sheet (12/31/x 2) a. Land was sold at cost for cash during the year. b. A building was purchased for cash during the year and no building or equipment was sold during the year. Statement of Cash Flows 44
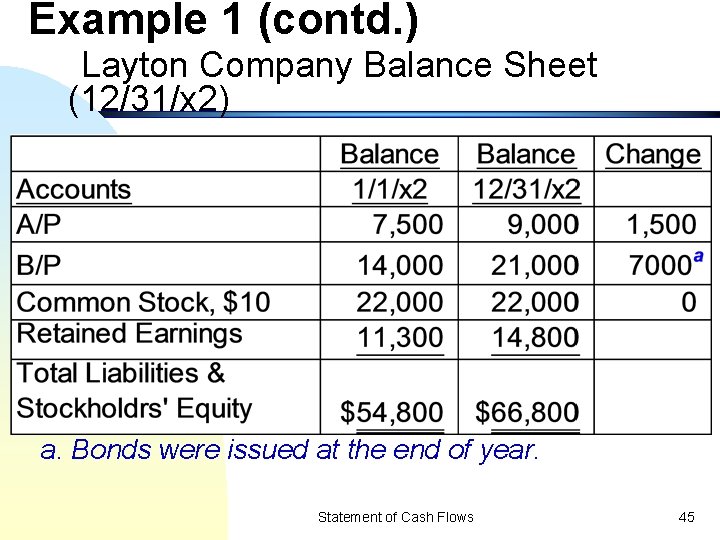
Example 1 (contd. ) Layton Company Balance Sheet (12/31/x 2) a. Bonds were issued at the end of year. Statement of Cash Flows 45
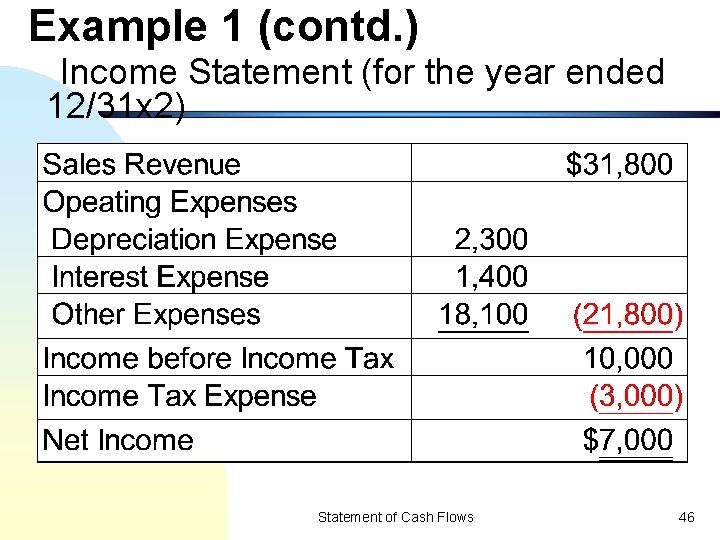
Example 1 (contd. ) Income Statement (for the year ended 12/31 x 2) Statement of Cash Flows 46
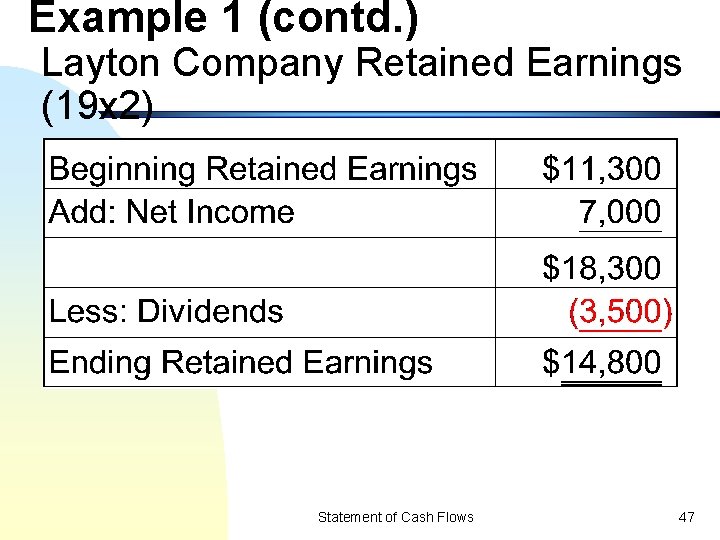
Example 1 (contd. ) Layton Company Retained Earnings (19 x 2) Statement of Cash Flows 47
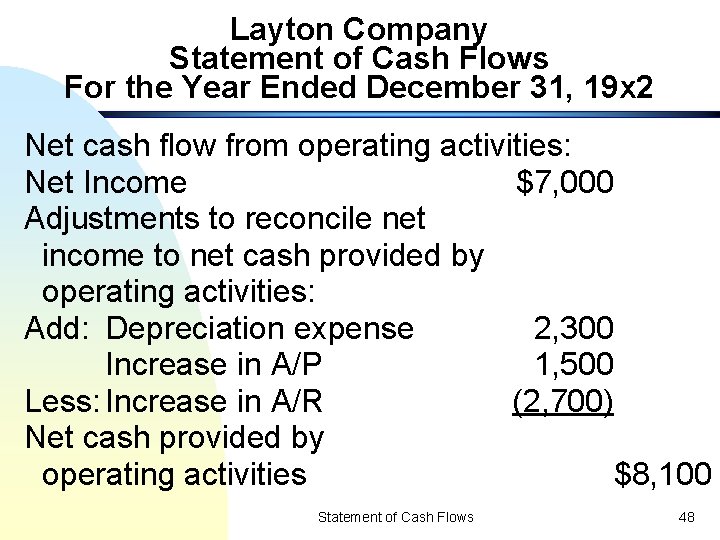
Layton Company Statement of Cash Flows For the Year Ended December 31, 19 x 2 Net cash flow from operating activities: Net Income $7, 000 Adjustments to reconcile net income to net cash provided by operating activities: Add: Depreciation expense 2, 300 Increase in A/P 1, 500 Less: Increase in A/R (2, 700) Net cash provided by operating activities $8, 100 Statement of Cash Flows 48
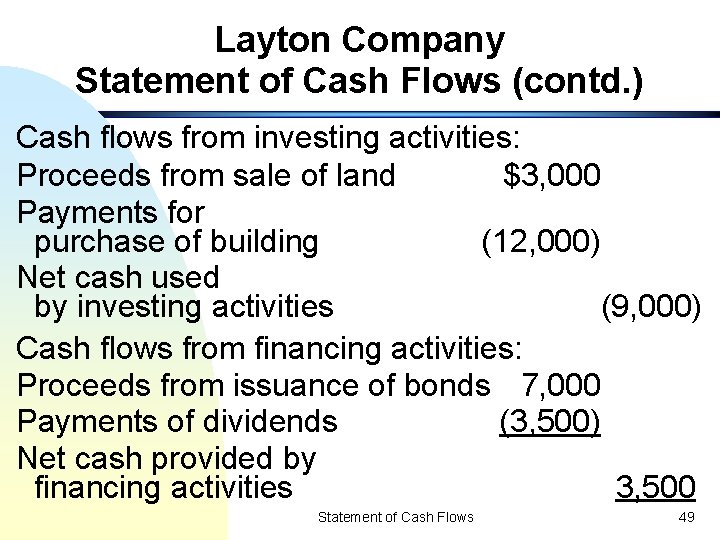
Layton Company Statement of Cash Flows (contd. ) Cash flows from investing activities: Proceeds from sale of land $3, 000 Payments for purchase of building (12, 000) Net cash used by investing activities (9, 000) Cash flows from financing activities: Proceeds from issuance of bonds 7, 000 Payments of dividends (3, 500) Net cash provided by financing activities 3, 500 Statement of Cash Flows 49
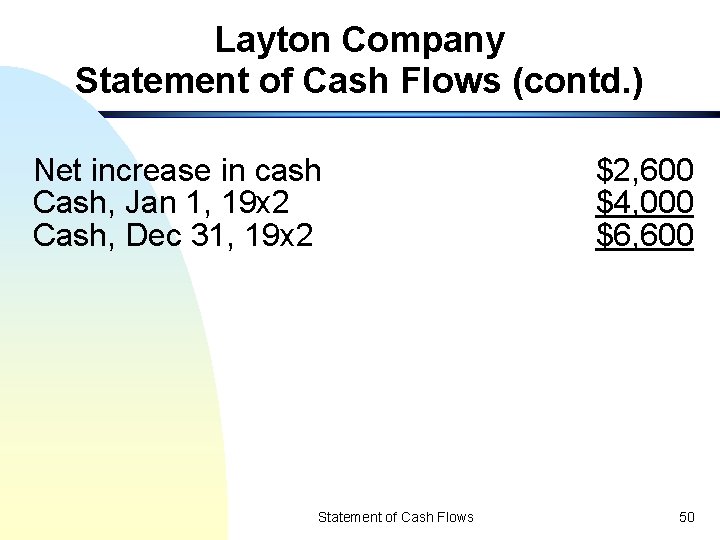
Layton Company Statement of Cash Flows (contd. ) Net increase in cash Cash, Jan 1, 19 x 2 Cash, Dec 31, 19 x 2 Statement of Cash Flows $2, 600 $4, 000 $6, 600 50
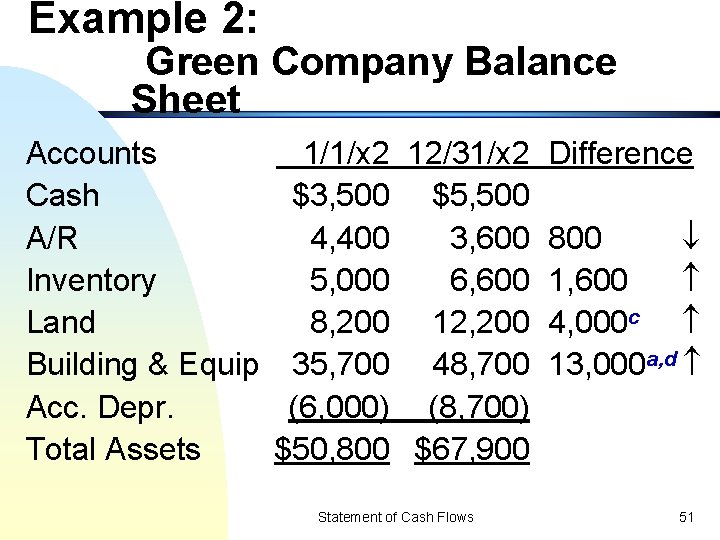
Example 2: Green Company Balance Sheet Accounts Cash A/R Inventory Land Building & Equip Acc. Depr. Total Assets 1/1/x 2 12/31/x 2 Difference $3, 500 $5, 500 4, 400 3, 600 800 5, 000 6, 600 1, 600 8, 200 12, 200 4, 000 c 35, 700 48, 700 13, 000 a, d (6, 000) (8, 700) $50, 800 $67, 900 Statement of Cash Flows 51
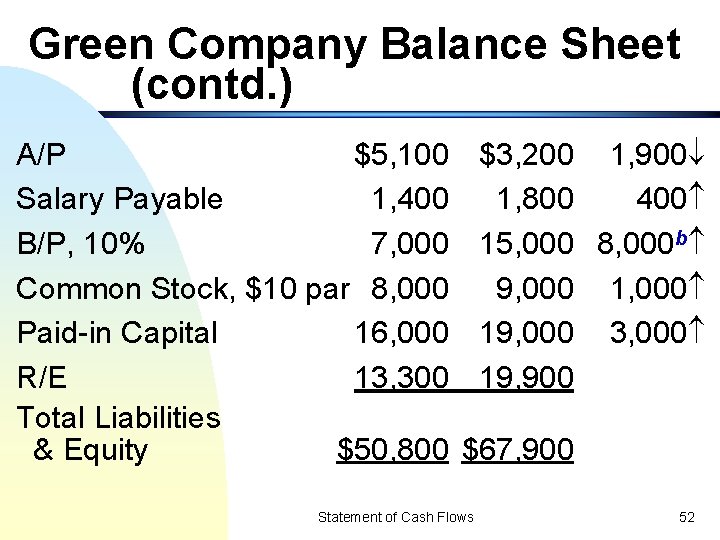
Green Company Balance Sheet (contd. ) A/P $5, 100 Salary Payable 1, 400 B/P, 10% 7, 000 Common Stock, $10 par 8, 000 Paid-in Capital 16, 000 R/E 13, 300 Total Liabilities & Equity $50, 800 $3, 200 1, 900 1, 800 400 15, 000 8, 000 b 9, 000 19, 000 3, 000 19, 900 $67, 900 Statement of Cash Flows 52
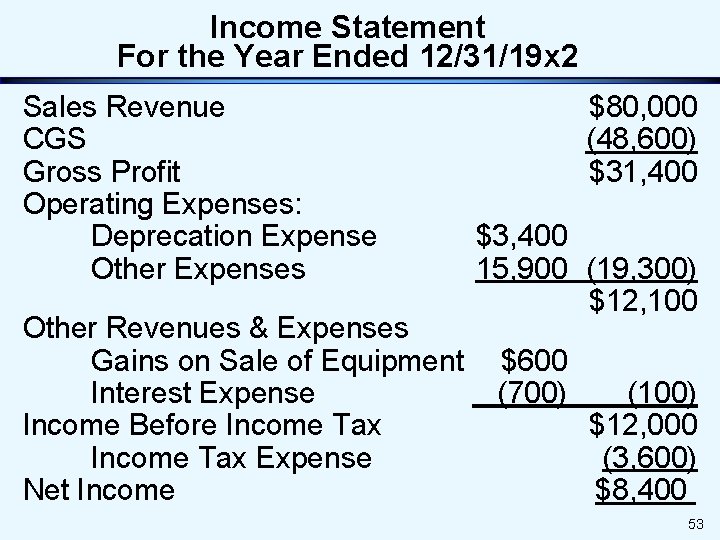
Income Statement For the Year Ended 12/31/19 x 2 Sales Revenue CGS Gross Profit Operating Expenses: Deprecation Expense Other Expenses Other Revenues & Expenses Gains on Sale of Equipment Interest Expense Income Before Income Tax Expense Net Income Statement of Cash Flows $80, 000 (48, 600) $31, 400 $3, 400 15, 900 (19, 300) $12, 100 $600 (700) (100) $12, 000 (3, 600) $8, 400. 53 53
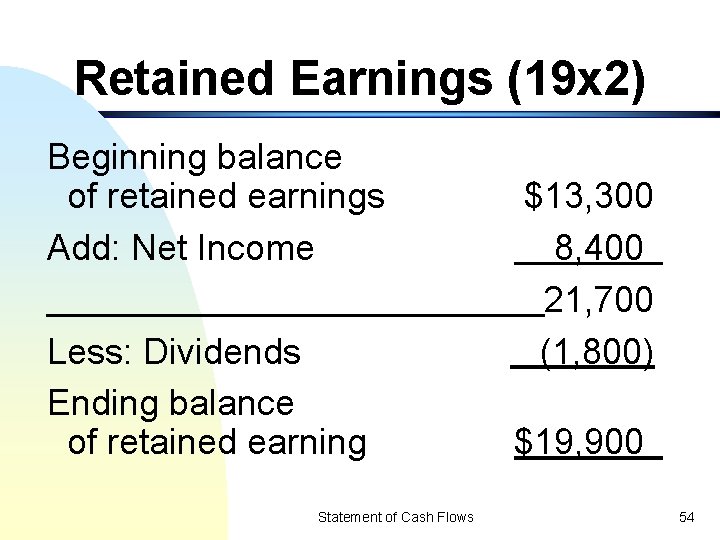
Retained Earnings (19 x 2) Beginning balance of retained earnings Add: Net Income Less: Dividends Ending balance of retained earning Statement of Cash Flows $13, 300 8, 400 21, 700 (1, 800) $19, 900 54
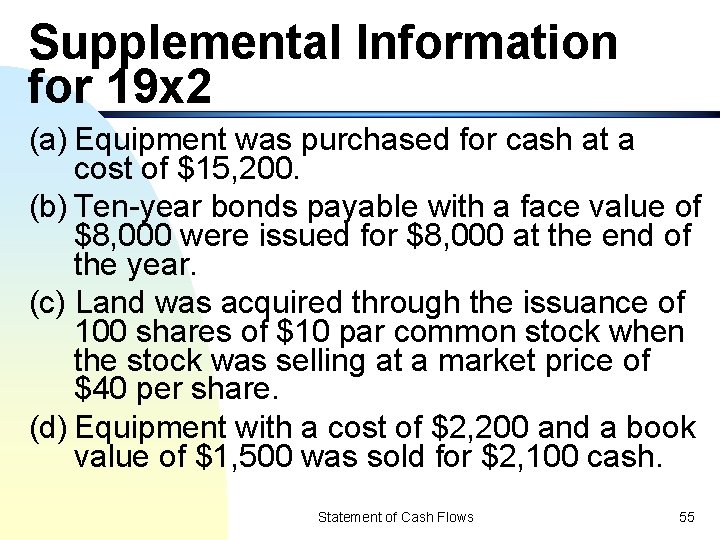
Supplemental Information for 19 x 2 (a) Equipment was purchased for cash at a cost of $15, 200. (b) Ten-year bonds payable with a face value of $8, 000 were issued for $8, 000 at the end of the year. (c) Land was acquired through the issuance of 100 shares of $10 par common stock when the stock was selling at a market price of $40 per share. (d) Equipment with a cost of $2, 200 and a book value of $1, 500 was sold for $2, 100 cash. Statement of Cash Flows 55
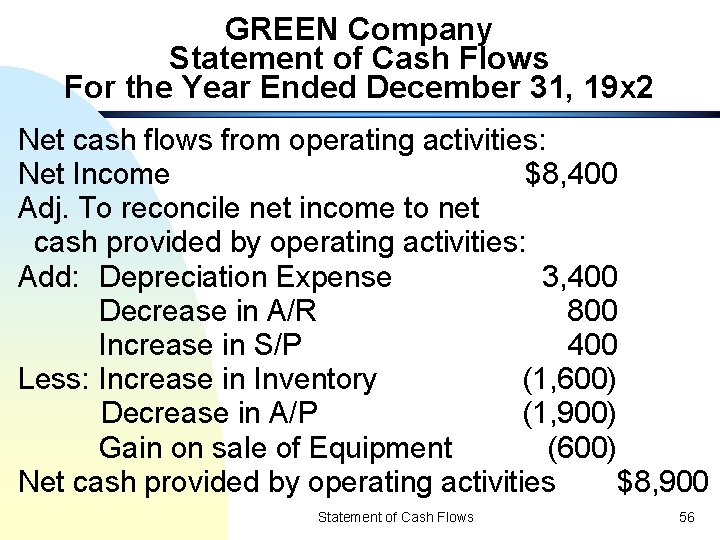
GREEN Company Statement of Cash Flows For the Year Ended December 31, 19 x 2 Net cash flows from operating activities: Net Income $8, 400 Adj. To reconcile net income to net cash provided by operating activities: Add: Depreciation Expense 3, 400 Decrease in A/R 800 Increase in S/P 400 Less: Increase in Inventory (1, 600) Decrease in A/P (1, 900) Gain on sale of Equipment (600) Net cash provided by operating activities $8, 900 Statement of Cash Flows 56
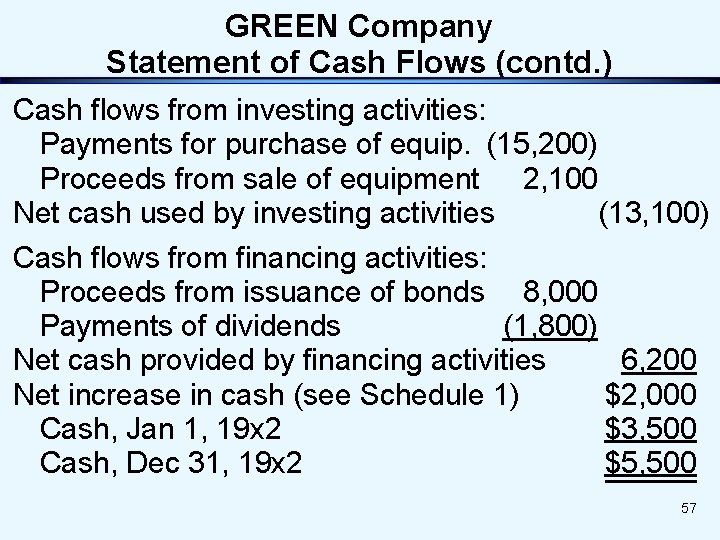
GREEN Company Statement of Cash Flows (contd. ) Cash flows from investing activities: Payments for purchase of equip. (15, 200) Proceeds from sale of equipment 2, 100 Net cash used by investing activities (13, 100) Cash flows from financing activities: Proceeds from issuance of bonds 8, 000 Payments of dividends (1, 800) Net cash provided by financing activities 6, 200 Net increase in cash (see Schedule 1) $2, 000 Cash, Jan 1, 19 x 2 $3, 500 Cash, Dec 31, 19 x 2 $5, 500 Statement of Cash Flows 57 57
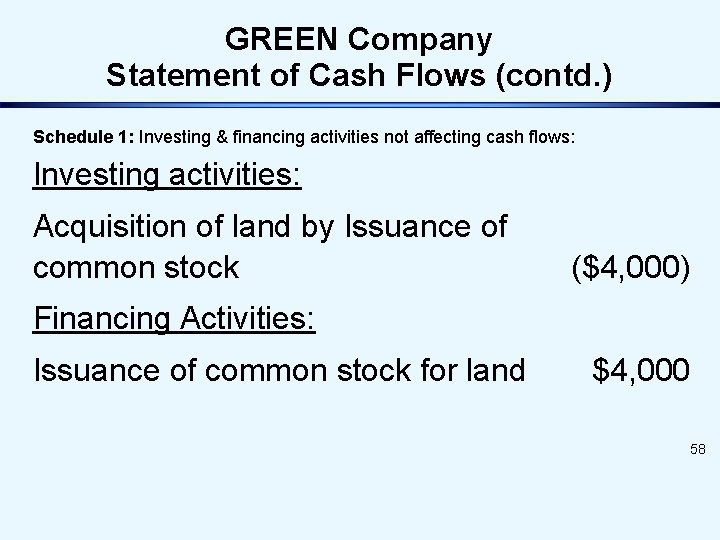
GREEN Company Statement of Cash Flows (contd. ) Schedule 1: Investing & financing activities not affecting cash flows: Investing activities: Acquisition of land by Issuance of common stock ($4, 000) Financing Activities: Issuance of common stock for land $4, 000 58 Statement of Cash Flows 58
Special Topics 1. Direct exchange. 2. Partial cash investing and financing activities. 3. Cash dividends declared. Statement of Cash Flows 59
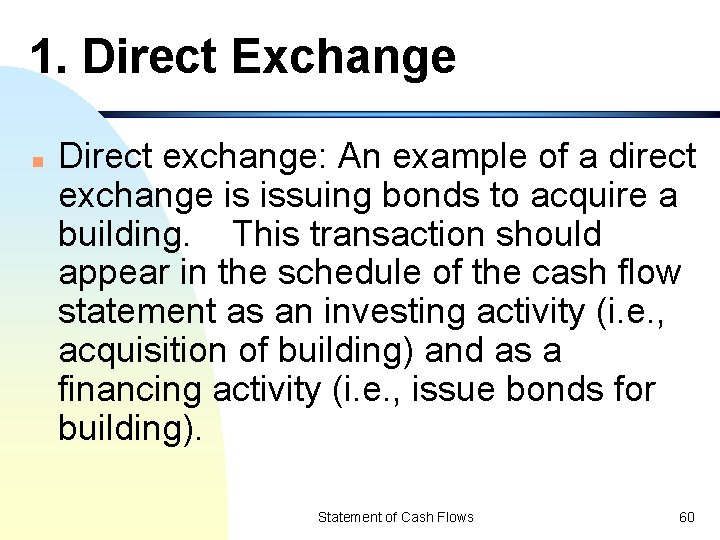
1. Direct Exchange n Direct exchange: An example of a direct exchange is issuing bonds to acquire a building. This transaction should appear in the schedule of the cash flow statement as an investing activity (i. e. , acquisition of building) and as a financing activity (i. e. , issue bonds for building). Statement of Cash Flows 60
2. Partial Cash Investing and Financing Activities n Example: acquiring land costing $10, 000 by paying $1, 000 down and signing a $9, 000 notes payable. Statement of Cash Flows 61
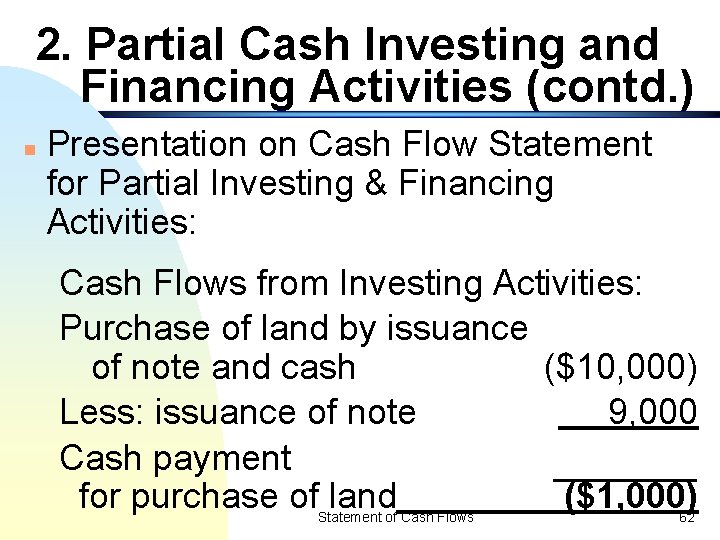
2. Partial Cash Investing and Financing Activities (contd. ) n Presentation on Cash Flow Statement for Partial Investing & Financing Activities: Cash Flows from Investing Activities: Purchase of land by issuance of note and cash ($10, 000) Less: issuance of note 9, 000 Cash payment for purchase of land ($1, 000) Statement of Cash Flows 62
3. Cash Dividends Declared (Stock dividends not reported on statement of cash flows. ) a. Cash dividends declared and paid in the same year: F Reported as a cash outflow of financing activities Statement of Cash Flows 63
3. Cash Dividends Declared (contd. ) b. Cash dividends declared in the current year but paid in the next year: (1)No impact on cash of the current year; only increase dividends payable (D/P). (2)When D/P decrease next year, reported as a cash outflow of financing activity. Statement of Cash Flows 64
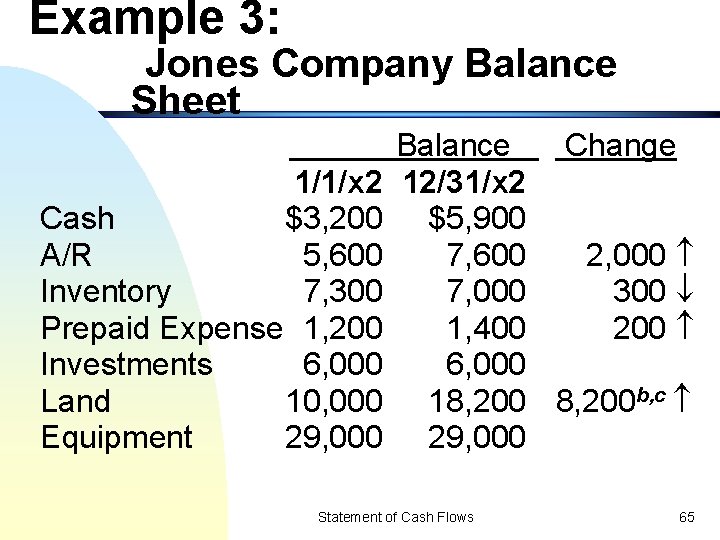
Example 3: Jones Company Balance Sheet 1/1/x 2 Cash $3, 200 A/R 5, 600 Inventory 7, 300 Prepaid Expense 1, 200 Investments 6, 000 Land 10, 000 Equipment 29, 000 Balance Change 12/31/x 2 $5, 900 7, 600 2, 000 7, 000 300 1, 400 200 6, 000 18, 200 b, c 29, 000 Statement of Cash Flows 65
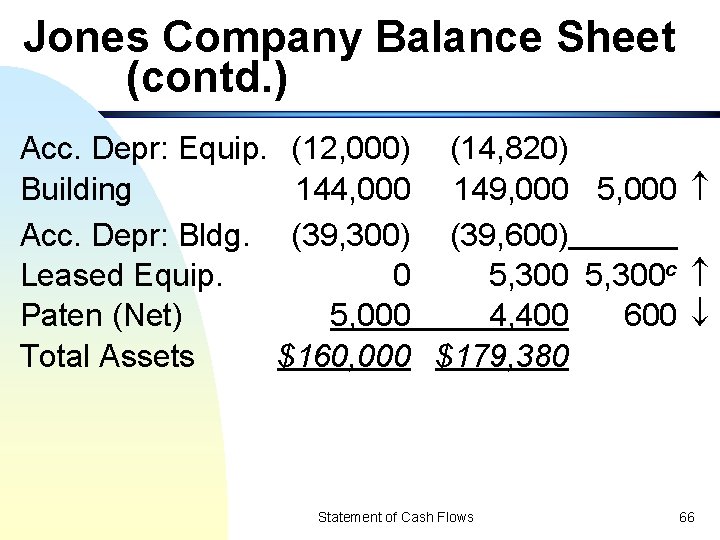
Jones Company Balance Sheet (contd. ) Acc. Depr: Equip. (12, 000) (14, 820) Building 144, 000 149, 000 5, 000 Acc. Depr: Bldg. (39, 300) (39, 600) Leased Equip. 0 5, 300 c Paten (Net) 5, 000 4, 400 600 Total Assets $160, 000 $179, 380 Statement of Cash Flows 66
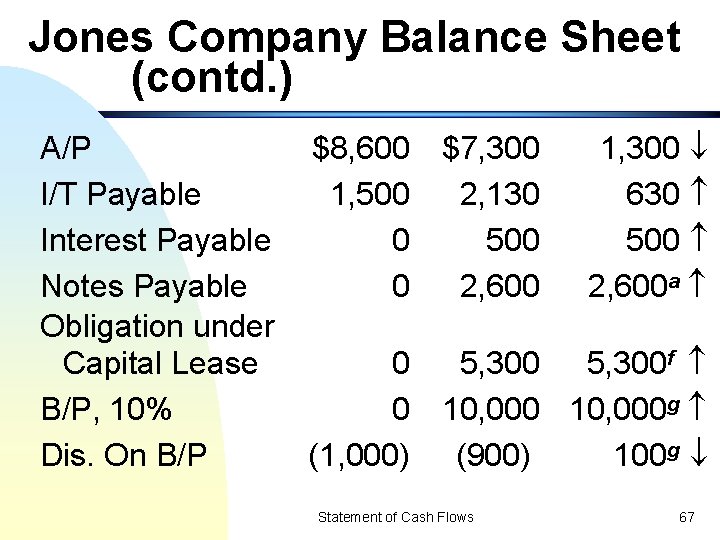
Jones Company Balance Sheet (contd. ) A/P I/T Payable Interest Payable Notes Payable Obligation under Capital Lease B/P, 10% Dis. On B/P 1, 300 630 500 2, 600 a $8, 600 1, 500 0 0 $7, 300 2, 130 500 2, 600 0 0 (1, 000) 5, 300 f 10, 000 g (900) 100 g Statement of Cash Flows 67
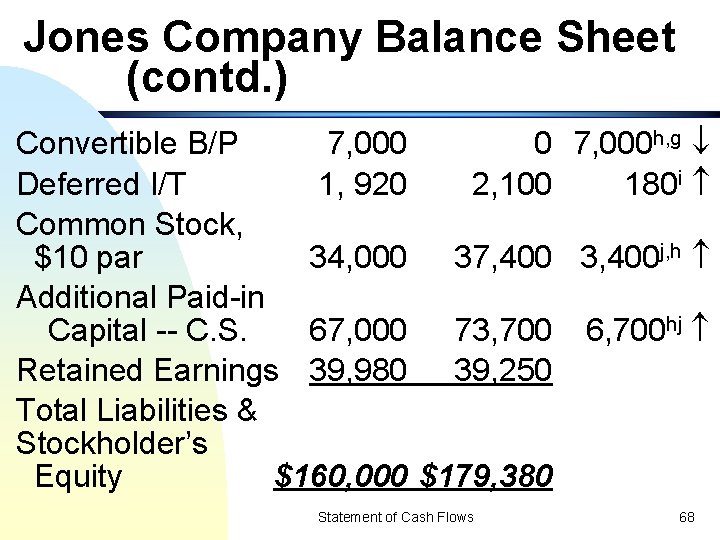
Jones Company Balance Sheet (contd. ) Convertible B/P 7, 000 0 7, 000 h, g Deferred I/T 1, 920 2, 100 180 i Common Stock, $10 par 34, 000 37, 400 3, 400 j, h Additional Paid-in Capital -- C. S. 67, 000 73, 700 6, 700 hj Retained Earnings 39, 980 39, 250 Total Liabilities & Stockholder’s Equity $160, 000 $179, 380 Statement of Cash Flows 68
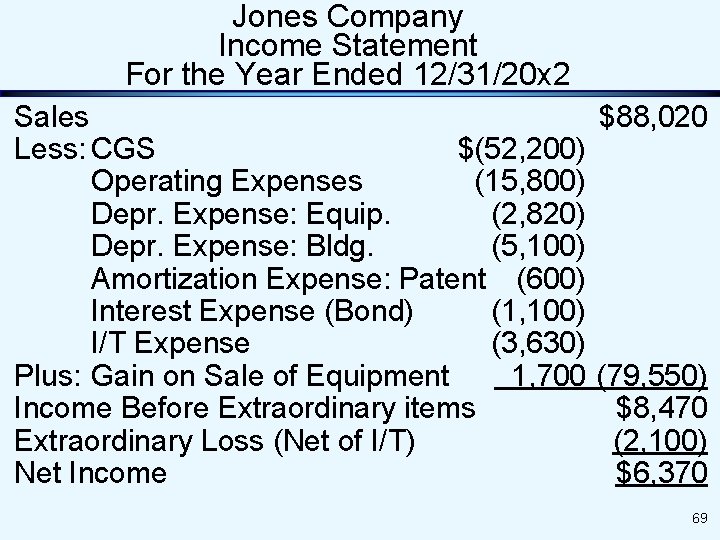
Jones Company Income Statement For the Year Ended 12/31/20 x 2 Sales $88, 020 Less: CGS $(52, 200) Operating Expenses (15, 800) Depr. Expense: Equip. (2, 820) Depr. Expense: Bldg. (5, 100) Amortization Expense: Patent (600) Interest Expense (Bond) (1, 100) I/T Expense (3, 630) Plus: Gain on Sale of Equipment 1, 700 (79, 550) Income Before Extraordinary items $8, 470 Extraordinary Loss (Net of I/T) (2, 100) Net Income $6, 370 Statement of Cash Flows 6969
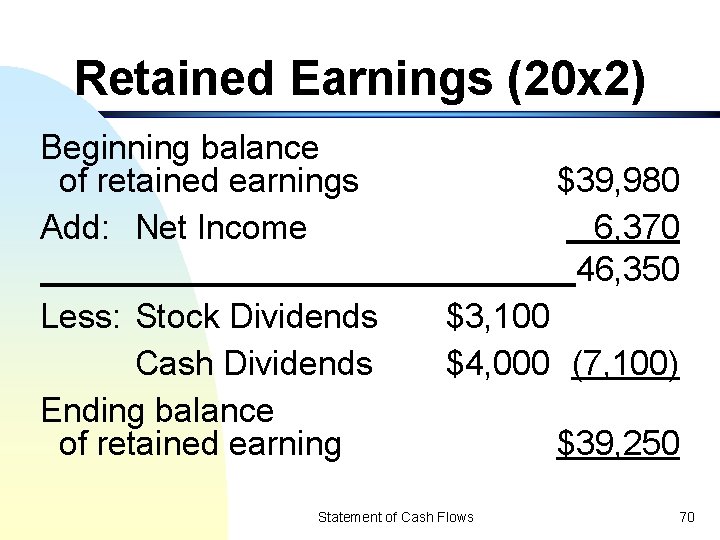
Retained Earnings (20 x 2) Beginning balance of retained earnings Add: Net Income Less: Stock Dividends Cash Dividends Ending balance of retained earning $39, 980 6, 370 46, 350 $3, 100 $4, 000 (7, 100) Statement of Cash Flows $39, 250 70
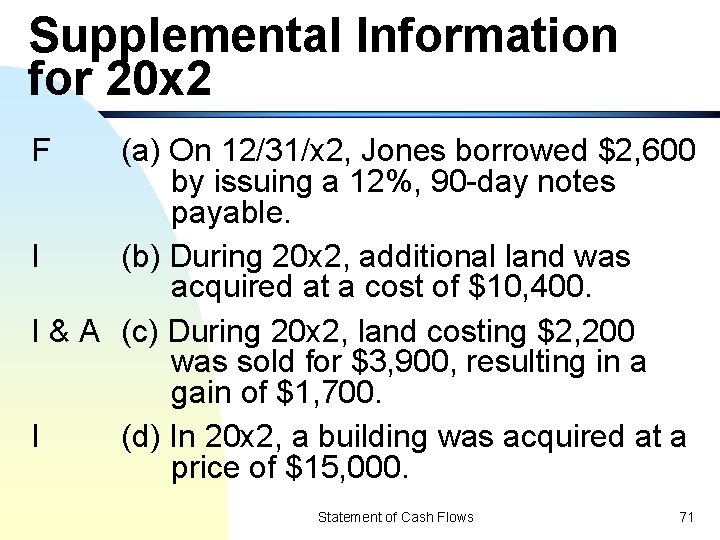
Supplemental Information for 20 x 2 F (a) On 12/31/x 2, Jones borrowed $2, 600 by issuing a 12%, 90 -day notes payable. I (b) During 20 x 2, additional land was acquired at a cost of $10, 400. I & A (c) During 20 x 2, land costing $2, 200 was sold for $3, 900, resulting in a gain of $1, 700. I (d) In 20 x 2, a building was acquired at a price of $15, 000. Statement of Cash Flows 71
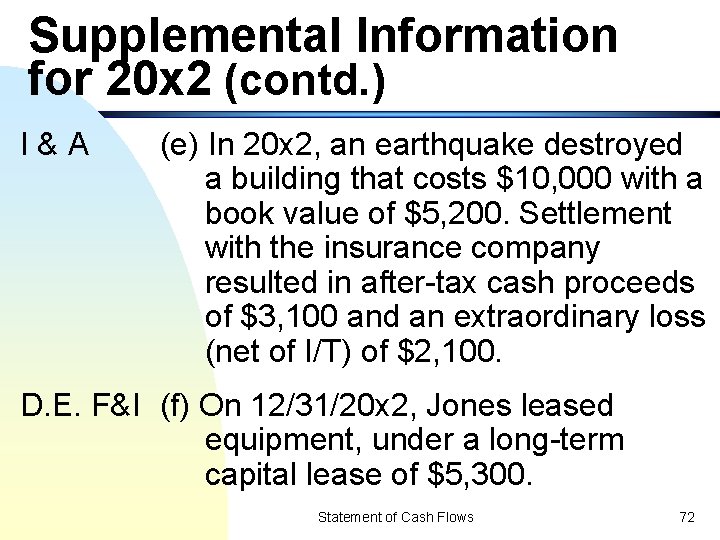
Supplemental Information for 20 x 2 (contd. ) I&A (e) In 20 x 2, an earthquake destroyed a building that costs $10, 000 with a book value of $5, 200. Settlement with the insurance company resulted in after-tax cash proceeds of $3, 100 and an extraordinary loss (net of I/T) of $2, 100. D. E. F&I (f) On 12/31/20 x 2, Jones leased equipment, under a long-term capital lease of $5, 300. Statement of Cash Flows 72
Supplemental Information for 20 x 2 (contd. ) F&A (g) On 1/1/x 2, Jones issued $10, 000 of long-term bond at 90. Bond discount amortization was $100 for the year. D. E. F&F (h) On 1/1/x 2, convertible bonds with a face value of $7, 000 were converted into 240 shares of common stock. The book value method was used to record the conversion. Statement of Cash Flows 73
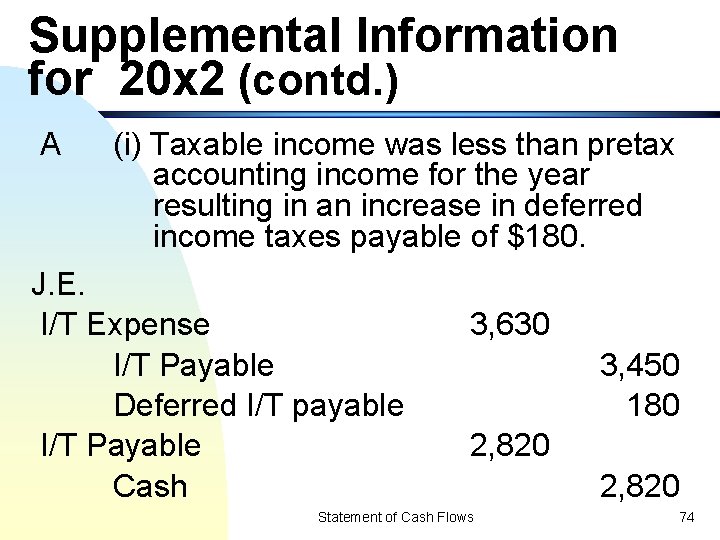
Supplemental Information for 20 x 2 (contd. ) A (i) Taxable income was less than pretax accounting income for the year resulting in an increase in deferred income taxes payable of $180. J. E. I/T Expense I/T Payable Deferred I/T payable I/T Payable Cash 3, 630 3, 450 180 2, 820 Statement of Cash Flows 2, 820 74
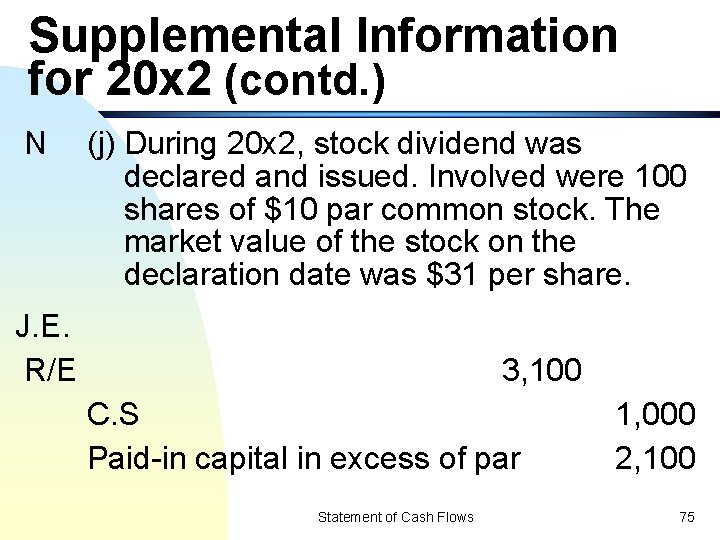
Supplemental Information for 20 x 2 (contd. ) N (j) During 20 x 2, stock dividend was declared and issued. Involved were 100 shares of $10 par common stock. The market value of the stock on the declaration date was $31 per share. J. E. R/E 3, 100 C. S Paid-in capital in excess of par Statement of Cash Flows 1, 000 2, 100 75
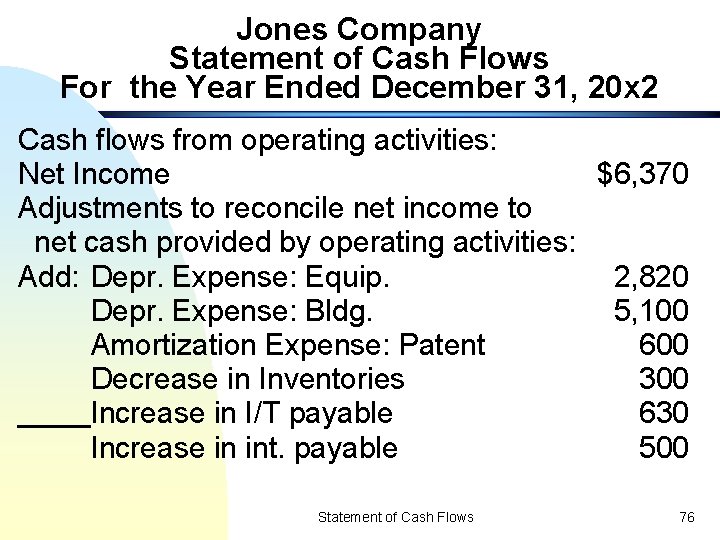
Jones Company Statement of Cash Flows For the Year Ended December 31, 20 x 2 Cash flows from operating activities: Net Income $6, 370 Adjustments to reconcile net income to net cash provided by operating activities: Add: Depr. Expense: Equip. 2, 820 Depr. Expense: Bldg. 5, 100 Amortization Expense: Patent 600 Decrease in Inventories 300 Increase in I/T payable 630 Increase in int. payable 500 Statement of Cash Flows 76
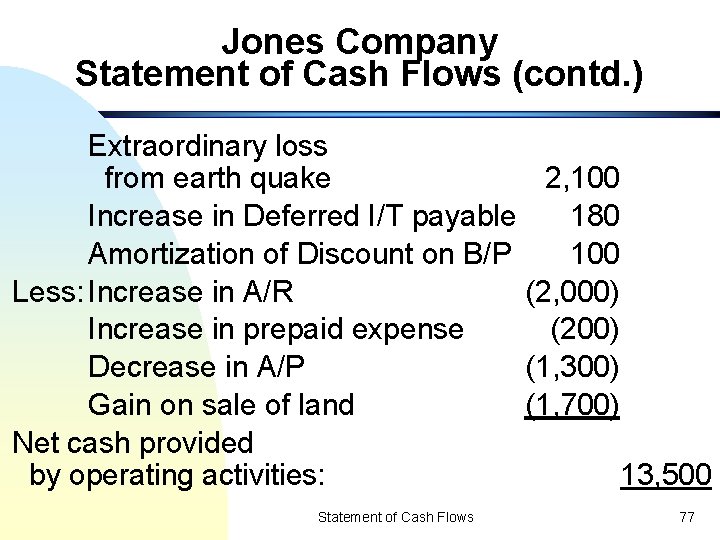
Jones Company Statement of Cash Flows (contd. ) Extraordinary loss from earth quake 2, 100 Increase in Deferred I/T payable 180 Amortization of Discount on B/P 100 Less: Increase in A/R (2, 000) Increase in prepaid expense (200) Decrease in A/P (1, 300) Gain on sale of land (1, 700) Net cash provided by operating activities: 13, 500 Statement of Cash Flows 77
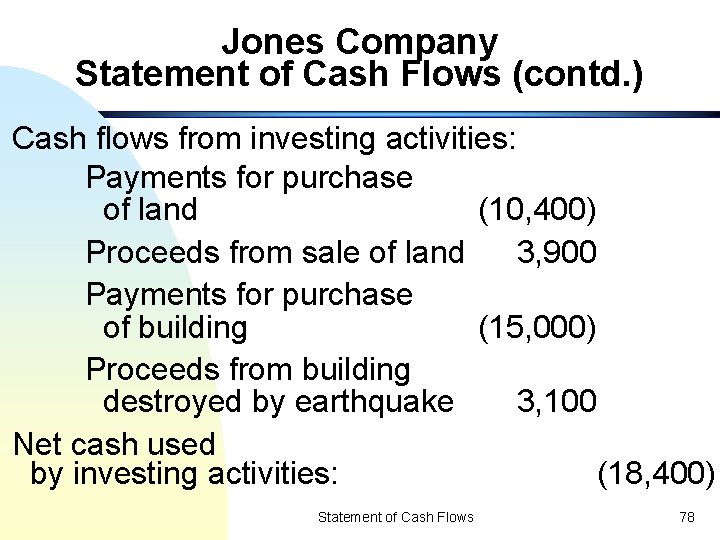
Jones Company Statement of Cash Flows (contd. ) Cash flows from investing activities: Payments for purchase of land (10, 400) Proceeds from sale of land 3, 900 Payments for purchase of building (15, 000) Proceeds from building destroyed by earthquake 3, 100 Net cash used by investing activities: (18, 400) Statement of Cash Flows 78
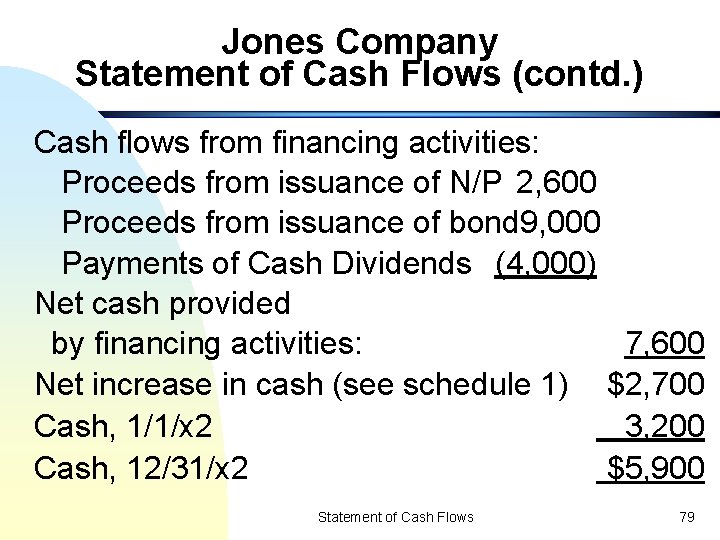
Jones Company Statement of Cash Flows (contd. ) Cash flows from financing activities: Proceeds from issuance of N/P 2, 600 Proceeds from issuance of bond 9, 000 Payments of Cash Dividends (4, 000) Net cash provided by financing activities: 7, 600 Net increase in cash (see schedule 1) $2, 700 Cash, 1/1/x 2 3, 200 Cash, 12/31/x 2 $5, 900 Statement of Cash Flows 79
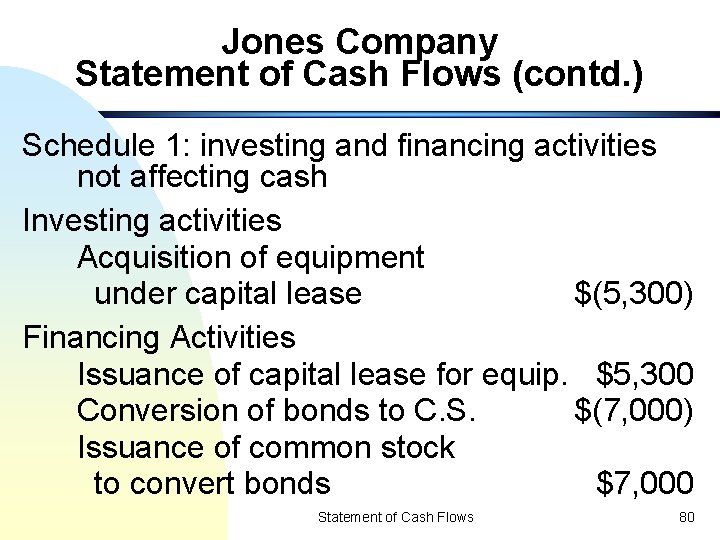
Jones Company Statement of Cash Flows (contd. ) Schedule 1: investing and financing activities not affecting cash Investing activities Acquisition of equipment under capital lease $(5, 300) Financing Activities Issuance of capital lease for equip. $5, 300 Conversion of bonds to C. S. $(7, 000) Issuance of common stock to convert bonds $7, 000 Statement of Cash Flows 80
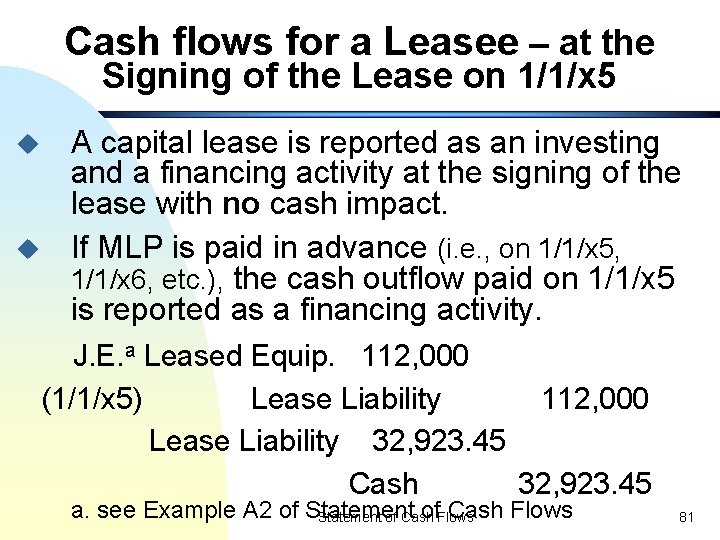
Cash flows for a Leasee – at the Signing of the Lease on 1/1/x 5 u u A capital lease is reported as an investing and a financing activity at the signing of the lease with no cash impact. If MLP is paid in advance (i. e. , on 1/1/x 5, 1/1/x 6, etc. ), the cash outflow paid on 1/1/x 5 is reported as a financing activity. J. E. a Leased Equip. 112, 000 (1/1/x 5) Lease Liability 112, 000 Lease Liability 32, 923. 45 Cash 32, 923. 45 a. see Example A 2 of Statement of. Flows Cash Flows Statement of Cash 81
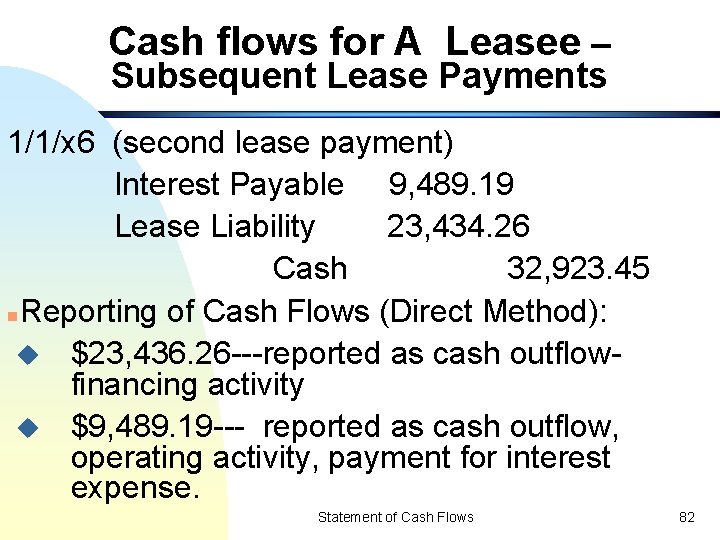
Cash flows for A Leasee – Subsequent Lease Payments 1/1/x 6 (second lease payment) Interest Payable 9, 489. 19 Lease Liability 23, 434. 26 Cash 32, 923. 45 n. Reporting of Cash Flows (Direct Method): u $23, 436. 26 ---reported as cash outflowfinancing activity u $9, 489. 19 --- reported as cash outflow, operating activity, payment for interest expense. Statement of Cash Flows 82
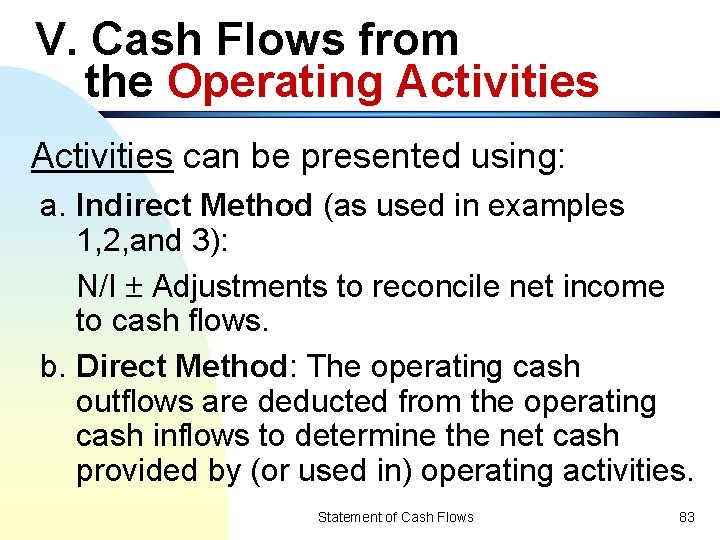
V. Cash Flows from the Operating Activities can be presented using: a. Indirect Method (as used in examples 1, 2, and 3): N/I Adjustments to reconcile net income to cash flows. b. Direct Method: The operating cash outflows are deducted from the operating cash inflows to determine the net cash provided by (or used in) operating activities. Statement of Cash Flows 83
Cash Flows from the Operating Activities (contd. ) n SFAS No. 95 allows the use of both methods, but encourages the use of the direct method. However, if the direct method is used, a reconcile of net income and cash using the indirect method must also be provided in the supplementary statement. Statement of Cash Flows 84
Using The Direct Method in Preparing The Operating Cash Flows Cash inflows from operating activities: 1. Collections from customers. 2. Interest & dividends collected. 3. Other operating receipts. Statement of Cash Flows 85
Using The Direct Method in Preparing The Operating Cash Flows (contd. ) Cash outflows from operating activities: 1. Payments to suppliers. 2. Payments to employees. 3. Payments of interest. 4. Other operating payments. 5. Payments of income taxes. Statement of Cash Flows 86
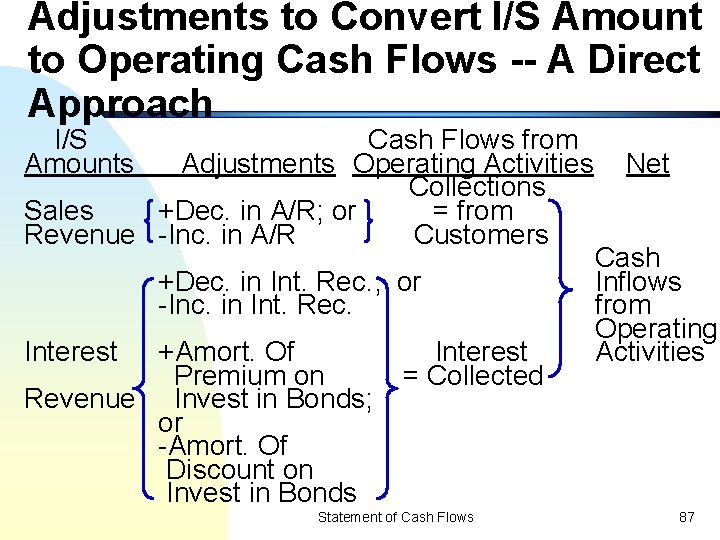
Adjustments to Convert I/S Amount to Operating Cash Flows -- A Direct Approach I/S Amounts Cash Flows from Adjustments Operating Activities Collections Sales +Dec. in A/R; or = from Revenue -Inc. in A/R Customers +Dec. in Int. Rec. ; or -Inc. in Int. Rec. Interest +Amort. Of Premium on Revenue Invest in Bonds; or -Amort. Of Discount on Invest in Bonds Interest = Collected Statement of Cash Flows Net Cash Inflows from Operating Activities 87
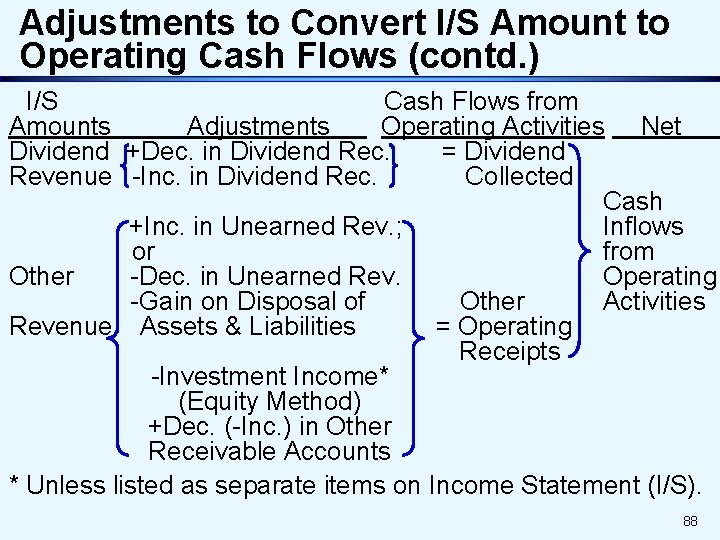
Adjustments to Convert I/S Amount to Operating Cash Flows (contd. ) I/S Cash Flows from Amounts Adjustments Operating Activities Net Dividend +Dec. in Dividend Rec. = Dividend Revenue -Inc. in Dividend Rec. Collected Cash +Inc. in Unearned Rev. ; Inflows or from Other -Dec. in Unearned Rev. Operating -Gain on Disposal of Other Activities Revenue Assets & Liabilities = Operating Receipts -Investment Income* (Equity Method) +Dec. (-Inc. ) in Other Receivable Accounts * Unless listed as separate items on Income Statement (I/S). Statement of Cash Flows 88 88
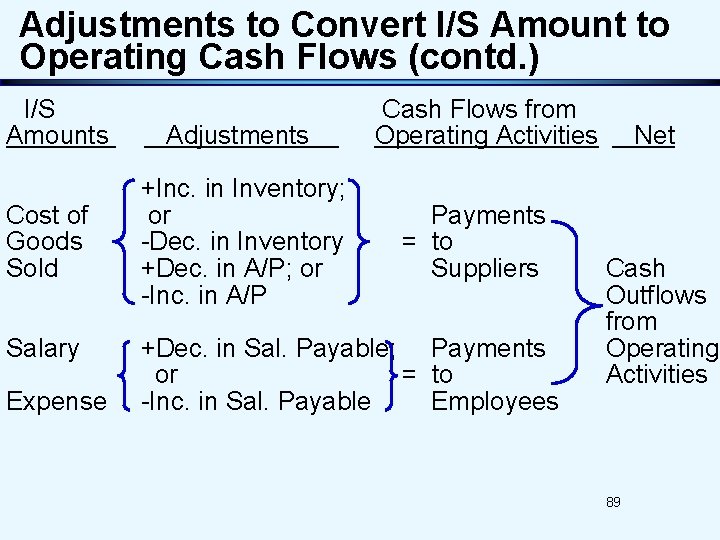
Adjustments to Convert I/S Amount to Operating Cash Flows (contd. ) I/S Amounts Cost of Goods Sold Salary Expense Cash Flows from Operating Activities Adjustments +Inc. in Inventory; or -Dec. in Inventory +Dec. in A/P; or -Inc. in A/P Payments = to Suppliers +Dec. in Sal. Payable; Payments or = to -Inc. in Sal. Payable Employees Statement of Cash Flows Net Cash Outflows from Operating Activities 89 89
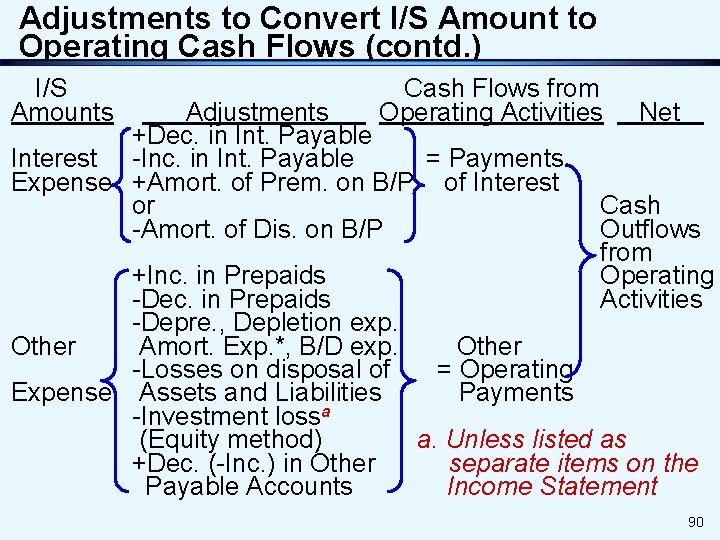
Adjustments to Convert I/S Amount to Operating Cash Flows (contd. ) I/S Amounts Cash Flows from Operating Activities Adjustments +Dec. in Int. Payable Interest -Inc. in Int. Payable = Payments Expense +Amort. of Prem. on B/P of Interest or -Amort. of Dis. on B/P Net Cash Outflows from Operating Activities +Inc. in Prepaids -Depre. , Depletion exp. Other Amort. Exp. *, B/D exp. Other -Losses on disposal of = Operating Expense Assets and Liabilities Payments -Investment lossa (Equity method) a. Unless listed as +Dec. (-Inc. ) in Other separate items on the Payable Accounts Income Statement of Cash Flows 9090
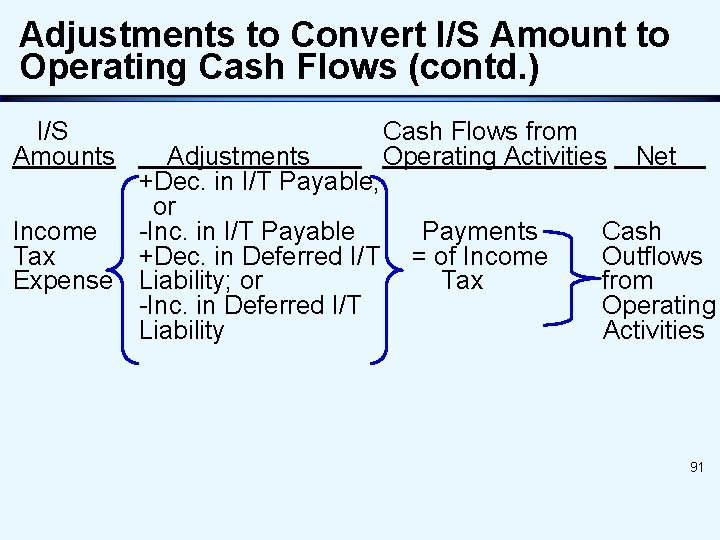
Adjustments to Convert I/S Amount to Operating Cash Flows (contd. ) I/S Amounts Adjustments +Dec. in I/T Payable; or Income -Inc. in I/T Payable Tax +Dec. in Deferred I/T Expense Liability; or -Inc. in Deferred I/T Liability Cash Flows from Operating Activities Payments = of Income Tax Net Cash Outflows from Operating Activities 91 Statement of Cash Flows 91
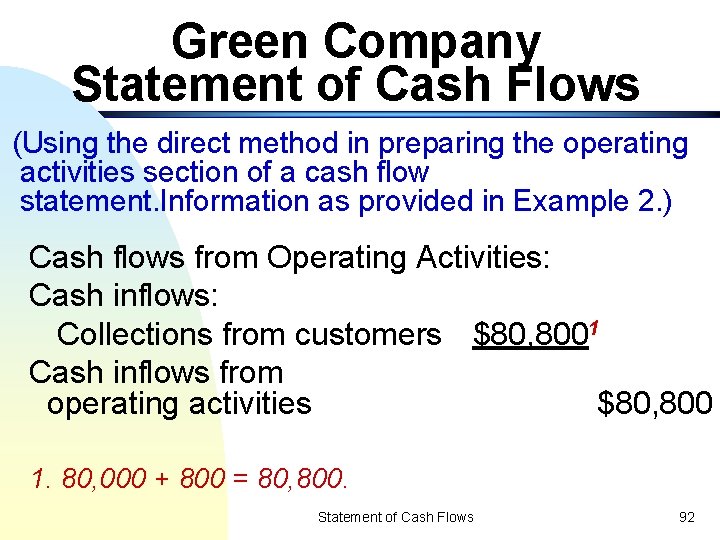
Green Company Statement of Cash Flows (Using the direct method in preparing the operating activities section of a cash flow statement. Information as provided in Example 2. ) Cash flows from Operating Activities: Cash inflows: Collections from customers $80, 8001 Cash inflows from operating activities $80, 800 1. 80, 000 + 800 = 80, 800. Statement of Cash Flows 92
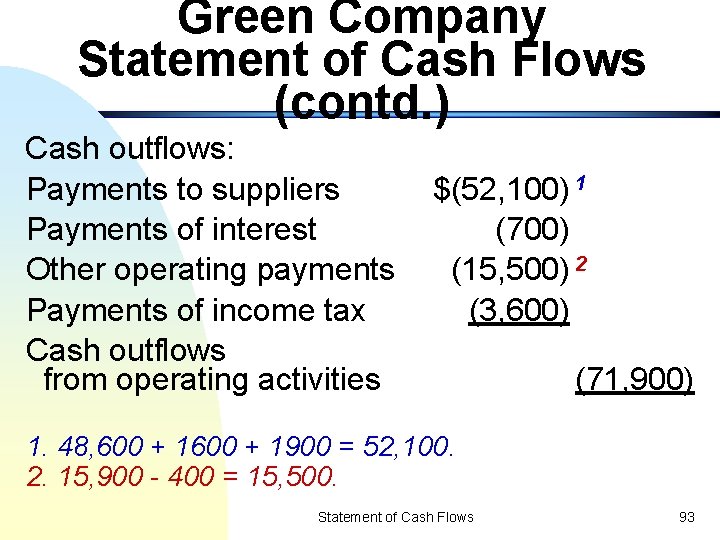
Green Company Statement of Cash Flows (contd. ) Cash outflows: Payments to suppliers Payments of interest Other operating payments Payments of income tax Cash outflows from operating activities $(52, 100) 1 (700) (15, 500) 2 (3, 600) (71, 900) 1. 48, 600 + 1900 = 52, 100. 2. 15, 900 - 400 = 15, 500. Statement of Cash Flows 93
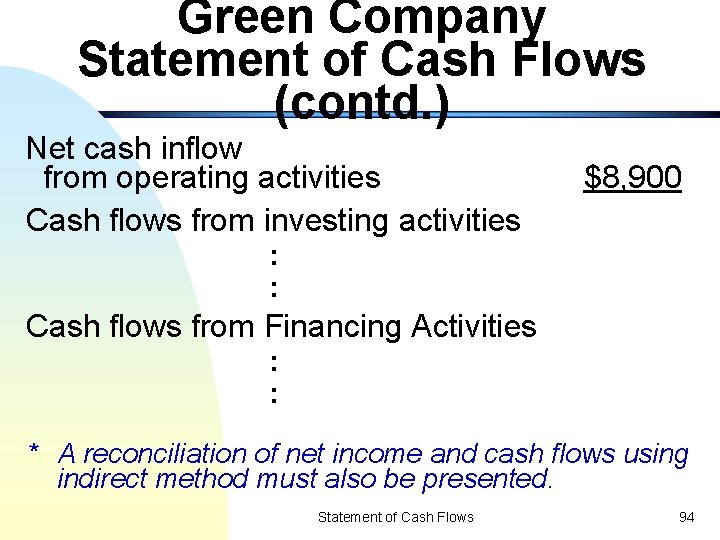
Green Company Statement of Cash Flows (contd. ) Net cash inflow from operating activities Cash flows from investing activities $8, 900 : : Cash flows from Financing Activities : : * A reconciliation of net income and cash flows using indirect method must also be presented. Statement of Cash Flows 94
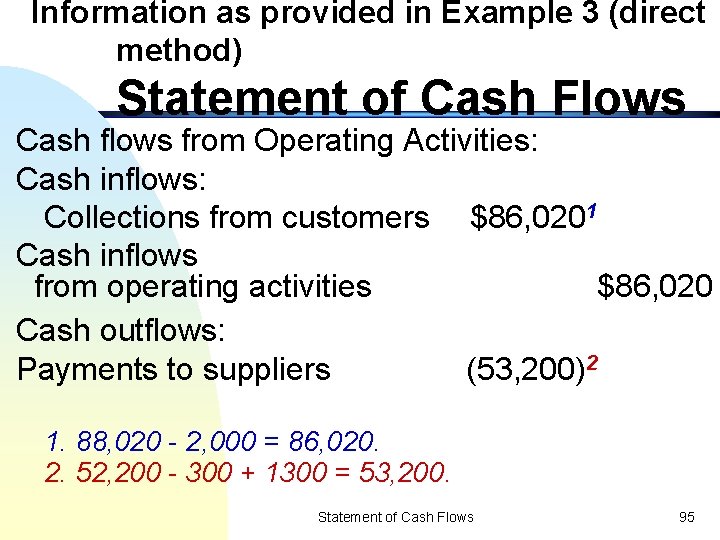
Information as provided in Example 3 (direct method) Statement of Cash Flows Cash flows from Operating Activities: Cash inflows: Collections from customers $86, 0201 Cash inflows from operating activities $86, 020 Cash outflows: Payments to suppliers (53, 200)2 1. 88, 020 - 2, 000 = 86, 020. 2. 52, 200 - 300 + 1300 = 53, 200. Statement of Cash Flows 95
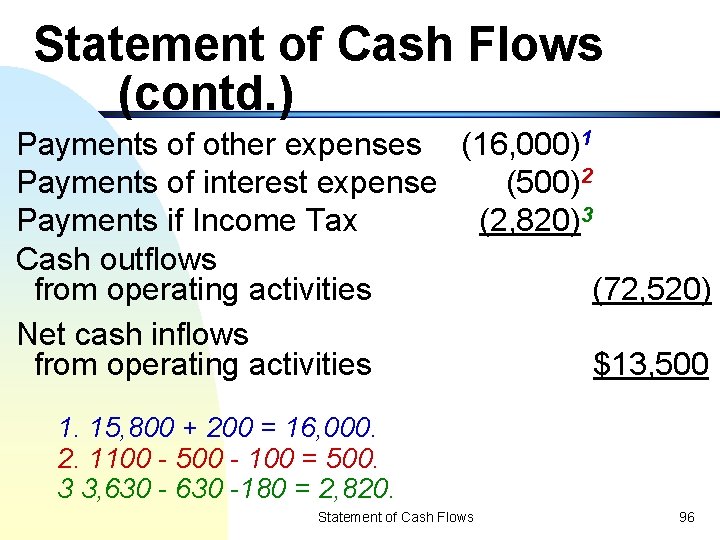
Statement of Cash Flows (contd. ) Payments of other expenses (16, 000)1 Payments of interest expense (500)2 Payments if Income Tax (2, 820)3 Cash outflows from operating activities (72, 520) Net cash inflows from operating activities $13, 500 1. 15, 800 + 200 = 16, 000. 2. 1100 - 500 - 100 = 500. 3 3, 630 -180 = 2, 820. Statement of Cash Flows 96
Other Special Topics 1. Gain from sale of cash equivalents. 2. Accounts Receivable. 3. Issues related to adjustment of income tax expense to cash payment for income tax. (see P 21 -11 for example) Statement of Cash Flows 97
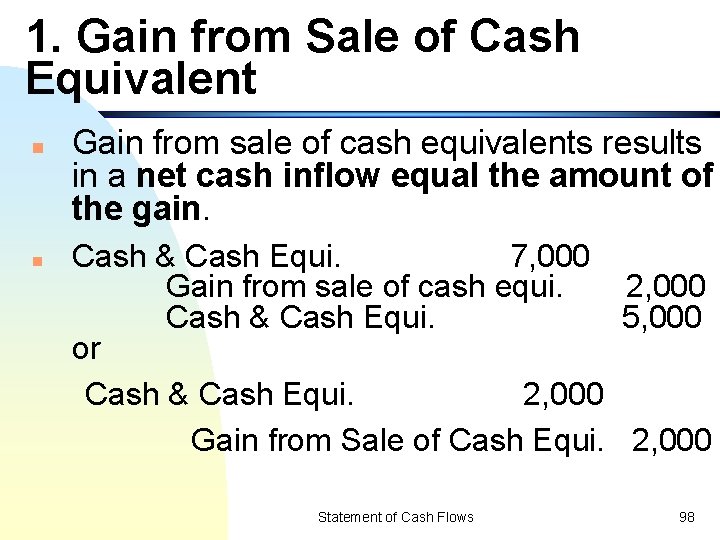
1. Gain from Sale of Cash Equivalent n n Gain from sale of cash equivalents results in a net cash inflow equal the amount of the gain. Cash & Cash Equi. 7, 000 Gain from sale of cash equi. 2, 000 Cash & Cash Equi. 5, 000 or Cash & Cash Equi. 2, 000 Gain from Sale of Cash Equi. 2, 000 Statement of Cash Flows 98
Gain from Sale of Cash Equivalent (Contd. ) n n n Using the indirect method, this gain should not be subtracted from net income. This is because the cash inflow from this sale is reported in the operating, not investing, activity section. Using the direct method, this gain should be reported as a cash inflow in the operating activities section. Statement of Cash Flows 99
2. Accounts Receivable n n n The balance used to compute the changes in accounts receivable should be the gross amount, not the balance net of allowance for bad debts. Also, this gross amount should be adjusted to prior to the any bad debt writeoffs occurred during the year. Allowance for bad debts does not affect cash flows and should not be considered. Statement of Cash Flows 100
3. Issues Related to Adjustments of Income Tax Expense to Cash Payment for Income Tax Expense n n In adjusting income tax expense to cash payment for income tax, the expense used should be the income tax expense for all existing components of the income statement for that yeara. a. Income tax expense for continuing operations, discontinued operations, extraordinary items and the cumulative effect. Statement of Cash Flows 101
3. Issues Related to Adjustments of Income Tax Expense to Cash Payment for Income Tax Expense (contd. ) n When income tax expense given is for the continuing operations only, any income tax savings (liabilities) from components other than continuing operations should be subtracted (added) prior to the adjustment. Statement of Cash Flows 102
- Slides: 102