
IND AS 116 Prepared By Abhishek Aggarwal IND
IND AS - 116 Prepared By: Abhishek Aggarwal
IND AS 116 Overview Effective date – 1 st April 2019 Eliminates the accounting difference between an operating lease and an finance lease for lessee Lessee’s with operating leases will have a major impact in accounting For lessor the accounting and classification is done based on existing operating/finance lease model
Pre-requisites of Lease Identified asset Lessee obtains substantially all of the economic benefits Lessee directs the use If all the above conditions are fulfilled the Contract will classify as lease.
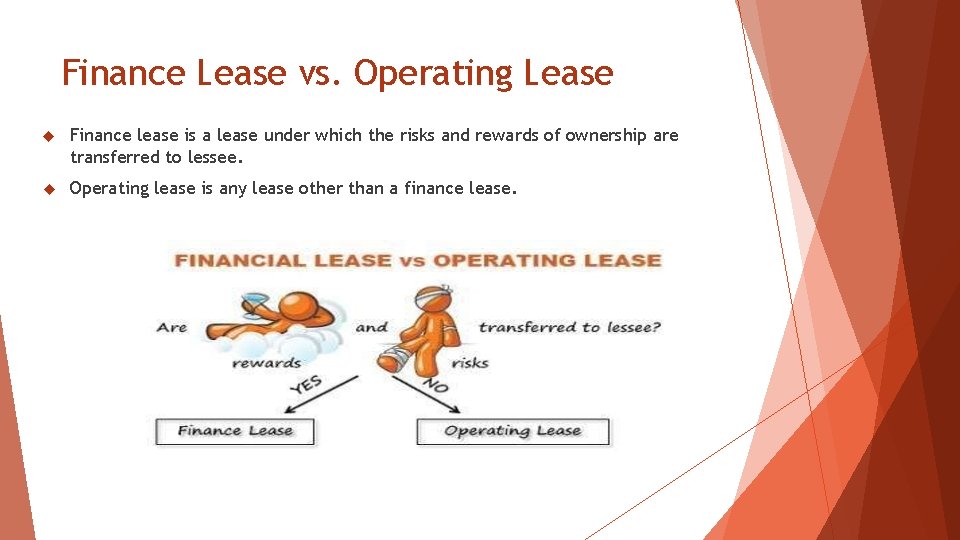
Finance Lease vs. Operating Lease Finance lease is a lease under which the risks and rewards of ownership are transferred to lessee. Operating lease is any lease other than a finance lease.
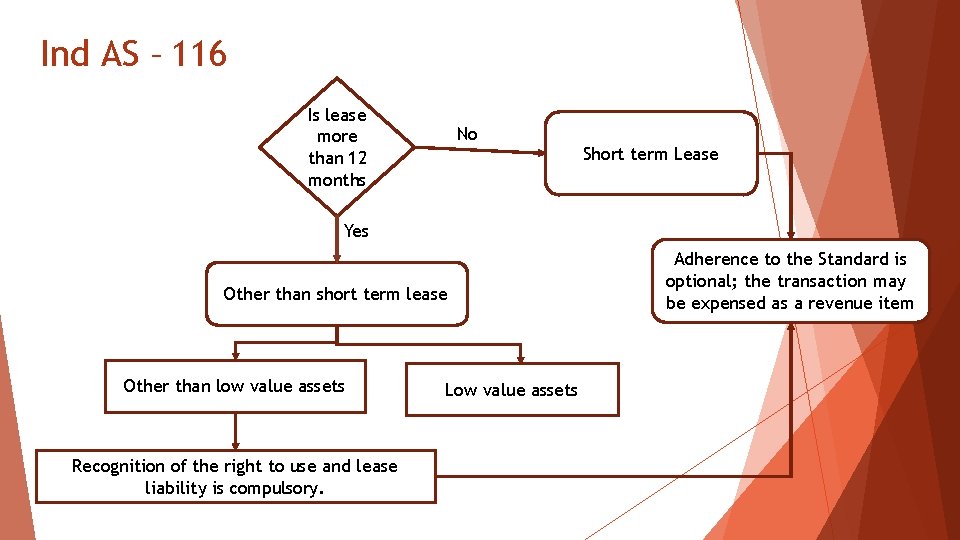
Ind AS – 116 Is lease more than 12 months No Short term Lease Yes Other than short term lease Other than low value assets Recognition of the right to use and lease liability is compulsory. Low value assets Adherence to the Standard is optional; the transaction may be expensed as a revenue item
Short term Leases Short-term leases upto 12 months “lease tenure” are excluded from the Standard. Lease tenure includes the right to renew, if it is reasonably certain that the right will be exercised.
Lessor accounting Finance Lease Recognition of the asset – Receivable at an amount equal to the net investment in the lease. Recognition of the Income – Finance income over the lease term, based on a pattern reflecting a constant periodic rate of return on the lessor’s net investment in the lease. Operating Lease Recognition of the asset – capitalised. Recognition of the Income – Either straight-line basis or another systematic basis which is more representative of the pattern in which benefit from the use of the underlying asset is diminished.
Lessee accounting Initial Recognition Recognise assets and liabilities for all leases for a term of more than 12 months, unless the underlying asset is of low value. recognise a right of use asset representing its right to use the underlying leased asset and a lease liability representing its obligations to make lease payments. Measure right-of-use assets similarly to other nonfinancial assets (such as property, plant and equipment) and lease liabilities similarly to other financial liabilities. Recognise depreciation of the right-of-use asset and interest on the lease liability (as per IND AS 17 the same was classified as rent in case of operating lease on a straight-line basis). Recognise interest cost as finance cost.
Lessee accounting Initial Recognition Lease liability = Present value of lease rentals + present value of expected payments at the end of lease. The lease liability will be amortised using the effective interest rate method. Lease term = Non-cancellable period + renewable period if lessee reasonably certain to exercise. Right to use asset = Lease liability + lease payments (advance)- lease incentives to be received if any initial + initial direct costs + cost of dismantling/ restoring etc. The asset will be depreciated as per IND AS 16 Property plant and equipment.
CASE STUDY – In books of lessee Rent of Rs. 10 lakhs per annum. Discount rate – 10%. Lease tenure – 5 years. Treatment in books of lessee – Right of use asset will be recognised at Rs. 37, 90, 986 (Present value of 5 instalments of Rs. 10 lakhs each) and will be depreciated over a period of 5 years.
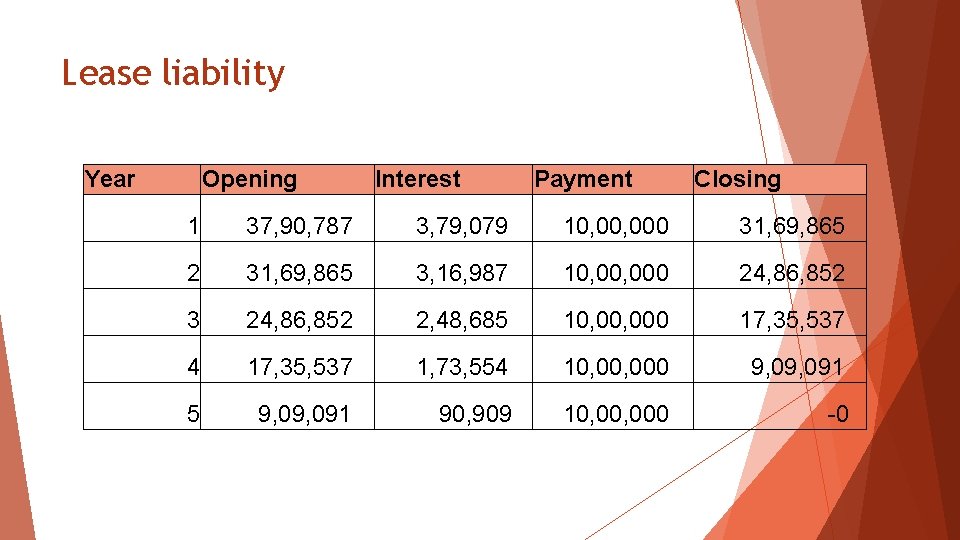
Lease liability Year Opening Interest Payment Closing 1 37, 90, 787 3, 79, 079 10, 000 31, 69, 865 2 31, 69, 865 3, 16, 987 10, 000 24, 86, 852 3 24, 86, 852 2, 48, 685 10, 000 17, 35, 537 4 17, 35, 537 1, 73, 554 10, 000 9, 091 5 9, 091 90, 909 10, 000 -0
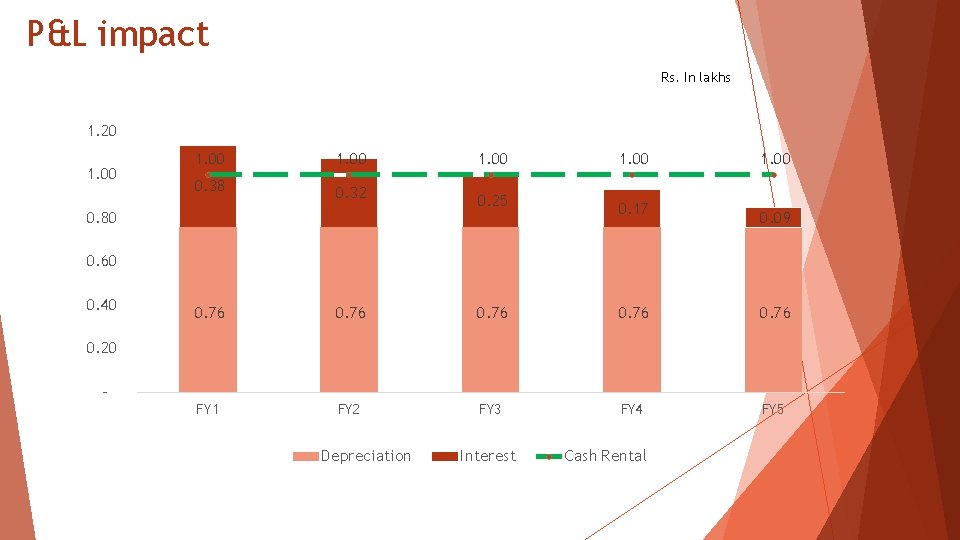
P&L impact Rs. In lakhs 1. 20 1. 00 0. 38 0. 32 0. 25 0. 80 1. 00 0. 17 1. 00 0. 09 0. 60 0. 40 0. 76 FY 1 FY 2 FY 3 FY 4 FY 5 0. 20 - Depreciation Interest Cash Rental
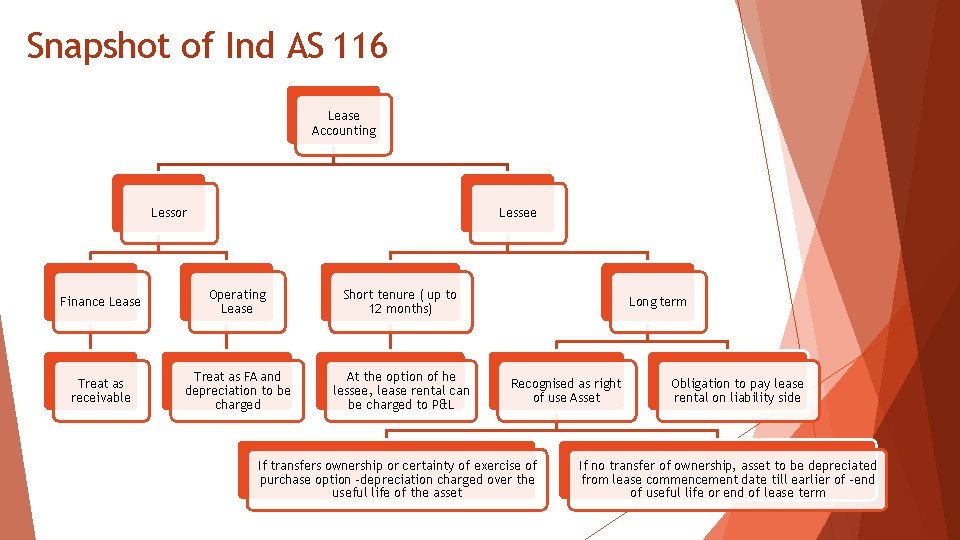
Snapshot of Ind AS 116 Lease Accounting Lessor Lessee Finance Lease Operating Lease Short tenure ( up to 12 months) Treat as receivable Treat as FA and depreciation to be charged At the option of he lessee, lease rental can be charged to P&L Long term Recognised as right of use Asset If transfers ownership or certainty of exercise of purchase option –depreciation charged over the useful life of the asset Obligation to pay lease rental on liability side If no transfer of ownership, asset to be depreciated from lease commencement date till earlier of –end of useful life or end of lease term
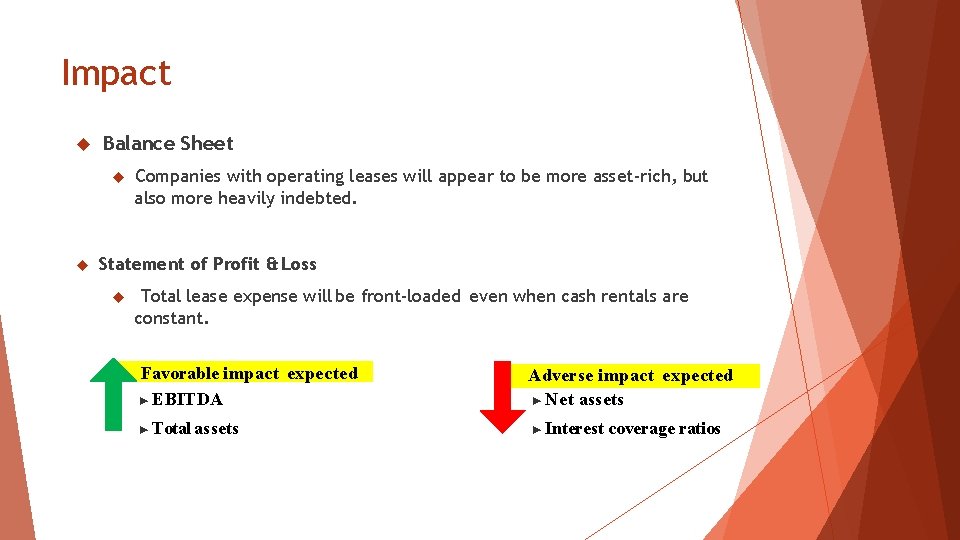
Impact Balance Sheet Companies with operating leases will appear to be more asset-rich, but also more heavily indebted. Statement of Profit & Loss Total lease expense will be front-loaded even when cash rentals are constant. Favorable impact expected ► EBITDA Adverse impact expected ► Net assets ► Total assets ► Interest coverage ratios
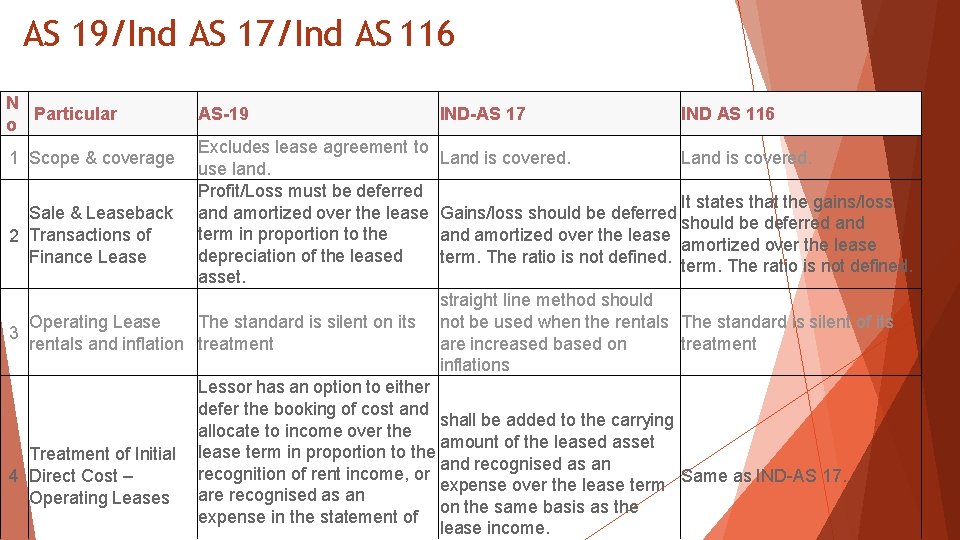
AS 19/Ind AS 17/Ind AS 116 N Particular o 1 Scope & coverage Sale & Leaseback 2 Transactions of Finance Lease 3 AS-19 Excludes lease agreement to use land. Profit/Loss must be deferred and amortized over the lease term in proportion to the depreciation of the leased asset. Operating Lease The standard is silent on its rentals and inflation treatment Treatment of Initial 4 Direct Cost – Operating Leases IND-AS 17 IND AS 116 Land is covered. It states that the gains/loss Gains/loss should be deferred and amortized over the lease term. The ratio is not defined. straight line method should not be used when the rentals The standard is silent of its are increased based on treatment inflations Lessor has an option to either defer the booking of cost and shall be added to the carrying allocate to income over the amount of the leased asset lease term in proportion to the and recognised as an recognition of rent income, or Same as IND-AS 17. expense over the lease term are recognised as an on the same basis as the expense in the statement of lease income.
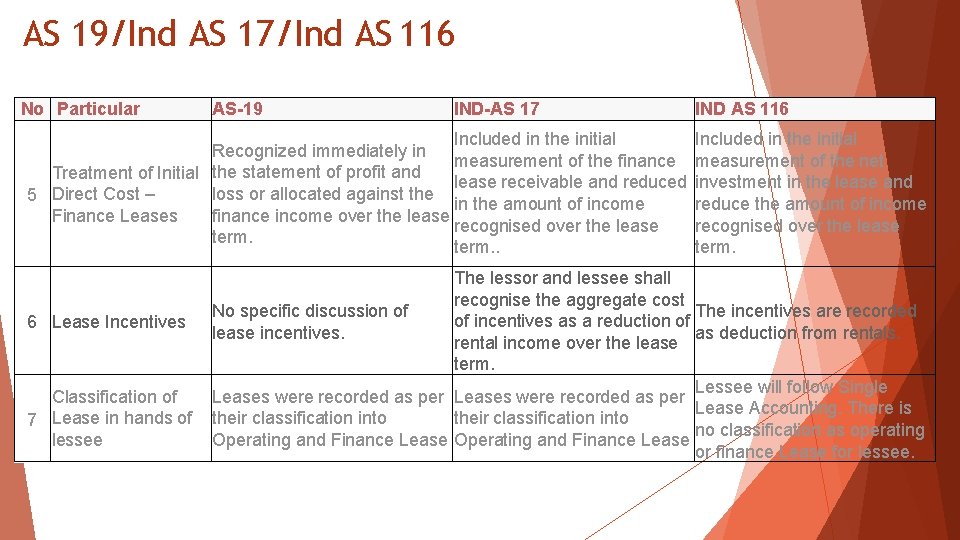
AS 19/Ind AS 17/Ind AS 116 No Particular AS-19 IND-AS 17 Included in the initial Recognized immediately in measurement of the finance Treatment of Initial the statement of profit and lease receivable and reduced loss or allocated against the 5 Direct Cost – in the amount of income finance income over the lease Finance Leases recognised over the lease term. . 6 Lease Incentives Classification of 7 Lease in hands of lessee IND AS 116 Included in the initial measurement of the net investment in the lease and reduce the amount of income recognised over the lease term. The lessor and lessee shall recognise the aggregate cost No specific discussion of The incentives are recorded of incentives as a reduction of lease incentives. as deduction from rentals. rental income over the lease term. Lessee will follow Single Leases were recorded as per Lease Accounting. There is their classification into no classification as operating Operating and Finance Lease or finance Lease for lessee.
AS 19/Ind AS 17/Ind AS 116 No Particular AS-19 IND-AS 17 IND AS 116 Lessee will recognize assets and liabilities for all leases with a term of more than 12 months, unless the underlying asset is of low value. Accounting and Under Operating lease, asset Under Operating lease, Presentation in was not recorded in books assets was not recorded in and recognized lease books and recognized lease 8 financial Statement Lessee would recognize by lessee by payments as expense in the depreciation expense on the lessee profit and loss account right of use asset and interest expense on the lease liability, classify the lease payments into principal and interest component.
AS 19/Ind AS 17/Ind AS 116 No Particular AS-19 IND-AS 17 Disclosures 9 Requirements of lessor Exemption granted to small and medium sized Exemption removed. companies for certain disclosures. Disclosures 10 Requirements of lessee NA NA IND AS 116 Additional Requirements of disclosure for lessor such as disclosure of maturity analysis of lease payments; quantitative and qualitative explanation of significant changes in carrying amount of new investment in finance lease. Additional requirements as disclosure of maturity analysis of lease payments; quantitative and qualitative explanation of significant changes in carrying amount of new investment in finance leases.
- Slides: 19