
IMPERFECTIONS OF CDOS VALUATION Petra Beneov Institute of
IMPERFECTIONS OF CDO’S VALUATION Petra Benešová Institute of Economic Studies, Faculty of Social Sciences Charles University in Prague, Czech Republic 24 November 2009
Agenda 1. Introduction 2. Basic Principles of CDOs 3. 4. One Factor Gaussian Copula Model Results of the Model 5. Main Flaws of the CDO Market 6. Conclusion 24 November 2009 Imperfections of CDO's Valuation 2
Introduction Definition of CDO Defininion of a CDO (collateralized debt obligation): “A structured credit security backed by a pool of securities, loans, or credit default swaps, where securitized interests in the security are divided into tranches with differing repayment and interest earning streams. ” - Source: Global Financial Stability report, IMF, 2008 24 November 2009 Imperfections of CDO's Valuation 3
Agenda 1. Introduction 2. Basic Principles of CDOs 3. 4. One Factor Gaussian Copula Model Results of the Model 5. Main Flaws of the CDO Market 6. Conclusion 24 November 2009 Imperfections of CDO's Valuation 4
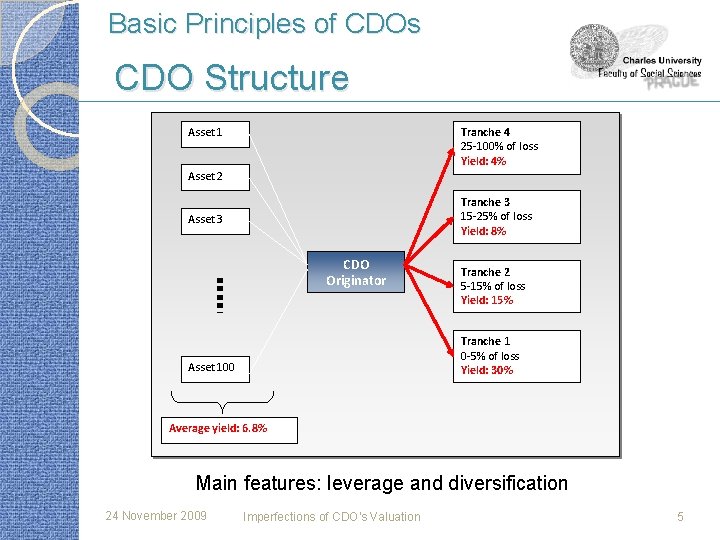
Basic Principles of CDOs CDO Structure Asset 1 Tranche 4 25 -100% of loss Yield: 4% Asset 2 Tranche 3 15 -25% of loss Yield: 8% Asset 3 CDO Originator Tranche 2 5 -15% of loss Yield: 15% Tranche 1 0 -5% of loss Yield: 30% Asset 100 Average yield: 6. 8% Main features: leverage and diversification 24 November 2009 Imperfections of CDO's Valuation 5
Basic Principles of CDOs Motivation Motives for an originator (CDO seller): 1. Transfer of a credit risk (original purpose) 2. Capital relief and liquidity 3. Arbitrage opportunity (main purpose) Motives for an investor (CDO buyer): 1. Standardization 2. Liquidity 3. Diversification 24 November 2009 Imperfections of CDO's Valuation 6
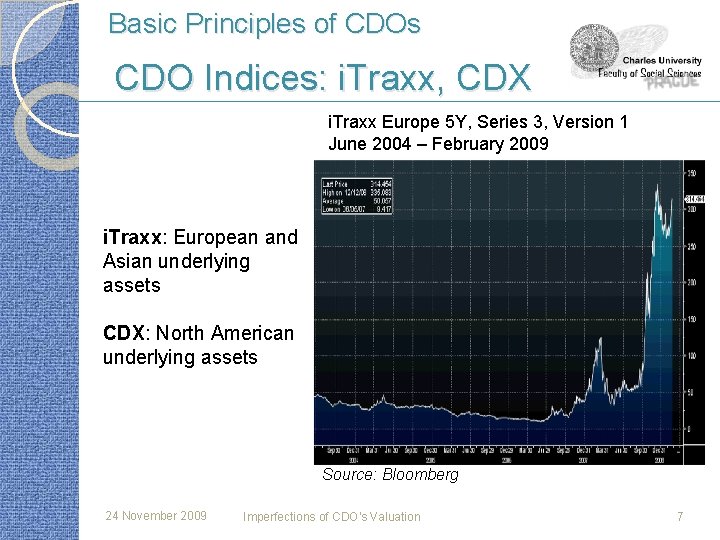
Basic Principles of CDOs CDO Indices: i. Traxx, CDX i. Traxx Europe 5 Y, Series 3, Version 1 June 2004 – February 2009 i. Traxx: European and Asian underlying assets CDX: North American underlying assets Source: Bloomberg 24 November 2009 Imperfections of CDO's Valuation 7
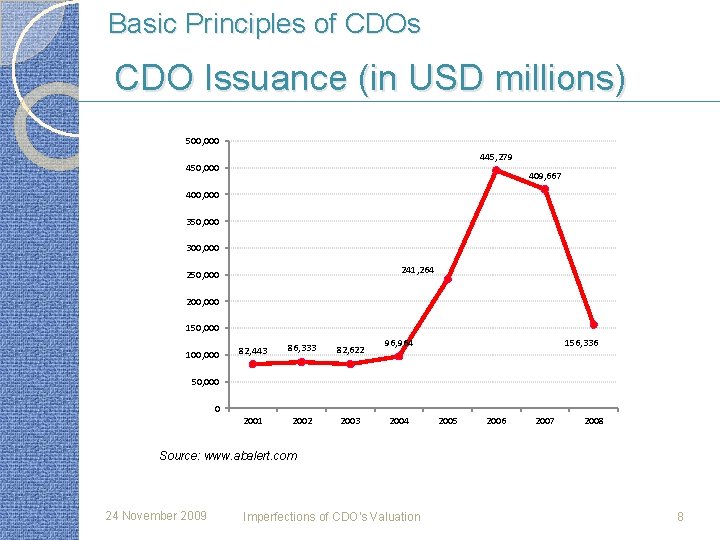
Basic Principles of CDOs CDO Issuance (in USD millions) 500, 000 445, 279 450, 000 409, 667 400, 000 350, 000 300, 000 241, 264 250, 000 200, 000 150, 000 100, 000 82, 443 86, 333 82, 622 2001 2002 2003 96, 964 156, 336 50, 000 0 2004 2005 2006 2007 2008 Source: www. abalert. com 24 November 2009 Imperfections of CDO's Valuation 8
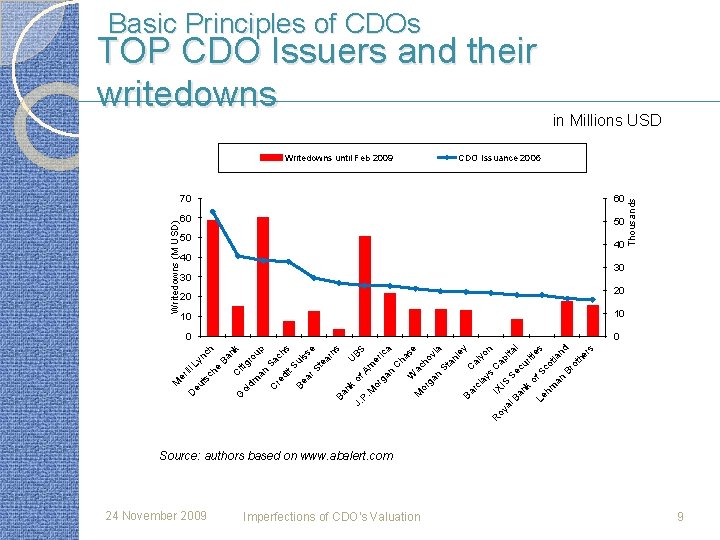
Basic Principles of CDOs TOP CDO Issuers and their writedowns 60 60 50 50 40 40 Thousands CDO Issuance 2006 70 30 30 20 20 10 0 0 G ol C iti Ba e nc ch Ly eu ts ill M er D nk g ro dm an up Sa C re ch di t. S s ui Be ss ar e St ea rn s Ba nk U BS of J. P. M Am e or ga rica n C ha s W ac e M or ho ga vi n a St an le y Ba C rc al yo la ys n R C oy IXI a pi S al Ba Se tal nk cur iti of es Le Sc hm ot la an nd Br ot he rs 10 h Writedowns (M USD) Writedowns until Feb 2009 in Millions USD Source: authors based on www. abalert. com 24 November 2009 Imperfections of CDO's Valuation 9
Agenda 1. Introduction 2. Basic Principles of CDOs 3. 4. One Factor Gaussian Copula Model Results of the Model 5. Main Flaws of the CDO Market 6. Conclusion 24 November 2009 Imperfections of CDO's Valuation 10
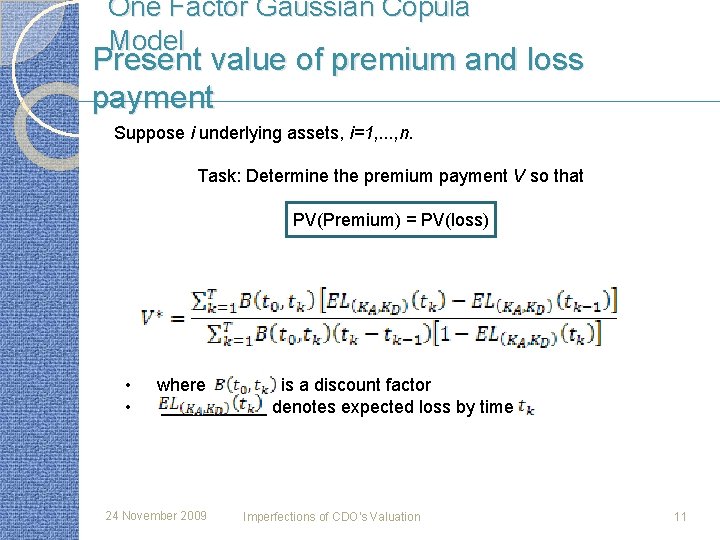
One Factor Gaussian Copula Model Present value of premium and loss payment Suppose i underlying assets, i=1, . . . , n. Task: Determine the premium payment V so that PV(Premium) = PV(loss) • • where 24 November 2009 is a discount factor denotes expected loss by time Imperfections of CDO's Valuation 11
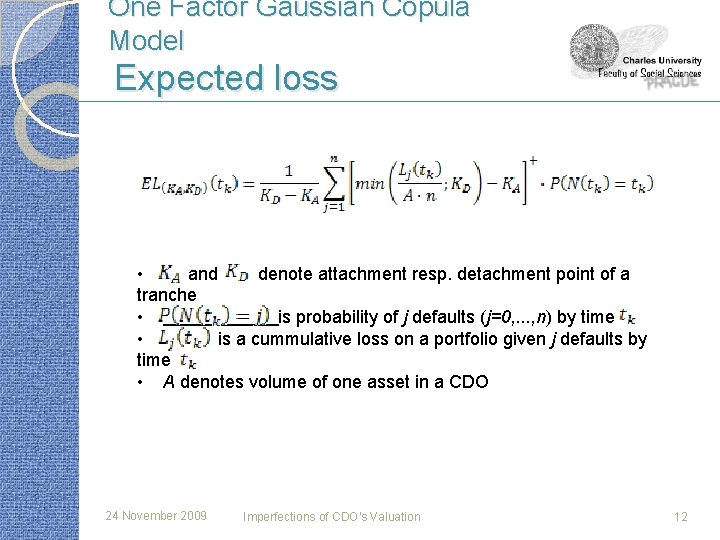
One Factor Gaussian Copula Model Expected loss • and denote attachment resp. detachment point of a tranche • is probability of j defaults (j=0, . . . , n) by time • is a cummulative loss on a portfolio given j defaults by time • A denotes volume of one asset in a CDO 24 November 2009 Imperfections of CDO's Valuation 12
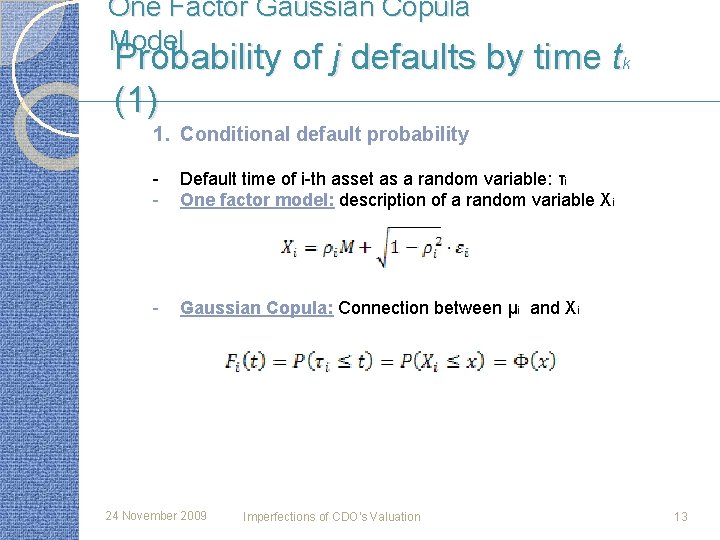
One Factor Gaussian Copula Model Probability of j defaults by time tk (1) 1. Conditional default probability - Default time of i-th asset as a random variable: τi One factor model: description of a random variable Xi - Gaussian Copula: Connection between μi and Xi 24 November 2009 Imperfections of CDO's Valuation 13
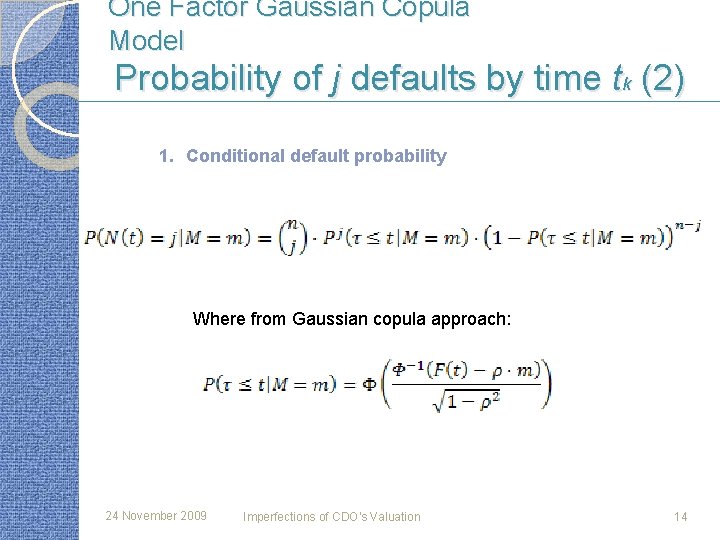
One Factor Gaussian Copula Model Probability of j defaults by time tk (2) 1. Conditional default probability Where from Gaussian copula approach: 24 November 2009 Imperfections of CDO's Valuation 14
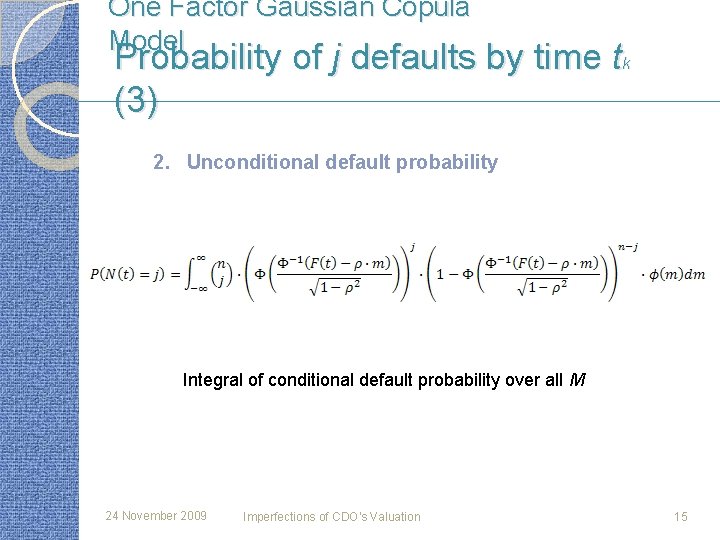
One Factor Gaussian Copula Model Probability of j defaults by time tk (3) 2. Unconditional default probability Integral of conditional default probability over all M 24 November 2009 Imperfections of CDO's Valuation 15
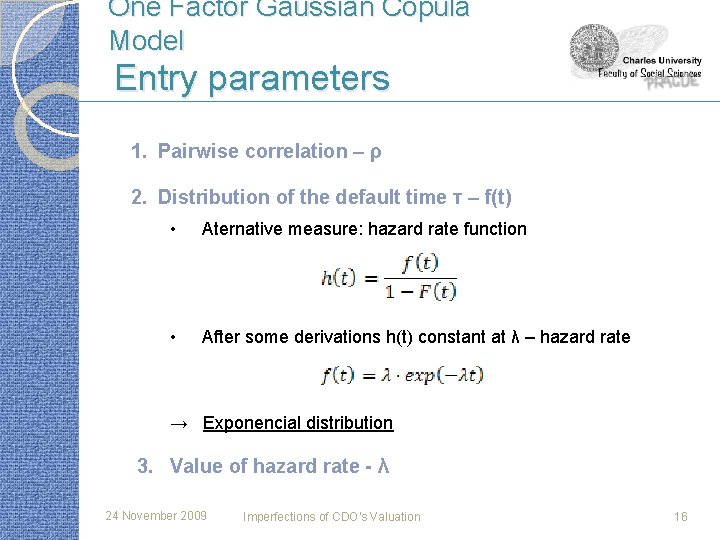
One Factor Gaussian Copula Model Entry parameters 1. Pairwise correlation – ρ 2. Distribution of the default time τ – f(t) • Aternative measure: hazard rate function • After some derivations h(t) constant at λ – hazard rate → Exponencial distribution 3. Value of hazard rate - λ 24 November 2009 Imperfections of CDO's Valuation 16
Agenda 1. Introduction 2. Basic Principles of CDOs 3. One Factor Gaussian Copula Model 4. Results of the Model 5. Main Flaws of the CDO Market 6. Conclusion 24 November 2009 Imperfections of CDO's Valuation 17
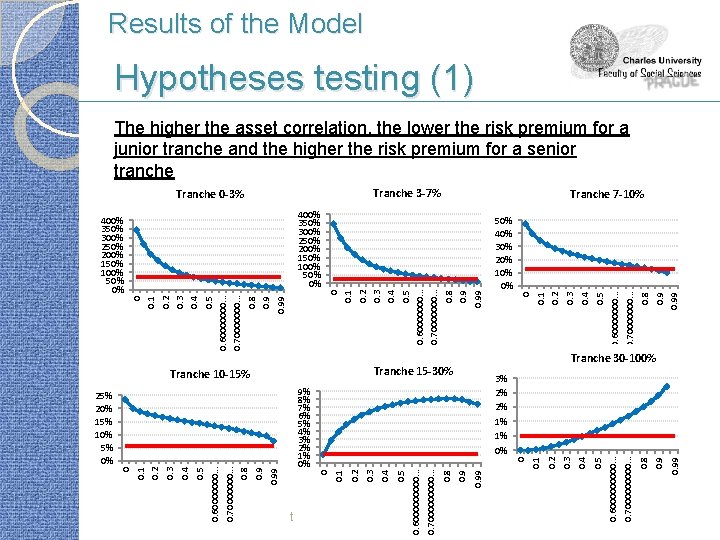
Results of the Model Hypotheses testing (1) The higher the asset correlation, the lower the risk premium for a junior tranche and the higher the risk premium for a senior tranche Tranche 3 -7% 0 0. 1 0. 2 0. 3 0. 4 0. 5 0. 60000000. . . 0. 70000000. . . 0. 8 0. 99 0. 8 0. 700000. . . 0. 5 0. 4 0. 3 0. 600000. . . 0. 99 0. 8 0. 2 3% 2% 2% 1% 1% 0% 0 Imperfections of CDO's Valuation 0. 700000. . . 0. 5 0. 4 0. 3 0. 2 0. 1 0. 600000. . . 24 November 2009 9% 8% 7% 6% 5% 4% 3% 2% 1% 0% 0 0 0. 1 0. 2 0. 3 0. 4 0. 5 0. 60000000. . . 0. 70000000. . . 0. 8 0. 99 25% 20% 15% 10% 5% 0% Tranche 30 -100% Tranche 15 -30% Tranche 10 -15% 50% 40% 30% 20% 10% 0% 0. 1 400% 350% 300% 250% 200% 150% 100% 50% 0% 0 0. 1 0. 2 0. 3 0. 4 0. 5 0. 60000000. . . 0. 70000000. . . 0. 8 0. 99 400% 350% 300% 250% 200% 150% 100% 50% 0% Tranche 7 -10% 0 0. 1 0. 2 0. 3 0. 4 0. 5 0. 60000000. . . 0. 70000000. . . 0. 8 0. 99 Tranche 0 -3% 18
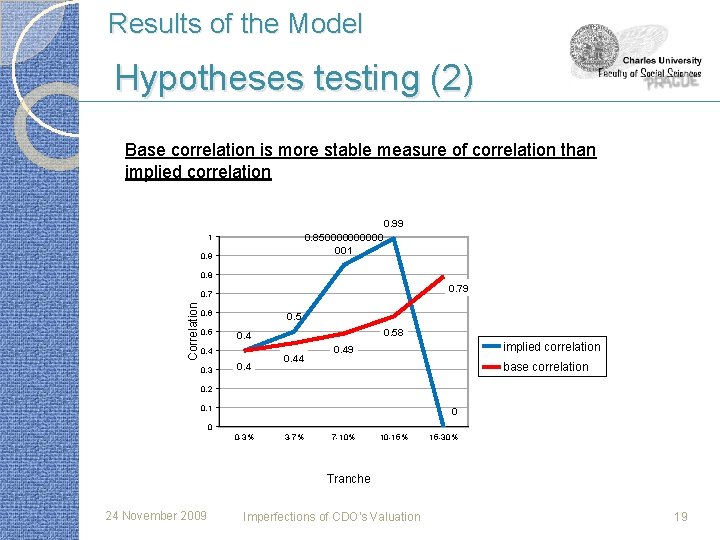
Results of the Model Hypotheses testing (2) Base correlation is more stable measure of correlation than implied correlation 0. 99 0. 8500000 001 1 0. 9 0. 8 0. 79 Correlation 0. 7 0. 6 0. 5 0. 4 0. 3 0. 58 0. 44 implied correlation 0. 49 base correlation 0. 2 0. 1 0 0 0 -3% 3 -7% 7 -10% 10 -15% 15 -30% Tranche 24 November 2009 Imperfections of CDO's Valuation 19
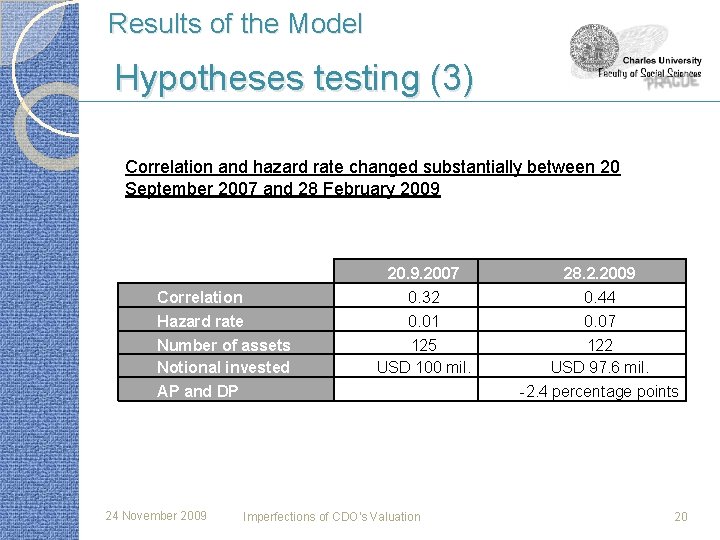
Results of the Model Hypotheses testing (3) Correlation and hazard rate changed substantially between 20 September 2007 and 28 February 2009 Correlation Hazard rate Number of assets Notional invested AP and DP 24 November 2009 20. 9. 2007 28. 2. 2009 0. 32 0. 44 0. 01 125 USD 100 mil. 0. 07 122 USD 97. 6 mil. -2. 4 percentage points Imperfections of CDO's Valuation 20
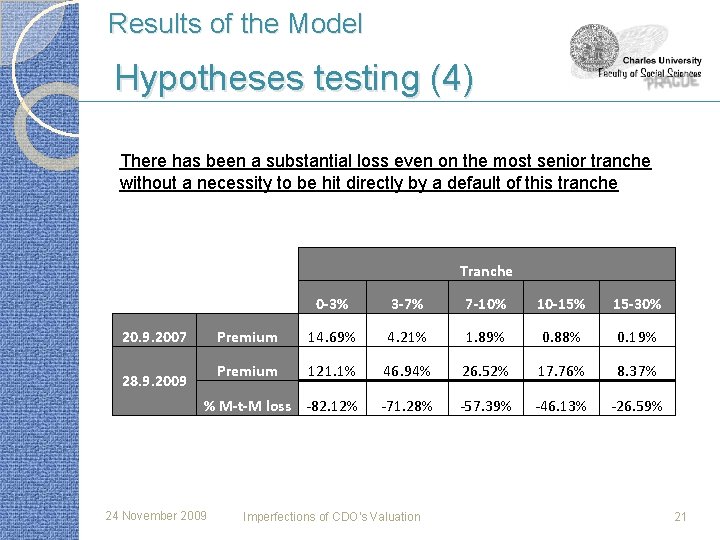
Results of the Model Hypotheses testing (4) There has been a substantial loss even on the most senior tranche without a necessity to be hit directly by a default of this tranche Tranche 0 -3% 3 -7% 7 -10% 10 -15% 15 -30% Premium 14. 69% 4. 21% 1. 89% 0. 88% 0. 19% Premium 121. 1% 46. 94% 26. 52% 17. 76% 8. 37% % M-t-M loss -82. 12% -71. 28% -57. 39% -46. 13% -26. 59% 20. 9. 2007 28. 9. 2009 24 November 2009 Imperfections of CDO's Valuation 21
Agenda 1. Introduction 2. Basic Principles of CDOs 3. One Factor Gaussian Copula Model 4. Results of the Model 5. Main Flaws of the CDO Market 6. Conclusion 24 November 2009 Imperfections of CDO's Valuation 22
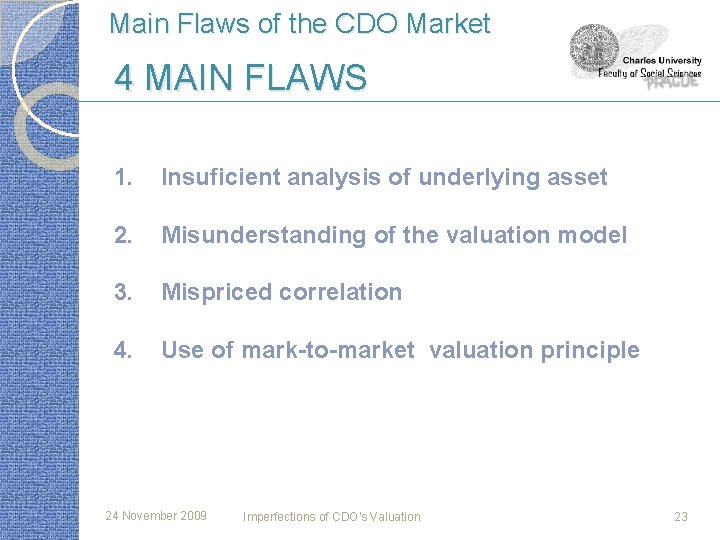
Main Flaws of the CDO Market 4 MAIN FLAWS 1. Insuficient analysis of underlying asset 2. Misunderstanding of the valuation model 3. Mispriced correlation 4. Use of mark-to-market valuation principle 24 November 2009 Imperfections of CDO's Valuation 23
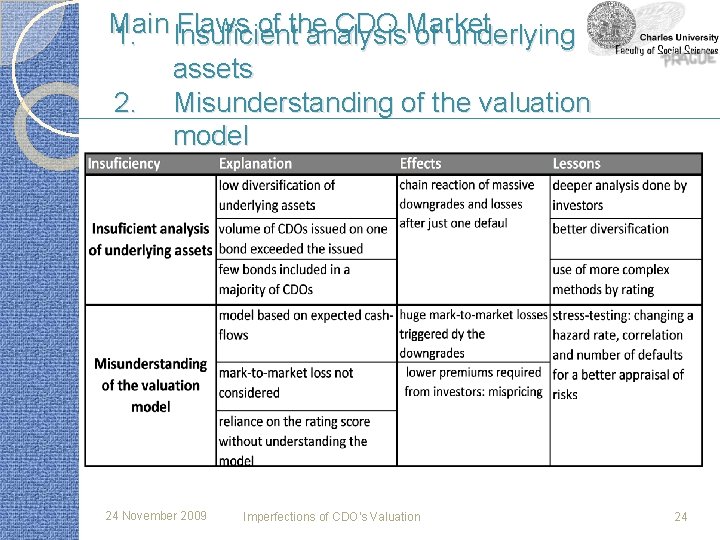
Main Flaws of the CDO Market 1. Insuficient analysis of underlying assets 2. Misunderstanding of the valuation model 24 November 2009 Imperfections of CDO's Valuation 24
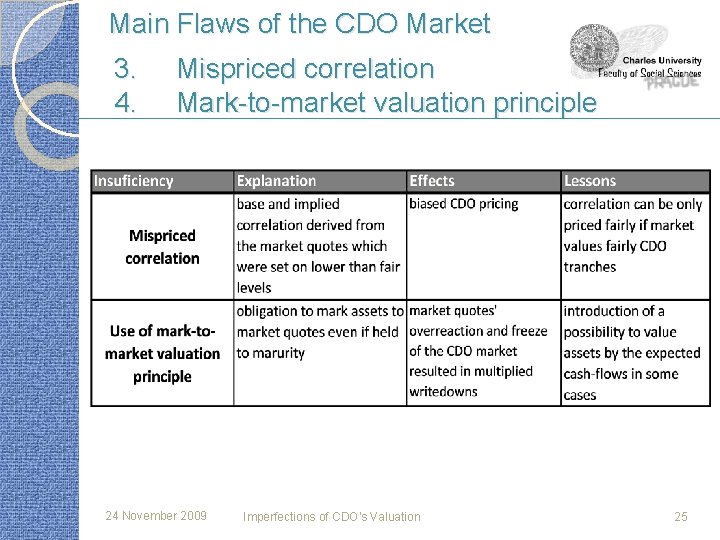
Main Flaws of the CDO Market 3. 4. Mispriced correlation Mark-to-market valuation principle 24 November 2009 Imperfections of CDO's Valuation 25
Agenda 1. Introduction 2. Basic Principles of CDOs 3. One Factor Gaussian Copula Model 4. Results of the Model 5. Main Flaws of the CDO Market 6. Conclusion 24 November 2009 Imperfections of CDO's Valuation 26
Conclusion ü CDO market has a chance to be regenerated. ü Securitization and credit market is needed, but the trades have to be done rationally and deliberately. ü A future CDO market would then be more conscious, driven by smarter motives and definitely less extensive. 24 November 2009 Imperfections of CDO's Valuation 27
Discussion Thanks for your attention. Let´s discuss it now! 24 November 2009 Imperfections of CDO's Valuation 28
Contact Petra Benešová Institute of Economic Studies Faculty of Social Sciences Charles University Opletalova str. 26 110 00 Prague Czech Republic E-mail: benesova_p@seznam. cz http: //ies. fsv. cuni. cz 24 November 2009 Imperfections of CDO's Valuation 29
- Slides: 29