
http wps prenhall comwpsmediaobjects438448710ch 21 ppt CHAPTER 21
http: //wps. prenhall. com/wps/media/objects/438/448710/ch 21. ppt CHAPTER 21 Completing the Audit Copyright 2003 Pearson Education Canada Inc. 21 - 1
Audit Completion Procedures Search for unrecorded contingent liabilities. What is a contingent liability and what are the relevant related GAAP recommendations? Copyright 2003 Pearson Education Canada Inc. 21 - 2
Audit Completion Procedures Search for unrecorded contingent liabilities. What is a contingent liability and what are the relevant GAAP recommendations? a potential future obligation to an outside party for an unknown amount resulting from activities that have already taken place Copyright 2003 Pearson Education Canada Inc. 21 - 3
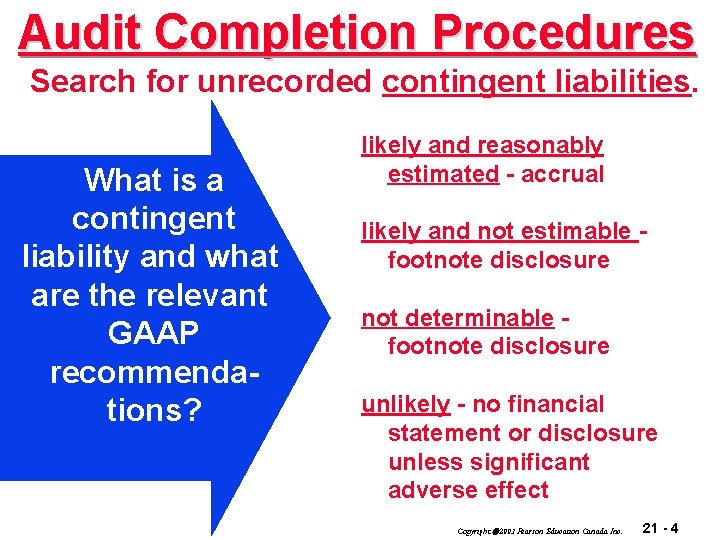
Audit Completion Procedures Search for unrecorded contingent liabilities. What is a contingent liability and what are the relevant GAAP recommendations? likely and reasonably estimated - accrual likely and not estimable footnote disclosure not determinable footnote disclosure unlikely - no financial statement or disclosure unless significant adverse effect Copyright 2003 Pearson Education Canada Inc. 21 - 4
Audit Completion Procedures Search for unrecorded contingent liabilities. What is a contingent liability and what are the related GAAP recommendations? Footnote disclosure should describe the contingency and the opinion of legal counsel or management regarding the expected outcome. Copyright 2003 Pearson Education Canada Inc. 21 - 5
Audit Completion Procedures Search for unrecorded contingent liabilities. - enquire of management Copyright 2003 Pearson Education Canada Inc. 21 - 6
Audit Completion Procedures Search for unrecorded contingent liabilities. - enquire of management - review: ~ client copies of Revenue Canada correspondence ~ minutes of board and shareholder meetings ~ invoices from client lawyers ~ existing audit workpapers ~ contracts, agreements, etc. Copyright 2003 Pearson Education Canada Inc. 21 - 7
Audit Completion Procedures Search for unrecorded contingent liabilities. - enquire of management - review: ~ client copies of Revenue Canada correspondence ~ minutes of board and shareholder meetings ~ invoices from client lawyers ~ existing audit work papers ~ contracts, agreements, etc. - obtain letters of confirmation from all client lawyers Joe Lawyer Canada 48 Jill Auditor, CA Copyright 2003 Pearson Education Canada Inc. 21 - 8
Lawyer Enquiry The auditor should ask the client to prepare a letter (on client letterhead, signed by client officer) asking the lawyer to respond directly to the auditor concerning: Copyright 2003 Pearson Education Canada Inc. 21 - 9
Lawyer Enquiry The auditor should ask the client to prepare a letter (on client letterhead, signed by client officer) asking the lawyer to respond directly to the client with a copy to the auditor concerning: - client’s description of the nature & current status of all outstanding & possible claims with which the lawyer has been involved Copyright 2003 Pearson Education Canada Inc. 21 - 10
Lawyer Enquiry The auditor should ask the client to prepare a letter (on client letterhead, signed by client officer) asking the lawyer to respond directly to the auditor concerning: - client’s description of the nature & current status of all outstanding & possible claims with which the lawyer has been involved - client’s evaluation of the amount & likelihood of loss or gain for each listed outstanding & possible claim Copyright 2003 Pearson Education Canada Inc. 21 - 11
Lawyer Enquiry The auditor should ask the client to prepare a letter (on client letterhead, signed by client officer) asking the lawyer to respond directly to the auditor concerning: - client’s description of the nature & current status of all outstanding & possible claims with which the lawyer has been involved - client’s evaluation of the amount & likelihood of loss or gain for each listed outstanding & possible claim - any unlisted or potential items, or whether the status of each claim or assessment Copyright 2003 Pearson Education Canada Inc. 21 - 12
Lawyer Enquiry If an lawyer refuses to respond or refuses to provide adequate information, the audit opinion will be qualified or denied. Copyright 2003 Pearson Education Canada Inc. 21 - 13
Review for Subsequent Events ? Copyright 2003 Pearson Education Canada Inc. 21 - 14
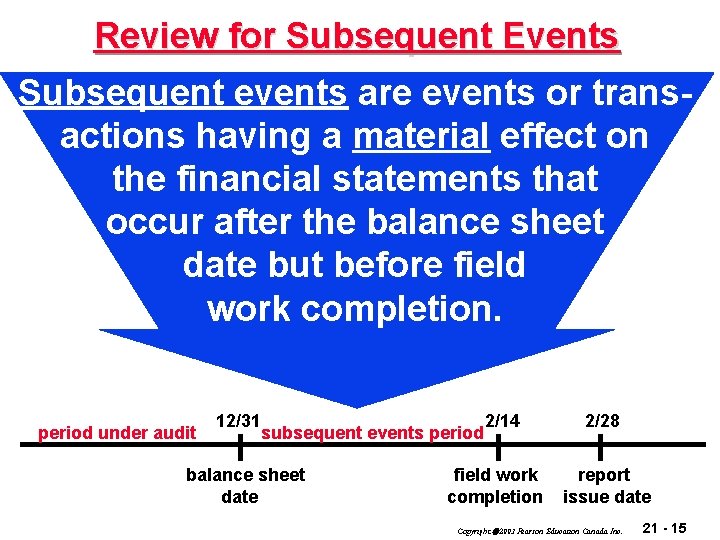
Review for Subsequent Events Subsequent events are events or transactions having a material effect on the financial statements that occur after the balance sheet date but before field work completion. period under audit 12/31 2/14 subsequent events period balance sheet date field work completion 2/28 report issue date Copyright 2003 Pearson Education Canada Inc. 21 - 15
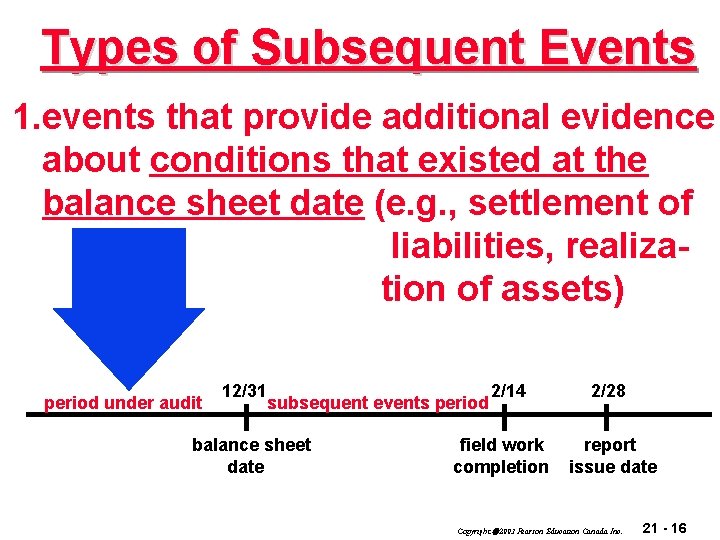
Types of Subsequent Events 1. events that provide additional evidence about conditions that existed at the balance sheet date (e. g. , settlement of liabilities, realization of assets) period under audit 12/31 2/14 subsequent events period balance sheet date field work completion 2/28 report issue date Copyright 2003 Pearson Education Canada Inc. 21 - 16
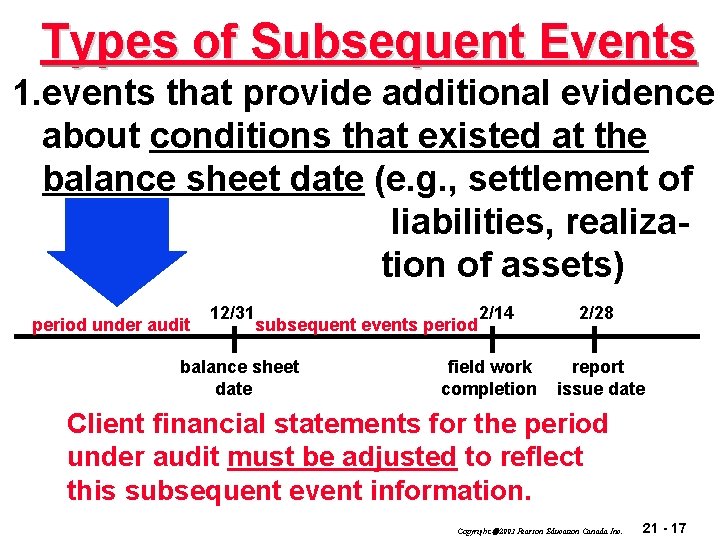
Types of Subsequent Events 1. events that provide additional evidence about conditions that existed at the balance sheet date (e. g. , settlement of liabilities, realization of assets) period under audit 12/31 2/14 subsequent events period balance sheet date field work completion 2/28 report issue date Client financial statements for the period under audit must be adjusted to reflect this subsequent event information. Copyright 2003 Pearson Education Canada Inc. 21 - 17
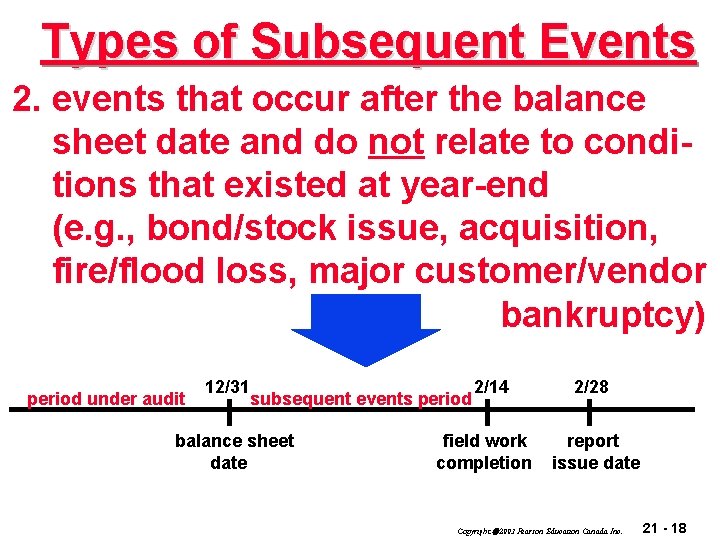
Types of Subsequent Events 2. events that occur after the balance sheet date and do not relate to conditions that existed at year-end (e. g. , bond/stock issue, acquisition, fire/flood loss, major customer/vendor bankruptcy) period under audit 12/31 2/14 subsequent events period balance sheet date field work completion 2/28 report issue date Copyright 2003 Pearson Education Canada Inc. 21 - 18
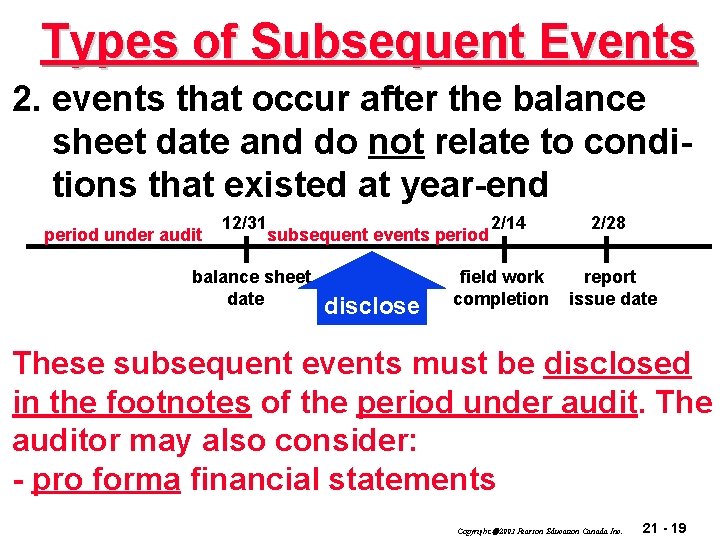
Types of Subsequent Events 2. events that occur after the balance sheet date and do not relate to conditions that existed at year-end period under audit 12/31 2/14 subsequent events period balance sheet date disclose field work completion 2/28 report issue date These subsequent events must be disclosed in the footnotes of the period under audit. The auditor may also consider: - pro forma financial statements Copyright 2003 Pearson Education Canada Inc. 21 - 19
Review for Subsequent Events What auditing procedures will identify subsequent events? Copyright 2003 Pearson Education Canada Inc. 21 - 20
Subsequent Events Auditing Procedures Near field work completion, auditors should: - read post-balance sheet interim statements and records Ace Company Financial Statements For the month of January 2005 Copyright 2003 Pearson Education Canada Inc. 21 - 21
Subsequent Events Auditing Procedures Near field work completion, auditors should: - read post-balance sheet interim statements and records - obtain a management representation letter and discuss with management: ~ contingent liabilities ~ significant changes in owners’ equity ~ items accounted for on tentative data ~ unusual adjustments in subsequent period Copyright 2003 Pearson Education Canada Inc. 21 - 22
Subsequent Events Auditing Procedures Near field work completion, auditors should: - read post-balance sheet interim statements and records - obtain a management representation letter - read minutes of board and shareholder meetings that have occurred since year-end Copyright 2003 Pearson Education Canada Inc. 21 - 23
Subsequent Events Auditing Procedures Near field work completion, auditors should: - read post-balance sheet interim statements and records - obtain a management representation letter - read minutes of board and shareholder meetings that have occurred since year-end - obtain letter from client’s lawyer Joe Lawyer Canada 48 Jill Auditor, CA Copyright 2003 Pearson Education Canada Inc. 21 - 24
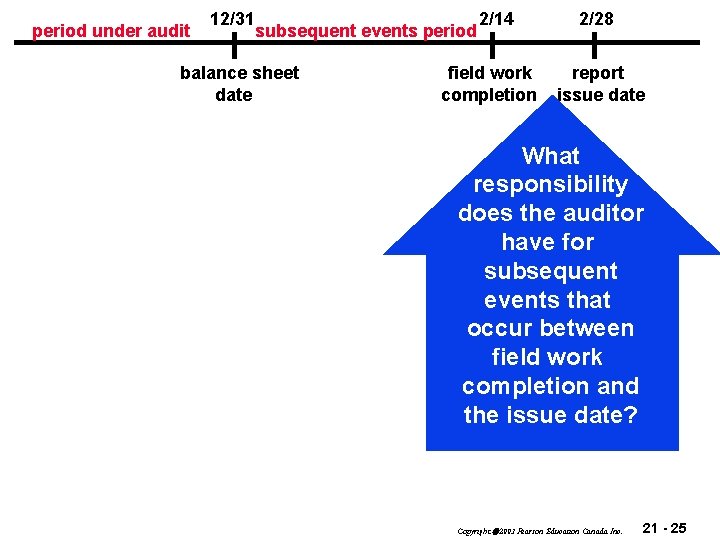
period under audit 12/31 2/14 subsequent events period balance sheet date field work completion 2/28 report issue date What responsibility does the auditor have for subsequent events that occur between field work completion and the issue date? Copyright 2003 Pearson Education Canada Inc. 21 - 25
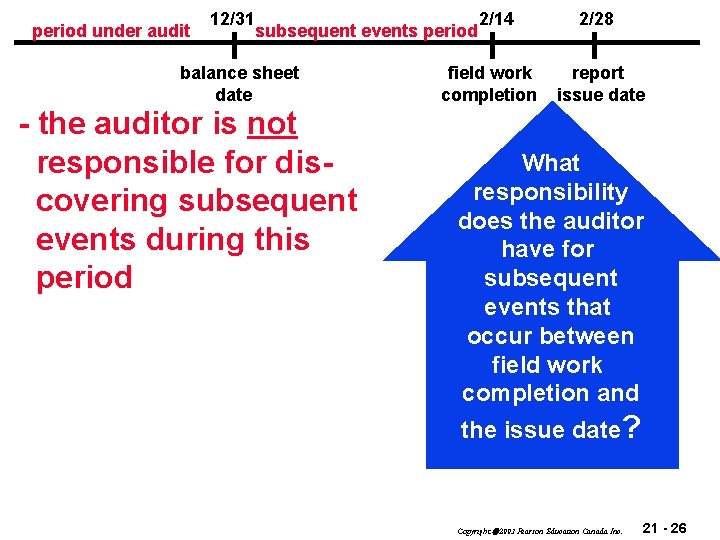
period under audit 12/31 2/14 subsequent events period balance sheet date - the auditor is not responsible for discovering subsequent events during this period field work completion 2/28 report issue date What responsibility does the auditor have for subsequent events that occur between field work completion and the issue date? Copyright 2003 Pearson Education Canada Inc. 21 - 26
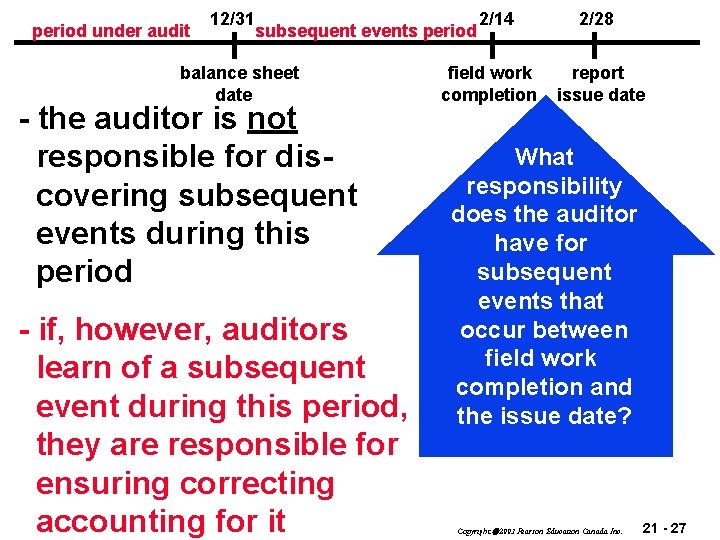
period under audit 12/31 2/14 subsequent events period balance sheet date - the auditor is not responsible for discovering subsequent events during this period - if, however, auditors learn of a subsequent event during this period, they are responsible for ensuring correcting accounting for it field work completion 2/28 report issue date What responsibility does the auditor have for subsequent events that occur between field work completion and the issue date? Copyright 2003 Pearson Education Canada Inc. 21 - 27
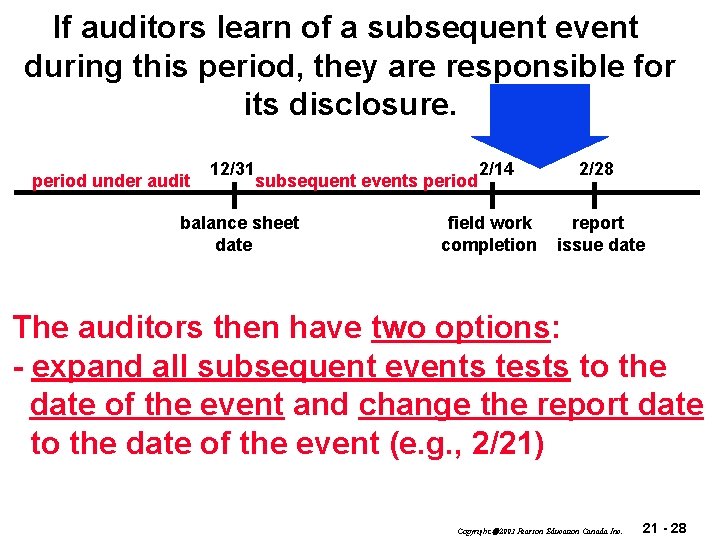
If auditors learn of a subsequent event during this period, they are responsible for its disclosure. period under audit 12/31 2/14 subsequent events period balance sheet date field work completion 2/28 report issue date The auditors then have two options: - expand all subsequent events tests to the date of the event and change the report date to the date of the event (e. g. , 2/21) Copyright 2003 Pearson Education Canada Inc. 21 - 28
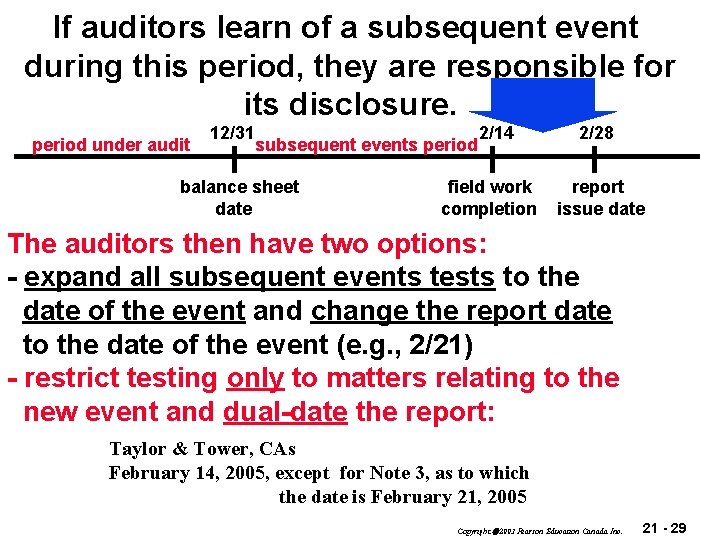
If auditors learn of a subsequent event during this period, they are responsible for its disclosure. period under audit 12/31 2/14 subsequent events period balance sheet date field work completion 2/28 report issue date The auditors then have two options: - expand all subsequent events tests to the date of the event and change the report date to the date of the event (e. g. , 2/21) - restrict testing only to matters relating to the new event and dual-date the report: Taylor & Tower, CAs February 14, 2005, except for Note 3, as to which the date is February 21, 2005 Copyright 2003 Pearson Education Canada Inc. 21 - 29
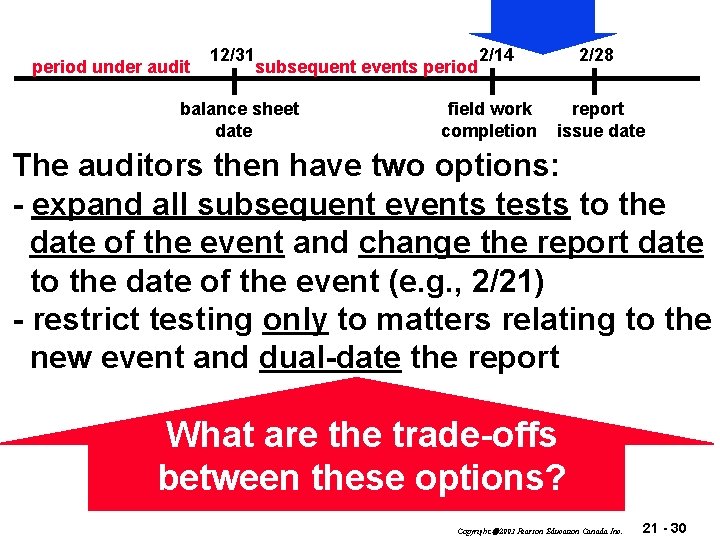
period under audit 12/31 2/14 subsequent events period balance sheet date field work completion 2/28 report issue date The auditors then have two options: - expand all subsequent events tests to the date of the event and change the report date to the date of the event (e. g. , 2/21) - restrict testing only to matters relating to the new event and dual-date the report What are the trade-offs between these options? Copyright 2003 Pearson Education Canada Inc. 21 - 30
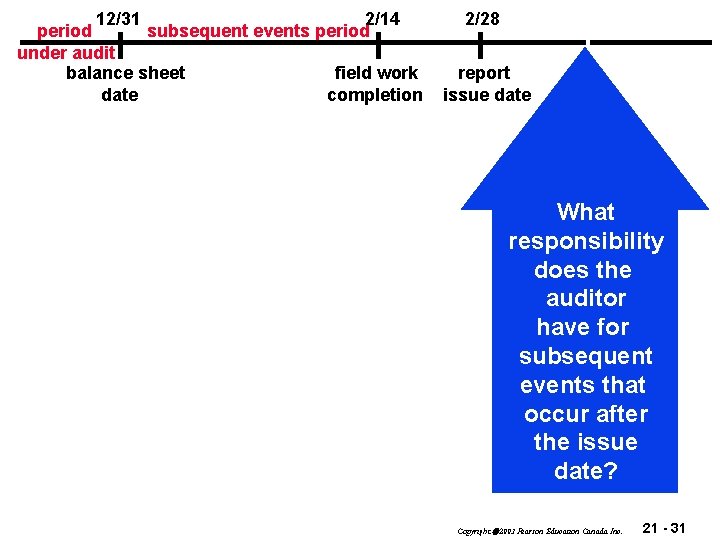
12/31 2/14 period subsequent events period under audit balance sheet field work date completion 2/28 report issue date What responsibility does the auditor have for subsequent events that occur after the issue date? Copyright 2003 Pearson Education Canada Inc. 21 - 31
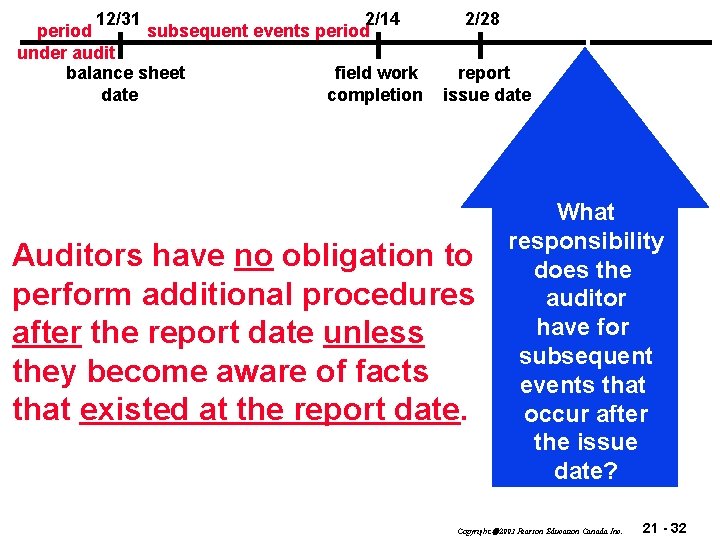
12/31 2/14 period subsequent events period under audit balance sheet field work date completion 2/28 report issue date Auditors have no obligation to perform additional procedures after the report date unless they become aware of facts that existed at the report date. What responsibility does the auditor have for subsequent events that occur after the issue date? Copyright 2003 Pearson Education Canada Inc. 21 - 32
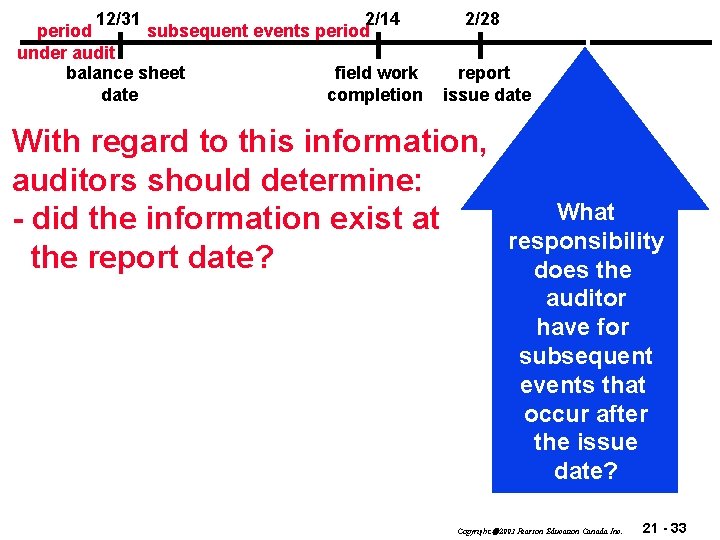
12/31 2/14 period subsequent events period under audit balance sheet field work date completion 2/28 report issue date With regard to this information, auditors should determine: - did the information exist at the report date? What responsibility does the auditor have for subsequent events that occur after the issue date? Copyright 2003 Pearson Education Canada Inc. 21 - 33
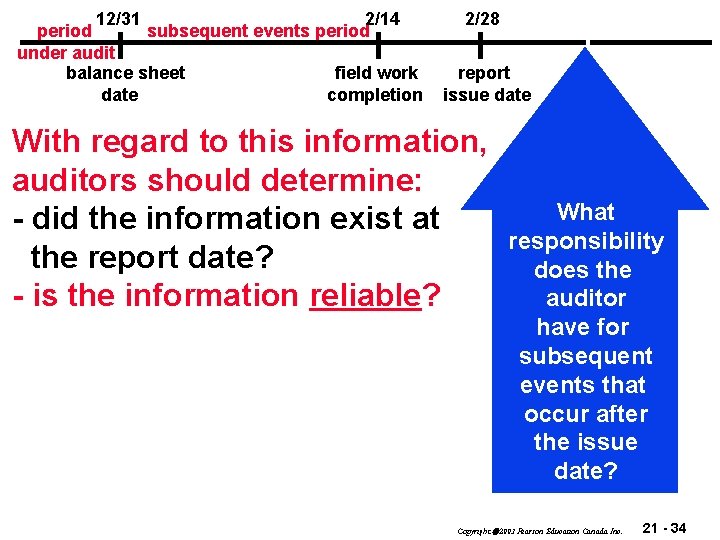
12/31 2/14 period subsequent events period under audit balance sheet field work date completion 2/28 report issue date With regard to this information, auditors should determine: - did the information exist at the report date? - is the information reliable? What responsibility does the auditor have for subsequent events that occur after the issue date? Copyright 2003 Pearson Education Canada Inc. 21 - 34
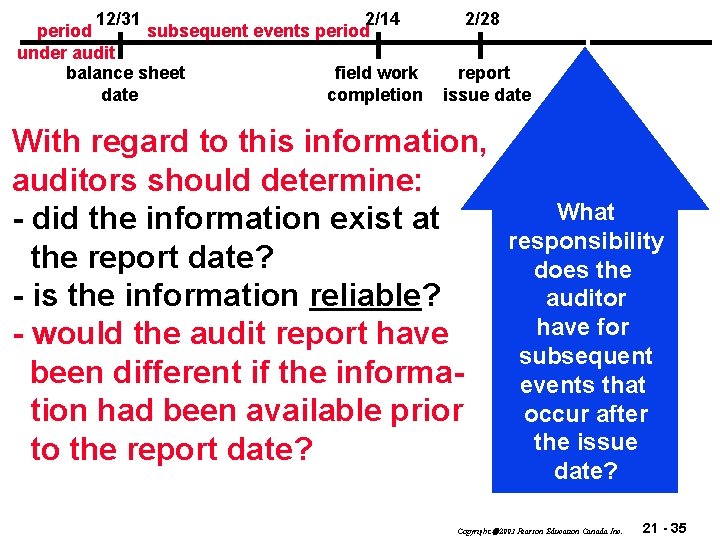
12/31 2/14 period subsequent events period under audit balance sheet field work date completion 2/28 report issue date With regard to this information, auditors should determine: - did the information exist at the report date? - is the information reliable? - would the audit report have been different if the information had been available prior to the report date? What responsibility does the auditor have for subsequent events that occur after the issue date? Copyright 2003 Pearson Education Canada Inc. 21 - 35
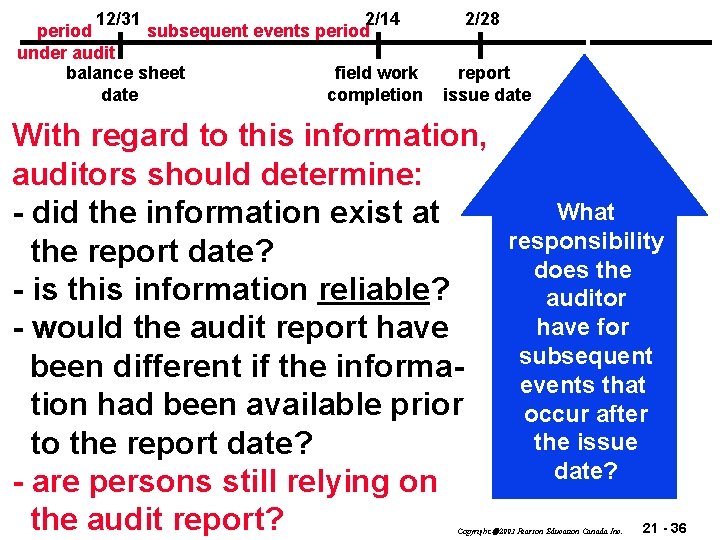
12/31 2/14 period subsequent events period under audit balance sheet field work date completion 2/28 report issue date With regard to this information, auditors should determine: - did the information exist at the report date? - is this information reliable? - would the audit report have been different if the information had been available prior to the report date? - are persons still relying on the audit report? What responsibility does the auditor have for subsequent events that occur after the issue date? Copyright 2003 Pearson Education Canada Inc. 21 - 36
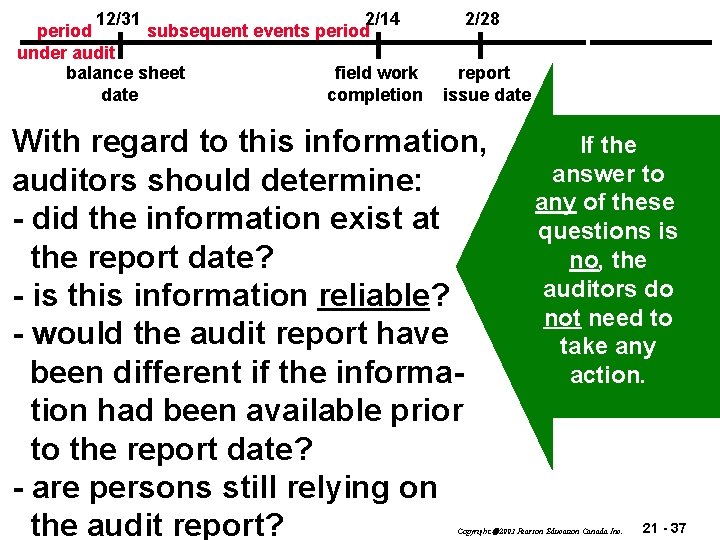
12/31 2/14 period subsequent events period under audit balance sheet field work date completion 2/28 report issue date With regard to this information, auditors should determine: - did the information exist at the report date? - is this information reliable? - would the audit report have been different if the information had been available prior to the report date? - are persons still relying on the audit report? If the answer to any of these questions is no, the auditors do not need to take any action. Copyright 2003 Pearson Education Canada Inc. 21 - 37
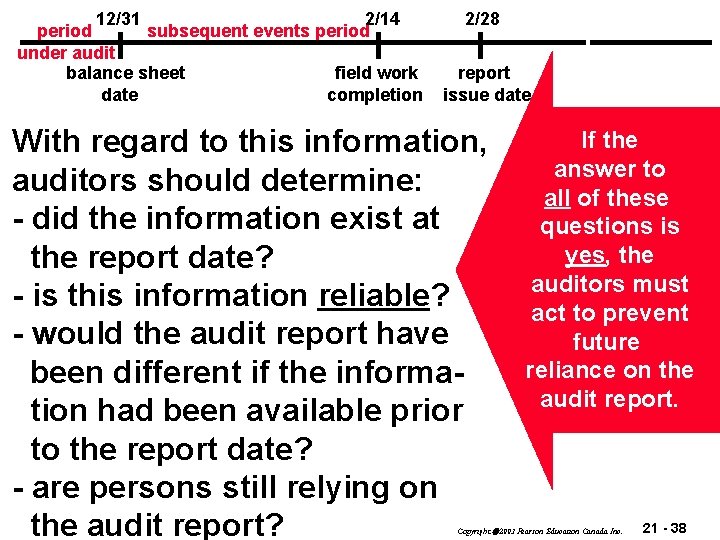
12/31 2/14 period subsequent events period under audit balance sheet field work date completion 2/28 report issue date With regard to this information, auditors should determine: - did the information exist at the report date? - is this information reliable? - would the audit report have been different if the information had been available prior to the report date? - are persons still relying on the audit report? If the answer to all of these questions is yes, the auditors must act to prevent future reliance on the audit report. Copyright 2003 Pearson Education Canada Inc. 21 - 38
How do auditors prevent future reliance on a previously-issued audit report? Auditors’ Report ggsfggsfrrff fsfftershj dytudtyiuhhfd fjty 7 yh rngag dgaroihaongn faidfnad faosdfnandsfafd ggsfggsfrrff fsfftershj dytudtyiuhhfd fjty 7 yh rngag dgaroihaongn faidfnad faosdfnandsfafd ggsfrrff fsfftershj dytudtyiuhhfd fjty 7 yh rngag dgaroihaongn faidfnad faosdfnandsfafd Copyright 2003 Pearson Education Canada Inc. 21 - 39
How do auditors prevent future reliance on a previously-issued audit report? If the financial statement effect of the subsequently-discovered information can be determined promptly the client must revise and reissue the financial statements Copyright 2003 Pearson Education Canada Inc. 21 - 40
How do auditors prevent future reliance on a previously-issued audit report? If the financial statement effect of the subsequently-discovered information cannot be determined promptly the client must notify persons known to be (and those likely to be) relying on the financial statements Copyright 2003 Pearson Education Canada Inc. 21 - 41
What should the auditor do if the client refuses to reissue the statements or contact those relying on the auditors’ report? revise and reissue? NO! Copyright 2003 Pearson Education Canada Inc. 21 - 42
What should the auditor do if the client refuses to reissue the statements or contact those relying on the auditors’ report? -first, notify the audit committee, or other body, such as the board, of management’s refusal Copyright 2003 Pearson Education Canada Inc. 21 - 43
What should the auditor do if the client refuses to reissue the statements or contact those relying on the auditors’ report? - first, notify the audit committee, etc. of management’s refusal - then: ~ inform client management that the audit report may no longer be associated with the statements Copyright 2003 Pearson Education Canada Inc. 21 - 44
What should the auditor do if the client refuses to reissue the statements or contact those relying on the auditors’ report? - first, notify the audit committee, etc. of management’s refusal - then: ~ inform client management that the audit report may no longer be associated with the statements ~ consider obtaining legal advice Copyright 2003 Pearson Education Canada Inc. 21 - 45
What should the auditor do if the client refuses to reissue the statements or contact those relying on the auditors’ report? - first, notify the audit committee, etc. of management’s refusal - then: ~ inform client management that the audit report may no longer be associated with the statements ~ consider obtaining legal advice ~ consider the appropriateness of other actions such as withdrawing Copyright 2003 Pearson Education Canada Inc. 21 - 46
Client Representation Letter ? Copyright 2003 Pearson Education Canada Inc. 21 - 47
Client Representation Letter The auditor must obtain a letter from the client documenting the client’s representations during the engagement. % $@!!!} { @@? ”{ +&*##@ Client Representation Letter % $@!!!} { @@? ”{ +&*##@ Copyright 2003 Pearson Education Canada Inc. 21 - 48
Client Representation Letter The auditor must obtain a letter from the client documenting the client’s representations during the engagement. The primary purposes are to: - confirm and document oral statements - reduce auditor-client misunderstanding - remind management of its responsibility for the financial statements Copyright 2003 Pearson Education Canada Inc. 21 - 49
Client Representation Letter The auditor must obtain a letter from the client documenting the client’s representations during the engagement. The primary purposes are to: - confirm and document oral statements - reduce auditor-client misunderstanding - remind management of responsibilities The letter should be signed by the client CFO and CEO and dated with the field work completion date. Copyright 2003 Pearson Education Canada Inc. 21 - 50
Client Representation Letter If the client refuses to give the auditor a representation letter, the auditor must qualify or deny the opinion. probable Copyright 2003 Pearson Education Canada Inc. 21 - 51
Final Audit Steps 1. Incorporating all audit evidence, materiality, and judgment, the auditor draws overall conclusions and prepares the audit report. Copyright 2003 Pearson Education Canada Inc. 21 - 52
Final Audit Steps 1. Incorporating all audit evidence, materiality, and judgment, the auditor draws overall conclusions and prepares the audit report. 2. The auditor prepares the management letter. ? Copyright 2003 Pearson Education Canada Inc. 21 - 53
Final Audit Steps 1. Incorporating all audit evidence, materiality, and judgment, the auditor draws overall conclusions and prepares the audit report. 2. The auditor prepares the management letter. recommendations for improving the client business Copyright 2003 Pearson Education Canada Inc. 21 - 54
Final Audit Steps 1. Incorporating all audit evidence, materiality, and judgment, the auditor draws overall conclusions and prepares the audit report. 2. The auditor prepares the management letter. 3. The auditor communicates the results to the audit committee/management and gives them the audit report and management letter. Copyright 2003 Pearson Education Canada Inc. 21 - 55
GAAS suggests that auditors to communicate (oral or written) to audit committees, etc. : - the auditor’s responsibilities under GAAS Copyright 2003 Pearson Education Canada Inc. 21 - 56
GAAS suggests that auditors communicate (oral or written) to audit committees, etc. : - the auditor’s responsibilities under GAAS - significant accounting policies selected, & judgments used by management Copyright 2003 Pearson Education Canada Inc. 21 - 57
GAAS suggests that auditors communicate (oral or written) to audit committees, etc. : - the auditor’s responsibilities under GAAS - significant accounting policies selected, & judgments used by management - audit planning Copyright 2003 Pearson Education Canada Inc. 21 - 58
GAAS suggests that auditors communicate (oral or written) to audit committees, etc. : - the auditor’s responsibilities under GAAS - significant accounting policies selected, & judgments used by management - audit planning - disagreements with management Copyright 2003 Pearson Education Canada Inc. 21 - 59
GAAS suggests that auditors communicate (oral or written) to audit committees, etc. : - the auditor’s responsibilities under GAAS - significant accounting policies selected, & judgments used by management - audit planning - disagreements with management - difficulties in performing the audit Copyright 2003 Pearson Education Canada Inc. 21 - 60
GAAS suggests that auditors communicate (oral or written) to audit committees, etc. : - the auditor’s responsibilities under GAAS - significant accounting policies selected, & judgments used by management - audit planning - disagreements with management - difficulties in performing the audit - consultations with other accountants Copyright 2003 Pearson Education Canada Inc. 21 - 61
What are the required communications with the audit committee, etc. ? Copyright 2003 Pearson Education Canada Inc. 21 - 62
What are other suggested communications with the audit committee? - significant deficiencies in internal control - misstatements that are other than trivial - illegal or possible illegal acts Copyright 2003 Pearson Education Canada Inc. 21 - 63
- Slides: 63