
Hello The global body for professional accountants Objectives
Hello! The global body for professional accountants
Objectives • Explore the relationship between trust and the public interest • Discuss the concept of fiduciary duty and agency relationship • Identify the levels of trust and risk • Identify the fundamental principles of professional behaviour The global body for professional accountants
Trust and the Public Interest defined “the people’s general welfare and well being; something in which the populace as a whole has a stake. ” Webster’s New World Dictionary The global body for professional accountants
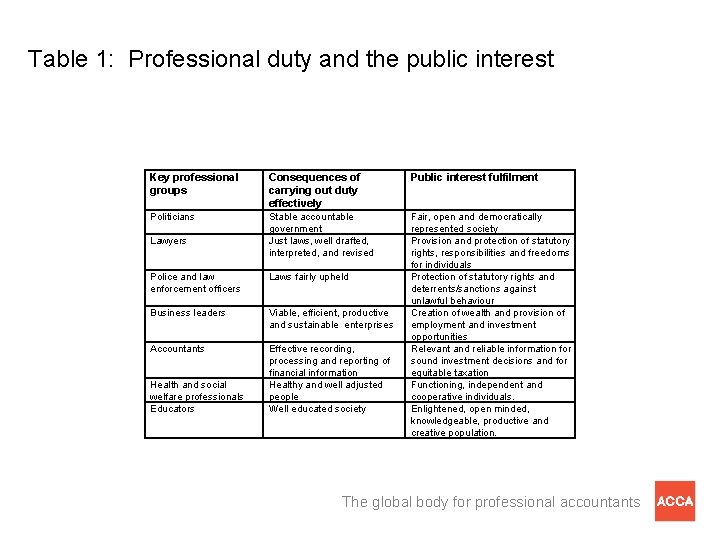
Table 1: Professional duty and the public interest Key professional groups Consequences of carrying out duty effectively Public interest fulfilment Politicians Stable accountable government Just laws, well drafted, interpreted, and revised Fair, open and democratically represented society Provision and protection of statutory rights, responsibilities and freedoms for individuals Protection of statutory rights and deterrents/sanctions against unlawful behaviour Creation of wealth and provision of employment and investment opportunities Relevant and reliable information for sound investment decisions and for equitable taxation Functioning, independent and cooperative individuals. Enlightened, open minded, knowledgeable, productive and creative population. Lawyers Police and law enforcement officers Laws fairly upheld Business leaders Viable, efficient, productive and sustainable enterprises Accountants Effective recording, processing and reporting of financial information Healthy and well adjusted people Well educated society Health and social welfare professionals Educators The global body for professional accountants
Investment of Trust and Higher Education The global body for professional accountants
Fiduciary duty and the agency relationship "one founded on trust or confidence reposed by one person in the integrity and fidelity of another. " Black’s Law Dictionary The global body for professional accountants
IES 4. The global body for professional accountants
Professional Values, Ethics & Attitudes. The global body for professional accountants
ETHICS EDUCATION FRAMEWORK • • Ethics knowledge Ethical sensitivity Ethical judgement Ethical behaviour (Attitudes) The global body for professional accountants
APPROACHES TO ETHICS EDUCATION • Discrete method • Pervasive method • Combined approach The global body for professional accountants
BROAD THEMES ? How should Accountants act The global body for professional accountants
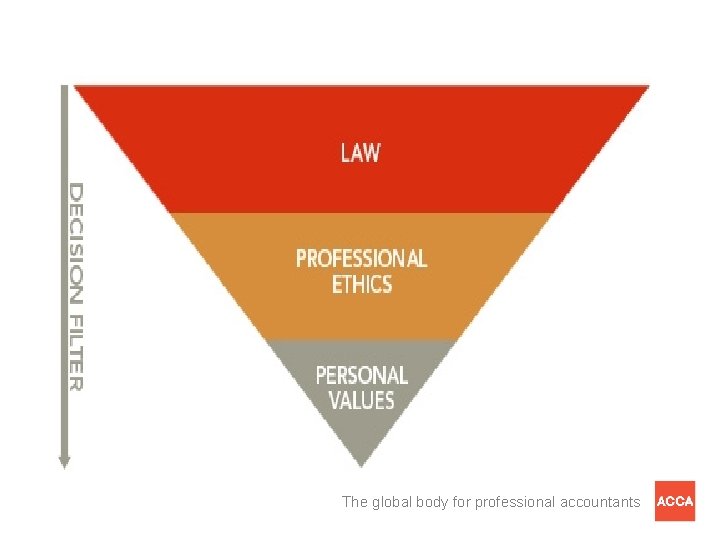
Figure 2: Professionalism and ethics decision filter The global body for professional accountants
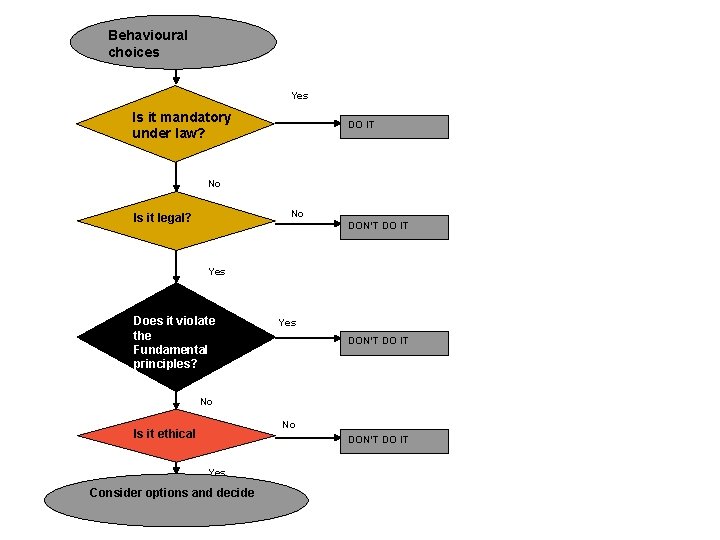
Behavioural choices Yes Is it mandatory under law? DO IT No No Is it legal? DON’T DO IT Yes Does it violate the Fundamental principles? Yes DON’T DO IT No No Is it ethical DON’T DO IT Yes Consider options and decide The global body for professional accountants
Ethics in the ACCA Qualification structure? The global body for professional accountants

ACCA membership Exams Ethics Experience The global body for professional accountants
EXAMS. The global body for professional accountants
P 1, Governance, Risk & Ethics The global body for professional accountants
Where is P 1 situated? The global body for professional accountants
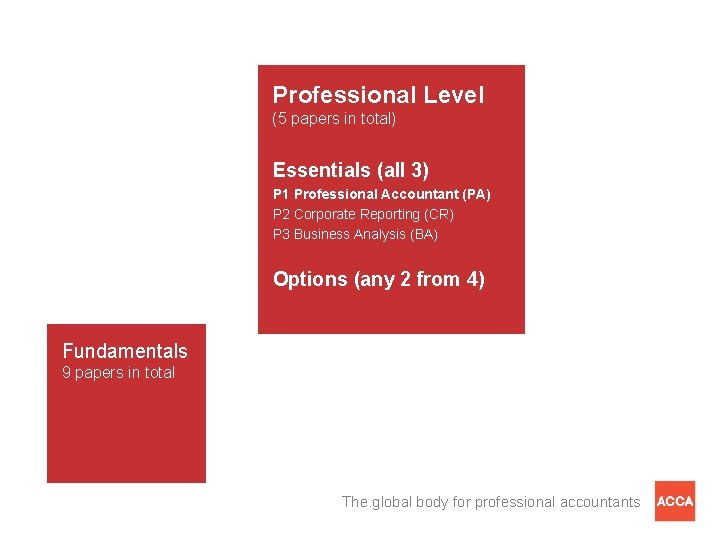
Professional Level (5 papers in total) Essentials (all 3) P 1 Professional Accountant (PA) P 2 Corporate Reporting (CR) P 3 Business Analysis (BA) Options (any 2 from 4) Fundamentals 9 papers in total The global body for professional accountants
Judgement Agency Professionalism Accountability Responsibility The global body for professional accountants
ETHICS. The global body for professional accountants
Professional Ethics Module. All other Professional papers and PER The global body for professional accountants
Objectives of the Professional Ethics Module? The global body for professional accountants
OBJECTIVES • Recognise technical expertise is not everything • Inculcate an ethical perspective • Explore ethical dimensions at work • Identify professional risks & threats • Adopt and apply ethical safeguards • Apply ethics and professionalism in business decision-making The global body for professional accountants
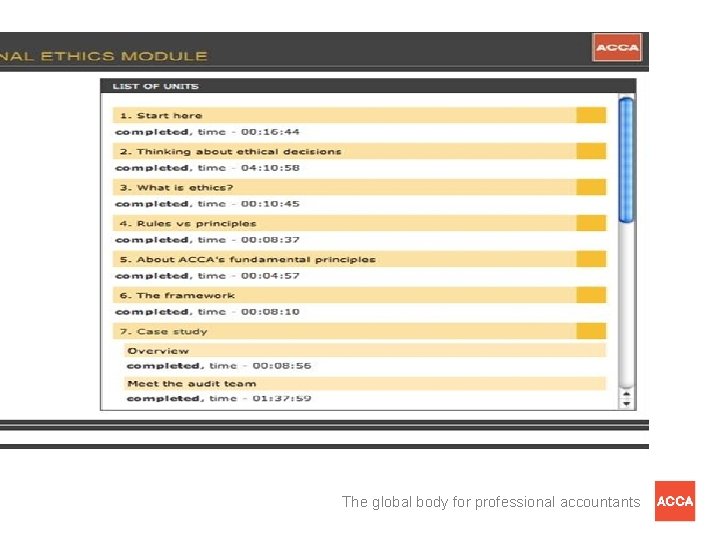
Structure of the Professional Ethics module. The global body for professional accountants
The global body for professional accountants
ETHICS AND EXPERIENCE. The global body for professional accountants
What are the practical experience requirements? The global body for professional accountants
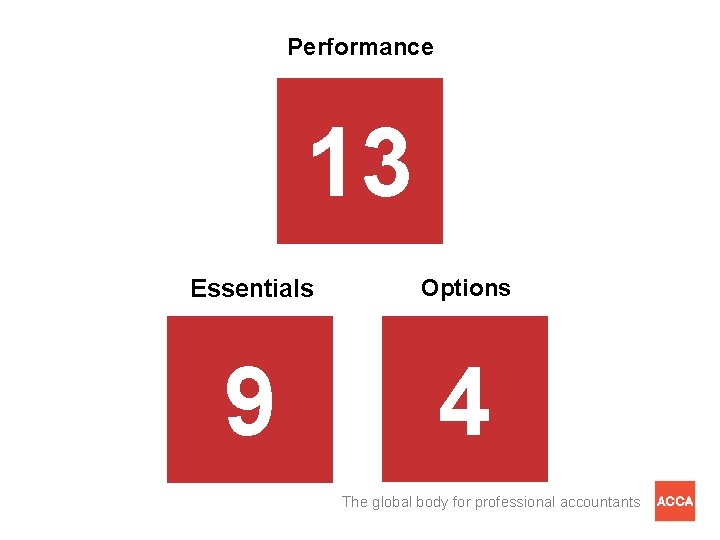
Performance objectives 13 Essentials Options 9 4 The global body for professional accountants
PERFORMANCE OBJECTIVES (ESSENTIALS) Professionalism, ethics & governance • Demonstrate the application of professional ethics, values and judgement • Contribute to the effective governance of an organisation • Raise awareness of non-financial risk The global body for professional accountants
QUESTIONS? The global body for professional accountants
Thanks! The global body for professional accountants
CONTACT Roger Gopaul Regional Head of Education ACCA Caribbean roger. gopaul@accaglobal. com 1 -868 -662 -4777 www. accaglobal. com The global body for professional accountants
- Slides: 35