
HARRV with Sector Variance Sharon Lee February 18
HAR-RV with Sector Variance Sharon Lee February 18, 2009
Starting Point • Intuitively, the returns of an individual equity should be correlated with returns from its sector • Using the predictive model HAR-RV, how does incorporating sector realized volatility affect the predicted values for an equity?
Consumer Goods Sector • Proctor & Gamble Co. (PG) • Avon Products, Inc. (AVP) • Colgate-Palmolive Co. (CL)
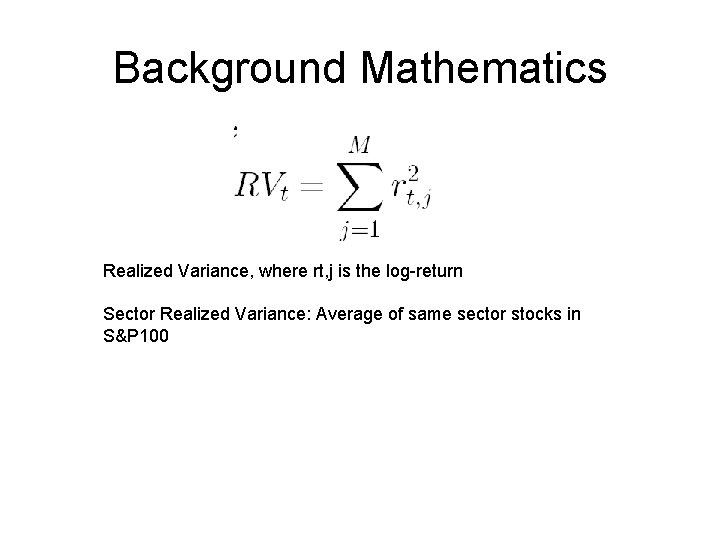
Background Mathematics Realized Variance, where rt, j is the log-return Sector Realized Variance: Average of same sector stocks in S&P 100
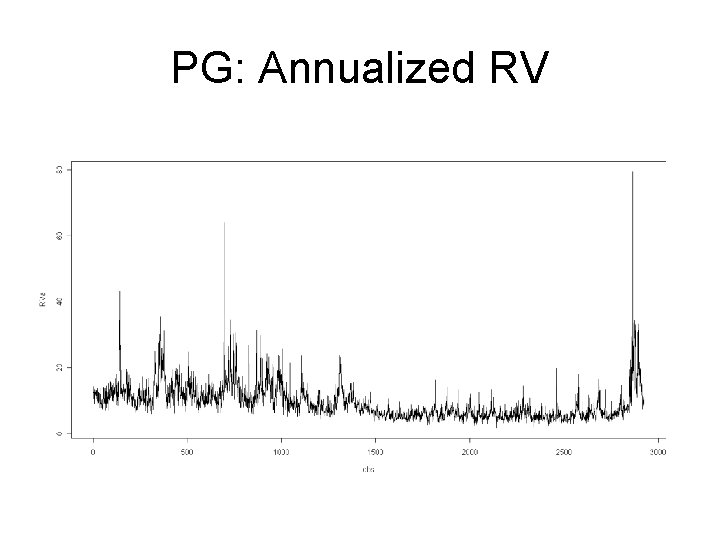
PG: Annualized RV
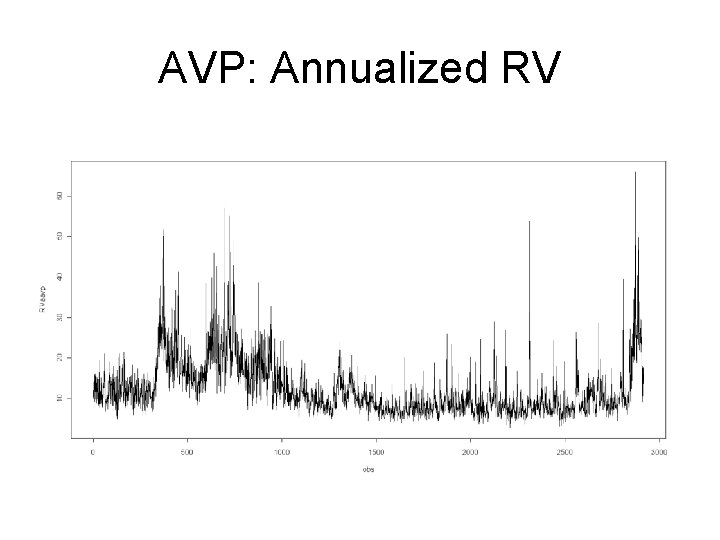
AVP: Annualized RV
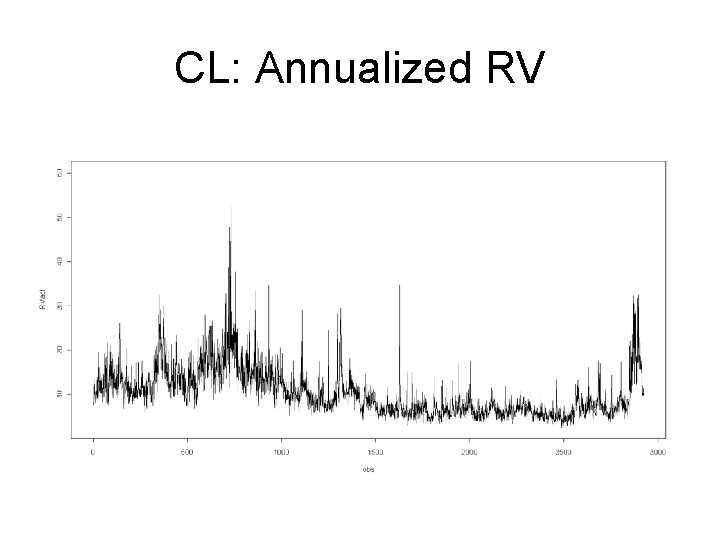
CL: Annualized RV
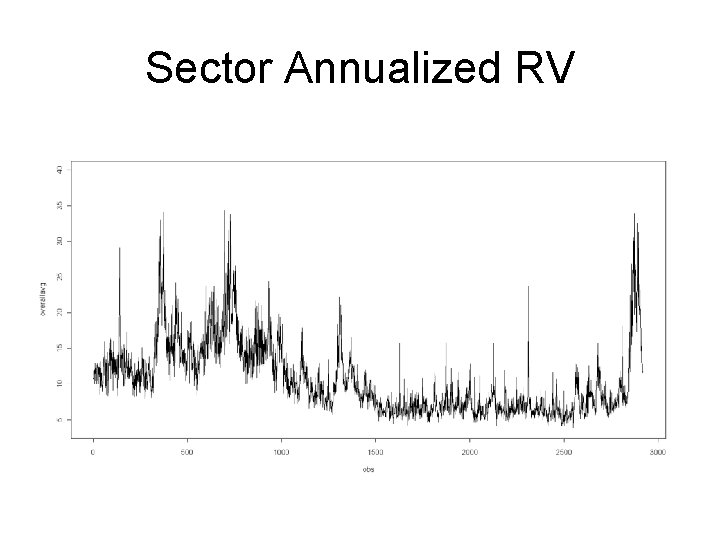
Sector Annualized RV
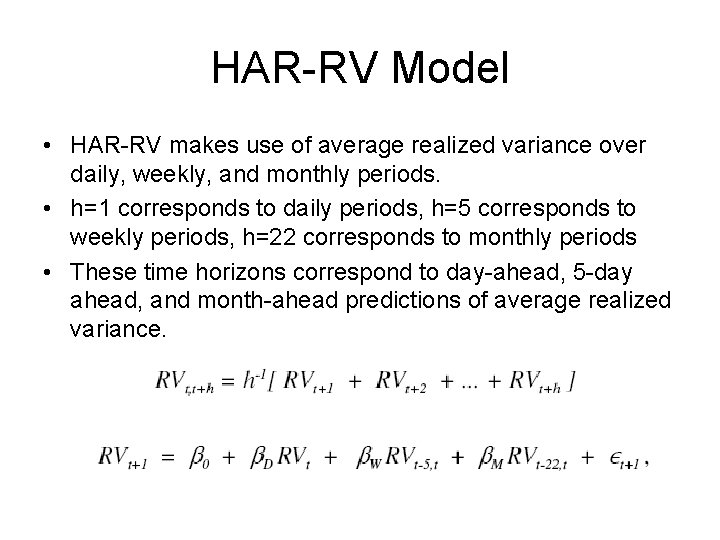
HAR-RV Model • HAR-RV makes use of average realized variance over daily, weekly, and monthly periods. • h=1 corresponds to daily periods, h=5 corresponds to weekly periods, h=22 corresponds to monthly periods • These time horizons correspond to day-ahead, 5 -day ahead, and month-ahead predictions of average realized variance.
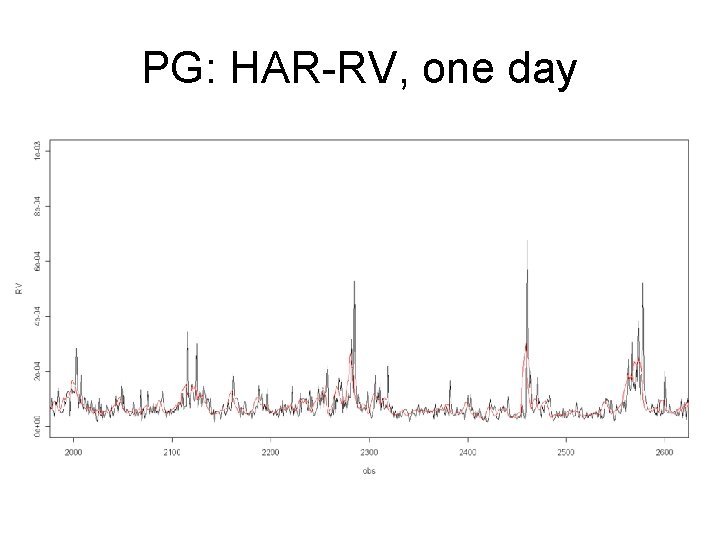
PG: HAR-RV, one day
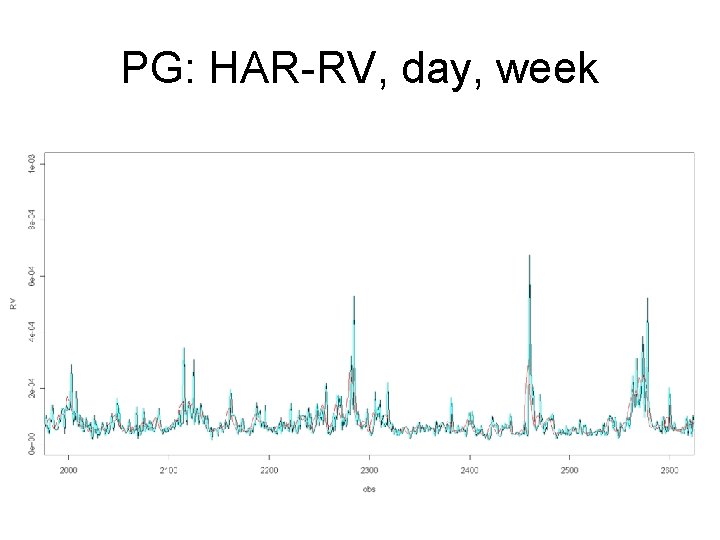
PG: HAR-RV, day, week
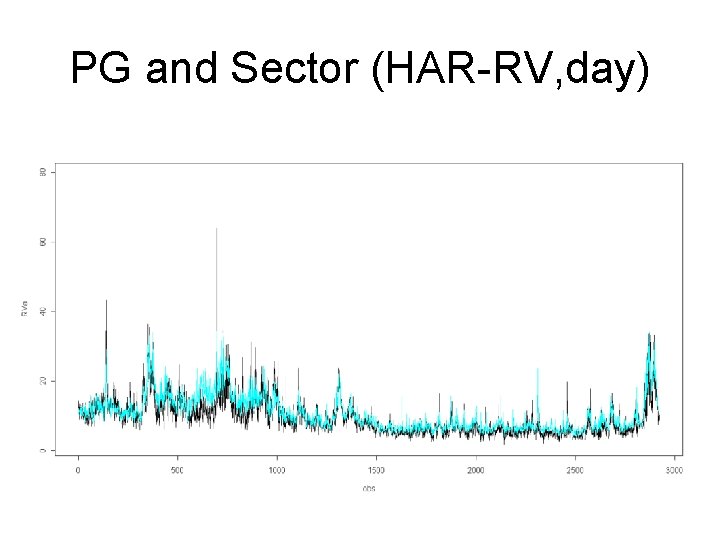
PG and Sector (HAR-RV, day)
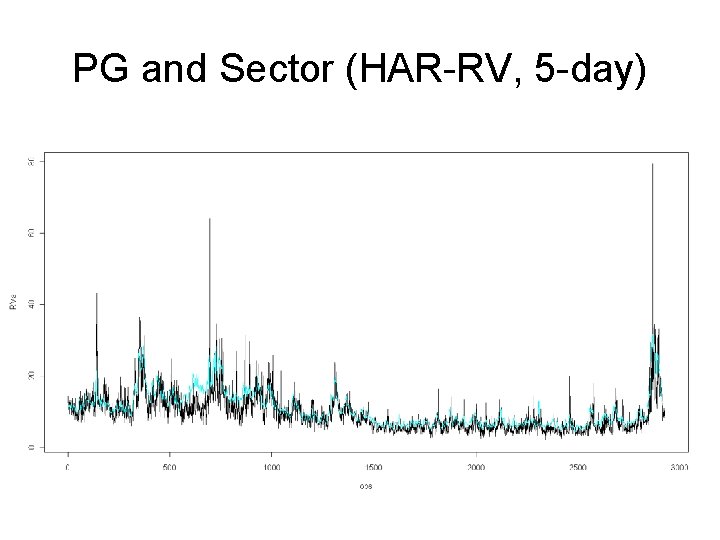
PG and Sector (HAR-RV, 5 -day)
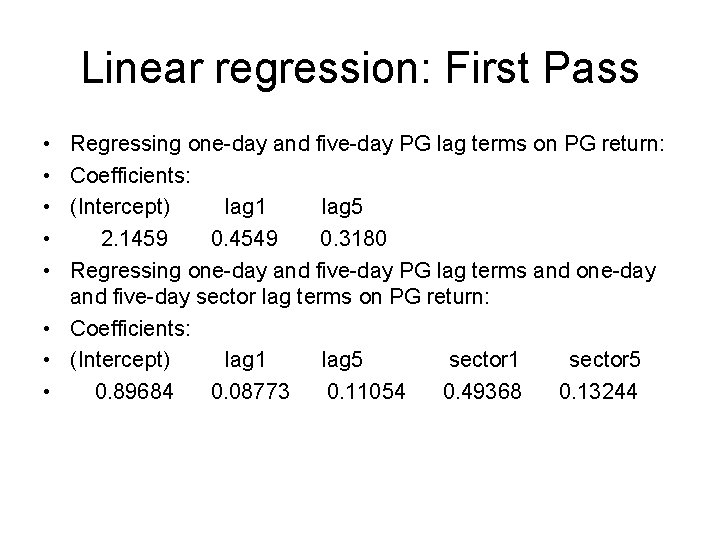
Linear regression: First Pass • • • Regressing one-day and five-day PG lag terms on PG return: Coefficients: (Intercept) lag 1 lag 5 2. 1459 0. 4549 0. 3180 Regressing one-day and five-day PG lag terms and one-day and five-day sector lag terms on PG return: • Coefficients: • (Intercept) lag 1 lag 5 sector 1 sector 5 • 0. 89684 0. 08773 0. 11054 0. 49368 0. 13244
What’s Next • Figure out how to run regressions with t-tests for significance • Investigate R-squared values • Incorporate more stocks and sectors • Consider additional regressors
- Slides: 15