
GSTR 9 9 C CA Shankara Narayanan V
- Slides: 87
GSTR 9 & 9 C CA Shankara Narayanan V GPVS & Associates 23 -03 -2019 CAShankara Narayanan V, Chennai 1
Checklists & Worksheets - Multilocation • Registered branches in two different States / UTs; • Registrants within the same State, as business verticals or otherwise; • Business locations outside India; • Branches in a State that are found liable to register but are not registered 23 -03 -2019 CAShankara Narayanan V, Chennai 2
Checklists & Worksheets – Multilocation – Books & Records • To be maintained GSTINwise • If Maintained Totally; • Methodology to derive Information – Work Sheet 23 -03 -2019 CAShankara Narayanan V, Chennai 3
Checklists & Worksheets – Multilocation – Books & Records • GSTIN-wise trial balance • Identification of GSTLedgers • GSTR 3 B and GSTR 2 A match • GSTR 3 B and GSTR 1 match • GSTR 3 B & 1 should match with Books of Accounts 23 -03 -2019 CAShankara Narayanan V, Chennai 4
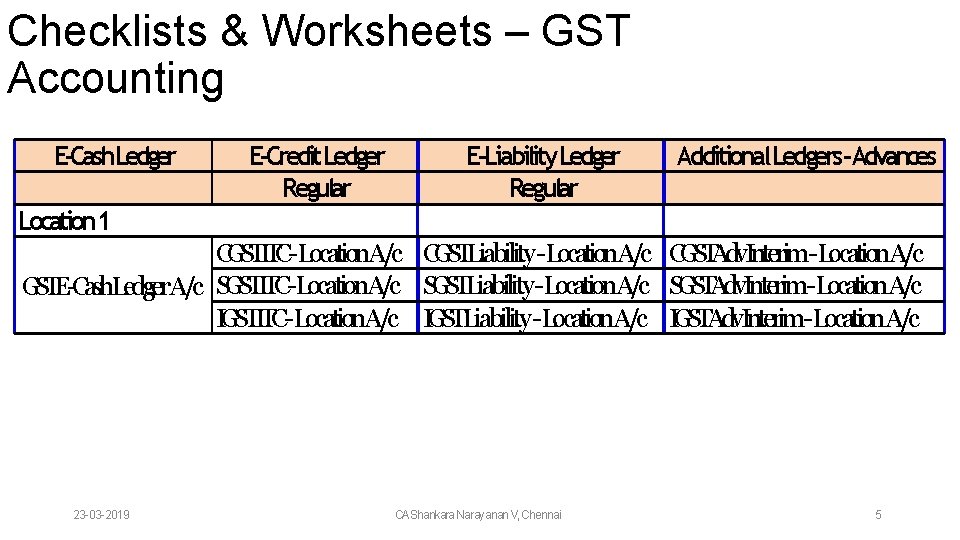
Checklists & Worksheets – GST Accounting E-Cash. Ledger E-Credit. Ledger Regular E-Liability Ledger Regular Additional Ledgers-Advances Location 1 CGSTITC-Location. A/c CGSTLiability-Location. A/c CGSTAdv. Interim-Location. A/c GSTE-Cash. Ledger. A/c SGSTITC-Location. A/c SGSTLiability-Location. A/c SGSTAdv. Interim-Location. A/c IGSTITC-Location. A/c IGSTLiability-Location. A/c IGSTAdv. Interim-Location. A/c 23 -03 -2019 CAShankara Narayanan V, Chennai 5
Checklists – Revenue Recognition vs Output Tax Liability • HSN Classification • Rate applicability • Goods • 177 items 28% to 18% from 15 th Nov 17 • Service - Maximum Rate • Transfer of Right to Use 23 -03 -2019 CAShankara Narayanan V, Chennai 6
Checklists – Revenue Recognition vs Output Tax Liability • Advances • For Goods Advances • No Tax before GST • GSTApplicable from 1 st July 2017 to 14 th Nov 2017 • No Tax from 15 th Nov 2017 23 -03 -2019 CAShankara Narayanan V, Chennai 7
Checklists – Revenue Recognition vs Output Tax Liability • Advances • For Service Advances • Service Tax POTwas applicable before GST • GSTApplicable • GSTcontinues to be applicable 23 -03 -2019 CAShankara Narayanan V, Chennai 8
Checklists – Deemed Supply vs Output Tax Liability Supply between Distinct Persons Taxable • Involves both Goods & Services • Elimination of Intra-Company Turnover • Reconciliation within Accounts & Returns 23 -03 -2019 CAShankara Narayanan V, Chennai 9
Checklists – Deemed Supply vs Output Tax Liability Food / Transportation to Employees • Free • at Subsidised Rate Section 15 – Related Person Gifts (Rs. 50, 000 limit) 23 -03 -2019 CAShankara Narayanan V, Chennai 10
Checklists – Deemed Supply vs Output Tax Liability – JOB WORK Inputs to be received back in one year Capital Goods to be received back in three years Else it will be regarded as supply by the principal to the job worker 23 -03 -2019 CAShankara Narayanan V, Chennai 11
Checklists & Worksheets – Outward Liability on Disposal of Assets • Motor Vehicles • Up to 12 th October • From 12 th October to 24 th January • From 25 th January 23 -03 -2019 CAShankara Narayanan V, Chennai 12
Checklists & Worksheets – Outward Liability on Disposal of Assets • Other than Motor Vehicles • 5% per quarter Eligibility • Transition Impact 23 -03 -2019 CAShankara Narayanan V, Chennai 13
Checklists & Worksheets – Outward Liability Other Recon Points • Debit Note • Interest Liability - Exceptions • Credit Note • Discount / Incentives – TREATMENT 23 -03 -2019 CAShankara Narayanan V, Chennai 14
Checklists & Worksheets – Outward Liability Other Recon Points • ZERO Rated Supply vs DEEMED Exports • LUT Compliance 23 -03 -2019 CAShankara Narayanan V, Chennai 15
Checklists & Worksheets – Other Outward Liabilities - RCM • Reverse Charge Mechanism • Section 9 (3) – Notified • Section 9 (4) – Unregistered • Deferred till 30 th September 2019 • Limit of Rs. 5, 000/- up to 12 th October 2017 23 -03 -2019 CAShankara Narayanan V, Chennai 16
Checklists & Worksheets – Other Outward Liabilities - RCM • Reverse Charge Section 9 (3) • Goods • Cashew Nuts; Tendu Leaves ; Tobacco Leaves • Silk yarn ; Raw Cotton • Goods disposed by Government • Lottery 23 -03 -2019 CAShankara Narayanan V, Chennai 17
Checklists & Worksheets – Other Outward Liabilities - RCM • Reverse Charge Section 9 (3) • Services • Legal Services by a Lawyer • Services of a Director • Services supplied by a director of a company or a body corporate to the said company or the body corporate • 23 -03 -2019 Sponsorship Services CAShankara Narayanan V, Chennai 18
Checklists & Worksheets – Other Outward Liabilities - RCM • Reverse Charge Section 9 (3) • Services • Goods Transport Services • Imports of Goods on CIF basis • Copyrights • Import of Services 23 -03 -2019 CAShankara Narayanan V, Chennai 19
Checklists & Worksheets – Input Tax Credit (a)Tax Invoice (b) Self - Invoice, subject to the payment of tax (c) a debit note issued by a supplier (d) a bill of entry or any similar document under the Customs Act, 1962 (e) an Input Service Distributor ISD invoice 23 -03 -2019 CAShankara Narayanan V, Chennai 20
Checklists & Worksheets – Input Tax Credit • Value of supply with tax payable FAILS to PAY within 180 days from Invoice Date • Time Limit 23 -03 -2019 CAShankara Narayanan V, Chennai 21
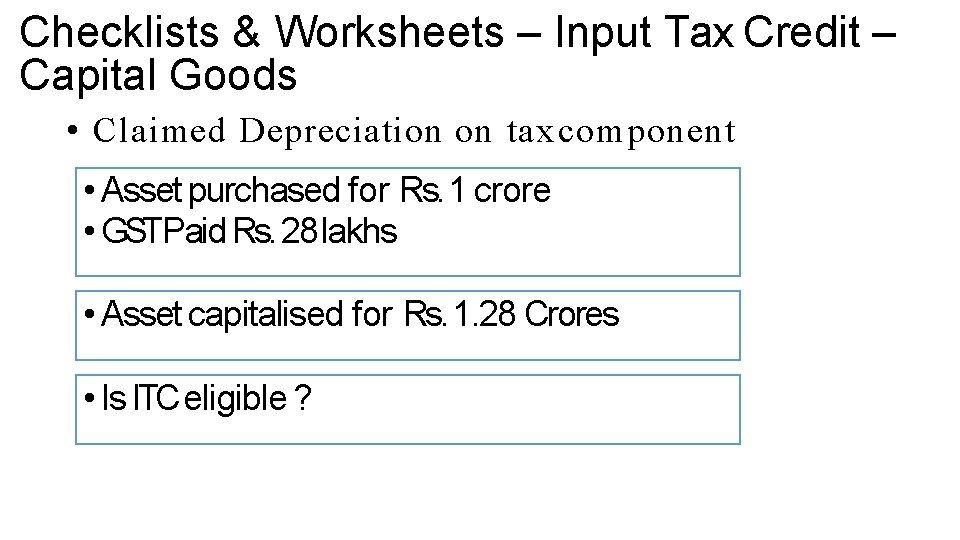
Checklists & Worksheets – Input Tax Credit – Capital Goods • Claimed Depreciation on tax component • Asset purchased for Rs. 1 crore • GSTPaid Rs. 28 lakhs • Asset capitalised for Rs. 1. 28 Crores • Is ITC eligible ?
Checklists & Worksheets – Input Tax Credit – Capital Goods o What is Capitalisation o Does taking to CWIP means Capitalisation o When the Credit can be availed 23 -03 -2019 CAShankara Narayanan V, Chennai 23
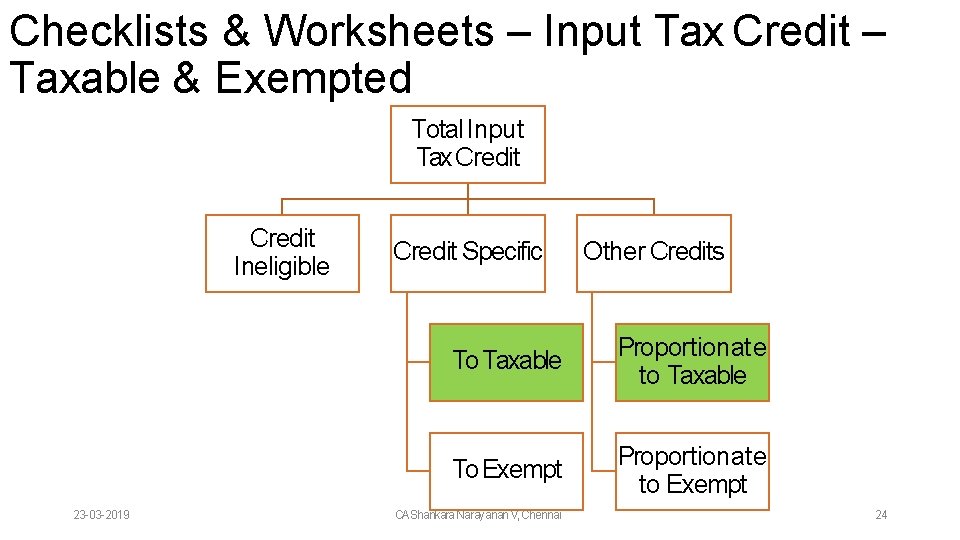
Checklists & Worksheets – Input Tax Credit – Taxable & Exempted Total Input Tax Credit Ineligible 23 -03 -2019 Credit Specific Other Credits To Taxable Proportionate to Taxable To Exempt Proportionate to Exempt CAShankara Narayanan V, Chennai 24
Checklists & Worksheets – Input Tax Credit • Goods lost, stolen, destroyed, written off or disposed of by way of gift or free samples • Impact Areas • Stock shortage on Physical Verification ? • Goods given on Warranty ? • Goods given as Free samples ? 23 -03 -2019 CAShankara Narayanan V, Chennai 25
Checklists & Worksheets – Input Tax Credit • Impact Areas • Goods used for Testing ? • New Year or Diwali Gifts ? • Inventory Written-Off ? • Slow moving Inventory PROVISION ? • Impairment on Fixed Assets ? 23 -03 -2019 CAShankara Narayanan V, Chennai 26
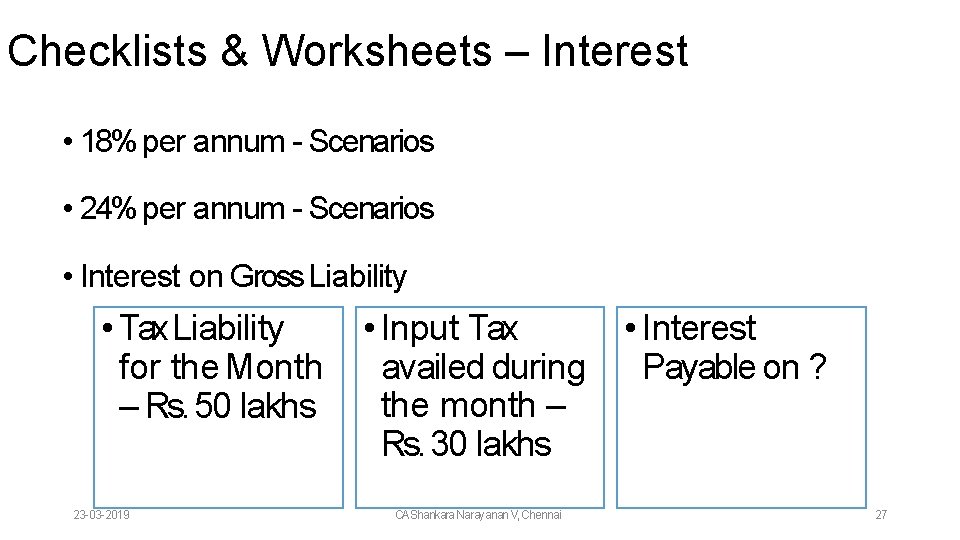
Checklists & Worksheets – Interest • 18% per annum - Scenarios • 24% per annum - Scenarios • Interest on Gross Liability • Tax Liability for the Month – Rs. 50 lakhs 23 -03 -2019 • Input Tax availed during the month – Rs. 30 lakhs CAShankara Narayanan V, Chennai • Interest Payable on ? 27
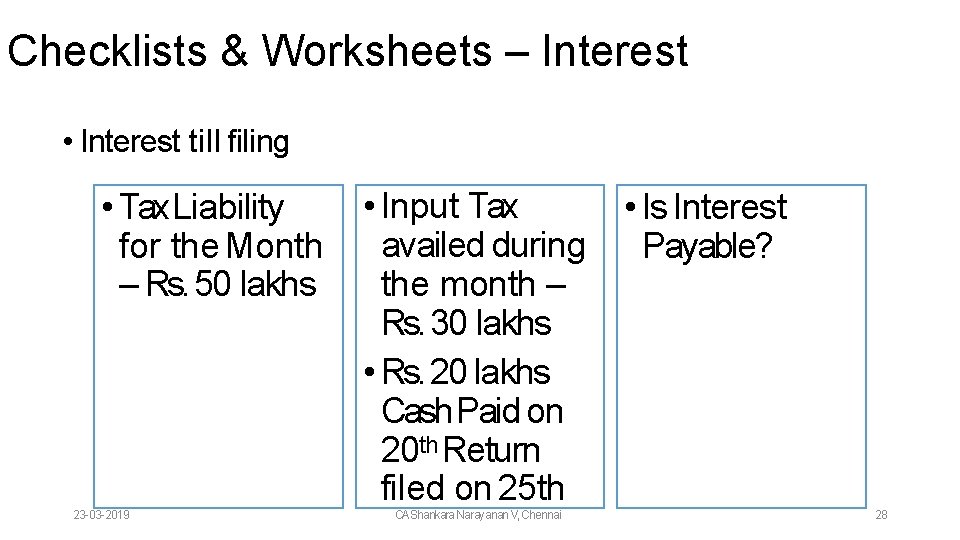
Checklists & Worksheets – Interest • Interest till filing • Tax Liability for the Month – Rs. 50 lakhs 23 -03 -2019 • Input Tax availed during the month – Rs. 30 lakhs • Rs. 20 lakhs Cash Paid on 20 th Return filed on 25 th CAShankara Narayanan V, Chennai • Is Interest Payable? 28
GSTR – 9 Clause by Clause 23 -03 -2019 CAShankara Narayanan V, Chennai 29
GST Annual Return On Screen Filing 23 -03 -2019 CAShankara Narayanan V, Chennai 30
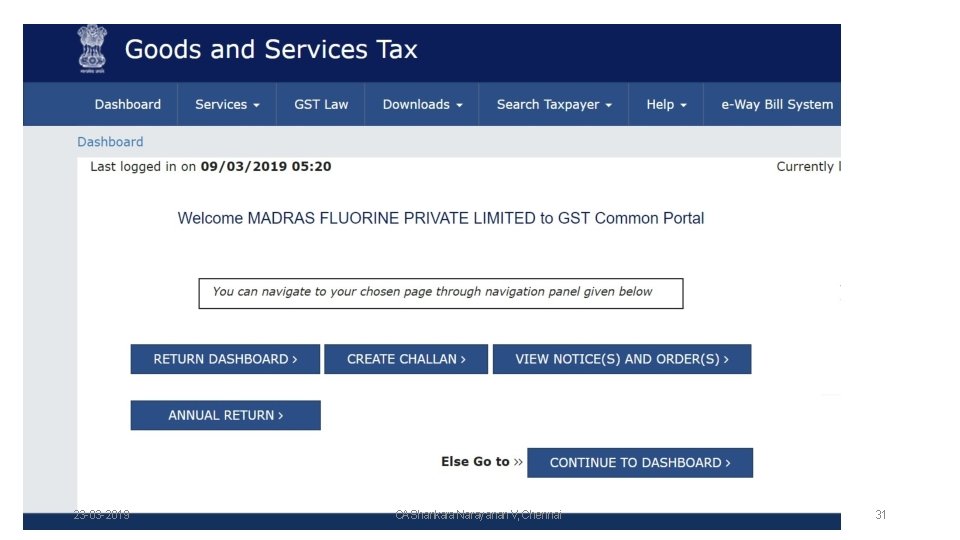
23 -03 -2019 CAShankara Narayanan V, Chennai 31
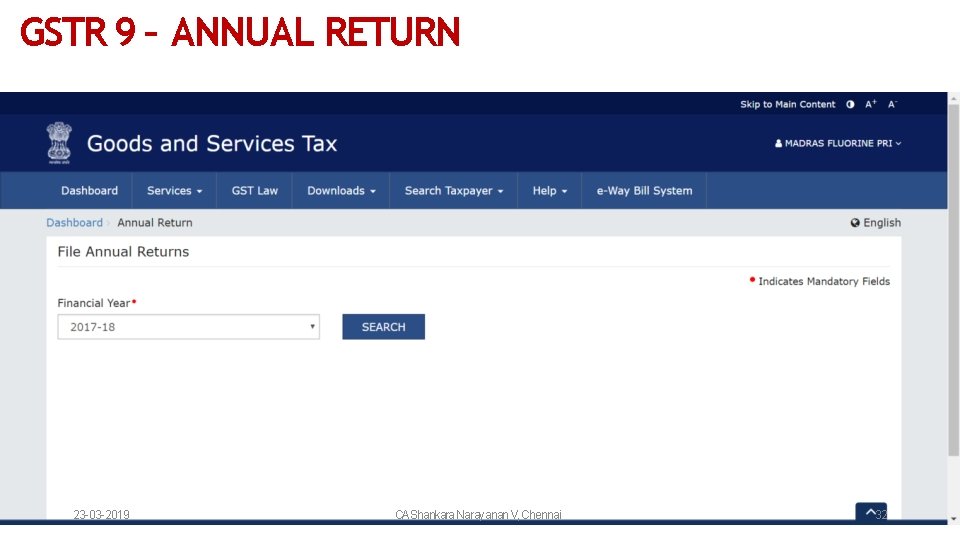
GSTR 9 – ANNUAL RETURN 23 -03 -2019 CAShankara Narayanan V, Chennai 32
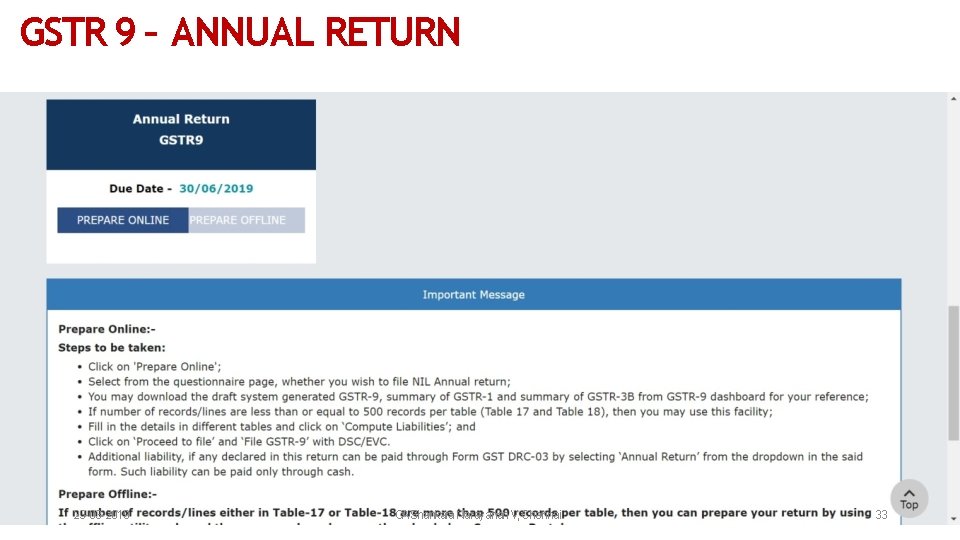
GSTR 9 – ANNUAL RETURN 23 -03 -2019 CAShankara Narayanan V, Chennai 33
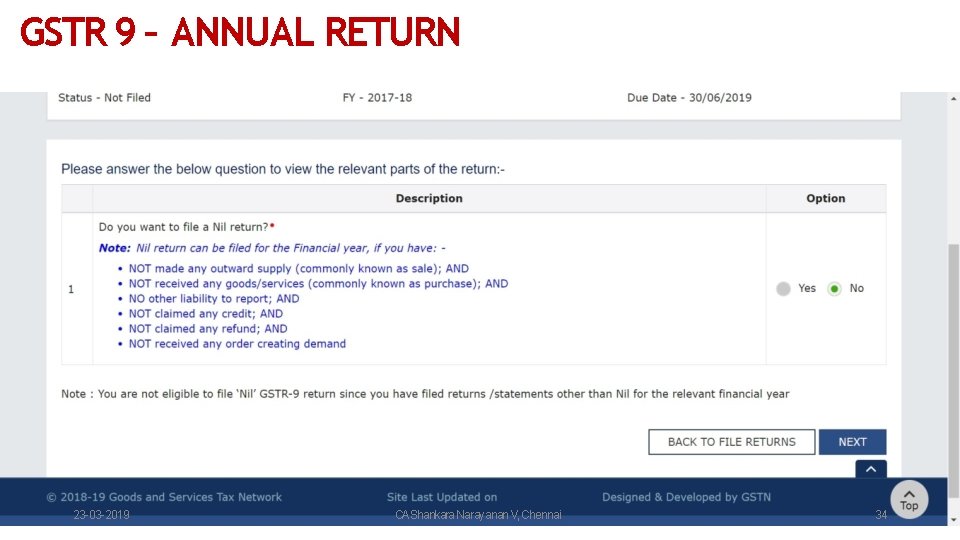
GSTR 9 – ANNUAL RETURN 23 -03 -2019 CAShankara Narayanan V, Chennai 34
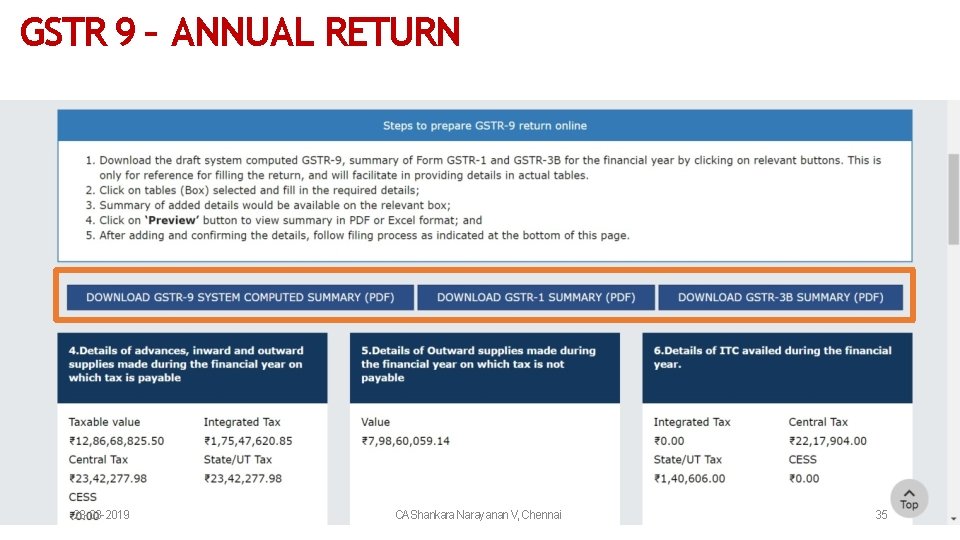
GSTR 9 – ANNUAL RETURN 23 -03 -2019 CAShankara Narayanan V, Chennai 35
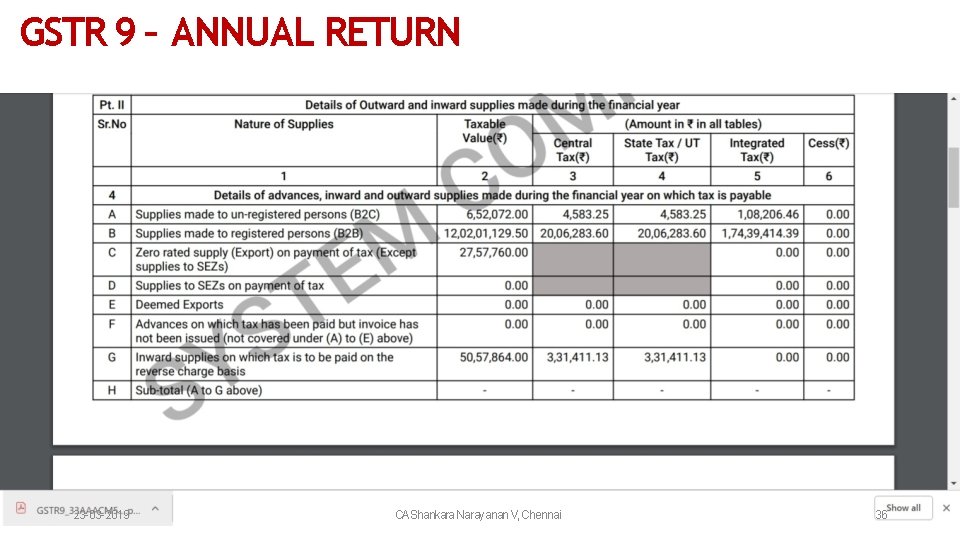
GSTR 9 – ANNUAL RETURN 23 -03 -2019 CAShankara Narayanan V, Chennai 36
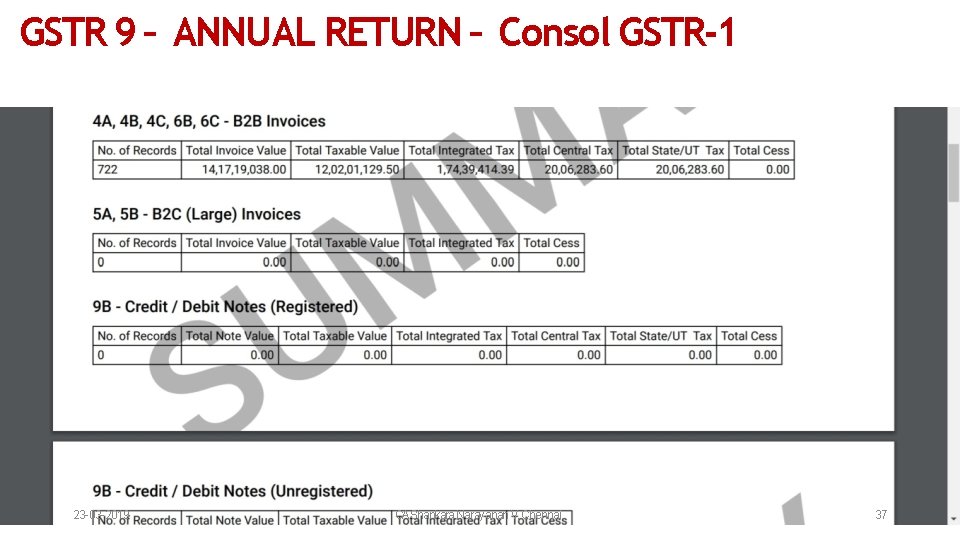
GSTR 9 – ANNUAL RETURN – Consol GSTR-1 23 -03 -2019 CAShankara Narayanan V, Chennai 37
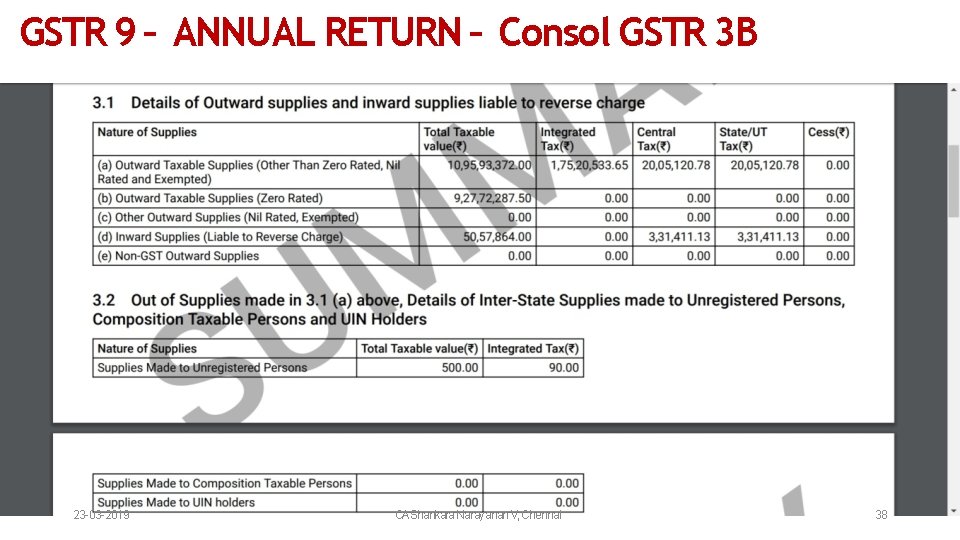
GSTR 9 – ANNUAL RETURN – Consol GSTR 3 B 23 -03 -2019 CAShankara Narayanan V, Chennai 38
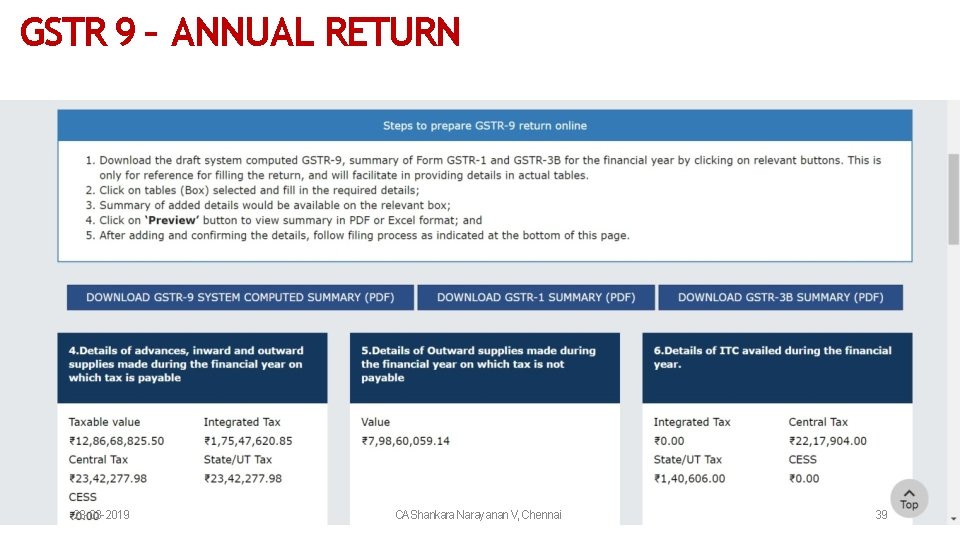
GSTR 9 – ANNUAL RETURN 23 -03 -2019 CAShankara Narayanan V, Chennai 39
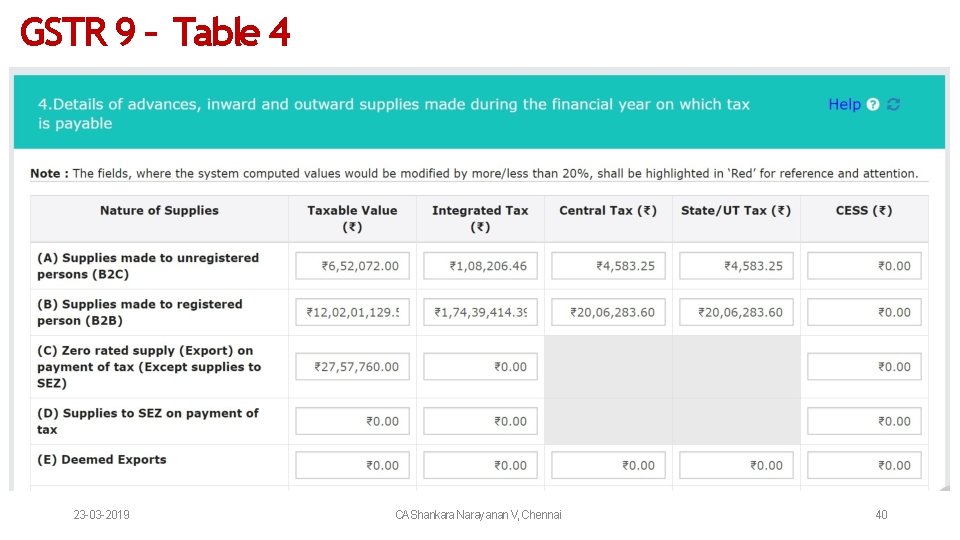
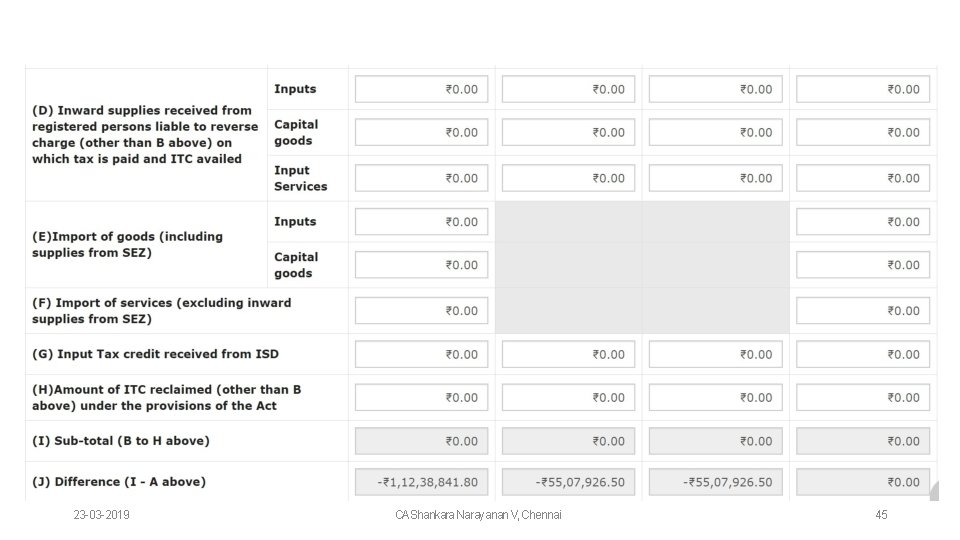
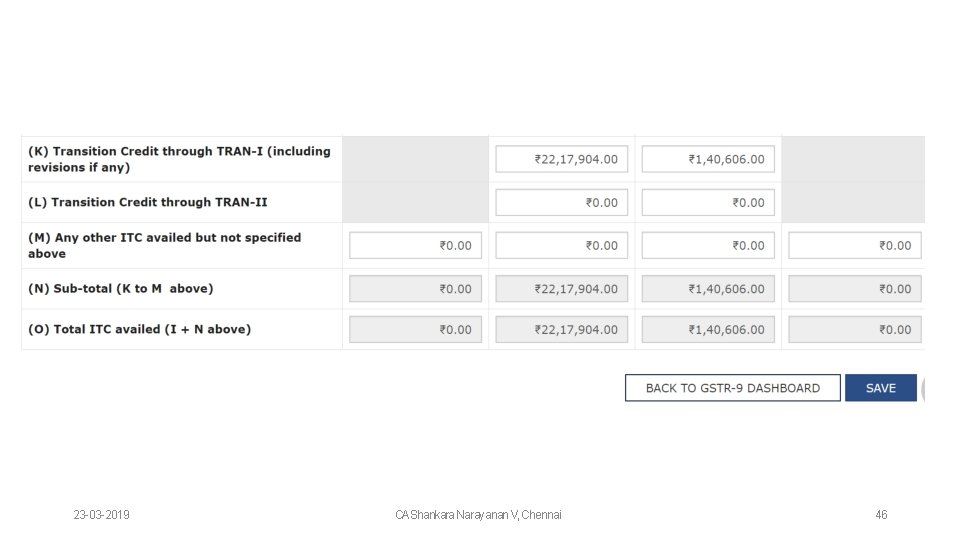
GSTR 9 – Table 4 23 -03 -2019 CAShankara Narayanan V, Chennai 40
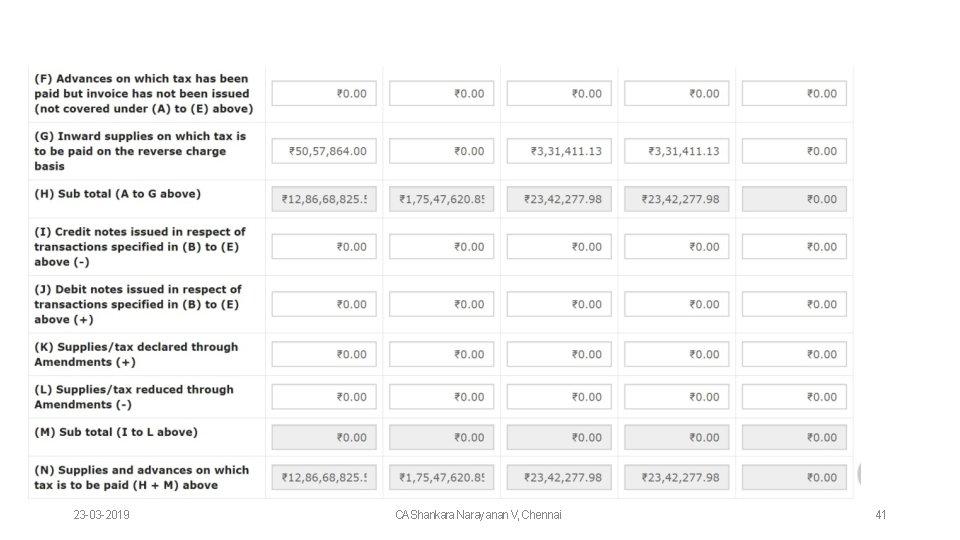
23 -03 -2019 CAShankara Narayanan V, Chennai 41
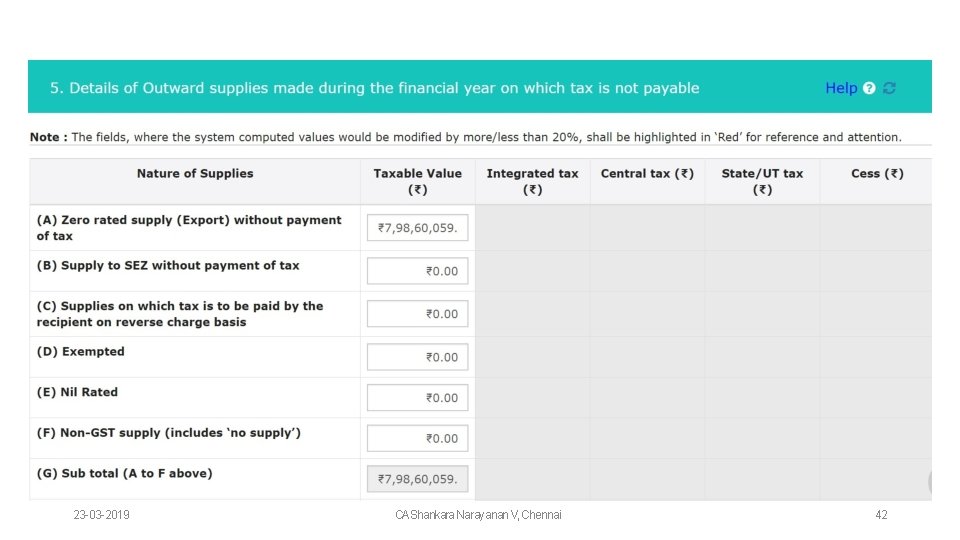
23 -03 -2019 CAShankara Narayanan V, Chennai 42
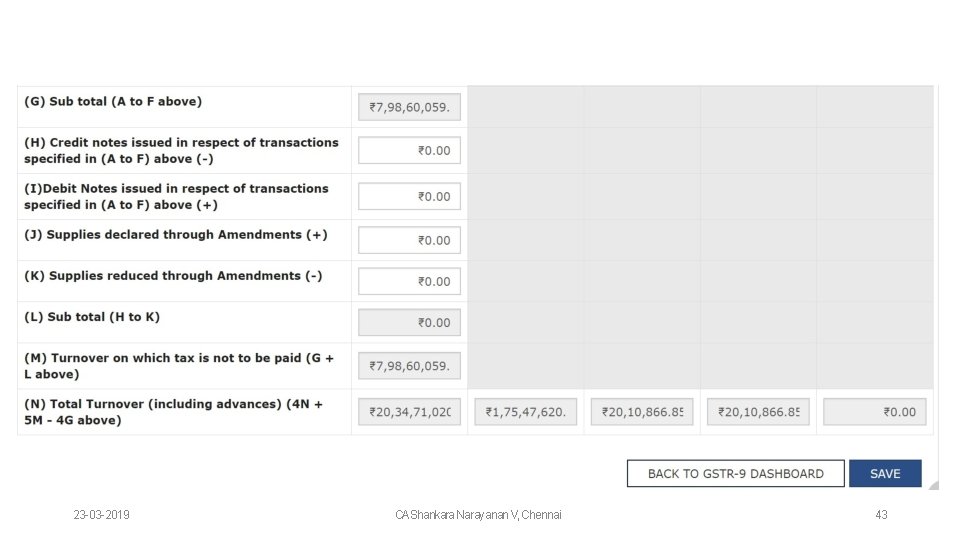
23 -03 -2019 CAShankara Narayanan V, Chennai 43
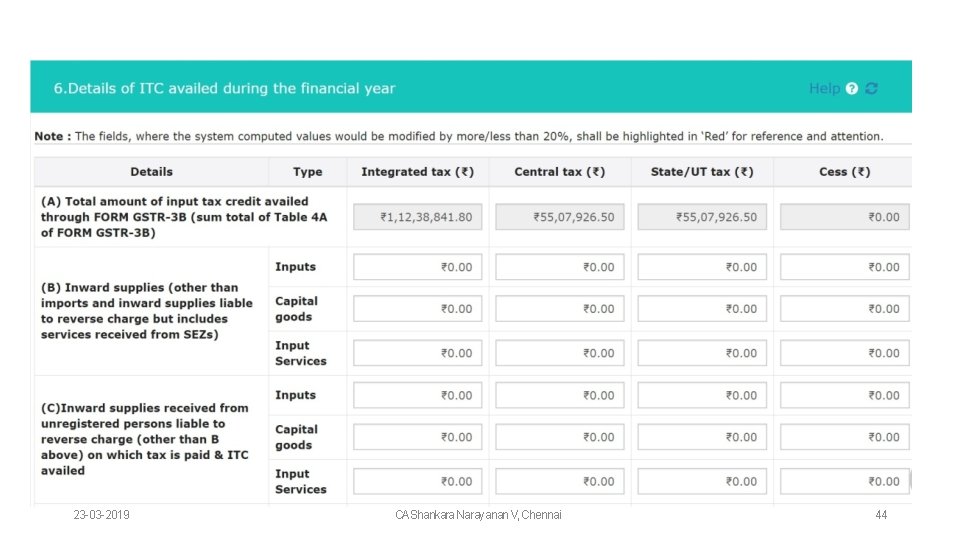
23 -03 -2019 CAShankara Narayanan V, Chennai 44
23 -03 -2019 CAShankara Narayanan V, Chennai 45
23 -03 -2019 CAShankara Narayanan V, Chennai 46
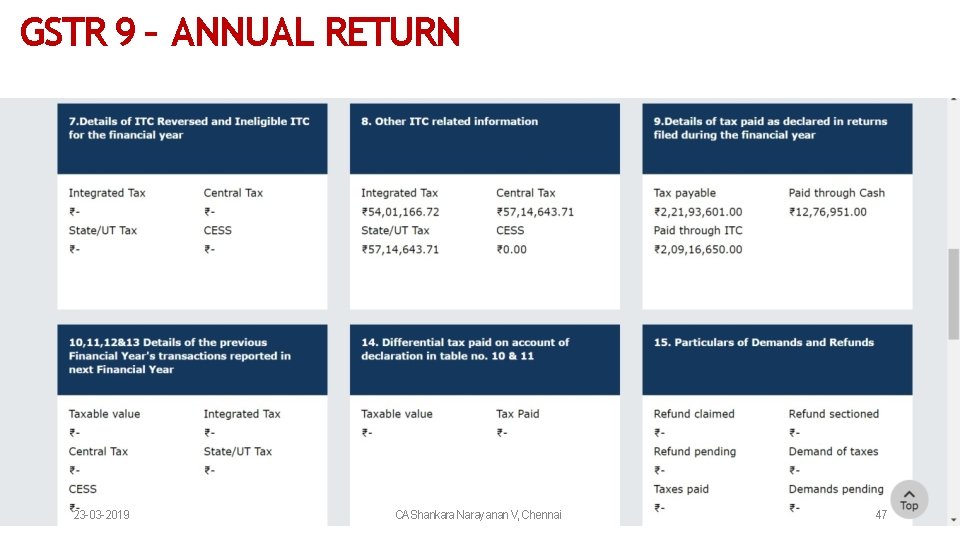
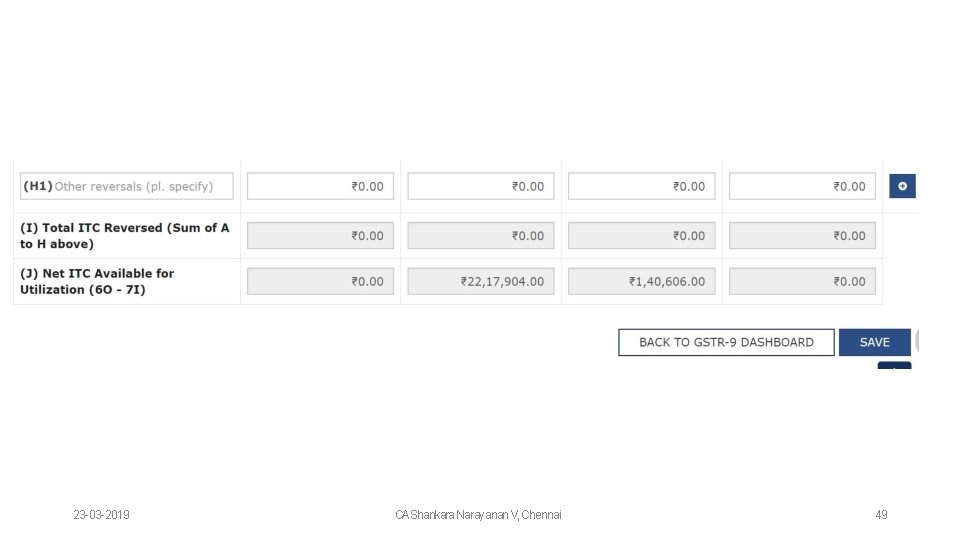
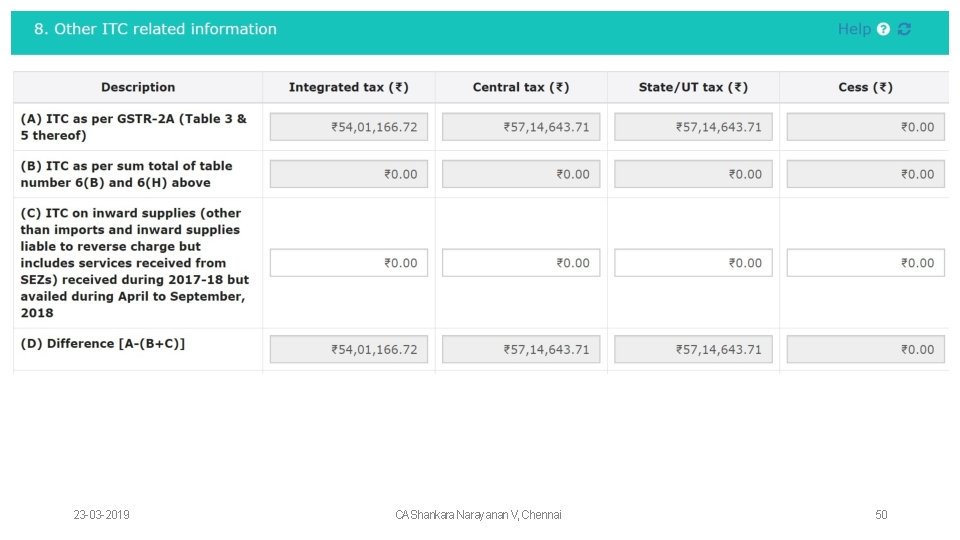
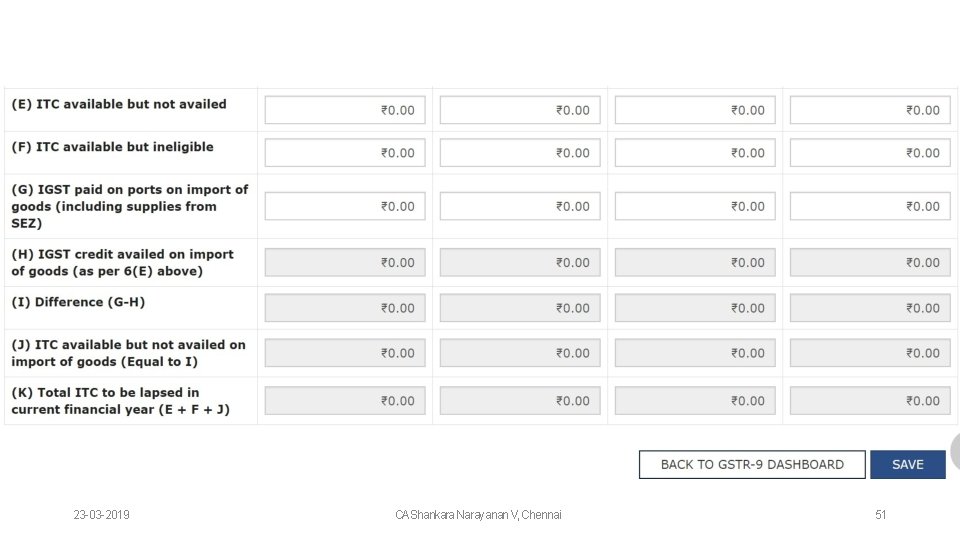
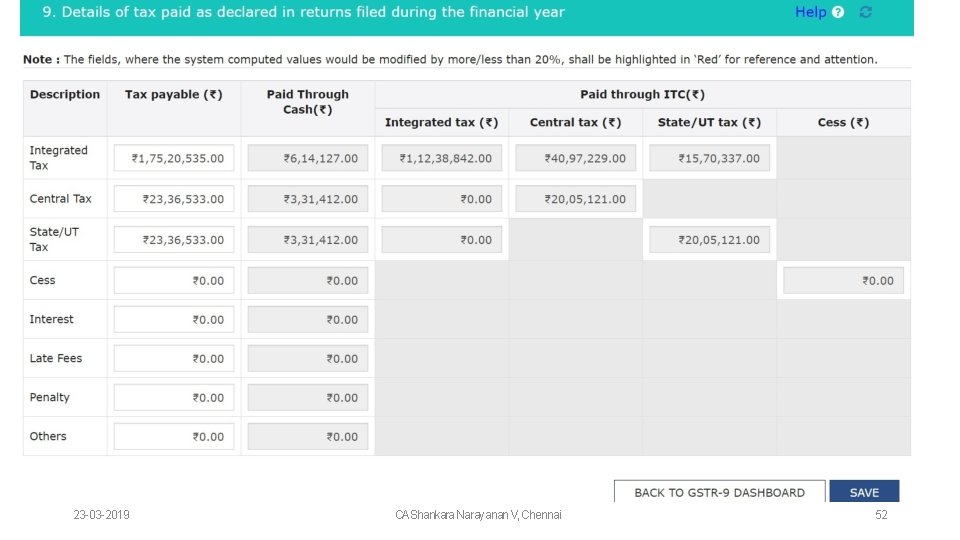
GSTR 9 – ANNUAL RETURN 23 -03 -2019 CAShankara Narayanan V, Chennai 47
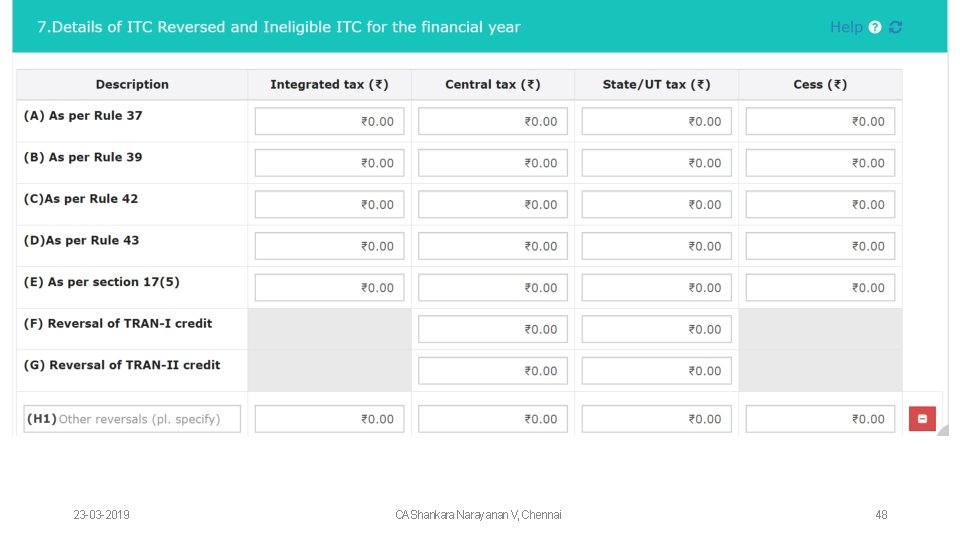
23 -03 -2019 CAShankara Narayanan V, Chennai 48
23 -03 -2019 CAShankara Narayanan V, Chennai 49
23 -03 -2019 CAShankara Narayanan V, Chennai 50
23 -03 -2019 CAShankara Narayanan V, Chennai 51
23 -03 -2019 CAShankara Narayanan V, Chennai 52
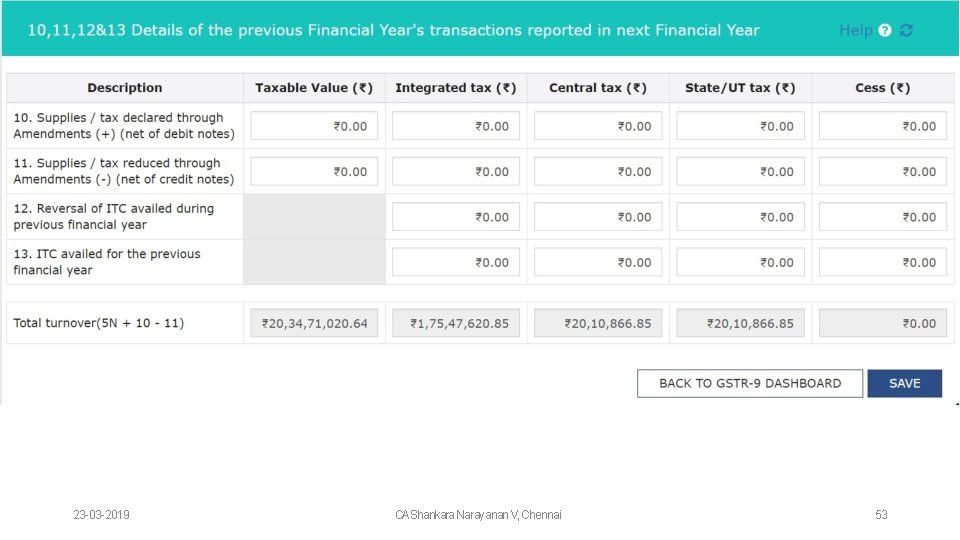
23 -03 -2019 CAShankara Narayanan V, Chennai 53
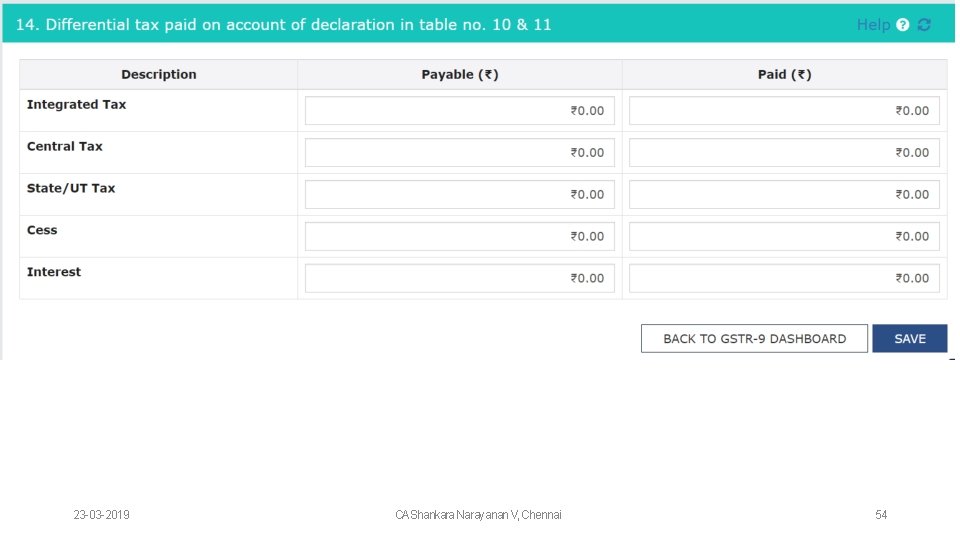
23 -03 -2019 CAShankara Narayanan V, Chennai 54
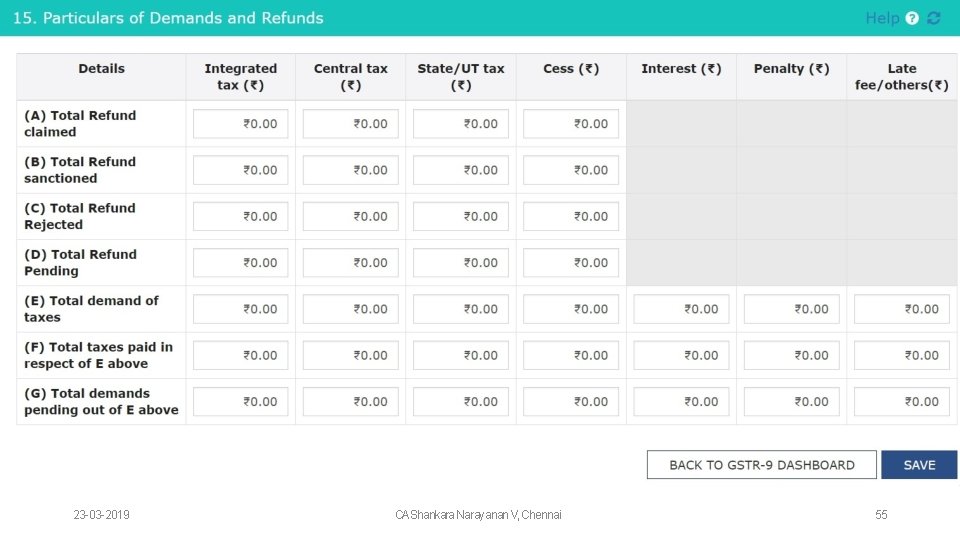
23 -03 -2019 CAShankara Narayanan V, Chennai 55
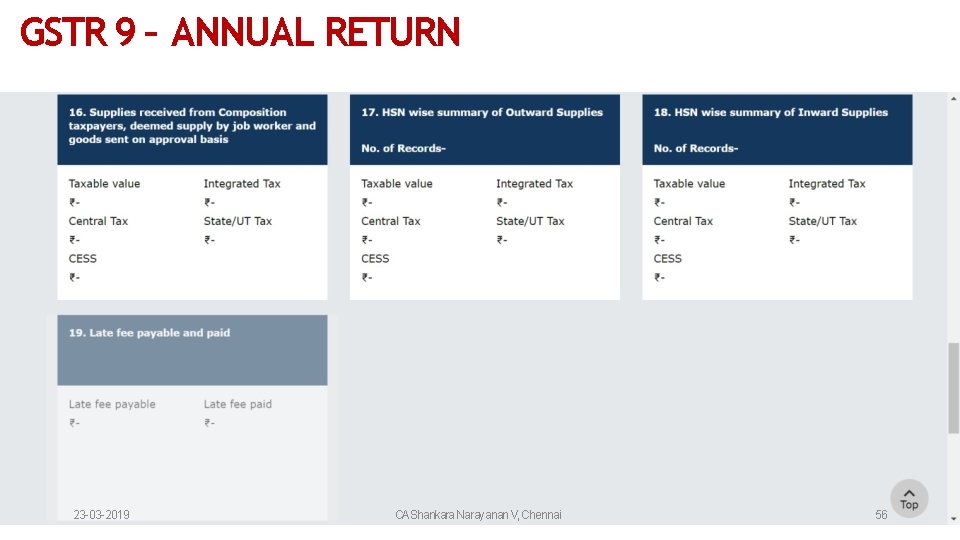
GSTR 9 – ANNUAL RETURN 23 -03 -2019 CAShankara Narayanan V, Chennai 56
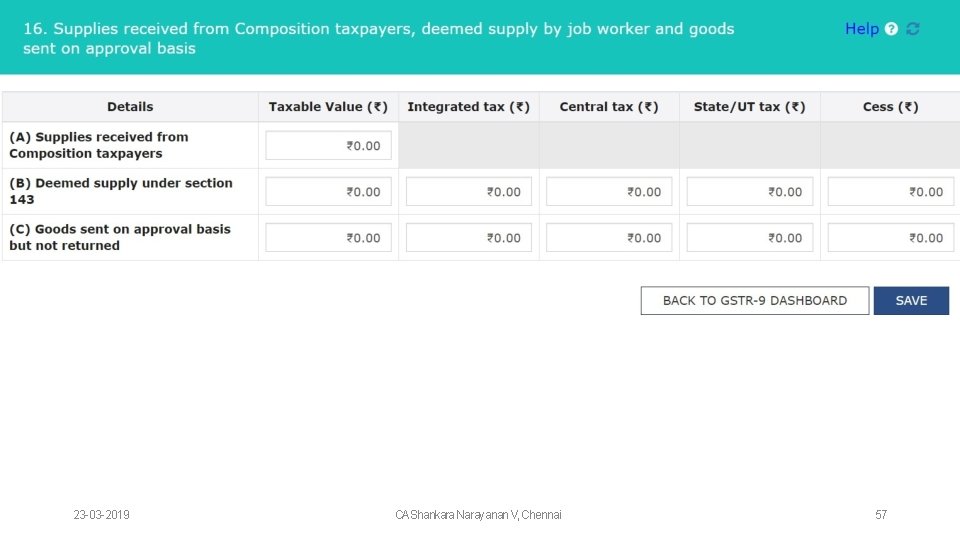
23 -03 -2019 CAShankara Narayanan V, Chennai 57
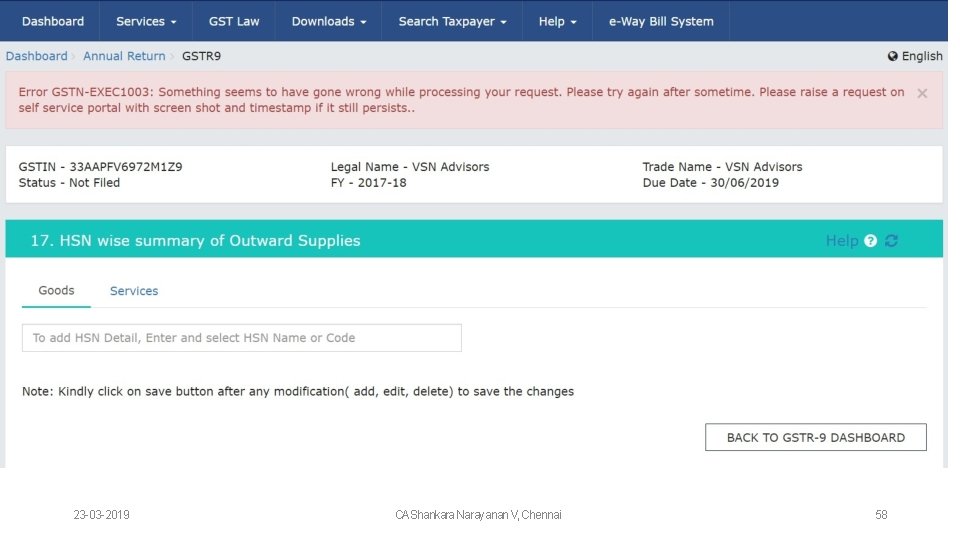
23 -03 -2019 CAShankara Narayanan V, Chennai 58
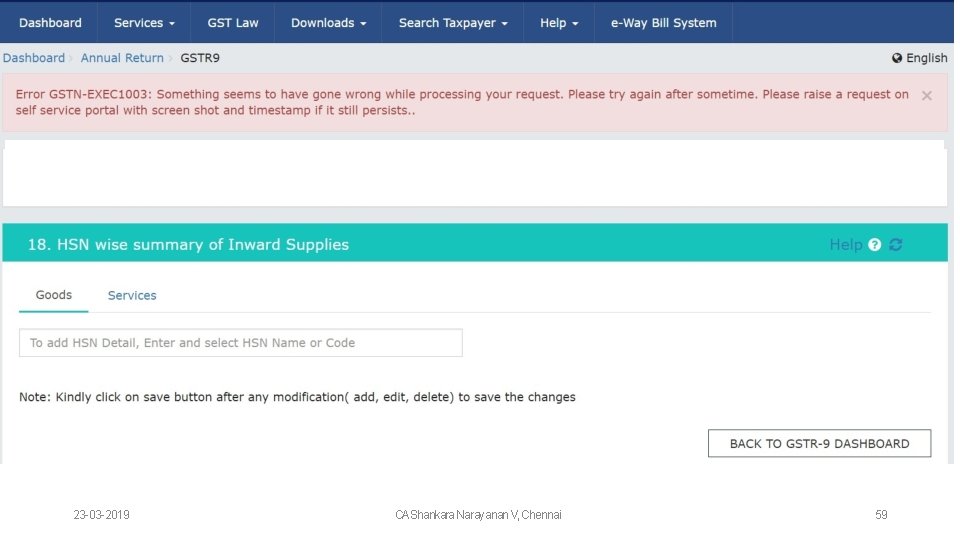
23 -03 -2019 CAShankara Narayanan V, Chennai 59
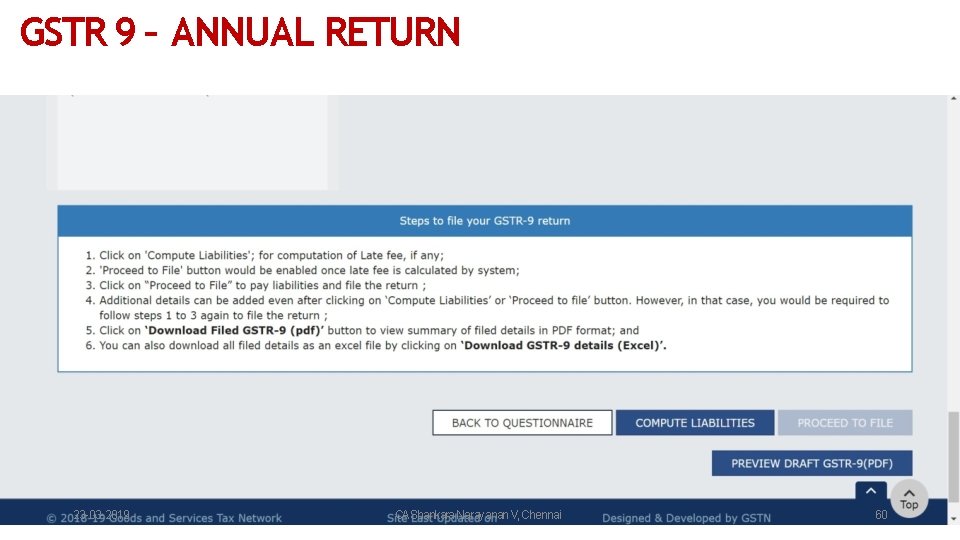
GSTR 9 – ANNUAL RETURN 23 -03 -2019 CAShankara Narayanan V, Chennai 60
GST - Reconciliation Statement & Audit by External Auditors CA Shankara Narayanan V 23 -03 -2019 CAShankara Narayanan V, Chennai 61
Types of Audit under GST – Audit by a Chartered Accountant – Sec. 35 (5) of the CGST Act, read with rule 80(3) of the CGST rules, 2017. Annual return to be filed u/s 44 in Form GSTR-9/9 A/9 B shall be supported by a certified reconciliation statement between Audited Financial statements and Returns filed. 23 -03 -2019 CAShankara Narayanan V, Chennai 62
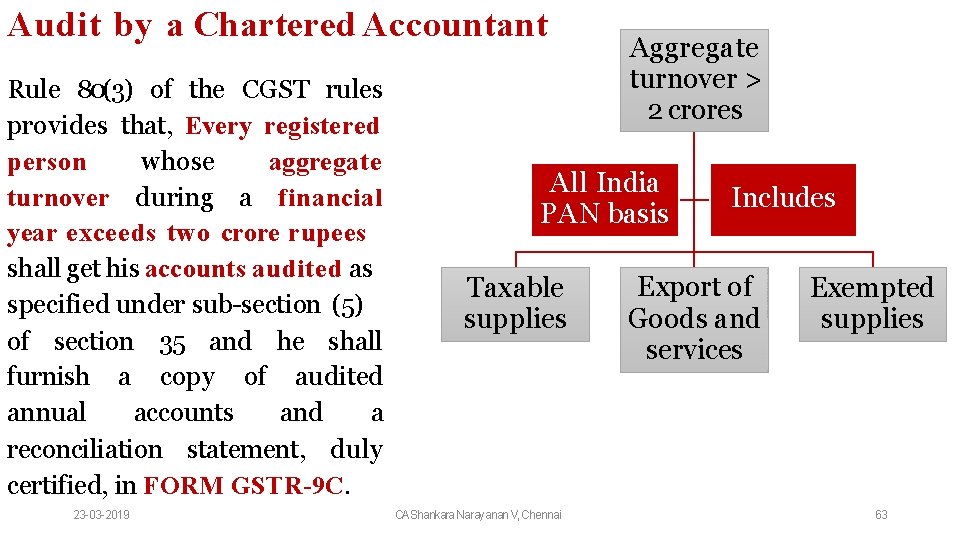
Audit by a Chartered Accountant Rule 80(3) of the CGST rules provides that, Every registered person aggregate whose turnover during a financial year exceeds two crore rupees shall get his accounts audited as specified under sub-section (5) of section 35 and he shall furnish a copy of audited annual accounts and a reconciliation statement, duly certified, in FORM GSTR-9 C. 23 -03 -2019 Aggregate turnover > 2 crores All India PAN basis Taxable supplies CAShankara Narayanan V, Chennai Includes Export of Goods and services Exempted supplies 63
Audit by a Chartered Accountant “Exempt supply” means supply of any goods or services or both which attracts nil rate of tax or which may be wholly exempt from tax under section 11, or under section 6 of the Integrated Goods and Services Tax Act, and includes non-taxable supply 23 -03 -2019 CAShankara Narayanan V, Chennai 64
Audit by a Chartered Accountant Annual Turnover – Rule 80(3) provides if aggregate turnover during the financial year exceeds INR 2 crores. GST is effective from 1 st July 2017 i. e, only for 9 months during FYE 2017 -18. What is the threshold for turnover for FYE 2017 -18 is yet to be clarified by Government Whether to consider INR 2 crores or proportionate for 9 months 23 -03 -2019 CAShankara Narayanan V, Chennai 65
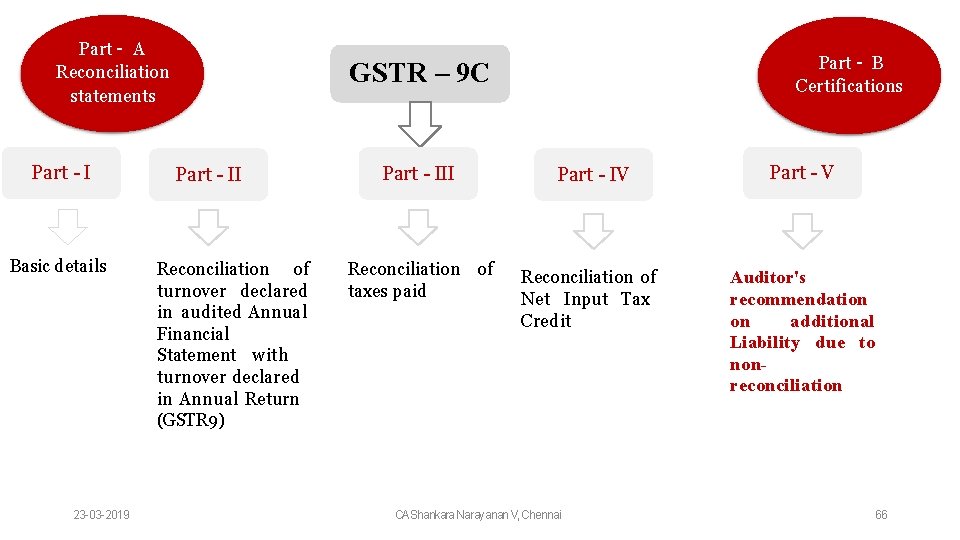
Part – A Reconciliation statements Part - I Basic details 23 -03 -2019 Part – B Certifications GSTR – 9 C Part - II Reconciliation of turnover declared in audited Annual Financial Statement with turnover declared in Annual Return (GSTR 9) Part - III Part - IV Part - V Reconciliation of taxes paid Reconciliation of Net Input Tax Credit Auditor's recommendation on additional Liability due to nonreconciliation CAShankara Narayanan V, Chennai 66
Part B - Certification Verification: I hereby solemnly affirm and declare that the information given herein above is true and correct to the best of my knowledge and belief and nothing has been concealed there from. Signature and stamp/Seal of the Auditor 23 -03 -2019 CAShankara Narayanan V, Chennai 67
Part B - Certification I. Certification in cases where the reconciliation statement (FORM GSTR-9 C) is drawn up by the person who had conducted the audit II. Certification in cases where the reconciliation statement (FORM GSTR-9 C) is drawn up by a person other than the person who had conducted the audit of the accounts: 23 -03 -2019 CAShankara Narayanan V, Chennai 68
Part B – Certification – Statutory is GST Auditor 1. I/we have examined the— (a)balance sheet as on ……… (b)the *profit and loss account/income and expenditure account for the period beginning from ………. . …toending on ……. , and (c) the cash flow statement for the period beginning from ……. . …toending on ………, —attached herewith, of M/s ……………(Name), ……………. ……… (Address), . . …………………(GSTIN). 23 -03 -2019 CAShankara Narayanan V, Chennai 69
Part B – Certification – Statutory is GST Auditor 2. Based on our audit I/we report that the said registered person— *has maintained the books of accounts, records and documents as required by the IGST/CGST/<<>>GST Act, 2017 and the rules/notifications made/issued thereunder 23 -03 -2019 CAShankara Narayanan V, Chennai 70
Part B – Certification – Statutory is GST Auditor 3. (a) *I/we report the following observations/ comments / discrepancies / inconsistencies; if any: …………………. 3. (b) *I/we further report that, (A) *I/we have obtained all the information and explanations which, to the best of *my/our knowledge and belief, were necessary for the purpose of the audit/ information and explanations which, to the best of *my/our knowledge and belief, were necessary for the purpose of the audit were not provided/partially provided to us. 23 -03 -2019 CAShankara Narayanan V, Chennai 71
Part B – Certification – Statutory is GST Auditor (B)In *my/our opinion, proper books of account *have/have not been kept by the registered person so far as appears from*my/ our examination of the books. (C)I/we certify that the balance sheet, the *profit and loss/income and expenditure account and the cash flow Statement are *in agreement/not in agreement with the books of account maintained at the Principal place of business at …………and* * …………additionalplace of business within the State. 23 -03 -2019 CAShankara Narayanan V, Chennai 72
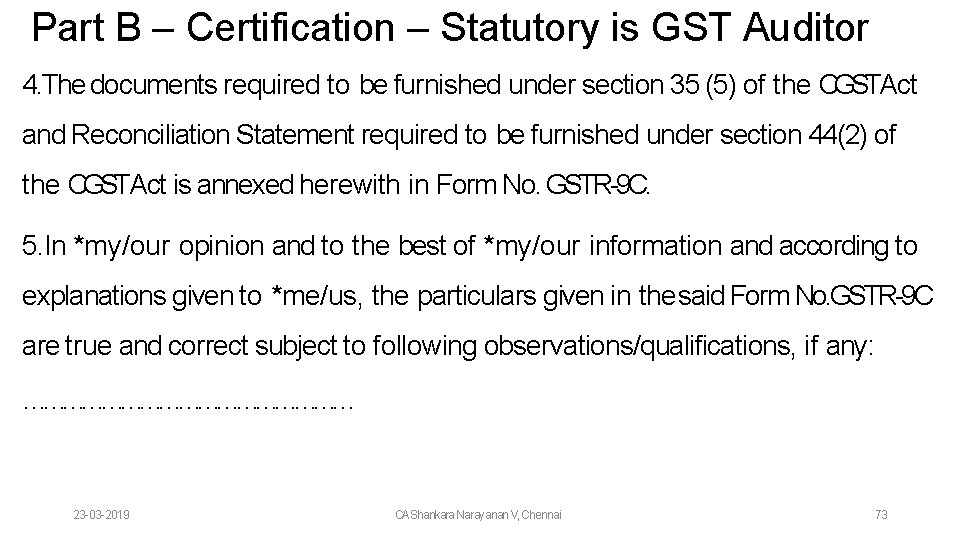
Part B – Certification – Statutory is GST Auditor 4. The documents required to be furnished under section 35 (5) of the CGSTAct and Reconciliation Statement required to be furnished under section 44(2) of the CGSTAct is annexed herewith in Form No. GSTR-9 C. 5. In *my/our opinion and to the best of *my/our information and according to explanations given to *me/us, the particulars given in the said Form No. GSTR-9 C are true and correct subject to following observations/qualifications, if any: ……………………… 23 -03 -2019 CAShankara Narayanan V, Chennai 73
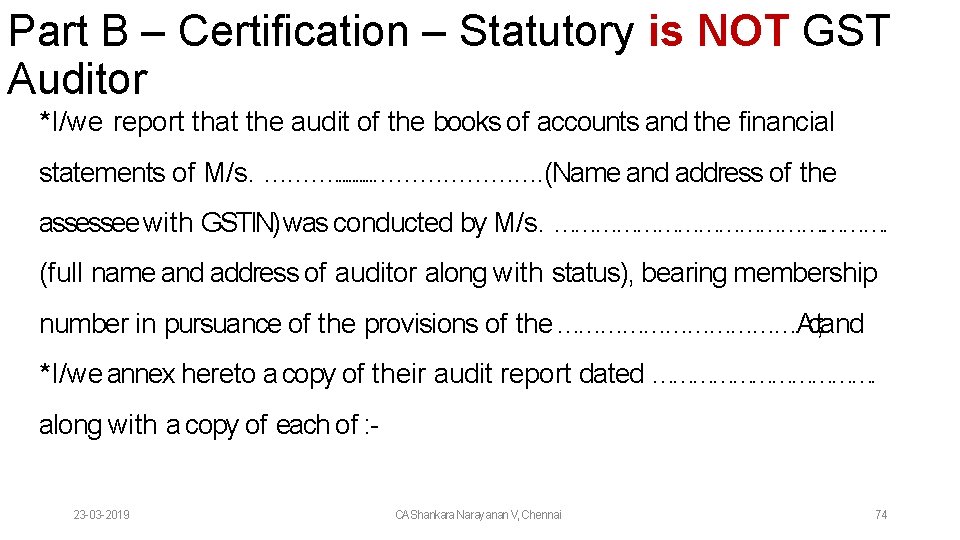
Part B – Certification – Statutory is NOT GST Auditor *I/we report that the audit of the books of accounts and the financial statements of M/s. ………. . . …………………. (Name and address of the assessee with GSTIN) was conducted by M/s. …………………. (full name and address of auditor along with status), bearing membership number in pursuance of the provisions of the ………………. Act, and *I/we annex hereto a copy of their audit report dated ………………. along with a copy of each of : 23 -03 -2019 CAShankara Narayanan V, Chennai 74
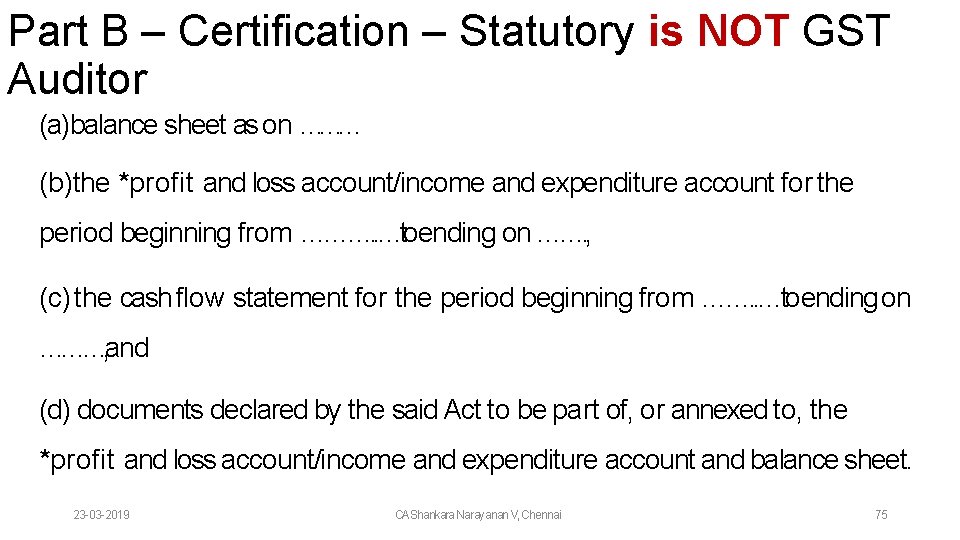
Part B – Certification – Statutory is NOT GST Auditor (a)balance sheet as on ……… (b)the *profit and loss account/income and expenditure account for the period beginning from ………. . …toending on ……. , (c) the cash flow statement for the period beginning from ……. . …toending on ………, and (d) documents declared by the said Act to be part of, or annexed to, the *profit and loss account/income and expenditure account and balance sheet. 23 -03 -2019 CAShankara Narayanan V, Chennai 75
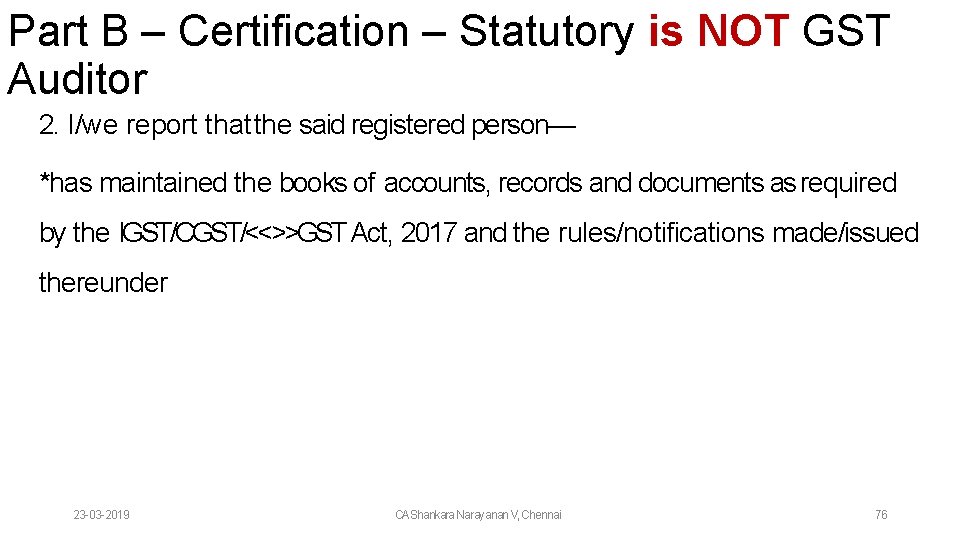
Part B – Certification – Statutory is NOT GST Auditor 2. I/we report that the said registered person— *has maintained the books of accounts, records and documents as required by the IGST/CGST/<<>>GST Act, 2017 and the rules/notifications made/issued thereunder 23 -03 -2019 CAShankara Narayanan V, Chennai 76
Part B – Certification – Statutory is NOT GST Auditor 3. The documents required to be furnished under section 35 (5) of the CGSTAct and Reconciliation Statement required to be furnished under section 44(2) of the CGSTAct is annexed herewith in Form No. GSTR-9 C. 4. In *my/our opinion and to the best of *my/our information and according to explanations given to *me/us, the particulars given in the said Form No. GSTR-9 C are true and correct subject to following observations/qualifications, if any: ……………………… 23 -03 -2019 CAShankara Narayanan V, Chennai 77
Checklists – Revenue Recognition vs Output Tax Liability • Unbilled Revenue • Revenue recognised for Accounting Purposes NOT YETin GST • Bi-monthly / quarterly billing • Work completed (30 days / 45 days) • Continuous Supply of Service – Construction / Works Contract 23 -03 -2019 CAShankara Narayanan V, Chennai 78
Checklists – Revenue Recognition vs Output Tax Liability • Deferred Revenue • Revenue recognised in GSTbut not in Accounts • GSTpaid on Invoicing • Insurance Contracts • AMC 23 -03 -2019 CAShankara Narayanan V, Chennai 79
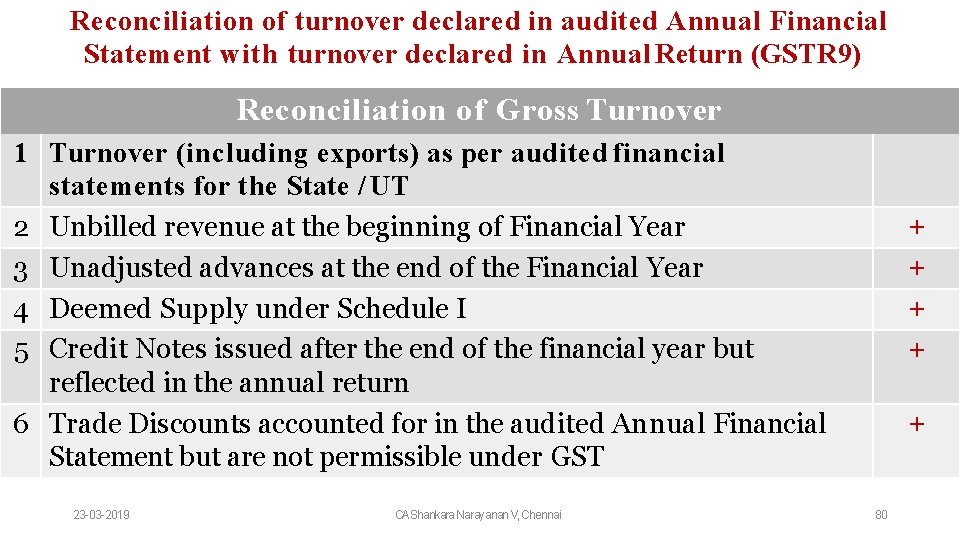
Reconciliation of turnover declared in audited Annual Financial Statement with turnover declared in Annual Return (GSTR 9) Reconciliation of Gross Turnover 1 Turnover (including exports) as per audited financial statements for the State / UT 2 Unbilled revenue at the beginning of Financial Year 3 Unadjusted advances at the end of the Financial Year 4 Deemed Supply under Schedule I 5 Credit Notes issued after the end of the financial year but reflected in the annual return 6 Trade Discounts accounted for in the audited Annual Financial Statement but are not permissible under GST 23 -03 -2019 CAShankara Narayanan V, Chennai + + + 80
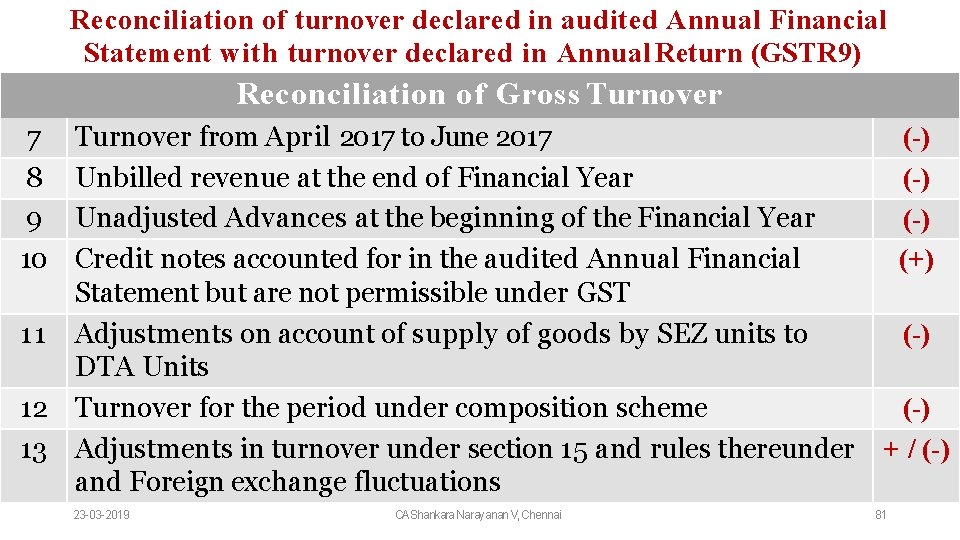
Reconciliation of turnover declared in audited Annual Financial Statement with turnover declared in Annual Return (GSTR 9) Reconciliation of Gross Turnover 7 8 9 10 Turnover from April 2017 to June 2017 Unbilled revenue at the end of Financial Year Unadjusted Advances at the beginning of the Financial Year Credit notes accounted for in the audited Annual Financial Statement but are not permissible under GST 11 Adjustments on account of supply of goods by SEZ units to DTA Units 12 Turnover for the period under composition scheme 13 Adjustments in turnover under section 15 and rules thereunder and Foreign exchange fluctuations 23 -03 -2019 CAShankara Narayanan V, Chennai (-) (-) (+) (-) + / (-) 81
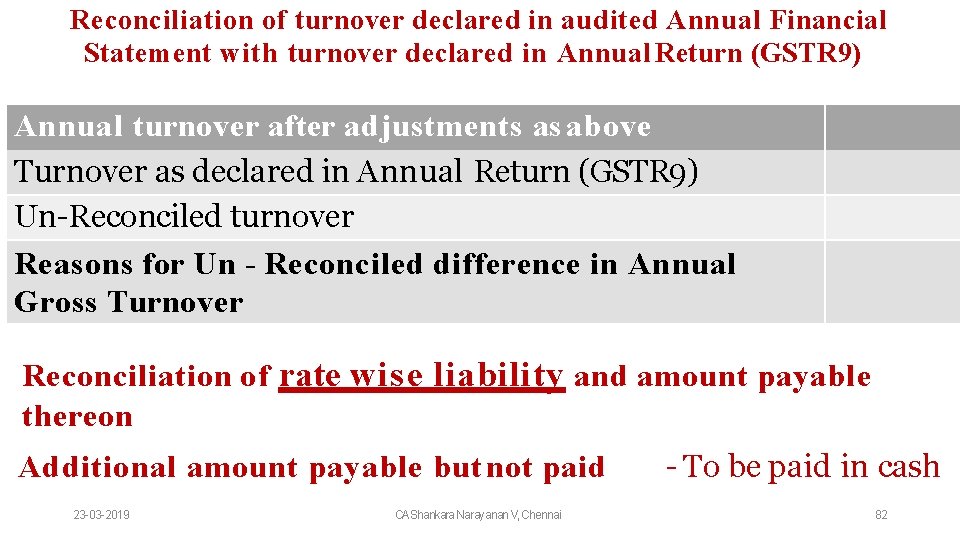
Reconciliation of turnover declared in audited Annual Financial Statement with turnover declared in Annual Return (GSTR 9) Annual turnover after adjustments as above Turnover as declared in Annual Return (GSTR 9) Un-Reconciled turnover Reasons for Un - Reconciled difference in Annual Gross Turnover Reconciliation of rate wise liability and amount payable thereon Additional amount payable but not paid 23 -03 -2019 CAShankara Narayanan V, Chennai - To be paid in cash 82
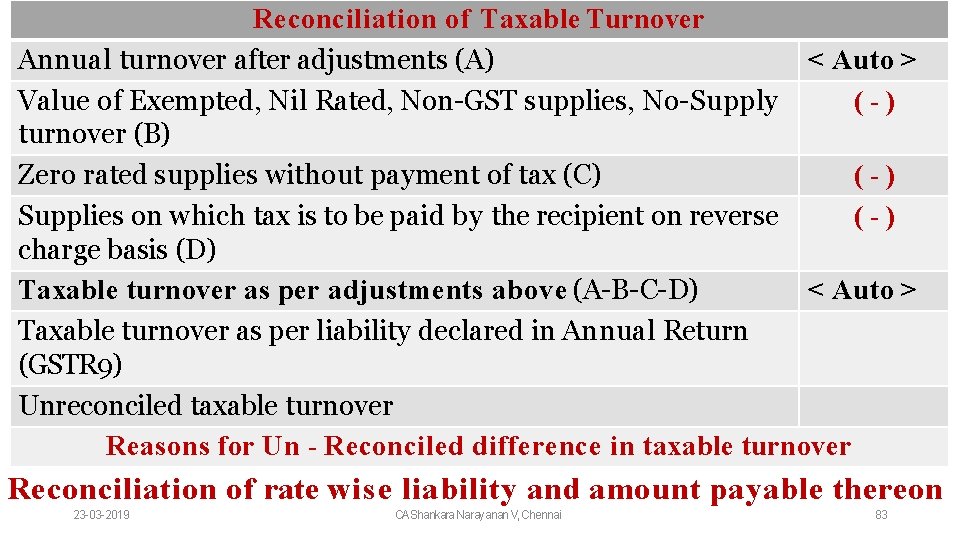
Reconciliation of Taxable Turnover Annual turnover after adjustments (A) < Auto > Value of Exempted, Nil Rated, Non-GST supplies, No-Supply (-) turnover (B) Zero rated supplies without payment of tax (C) (-) Supplies on which tax is to be paid by the recipient on reverse (-) charge basis (D) Taxable turnover as per adjustments above (A-B-C-D) < Auto > Taxable turnover as per liability declared in Annual Return (GSTR 9) Unreconciled taxable turnover Reasons for Un - Reconciled difference in taxable turnover Reconciliation of rate wise liability and amount payable thereon 23 -03 -2019 CAShankara Narayanan V, Chennai 83
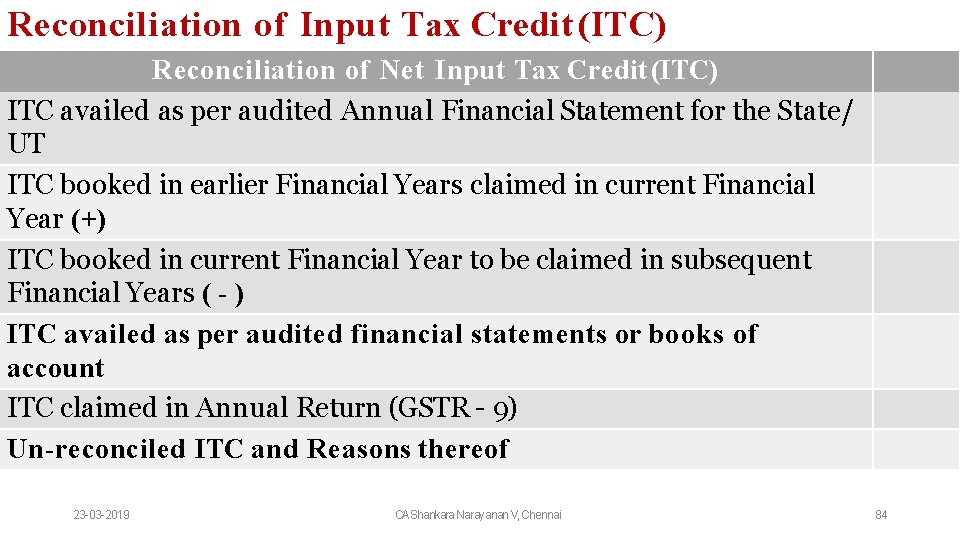
Reconciliation of Input Tax Credit (ITC) Reconciliation of Net Input Tax Credit (ITC) ITC availed as per audited Annual Financial Statement for the State/ UT ITC booked in earlier Financial Years claimed in current Financial Year (+) ITC booked in current Financial Year to be claimed in subsequent Financial Years ( - ) ITC availed as per audited financial statements or books of account ITC claimed in Annual Return (GSTR - 9) Un-reconciled ITC and Reasons thereof 23 -03 -2019 CAShankara Narayanan V, Chennai 84
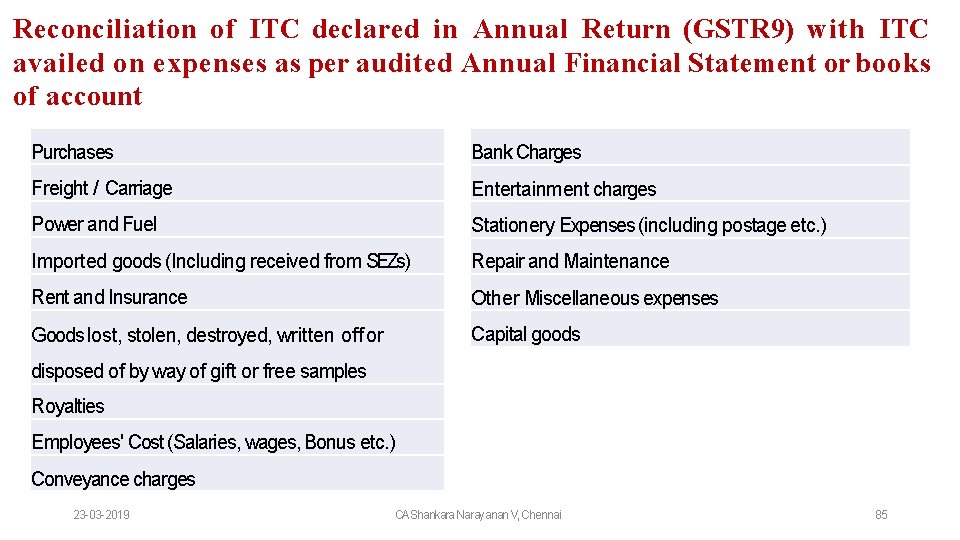
Reconciliation of ITC declared in Annual Return (GSTR 9) with ITC availed on expenses as per audited Annual Financial Statement or books of account Purchases Bank Charges Freight / Carriage Entertainment charges Power and Fuel Stationery Expenses (including postage etc. ) Imported goods (Including received from SEZs) Repair and Maintenance Rent and Insurance Other Miscellaneous expenses Goods lost, stolen, destroyed, written off or Capital goods disposed of by way of gift or free samples Royalties Employees' Cost (Salaries, wages, Bonus etc. ) Conveyance charges 23 -03 -2019 CAShankara Narayanan V, Chennai 85
Auditor's recommendation on additional Liability due to non-reconciliation Tax payable on un-reconciled difference in ITC 23 -03 -2019 CAShankara Narayanan V, Chennai 86
Thank you CA Shankar Narayanan V Mail@ shankar@gpvs. co. in 23 -03 -2019 CAShankara Narayanan V, Chennai 87