
GST UPDATES By CA Umesh Sharma Agenda Retrospective
GST UPDATES By CA Umesh Sharma
Agenda Retrospective Amendments i. e. w. e. f. 01. 07. 2017 effective from 01. 02. 2019 Notifications Circulars Expected Changes after 01. 04. 2019
Retrospective Amendments i. e. w. e. f. 01. 07. 2017

Section 7 – Scope of Supply
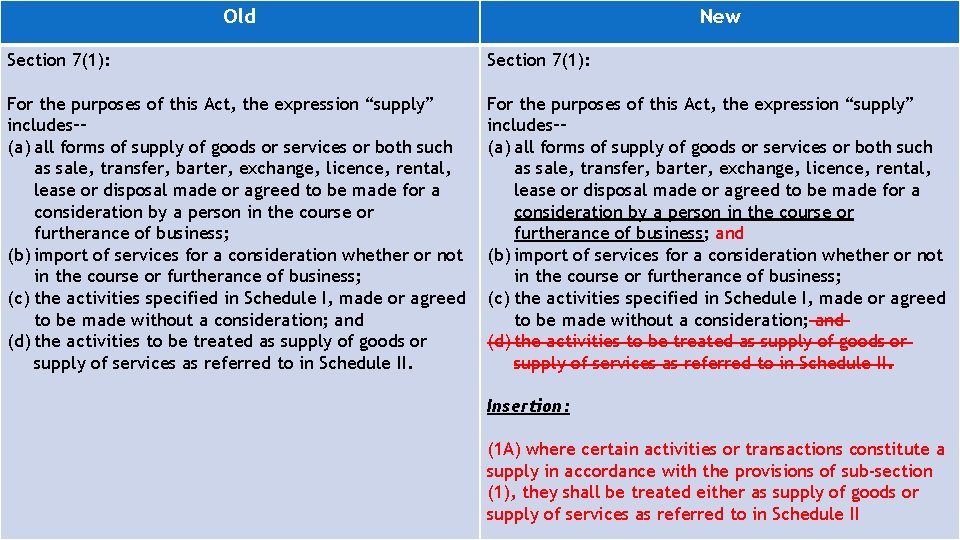
Old New Section 7(1): For the purposes of this Act, the expression “supply” includes–– (a) all forms of supply of goods or services or both such as sale, transfer, barter, exchange, licence, rental, lease or disposal made or agreed to be made for a consideration by a person in the course or furtherance of business; (b) import of services for a consideration whether or not in the course or furtherance of business; (c) the activities specified in Schedule I, made or agreed to be made without a consideration; and (d) the activities to be treated as supply of goods or supply of services as referred to in Schedule II. For the purposes of this Act, the expression “supply” includes–– (a) all forms of supply of goods or services or both such as sale, transfer, barter, exchange, licence, rental, lease or disposal made or agreed to be made for a consideration by a person in the course or furtherance of business; and (b) import of services for a consideration whether or not in the course or furtherance of business; (c) the activities specified in Schedule I, made or agreed to be made without a consideration; and (d) the activities to be treated as supply of goods or supply of services as referred to in Schedule II. Insertion: (1 A) where certain activities or transactions constitute a supply in accordance with the provisions of sub-section (1), they shall be treated either as supply of goods or supply of services as referred to in Schedule II
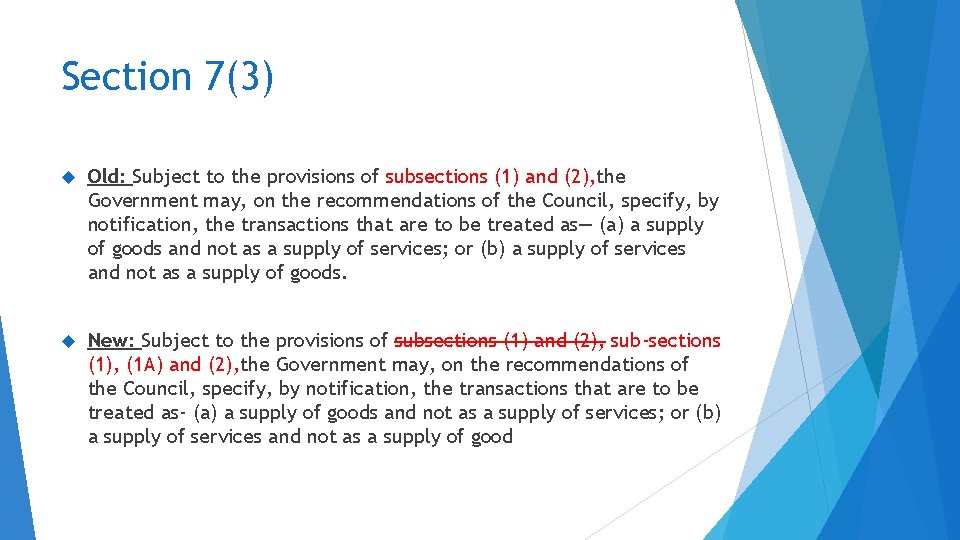
Section 7(3) Old: Subject to the provisions of subsections (1) and (2), the Government may, on the recommendations of the Council, specify, by notification, the transactions that are to be treated as— (a) a supply of goods and not as a supply of services; or (b) a supply of services and not as a supply of goods. New: Subject to the provisions of subsections (1) and (2), sub-sections (1), (1 A) and (2), the Government may, on the recommendations of the Council, specify, by notification, the transactions that are to be treated as- (a) a supply of goods and not as a supply of services; or (b) a supply of services and not as a supply of good

Section 140 (1)- Transitional arrangements for Input Tax Credit Old : A registered person, other than a person opting to pay tax under section 10, shall be entitled to take, in his electronic credit ledger, the amount of CENVAT credit carried forward in the return relating to the period ending with the day immediately preceding the appointed day, furnished by him under the existing law in such manner as may be prescribed New : A registered person, other than a person opting to pay tax under section 10, shall be entitled to take, in his electronic credit ledger, the amount of CENVAT credit of eligible duties carried forward in the return relating to the period ending with the day immediately preceding the appointed day, furnished by him under the existing law in such manner as may be prescribed
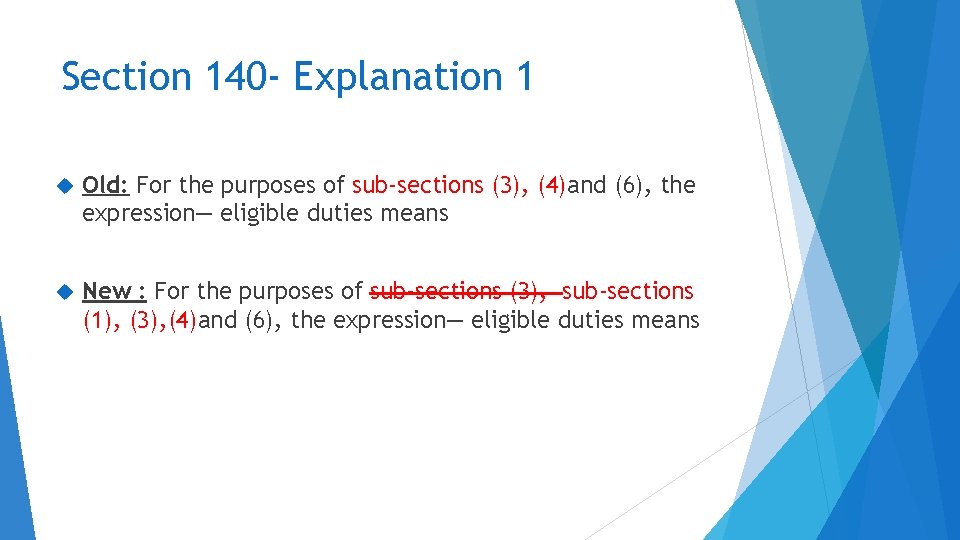
Section 140 - Explanation 1 Old: For the purposes of sub-sections (3), (4)and (6), the expression― eligible duties means New : For the purposes of sub-sections (3), sub-sections (1), (3), (4)and (6), the expression― eligible duties means
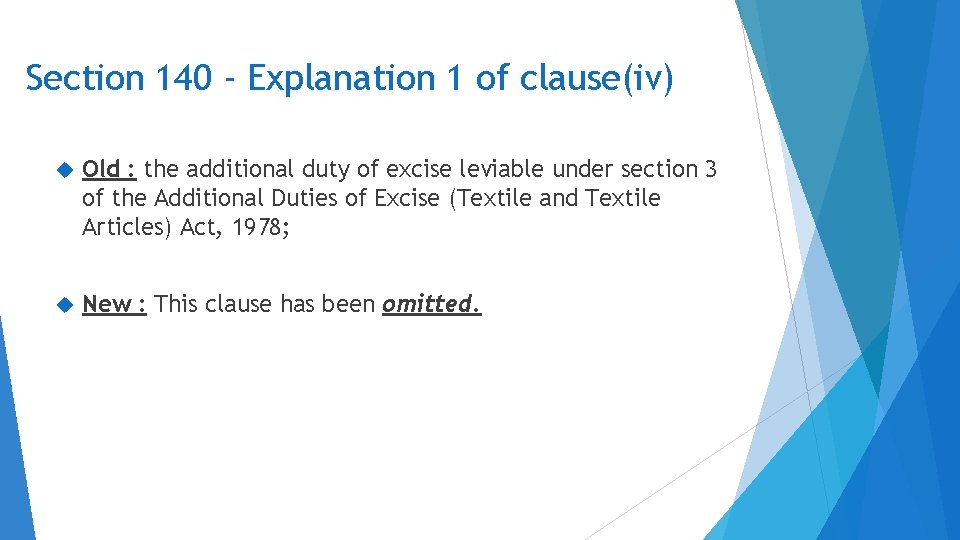
Section 140 - Explanation 1 of clause(iv) Old : the additional duty of excise leviable under section 3 of the Additional Duties of Excise (Textile and Textile Articles) Act, 1978; New : This clause has been omitted.
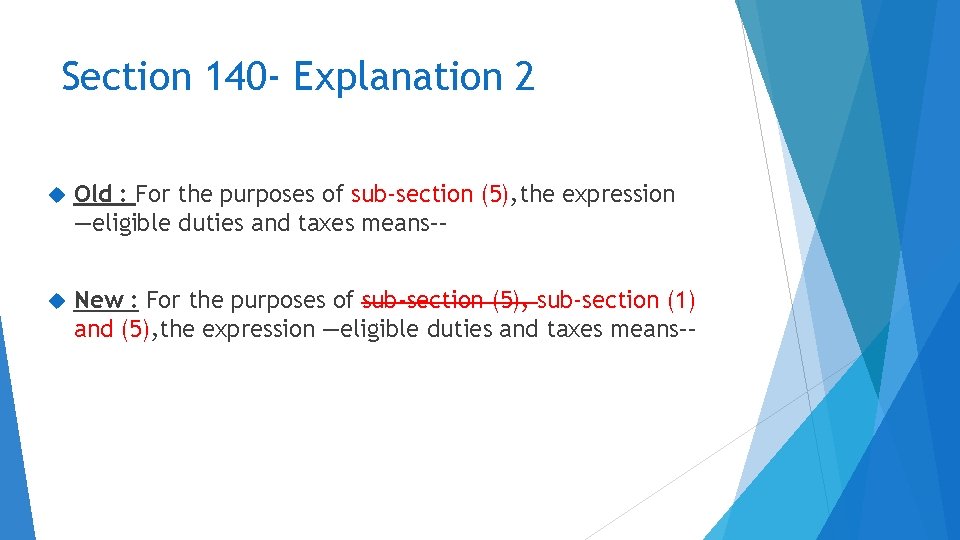
Section 140 - Explanation 2 Old : For the purposes of sub-section (5), the expression ―eligible duties and taxes means–– New : For the purposes of sub-section (5), sub-section (1) and (5), the expression ―eligible duties and taxes means––
Section 140 - Explanation 2 of clause(iv) Old : the additional duty of excise leviable under section 3 of the Additional Duties of Excise (Textile and Textile Articles) Act, 1978; New : This clause has been omitted
Section 140 - Explanation 3 New Insertion For removal of doubts, it is hereby clarified that the expression ―eligible duties and taxes excludes any cess which has not been specified in Explanation 1 or Explanation 2 and any cess which is collected as additional duty of customs under sub-section (1) of section 3 of the Customs Tariff Act, 1975.
Schedule 2 - Heading Old : Activities to be treated as supply of goods or supply of service New : Activities or transactions to be treated as supply of goods or supply of services
Amendments effective from 01. 02. 2019
Section 2(4)- Definition of Adjudicating Authority Old : ―adjudicating authority means any authority, appointed or authorised to pass any order or decision under this Act, but does not include the Central Board of Excise and Customs, the Revisional Authority, the Authority for Advance Ruling, the Appellate Authority and the Appellate Tribunal; New : adjudicating authority means any authority, appointed or authorised to pass any order or decision under this Act, but does not include the Central Board of Indirect Taxes and Customs, the Revisional Authority, the Authority for Advance Ruling, the Appellate Authority, the Appellate Tribunal and the Authority referred to in sub-section (2) of section 171”
Section 2(17) (h)- Business Old : services provided by a race club by way of totalisator or a licence to bookmaker in such club; and New : activities of a race club including by way of totalisator or a license to bookmaker or activities of a licensed bookmaker in such club;
Section 2(18)- Definition of Business vertical Old : ―Business vertical means a distinguishable component of an enterprise that is engaged in the supply of individual goods or services or a group of related goods or services which is subject to risks and returns that are different from those of the other business vertical New : The whole definition is omitted
Section 2(35)- Definition of Cost Accountant Old : ―cost accountant means a cost accountant as defined in clause (c) of sub-section (1) of section 2 of the Cost and Works Accountants Act, 1959. New : Cost accountant means a cost accountant as defined in clause (c) clause (b)of sub-section (1) of section 2 of the Cost and Works Accountants Act, 1959.
Section 2(69) (f)- Definition Local Authority Old : A Development Board constituted under article 371 of the Constitution; New : A Development Board constituted under article 371 and article 371 J of the Constitution;
Section 2(102) - Definition of Services. Explanation inserted New Insertion Explanation. – For the removal of doubts, it is hereby clarified that the Expression ―services includes facilitating or arranging transactions in securities;
Section 9(4)-Levy and collection Old : The central tax in respect of the supply of taxable goods or services or both by a supplier, who is not registered, to a registered person shall be paid by such person on reverse charge basis as the recipient and all the provisions of this Act shall apply to such recipient as if he is the person liable for paying the tax in relation to the supply of such goods or services or both. New : The Government may, on the recommendations of the Council, by notification, Specify a class of registered persons who shall, in respect of supply of specified categories of goods or services or both received from an unregistered supplier, pay the tax on reverse charge basis as the recipient of such supply of goods or services or both, and all the provisions of this Act shall apply to such recipient as if he is the person liable for paying the tax in relation to such supply of goods or services or both
Section 10(1)-Composition levy Old : Notwithstanding anything to the contrary contained in this Act but subject to the provisions of sub-sections (3) and (4) of section 9, a registered person, whose aggregate turnover in the preceding financial year did not exceed fifty lakh rupees, may opt to pay, in lieu of the tax payable by him, an amount calculated at such rate as may be prescribed, but not exceeding, New : Notwithstanding anything to the contrary contained in this Act but subject to the provisions of subsections (3) and (4) of section 9, a registered person, whose aggregate turnover in the preceding financial year did not exceed fifty lakh rupees, may opt to pay, , in lieu of the tax payable by him, an amount calculated at such rate in lieu of the tax payable by him under sub-section (1) of Section 9, an amount of tax calculated at such rate as may be prescribed, but not exceeding,
Proviso to Sec 10(1) Old : Provided that the Government may, by notification, increase the said limit of fifty lakh rupees to such higher amount, not exceeding one crore rupees, as may be recommended by The Council. New : Provided that the Government may, by notification, increase the said limit of fifty lakh rupees to such higher amount, not exceeding one crore rupees one crore and fifty lakh rupees, as may be recommended by the Council. After the proviso Provided further that a person who opts to pay tax under clause (a) or clause (b) or clause (c) may supply services (other than those referred to in clause (b) of paragraph 6 of Schedule II), of value not exceeding ten percent of turnover in a State or Union territory in the preceding financial year or five lakh rupees, whichever is higher. Inserted
Section 10(2)(a) Old : he is not engaged in the supply of services other than supplies referred to in clause (b) of paragraph 6 of Schedule II; Substitution : save as provided in sub-section (1), he is not engaged in the supply of services;
Section 12(2)(a)-Time of supply of goods Old : the date of issue of invoice by the supplier or the last date on which he is required, under subsection (1)of section 31, to issue the invoice with respect to the supply; or New : the date of issue of invoice by the supplier or the last date on which he is required, under sub-section (1) section 31, to issue the invoice with respect to the supply; or
Section 13(2)(a)-Time of supply of Services Old : the date of issue of invoice by the supplier, if the invoice is issued within the period prescribed under sub-section (2)of section 31 or the date of receipt of payment, whichever is earlier; or New : the date of issue of invoice by the supplier, if the invoice is issued within the period prescribed under sub-section (2) section 31 or the date of receipt of payment, whichever is earlier; or
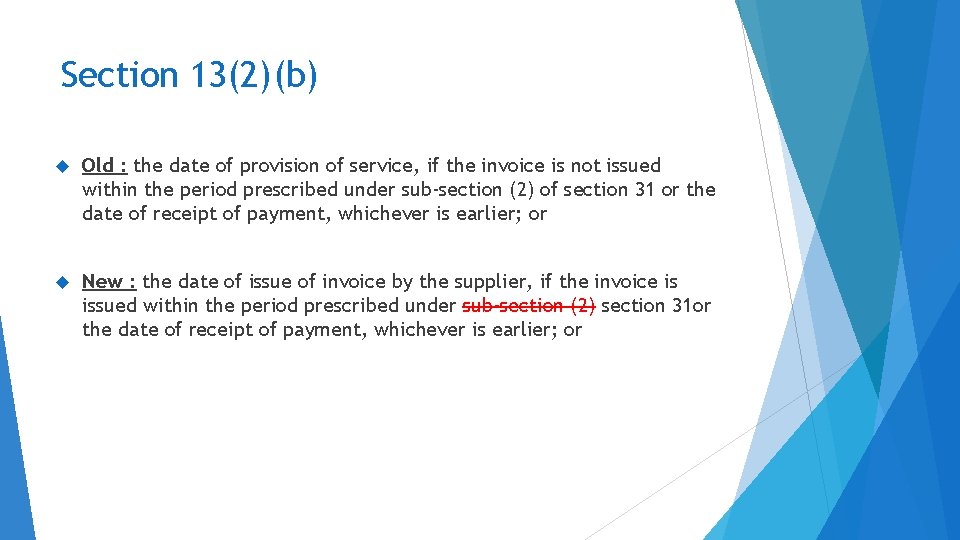
Section 13(2)(b) Old : the date of provision of service, if the invoice is not issued within the period prescribed under sub-section (2) of section 31 or the date of receipt of payment, whichever is earlier; or New : the date of issue of invoice by the supplier, if the invoice is issued within the period prescribed under sub-section (2) section 31 or the date of receipt of payment, whichever is earlier; or
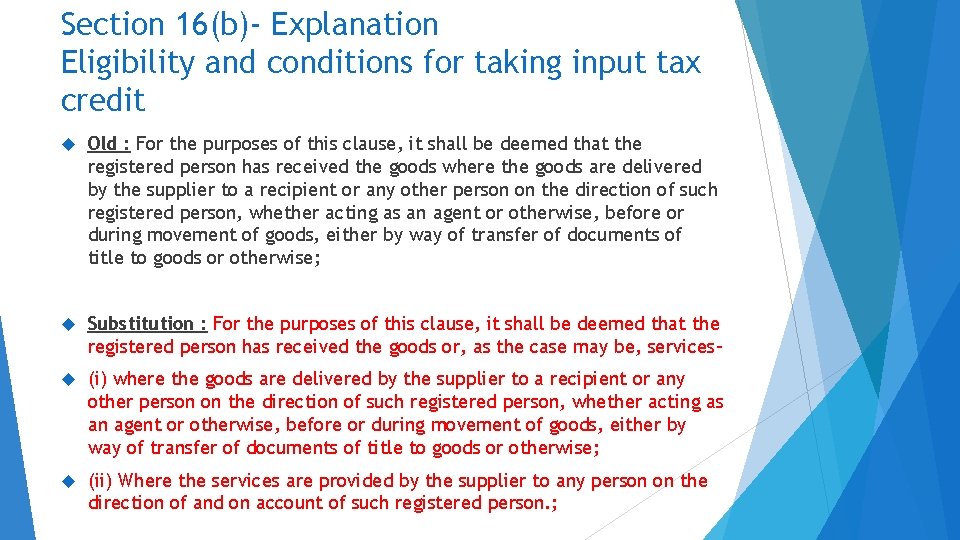
Section 16(b)- Explanation Eligibility and conditions for taking input tax credit Old : For the purposes of this clause, it shall be deemed that the registered person has received the goods where the goods are delivered by the supplier to a recipient or any other person on the direction of such registered person, whether acting as an agent or otherwise, before or during movement of goods, either by way of transfer of documents of title to goods or otherwise; Substitution : For the purposes of this clause, it shall be deemed that the registered person has received the goods or, as the case may be, services– (i) where the goods are delivered by the supplier to a recipient or any other person on the direction of such registered person, whether acting as an agent or otherwise, before or during movement of goods, either by way of transfer of documents of title to goods or otherwise; (ii) Where the services are provided by the supplier to any person on the direction of and on account of such registered person. ;
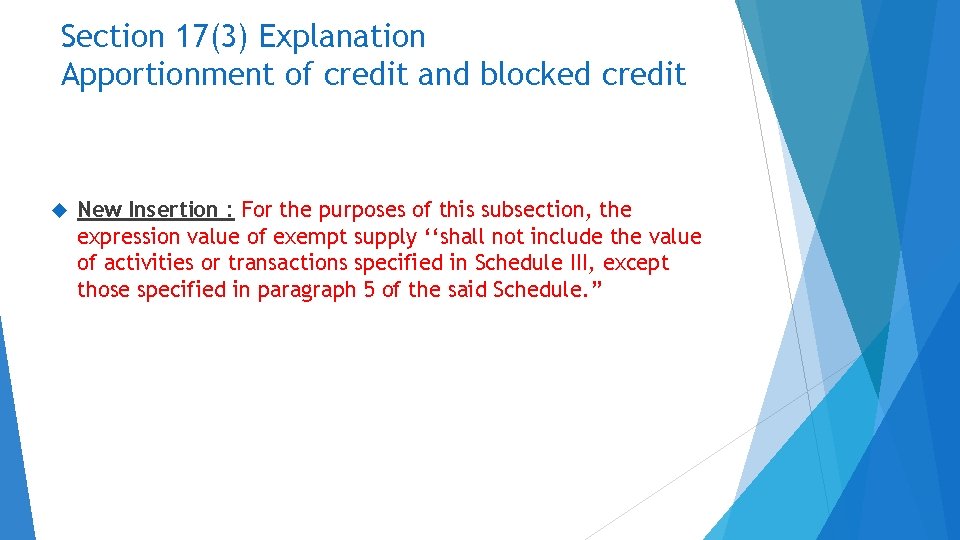
Section 17(3) Explanation Apportionment of credit and blocked credit New Insertion : For the purposes of this subsection, the expression value of exempt supply ‘‘shall not include the value of activities or transactions specified in Schedule III, except those specified in paragraph 5 of the said Schedule. ”
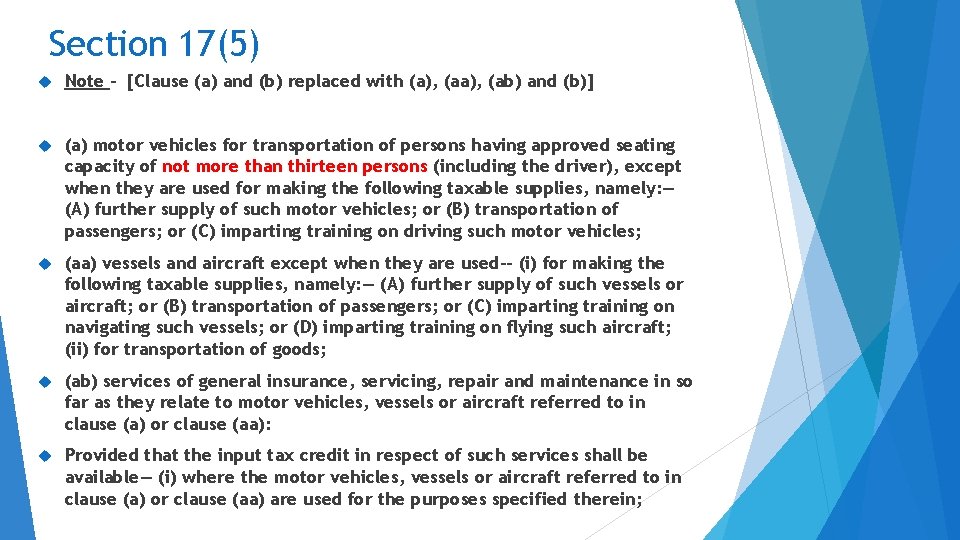
Section 17(5) Note - [Clause (a) and (b) replaced with (a), (ab) and (b)] (a) motor vehicles for transportation of persons having approved seating capacity of not more than thirteen persons (including the driver), except when they are used for making the following taxable supplies, namely: — (A) further supply of such motor vehicles; or (B) transportation of passengers; or (C) imparting training on driving such motor vehicles; (aa) vessels and aircraft except when they are used–– (i) for making the following taxable supplies, namely: — (A) further supply of such vessels or aircraft; or (B) transportation of passengers; or (C) imparting training on navigating such vessels; or (D) imparting training on flying such aircraft; (ii) for transportation of goods; (ab) services of general insurance, servicing, repair and maintenance in so far as they relate to motor vehicles, vessels or aircraft referred to in clause (a) or clause (aa): Provided that the input tax credit in respect of such services shall be available— (i) where the motor vehicles, vessels or aircraft referred to in clause (a) or clause (aa) are used for the purposes specified therein;
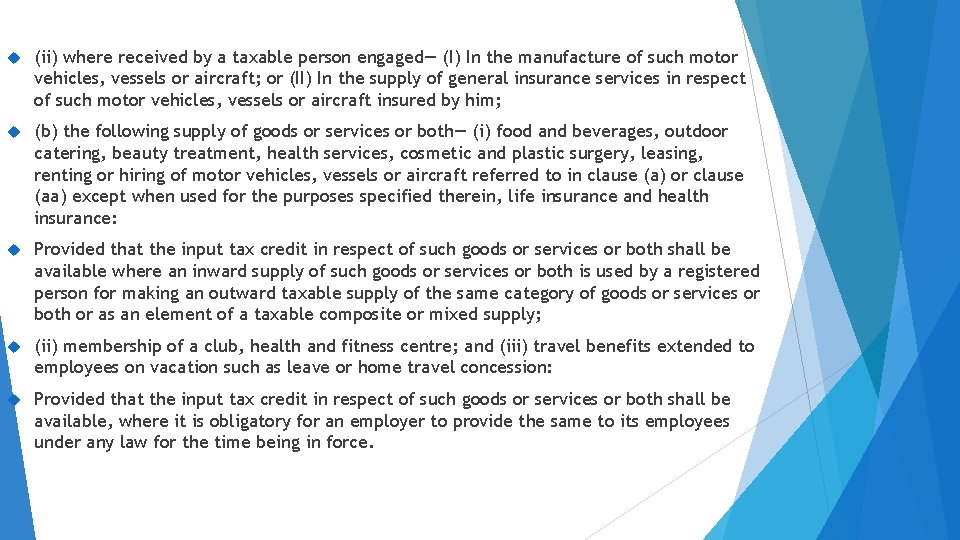
(ii) where received by a taxable person engaged— (I) In the manufacture of such motor vehicles, vessels or aircraft; or (II) In the supply of general insurance services in respect of such motor vehicles, vessels or aircraft insured by him; (b) the following supply of goods or services or both— (i) food and beverages, outdoor catering, beauty treatment, health services, cosmetic and plastic surgery, leasing, renting or hiring of motor vehicles, vessels or aircraft referred to in clause (a) or clause (aa) except when used for the purposes specified therein, life insurance and health insurance: Provided that the input tax credit in respect of such goods or services or both shall be available where an inward supply of such goods or services or both is used by a registered person for making an outward taxable supply of the same category of goods or services or both or as an element of a taxable composite or mixed supply; (ii) membership of a club, health and fitness centre; and (iii) travel benefits extended to employees on vacation such as leave or home travel concession: Provided that the input tax credit in respect of such goods or services or both shall be available, where it is obligatory for an employer to provide the same to its employees under any law for the time being in force.
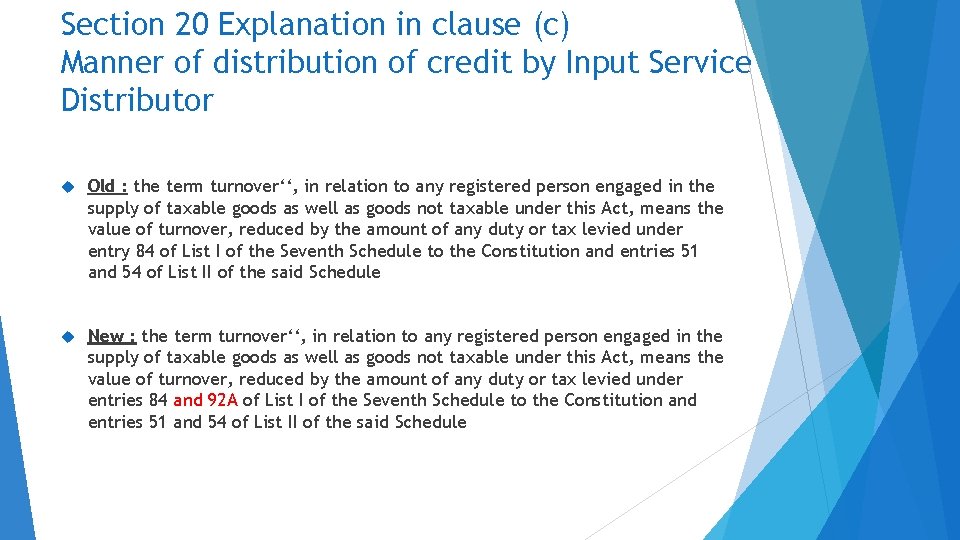
Section 20 Explanation in clause (c) Manner of distribution of credit by Input Service Distributor Old : the term turnover‘‘, in relation to any registered person engaged in the supply of taxable goods as well as goods not taxable under this Act, means the value of turnover, reduced by the amount of any duty or tax levied under entry 84 of List I of the Seventh Schedule to the Constitution and entries 51 and 54 of List II of the said Schedule New : the term turnover‘‘, in relation to any registered person engaged in the supply of taxable goods as well as goods not taxable under this Act, means the value of turnover, reduced by the amount of any duty or tax levied under entries 84 and 92 A of List I of the Seventh Schedule to the Constitution and entries 51 and 54 of List II of the said Schedule
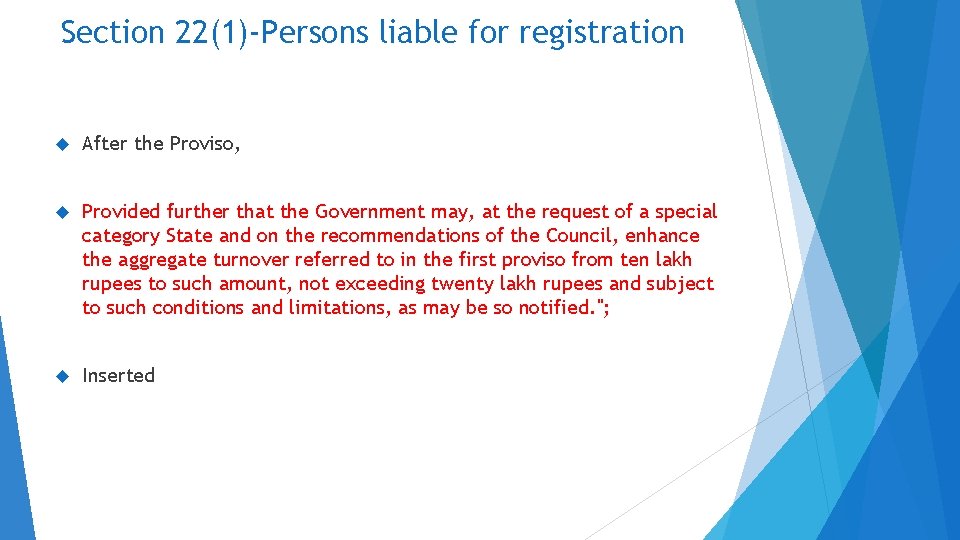
Section 22(1)-Persons liable for registration After the Proviso, Provided further that the Government may, at the request of a special category State and on the recommendations of the Council, enhance the aggregate turnover referred to in the first proviso from ten lakh rupees to such amount, not exceeding twenty lakh rupees and subject to such conditions and limitations, as may be so notified. "; Inserted
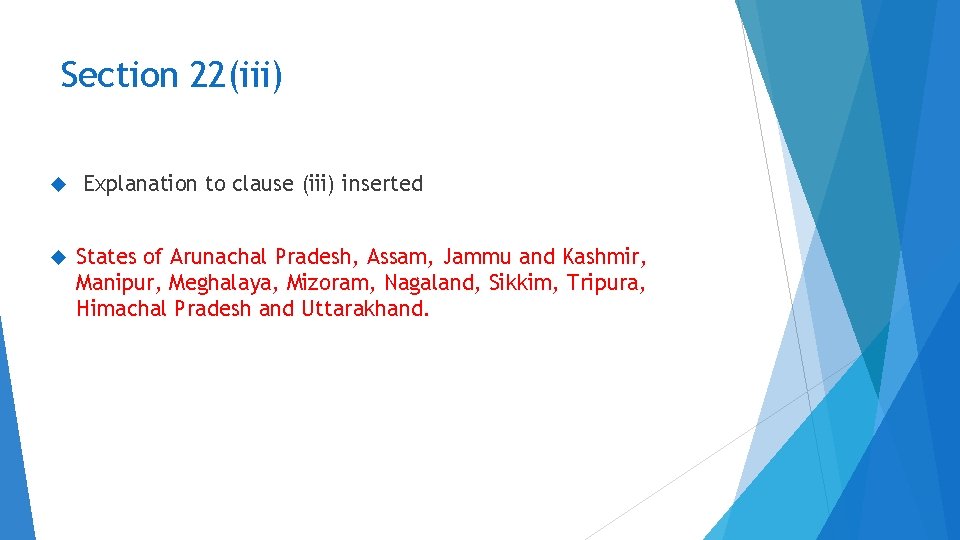
Section 22(iii) Explanation to clause (iii) inserted States of Arunachal Pradesh, Assam, Jammu and Kashmir, Manipur, Meghalaya, Mizoram, Nagaland, Sikkim, Tripura, Himachal Pradesh and Uttarakhand.
Section 24 (x)- Compulsory registration in certain cases Old : every electronic commerce operator New : Every electronic commerce operator who is required to collect tax at source under section 52
Section 25 (1) Procedure for registration After the proviso Provided further that a person having a unit, as defined in the Special Economic Zones Act, 2005, in a Special Economic Zone or being a Special Economic Zone developer shall have to apply for a separate registration, as distinct from his place of business located outside the Special Economic Zone in the same State or Union territory. "; Inserted
Section 25(2) Old : Provided that a person having multiple business verticals in a State or Union territory may be granted a separate registration for each business vertical, subject to such conditions as may be prescribed. Substitution: Provided that a person having multiple places of business in a State or Union territory may be granted a separate registration for each such place of business, subject to such conditions as may be prescribed.
Section 29 - The marginal heading is changed Old : Cancellation Of registration New : Cancellation or suspension Of registration
Section 29 (1)(c) Proviso inserted ― Provided that during pendency of the proceedings relating to cancellation of registration filed by the registered person, the registration may be suspended for such period and in such manner as may be prescribed.
Section 29(2) After the proviso Provided further that during pendency of the proceedings relating to Cancellation of registration, the proper officer may suspend the registration for such period and in such manner as may be prescribed. Inserted
Section 34(1)- Credit and Debit notes Old : Where a tax invoice has been issued for supply of any goods or services or both and the taxable value or tax charged in that tax invoice is found to exceed the taxable value or tax payable in respect of such supply, or where the goods supplied are returned by the recipient, or where goods or services or both supplied are found to be deficient, the registered person, who has supplied such goods or services or both, may issue to the recipient a credit note containing such particulars as may be prescribed. New : Where a tax invoice has Where one or more tax invoices have been issued for supply of any goods or services or both and the taxable value or tax charged in that tax invoice is found to exceed the taxable value or tax payable in respect of such supply, or where the goods supplied are returned by the recipient, or where goods or services or both supplied are found to be deficient, the registered person, who has supplied such goods or services or both, may issue to the recipient a credit note one or more credit notes for supplies made in a financial year containing such particulars as may be prescribed.
Section 34(3) Old : Where a tax invoice has been issued for supply of any goods or services or both and the taxable value or tax charged in that tax invoice is found to be less than the taxable value or tax payable in respect of such supply, the registered person, who has supplied such goods or services or both, shall issue to the recipient a debit note containing such particulars as may be prescribed. New : Where a tax invoice has Where one or more tax invoices have been issued for supply of any goods or services or both and the taxable value or tax charged in that tax invoice is found to be less than the taxable value or tax payable in respect of such supply, the registered person, who has supplied such goods or services or both, shall issue to the recipient a debit note one or more debit notes for supplies made in a financial year containing such particulars as may be prescribed.
Section 35(5)- Accounts and other records Proviso inserted Provided that nothing contained in this sub-section shall apply to any department of the Central Government or a State Government or a local authority, whose books of account are subject to audit by the Comptroller and Auditor-General of India or an auditor appointed for auditing the accounts of local authorities under any law for the time being in force.
Section 48(2) Goods and services tax practitioners Old : A registered person may authorise an approved goods and services tax practitioner to furnish the details of outward supplies under section 37, the details of inward supplies under section 38 and the return under section 39 or section 44 or section 45 in such manner as may be prescribed. New : A registered person may authorise an approved goods and services tax practitioner to furnish the details of outward supplies under section 37, the details of inward supplies under section 38 and the return under section 39 or section 44 section 45 and to perform such other functions in such manner as may be prescribed
Section 49(5)(c)- Payment of tax, interest, penalty and other amounts proviso inserted Provided that the input tax credit on account of State tax shall be utilised towards payment of integrated tax only where the balance of the input tax credit on account of central tax is not available for payment of integrated tax;
Section 49(5)(d) proviso inserted ―Provided that the input tax credit on account of Union territory tax shall be utilised towards payment of integrated tax only where the balance of the input tax credit on account of central tax is not available for payment of integrated tax;
Section 49 A New Insertion Notwithstanding anything contained in section 49, the input tax credit on account of Central tax, State tax or Union territory tax shall be utilised towards payment of Integrated tax, Central tax, State tax or Union territory tax, as the case may be, only after the input tax credit available on account of Integrated tax has first been utilised fully towards such payment.
Section 49 B New Insertion Notwithstanding anything contained in this Chapter and subject to the provisions of clause (e) and clause (f) of sub-section (5) of section 49, the Government may, on the recommendations of the Council, prescribe the order and manner of utilisation of the input tax credit on account of Integrated tax, Central tax, State tax or Union territory tax, as the case may be, towards payment of any such tax.
Section 52(9)-Collection of tax at source Old : Where the details of outward supplies furnished by the operator under sub-section (4) do not match with the corresponding details furnished by the supplier undersection 37, the discrepancy shall be communicated to both persons in such manner and within such time as may be prescribed. New : Where the details of outward supplies furnished by the operator under sub-section (4) do not match with the corresponding details furnished by the supplier under section 37 or section 39, the discrepancy shall be communicated to both persons in such manner and within such time as may be prescribed.
Section 54(8)(a)- Refund of tax: NON APPLICABILITY OF UNJUST ENRICHMENT Old : refund of tax paid on zero-rated supplies of goods or services or both or on inputs or input services used in making such zero-rated supplies; New : refund of tax paid on zero- rated supplies export of goods or services or both or on inputs or input services used in making such exports;
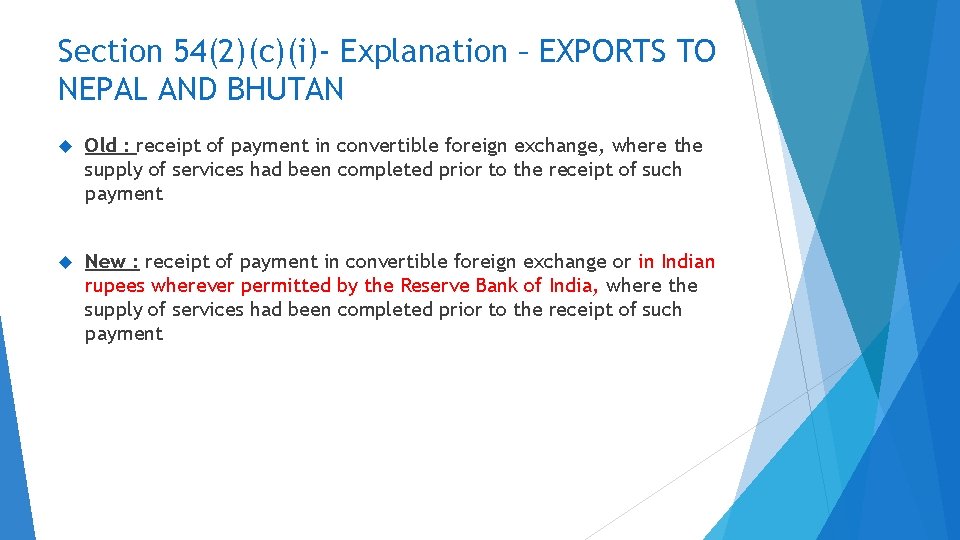
Section 54(2)(c)(i)- Explanation – EXPORTS TO NEPAL AND BHUTAN Old : receipt of payment in convertible foreign exchange, where the supply of services had been completed prior to the receipt of such payment New : receipt of payment in convertible foreign exchange or in Indian rupees wherever permitted by the Reserve Bank of India, where the supply of services had been completed prior to the receipt of such payment
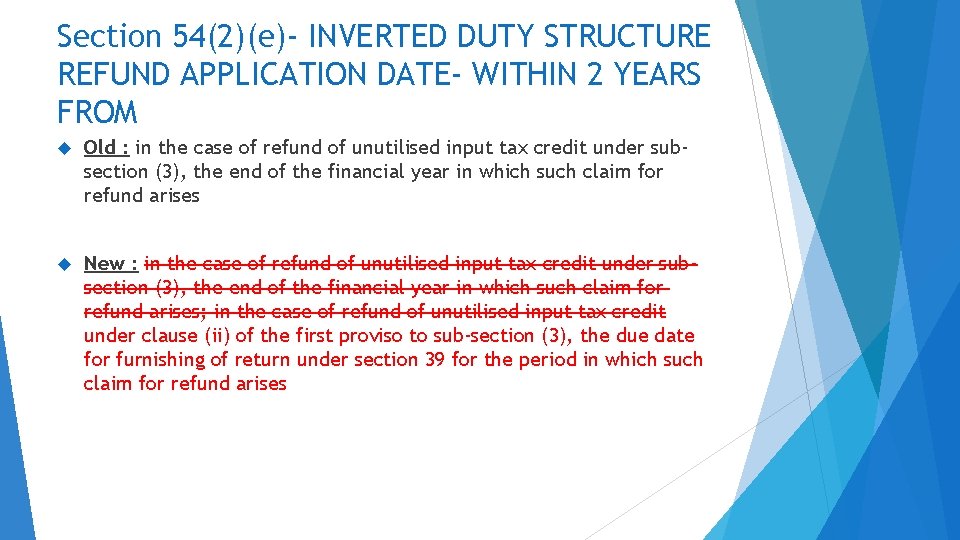
Section 54(2)(e)- INVERTED DUTY STRUCTURE REFUND APPLICATION DATE- WITHIN 2 YEARS FROM Old : in the case of refund of unutilised input tax credit under subsection (3), the end of the financial year in which such claim for refund arises New : in the case of refund of unutilised input tax credit under subsection (3), the end of the financial year in which such claim for refund arises; in the case of refund of unutilised input tax credit under clause (ii) of the first proviso to sub-section (3), the due date for furnishing of return under section 39 for the period in which such claim for refund arises
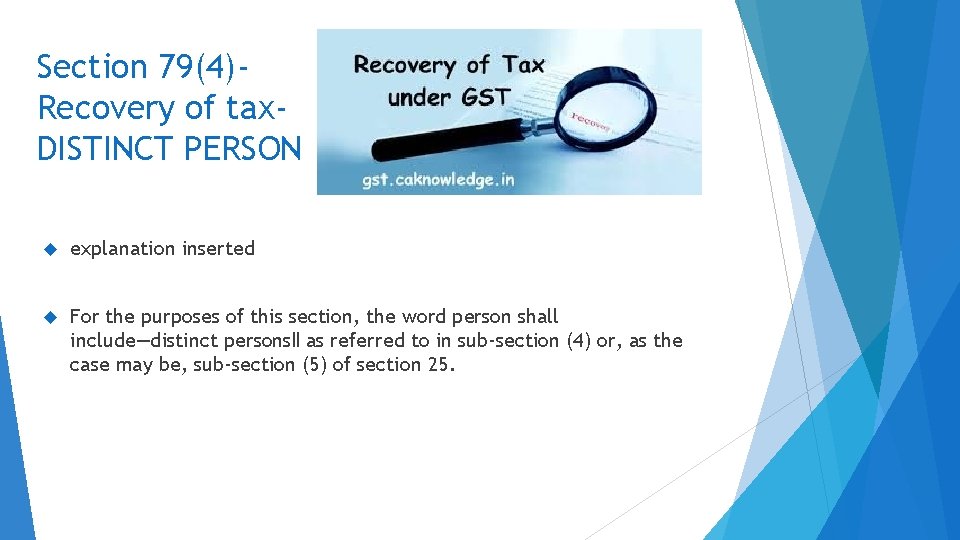
Section 79(4)Recovery of tax. DISTINCT PERSON explanation inserted For the purposes of this section, the word person shall include―distinct persons‖ as referred to in sub-section (4) or, as the case may be, sub-section (5) of section 25.
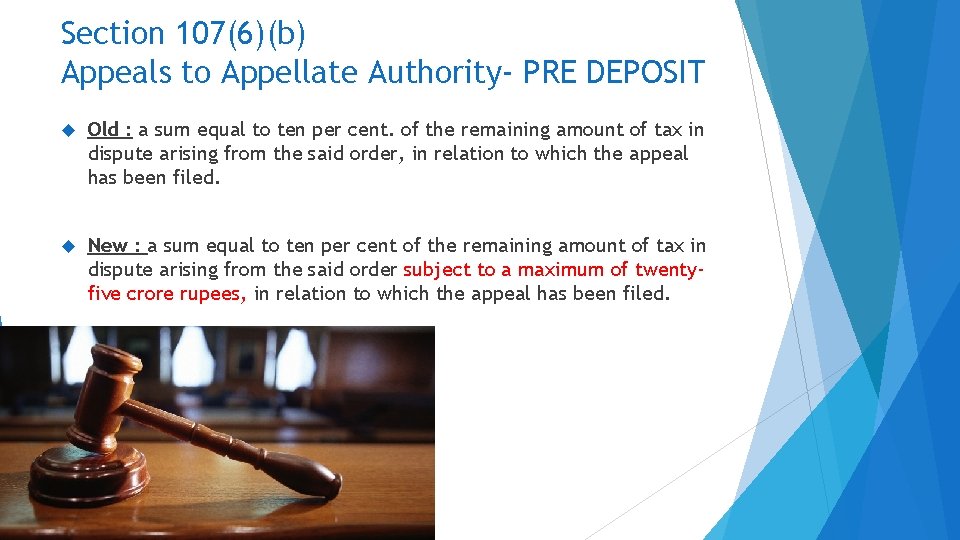
Section 107(6)(b) Appeals to Appellate Authority- PRE DEPOSIT Old : a sum equal to ten per cent. of the remaining amount of tax in dispute arising from the said order, in relation to which the appeal has been filed. New : a sum equal to ten per cent of the remaining amount of tax in dispute arising from the said order subject to a maximum of twentyfive crore rupees, in relation to which the appeal has been filed.
Section 112(8)(b)-Appeals to Appellate Tribunal- PRE DEPOSIT Old : a sum equal to twenty per cent. of the remaining amount of tax in dispute, in addition to the amount paid under sub-section (6) of section 107, arising from the said order, in relation to which the appeal has been filed New : a sum equal to twenty per cent. of the remaining amount of tax in dispute, in addition to the amount paid under sub-section (6) of section 107, arising from the said order subject to a maximum of fifty crore rupees, in relation to which the appeal has been filed
Section 129(6)-Detention, seizure and release of goods and conveyances in transit- TIME LIMIT TO PAY TAX Old : Where the person transporting any goods or the owner of the goods fails to pay the amount of tax and penalty as provided in subsection (1) within seven days of such detention or seizure, further proceedings shall be initiated in accordance with the provisions of section 130 New : Where the person transporting any goods or the owner of the goods fails to pay the amount of tax and penalty as provided in subsection (1) within seven days fourteen days of such detention or seizure, further proceedings shall be initiated in accordance with the provisions of section 130:
Section 143(1)(b)-Job work procedure- TIME LIMIT FOR RECEIVING BACK THE GOODS SENT ON JOB WORK after the proviso, the following proviso inserted Provided further that the period of one year and three years may, on sufficient cause being shown, be extended by the Commissioner for a further period not exceeding one year and two years respectively.
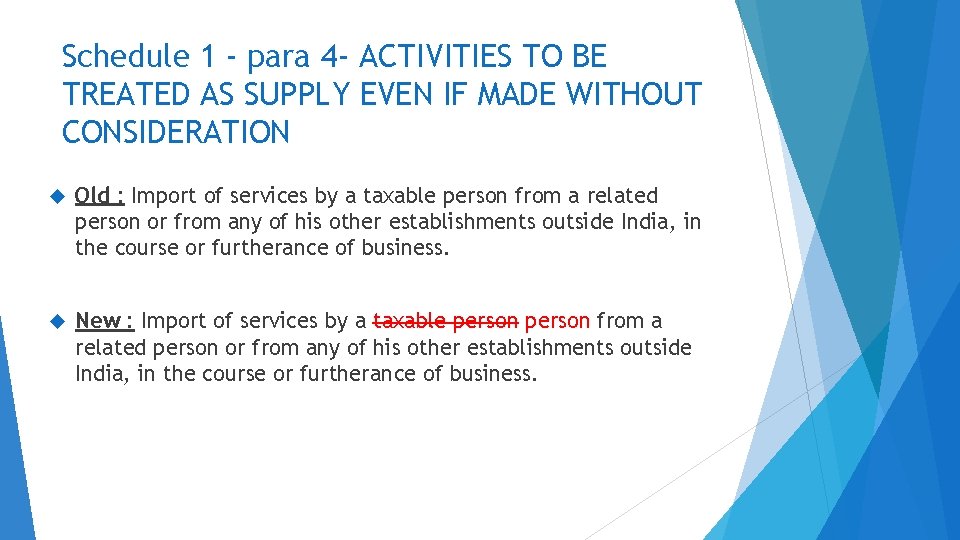
Schedule 1 - para 4 - ACTIVITIES TO BE TREATED AS SUPPLY EVEN IF MADE WITHOUT CONSIDERATION Old : Import of services by a taxable person from a related person or from any of his other establishments outside India, in the course or furtherance of business. New : Import of services by a taxable person from a related person or from any of his other establishments outside India, in the course or furtherance of business.
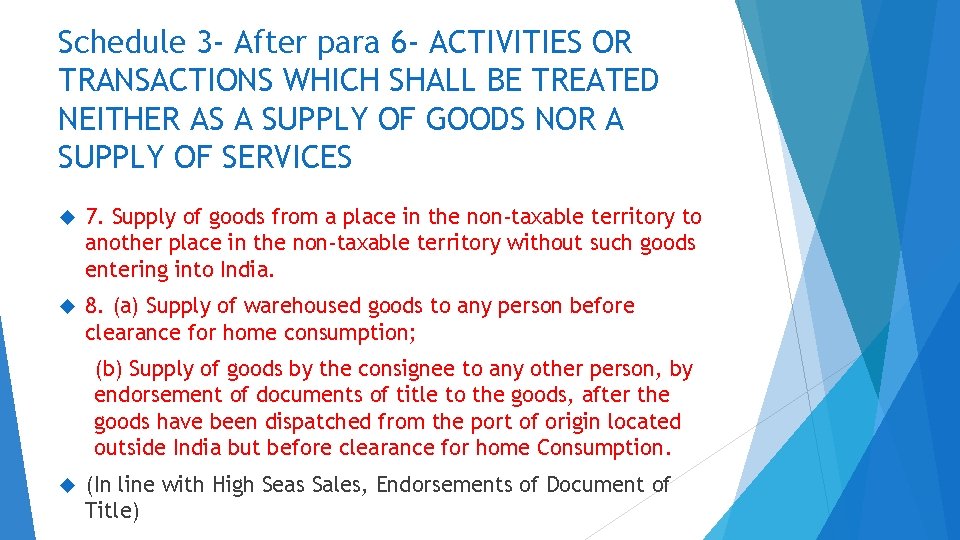
Schedule 3 - After para 6 - ACTIVITIES OR TRANSACTIONS WHICH SHALL BE TREATED NEITHER AS A SUPPLY OF GOODS NOR A SUPPLY OF SERVICES 7. Supply of goods from a place in the non-taxable territory to another place in the non-taxable territory without such goods entering into India. 8. (a) Supply of warehoused goods to any person before clearance for home consumption; (b) Supply of goods by the consignee to any other person, by endorsement of documents of title to the goods, after the goods have been dispatched from the port of origin located outside India but before clearance for home Consumption. (In line with High Seas Sales, Endorsements of Document of Title)
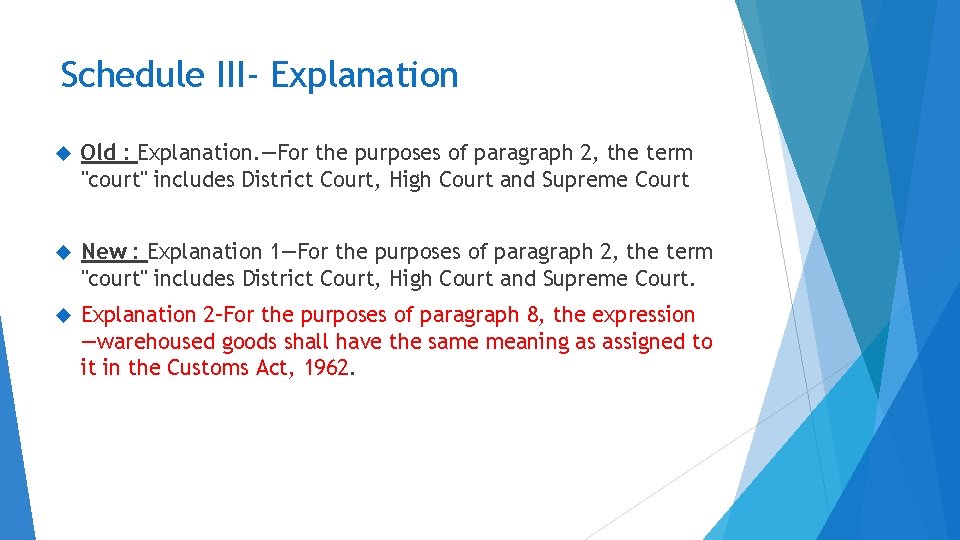
Schedule III- Explanation Old : Explanation. —For the purposes of paragraph 2, the term "court" includes District Court, High Court and Supreme Court New : Explanation 1—For the purposes of paragraph 2, the term "court" includes District Court, High Court and Supreme Court. Explanation 2–For the purposes of paragraph 8, the expression ―warehoused goods shall have the same meaning as assigned to it in the Customs Act, 1962.
Notifications
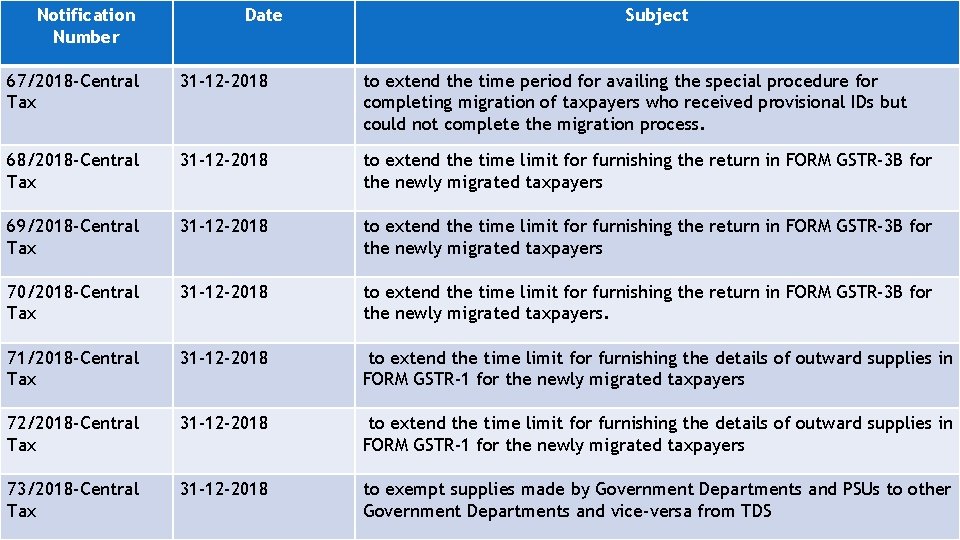
Notification Number Date Subject 67/2018 -Central Tax 31 -12 -2018 to extend the time period for availing the special procedure for completing migration of taxpayers who received provisional IDs but could not complete the migration process. 68/2018 -Central Tax 31 -12 -2018 to extend the time limit for furnishing the return in FORM GSTR-3 B for the newly migrated taxpayers 69/2018 -Central Tax 31 -12 -2018 to extend the time limit for furnishing the return in FORM GSTR-3 B for the newly migrated taxpayers 70/2018 -Central Tax 31 -12 -2018 to extend the time limit for furnishing the return in FORM GSTR-3 B for the newly migrated taxpayers. 71/2018 -Central Tax 31 -12 -2018 to extend the time limit for furnishing the details of outward supplies in FORM GSTR-1 for the newly migrated taxpayers 72/2018 -Central Tax 31 -12 -2018 to extend the time limit for furnishing the details of outward supplies in FORM GSTR-1 for the newly migrated taxpayers 73/2018 -Central Tax 31 -12 -2018 to exempt supplies made by Government Departments and PSUs to other Government Departments and vice-versa from TDS
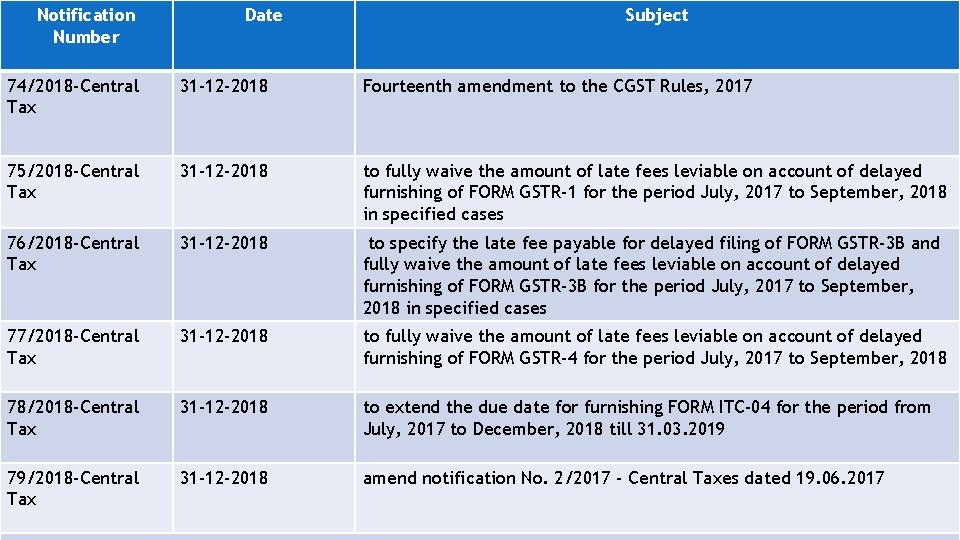
Notification Number Date Subject 74/2018 -Central Tax 31 -12 -2018 Fourteenth amendment to the CGST Rules, 2017 75/2018 -Central Tax 31 -12 -2018 to fully waive the amount of late fees leviable on account of delayed furnishing of FORM GSTR-1 for the period July, 2017 to September, 2018 in specified cases 76/2018 -Central Tax 31 -12 -2018 to specify the late fee payable for delayed filing of FORM GSTR-3 B and fully waive the amount of late fees leviable on account of delayed furnishing of FORM GSTR-3 B for the period July, 2017 to September, 2018 in specified cases 77/2018 -Central Tax 31 -12 -2018 to fully waive the amount of late fees leviable on account of delayed furnishing of FORM GSTR-4 for the period July, 2017 to September, 2018 78/2018 -Central Tax 31 -12 -2018 to extend the due date for furnishing FORM ITC-04 for the period from July, 2017 to December, 2018 till 31. 03. 2019 79/2018 -Central Tax 31 -12 -2018 amend notification No. 2/2017 - Central Taxes dated 19. 06. 2017
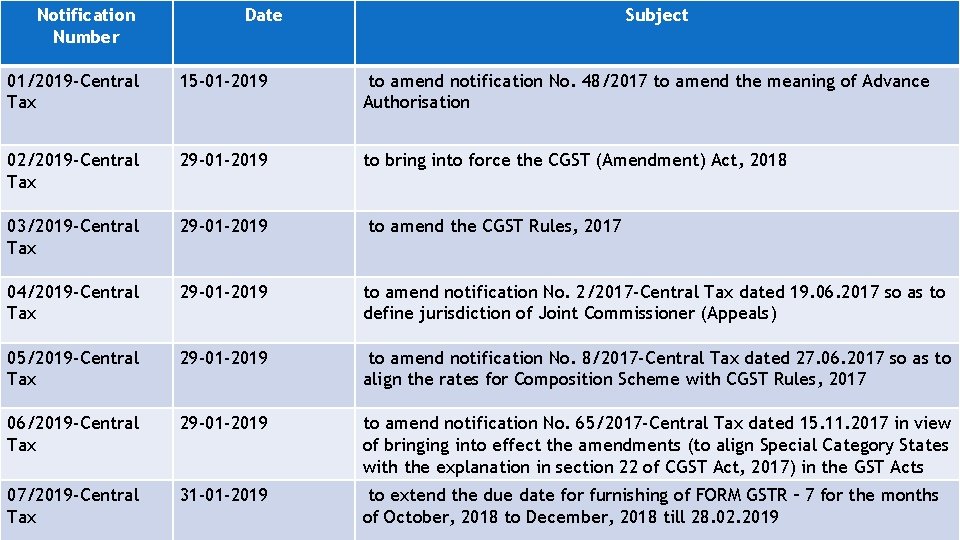
Notification Number Date Subject 01/2019 -Central Tax 15 -01 -2019 to amend notification No. 48/2017 to amend the meaning of Advance Authorisation 02/2019 -Central Tax 29 -01 -2019 to bring into force the CGST (Amendment) Act, 2018 03/2019 -Central Tax 29 -01 -2019 to amend the CGST Rules, 2017 04/2019 -Central Tax 29 -01 -2019 to amend notification No. 2/2017 -Central Tax dated 19. 06. 2017 so as to define jurisdiction of Joint Commissioner (Appeals) 05/2019 -Central Tax 29 -01 -2019 to amend notification No. 8/2017 -Central Tax dated 27. 06. 2017 so as to align the rates for Composition Scheme with CGST Rules, 2017 06/2019 -Central Tax 29 -01 -2019 to amend notification No. 65/2017 -Central Tax dated 15. 11. 2017 in view of bringing into effect the amendments (to align Special Category States with the explanation in section 22 of CGST Act, 2017) in the GST Acts 07/2019 -Central Tax 31 -01 -2019 to extend the due date for furnishing of FORM GSTR – 7 for the months of October, 2018 to December, 2018 till 28. 02. 2019
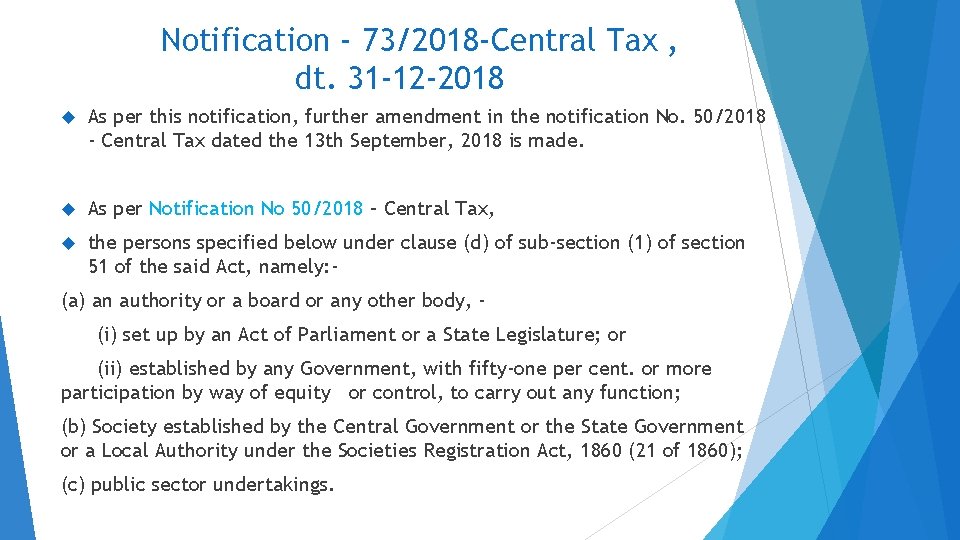
Notification - 73/2018 -Central Tax , dt. 31 -12 -2018 As per this notification, further amendment in the notification No. 50/2018 - Central Tax dated the 13 th September, 2018 is made. As per Notification No 50/2018 – Central Tax, the persons specified below under clause (d) of sub-section (1) of section 51 of the said Act, namely: - (a) an authority or a board or any other body, (i) set up by an Act of Parliament or a State Legislature; or (ii) established by any Government, with fifty-one per cent. or more participation by way of equity or control, to carry out any function; (b) Society established by the Central Government or the State Government or a Local Authority under the Societies Registration Act, 1860 (21 of 1860); (c) public sector undertakings.
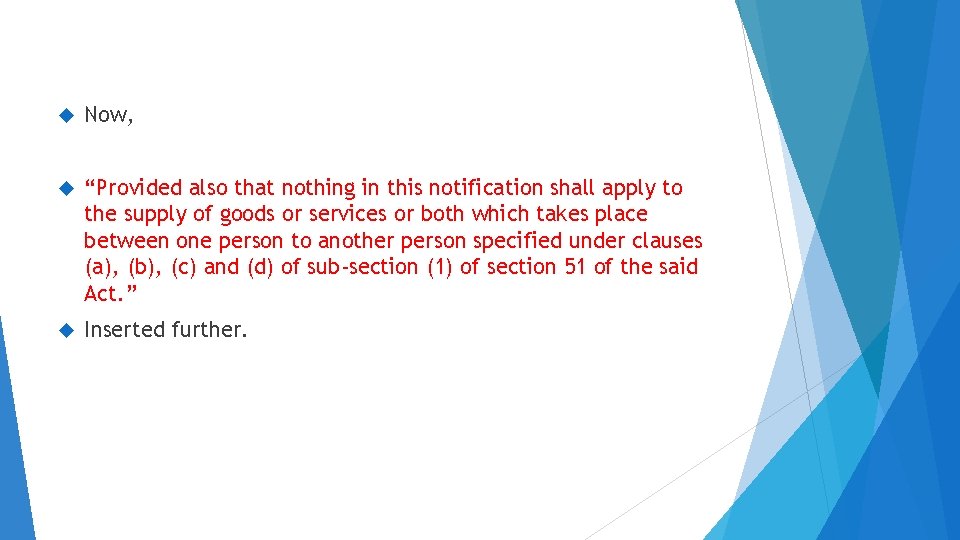
Now, “Provided also that nothing in this notification shall apply to the supply of goods or services or both which takes place between one person to another person specified under clauses (a), (b), (c) and (d) of sub-section (1) of section 51 of the said Act. ” Inserted further.
Notification - 74/2018 -Central Tax , dt. 31 -12 -2018 Through this notification, certain amendments are made in “Central Goods and Services Tax Rules, 2017”
Rule 45 - Conditions and restrictions in respect of inputs and capital goods sent to the job worker in rule 45, in sub-rule (3), after the words “received from a job worker”, the words, “or sent from one job worker to another” shall be omitted
Explanation (b) to sub-rule (5) of rule 89 – Application for refund of tax, interest, penalty, fees or any other amount in explanation (b) to sub-rule (5) of rule 89, the following clause shall be substituted, namely: - “Adjusted Total turnover” and “relevant period” shall have the same meaning as assigned to them in sub-rule (4)
Rule 101 - Audit in rule 101, in sub-rule (1), after the words “financial year”, the words “or part thereof” shall be inserted
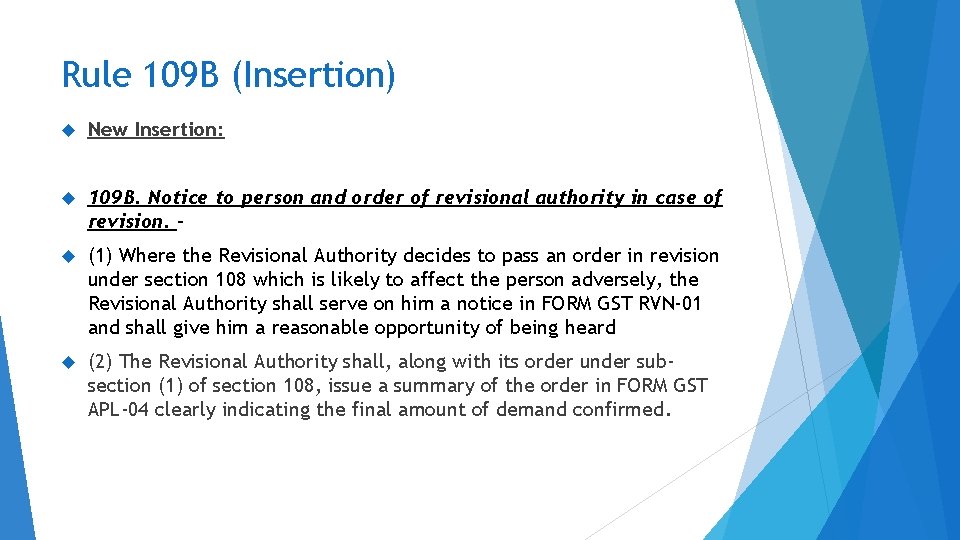
Rule 109 B (Insertion) New Insertion: 109 B. Notice to person and order of revisional authority in case of revision. – (1) Where the Revisional Authority decides to pass an order in revision under section 108 which is likely to affect the person adversely, the Revisional Authority shall serve on him a notice in FORM GST RVN-01 and shall give him a reasonable opportunity of being heard (2) The Revisional Authority shall, along with its order under subsection (1) of section 108, issue a summary of the order in FORM GST APL-04 clearly indicating the final amount of demand confirmed.
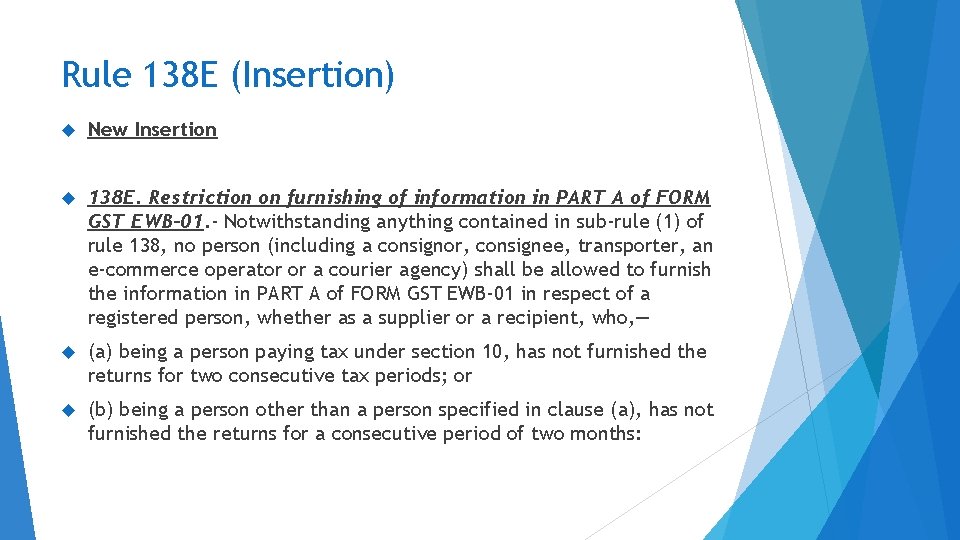
Rule 138 E (Insertion) New Insertion 138 E. Restriction on furnishing of information in PART A of FORM GST EWB-01. - Notwithstanding anything contained in sub-rule (1) of rule 138, no person (including a consignor, consignee, transporter, an e-commerce operator or a courier agency) shall be allowed to furnish the information in PART A of FORM GST EWB-01 in respect of a registered person, whether as a supplier or a recipient, who, — (a) being a person paying tax under section 10, has not furnished the returns for two consecutive tax periods; or (b) being a person other than a person specified in clause (a), has not furnished the returns for a consecutive period of two months:
Notification - 03/2019 -Central Tax , dt. 29 -01 -2019 Through this notification, certain amendments are made in “Central Goods and Services Tax Rules, 2017”
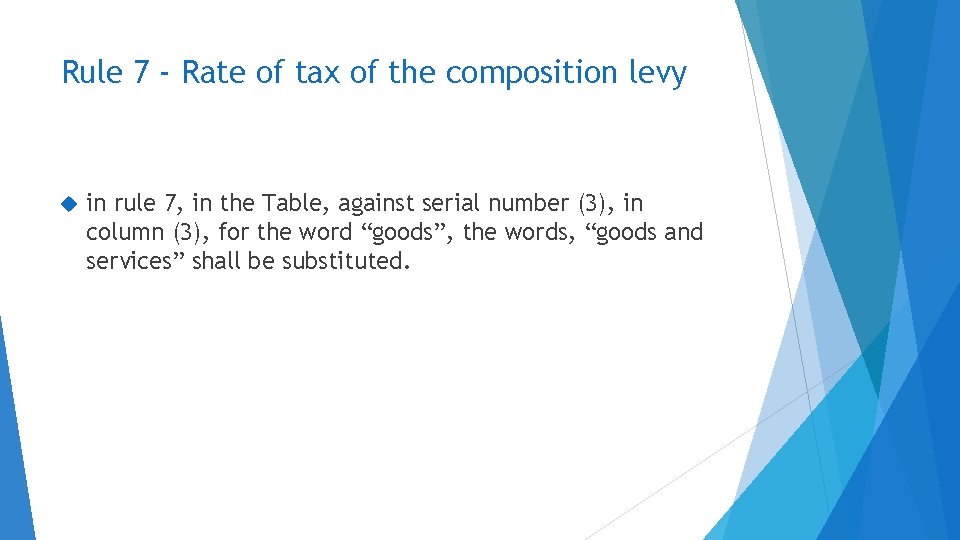
Rule 7 - Rate of tax of the composition levy in rule 7, in the Table, against serial number (3), in column (3), for the word “goods”, the words, “goods and services” shall be substituted.
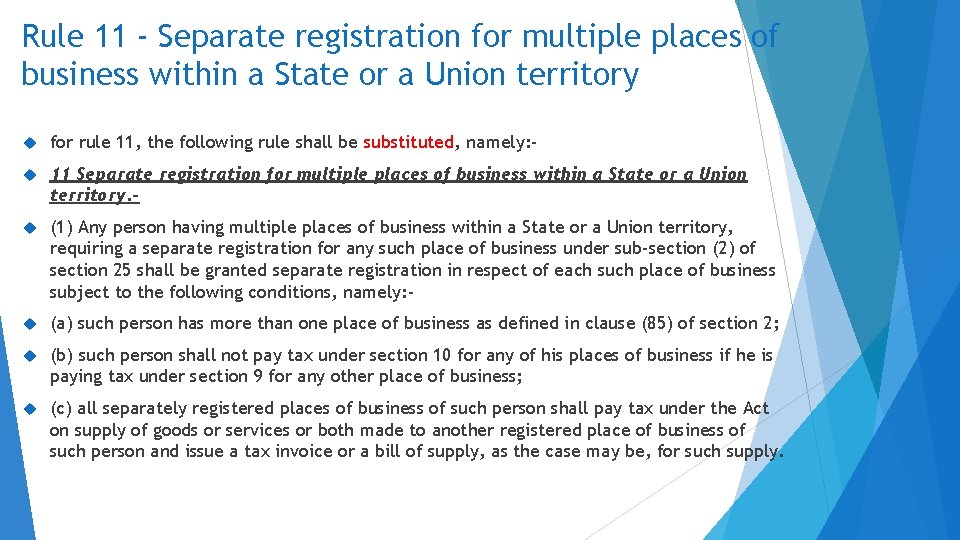
Rule 11 - Separate registration for multiple places of business within a State or a Union territory for rule 11, the following rule shall be substituted, namely: - 11 Separate registration for multiple places of business within a State or a Union territory. - (1) Any person having multiple places of business within a State or a Union territory, requiring a separate registration for any such place of business under sub-section (2) of section 25 shall be granted separate registration in respect of each such place of business subject to the following conditions, namely: - (a) such person has more than one place of business as defined in clause (85) of section 2; (b) such person shall not pay tax under section 10 for any of his places of business if he is paying tax under section 9 for any other place of business; (c) all separately registered places of business of such person shall pay tax under the Act on supply of goods or services or both made to another registered place of business of such person and issue a tax invoice or a bill of supply, as the case may be, for such supply.
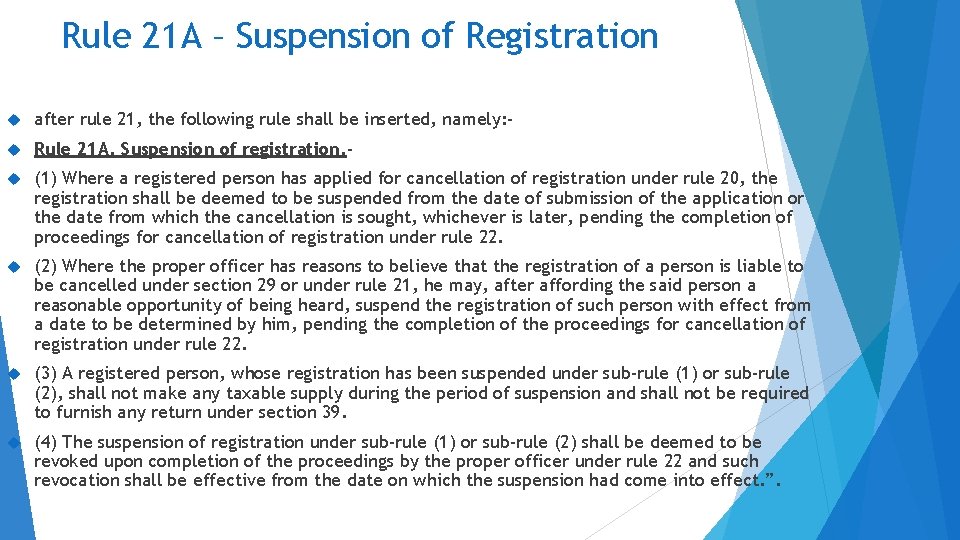
Rule 21 A – Suspension of Registration after rule 21, the following rule shall be inserted, namely: - Rule 21 A. Suspension of registration. - (1) Where a registered person has applied for cancellation of registration under rule 20, the registration shall be deemed to be suspended from the date of submission of the application or the date from which the cancellation is sought, whichever is later, pending the completion of proceedings for cancellation of registration under rule 22. (2) Where the proper officer has reasons to believe that the registration of a person is liable to be cancelled under section 29 or under rule 21, he may, after affording the said person a reasonable opportunity of being heard, suspend the registration of such person with effect from a date to be determined by him, pending the completion of the proceedings for cancellation of registration under rule 22. (3) A registered person, whose registration has been suspended under sub-rule (1) or sub-rule (2), shall not make any taxable supply during the period of suspension and shall not be required to furnish any return under section 39. (4) The suspension of registration under sub-rule (1) or sub-rule (2) shall be deemed to be revoked upon completion of the proceedings by the proper officer under rule 22 and such revocation shall be effective from the date on which the suspension had come into effect. ”.
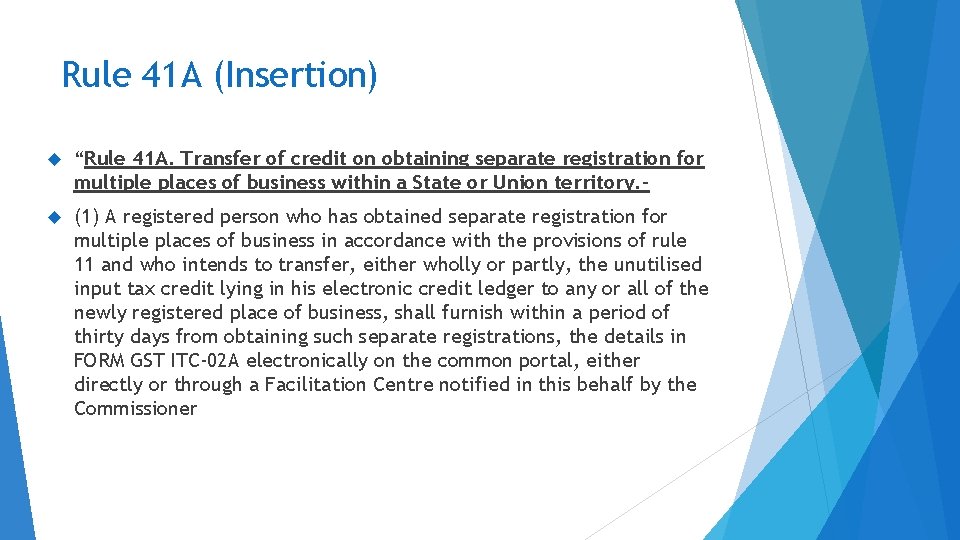
Rule 41 A (Insertion) “Rule 41 A. Transfer of credit on obtaining separate registration for multiple places of business within a State or Union territory. - (1) A registered person who has obtained separate registration for multiple places of business in accordance with the provisions of rule 11 and who intends to transfer, either wholly or partly, the unutilised input tax credit lying in his electronic credit ledger to any or all of the newly registered place of business, shall furnish within a period of thirty days from obtaining such separate registrations, the details in FORM GST ITC-02 A electronically on the common portal, either directly or through a Facilitation Centre notified in this behalf by the Commissioner
Circulars
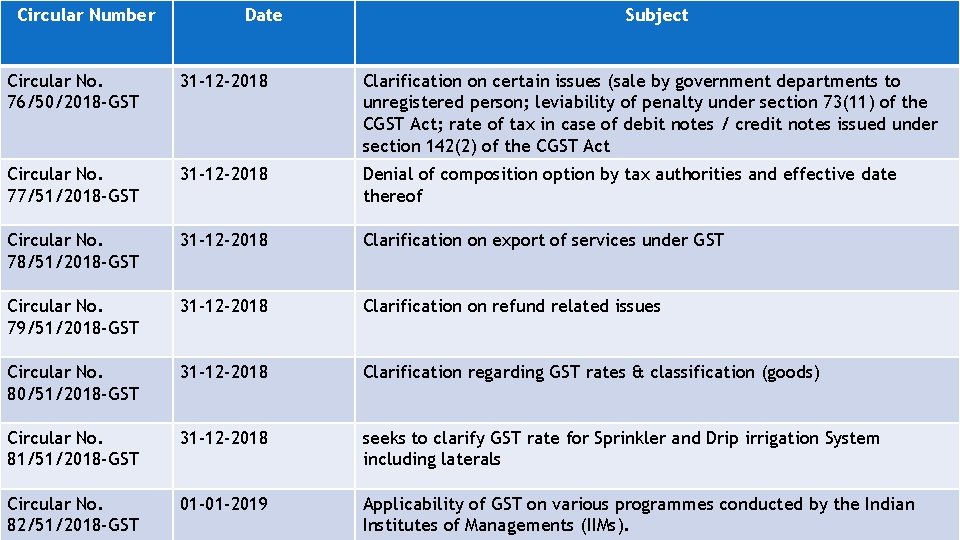
Circular Number Date Subject Circular No. 76/50/2018 -GST 31 -12 -2018 Clarification on certain issues (sale by government departments to unregistered person; leviability of penalty under section 73(11) of the CGST Act; rate of tax in case of debit notes / credit notes issued under section 142(2) of the CGST Act Circular No. 77/51/2018 -GST 31 -12 -2018 Denial of composition option by tax authorities and effective date thereof Circular No. 78/51/2018 -GST 31 -12 -2018 Clarification on export of services under GST Circular No. 79/51/2018 -GST 31 -12 -2018 Clarification on refund related issues Circular No. 80/51/2018 -GST 31 -12 -2018 Clarification regarding GST rates & classification (goods) Circular No. 81/51/2018 -GST 31 -12 -2018 seeks to clarify GST rate for Sprinkler and Drip irrigation System including laterals Circular No. 82/51/2018 -GST 01 -01 -2019 Applicability of GST on various programmes conducted by the Indian Institutes of Managements (IIMs).
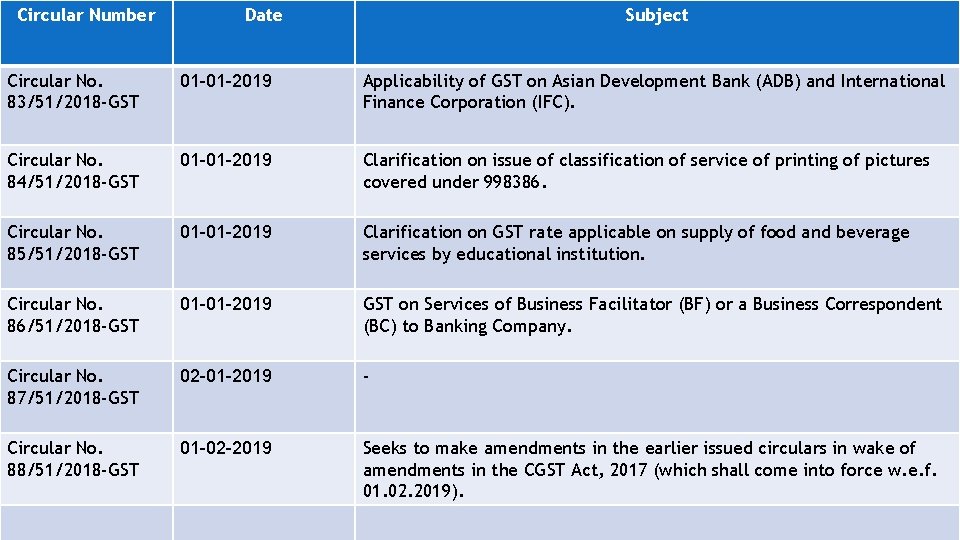
Circular Number Date Subject Circular No. 83/51/2018 -GST 01 -01 -2019 Applicability of GST on Asian Development Bank (ADB) and International Finance Corporation (IFC). Circular No. 84/51/2018 -GST 01 -01 -2019 Clarification on issue of classification of service of printing of pictures covered under 998386. Circular No. 85/51/2018 -GST 01 -01 -2019 Clarification on GST rate applicable on supply of food and beverage services by educational institution. Circular No. 86/51/2018 -GST 01 -01 -2019 GST on Services of Business Facilitator (BF) or a Business Correspondent (BC) to Banking Company. Circular No. 87/51/2018 -GST 02 -01 -2019 - Circular No. 88/51/2018 -GST 01 -02 -2019 Seeks to make amendments in the earlier issued circulars in wake of amendments in the CGST Act, 2017 (which shall come into force w. e. f. 01. 02. 2019).
EXPECTED CHANGES IN GST AFTER 01. 04. 2019
Whether it is a BJP-led government or a Congress one at the Centre after the 2019 general election, one thing is sure: The goods and services tax will see quite a number of changes. While the Congress has promised an overhaul of the tax, the BJP itself is talking about a single standard rate now.
5 POSSIBLE CHANGES : Ø Changes in rates – Builders and Developers Ø Return simplification Ø Composition scheme for services Ø Threshold limit of exemption
Changes in rates – Builders and Developers 3 % for Affordable Housing Scheme 5% If for Others no ITC is availed.
RETURN SIMPLIFICATIONØ This process is underway and is expected to be rolled out on July 1 this year. Originally, it was to be rolled out in December 2018 or in January 2019. Ø The annual turnover cap for this category was fixed at Rs 1 crore earlier, but now it has been increased to Rs 10 crore. Ø Also, form GSTR 2 (purchase returns) and input-output returns (GSTR 3) had been suspended. However, taxpayers have to file GSTR 1 (supply returns) and GSTR 3 B (summary input-output returns). Ø So, big businesses are filing two returns in a month and one annual return, or 25 returns a year. Small businesses file one return -- summary input-output return -- a month and one supply return in a quarter, apart from the annual return. So they file 17 returns in a year.
COMPOSITION SCHEME FOR SERVICESUnder the Composition scheme, which has been introduced in GST to woo small businesses, taxpayers pay a flat rate at lower level, but aren't entitled to get input tax credit. The ceiling for availing this scheme currently is Rs 1. 5 crore. Manufacturers, dealers and restaurant owners can avail this scheme. While manufacturers and dealers are required to pay 1% tax, restaurant service providers pay 5%. Now, there are demands that small service providers also be brought under the scheme. The issue is that when these service providers raise bills, their buyers are reluctant to pay GST. As such, these providers are unwilling to join the new tax system. The next Council meeting will discuss this issue this month and will come out with the rules and the rate for this purpose. But experts say the limit could be fixed at Rs 50 lakh to Rs 1 crore.
THRESHOLD LIMIT OF EXEMPTIONØ The next Council meeting is likely to increase the exemption limit for medium and small enterprises to Rs 40 lakh annual turnover from the current Rs 20 lakh. Those with annual turnovers less than or equal to this threshold are not required to register under GST. Ø However, this is unlikely to impact the number of GST registrants or the exchequer significantly. Ø About 10. 2 million assessees are registered under GST as of now. Ø Almost 25% of those registered with GSTN have a turnover in the range of Rs 20 lakh to Rs 1 crore. GST paid by them makes up only 5% of the overall collection.
HAPPY LEARNING!
- Slides: 88