
GSN FUN Technologies Status Update November 2007 Liberty
GSN / FUN Technologies Status Update November 2007
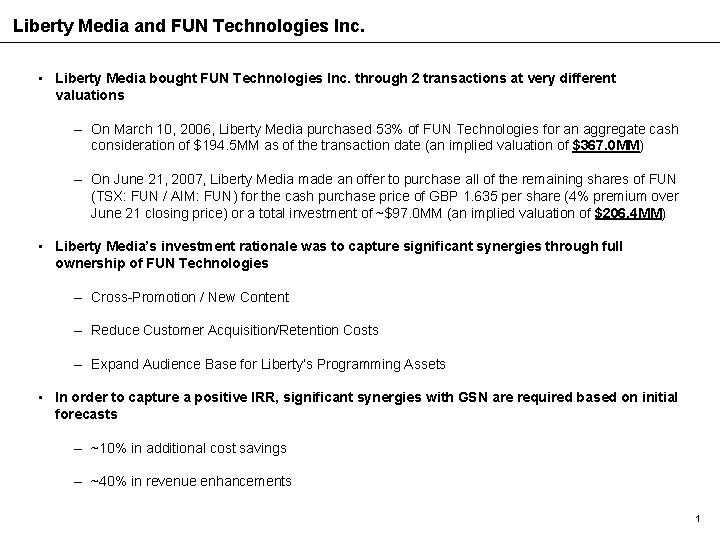
Liberty Media and FUN Technologies Inc. • Liberty Media bought FUN Technologies Inc. through 2 transactions at very different valuations – On March 10, 2006, Liberty Media purchased 53% of FUN Technologies for an aggregate cash consideration of $194. 5 MM as of the transaction date (an implied valuation of $367. 0 MM) – On June 21, 2007, Liberty Media made an offer to purchase all of the remaining shares of FUN (TSX: FUN / AIM: FUN) for the cash purchase price of GBP 1. 635 per share (4% premium over June 21 closing price) or a total investment of ~$97. 0 MM (an implied valuation of $206. 4 MM) • Liberty Media’s investment rationale was to capture significant synergies through full ownership of FUN Technologies – Cross-Promotion / New Content – Reduce Customer Acquisition/Retention Costs – Expand Audience Base for Liberty’s Programming Assets • In order to capture a positive IRR, significant synergies with GSN are required based on initial forecasts – ~10% in additional cost savings – ~40% in revenue enhancements 1
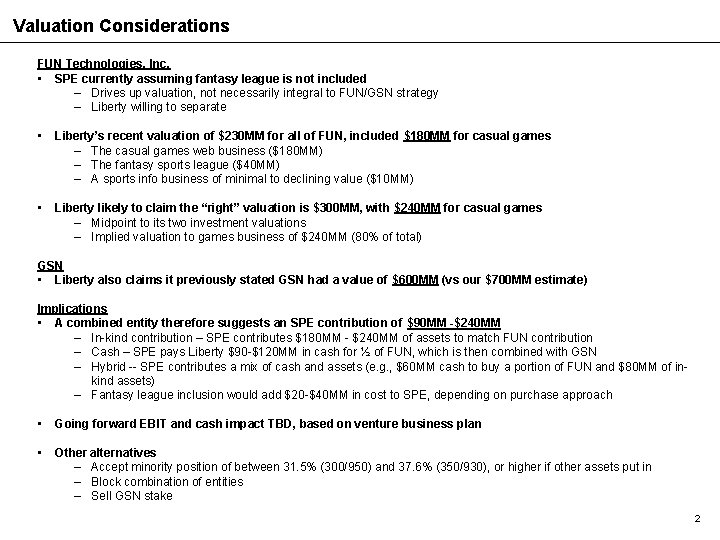
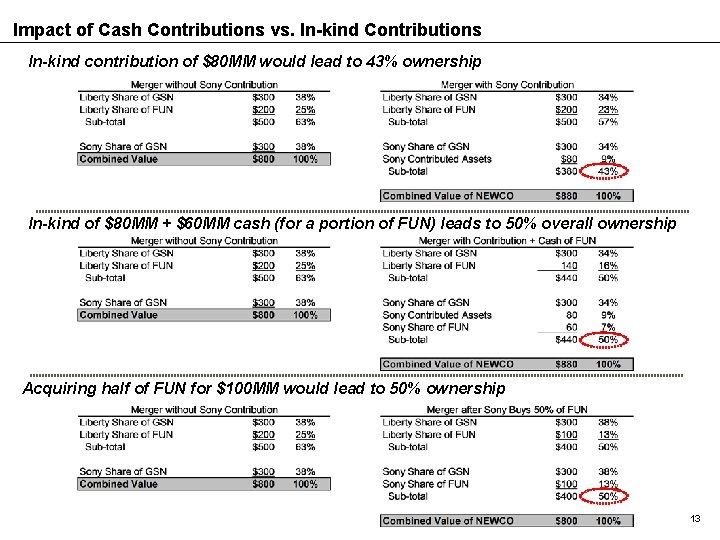
Valuation Considerations FUN Technologies, Inc. • SPE currently assuming fantasy league is not included – Drives up valuation, not necessarily integral to FUN/GSN strategy – Liberty willing to separate • Liberty’s recent valuation of $230 MM for all of FUN, included $180 MM for casual games – The casual games web business ($180 MM) – The fantasy sports league ($40 MM) – A sports info business of minimal to declining value ($10 MM) • Liberty likely to claim the “right” valuation is $300 MM, with $240 MM for casual games – Midpoint to its two investment valuations – Implied valuation to games business of $240 MM (80% of total) GSN • Liberty also claims it previously stated GSN had a value of $600 MM (vs our $700 MM estimate) Implications • A combined entity therefore suggests an SPE contribution of $90 MM -$240 MM – In-kind contribution – SPE contributes $180 MM - $240 MM of assets to match FUN contribution – Cash – SPE pays Liberty $90 -$120 MM in cash for ½ of FUN, which is then combined with GSN – Hybrid -- SPE contributes a mix of cash and assets (e. g. , $60 MM cash to buy a portion of FUN and $80 MM of inkind assets) – Fantasy league inclusion would add $20 -$40 MM in cost to SPE, depending on purchase approach • Going forward EBIT and cash impact TBD, based on venture business plan • Other alternatives – Accept minority position of between 31. 5% (300/950) and 37. 6% (350/930), or higher if other assets put in – Block combination of entities – Sell GSN stake 2
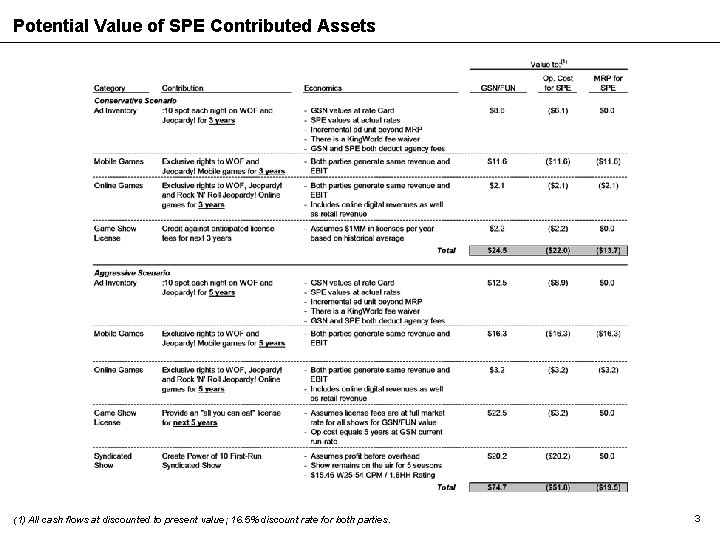
Potential Value of SPE Contributed Assets (1) All cash flows at discounted to present value; 16. 5% discount rate for both parties. 3
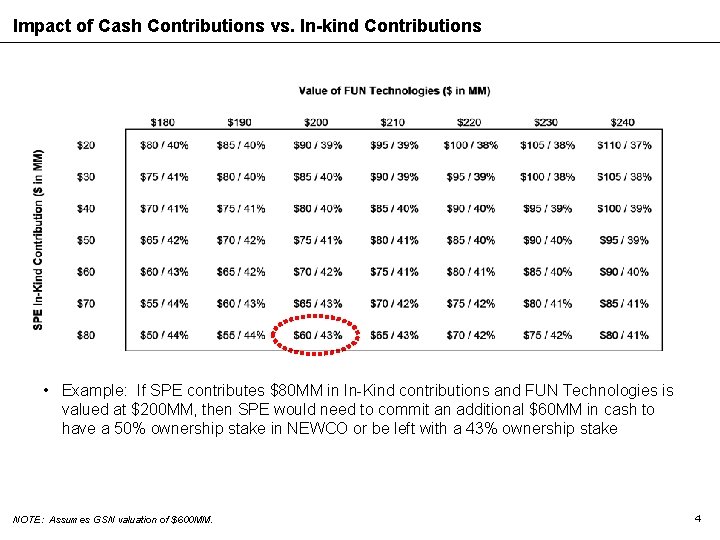
Impact of Cash Contributions vs. In-kind Contributions • Example: If SPE contributes $80 MM in In-Kind contributions and FUN Technologies is valued at $200 MM, then SPE would need to commit an additional $60 MM in cash to have a 50% ownership stake in NEWCO or be left with a 43% ownership stake NOTE: Assumes GSN valuation of $600 MM. 4
Next Steps • GSN forecasts – With and without FUN combination • FUN valuation and forecasts • Potential additional sources of value – Allow GSN to air Wheel of Fortune and Jeopardy! Episodes 2 years after broadcast and in better time-periods) • EBIT and gain estimates, vs. current MRP • Assess value of digital gameshow rights via other avenues (e. g. , JV with game publisher) • Agree on proposal to Liberty – Assets to contribute, plus cash – Sale alternative price – Timing/GSN plan approval pending…? 5
Appendix A: GSN / FUN Overview 6
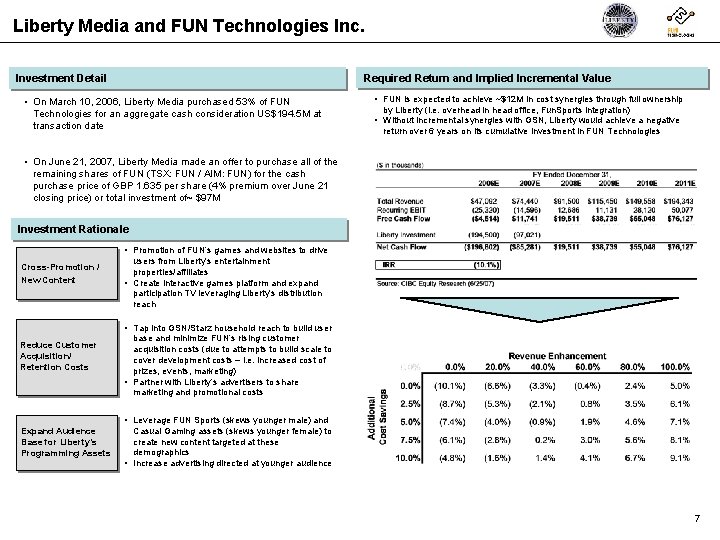
Liberty Media and FUN Technologies Inc. Required Return and Implied Incremental Value Investment Detail • On March 10, 2006, Liberty Media purchased 53% of FUN Technologies for an aggregate cash consideration US$194. 5 M at transaction date • FUN is expected to achieve ~$12 M in cost synergies through full ownership by Liberty (i. e. overhead in head office, Fun. Sports integration) • Without incremental synergies with GSN, Liberty would achieve a negative return over 6 years on its cumulative investment in FUN Technologies • On June 21, 2007, Liberty Media made an offer to purchase all of the remaining shares of FUN (TSX: FUN / AIM: FUN) for the cash purchase price of GBP 1. 635 per share (4% premium over June 21 closing price) or total investment of~ $97 M Investment Rationale • Promotion of FUN’s games and websites to drive Cross-Promotion / New Content users from Liberty’s entertainment properties/affiliates • Create interactive games platform and expand participation TV leveraging Liberty’s distribution reach • Tap into GSN/Starz household reach to build user Reduce Customer Acquisition/ Retention Costs base and minimize FUN’s rising customer acquisition costs (due to attempts to build scale to cover development costs – i. e. increased cost of prizes, events, marketing) • Partner with Liberty’s advertisers to share marketing and promotional costs • Leverage FUN Sports (skews younger male) and Expand Audience Base for Liberty’s Programming Assets Casual Gaming assets (skews younger female) to create new content targeted at these demographics • Increase advertising directed at younger audience 7
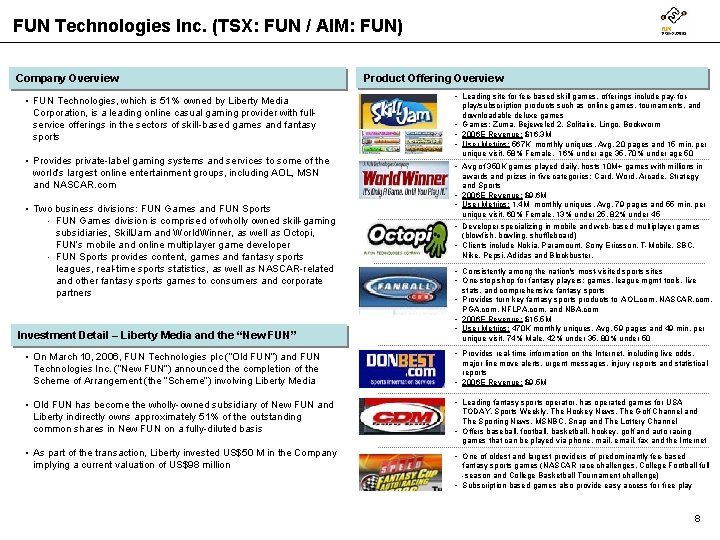
FUN Technologies Inc. (TSX: FUN / AIM: FUN) Company Overview • FUN Technologies, which is 51% owned by Liberty Media Corporation, is a leading online casual gaming provider with fullservice offerings in the sectors of skill-based games and fantasy sports • Provides private-label gaming systems and services to some of the world’s largest online entertainment groups, including AOL, MSN and NASCAR. com • Two business divisions: FUN Games and FUN Sports • FUN Games division is comprised of wholly owned skill-gaming subsidiaries, Skill. Jam and World. Winner, as well as Octopi, FUN’s mobile and online multiplayer game developer • FUN Sports provides content, games and fantasy sports leagues, real-time sports statistics, as well as NASCAR-related and other fantasy sports games to consumers and corporate partners Product Offering Overview • Leading site for fee-based skill games, offerings include pay-forplay/subscription products such as online games, tournaments, and downloadable deluxe games • Games: Zuma, Bejeweled 2, Solitaire, Lingo, Bookworm • 2006 E Revenue: $16. 3 M • User Metrics: 567 K monthly uniques, Avg. 20 pages and 15 min. per unique visit, 58% Female, 16% under age 35, 70% under age 50 • Avg of 350 K games played daily, hosts 10 M+ games with millions in • • awards and prizes in five categories: Card, Word, Arcade, Strategy and Sports 2006 E Revenue: $9. 6 M User Metrics: 1. 4 M monthly uniques, Avg. 79 pages and 55 min. per unique visit, 60% Female, 13% under 25, 82% under 45 Developer specializing in mobile and web-based multiplayer games (blowfish, bowling, shuffleboard) Clients include Nokia, Paramount, Sony Ericsson, T-Mobile, SBC, Nike, Pepsi, Adidas and Blockbuster. • Consistently among the nation's most-visited sports sites • One-stop shop for fantasy players; games, league mgmt tools, live stats, and comprehensive fantasy sports • Provides turn key fantasy sports products to AOL. com, NASCAR. com, PGA. com, NFLPA. com, and NBA. com Investment Detail – Liberty Media and the “New FUN” • 2006 E Revenue: $15. 5 M • User Metrics: 470 K monthly uniques, Avg. 59 pages and 49 min. per unique visit, 74% Male, 42% under 35, 80% under 50 • On March 10, 2006, FUN Technologies plc (“Old FUN”) and FUN Technologies Inc. (“New FUN”) announced the completion of the Scheme of Arrangement (the “Scheme”) involving Liberty Media • Provides real-time information on the Internet, including live odds, • Old FUN has become the wholly-owned subsidiary of New FUN and Liberty indirectly owns approximately 51% of the outstanding common shares in New FUN on a fully-diluted basis • Leading fantasy sports operator, has operated games for USA • As part of the transaction, Liberty invested US$50 M in the Company implying a current valuation of US$98 million major line move alerts, urgent messages, injury reports and statistical reports • 2006 E Revenue: $9. 5 M TODAY, Sports Weekly, The Hockey News, The Golf Channel and The Sporting News, MSNBC, Snap and The Lottery Channel • Offers baseball, football, basketball, hockey, golf and auto racing games that can be played via phone, mail, email, fax and the Internet • One of oldest and largest providers of predominantly fee-based fantasy sports games (NASCAR race challenges, College Football full -season and College Basketball Tournament challenge) • Subscription based games also provide easy access for free play 8
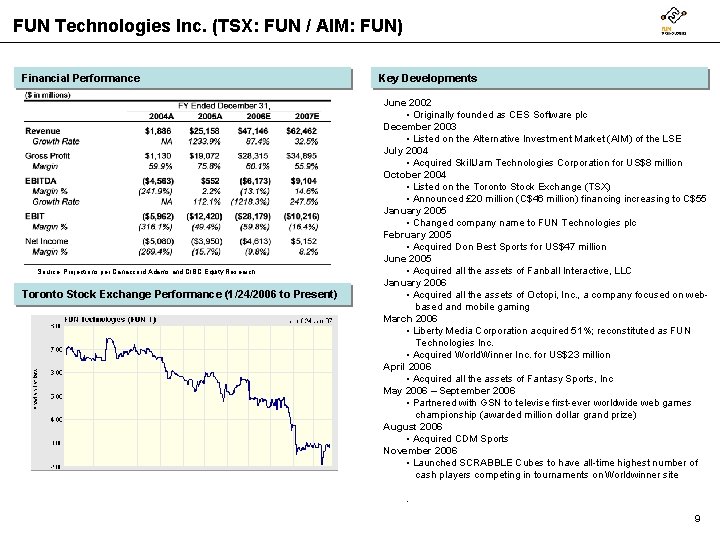
FUN Technologies Inc. (TSX: FUN / AIM: FUN) Financial Performance Source: Projections per Canaccord Adams and CIBC Equity Research Toronto Stock Exchange Performance (1/24/2006 to Present) Key Developments June 2002 • Originally founded as CES Software plc December 2003 • Listed on the Alternative Investment Market (AIM) of the LSE July 2004 • Acquired Skill. Jam Technologies Corporation for US$8 million October 2004 • Listed on the Toronto Stock Exchange (TSX) • Announced £ 20 million (C$46 million) financing increasing to C$55 January 2005 • Changed company name to FUN Technologies plc February 2005 • Acquired Don Best Sports for US$47 million June 2005 • Acquired all the assets of Fanball Interactive, LLC January 2006 • Acquired all the assets of Octopi, Inc. , a company focused on webbased and mobile gaming March 2006 • Liberty Media Corporation acquired 51%; reconstituted as FUN Technologies Inc. • Acquired World. Winner Inc. for US$23 million April 2006 • Acquired all the assets of Fantasy Sports, Inc May 2006 – September 2006 • Partnered with GSN to televise first-ever worldwide web games championship (awarded million dollar grand prize) August 2006 • Acquired CDM Sports November 2006 • Launched SCRABBLE Cubes to have all-time highest number of cash players competing in tournaments on Worldwinner site. 9
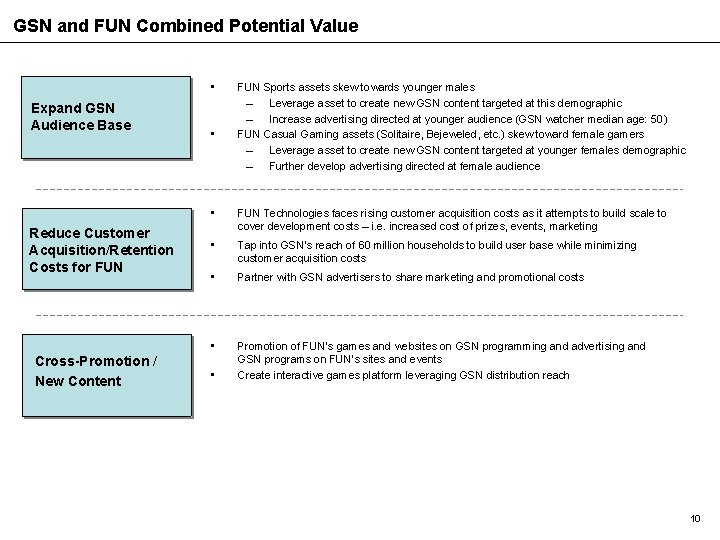
GSN and FUN Combined Potential Value • Expand GSN Audience Base Reduce Customer Acquisition/Retention Costs for FUN Cross-Promotion / New Content • FUN Sports assets skew towards younger males – Leverage asset to create new GSN content targeted at this demographic – Increase advertising directed at younger audience (GSN watcher median age: 50) FUN Casual Gaming assets (Solitaire, Bejeweled, etc. ) skew toward female gamers – Leverage asset to create new GSN content targeted at younger females demographic – Further develop advertising directed at female audience • FUN Technologies faces rising customer acquisition costs as it attempts to build scale to cover development costs – i. e. increased cost of prizes, events, marketing • Tap into GSN’s reach of 60 million households to build user base while minimizing customer acquisition costs • Partner with GSN advertisers to share marketing and promotional costs • Promotion of FUN’s games and websites on GSN programming and advertising and GSN programs on FUN’s sites and events Create interactive games platform leveraging GSN distribution reach • 10
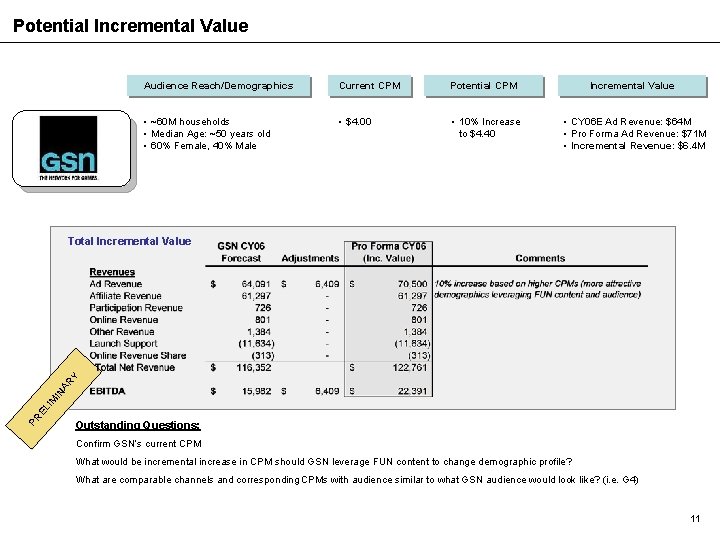
Potential Incremental Value Audience Reach/Demographics Current CPM Potential CPM Incremental Value • ~60 M households • Median Age: ~50 years old • 60% Female, 40% Male • $4. 00 • 10% Increase to $4. 40 • CY 06 E Ad Revenue: $64 M • Pro Forma Ad Revenue: $71 M • Incremental Revenue: $6. 4 M PR EL IM IN AR Y Total Incremental Value Outstanding Questions: Confirm GSN’s current CPM What would be incremental increase in CPM should GSN leverage FUN content to change demographic profile? What are comparable channels and corresponding CPMs with audience similar to what GSN audience would look like? (i. e. G 4) 11
Appendix B: Financial Calculations 12
Impact of Cash Contributions vs. In-kind Contributions In-kind contribution of $80 MM would lead to 43% ownership In-kind of $80 MM + $60 MM cash (for a portion of FUN) leads to 50% overall ownership Acquiring half of FUN for $100 MM would lead to 50% ownership 13
Ad Inventory Value 14
Game / License Values 15
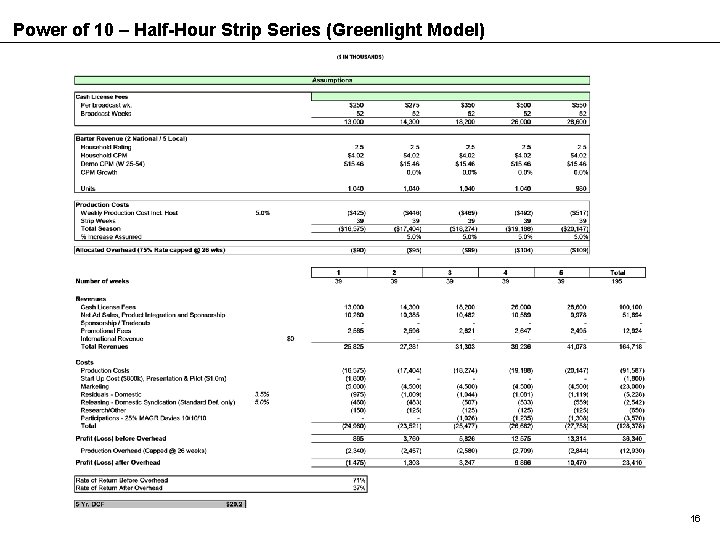
Power of 10 – Half-Hour Strip Series (Greenlight Model) 16
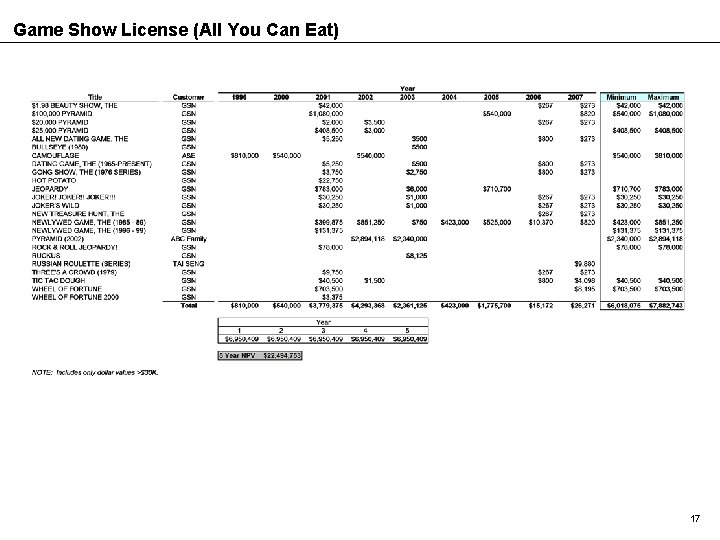
Game Show License (All You Can Eat) 17
- Slides: 18