
GROUP FINANCIAL REPORTING ACF 202 PART 2 FAIR
- Slides: 28
GROUP FINANCIAL REPORTING ACF 202 PART 2 FAIR VALUE 1 Cynthia Fortin, CPA, CMA Spring 2018
Objective Describe and explain the importance of fair valuation and the treatment of goodwill in group accounting 2
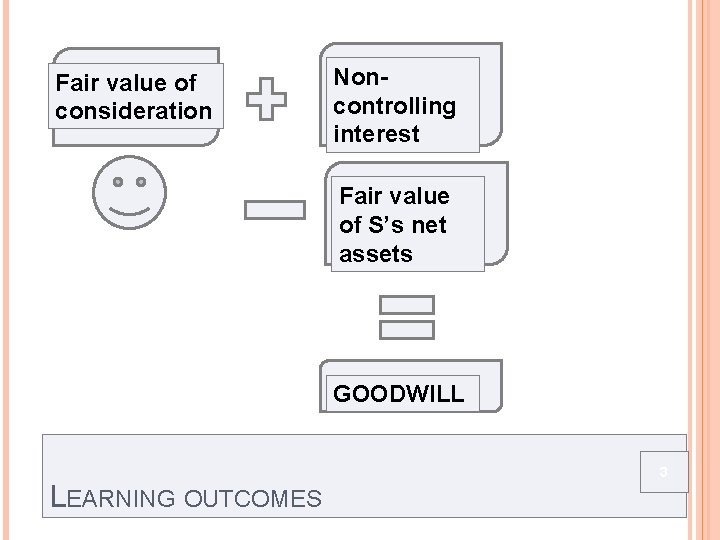
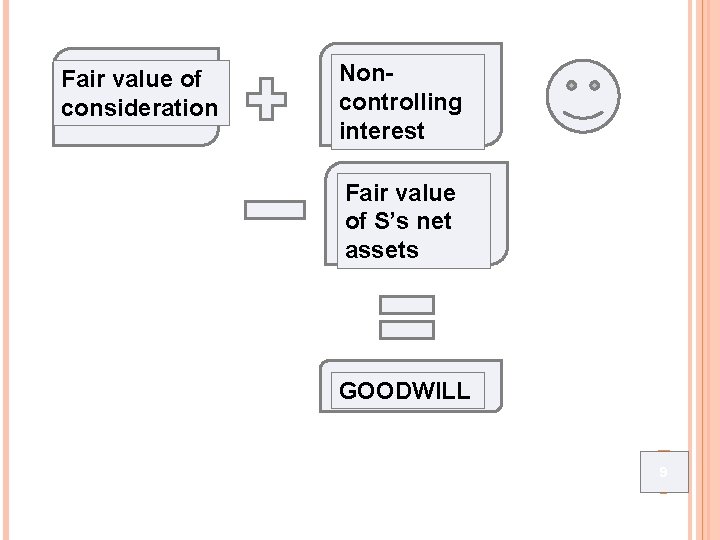
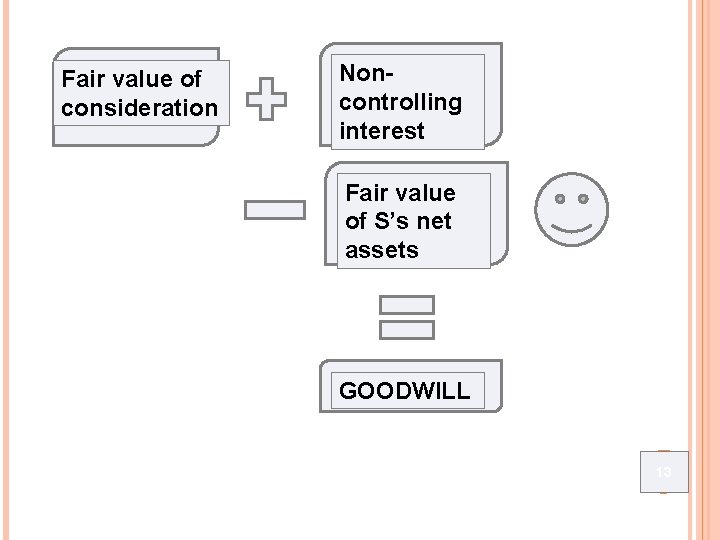
Fair value of consideration Noncontrolling interest Fair value of S’s net assets GOODWILL LEARNING OUTCOMES 3
P’S INVESTMENT AT DATE OF ACQUISITION IFRS 13: Fair value measurement: ‘Amount that would be received to sell an asset at market value’ 4
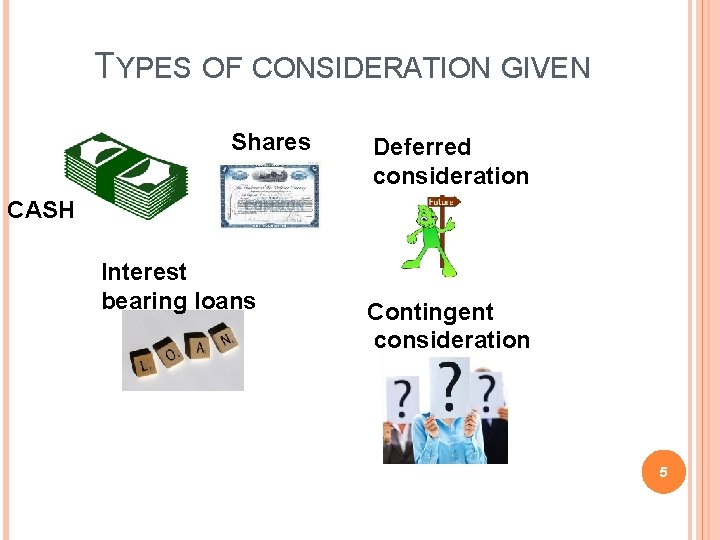
TYPES OF CONSIDERATION GIVEN Shares Deferred consideration CASH Interest bearing loans Contingent consideration 5
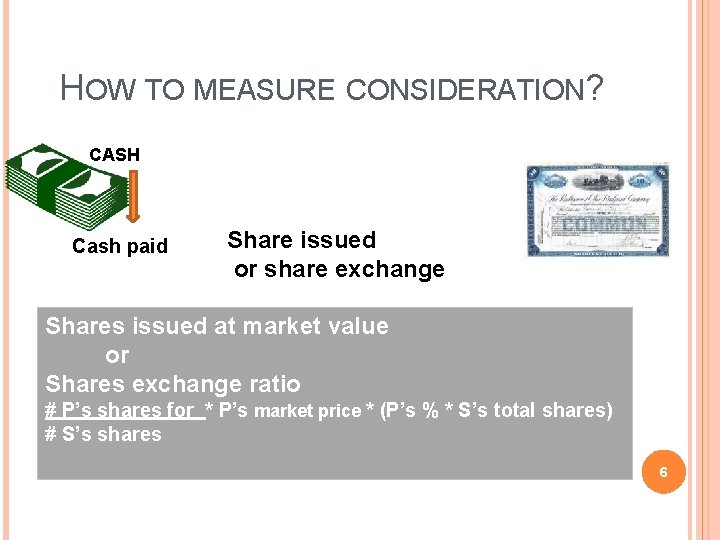
HOW TO MEASURE CONSIDERATION? CASH Cash paid Share issued or share exchange Shares issued at market value or Shares exchange ratio # P’s shares for * P’s market price * (P’s % * S’s total shares) # S’s shares 6
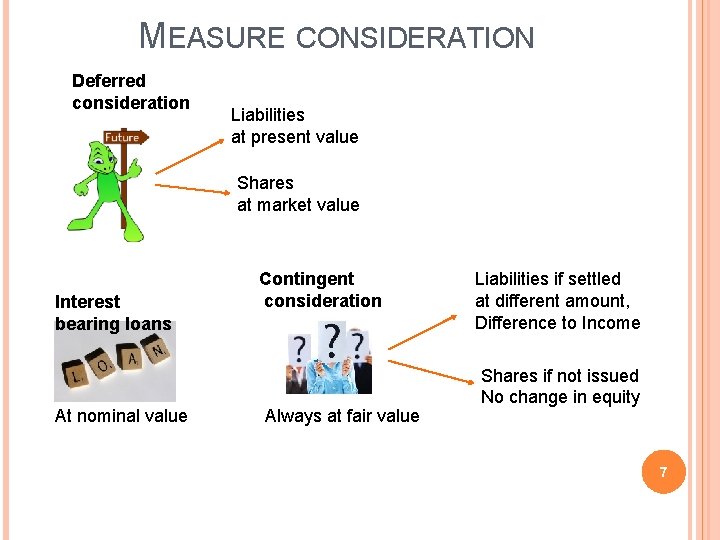
MEASURE CONSIDERATION Deferred consideration Liabilities at present value Shares at market value Interest bearing loans At nominal value Contingent consideration Always at fair value Liabilities if settled at different amount, Difference to Income Shares if not issued No change in equity 7
EXERCISE Let’s do Poland 8
Fair value of consideration Noncontrolling interest Fair value of S’s net assets GOODWILL 9
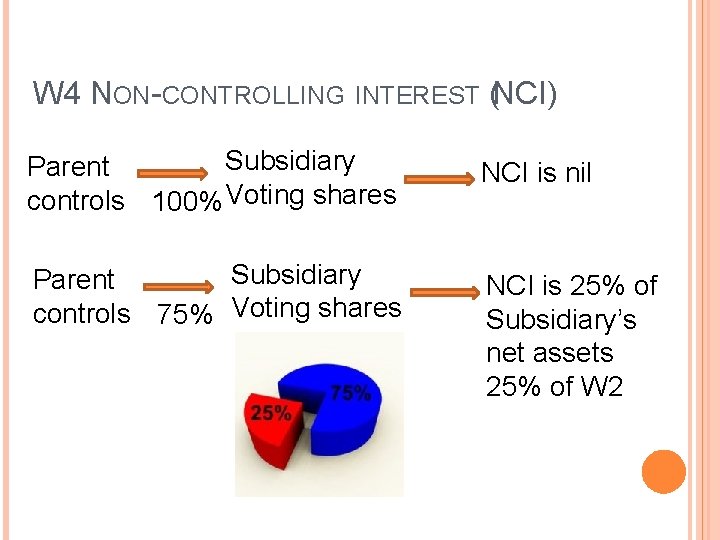
W 4 NON-CONTROLLING INTEREST (NCI) Subsidiary Parent controls 100% Voting shares NCI is nil Subsidiary Parent controls 75% Voting shares NCI is 25% of Subsidiary’s net assets 25% of W 2
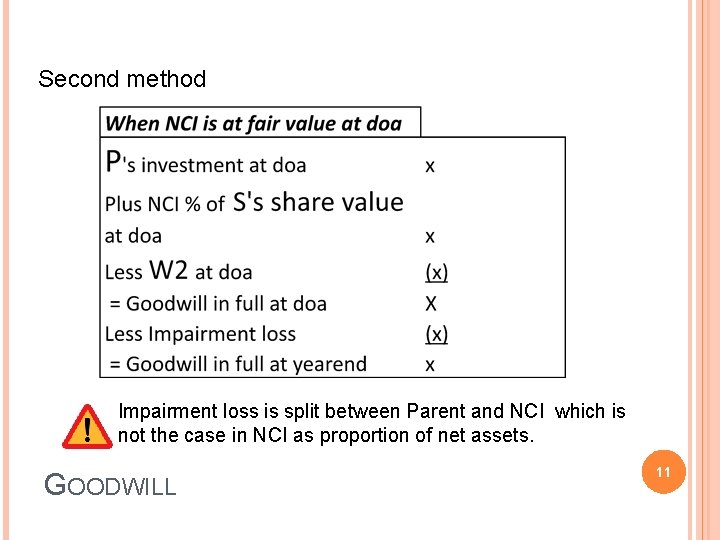
Second method Impairment loss is split between Parent and NCI which is not the case in NCI as proportion of net assets. GOODWILL 11
Excel demo problems. xlsx Let’s do Mount Then Thames 12
Fair value of consideration Noncontrolling interest Fair value of S’s net assets GOODWILL 13
MEASURING S’S NET ASSETS AT ACQUISITION AT FAIR VALUE Parent Performs a fair value exercise of S’s net assets If Fair value is higher than net assets, then a fair value adjustment is made at doa and depreciation is taken at yearend 14
Let’s do Malta Then Barbados MEASURING S’S NET ASSETS AT ACQUISITION AT FAIR VALUE 15
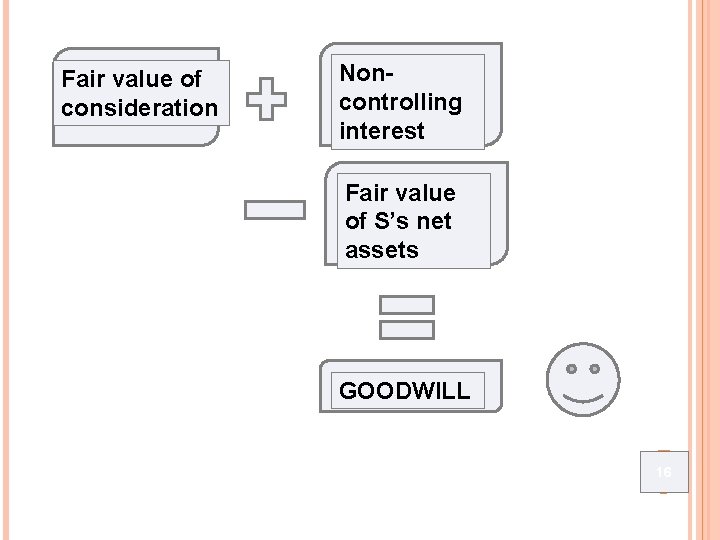
Fair value of consideration Noncontrolling interest Fair value of S’s net assets GOODWILL 16
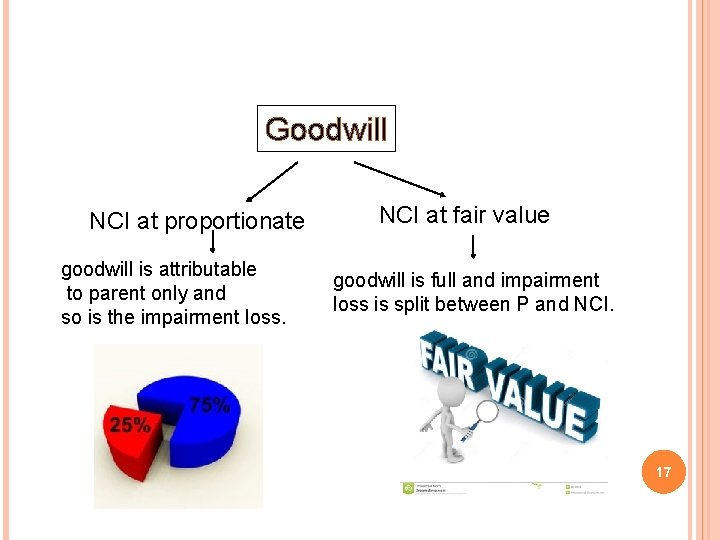
Goodwill NCI at proportionate goodwill is attributable to parent only and so is the impairment loss. NCI at fair value goodwill is full and impairment loss is split between P and NCI. 17
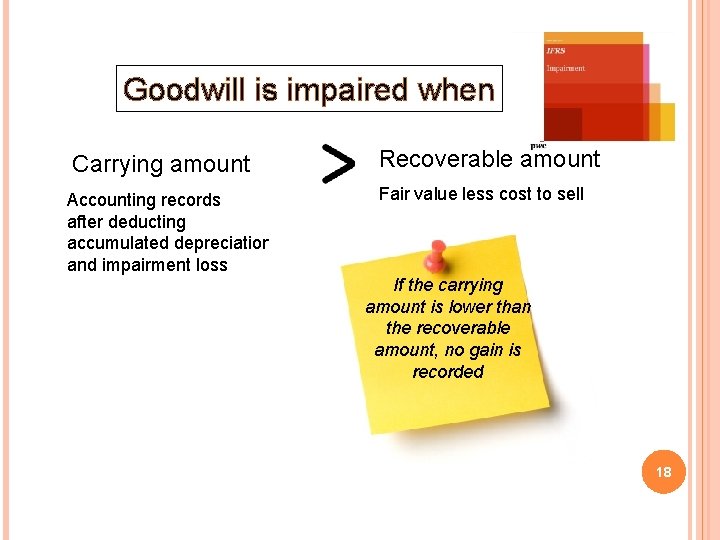
Goodwill is impaired when Carrying amount Accounting records after deducting accumulated depreciation and impairment loss Recoverable amount Fair value less cost to sell If the carrying amount is lower than the recoverable amount, no gain is recorded 18
Goodwill impairment loss Must be recorded Asset written down IAS 36 does not allow goodwill impairment loss to be reversed 19
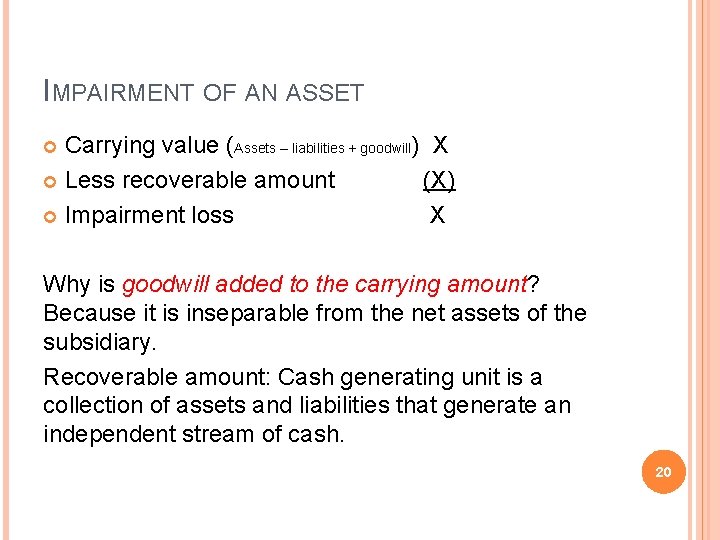
IMPAIRMENT OF AN ASSET Carrying value (Assets – liabilities + goodwill) X Less recoverable amount (X) Impairment loss X Why is goodwill added to the carrying amount? Because it is inseparable from the net assets of the subsidiary. Recoverable amount: Cash generating unit is a collection of assets and liabilities that generate an independent stream of cash. 20
Let’s do Oman Then Singapore 21
MID-YEAR ACQUISITIONS ASSUMPTION ON POST ACQUISITION PROFITS When acquisition occurs during a period, assume profits accrue evenly during the period and that no dividends will have been paid by Subsidiary. 22
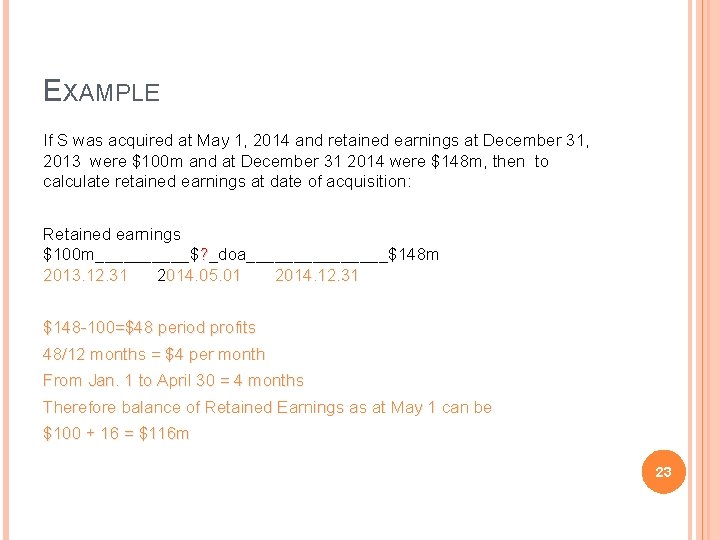
EXAMPLE If S was acquired at May 1, 2014 and retained earnings at December 31, 2013 were $100 m and at December 31 2014 were $148 m, then to calculate retained earnings at date of acquisition: Retained earnings $100 m_____$? _doa________$148 m 2013. 12. 31 2014. 05. 01 2014. 12. 31 $148 -100=$48 period profits 48/12 months = $4 per month From Jan. 1 to April 30 = 4 months Therefore balance of Retained Earnings as at May 1 can be $100 + 16 = $116 m 23
WHAT I NEED TO KNOW 1. Fair value (FV) is the price to be received to sell an asset. 2. P records the investment in the S at FV of the consideration given. 3. FV of P’s shares issued for the investment in S will be measured at their market value. 4. FV of deferred consideration given for the investment in S creates a liability that is measured at present value of future cash flow. 24
WHAT I NEED TO KNOW 5. Consideration given for the investment that is dependent on a contingency is recorded at FV and creates a provision for a liability (if cash) or and equity reserve (if settled in shares). 6. If provision for liability for contingent consideration does not have to be paid it is derecognised and a gain recognised in income. 25
WHAT I NEED TO KNOW 7. FV of P’s interest bearing loan notes issued as consideration given is recorded at nominal value. 8. NCI at acquisition can be measured at FV and goodwill be in full. 9. NCI at acquisition can be proportionate of S’s net assets and goodwill be given to P only. 10. At doa net assets of S have to be adjusted to FV 26
WHAT I NEED TO KNOW 11. 12. 13. 14. If at year-end FV asset adjustments are depreciated, then S’s profits must be adjusted as well. Asset is impaired when the carrying value is higher than the recoverable amount. Impairment loss on full goodwill is shared between P(W 5) and NCI (W 4). Impairment loss on goodwill attributable to P is wholly charged against P’s profits (W 5). 27
REFERENCES Clendon, Tom (2013), “A Student's Guide to Group Accounts, 2 nd Ed. ”, Kaplan Publishing UK ISBN: 9780857327642 chapters 4, 5, 6, 7 and 10. Recap pp 89 -90. 28