
Gross Receipts and Income Tax for Hunting Licenses
- Slides: 14
Gross Receipts and Income Tax for: Hunting Licenses (Permits) and Services
Landowner permits – Income from selling a right to access and hunt is taxable for both income and gross receipts tax. IE: landowner sells an elk permit to an outfitter for $1, 200 and sells a deer hunting permit to a family friend for $800. The landowner has taxable income of $2, 000.
Why? – 7 -9 -3(A). "buying" or "selling" means a transfer of property for consideration or the performance of service for consideration – 7 -9 -3(J). "property" means real property, tangible personal property, licenses other than the licenses of copyrights, trademarks or patents and franchises. Tangible personal property includes electricity and manufactured homes
Continued – Section 7 -9 -3 (J) NMSA 1978; Regulation 3. 2. 1. 27 (C) NMAC states: Granting the right to hunt is the sale of a license to use. For purposes of this section, granting by a landowner to another, a right to access and hunt within the boundaries of the landowner’s real property is a license to use the real property. A license is a form of property as defined in Subsection J of Section 7 -9 -3 NMSA 1978 and the receipts from the sale of a license are subject to the gross receipts tax.
Hunting Services can include: Lodging, meals, hunting guide and retrieval. The seller must determine what components of the package are taxable or non-taxable.
NT T C In order to execute an NTTC to another party, both parties must be registered with NMTRD. Even Out of State brokers and outfitters need to be registered.
– All income earned from the sale of permits or services must be reported to the state as gross receipts and included on income tax returns. – Deductible income is still reported on the combined reporting system return (CRS-1) and is then deducted.
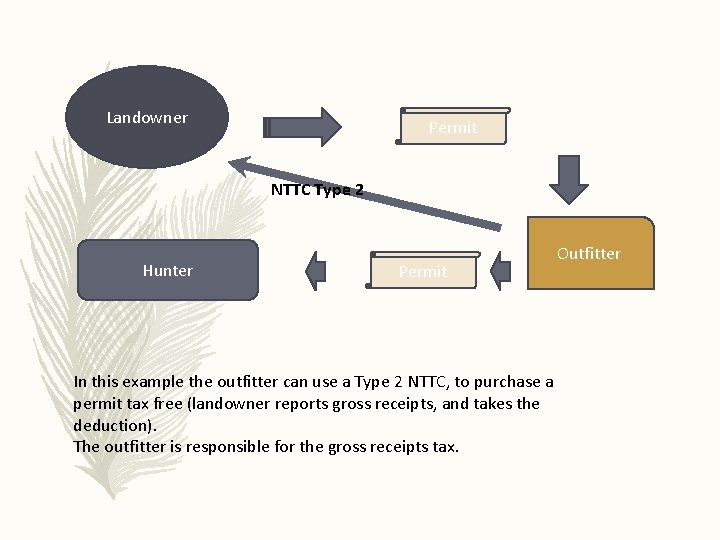
NT T C – Type 2 : For the sale of property for resale. – IE: The landowner sells a NM hunting permit to the hunting guide who sells the permit to a hunter. The hunting guide can then provide the landowner with a Type 2 NTTC. The landowner does not pay tax on the sale, the hunting guide pays the gross receipts tax.
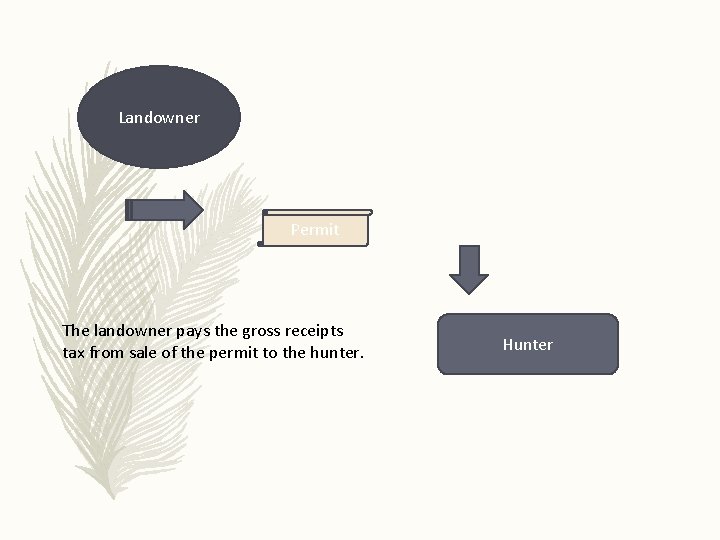
Landowner Permit The landowner pays the gross receipts tax from sale of the permit to the hunter. Hunter
Landowner Permit NTTC Type 2 Hunter Permit In this example the outfitter can use a Type 2 NTTC, to purchase a permit tax free (landowner reports gross receipts, and takes the deduction). The outfitter is responsible for the gross receipts tax. Outfitter
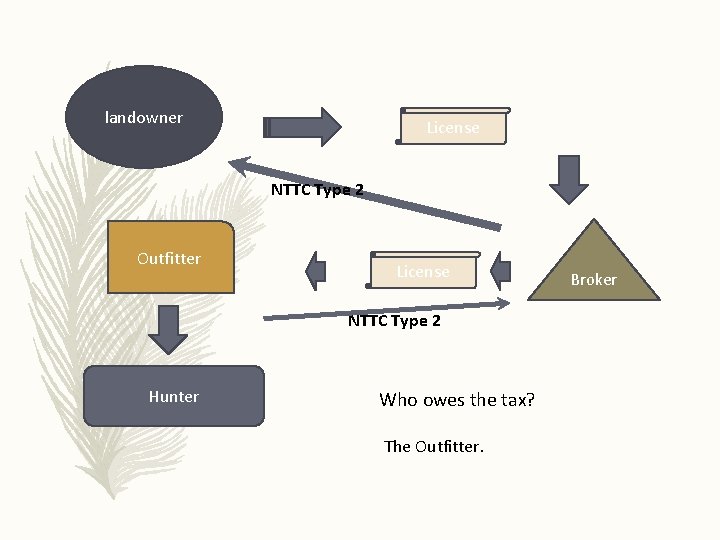
landowner License NTTC Type 2 Outfitter License NTTC Type 2 Hunter Who owes the tax? The Outfitter. Broker
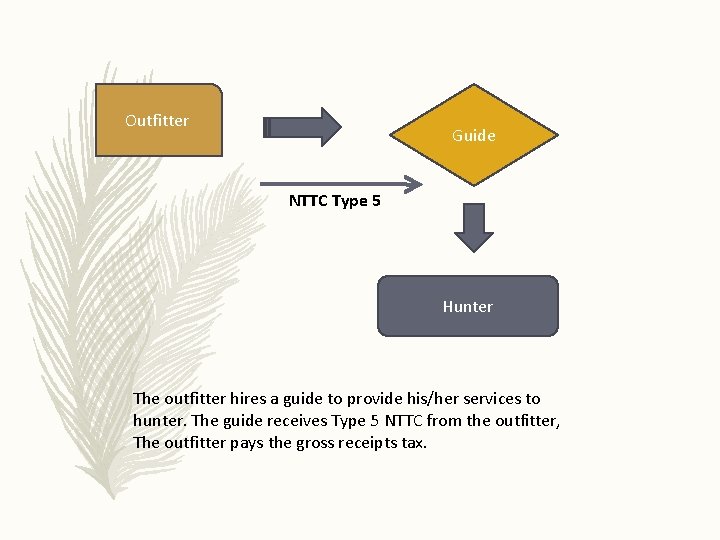
NT T C Nontaxable Transaction Certificate Type 5 : For services sold for resale in the ordinary course of business. IE: The outfitter hires a hunting guide. The outfitter executes a Type 5 NTTC to the guide. Now the income earned by the guide is deductible, the outfitter pays the gross receipts tax.
Outfitter Guide NTTC Type 5 Hunter The outfitter hires a guide to provide his/her services to hunter. The guide receives Type 5 NTTC from the outfitter, The outfitter pays the gross receipts tax.
Contact Information General Questions about CRS and NTTC’s: New Mexico Taxation & Revenue Call Center 505 -841 -6352 Managed Audit information: New Mexico Taxation & Revenue Managed Audit Hotline 505 -841 -6216 New Mexico Taxation & Revenue Taxpayer Access Point (TAP): tap. state. nm. us