
Governing Quality of Audit Firms in Malaysia AuthorsResearchers
- Slides: 16
Governing Quality of Audit Firms in Malaysia Authors/Researchers: Zuraidah Mohd Sanusi, Aida Hazlin Ismail, Yusarina Mat Isa, Roszana Tapsir, Syazliana Kasim, Kamaruzzaman Muhammad, Nor’Azam Mastuki and Normah Omar 2008 International Conference on Governance, Jakarta, Indonesia 12 – 14 November 2008
Presentation Outline Overview of Audit Quality n Background n Elements of Quality Control in ISQC 1 n Methodology n Objective 1: Effectiveness of ISQC 1 in Governing Quality of Audit Firms n Objective 2: Development of ISQC 1 Self Assessment Checklist n Score Assessment n Next Action n
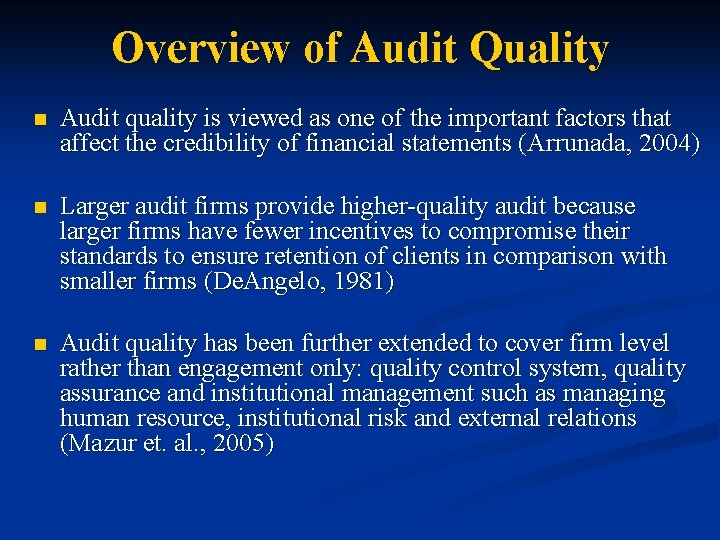
Overview of Audit Quality n Audit quality is viewed as one of the important factors that affect the credibility of financial statements (Arrunada, 2004) n Larger audit firms provide higher-quality audit because larger firms have fewer incentives to compromise their standards to ensure retention of clients in comparison with smaller firms (De. Angelo, 1981) n Audit quality has been further extended to cover firm level rather than engagement only: quality control system, quality assurance and institutional management such as managing human resource, institutional risk and external relations (Mazur et. al. , 2005)
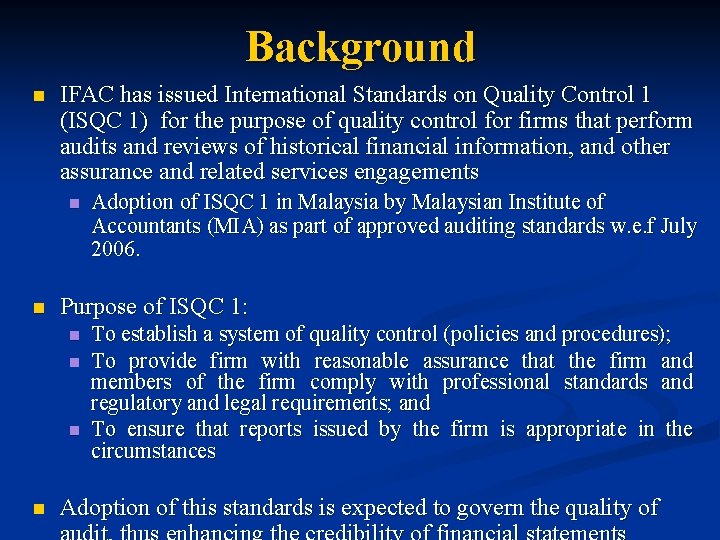
Background n IFAC has issued International Standards on Quality Control 1 (ISQC 1) for the purpose of quality control for firms that perform audits and reviews of historical financial information, and other assurance and related services engagements n n Purpose of ISQC 1: n n Adoption of ISQC 1 in Malaysia by Malaysian Institute of Accountants (MIA) as part of approved auditing standards w. e. f July 2006. To establish a system of quality control (policies and procedures); To provide firm with reasonable assurance that the firm and members of the firm comply with professional standards and regulatory and legal requirements; and To ensure that reports issued by the firm is appropriate in the circumstances Adoption of this standards is expected to govern the quality of
Background n Although accounting bodies in countries, such as Malaysia, Australia and Pakistan, have supplemented ISQC 1 with audit manual and guidelines, it is difficult to ascertain to what extent the compliance with ISQC 1 has been achieved. n Objectives of this study: n n To ascertain the effectiveness of ISQC 1 to govern quality of audit firms To develop ISQC 1 Self-Assessment Checklist to assist audit firms in complying with ISQC 1 n By adopting the framework of ISQC 1 questionnaires which have been developed by the accounting bodies in Australia and Pakistan, this study has further extended the questionnaires into ISQC 1 Self. Assessment Checklist to cover two parts i. e. Policies & Procedures and Practices as well as the score assessment.
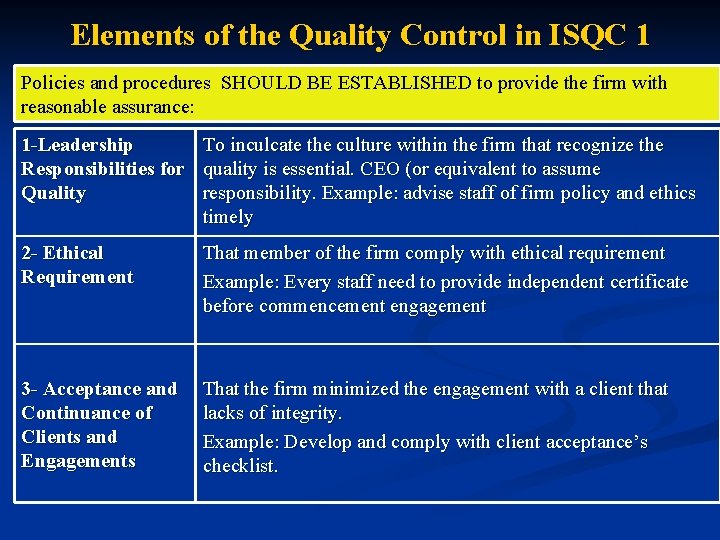
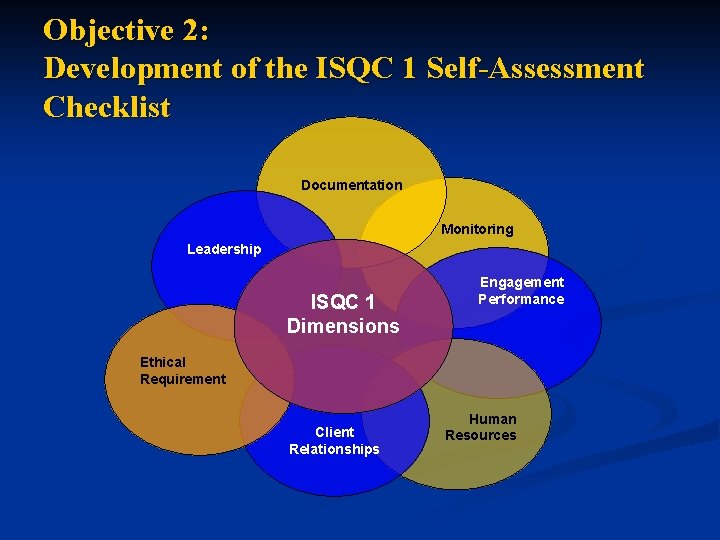
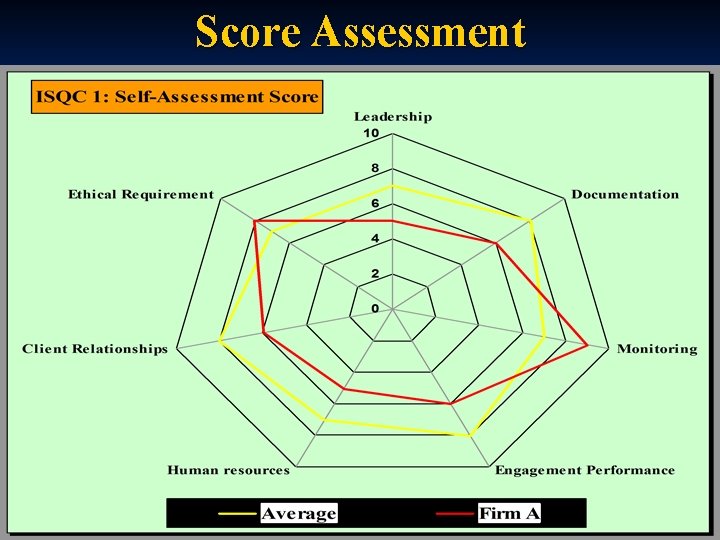
Elements of the Quality Control in ISQC 1 Policies and procedures SHOULD BE ESTABLISHED to provide the firm with reasonable assurance: 1 -Leadership To inculcate the culture within the firm that recognize the Responsibilities for quality is essential. CEO (or equivalent to assume Quality responsibility. Example: advise staff of firm policy and ethics timely 2 - Ethical Requirement That member of the firm comply with ethical requirement Example: Every staff need to provide independent certificate before commencement engagement 3 - Acceptance and Continuance of Clients and Engagements That the firm minimized the engagement with a client that lacks of integrity. Example: Develop and comply with client acceptance’s checklist.
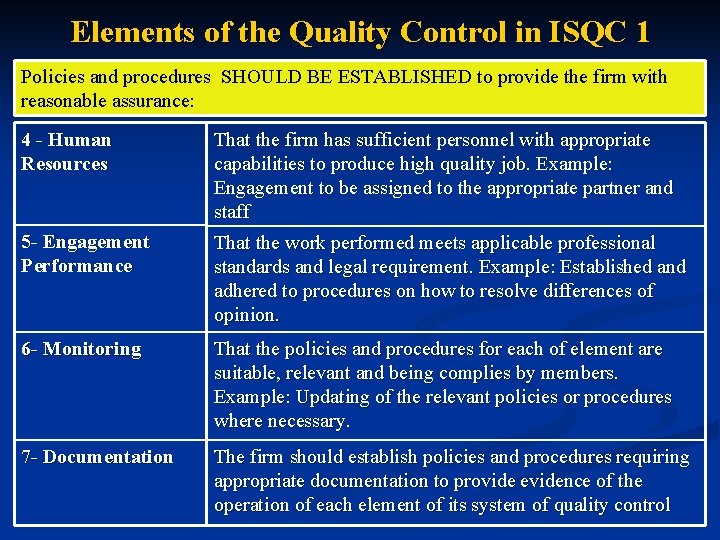
Elements of the Quality Control in ISQC 1 Policies and procedures SHOULD BE ESTABLISHED to provide the firm with reasonable assurance: 4 - Human Resources That the firm has sufficient personnel with appropriate capabilities to produce high quality job. Example: Engagement to be assigned to the appropriate partner and staff 5 - Engagement Performance That the work performed meets applicable professional standards and legal requirement. Example: Established and adhered to procedures on how to resolve differences of opinion. 6 - Monitoring That the policies and procedures for each of element are suitable, relevant and being complies by members. Example: Updating of the relevant policies or procedures where necessary. 7 - Documentation The firm should establish policies and procedures requiring appropriate documentation to provide evidence of the operation of each element of its system of quality control
Methodology n Preliminary study on the ISQC 1 implementation issues Questionnaires sent to audit firms n Brainstorming session among the researchers to form common themes of ISQC 1 Self-Assessment Checklist based on several sources: ISQC 1, MIA Quality Control Manual etc. n Review of ISQC 1 Self-Assessment Checklist with two representatives from MIA and ten audit practitioners from medium and small size firms (similar methodology applied by Sutton, 1993)
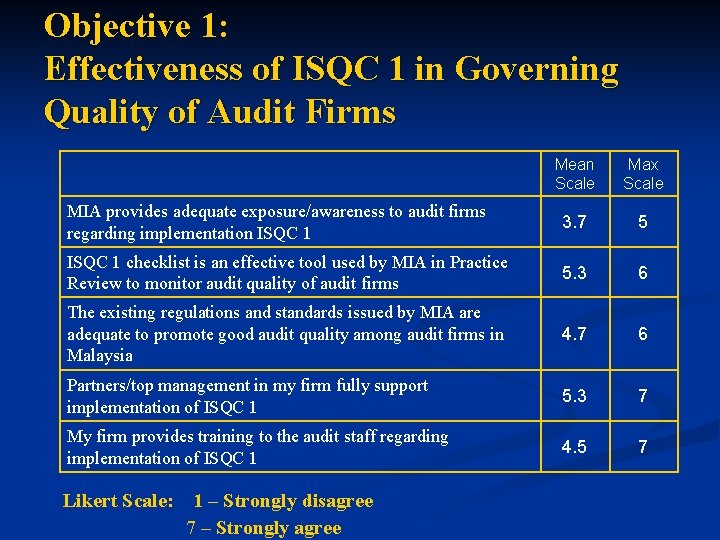
Objective 1: Effectiveness of ISQC 1 in Governing Quality of Audit Firms Mean Scale Max Scale MIA provides adequate exposure/awareness to audit firms regarding implementation ISQC 1 3. 7 5 ISQC 1 checklist is an effective tool used by MIA in Practice Review to monitor audit quality of audit firms 5. 3 6 The existing regulations and standards issued by MIA are adequate to promote good audit quality among audit firms in Malaysia 4. 7 6 Partners/top management in my firm fully support implementation of ISQC 1 5. 3 7 My firm provides training to the audit staff regarding implementation of ISQC 1 4. 5 7 Likert Scale: 1 – Strongly disagree 7 – Strongly agree
Objective 2: Development of the ISQC 1 Self-Assessment Checklist Documentation Monitoring Leadership ISQC 1 Dimensions Engagement Performance Ethical Requirement Client Relationships Human Resources
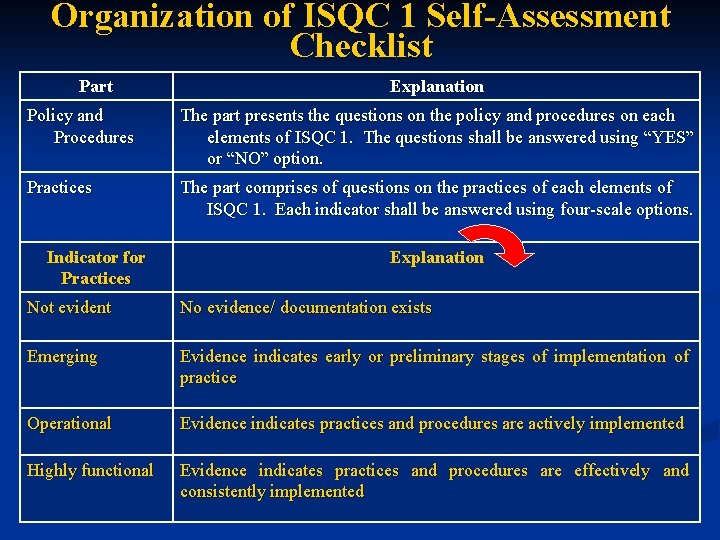
Organization of ISQC 1 Self-Assessment Checklist Part Explanation Policy and Procedures The part presents the questions on the policy and procedures on each elements of ISQC 1. The questions shall be answered using “YES” or “NO” option. Practices The part comprises of questions on the practices of each elements of ISQC 1. Each indicator shall be answered using four-scale options. Indicator for Practices Explanation Not evident No evidence/ documentation exists Emerging Evidence indicates early or preliminary stages of implementation of practice Operational Evidence indicates practices and procedures are actively implemented Highly functional Evidence indicates practices and procedures are effectively and consistently implemented
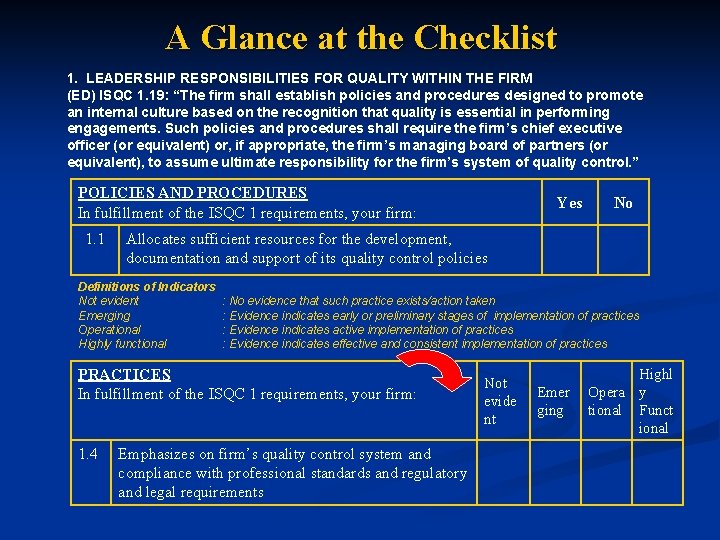
A Glance at the Checklist 1. LEADERSHIP RESPONSIBILITIES FOR QUALITY WITHIN THE FIRM (ED) ISQC 1. 19: “The firm shall establish policies and procedures designed to promote an internal culture based on the recognition that quality is essential in performing engagements. Such policies and procedures shall require the firm’s chief executive officer (or equivalent) or, if appropriate, the firm’s managing board of partners (or equivalent), to assume ultimate responsibility for the firm’s system of quality control. ” POLICIES AND PROCEDURES In fulfillment of the ISQC 1 requirements, your firm: 1. 1 No Allocates sufficient resources for the development, documentation and support of its quality control policies Definitions of Indicators Not evident Emerging Operational Highly functional : No evidence that such practice exists/action taken : Evidence indicates early or preliminary stages of implementation of practices : Evidence indicates active implementation of practices : Evidence indicates effective and consistent implementation of practices PRACTICES In fulfillment of the ISQC 1 requirements, your firm: 1. 4 Yes Emphasizes on firm’s quality control system and compliance with professional standards and regulatory and legal requirements Not evide nt Emer ging Highl Opera y tional Funct ional
Score Assessment
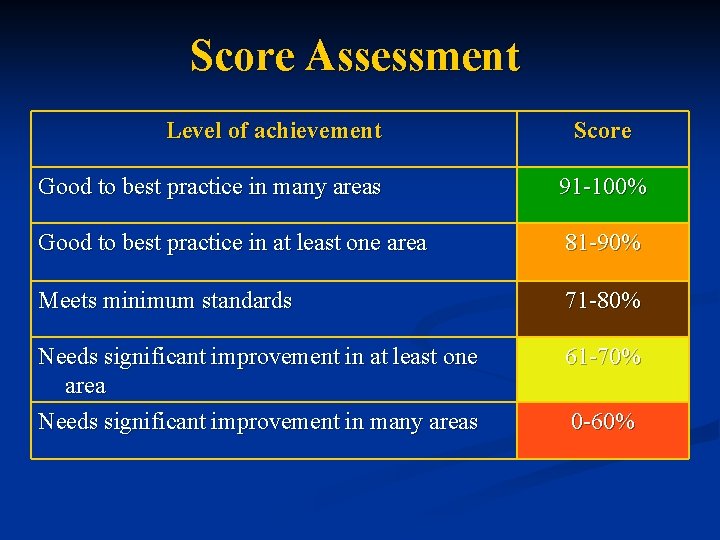
Score Assessment Level of achievement Score Good to best practice in many areas 91 -100% Good to best practice in at least one area 81 -90% Meets minimum standards 71 -80% Needs significant improvement in at least one area Needs significant improvement in many areas 61 -70% 0 -60%
Next Action One day seminar: launch and introduce the checklist to the auditors n Negotiate with MIA to leverage the checklist for annual license renewal for audit firms – green light from MIA n
Governing Quality of Audit Firms in Malaysia Faculty of Accountancy and Accounting Research Institute Universiti Teknologi MARA Appreciate any comment for improvement & THANK YOU