
Glencoe Personal Finance Copyright by The Mc GrawHill
Glencoe Personal Finance Copyright © by The Mc. Graw-Hill Companies, Inc. All rights reserved.
Chapter Consumer Credit 8 What steps can you take now to start building and maintaining a strong credit rating? Glencoe Personal Finance Copyright © by The Mc. Graw-Hill Companies, Inc. All rights reserved.
Chapter Consumer Credit 8 There advantages to using consumer credit if you use it correctly. You must protect your credit and watch for the warning signs of debt problems. Glencoe Personal Finance Copyright © by The Mc. Graw-Hill Companies, Inc. All rights reserved.
Chapter Consumer Credit 8 credit consumer credit annual percentage rate (APR) creditor closed-end credit open-end credit line of credit grace period finance charge collateral simple interest minimum monthly payment credit rating cosigning bankruptcy net income Glencoe Personal Finance Copyright © by The Mc. Graw-Hill Companies, Inc. All rights reserved.
Chapter Consumer Credit 8 Glencoe Personal Finance Copyright © by The Mc. Graw-Hill Companies, Inc. All rights reserved.
Chapter 8 Consumer Credit Section 1 What Is Consumer Credit? Explain the meaning of consumer credit. Differentiate between closed-end and open-end credit. Glencoe Personal Finance Copyright © by The Mc. Graw-Hill Companies, Inc. All rights reserved.
Chapter 8 Consumer Credit Section 1 What Is Consumer Credit? Using Consumer Credit Wisely Good credit means you have the ability to borrow funds to buy things you would otherwise have to save for. credit an arrangement to receive cash, goods, or services now and pay for them in the future Glencoe Personal Finance Copyright © by The Mc. Graw-Hill Companies, Inc. All rights reserved.
Chapter 8 Consumer Credit Section 1 What Is Consumer Credit? Using Consumer Credit Wisely Consumer credit is a major force in the American economy. consumer credit use of credit for personal needs Glencoe Personal Finance Copyright © by The Mc. Graw-Hill Companies, Inc. All rights reserved.
Chapter 8 Consumer Credit Section 1 What Is Consumer Credit? Using Consumer Credit Wisely What is a creditor? creditor an entity that lends money Glencoe Personal Finance Copyright © by The Mc. Graw-Hill Companies, Inc. All rights reserved.
Chapter 8 Consumer Credit Section 1 What Is Consumer Credit? Using Consumer Credit Wisely Using credit increases the amount of money you can spend now, but the cost of credit decreases the amount of money you will have in the future. Glencoe Personal Finance Copyright © by The Mc. Graw-Hill Companies, Inc. All rights reserved.
Chapter 8 Consumer Credit Section 1 What Is Consumer Credit? Factors to Consider Before Using Credit What should you know before using credit? Do you have the cash you need for the down payment? Do you want to use your savings instead of credit? Can you afford the item? Could you use the credit in some better way? Could you put off buying the item for a while? What are the opportunity costs of postponing the purchase? What are the costs of using credit? Glencoe Personal Finance Copyright © by The Mc. Graw-Hill Companies, Inc. All rights reserved.
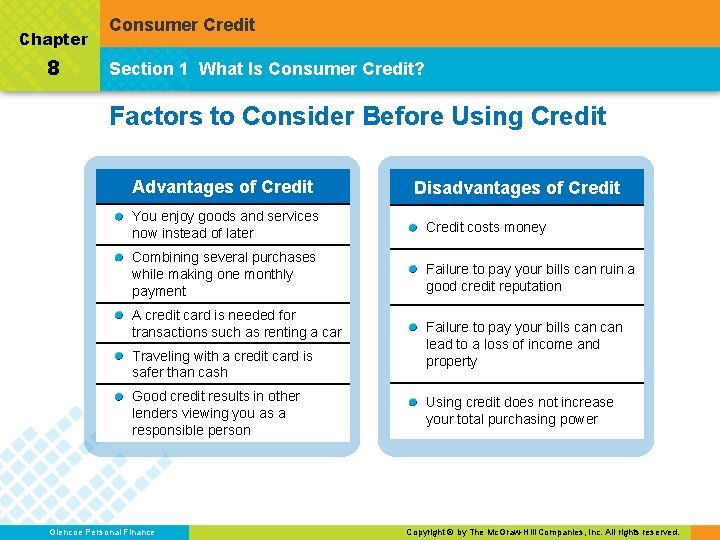
Chapter 8 Consumer Credit Section 1 What Is Consumer Credit? Factors to Consider Before Using Credit Advantages of Credit Disadvantages of Credit You enjoy goods and services now instead of later Credit costs money Combining several purchases while making one monthly payment Failure to pay your bills can ruin a good credit reputation A credit card is needed for transactions such as renting a car Traveling with a credit card is safer than cash Good credit results in other lenders viewing you as a responsible person Glencoe Personal Finance Failure to pay your bills can lead to a loss of income and property Using credit does not increase your total purchasing power Copyright © by The Mc. Graw-Hill Companies, Inc. All rights reserved.
Chapter 8 Consumer Credit Section 1 What Is Consumer Credit? Types of Credit Closed-End Credit Open-End Credit closed-end credit as a one-time loan that is paid back over a specified period of time in payments of equal amounts open-end credit as a loan with a certain limit on the amount of money that can be borrowed for a variety of goods and services Glencoe Personal Finance Copyright © by The Mc. Graw-Hill Companies, Inc. All rights reserved.
Chapter 8 Consumer Credit Section 1 What Is Consumer Credit? Types of Credit What is a line of credit? line of credit maximum amount of money a creditor will allow a credit user to borrow Glencoe Personal Finance Copyright © by The Mc. Graw-Hill Companies, Inc. All rights reserved.
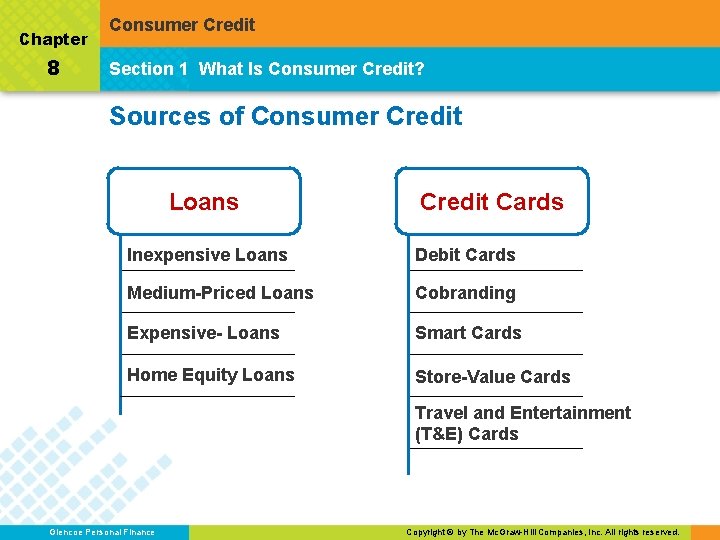
Chapter 8 Consumer Credit Section 1 What Is Consumer Credit? Sources of Consumer Credit Loans Credit Cards Inexpensive Loans Debit Cards Medium-Priced Loans Cobranding Expensive- Loans Smart Cards Home Equity Loans Store-Value Cards Travel and Entertainment (T&E) Cards Glencoe Personal Finance Copyright © by The Mc. Graw-Hill Companies, Inc. All rights reserved.
Chapter 8 Consumer Credit Section 1 What Is Consumer Credit? Sources of Consumer Credit When you have a credit card, you should know the grace period and the finance charge. grace period time period during which no finance charges will be added to an account finance charge total dollar amount paid to use credit Glencoe Personal Finance Copyright © by The Mc. Graw-Hill Companies, Inc. All rights reserved.
Chapter 8 Consumer Credit Section 1 What Is Consumer Credit? Look at the suggestions in Figure 3 on page 460. Which of the factors do you think might be most important in your choice of a credit card? Sample answer: tip number 2 is most important as it stresses the need to compare credit cards and their terms from several different banks before making an informed decision. Glencoe Personal Finance Copyright © by The Mc. Graw-Hill Companies, Inc. All rights reserved.
Chapter 8 Consumer Credit Section 2 The Costs and Methods of Obtaining Credit Name the five Cs of credit. Identify factors to consider when choosing a loan or credit card. Explain how to build and protect your credit rating. Glencoe Personal Finance Copyright © by The Mc. Graw-Hill Companies, Inc. All rights reserved.
Chapter 8 Consumer Credit Section 2 The Costs and Methods of Obtaining Credit Can You Afford a Loan? Add up all your basic monthly expenses and then subtract the total from your take-home pay. Glencoe Personal Finance Consider what you might give up to make a monthly loan payment. Copyright © by The Mc. Graw-Hill Companies, Inc. All rights reserved.
Chapter 8 Consumer Credit Section 2 The Costs and Methods of Obtaining Credit Can You Afford a Loan? Debt Payments-to-Income Ratio The percentage of debt you have in relation to your net income received from take-home pay, allowance, gifts, and interests Glencoe Personal Finance Copyright © by The Mc. Graw-Hill Companies, Inc. All rights reserved.
Chapter 8 Consumer Credit Section 2 The Costs and Methods of Obtaining Credit The Cost of Credit When shopping for credit, you should know the finance charges and annual percentage rates (APR) of the credit sources you are considering. annual percentage rate (APRP cost of credit on a yearly basis, expressed as a percentage Glencoe Personal Finance Copyright © by The Mc. Graw-Hill Companies, Inc. All rights reserved.
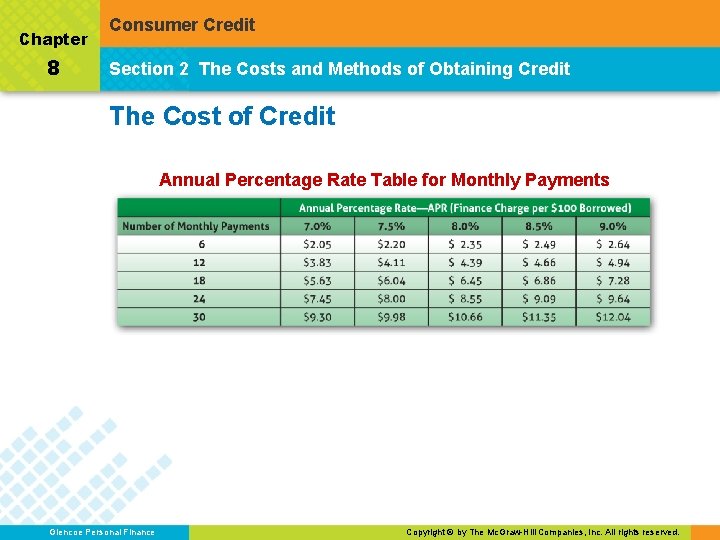
Chapter 8 Consumer Credit Section 2 The Costs and Methods of Obtaining Credit The Cost of Credit Annual Percentage Rate Table for Monthly Payments Glencoe Personal Finance Copyright © by The Mc. Graw-Hill Companies, Inc. All rights reserved.
Chapter 8 Consumer Credit Section 2 The Costs and Methods of Obtaining Credit The Cost of Credit Trade-Offs Term Versus Interest Costs Lender Risk Versus Interest Rate Reduce Risk by Considering: Variable Interest Rate Secured Loan (Requires Collateral) Up-Front Cash Shorter Term collateral a form of security that helps guarantee that the creditor will be repaid Glencoe Personal Finance Copyright © by The Mc. Graw-Hill Companies, Inc. All rights reserved.
Chapter 8 Consumer Credit Section 2 The Costs and Methods of Obtaining Credit The Cost of Credit Calculating the Cost of Credit Simple Interest Cost of Open-End Credit Simple Interest on the Declining Balance Cost of Credit and Expected Inflation Add-On Interest The Minimum Monthly Payment Trap simple interest computed only on the principal minimum monthly payment smallest amount that one can pay and remain a borrower in good standing Glencoe Personal Finance Copyright © by The Mc. Graw-Hill Companies, Inc. All rights reserved.
Chapter 8 Consumer Credit Section 2 The Costs and Methods of Obtaining Credit Applying for Credit The Five Cs of Credit Character Glencoe Personal Finance Capacity Capital Collateral Conditions Copyright © by The Mc. Graw-Hill Companies, Inc. All rights reserved.
Chapter 8 Consumer Credit Section 2 The Costs and Methods of Obtaining Credit Applying for Credit Factors that Determine Credit Rating Income Current Debt Information About Character Debt Payment History credit rating a measure of a person’s ability and willingness to make credit payments on time Glencoe Personal Finance Copyright © by The Mc. Graw-Hill Companies, Inc. All rights reserved.
Chapter 8 Consumer Credit Section 2 The Costs and Methods of Obtaining Credit Applying for Credit Two Types of Credit Reports FICO Glencoe Personal Finance Vantagescore Copyright © by The Mc. Graw-Hill Companies, Inc. All rights reserved.
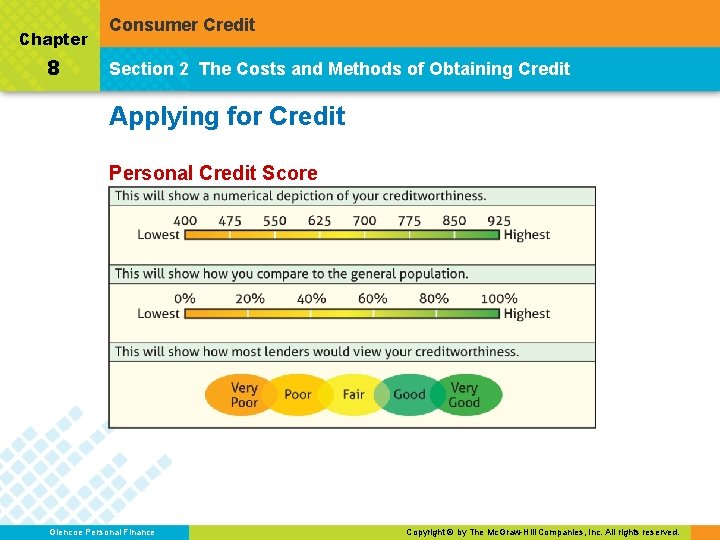
Chapter 8 Consumer Credit Section 2 The Costs and Methods of Obtaining Credit Applying for Credit Personal Credit Score Glencoe Personal Finance Copyright © by The Mc. Graw-Hill Companies, Inc. All rights reserved.
Chapter 8 Consumer Credit Section 2 The Costs and Methods of Obtaining Credit Applying for Credit Because of the Equal Credit Opportunity Act (ECOA), a Creditor May Not: Turn you down or decrease your credit because of your age Ignore your retirement income in rating your application Close your credit account because you have reached a certain age Close your credit account because you have retired Deny you credit because you receive public assistance You have a right to know why you are refused credit. Glencoe Personal Finance Copyright © by The Mc. Graw-Hill Companies, Inc. All rights reserved.
Chapter 8 Consumer Credit Section 2 The Costs and Methods of Obtaining Credit Your Credit Report The Three Major Credit Bureaus Experian Where Do Credit Bureaus Get Information? Banks Finance Companies Trans Union Stores Credit Card Companies Equifax Glencoe Personal Finance Other Lenders Copyright © by The Mc. Graw-Hill Companies, Inc. All rights reserved.
Chapter 8 Consumer Credit Section 2 The Costs and Methods of Obtaining Credit Your Credit Report Contents of Your Credit File Employer, Position, Income Previous Address Previous Employer Spouse’s Information Homeowner or Renter Status Checks Returned or Insufficient Funds Glencoe Personal Finance Copyright © by The Mc. Graw-Hill Companies, Inc. All rights reserved.
Chapter 8 Consumer Credit Section 2 The Costs and Methods of Obtaining Credit Your Credit Report You and Your Credit File There are time limits on unfavorable data. Credit bureaus must ensure information in your credit file is correct. You can sue a credit bureau or creditor that has caused you harm by not following rules established by the Fair Credit Reporting Act. Glencoe Personal Finance Copyright © by The Mc. Graw-Hill Companies, Inc. All rights reserved.
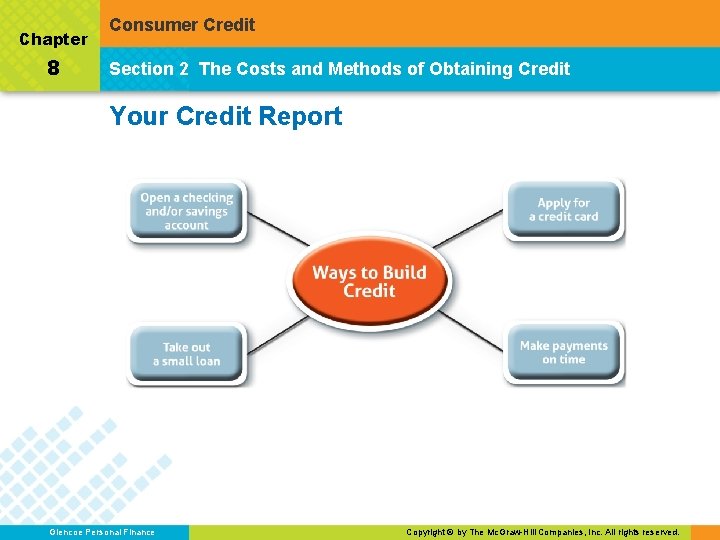
Chapter 8 Consumer Credit Section 2 The Costs and Methods of Obtaining Credit Your Credit Report Glencoe Personal Finance Copyright © by The Mc. Graw-Hill Companies, Inc. All rights reserved.
Chapter 8 Consumer Credit Section 2 The Costs and Methods of Obtaining Credit Suppose you applied for a car loan of $40, 000 and were denied for valid reasons. What would your next steps be toward getting a car loan? According to Figure 6 on page 471, you can ask the creditor if you can provide additional information, apply to a different creditor, or work toward improving your creditworthiness and reapply. Students may also indicate that they might apply for a smaller loan and settle for a less expensive automobile. Glencoe Personal Finance Copyright © by The Mc. Graw-Hill Companies, Inc. All rights reserved.
Chapter 8 Consumer Credit Section 3 Protecting Your Credit Protect yourself from fraud and identity theft. Identify consumer protection laws. Glencoe Personal Finance Copyright © by The Mc. Graw-Hill Companies, Inc. All rights reserved.
Chapter 8 Consumer Credit Section 3 Protecting Your Credit Billing Errors and Disputes If you write a letter to a creditor to dispute a charge: The creditor must acknowledge your letter within 30 days. If the creditor made a mistake, you do not have to pay any finance charges on the disputed amount. If no mistake is found, the creditor must promptly send you a letter of explanation. Glencoe Personal Finance Copyright © by The Mc. Graw-Hill Companies, Inc. All rights reserved.
Chapter 8 Consumer Credit Section 3 Protecting Your Credit Billing Errors and Disputes For your protection: A creditor may not threaten your credit rating. A creditor cannot take any action against you until a complaint is settled. You may instruct a credit card company to hold payment if you purchase a defective item. Glencoe Personal Finance Copyright © by The Mc. Graw-Hill Companies, Inc. All rights reserved.
Chapter 8 Consumer Credit Section 3 Protecting Your Credit and Stolen Identity If you think you are a victim of identity theft: Contact the Credit Bureaus Glencoe Personal Finance Contact the Creditors File a Police Report Copyright © by The Mc. Graw-Hill Companies, Inc. All rights reserved.
Chapter 8 Consumer Credit Section 3 Protecting Your Credit From Theft or Loss Avoid Having Your Credit Card Being Stolen or Lost Always retrieve your card after a purchase. Keep a record of your credit card numbers. Notify the credit card company immediately if your card is lost or stolen. Glencoe Personal Finance Copyright © by The Mc. Graw-Hill Companies, Inc. All rights reserved.
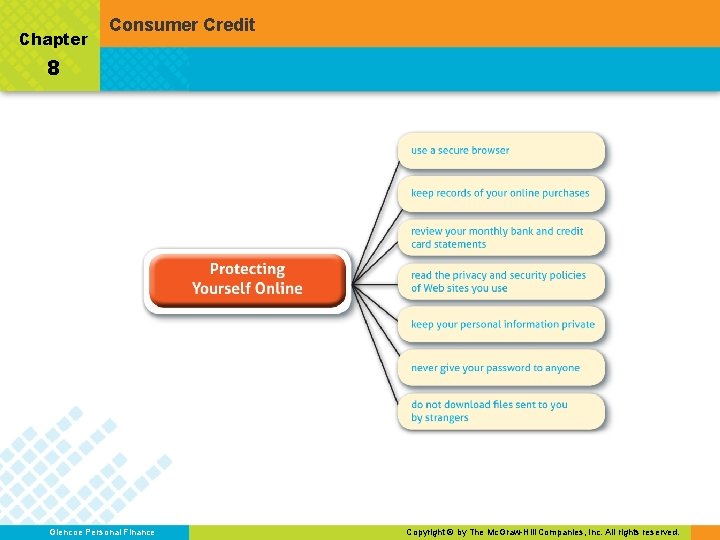
Chapter 8 Consumer Credit Section 3 Protecting Your Credit from Theft or Loss Protecting Your Credit on the Internet Use a secure browser. Keep records of online transactions. Review monthly bank and credit card statements. Read privacy and security policies of Web sites. Keep your personal information private. Never give your password to anyone online. Do not download files sent to you by strangers. Glencoe Personal Finance Copyright © by The Mc. Graw-Hill Companies, Inc. All rights reserved.
Chapter 8 Consumer Credit Section 3 Protecting Your Credit Cosigning a Loan When Cosigning a Loan: Be sure you can afford to pay the loan. Consider your liability for the loan. Understand that you could lose property. Understand your legal rights as a cosigner. Request that a copy of overdue-payment notices be given to you. cosigning agreeing to take responsibility for loan payments if the other person fails to make them Glencoe Personal Finance Copyright © by The Mc. Graw-Hill Companies, Inc. All rights reserved.
Chapter 8 Consumer Credit Section 3 Protecting Your Credit Complaining About Consumer Credit Consumer Protection Laws Credit Card Act Truth in Lending Act Consumer Leasing Act Equal Opportunity Act (ECOA) Fair Credit Opportunity Act Fair Credit Reporting Act Consumer Credit Reporting Reform Act Glencoe Personal Finance Copyright © by The Mc. Graw-Hill Companies, Inc. All rights reserved.
Chapter 8 Consumer Credit Section 3 Protecting Your Credit Complaining About Consumer Credit In Cases of Discrimination: Complain to the creditor. File a complaint with the government. If all else fails, sue the creditor. Glencoe Personal Finance Copyright © by The Mc. Graw-Hill Companies, Inc. All rights reserved.
Chapter 8 Consumer Credit Section 3 Protecting Your Credit The Consumer Credit Reporting Reform Act states that the burden of proof for accurate information is on the credit bureau rather than on you. How can this benefit you if you find information you feel is wrong on your credit report? Students should understand that if you dispute information on your credit report and the credit bureau cannot prove it is accurate, then they must remove the information from your report. Prior to the law, the information would have remained on the report until you could prove it was inaccurate. Glencoe Personal Finance Copyright © by The Mc. Graw-Hill Companies, Inc. All rights reserved.
Chapter 8 Consumer Credit Section 4 Managing Your Debts Describe options for managing debt problems. Identify signs of debt problems. Glencoe Personal Finance Copyright © by The Mc. Graw-Hill Companies, Inc. All rights reserved.
Chapter 8 Consumer Credit Section 4 Managing Your Debts Signs of Debt Problems Are You Experiencing Two or More of These Warning Signs? You make only the minimum monthly payment You struggle to make the monthly payment The total balance increases every month You miss payments or you are often late You use savings to pay for necessities You receive second or third late payment due notices You borrow money to pay off old debts You exceed credit limits You have been denied credit because of bad credit Glencoe Personal Finance Copyright © by The Mc. Graw-Hill Companies, Inc. All rights reserved.
Chapter 8 Consumer Credit Section 4 Managing Your Debts Debt Collection Practices Creditors often turn over bad debts to debt collection companies. The Federal Trade Commission enforces the Fair Debt Collection Practices Act (FDCPA). Glencoe Personal Finance Copyright © by The Mc. Graw-Hill Companies, Inc. All rights reserved.
Chapter 8 Consumer Credit Section 4 Managing Your Debts Financial Counseling Services Trouble Paying Your Bills? Contact your creditors Consumer Credit Counseling Service (CCCS) Universities, credit unions, military bases State and federal housing authorities Banks Reputable financial counseling services Glencoe Personal Finance Copyright © by The Mc. Graw-Hill Companies, Inc. All rights reserved.
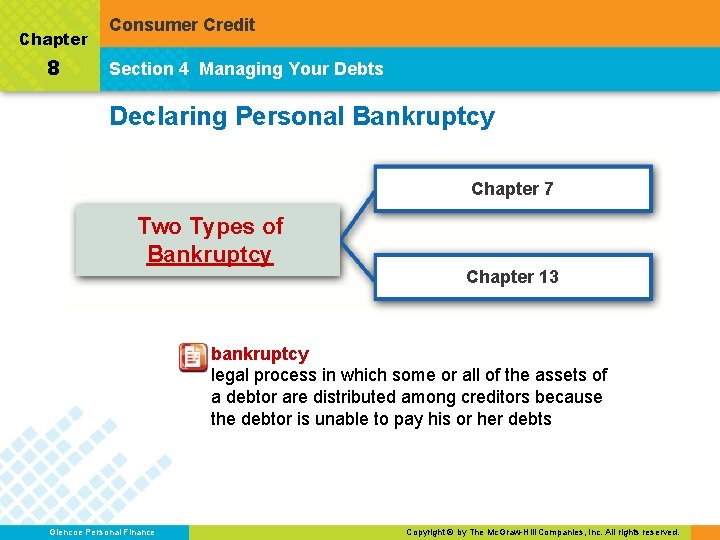
Chapter 8 Consumer Credit Section 4 Managing Your Debts Declaring Personal Bankruptcy Chapter 7 Two Types of Bankruptcy Chapter 13 bankruptcy legal process in which some or all of the assets of a debtor are distributed among creditors because the debtor is unable to pay his or her debts Glencoe Personal Finance Copyright © by The Mc. Graw-Hill Companies, Inc. All rights reserved.
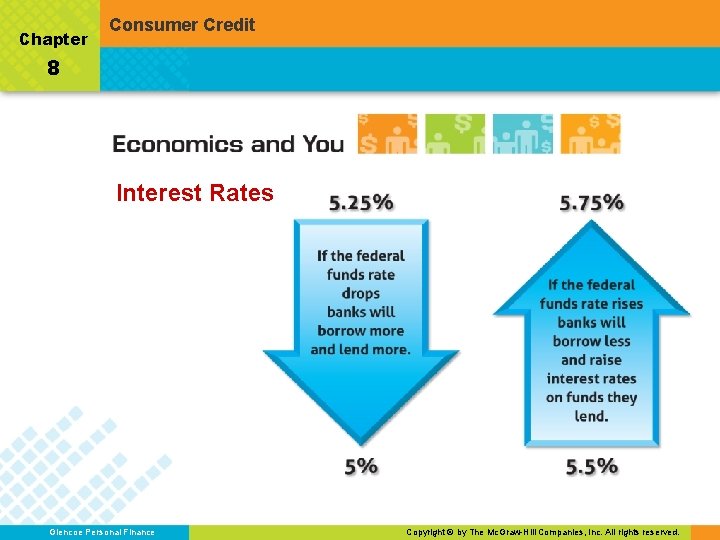
Chapter Consumer Credit 8 Interest Rates Glencoe Personal Finance Copyright © by The Mc. Graw-Hill Companies, Inc. All rights reserved.
Chapter Consumer Credit 8 Glencoe Personal Finance Copyright © by The Mc. Graw-Hill Companies, Inc. All rights reserved.
Chapter Consumer Credit 8 Glencoe Personal Finance Copyright © by The Mc. Graw-Hill Companies, Inc. All rights reserved.
End of Glencoe Personal Finance Copyright © by The Mc. Graw-Hill Companies, Inc. All rights reserved.
- Slides: 53