
FUND ACCOUNTING INFORMATION PRESENTATION By Dalana Moore AGENDA
FUND ACCOUNTING INFORMATION PRESENTATION By Dalana Moore
AGENDA l Fund Accounting l Fund Definitions (Handout) l Fund Transfers l Consolidated Fund Valid Account List l MPathways Relationships (“Flower” Handout) l Chartfield Definitions (Handout) l Shortcodes vs. Chartfields (Handout) l Questions
FUND ACCOUNTING What is Fund Accounting? l l The University is a non-profit, governmental entity, therefore it has to follow the fund accounting principles. l The University receives money from many different sources. The source determines what Fund the money will be deposited into. The Fund also dictates what kind of expenditures will be allowable. l Unrestricted vs. Restricted Funds l Unrestricted Funds - resources the University receives in which the donor or grantor has not made stipulations regarding their use. However University and IRS rules do apply. l l Examples: General, Designated, & Auxiliary Funds Restricted Funds - resources the University receives where a donor or grantor specifically defines the purpose, program, Department, or School/College. l Examples: Gift and Sponsored
Fund Definitions The University’s major fund groupings for internal operating and reporting purposes. l Funds include: l General - 10000 l Expendable Restricted – 20000, 25000, 30000 l Designated – 40000 l Auxiliary – 5 xxxx l Student Loans – 6 xxxx (Ann Arbor Only) l Endowment and Other Invested Funds – 7 xxxx l Plant – 8 xxxx l Agency - 90000 l
Fund Transfers l Why can’t you do transfers between Funds? By moving money from one Fund to another, it changes how the money can be spent. l When the University is audited, we have to be able to confirm that each Fund spends its money for the correct type of expenditures defined by the Fund. l
CONSOLIDATED FUND VALID ACCOUNT LISTING This list defines what revenue and expense accounts are allowed and not allowed across all Funds. l You can open the list (Excel) from the web from the Financial Services & Budget Website. l l https: //www. umflint. edu/fi ancialservices/validaccount-list
MPATHWAYS RELATIONSHIPS l “Flower” Diagram l This illustrates the relationships between the different MPathways Systems. l l l Financial Procurement HRMS/Payroll Student (only Ann Arbor) Accounts Receivable
CHARTFIELD DEFINITIONS l What are chartfields? l Budget Period – The fiscal year we are currently in. l l Budget Period is July 1 st – June 30 th BP xxxx = June 30 th calendar year (EX: June 30, 2004 = BP 2004) l l l Fund - Where your money comes from and how that money can be spent. Dept ID - Who the money belongs to. Program - How the Dept. wants to keep track of their money. Project/Grant - A further definition of how the Dept. wants to keep track of their $. Class - What the Dept. is using the money for. (Handout) Account - What type of transaction it is.
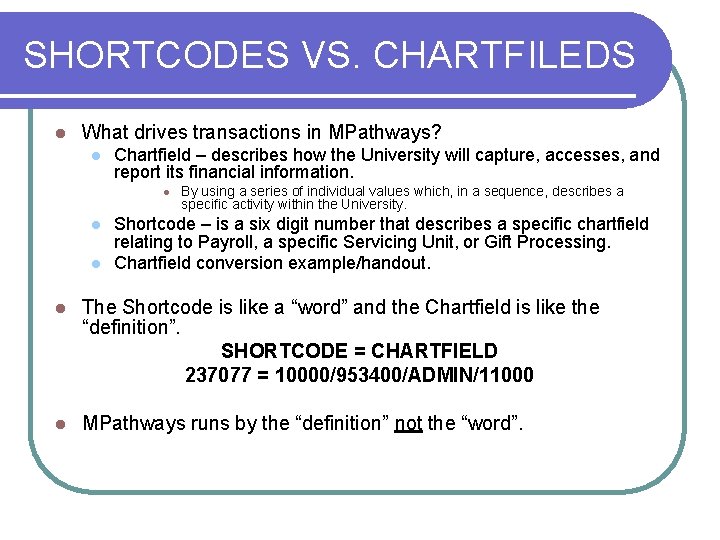
SHORTCODES VS. CHARTFILEDS l What drives transactions in MPathways? l Chartfield – describes how the University will capture, accesses, and report its financial information. l l l By using a series of individual values which, in a sequence, describes a specific activity within the University. Shortcode – is a six digit number that describes a specific chartfield relating to Payroll, a specific Servicing Unit, or Gift Processing. Chartfield conversion example/handout. l The Shortcode is like a “word” and the Chartfield is like the “definition”. SHORTCODE = CHARTFIELD 237077 = 10000/953400/ADMIN/11000 l MPathways runs by the “definition” not the “word”.
QUESTIONS
- Slides: 10