
Forest Health Protection Cost Share Tax Updated August
- Slides: 9
Forest Health Protection Cost Share Tax Updated August 2009
Dr. Linda Wang National Forest Tax Specialist USDA Forest Service lwang@fs. fed. us
Forest Health Protection Cost Share § Forest Health Protection program cost share provide treatment for: § southern pine beetle § western bark beetle § forest diseases § invasive plants § or other major insect infestations
Cost Share Tax Treatment § Generally governmental cost share payment are taxable income § However, qualified cost share payment may be excluded from a taxpayer’s income (Tax Code § 126)
Sec. 126 Income Exclusion An example § Mr. Smith received $3, 000 cost share payment (shown on Form 1099 -G) from qualified forestry program to manage his timberland. § He may elect to exclude all or part of the $3, 000 from his income, using the IRS formula, under the tax regulation of § 126
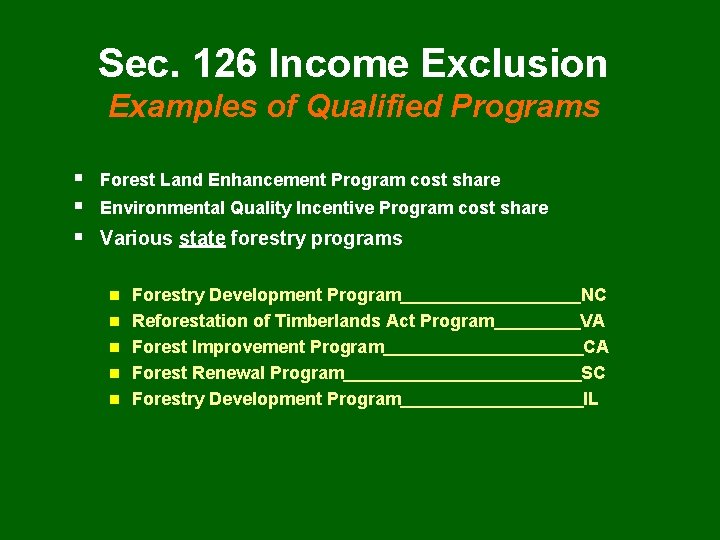
Sec. 126 Income Exclusion Examples of Qualified Programs § § Forest Land Enhancement Program cost share § Various state forestry programs Environmental Quality Incentive Program cost share n n n Forestry Development Program Reforestation of Timberlands Act Program Forest Improvement Program Forest Renewal Program Forestry Development Program NC VA CA SC IL
Filing for Sec. 126 Exclusion Forest Health Protection Cost Share § First step The Secretary of Department of Agriculture has approved the Forest Health Protection cost share (Tax Code § 126 (b)(1)(A)) (USDA Reg. 7 CFR part 14)
Filing for Sec. 126 Exclusion Forest Health Protection Cost Share § Second step § The Forest Health Protection cost share program is approved by the IRS § Revenue ruling 2009 -23 was issued by the IRS (IRB 2009 -32)
Forest Health Protection Cost Share Approved for Sec. 126 • For more information, please go to www. timbertax. org front page