
Follow up of NYC Netflix Strategic Partnership Fact
- Slides: 11
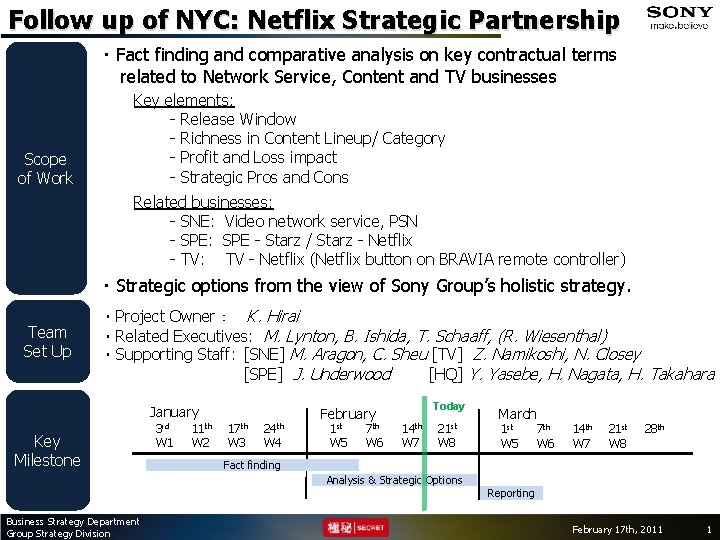
Follow up of NYC: Netflix Strategic Partnership ・Fact finding and comparative analysis on key contractual terms related to Network Service, Content and TV businesses Scope of Work Key elements: - Release Window - Richness in Content Lineup/ Category - Profit and Loss impact - Strategic Pros and Cons Related businesses: - SNE: Video network service, PSN - SPE: SPE - Starz / Starz - Netflix - TV: TV - Netflix (Netflix button on BRAVIA remote controller) ・Strategic options from the view of Sony Group’s holistic strategy. Team Set Up ・Project Owner: K. Hirai ・Related Executives: M. Lynton, B. Ishida, T. Schaaff, (R. Wiesenthal) ・Supporting Staff: [SNE] M. Aragon, C. Sheu [TV] Z. Namikoshi, N. Closey [SPE] J. Underwood [HQ] Y. Yasebe, H. Nagata, H. Takahara January Key Milestone 3 rd W 1 11 th W 2 17 th W 3 24 th W 4 February 1 st W 5 7 th W 6 Today 14 th W 7 21 st W 8 1 st W 5 7 th W 6 14 th W 7 21 st W 8 28 th Fact finding Analysis & Strategic Options Business Strategy Department Group Strategy Division | 2010 MRP Group Strategy Division March Reporting February 17 th, 2011 1
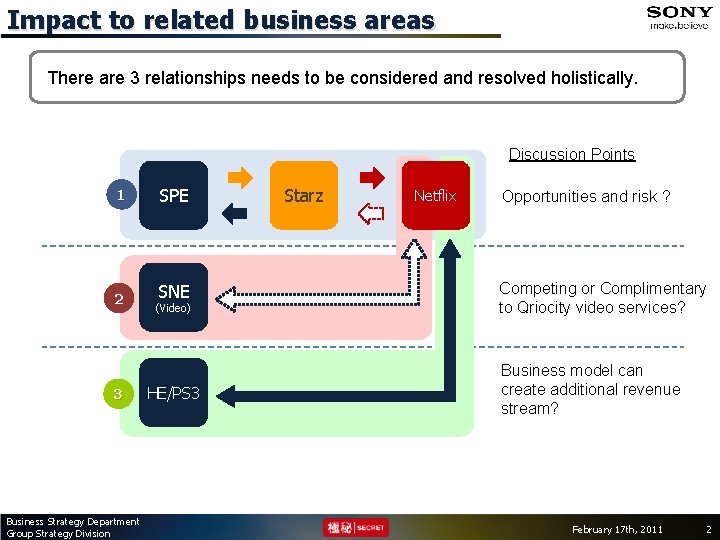
Impact to related business areas There are 3 relationships needs to be considered and resolved holistically. Discussion Points 1 SPE 2 SNE 3 (Video) HE/PS 3 Business Strategy Department Group Strategy Division | 2010 MRP Group Strategy Division Starz Netflix Opportunities and risk ? Competing or Complimentary to Qriocity video services? Business model can create additional revenue stream? February 17 th, 2011 2
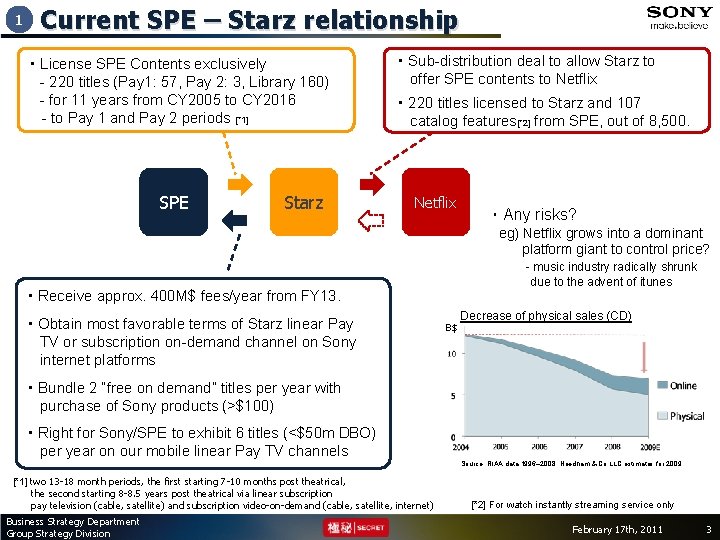
1 Current SPE – Starz relationship ・License SPE Contents exclusively - 220 titles (Pay 1: 57, Pay 2: 3, Library 160) - for 11 years from CY 2005 to CY 2016 - to Pay 1 and Pay 2 periods [*1] SPE Starz ・Sub-distribution deal to allow Starz to offer SPE contents to Netflix ・ 220 titles licensed to Starz and 107 catalog features[*2] from SPE, out of 8, 500. Netflix ・Any risks? eg) Netflix grows into a dominant platform giant to control price? - music industry radically shrunk due to the advent of itunes ・Receive approx. 400 M$ fees/year from FY 13. ・Obtain most favorable terms of Starz linear Pay TV or subscription on-demand channel on Sony internet platforms B$ Decrease of physical sales (CD) ・Bundle 2 “free on demand” titles per year with purchase of Sony products (>$100) ・Right for Sony/SPE to exhibit 6 titles (<$50 m DBO) per year on our mobile linear Pay TV channels [*1] two 13 -18 month periods, the first starting 7 -10 months post theatrical, the second starting 8 -8. 5 years post theatrical via linear subscription pay television (cable, satellite) and subscription video-on-demand (cable, satellite, internet) Business Strategy Department Group Strategy Division | 2010 MRP Group Strategy Division Source: RIAA data 1996– 2008; Needham & Co LLC estimates for 2009 [*2] For watch instantly streaming service only February 17 th, 2011 3
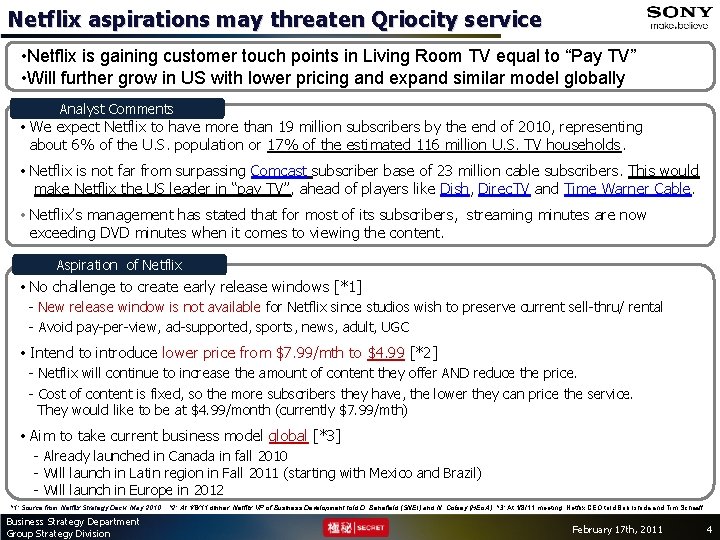
Netflix aspirations may threaten Qriocity service • Netflix is gaining customer touch points in Living Room TV equal to “Pay TV” • Will further grow in US with lower pricing and expand similar model globally Analyst Comments • We expect Netflix to have more than 19 million subscribers by the end of 2010, representing about 6% of the U. S. population or 17% of the estimated 116 million U. S. TV households. • Netflix is not far from surpassing Comcast subscriber base of 23 million cable subscribers. This would make Netflix the US leader in “pay TV”, ahead of players like Dish, Direc. TV and Time Warner Cable. • Netflix’s management has stated that for most of its subscribers, streaming minutes are now exceeding DVD minutes when it comes to viewing the content. Aspiration of Netflix • No challenge to create early release windows [*1] - New release window is not available for Netflix since studios wish to preserve current sell-thru/ rental - Avoid pay-per-view, ad-supported, sports, news, adult, UGC • Intend to introduce lower price from $7. 99/mth to $4. 99 [*2] - Netflix will continue to increase the amount of content they offer AND reduce the price. - Cost of content is fixed, so the more subscribers they have, the lower they can price the service. They would like to be at $4. 99/month (currently $7. 99/mth) • Aim to take current business model global [*3] - Already launched in Canada in fall 2010 - Will launch in Latin region in Fall 2011 (starting with Mexico and Brazil) - Will launch in Europe in 2012 *1: Source from Netflix Strategy Deck, May 2010. *2: At 1/8/11 dinner, Netflix VP of Business Development told D. Benefield (SNEI) and N. Colsey (HEo. A) *3; At 1/8/11 meeting, Netflix CEO told Bob Ishida and Tim Schaaff Business Strategy Department Group Strategy Division | 2010 MRP Group Strategy Division February 17 th, 2011 4
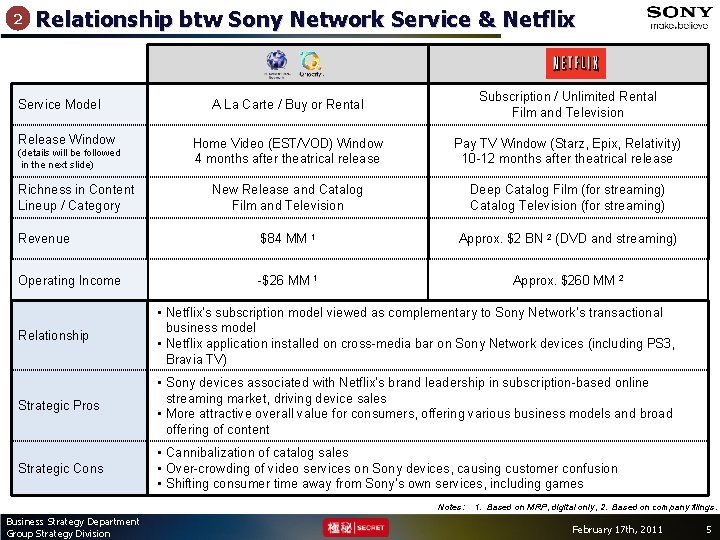
2 Relationship btw Sony Network Service & Netflix A La Carte / Buy or Rental Subscription / Unlimited Rental Film and Television Home Video (EST/VOD) Window 4 months after theatrical release Pay TV Window (Starz, Epix, Relativity) 10 -12 months after theatrical release New Release and Catalog Film and Television Deep Catalog Film (for streaming) Catalog Television (for streaming) Revenue $84 MM 1 Approx. $2 BN 2 (DVD and streaming) Operating Income -$26 MM 1 Approx. $260 MM 2 Service Model Release Window (details will be followed in the next slide) Richness in Content Lineup / Category Relationship • Netflix’s subscription model viewed as complementary to Sony Network’s transactional business model • Netflix application installed on cross-media bar on Sony Network devices (including PS 3, Bravia TV) Strategic Pros • Sony devices associated with Netflix’s brand leadership in subscription-based online streaming market, driving device sales • More attractive overall value for consumers, offering various business models and broad offering of content Strategic Cons • Cannibalization of catalog sales • Over-crowding of video services on Sony devices, causing customer confusion • Shifting consumer time away from Sony’s own services, including games Notes: Business Strategy Department Group Strategy Division | 2010 MRP Group Strategy Division 1. Based on MRP, digital only, 2. Based on company filings. February 17 th, 2011 5
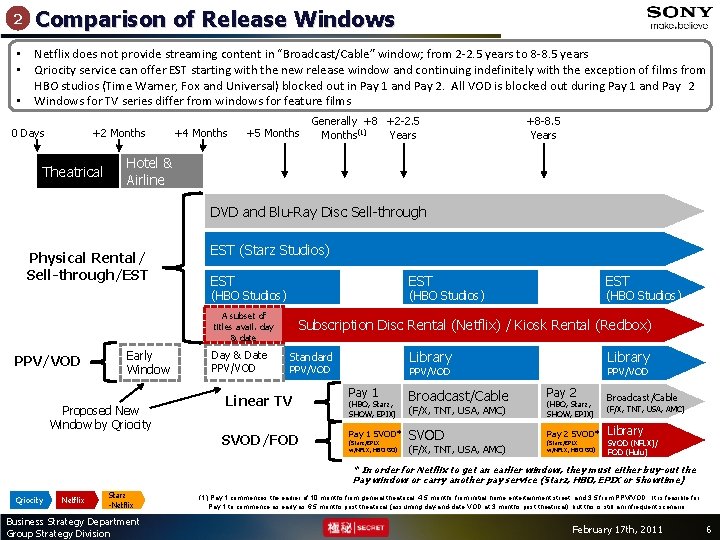
2 Comparison of Release Windows • Netflix does not provide streaming content in “Broadcast/Cable” window; from 2 -2. 5 years to 8 -8. 5 years • Qriocity service can offer EST starting with the new release window and continuing indefinitely with the exception of films from HBO studios (Time Warner, Fox and Universal) blocked out in Pay 1 and Pay 2. All VOD is blocked out during Pay 1 and Pay 2 • Windows for TV series differ from windows for feature films 0 Days +2 Months Theatrical +4 Months +5 Months Generally +8 +2 -2. 5 Months(1) Years +8 -8. 5 Years Hotel & Airline DVD and Blu-Ray Disc Sell-through Physical Rental/ Sell-through/EST (Starz Studios) EST (HBO Studios) A subset of titles avail. day Subscription Disc Rental (Netflix) / Kiosk Rental (Redbox) & date PPV/VOD Early Window Day & Date PPV/VOD Linear TV Proposed New Window by Qriocity Library Standard SVOD/FOD Library PPV/VOD Pay 1 (HBO, Starz, SHOW, EPIX) Pay 1 SVOD* (Starz/EPIX w/NFLX, HBO GO) PPV/VOD Broadcast/Cable Pay 2 (F/X, TNT, USA, AMC) (HBO, Starz, SHOW, EPIX) SVOD Pay 2 SVOD* (F/X, TNT, USA, AMC) (Starz/EPIX w/NFLX, HBO GO) Broadcast/Cable (F/X, TNT, USA, AMC) Library SVOD (NFLX)/ FOD (Hulu) * In order for Netflix to get an earlier window, they must either buy-out the Pay window or carry another pay service (Starz, HBO, EPIX or Showtime) Qriocity Netflix Starz -Netflix (1) Pay 1 commences the earlier of 10 months from general theatrical, 4. 5 months from initial home entertainment street, and 3. 5 from PPV/VOD. It is feasible for Pay 1 to commence as early as 6. 5 months post theatrical (assuming day-and-date VOD at 3 months post theatrical), but this is still an infrequent scenario. Business Strategy Department Group Strategy Division | 2010 MRP Group Strategy Division February 17 th, 2011 6
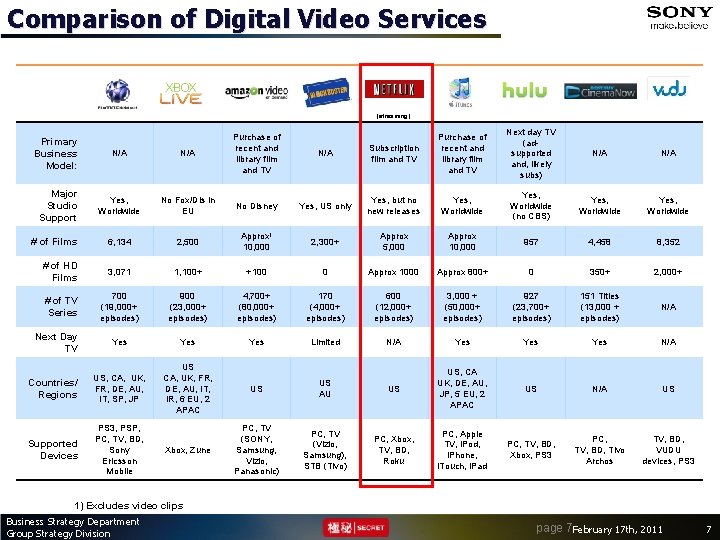
Comparison of Digital Video Services (streaming) Subscription film and TV Purchase of recent and library film and TV Next day TV (adsupported and, likely subs) N/A N/A Purchase of recent and library film and TV Yes, Worldwide No Fox/Dis in EU No Disney Yes, US only Yes, but no new releases Yes, Worldwide (no CBS) Yes, Worldwide # of Films 6, 134 2, 500 Approx 1 10, 000 2, 300+ Approx 5, 000 Approx 10, 000 957 4, 458 8, 352 # of HD Films 3, 071 1, 100+ +100 0 Approx 1000 Approx 800+ 0 350+ 2, 000+ # of TV Series 700 (19, 000+ episodes) 900 (23, 000+ episodes) 4, 700+ (80, 000+ episodes) 170 (4, 000+ episodes) 600 (12, 000+ episodes) 3, 000 + (50, 000+ episodes) 927 (23, 700+ episodes) 151 Titles (13, 000 + episodes) N/A Yes Yes Limited N/A Yes Yes N/A Countries/ Regions US, CA, UK, FR, DE, AU, IT, SP, JP US CA, UK, FR, DE, AU, IT, IR, 6 EU, 2 APAC US US AU US US, CA UK, DE, AU, JP, 5 EU, 2 APAC US N/A US Supported Devices PS 3, PSP, PC, TV, BD, Sony Ericsson Mobile Xbox, Zune PC, TV (SONY, Samsung, Vizio, Panasonic) PC, TV (Vizio, Samsung), STB (Tivo) PC, Xbox, TV, BD, Roku PC, Apple TV, i. Pod, i. Phone, i. Touch, i. Pad PC, TV, BD, Xbox, PS 3 PC, TV, BD, Tivo Archos TV, BD, VUDU devices, PS 3 Primary Business Model: Major Studio Support Next Day TV N/A 1) Excludes video clips Business Strategy Department Group Strategy Division | 2010 MRP Group Strategy Division page 7 February 17 th, 2011 7
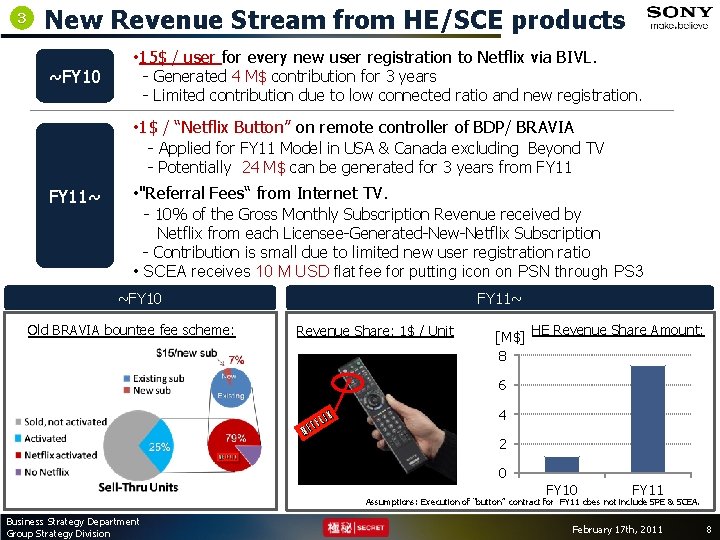
3 New Revenue Stream from HE/SCE products ~FY 10 • 15$ / user for every new user registration to Netflix via BIVL. - Generated 4 M$ contribution for 3 years - Limited contribution due to low connected ratio and new registration. • 1$ / “Netflix Button” on remote controller of BDP/ BRAVIA - Applied for FY 11 Model in USA & Canada excluding Beyond TV - Potentially 24 M$ can be generated for 3 years from FY 11~ • "Referral Fees“ from Internet TV. - 10% of the Gross Monthly Subscription Revenue received by Netflix from each Licensee-Generated-New-Netflix Subscription - Contribution is small due to limited new user registration ratio • SCEA receives 10 M USD flat fee for putting icon on PSN through PS 3 ~FY 10 Old BRAVIA bountee fee scheme: FY 11~ Revenue Share: 1$ / Unit [M$] HE Revenue Share Amount: 8 6 4 2 0 FY 11 Assumptions: Execution of “button” contract for FY 11 does not include SPE & SCEA. Business Strategy Department Group Strategy Division | 2010 MRP Group Strategy Division February 17 th, 2011 8
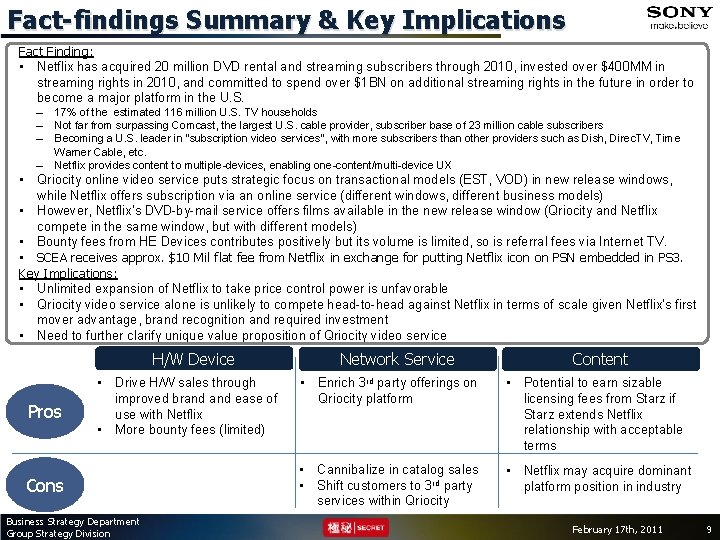
Fact-findings Summary & Key Implications Fact Finding: • Netflix has acquired 20 million DVD rental and streaming subscribers through 2010, invested over $400 MM in streaming rights in 2010, and committed to spend over $1 BN on additional streaming rights in the future in order to become a major platform in the U. S. – – 17% of the estimated 116 million U. S. TV households Not far from surpassing Comcast, the largest U. S. cable provider, subscriber base of 23 million cable subscribers Becoming a U. S. leader in “subscription video services”, with more subscribers than other providers such as Dish, Direc. TV, Time Warner Cable, etc. Netflix provides content to multiple-devices, enabling one-content/multi-device UX • Qriocity online video service puts strategic focus on transactional models (EST, VOD) in new release windows, while Netflix offers subscription via an online service (different windows, different business models) • However, Netflix’s DVD-by-mail service offers films available in the new release window (Qriocity and Netflix compete in the same window, but with different models) • Bounty fees from HE Devices contributes positively but its volume is limited, so is referral fees via Internet TV. • SCEA receives approx. $10 Mil flat fee from Netflix in exchange for putting Netflix icon on PSN embedded in PS 3. Key Implications: • Unlimited expansion of Netflix to take price control power is unfavorable • Qriocity video service alone is unlikely to compete head-to-head against Netflix in terms of scale given Netflix’s first mover advantage, brand recognition and required investment • Need to further clarify unique value proposition of Qriocity video service H/W Device Pros • Drive H/W sales through improved brand ease of use with Netflix • More bounty fees (limited) Cons Business Strategy Department Group Strategy Division | 2010 MRP Group Strategy Division Network Service Content • Enrich 3 rd party offerings on Qriocity platform • Potential to earn sizable licensing fees from Starz if Starz extends Netflix relationship with acceptable terms • Cannibalize in catalog sales • Shift customers to 3 rd party services within Qriocity • Netflix may acquire dominant platform position in industry February 17 th, 2011 9
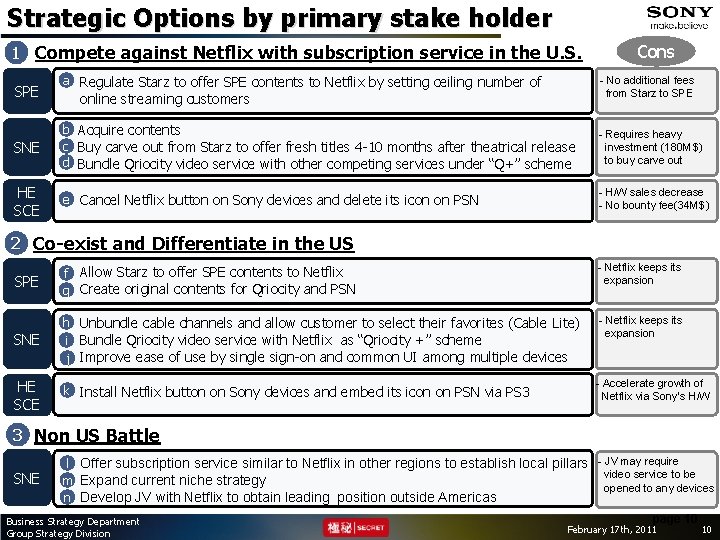
Strategic Options by primary stake holder 1 Compete against Netflix with subscription service in the U. S. SPE a Regulate Starz to offer SPE contents to Netflix by setting ceiling number of Cons - No additional fees from Starz to SPE online streaming customers SNE b Acquire contents c Buy carve out from Starz to offer fresh titles 4 -10 months after theatrical release d Bundle Qriocity video service with other competing services under “Q+” scheme - Requires heavy investment (180 M$) to buy carve out HE SCE e Cancel Netflix button on Sony devices and delete its icon on PSN - H/W sales decrease xx - No bounty fee(34 M$) 2 Co-exist and Differentiate in the US SPE f Allow Starz to offer SPE contents to Netflix g Create original contents for Qriocity and PSN - Netflix keeps its expansion SNE h Unbundle cable channels and allow customer to select their favorites (Cable Lite) i Bundle Qriocity video service with Netflix as “Qriocity +” scheme j Improve ease of use by single sign-on and common UI among multiple devices - Netflix keeps its expansion HE SCE k Install Netflix button on Sony devices and embed its icon on PSN via PS 3 - Accelerate growth of Netflix via Sony’s H/W 3 Non US Battle SNE l Offer subscription service similar to Netflix in other regions to establish local pillars - JV may require video service to be m Expand current niche strategy opened to any devices n Develop JV with Netflix to obtain leading position outside Americas Business Strategy Department Group Strategy Division | 2010 MRP Group Strategy Division page 10 February 17 th, 2011 10
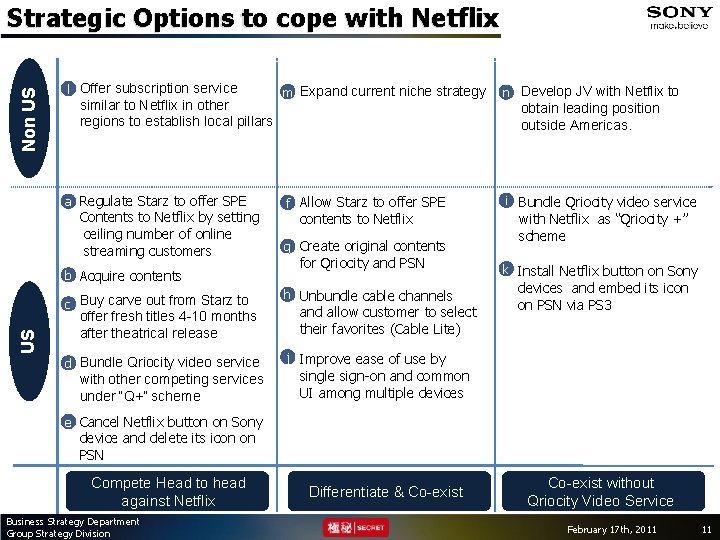
Non US Strategic Options to cope with Netflix l Offer subscription service similar to Netflix in other regions to establish local pillars a Regulate Starz to offer SPE Contents to Netflix by setting ceiling number of online streaming customers US b Acquire contents m Expand current niche strategy obtain leading position outside Americas. f Allow Starz to offer SPE contents to Netflix g Create original contents for Qriocity and PSN c Buy carve out from Starz to offer fresh titles 4 -10 months after theatrical release h Unbundle cable channels d Bundle Qriocity video service j Improve ease of use by with other competing services under “Q+” scheme n Develop JV with Netflix to and allow customer to select their favorites (Cable Lite) i Bundle Qriocity video service with Netflix as “Qriocity +” scheme k Install Netflix button on Sony devices and embed its icon on PSN via PS 3 single sign-on and common UI among multiple devices e Cancel Netflix button on Sony device and delete its icon on PSN Compete Head to head against Netflix Business Strategy Department Group Strategy Division | 2010 MRP Group Strategy Division Differentiate & Co-exist without Qriocity Video Service February 17 th, 2011 11