
FIXED ASSETS PROPERTY PLANT AND EQUIPMENT A CHARACTERISTICS
- Slides: 34
FIXED ASSETS (PROPERTY, PLANT, AND EQUIPMENT)
A. CHARACTERISTICS 1) They are acquired for use in operations and not for resale 2) They are long term in nature and usually subject to depreciation 3) They possess physical substance § Examples of fixed assets (property, plant and equipment) Land Building structures (offices, factories, warehouses) Equipment ( machinery, furniture, tools, vehicles)
B. ACQUISITION OF PROPERTY, PLANT, AND EQUIPMENT Cost of property, plant and equipment includes all amount spent to get it in place and ready for use 1) Cost of acquiring land a) Purchase price b) sale taxes c) permits from governmenth) d) Broker’s commissions e) Title fees f) Surveying fees g) delinquent real estate Razing or removing unwanted buildings, less any salvage i) Grading and leveling j) Paving a public street bordering the land
2. ) Cost of acquiring building - Architecs’ fees - Engineers’ fees - Insurance costs incurred during construction - Interest on manoey borrowed to finance contruction - Walkways to and pound the building - Sales taxes - Reapirs (purchase of existing building) - Reconditioning - Modifying for use - Permits from government agencies
3) Cost of acquiring land improvements - Trees and shrubs - Fences - Outdoor lighting - Paved parking areas 4) Cost of acquiring land machinery and equipment - Sales taxes - Freight - Installation - Repairs (purchase of used equipment) - Assembly - Modifying for use - Testing for use - Permits from government agencies
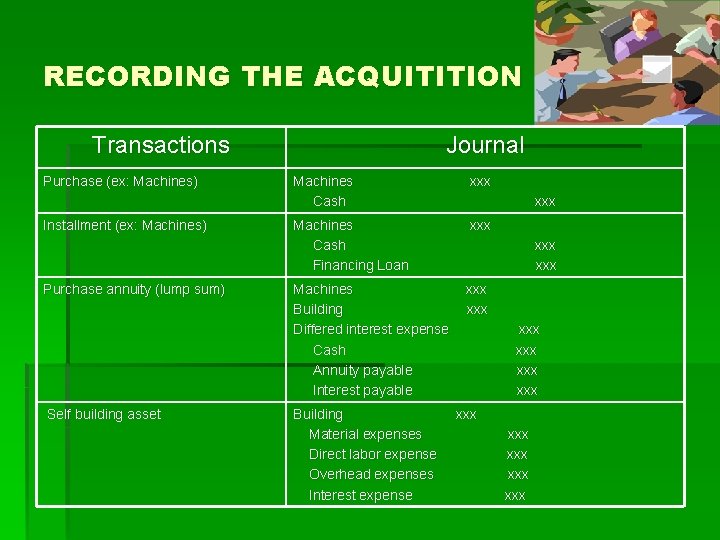
RECORDING THE ACQUITITION Transactions Purchase (ex: Machines) Installment (ex: Machines) Purchase annuity (lump sum) Self building asset Journal Machines Cash xxx Machines Cash Financing Loan xxx Machines Building Differed interest expense Cash Annuity payable Interest payable xxx Building Material expenses Direct labor expense Overhead expenses Interest expense xxx xxx xxx
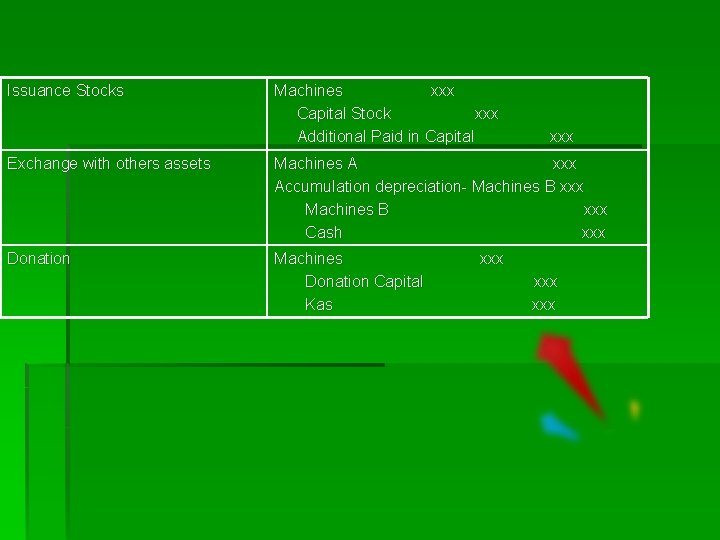
Issuance Stocks Machines xxx Capital Stock xxx Additional Paid in Capital xxx Exchange with others assets Machines A xxx Accumulation depreciation- Machines B xxx Cash xxx Donation Machines Donation Capital Kas xxx xxx
DEPRECIATION § Depreciation is periodic transfer of cost to expense § Factors that course a decline in the ability of fixed asst - Physical depreciation - Functional depreciation § Factor involved in Depreciation Proces § Cost of fixed assets § Usefull life § Residual Value (salvage value)
METHODS OF DEPRECIATION 1. 2. 3. 4. Activity methods Straight-line methods Decreasing charge methods (accelerated) a) Sum-of-the years’-digits b) Declining – balance method Special Depreciation Method a) Group and composite methods b) Hybrid or combination methods
DATE USED TO ILLUSTRATE DEPRECIATION METHODS The following is fixed asset (machines) owned by Sine Furniture, Co: Purchased date January, 1, 2008 Cost of machines Rp. 500. 00 Estimated useful life 5 years’ Estimated Residual Value Rp. 50. 000 Estimated life in hours 30, 000 hours Hours use this year 4, 000 hours
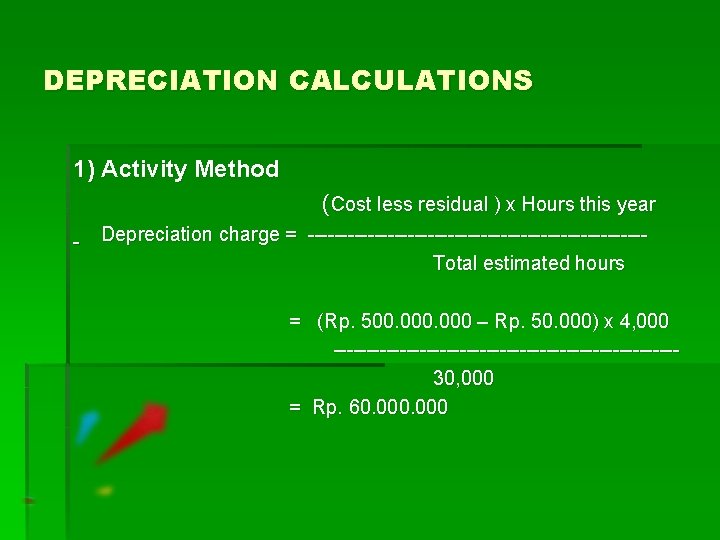
DEPRECIATION CALCULATIONS 1) Activity Method (Cost less residual ) x Hours this year Depreciation charge = -------------------------Total estimated hours = (Rp. 500. 000 – Rp. 50. 000) x 4, 000 --------------------------30, 000 = Rp. 60. 000
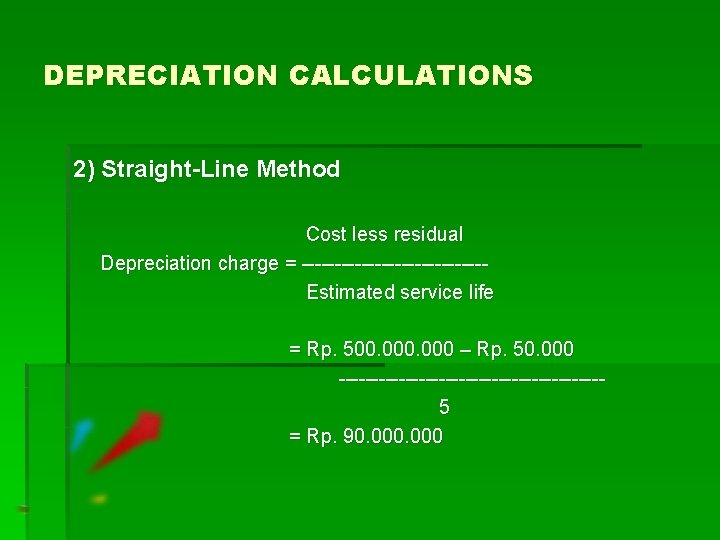
DEPRECIATION CALCULATIONS 2) Straight-Line Method Cost less residual Depreciation charge = --------------Estimated service life = Rp. 500. 000 – Rp. 50. 000 --------------------5 = Rp. 90. 000
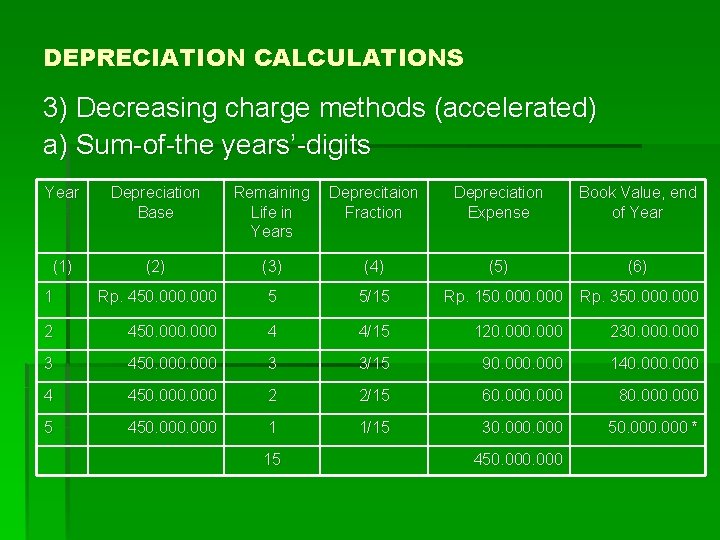
DEPRECIATION CALCULATIONS 3) Decreasing charge methods (accelerated) a) Sum-of-the years’-digits Year Depreciation Base Remaining Life in Years Deprecitaion Fraction Depreciation Expense Book Value, end of Year (1) (2) (3) (4) (5) (6) 1 Rp. 450. 000 5 5/15 Rp. 150. 000 Rp. 350. 000 2 450. 000 4 4/15 120. 000 230. 000 3 450. 000 3 3/15 90. 000 140. 000 4 450. 000 2 2/15 60. 000 80. 000 5 450. 000 1 1/15 30. 000 50. 000 * 15 450. 000
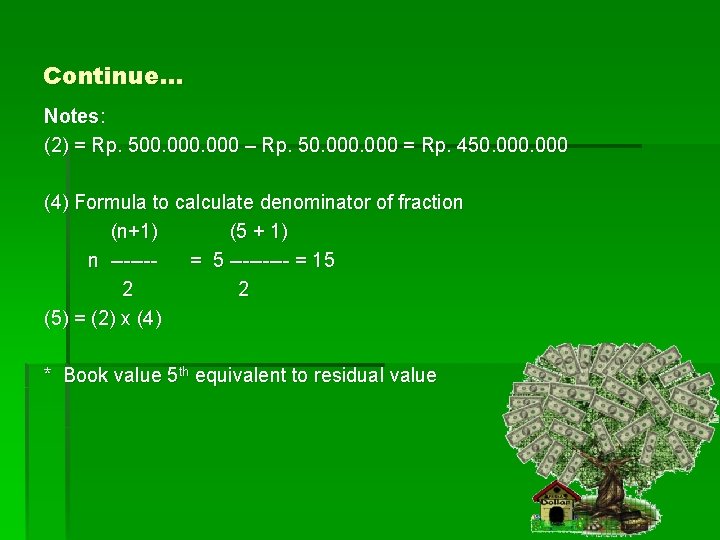
Continue… Notes: (2) = Rp. 500. 000 – Rp. 50. 000 = Rp. 450. 000 (4) Formula to calculate denominator of fraction (n+1) (5 + 1) n ------= 5 ----- = 15 2 2 (5) = (2) x (4) * Book value 5 th equivalent to residual value
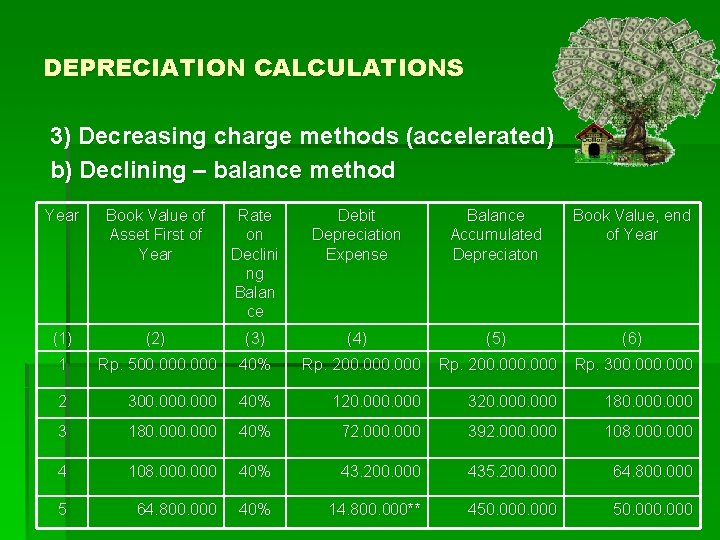
DEPRECIATION CALCULATIONS 3) Decreasing charge methods (accelerated) b) Declining – balance method Year Book Value of Asset First of Year Rate on Declini ng Balan ce Debit Depreciation Expense Balance Accumulated Depreciaton Book Value, end of Year (1) (2) (3) (4) (5) (6) 1 Rp. 500. 000 40% Rp. 200. 000 Rp. 300. 000 2 300. 000 40% 120. 000 320. 000 180. 000 3 180. 000 40% 72. 000 392. 000 108. 000 40% 43. 200. 000 435. 200. 000 64. 800. 000 5 64. 800. 000 40% 14. 800. 000** 450. 000
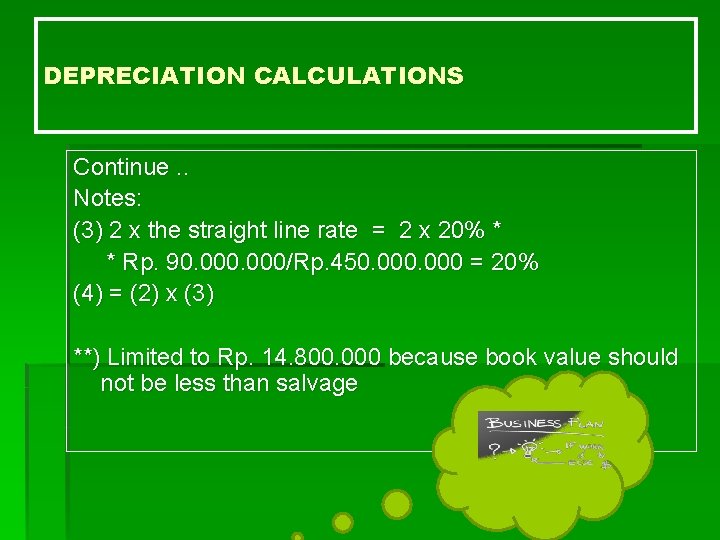
DEPRECIATION CALCULATIONS Continue. . Notes: (3) 2 x the straight line rate = 2 x 20% * * Rp. 90. 000/Rp. 450. 000 = 20% (4) = (2) x (3) **) Limited to Rp. 14. 800. 000 because book value should not be less than salvage
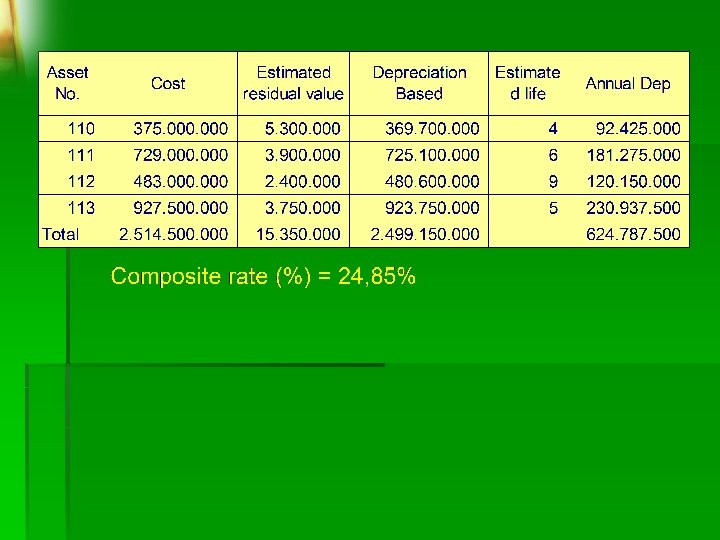
4. § § § Special Depreciation Method (Group and composite methods) This method is applied for group of fixed assets Calculation procedures as follows 1. Computing the annual depreciation for each asset based on straight line method 2. The composite depreciation rate calculate by the total annual depreciation dividing with the sum of cost all assets 3. Useful life of composite assets determined base on sum of depreciation cost all assets by annual depreciation
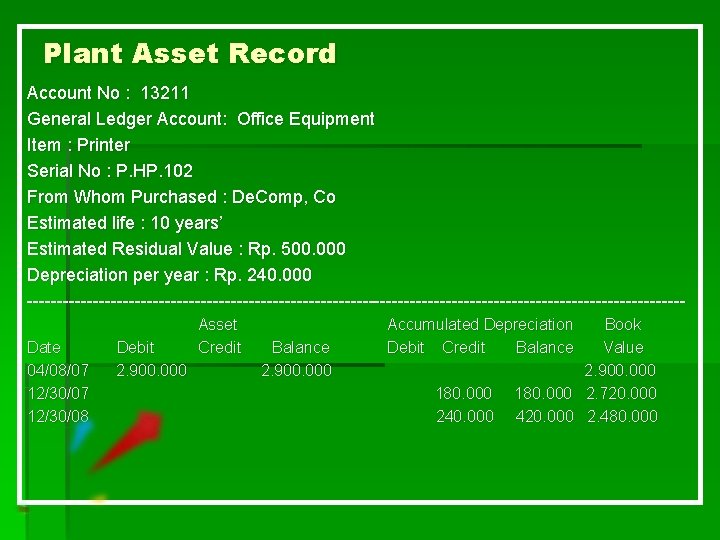
Plant Asset Record Account No : 13211 General Ledger Account: Office Equipment Item : Printer Serial No : P. HP. 102 From Whom Purchased : De. Comp, Co Estimated life : 10 years’ Estimated Residual Value : Rp. 500. 000 Depreciation per year : Rp. 240. 000 -------------------------------------------------------Date 04/08/07 12/30/08 Debit 2. 900. 000 Asset Credit Balance 2. 900. 000 Accumulated Depreciation Debit Credit Balance 180. 000 240. 000 Book Value 2. 900. 000 180. 000 2. 720. 000 420. 000 2. 480. 000
Expenditures During Useful Life A. Revenue expenditure § Cost that benefit only the current period or costs incurred for normal maintenance and repairs § It is debited to expense account § Example: maintenance expense, repainting building, small repairs, etc
B. Capital Expenditure § Costs of acquiring fixed asset, adding to fixed asset, improving fixed asset, or extending a fixed asset’s useful life § It debited to asset account or related to accumulated depreciation account § Types of capital expenditure 1) additions 2) betterments 3) extraordinary repairs
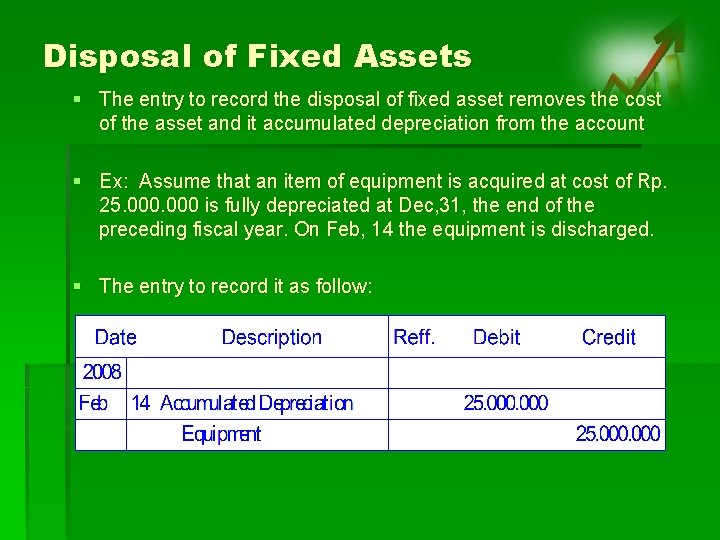
Disposal of Fixed Assets § The entry to record the disposal of fixed asset removes the cost of the asset and it accumulated depreciation from the account § Ex: Assume that an item of equipment is acquired at cost of Rp. 25. 000 is fully depreciated at Dec, 31, the end of the preceding fiscal year. On Feb, 14 the equipment is discharged. § The entry to record it as follow:
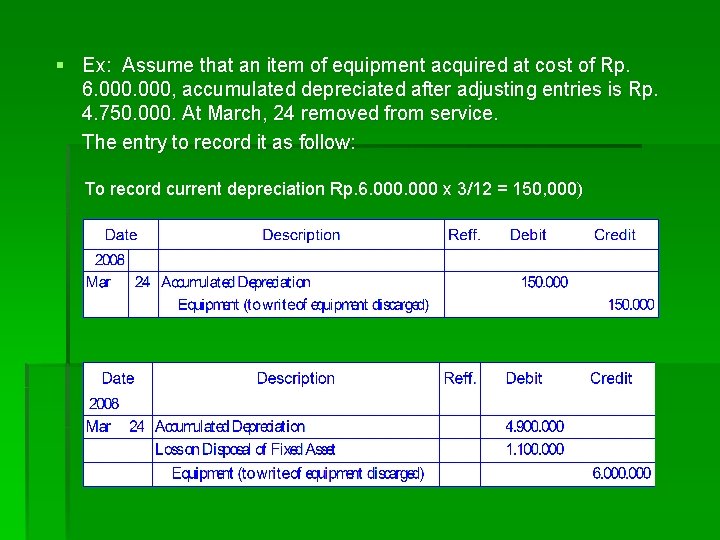
§ Ex: Assume that an item of equipment acquired at cost of Rp. 6. 000, accumulated depreciated after adjusting entries is Rp. 4. 750. 000. At March, 24 removed from service. The entry to record it as follow: To record current depreciation Rp. 6. 000 x 3/12 = 150, 000)
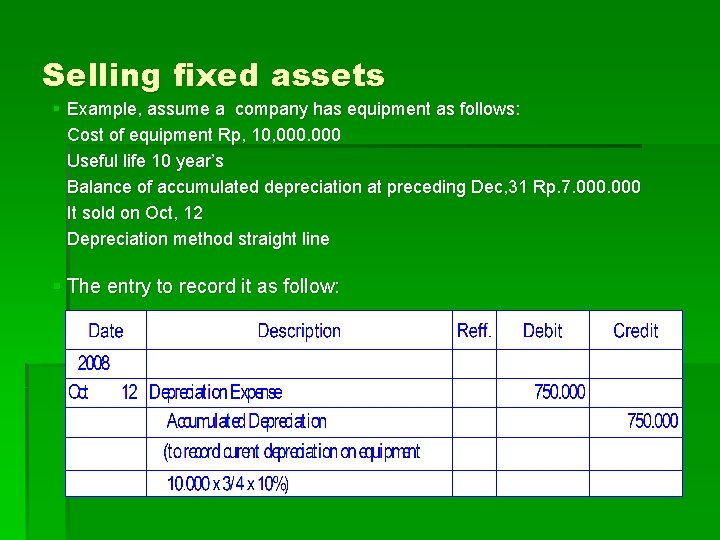
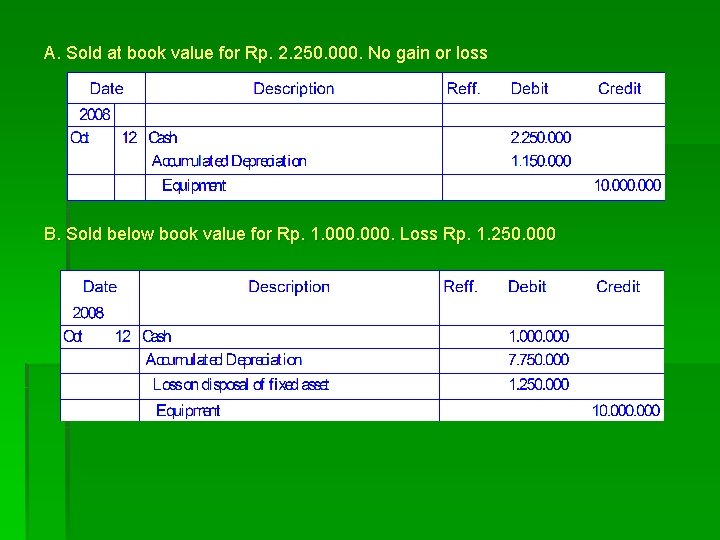
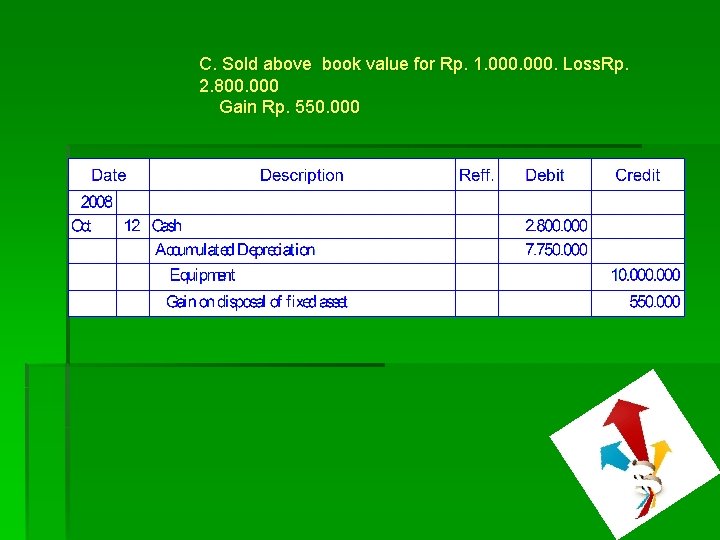
Selling fixed assets § Example, assume a company has equipment as follows: Cost of equipment Rp, 10, 000 Useful life 10 year’s Balance of accumulated depreciation at preceding Dec, 31 Rp. 7. 000 It sold on Oct, 12 Depreciation method straight line § The entry to record it as follow:
A. Sold at book value for Rp. 2. 250. 000. No gain or loss B. Sold below book value for Rp. 1. 000. Loss Rp. 1. 250. 000
C. Sold above book value for Rp. 1. 000. Loss. Rp. 2. 800. 000 Gain Rp. 550. 000
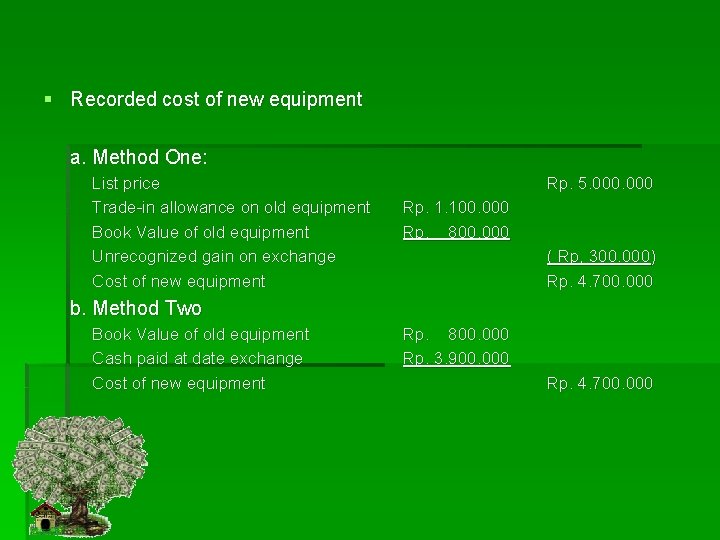
Exchanging Similar Assets § It is old equipment traded in for new equipment having similar use. § The cost recorded for the new asset can be determined in either of two types ways: 1. Cost of new asset = List price of new asset – unrecognized gain or 2. Cost of new asset = cash given (or liability assumed) + Book value of old asset
Continue § Illustration § Assume the folllowing exchange: Book value old equipment Rp. 14. 000 List price of new equipment Rp. 50. 000 A trade in allowance of the old equipment Rp. 15. 000 Similar equipment acquired (new) List price 5. 000 Trade-in allowance on old equipment 1. 100. 000 Cash paid at June, 19
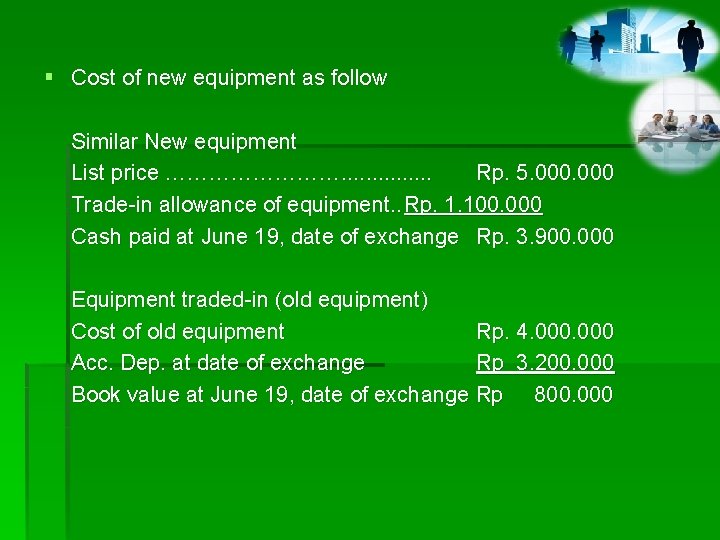
§ Cost of new equipment as follow Similar New equipment List price …………. . . . Rp. 5. 000 Trade-in allowance of equipment. . Rp. 1. 100. 000 Cash paid at June 19, date of exchange Rp. 3. 900. 000 Equipment traded-in (old equipment) Cost of old equipment Rp. 4. 000 Acc. Dep. at date of exchange Rp 3. 200. 000 Book value at June 19, date of exchange Rp 800. 000
§ Recorded cost of new equipment a. Method One: List price Trade-in allowance on old equipment Book Value of old equipment Unrecognized gain on exchange Cost of new equipment Rp. 5. 000 Rp. 1. 100. 000 Rp. 800. 000 ( Rp, 300. 000) Rp. 4. 700. 000 b. Method Two Book Value of old equipment Cash paid at date exchange Cost of new equipment Rp. 800. 000 Rp. 3. 900. 000 Rp. 4. 700. 000
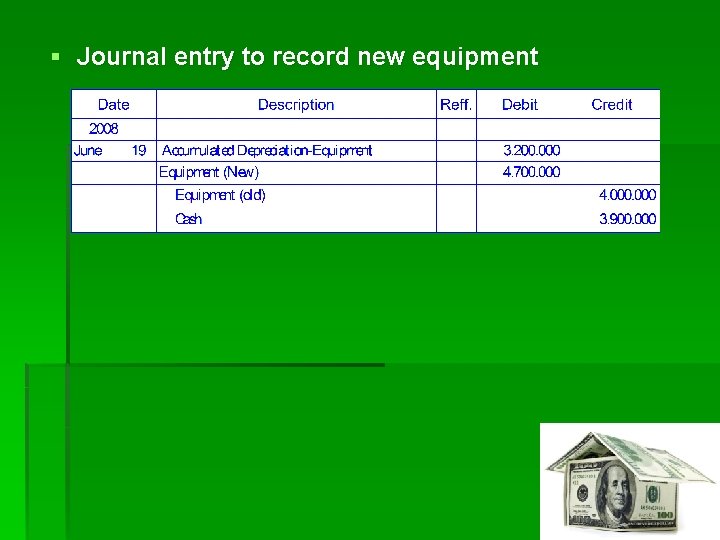
§ Journal entry to record new equipment
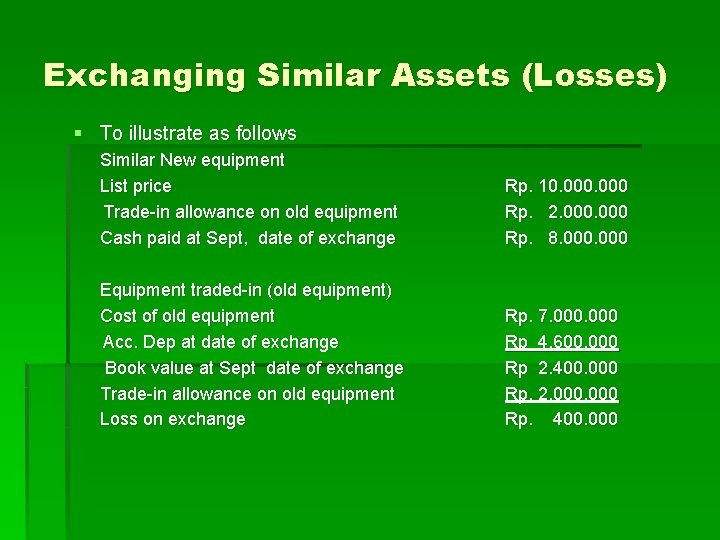
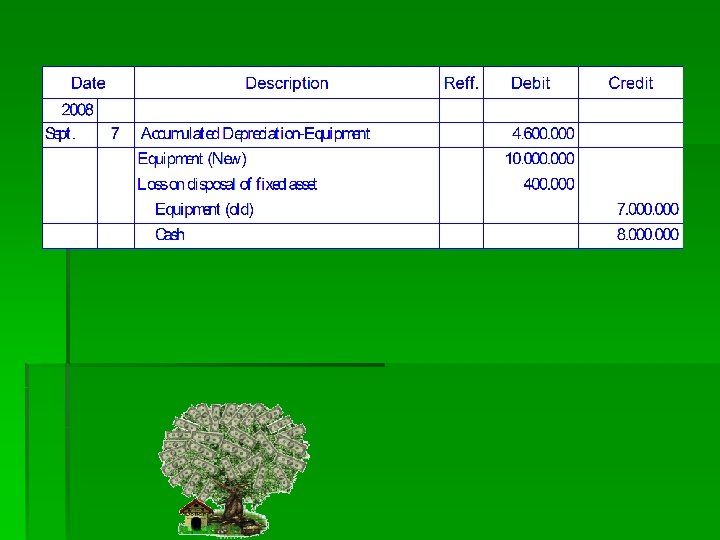
Exchanging Similar Assets (Losses) § To illustrate as follows Similar New equipment List price Trade-in allowance on old equipment Cash paid at Sept, date of exchange Rp. 10. 000 Rp. 2. 000 Rp. 8. 000 Equipment traded-in (old equipment) Cost of old equipment Acc. Dep at date of exchange Book value at Sept date of exchange Trade-in allowance on old equipment Loss on exchange Rp. 7. 000 Rp 4. 600. 000 Rp 2. 400. 000 Rp. 2. 000 Rp. 400. 000