
Financial Statements Analysis 6 1 3 1 Dr
- Slides: 42
Financial Statements Analysis 6 -1 3 -1 Dr. Mazharul Islam
Learning objectives 6 -2 3 -2 u Identify the ways that firms obtain and use cash as reported in the Cash Flow Statement. u Calculate and interpret key financial ratios. u Discuss the Du Pont identity as a method of financial analysis. u Understand the use of financial information for comparative purposes. u Outline the problems associated with using financial ratios. Dr. Mazharul Islam
Sources and Uses of Cash u At the most fundamental level, firms do two things: generate cash and spend cash. u Cash is generated by selling a product or service, asset or security. u Cash is spent by paying for materials and labor to produce a product or service and by purchasing assets. 6 -3 3 -3 Dr. Mazharul Islam
Sources and Uses of Cash u Activities that bring in cash are called sources of cash. u Activities that involve spending cash are called uses (or applications) of cash. u An increase in an asset account or a decrease in a liability or equity account is a use of cash. u A decrease in an asset account or an increase in a liability or equity account is a source of cash. 6 -4 3 -1 Dr. Mazharul Islam
Financial Ratio Analysis u A Financial ratios is an index that relates two accounting numbers and is obtained by dividing one number by the other. u Used to compare and investigate relationships between different pieces of financial information, either over time or between companies. Types of Comparisons: Internal Comparisons and External Comparisons u Ratios eliminate the size problem. 6 -5 3 -1 Dr. Mazharul Islam
Ratio Analysis: Questions to Consider for Each Ratio u How is it computed? u What is it intended to measure, and why might we be interested? u What is the unit of measurement? u What might a high or low value be telling us? How might such values be misleading? u How could this measure be improved? 6 -6 3 -1 Dr. Mazharul Islam
Categories of Financial Ratios u. Liquidity Ratios u. Leverage ratios (Capital Structure Ratios) u. Profitability ratios u. Valuation ratios u. Turnover Ratios 6 -7 3 -1 Dr. Mazharul Islam
Liquidity Ratios u Current Ratio u Quick Ratio u Profit before depreciation and amortization to current liabilities (PDACL) u Operating cash flow to current liabilities (OCFCL) u Cash balance to total liabilities (CBTL) 6 -8 3 -1 Dr. Mazharul Islam
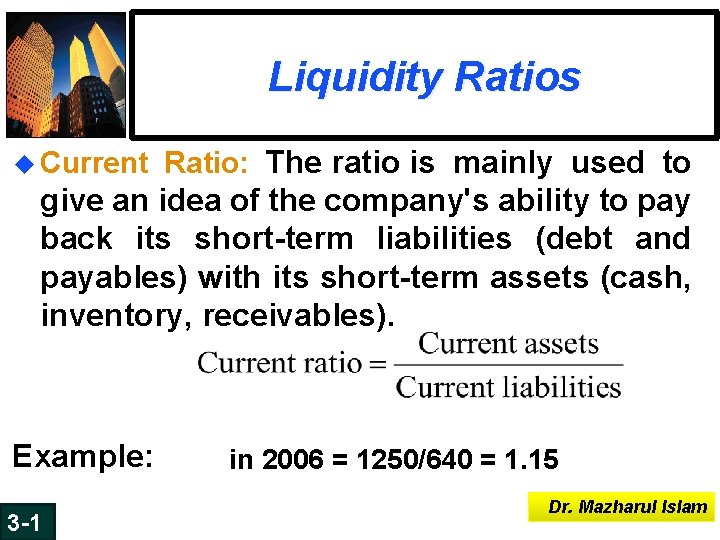
Liquidity Ratios u Current Ratio: The ratio is mainly used to give an idea of the company's ability to pay back its short-term liabilities (debt and payables) with its short-term assets (cash, inventory, receivables). Example: 6 -9 3 -1 in 2006 = 1250/640 = 1. 15 Dr. Mazharul Islam
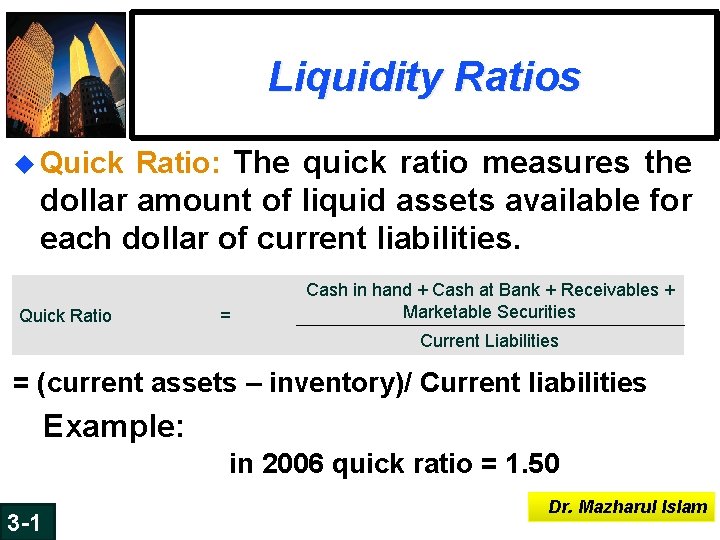
Liquidity Ratios u Quick Ratio: The quick ratio measures the dollar amount of liquid assets available for each dollar of current liabilities. Quick Ratio = Cash in hand + Cash at Bank + Receivables + Marketable Securities Current Liabilities = (current assets – inventory)/ Current liabilities Example: in 2006 quick ratio = 1. 50 6 -10 3 -1 Dr. Mazharul Islam
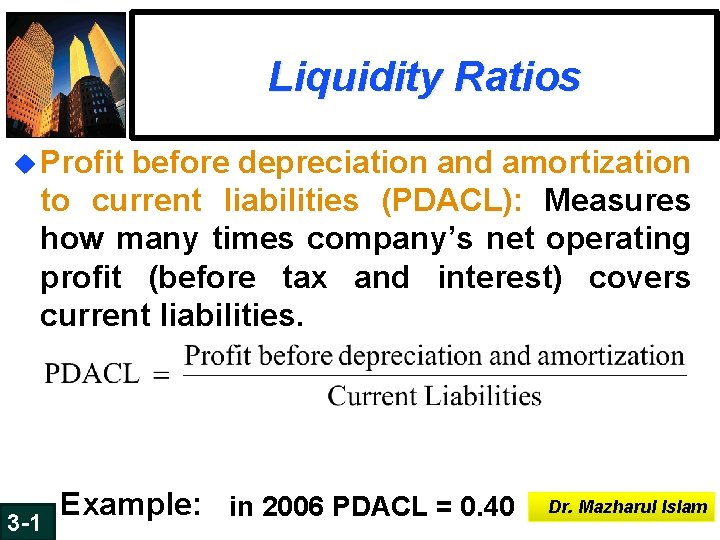
Liquidity Ratios u Profit before depreciation and amortization to current liabilities (PDACL): Measures how many times company’s net operating profit (before tax and interest) covers current liabilities. 6 -11 3 -1 Example: in 2006 PDACL = 0. 40 Dr. Mazharul Islam
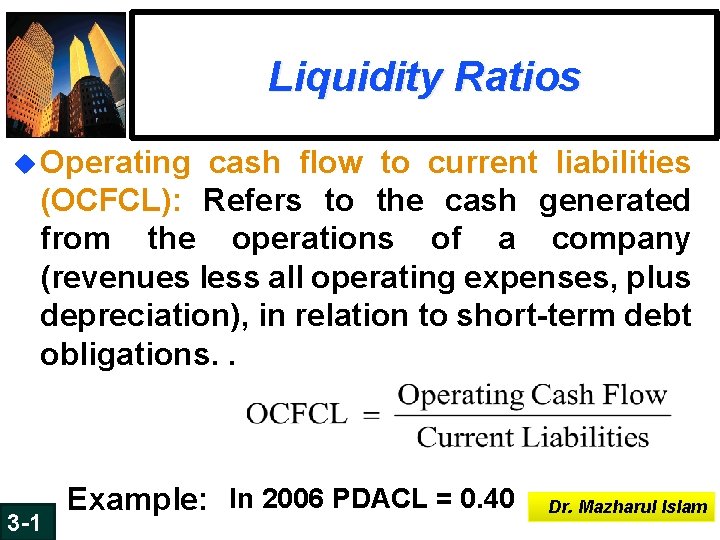
Liquidity Ratios u Operating cash flow to current liabilities (OCFCL): Refers to the cash generated from the operations of a company (revenues less all operating expenses, plus depreciation), in relation to short-term debt obligations. . 6 -12 3 -1 Example: In 2006 PDACL = 0. 40 Dr. Mazharul Islam
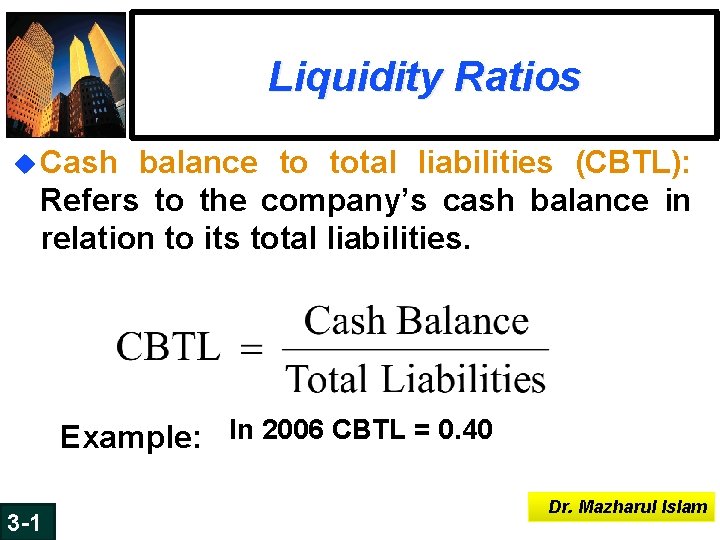
Liquidity Ratios u Cash balance to total liabilities (CBTL): Refers to the company’s cash balance in relation to its total liabilities. Example: In 2006 CBTL = 0. 40 6 -13 3 -1 Dr. Mazharul Islam
Leverage (Capital Structure) Ratios u Debt to equity ratio (DE ratio) u Total liabilities to total tangible assets (TLTAI) u Interest cover ratio u Net debt to equity ratio u Equity multiplier 6 -14 3 -1 Dr. Mazharul Islam
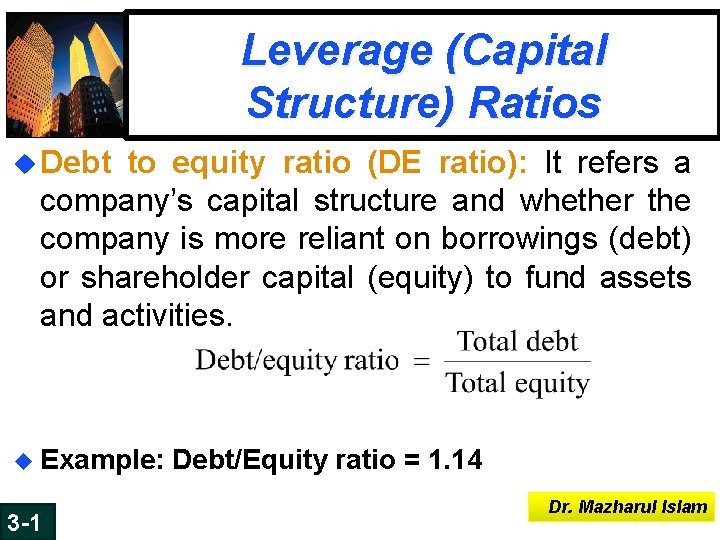
Leverage (Capital Structure) Ratios u Debt to equity ratio (DE ratio): It refers a company’s capital structure and whether the company is more reliant on borrowings (debt) or shareholder capital (equity) to fund assets and activities. u Example: Debt/Equity ratio = 1. 14 6 -15 3 -1 Dr. Mazharul Islam
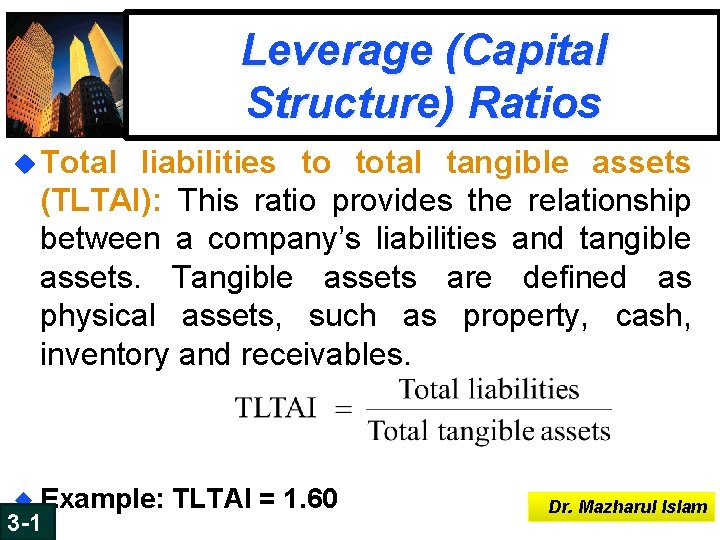
Leverage (Capital Structure) Ratios u Total liabilities to total tangible assets (TLTAI): This ratio provides the relationship between a company’s liabilities and tangible assets. Tangible assets are defined as physical assets, such as property, cash, inventory and receivables. u Example: TLTAI = 1. 60 6 -16 3 -1 Dr. Mazharul Islam
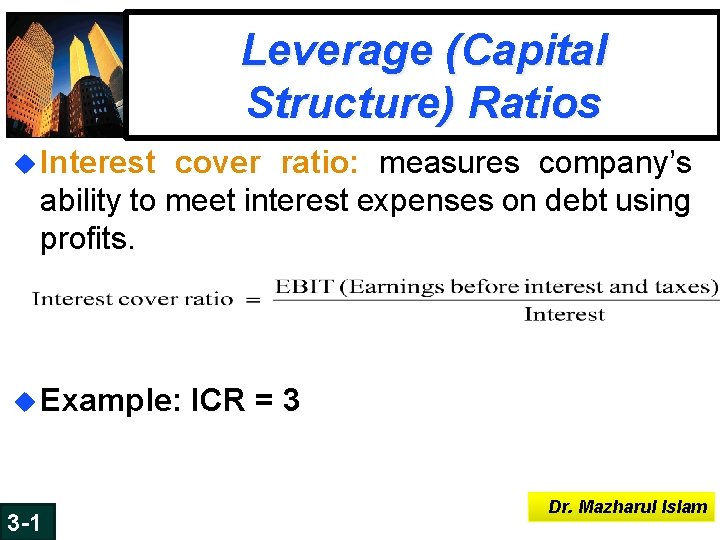
Leverage (Capital Structure) Ratios u Interest cover ratio: measures company’s ability to meet interest expenses on debt using profits. u Example: ICR = 3 6 -17 3 -1 Dr. Mazharul Islam
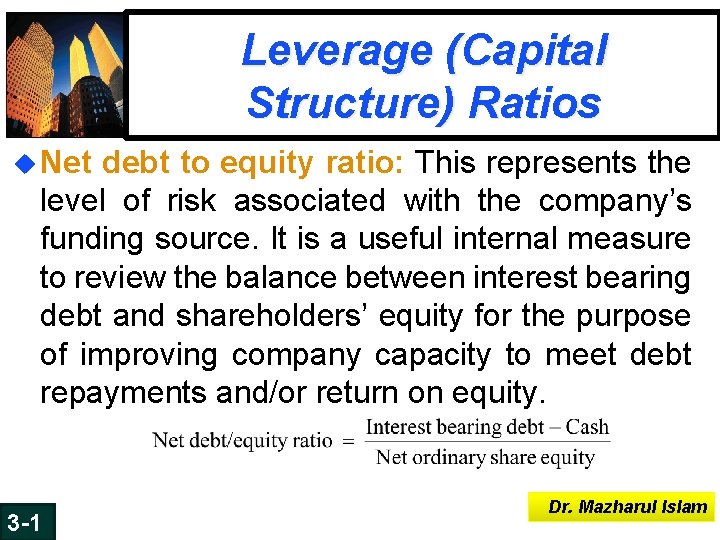
Leverage (Capital Structure) Ratios u Net debt to equity ratio: This represents the level of risk associated with the company’s funding source. It is a useful internal measure to review the balance between interest bearing debt and shareholders’ equity for the purpose of improving company capacity to meet debt repayments and/or return on equity. 6 -18 3 -1 Dr. Mazharul Islam
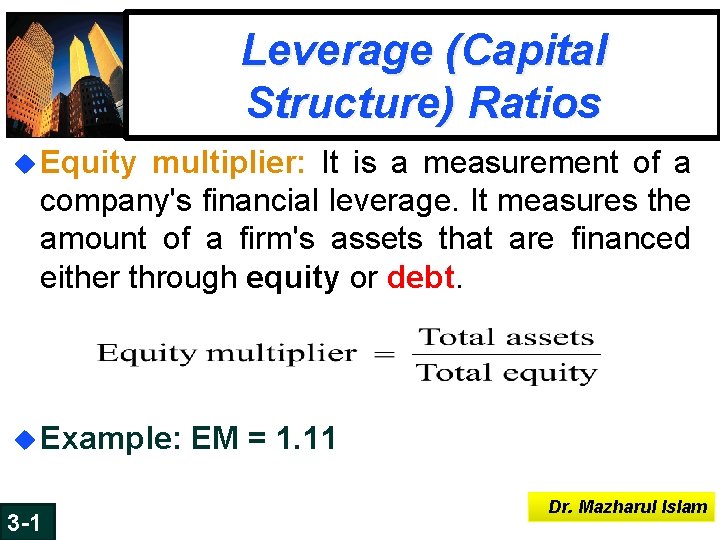
Leverage (Capital Structure) Ratios u Equity multiplier: It is a measurement of a company's financial leverage. It measures the amount of a firm's assets that are financed either through equity or debt. u Example: EM = 1. 11 6 -19 3 -1 Dr. Mazharul Islam
Profitability Ratios u Earnings per share (EPS ) u Gross profit margin u Net profit margin u Return on assets (ROA ) u Return on equity (ROE ) 6 -20 3 -1 Dr. Mazharul Islam
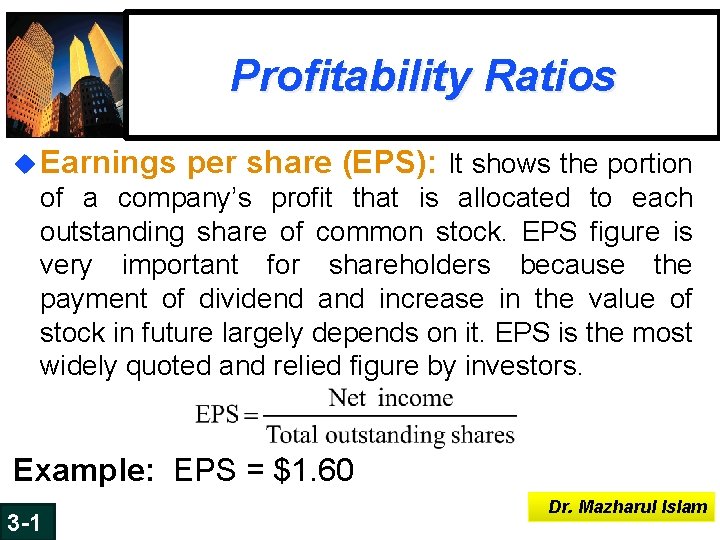
Profitability Ratios u Earnings per share (EPS): It shows the portion of a company’s profit that is allocated to each outstanding share of common stock. EPS figure is very important for shareholders because the payment of dividend and increase in the value of stock in future largely depends on it. EPS is the most widely quoted and relied figure by investors. Example: EPS = $1. 60 6 -21 3 -1 Dr. Mazharul Islam
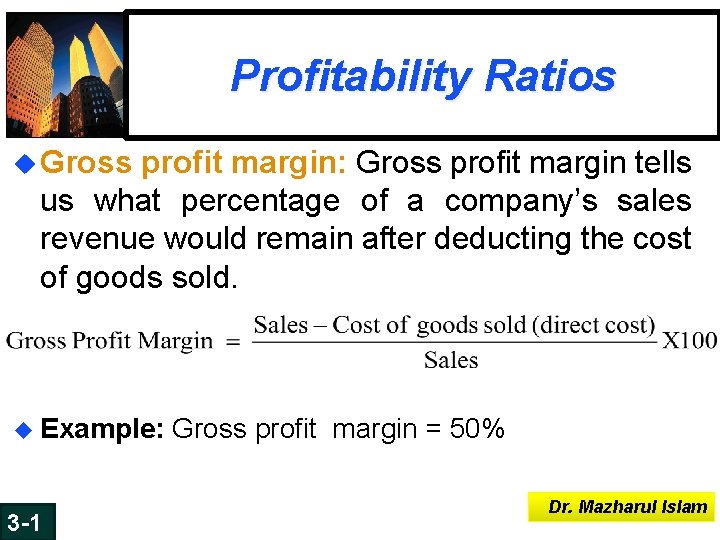
Profitability Ratios u Gross profit margin: Gross profit margin tells us what percentage of a company’s sales revenue would remain after deducting the cost of goods sold. u Example: Gross profit margin = 50% 6 -22 3 -1 Dr. Mazharul Islam
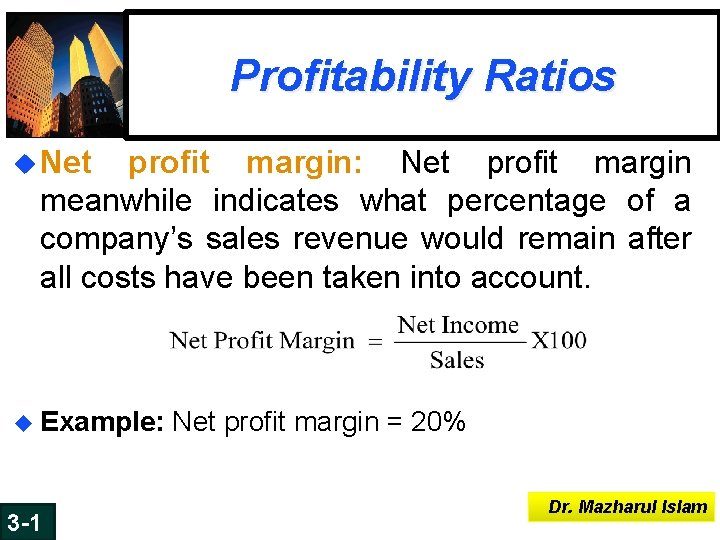
Profitability Ratios u Net profit margin: Net profit margin meanwhile indicates what percentage of a company’s sales revenue would remain after all costs have been taken into account. u Example: Net profit margin = 20% 6 -23 3 -1 Dr. Mazharul Islam
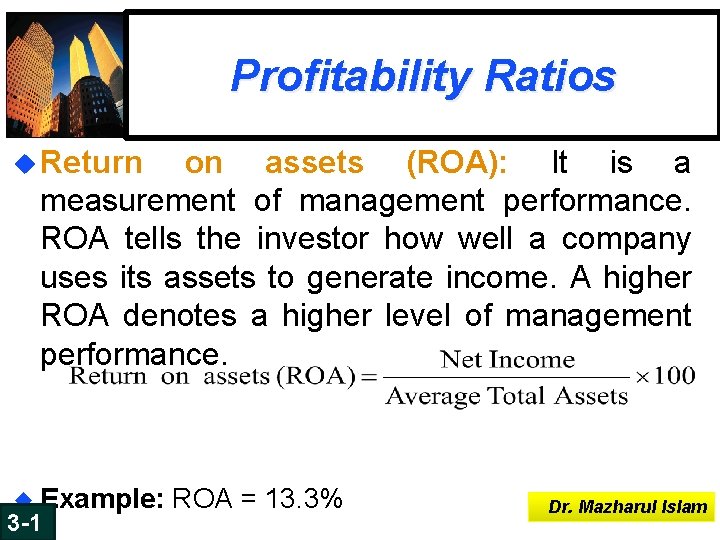
Profitability Ratios u Return on assets (ROA): It is a measurement of management performance. ROA tells the investor how well a company uses its assets to generate income. A higher ROA denotes a higher level of management performance. u Example: ROA = 13. 3% 6 -24 3 -1 Dr. Mazharul Islam
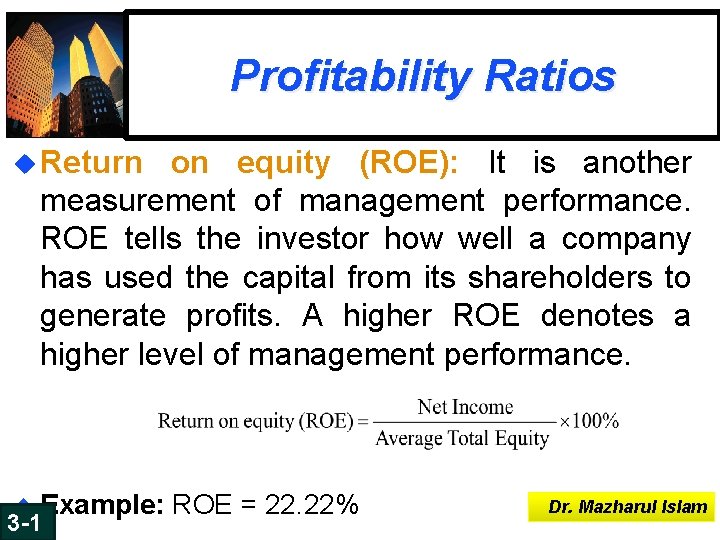
Profitability Ratios u Return on equity (ROE): It is another measurement of management performance. ROE tells the investor how well a company has used the capital from its shareholders to generate profits. A higher ROE denotes a higher level of management performance. u Example: ROE = 22. 22% 6 -25 3 -1 Dr. Mazharul Islam
Valuation Ratios u. Price to earnings ratio (PE) u. Price/earnings to growth ratio (PEG) u. Dividend yield 6 -26 3 -1 Dr. Mazharul Islam
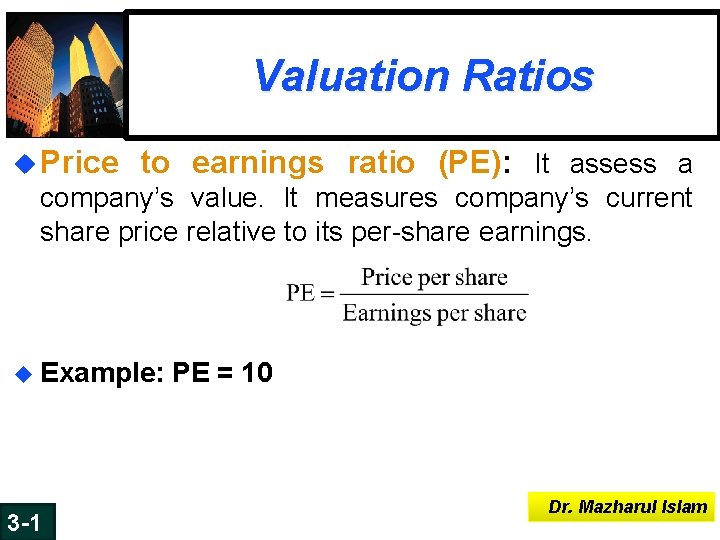
Valuation Ratios u Price to earnings ratio (PE): It assess a company’s value. It measures company’s current share price relative to its per-share earnings. u Example: PE = 10 6 -27 3 -1 Dr. Mazharul Islam
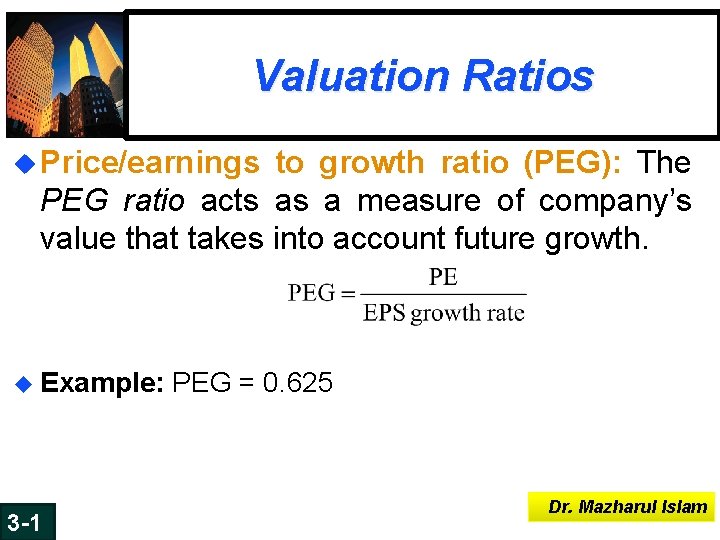
Valuation Ratios u Price/earnings to growth ratio (PEG): The PEG ratio acts as a measure of company’s value that takes into account future growth. u Example: PEG = 0. 625 6 -28 3 -1 Dr. Mazharul Islam
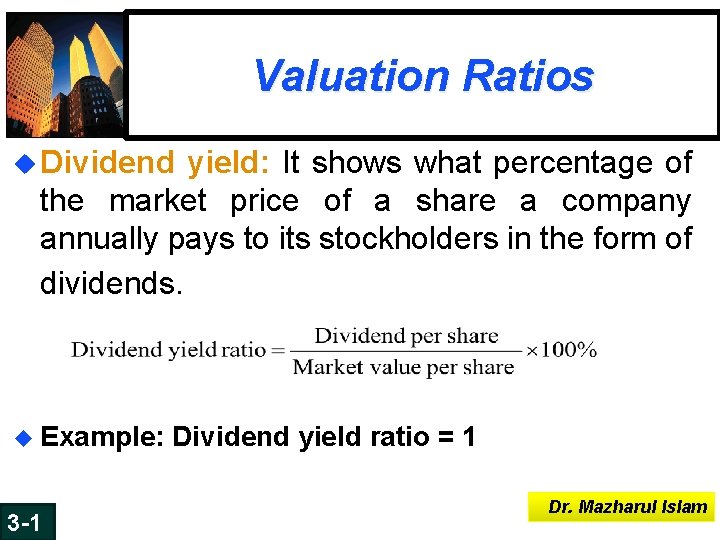
Valuation Ratios u Dividend yield: It shows what percentage of the market price of a share a company annually pays to its stockholders in the form of dividends. u Example: Dividend yield ratio = 1 6 -29 3 -1 Dr. Mazharul Islam
Turnover Ratios u. Inventory turnover u. Fixed asset turnover u. Total asset turnover u. Day’s sales in inventory u. Receivables turnover u. Day’s sales in receivable 6 -30 3 -1 Dr. Mazharul Islam
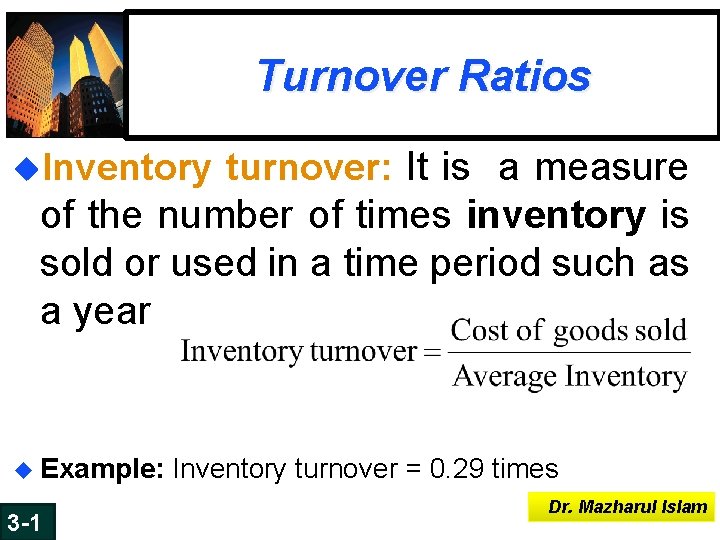
Turnover Ratios u. Inventory turnover: It is a measure of the number of times inventory is sold or used in a time period such as a year u Example: Inventory turnover = 0. 29 times 6 -31 3 -1 Dr. Mazharul Islam
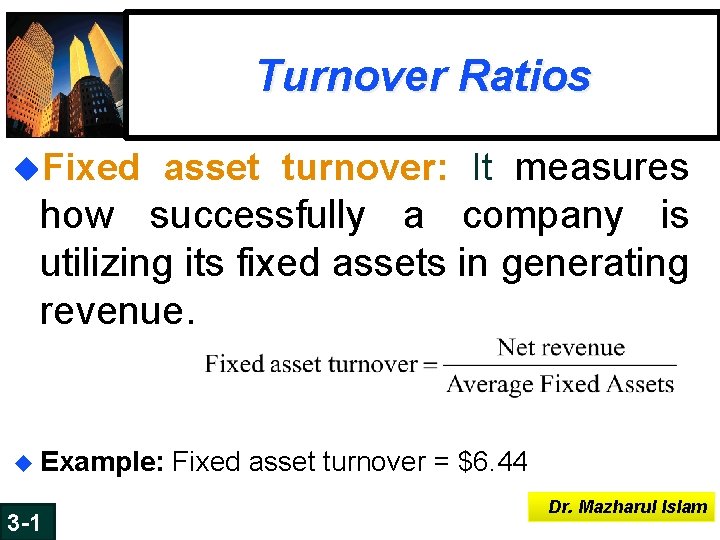
Turnover Ratios u. Fixed asset turnover: It measures how successfully a company is utilizing its fixed assets in generating revenue. u Example: Fixed asset turnover = $6. 44 6 -32 3 -1 Dr. Mazharul Islam
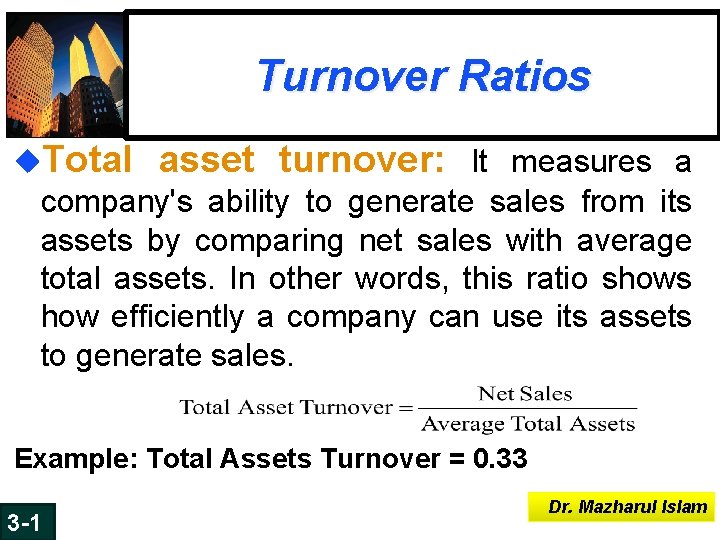
Turnover Ratios u. Total asset turnover: It measures a company's ability to generate sales from its assets by comparing net sales with average total assets. In other words, this ratio shows how efficiently a company can use its assets to generate sales. Example: Total Assets Turnover = 0. 33 6 -33 3 -1 Dr. Mazharul Islam
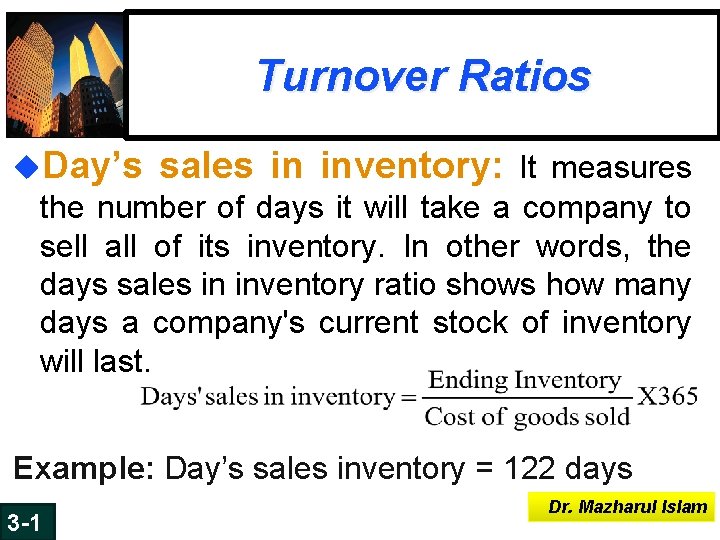
Turnover Ratios u. Day’s sales in inventory: It measures the number of days it will take a company to sell all of its inventory. In other words, the days sales in inventory ratio shows how many days a company's current stock of inventory will last. Example: Day’s sales inventory = 122 days 6 -34 3 -1 Dr. Mazharul Islam
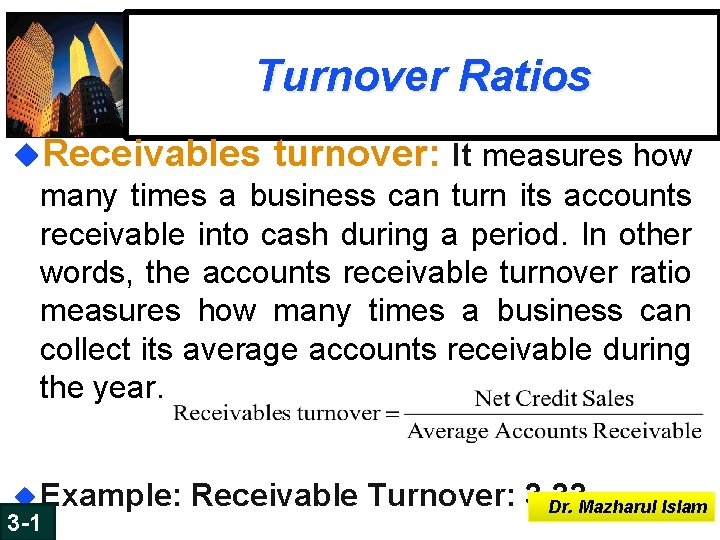
Turnover Ratios u. Receivables turnover: It measures how many times a business can turn its accounts receivable into cash during a period. In other words, the accounts receivable turnover ratio measures how many times a business can collect its average accounts receivable during the year. u Example: Receivable Turnover: 3. 33 Dr. Mazharul Islam 6 -35 3 -1
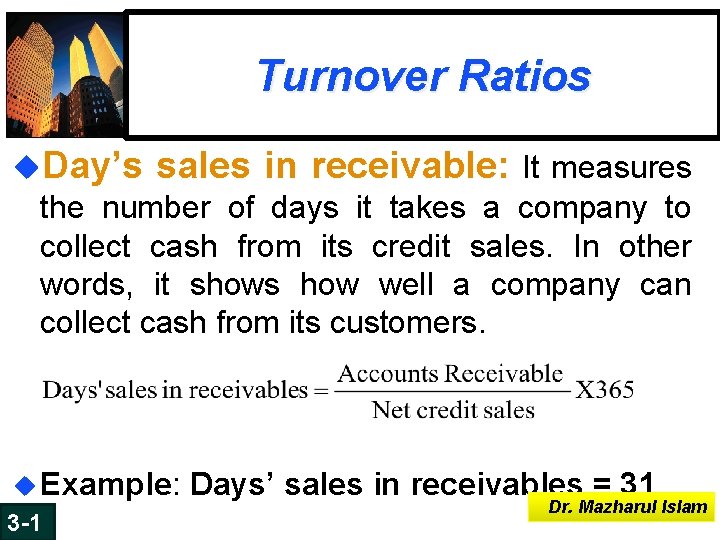
Turnover Ratios u. Day’s sales in receivable: It measures the number of days it takes a company to collect cash from its credit sales. In other words, it shows how well a company can collect cash from its customers. u Example: Days’ sales in receivables = 31 Dr. Mazharul Islam 6 -36 3 -1
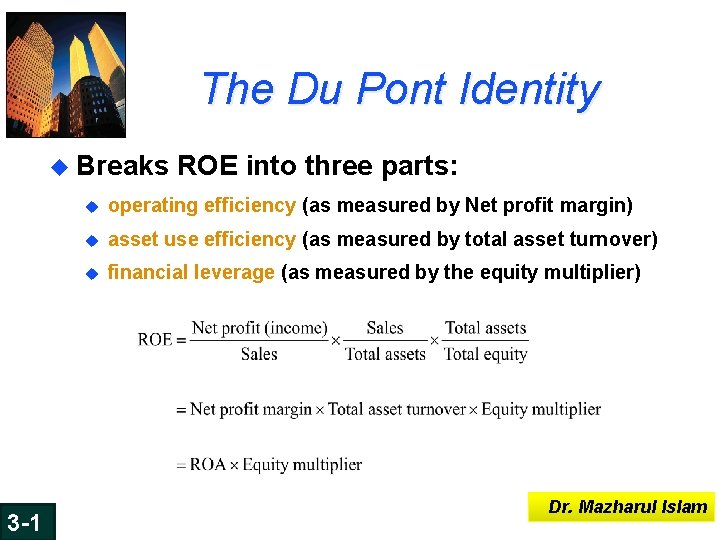
The Du Pont Identity u Breaks ROE into three parts: 6 -37 3 -1 u operating efficiency (as measured by Net profit margin) u asset use efficiency (as measured by total asset turnover) u financial leverage (as measured by the equity multiplier) Dr. Mazharul Islam
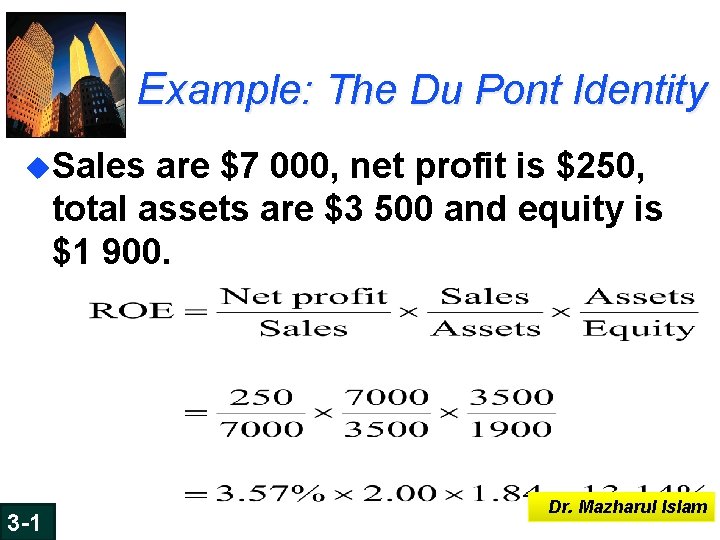
Example: The Du Pont Identity u. Sales are $7 000, net profit is $250, total assets are $3 500 and equity is $1 900. 6 -38 3 -1 Dr. Mazharul Islam
Why Evaluate Financial Statements? u Internal uses: u performance evaluation u planning for the future u External uses: u evaluation by outside parties u evaluation of main competitors u identifying potential takeover targets 6 -39 3 -1 Dr. Mazharul Islam
Benchmarks for Comparison u Ratios are most useful when compared to a benchmark. u Time-trend analysis—examine how a particular ratio(s) has performed historically. u Peer group analysis—using similar 6 -40 3 -1 firms (competitors) for comparison of results. Dr. Mazharul Islam
Problems with Financial Statement Analysis u No underlying theory to identify correct ratios to use or appropriate benchmarks. u Benchmarking is difficult for diversified firms. u Firms may use different accounting procedures. u Firms may have different recording periods. u One-off events can severely affect financial performance. 6 -41 3 -1 Dr. Mazharul Islam
Summary and Conclusions u Activities that bring in cash are called ‘sources of cash’, and activities that involve spending cash are called ‘uses of cash’. u A Cash Flow Statement summarises sources and uses of cash over a specified period. u Financial ratios are grouped together into five main categories: Liquidity, Capital Structure, Valuation, Profitability, and Turnover. u Ratios are most useful when compared to a benchmark (e. g. time-trend and peer group analysis). u Problems can arise in using financial statements. 6 -42 3 -1 Dr. Mazharul Islam