
FINANCIAL LITERACY PROGRAM BUILDING SOUND FINANCIAL MANAGEMENT SKILLS
FINANCIAL LITERACY PROGRAM BUILDING SOUND FINANCIAL MANAGEMENT SKILLS MODULE 8 Wealth Stage Plans Charles Nowochin Oct 2020
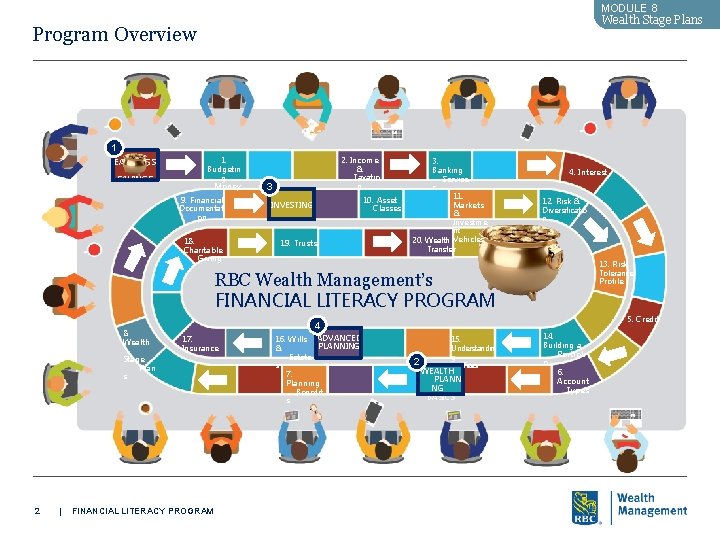
MODULE 8 Wealth. Stage. Plans Program Overview 1 EARNINGS & SAVINGS 1. Budgetin g Money 9. Financial Documentati on 18. Charitable Giving 2. Income & Taxatio n 3 10. Asset Classes INVESTING 19. Trusts 3. Banking Service s 11. Markets & Investme nt 20. Wealth Vehicles Transfer 4. Interest 12. Risk & Diversificatio n 13. Risk Tolerance Profile RBC Wealth Management’s FINANCIAL LITERACY PROGRAM 8. Wealth 17. Insurance Stage Plan s 2 5. Credit 4 | FINANCIAL LITERACY PROGRAM 16. Wills ADVANCED PLANNING & Estate s 7. Planning Benefit s 15. Understandin g 2 Fees WEALTH PLANNI NG BASICS 14. Building a Portfoli o 6. Account Types
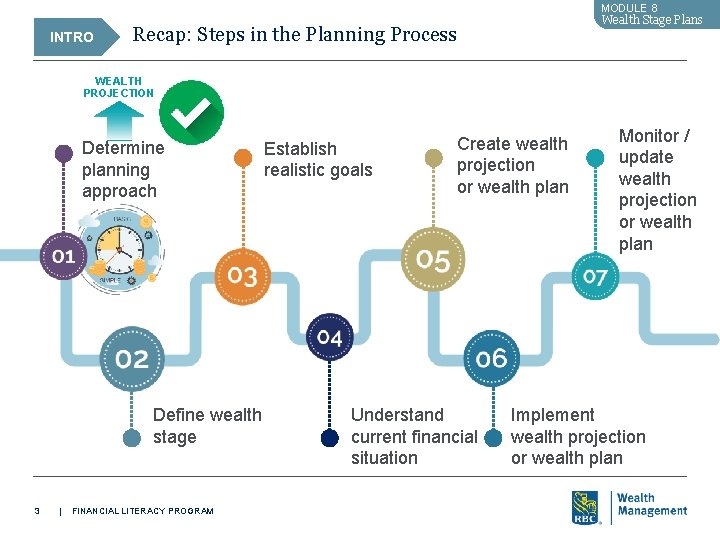
MODULE 8 INTRO Wealth. Stage. Plans Recap: Steps in the Planning Process WEALTH PROJECTION Determine planning approach Establish realistic goals Define wealth stage 3 | FINANCIAL LITERACY PROGRAM Create wealth projection or wealth plan Understand current financial situation Monitor / update wealth projection or wealth plan Implement wealth projection or wealth plan
MODULE 8 Wealth. Stage. Plans Today’s Lesson INTRO Meet the Green Family EARLY SAVER Karen Green MID-LIFE Tom & Sally Green ACCUMULATORS 4 PRESERVER/ SPENDER Joan Green SUMMARY Family Recap | FINANCIAL LITERACY PROGRAM
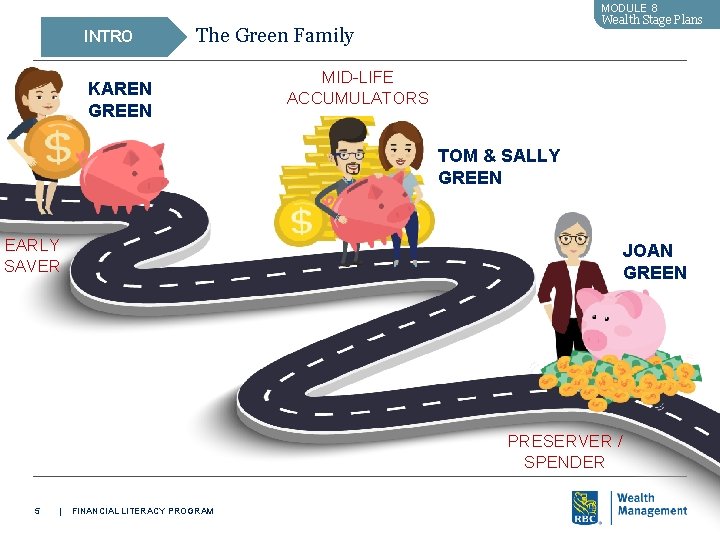
MODULE 8 INTRO Wealth. Stage. Plans The Green Family KAREN GREEN MID-LIFE ACCUMULATORS TOM & SALLY GREEN EARLY SAVER JOAN GREEN PRESERVER / SPENDER 5 | FINANCIAL LITERACY PROGRAM
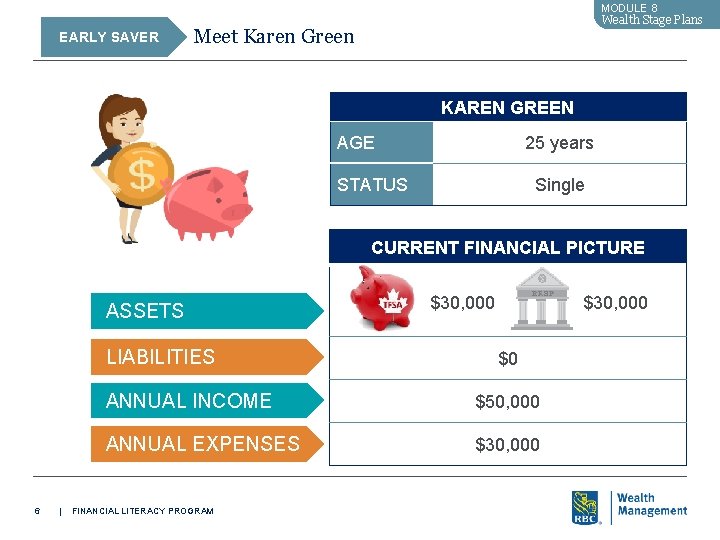
MODULE 8 EARLY SAVER Wealth Stage Plans Meet Karen Green KAREN GREEN AGE 25 years STATUS Single CURRENT FINANCIAL PICTURE ASSETS LIABILITIES 6 $30, 000 $0 ANNUAL INCOME $50, 000 ANNUAL EXPENSES $30, 000 | FINANCIAL LITERACY PROGRAM
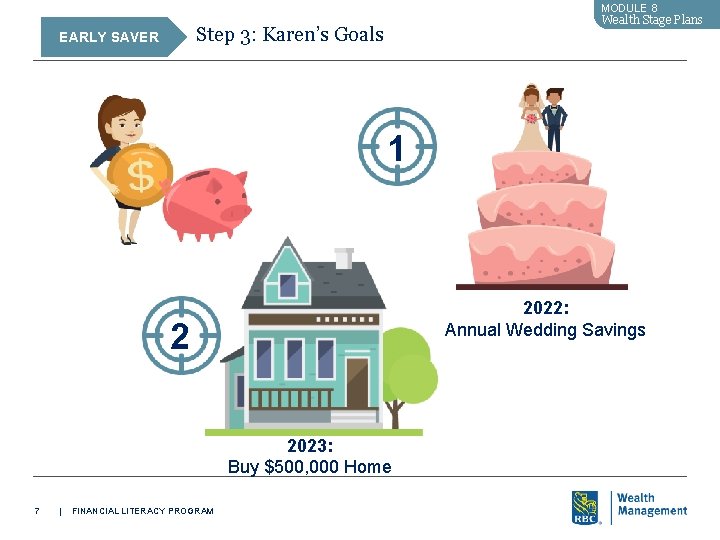
MODULE 8 Wealth Stage Plans Step 3: Karen’s Goals EARLY SAVER 1 2022: Annual Wedding Savings 2 2023: Buy $500, 000 Home 7 | FINANCIAL LITERACY PROGRAM
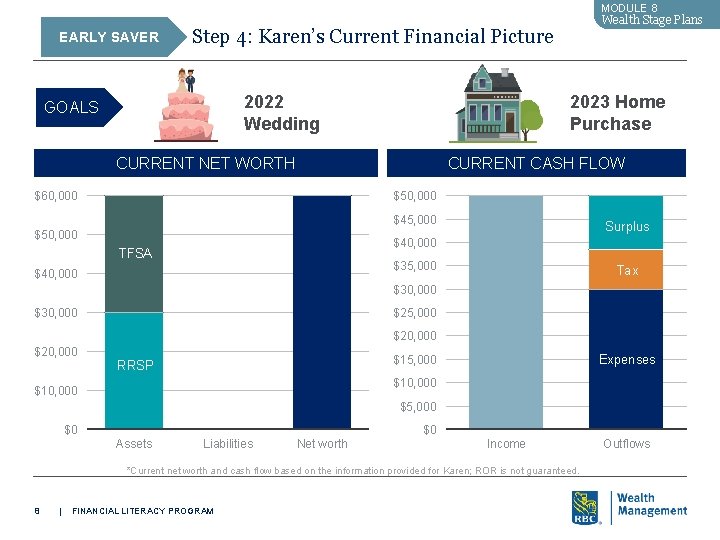
MODULE 8 EARLY SAVER Wealth. Stage. Plans Step 4: Karen’s Current Financial Picture 2023 Home Purchase 2022 Wedding GOALS CURRENT NET WORTH CURRENT CASH FLOW $60, 000 $50, 000 $45, 000 $50, 000 Surplus $40, 000 TFSA $35, 000 $40, 000 Tax $30, 000 $25, 000 $20, 000 Expenses $15, 000 RRSP $10, 000 $5, 000 $0 $0 Assets Liabilities Net worth Income *Current net worth and cash flow based on the information provided for Karen; ROR is not guaranteed. 8 | FINANCIAL LITERACY PROGRAM Outflows
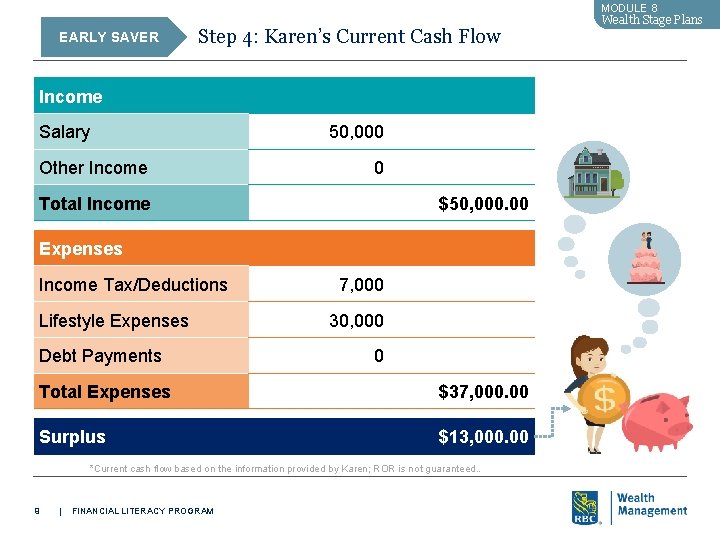
MODULE 8 EARLY SAVER Wealth. Stage. Plans Step 4: Karen’s Current Cash Flow Income Salary 50, 000 Other Income 0 Total Income $50, 000. 00 Expenses 7, 000 30, 000 Debt Payments 0 Total Expenses $37, 000. 00 Surplus $13, 000. 00 Income Tax/Deductions Lifestyle Expenses *Current cash flow based on the information provided by Karen; ROR is not guaranteed. . 9 | FINANCIAL LITERACY PROGRAM
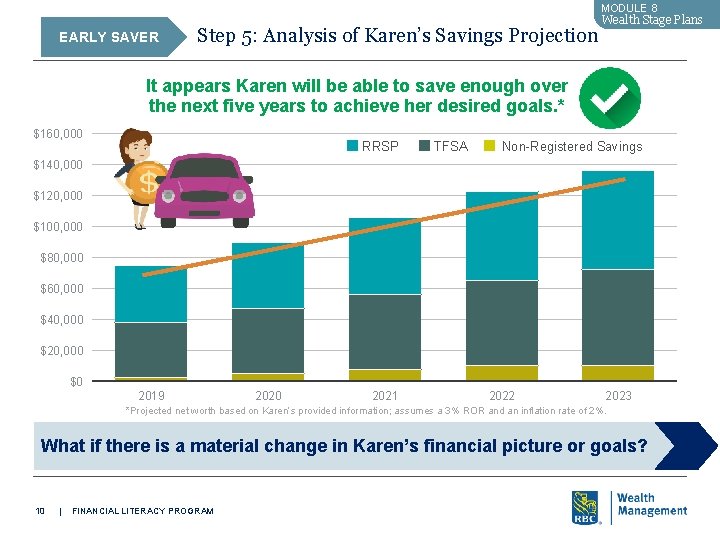
MODULE 8 EARLY SAVER Step 5: Analysis of Karen’s Savings Projection Wealth. Stage. Plans It appears Karen will be able to save enough over the next five years to achieve her desired goals. * $160, 000 RRSP TFSA Non-Registered Savings $140, 000 $120, 000 $100, 000 $80, 000 $60, 000 $40, 000 $20, 000 $0 2019 2020 2021 2022 2023 *Projected net worth based on Karen’s provided information; assumes a 3% ROR and an inflation rate of 2%. What if there is a material change in Karen’s financial picture or goals? 10 | FINANCIAL LITERACY PROGRAM
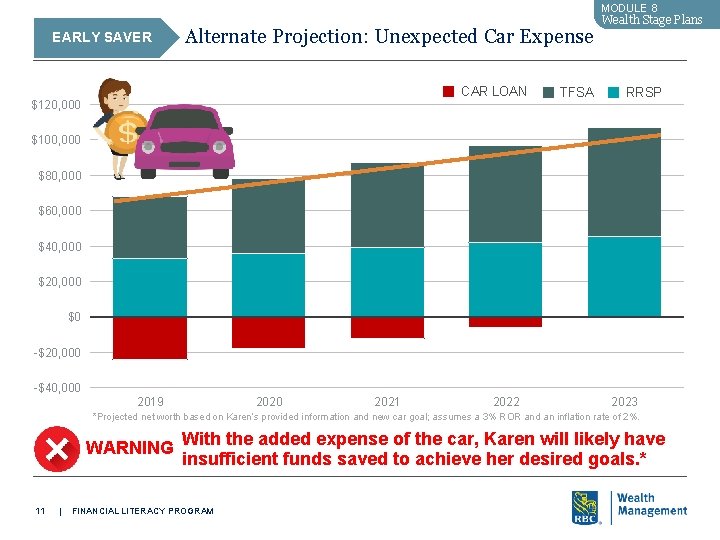
MODULE 8 EARLY SAVER Alternate Projection: Unexpected Car Expense CAR LOAN $120, 000 TFSA Wealth. Stage. Plans RRSP $100, 000 $80, 000 $60, 000 $40, 000 $20, 000 $0 -$20, 000 -$40, 000 2019 2020 2021 2022 2023 *Projected net worth based on Karen’s provided information and new car goal; assumes a 3% ROR and an inflation rate of 2%. WARNING With the added expense of the car, Karen will likely have insufficient funds saved to achieve her desired goals. * 11 | FINANCIAL LITERACY PROGRAM
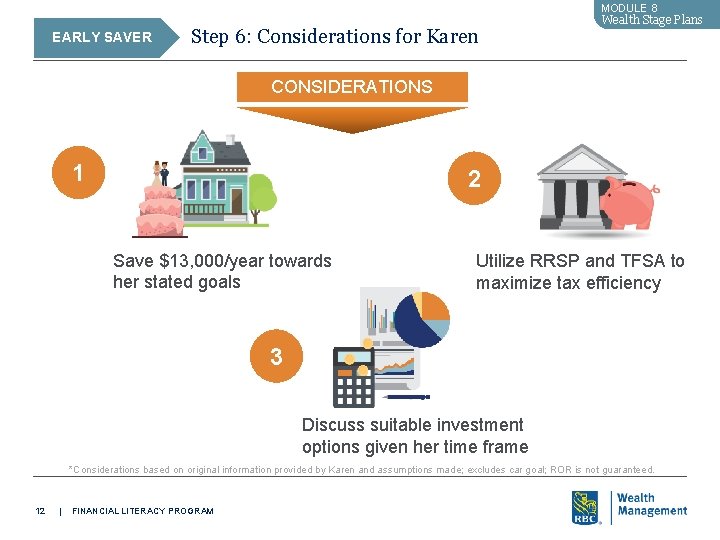
MODULE 8 EARLY SAVER Step 6: Considerations for Karen Wealth. Stage. Plans CONSIDERATIONS 1 2 Save $13, 000/year towards her stated goals Utilize RRSP and TFSA to maximize tax efficiency 3 Discuss suitable investment options given her time frame *Considerations based on original information provided by Karen and assumptions made; excludes car goal; ROR is not guaranteed. 12 | FINANCIAL LITERACY PROGRAM
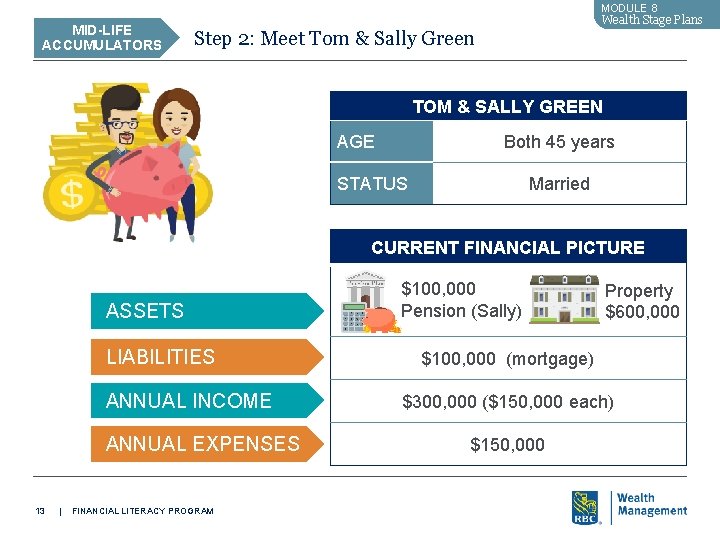
MODULE 8 MID-LIFE ACCUMULATORS Wealth Stage Plans Step 2: Meet Tom & Sally Green TOM & SALLY GREEN AGE Both 45 years STATUS Married CURRENT FINANCIAL PICTURE ASSETS LIABILITIES ANNUAL INCOME ANNUAL EXPENSES 13 | FINANCIAL LITERACY PROGRAM $100, 000 Pension (Sally) Property $600, 000 $100, 000 (mortgage) $300, 000 ($150, 000 each) $150, 000
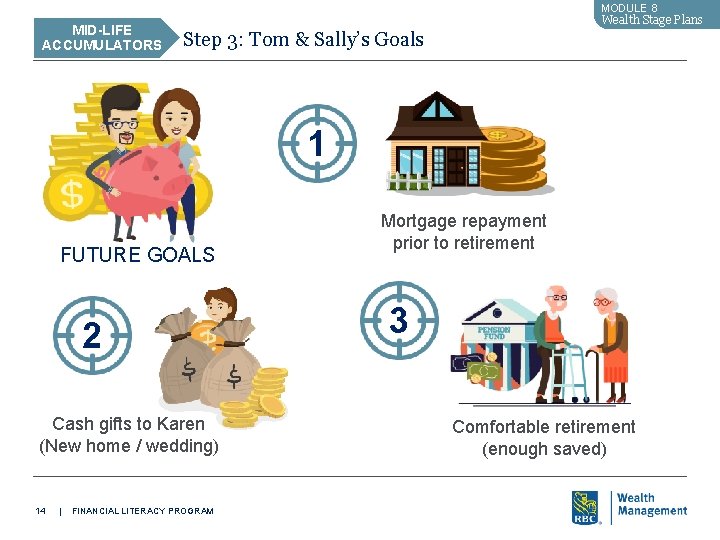
MODULE 8 MID-LIFE ACCUMULATORS Wealth. Stage. Plans Step 3: Tom & Sally’s Goals 1 FUTURE GOALS 2 Cash gifts to Karen (New home / wedding) 14 | FINANCIAL LITERACY PROGRAM Mortgage repayment prior to retirement 3 Comfortable retirement (enough saved)
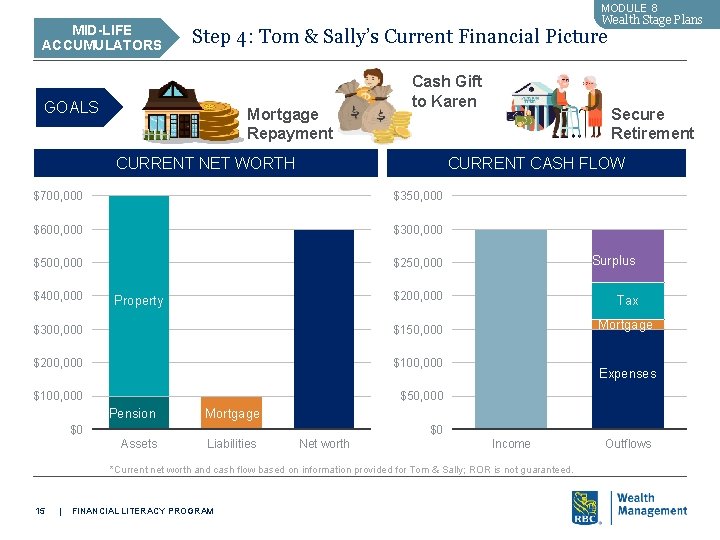
MODULE 8 MID-LIFE ACCUMULATORS Wealth. Stage. Plans Step 4: Tom & Sally’s Current Financial Picture GOALS Mortgage Repayment Cash Gift to Karen CURRENT NET WORTH Secure Retirement CURRENT CASH FLOW $700, 000 $350, 000 $600, 000 $300, 000 $500, 000 $250, 000 Surplus $200, 000 Tax $300, 000 $150, 000 Mortgage $200, 000 $100, 000 $50, 000 $400, 000 Property Pension Expenses Mortgage $0 $0 Assets Liabilities Net worth Income *Current net worth and cash flow based on information provided for Tom & Sally; ROR is not guaranteed. 15 | FINANCIAL LITERACY PROGRAM Outflows
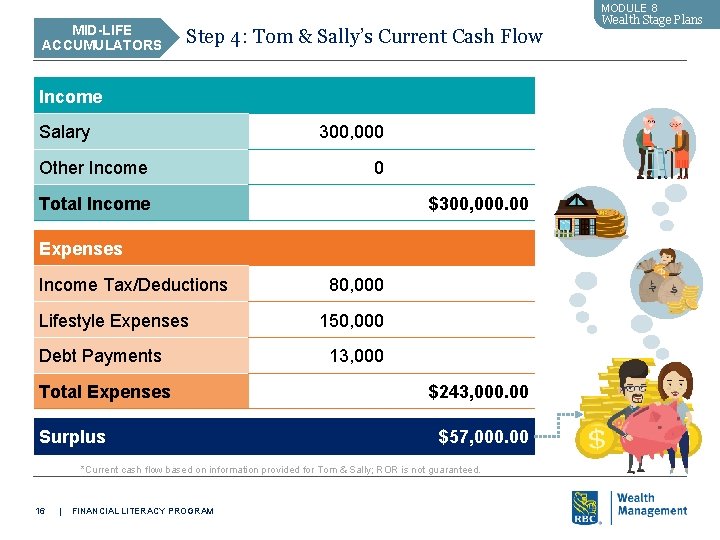
MODULE 8 MID-LIFE ACCUMULATORS Step 4: Tom & Sally’s Current Cash Flow Income Salary 300, 000 Other Income 0 Total Income $300, 000. 00 Expenses 80, 000 150, 000 13, 000 Total Expenses $243, 000. 00 Surplus $57, 000. 00 Income Tax/Deductions Lifestyle Expenses Debt Payments *Current cash flow based on information provided for Tom & Sally; ROR is not guaranteed. 16 | FINANCIAL LITERACY PROGRAM Wealth. Stage. Plans
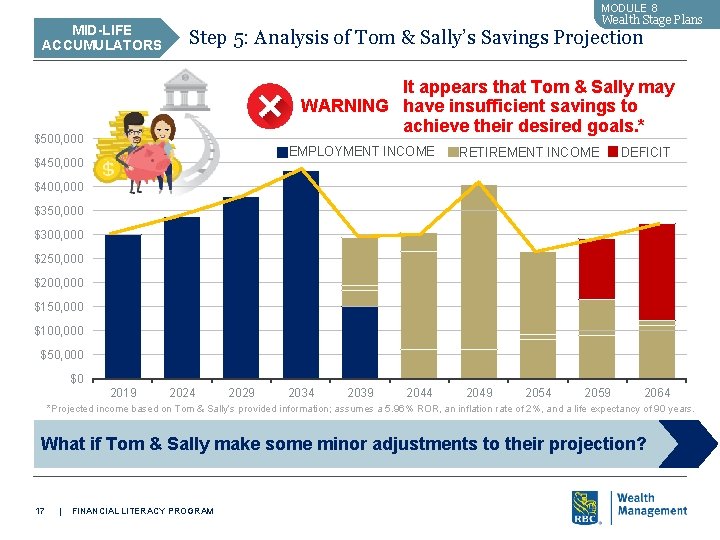
MODULE 8 MID-LIFE ACCUMULATORS Wealth. Stage. Plans Step 5: Analysis of Tom & Sally’s Savings Projection It appears that Tom & Sally may WARNING have insufficient savings to achieve their desired goals. * $500, 000 EMPLOYMENT INCOME $450, 000 RETIREMENT INCOME DEFICIT $400, 000 $350, 000 $300, 000 $250, 000 $200, 000 $150, 000 $100, 000 $50, 000 $0 2019 2024 2029 2034 2039 2044 2049 2054 2059 2064 *Projected income based on Tom & Sally’s provided information; assumes a 5. 96% ROR, an inflation rate of 2%, and a life expectancy of 90 years. What if Tom & Sally make some minor adjustments to their projection? 17 | FINANCIAL LITERACY PROGRAM
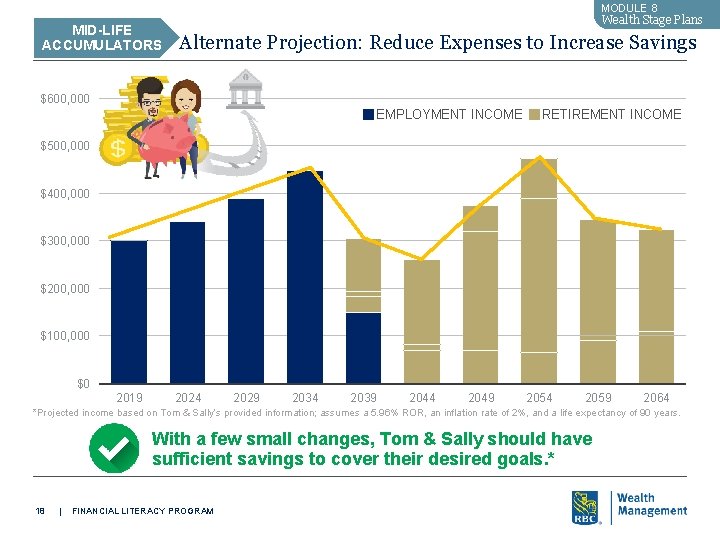
MODULE 8 MID-LIFE ACCUMULATORS Wealth. Stage. Plans Alternate Projection: Reduce Expenses to Increase Savings $600, 000 EMPLOYMENT INCOME RETIREMENT INCOME $500, 000 $400, 000 $300, 000 $200, 000 $100, 000 $0 2019 2024 2029 2034 2039 2044 2049 2054 2059 2064 *Projected income based on Tom & Sally’s provided information; assumes a 5. 96% ROR, an inflation rate of 2%, and a life expectancy of 90 years. With a few small changes, Tom & Sally should have sufficient savings to cover their desired goals. * 18 | FINANCIAL LITERACY PROGRAM
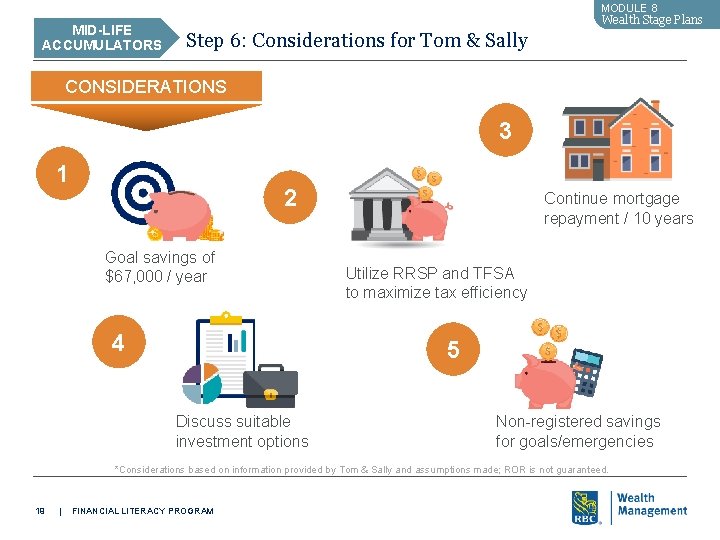
MODULE 8 MID-LIFE ACCUMULATORS Wealth. Stage. Plans Step 6: Considerations for Tom & Sally CONSIDERATIONS 3 1 2 Goal savings of $67, 000 / year 4 Continue mortgage repayment / 10 years Utilize RRSP and TFSA to maximize tax efficiency 5 Discuss suitable investment options Non-registered savings for goals/emergencies *Considerations based on information provided by Tom & Sally and assumptions made; ROR is not guaranteed. 19 | FINANCIAL LITERACY PROGRAM
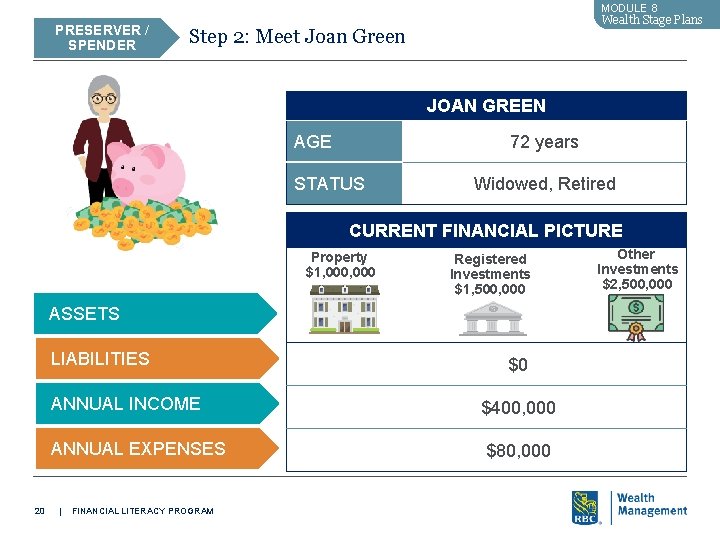
MODULE 8 PRESERVER / SPENDER Wealth. Stage. Plans Step 2: Meet Joan Green JOAN GREEN AGE 72 years STATUS Widowed, Retired CURRENT FINANCIAL PICTURE Property $1, 000 Registered Investments $1, 500, 000 ASSETS LIABILITIES 20 $0 ANNUAL INCOME $400, 000 ANNUAL EXPENSES $80, 000 | FINANCIAL LITERACY PROGRAM Other Investments $2, 500, 000
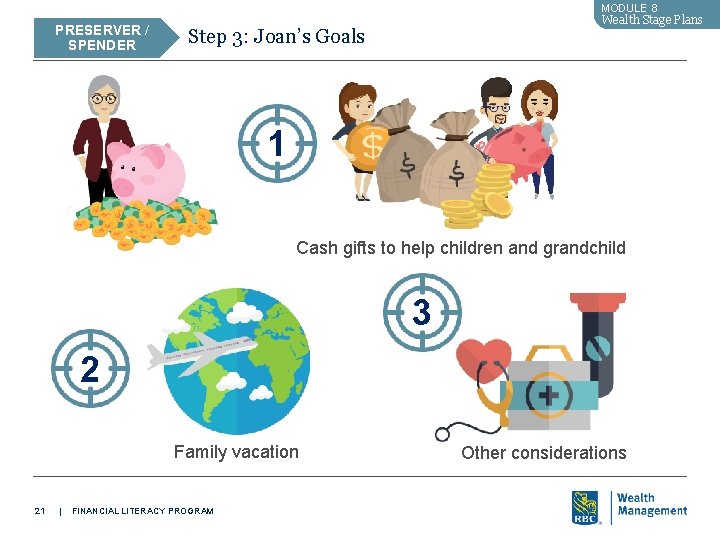
MODULE 8 PRESERVER / SPENDER Wealth. Stage. Plans Step 3: Joan’s Goals 1 Cash gifts to help children and grandchild 3 2 Family vacation 21 | FINANCIAL LITERACY PROGRAM Other considerations
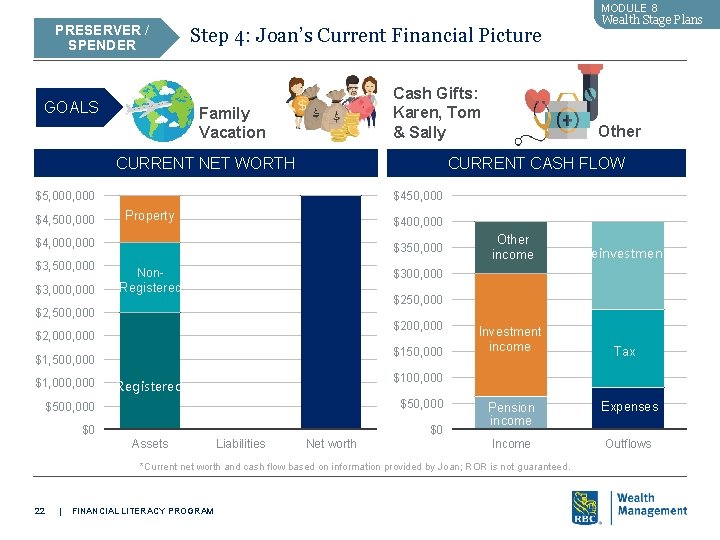
MODULE 8 PRESERVER / SPENDER GOALS Step 4: Joan’s Current Financial Picture Cash Gifts: Karen, Tom & Sally Family Vacation CURRENT NET WORTH $450, 000 Property $400, 000 $4, 000 $3, 500, 000 $3, 000 $350, 000 Non. Registered Reinvestments Investment income Tax $250, 000 $200, 000 $2, 000 $150, 000 $1, 500, 000 $100, 000 Registered $500, 000 $50, 000 $0 $0 Assets Other income $300, 000 $2, 500, 000 $1, 000 Other CURRENT CASH FLOW $5, 000 $4, 500, 000 Liabilities Net worth Pension income Expenses Income Outflows *Current net worth and cash flow based on information provided by Joan; ROR is not guaranteed. 22 Wealth. Stage. Plans | FINANCIAL LITERACY PROGRAM
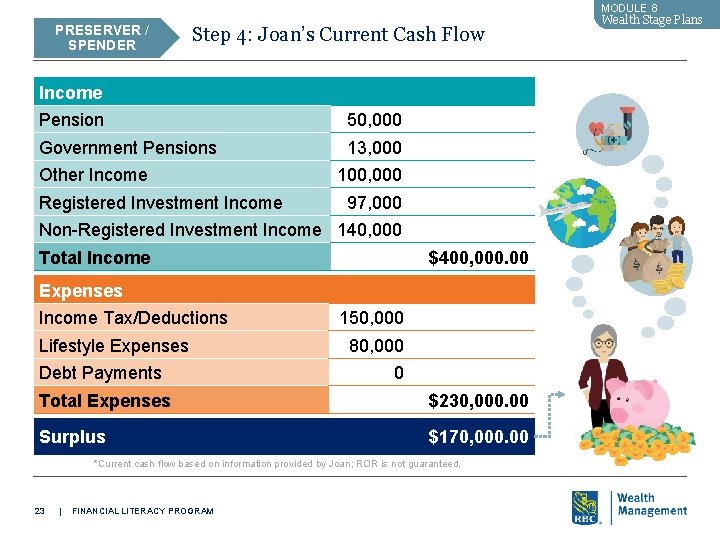
MODULE 8 PRESERVER / SPENDER Wealth. Stage. Plans Step 4: Joan’s Current Cash Flow Income Pension 50, 000 Government Pensions 13, 000 Other Income Registered Investment Income 100, 000 97, 000 Non-Registered Investment Income 140, 000 Total Income $400, 000. 00 Expenses 150, 000 80, 000 Debt Payments 0 Total Expenses $230, 000. 00 Income Tax/Deductions Lifestyle Expenses Surplus $170, 000. 00 *Current cash flow based on information provided by Joan; ROR is not guaranteed. 23 | FINANCIAL LITERACY PROGRAM
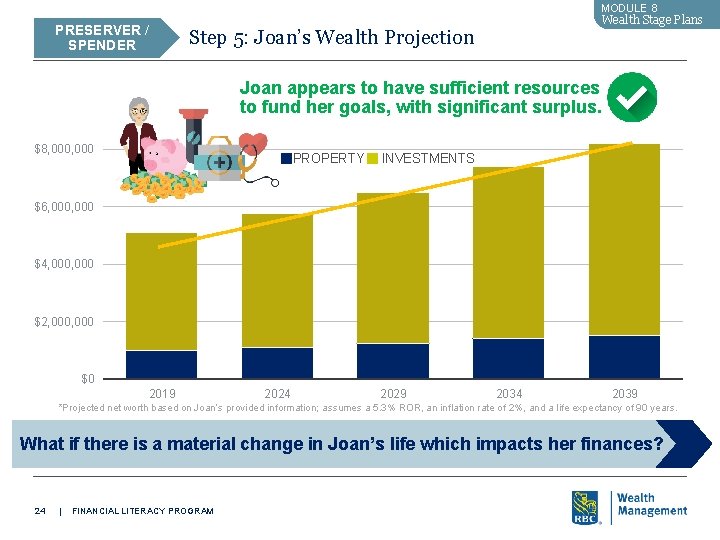
MODULE 8 PRESERVER / SPENDER Wealth. Stage. Plans Step 5: Joan’s Wealth Projection Joan appears to have sufficient resources to fund her goals, with significant surplus. $8, 000 PROPERTY INVESTMENTS $6, 000 $4, 000 $2, 000 $0 2019 2024 2029 2034 2039 *Projected net worth based on Joan’s provided information; assumes a 5. 3% ROR, an inflation rate of 2%, and a life expectancy of 90 years. What if there is a material change in Joan’s life which impacts her finances? 24 | FINANCIAL LITERACY PROGRAM
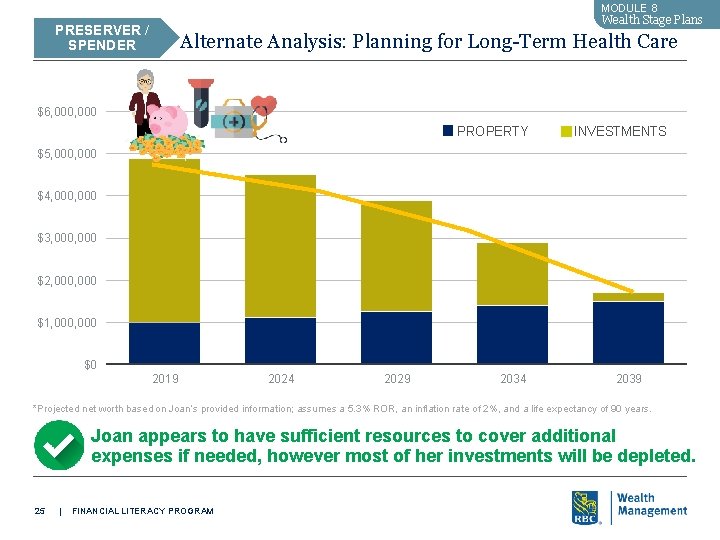
MODULE 8 PRESERVER / SPENDER Wealth. Stage. Plans Alternate Analysis: Planning for Long-Term Health Care $6, 000 PROPERTY INVESTMENTS $5, 000 $4, 000 $3, 000 $2, 000 $1, 000 $0 2019 2024 2029 2034 2039 *Projected net worth based on Joan’s provided information; assumes a 5. 3% ROR, an inflation rate of 2%, and a life expectancy of 90 years. Joan appears to have sufficient resources to cover additional expenses if needed, however most of her investments will be depleted. 25 | FINANCIAL LITERACY PROGRAM
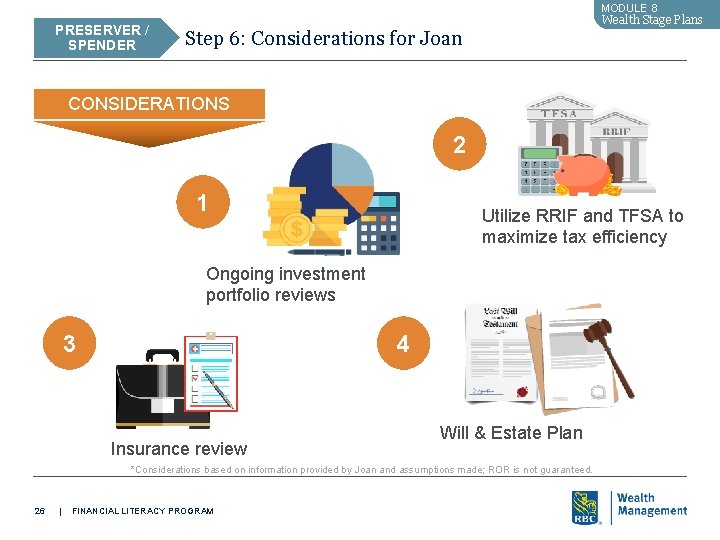
MODULE 8 PRESERVER / SPENDER Wealth. Stage. Plans Step 6: Considerations for Joan CONSIDERATIONS 2 1 Utilize RRIF and TFSA to maximize tax efficiency Ongoing investment portfolio reviews 3 4 Insurance review Will & Estate Plan *Considerations based on information provided by Joan and assumptions made; ROR is not guaranteed. 26 | FINANCIAL LITERACY PROGRAM
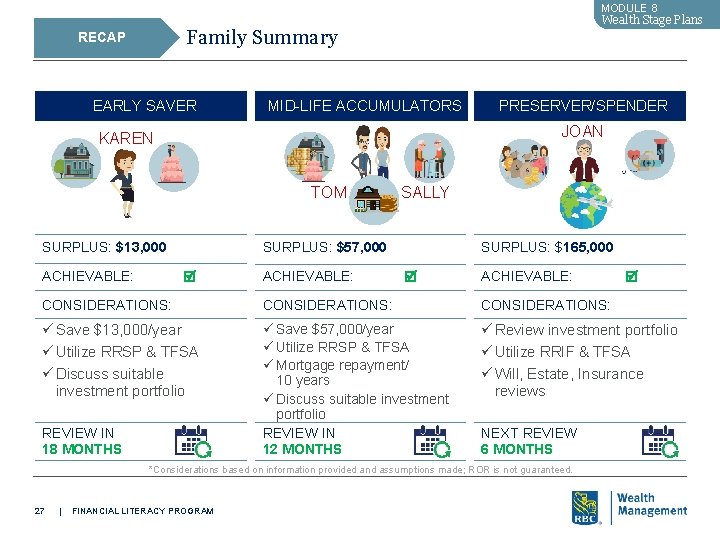
MODULE 8 Wealth. Stage. Plans Family Summary RECAP EARLY SAVER MID-LIFE ACCUMULATORS JOAN KAREN TOM SURPLUS: $13, 000 ACHIEVABLE: PRESERVER/SPENDER SALLY SURPLUS: $57, 000 ACHIEVABLE: SURPLUS: $165, 000 ACHIEVABLE: CONSIDERATIONS: ü Save $13, 000/year ü Utilize RRSP & TFSA ü Discuss suitable investment portfolio ü Save $57, 000/year ü Utilize RRSP & TFSA ü Mortgage repayment/ 10 years ü Discuss suitable investment portfolio REVIEW IN 12 MONTHS ü Review investment portfolio ü Utilize RRIF & TFSA ü Will, Estate, Insurance reviews REVIEW IN 18 MONTHS NEXT REVIEW 6 MONTHS *Considerations based on information provided and assumptions made; ROR is not guaranteed. 27 | FINANCIAL LITERACY PROGRAM
MODULE 8 Wealth. Stage. Plans Contact Us Nowochin Wealth Management Charles Nowochin Charles. Nowochin@rbc. com 403 -341 -7996 Melissa Rhodes melissa. rhodes@rbc. com 403 -341 -7407 28 | FINANCIAL LITERACY PROGRAM
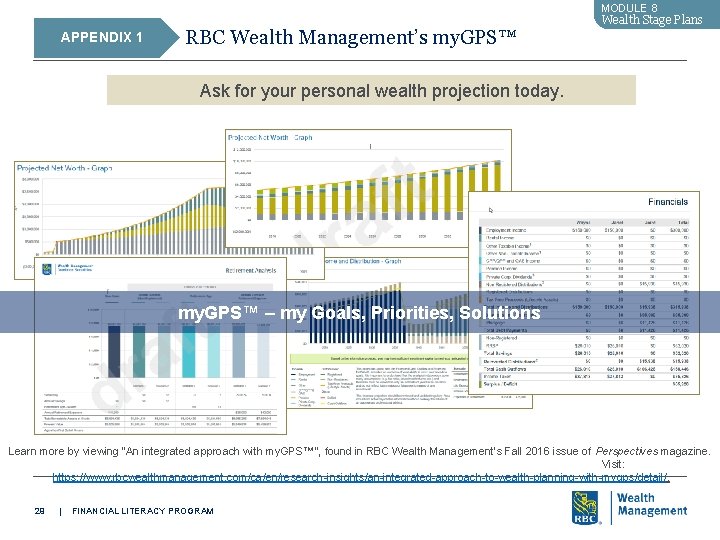
MODULE 8 APPENDIX 1 RBC Wealth Management’s my. GPS™ Wealth. Stage. Plans Ask for your personal wealth projection today. my. GPS™ – my Goals, Priorities, Solutions Learn more by viewing “An integrated approach with my. GPS™”, found in RBC Wealth Management’s Fall 2016 issue of Perspectives magazine. Visit: https: //www. rbcwealthmanagement. com/ca/en/research-insights/an-integrated-approach-to-wealth-planning-with-mygps/detail/. 29 | FINANCIAL LITERACY PROGRAM
MODULE 8 Wealth. Stage. Plans Thank you! This presentation has been prepared for use by the RBC Wealth Management member companies, RBC Dominion Securities Inc. (RBC DS)*, RBC Phillips, Hager & North Investment Counsel Inc. (RBC PH&N IC), RBC Global Asset Management Inc. (RBC GAM), Royal Trust Corporation of Canada and The Royal Trust Company (collectively, the “Companies”) and their affiliates, RBC Direct Investing Inc. (RBC DI)*, RBC Wealth Management Financial Services Inc. (RBC WMFS) and Royal Mutual Funds Inc. (RMFI). *Member–Canadian Investor Protection Fund. Each of the Companies, their affiliates and the Royal Bank of Canada are separate corporate entities which are affiliated. “RBC advisor” refers to Private Bankers who are employees of Royal Bank of Canada and licensed representatives of RMFI, Investment Counsellors who are employees of RBC PH&N IC and the private client division of RBC GAM, Senior Trust Advisors and Trust Officers who are employees of The Royal Trust Company or Royal Trust Corporation of Canada, or Investment Advisors who are employees of RBC DS. In Quebec, financial planning services are provided by RMFI or RBC WMFS and each is licensed as a financial services firm in that province. In the rest of Canada, financial planning services are available through RMFI, Royal Trust Corporation of Canada, The Royal Trust Company, or RBC DS. Estate and trust services are provided by Royal Trust Corporation of Canada and The Royal Trust Company. If specific products or services are not offered by one of the Companies or RMFI, clients may request a referral to another RBC partner. Insurance products are offered through RBC WMFS, a subsidiary of RBC DS. When providing life insurance products in all provinces except Quebec, Investment Advisors are acting as Insurance Representatives of RBC WMFS. In Quebec, Investment Advisors are acting as Financial Security Advisors of RBC WMFS. The strategies, advice and technical content in this publication are provided for the general guidance and benefit of our clients, based on information believed to be accurate and complete, but we cannot guarantee its accuracy or completeness. This publication is not intended as nor does it constitute tax or legal advice. Readers should consult a qualified legal, tax or other professional advisor when planning to implement a strategy. This will ensure that their individual circumstances have been considered properly and that action is taken on the latest available information. Interest rates, market conditions, tax rules, and other investment factors are subject to change. This information is not investment advice and should only be used in conjunction with a discussion with your RBC advisor. None of the Companies, RMFI, RBC WMFS, RBC DI, Royal Bank of Canada or any of its affiliates or any other person accepts any liability whatsoever for any direct or consequential loss arising from any use of this report or the information contained herein. ® Registered trademarks of Royal Bank of Canada. Used under license. © 2019 Royal Bank of Canada. All rights reserved. 30 | FINANCIAL LITERACY PROGRAM Content themes sourced by
- Slides: 30