
FINANCIAL ACCOUNTING N 4 MODULE 5 CASH FLOW
- Slides: 10
FINANCIAL ACCOUNTING N 4 MODULE 5: CASH FLOW STATEMENT OF A SOLE TRADER NOTES BY: MOTAUNG M. R
PURPOSE OF A CASH FLOW STATEMENT • The aim of a cash flow statement is to identify the inflow and outflow of cash during a specific financial period in the organization. • The cash flow statement only deals with cash transactions (money coming in and out of the organization)that can increase or decrease cash position in the organization. • The income of the business is generated by rendering a service and selling of goods, so the cash flow statement is used to analyze the inflow and outflow of cash. • (Strydom & Groenwald, 2013)
THE USERS OF THE CASH FLOW STATEMENT • The following stakeholders will utilize the cash flow statement: • The owner of the organization • The management of the organization • Credit suppliers (banks and other financial institutions) • (Strydom & Groenwald, 2013)
HOW TO COMPILE A CASH FLOW STATEMENT • The following financial information is required to compile a cash flow statement: • The income statement of the current financial period • The balance statement of two consecutive financial periods • Adjustments with regard to Non-current assets (Strydom & Groenwald, 2013).
NON-CASH FLOW ITEMS • Other items in the Income statement do not represent cash flow, but they are taken into the notes of the cash flow statement: • Profit/loss with the disposal and revaluation of fixed assets, • Discount received and allowed • Depreciation on non-current assets • Stock written off • (Strydom & Groenwald, 2013)
PROCEDURE • The cash flow statement is divided into three parts: • 1. Cash operating activities -note 1&2, Interest paid, interest received and drawings • 2. Cash flow from investing activities • -Purchases of fixed assets, proceeds from sale of assets • 3. Cash flow from financing activities -Loan received/paid and capital contribution by the owner (Strydom & Groenwald, 2013)
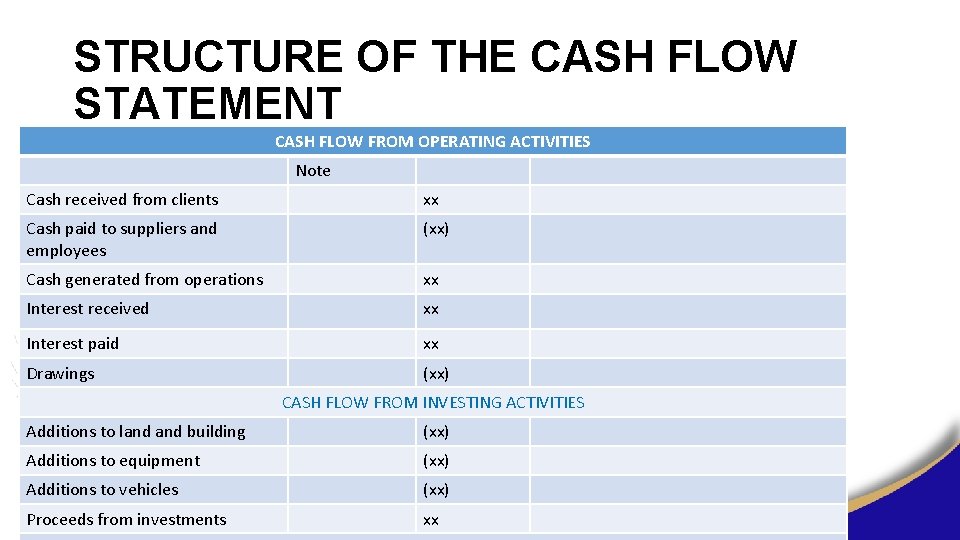
STRUCTURE OF THE CASH FLOW STATEMENT CASH FLOW FROM OPERATING ACTIVITIES Note Cash received from clients xx Cash paid to suppliers and employees (xx) Cash generated from operations xx Interest received xx Interest paid xx Drawings (xx) CASH FLOW FROM INVESTING ACTIVITIES Additions to land building (xx) Additions to equipment (xx) Additions to vehicles (xx) Proceeds from investments xx
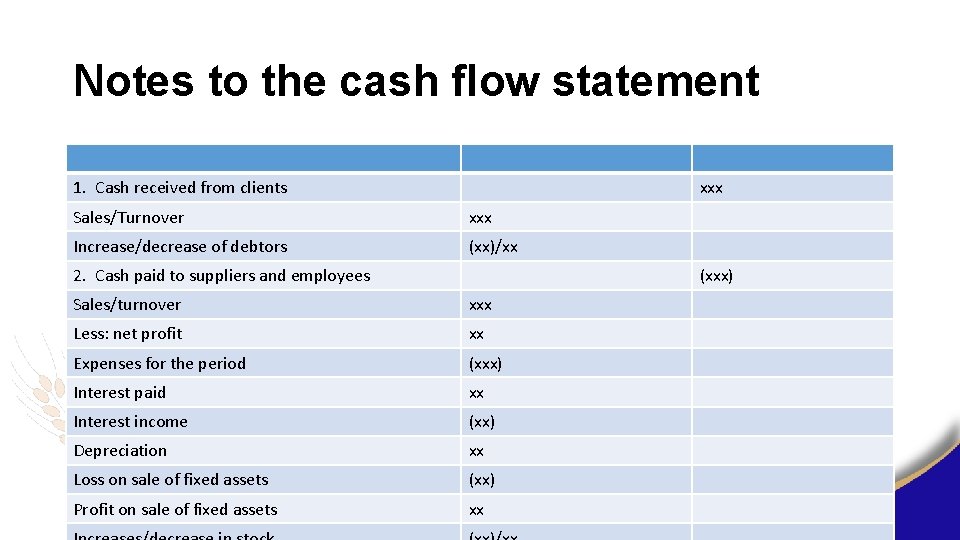
Notes to the cash flow statement 1. Cash received from clients xxx Sales/Turnover xxx Increase/decrease of debtors (xx)/xx 2. Cash paid to suppliers and employees (xxx) Sales/turnover xxx Less: net profit xx Expenses for the period (xxx) Interest paid xx Interest income (xx) Depreciation xx Loss on sale of fixed assets (xx) Profit on sale of fixed assets xx
• Exercises in the text-book • Exercise 5 B, pg 357 • Exercise 5 C, pg 360
BIBLIOGRAPHY • Strydom, H. and Groenwald, S. (2013) Financial accounting N 4. Pretoria. Seyfferdt Publishers • www. futuremanagers. com