
FERS Retirement Planning Benefits Division Administrative Office of
FERS Retirement Planning Benefits Division Administrative Office of the U. S. Courts
FERS RETIREMENT PLANNING Agenda • Retirement Overview • Helping Employees Prepare for Retirement • Crunching the Numbers • Survivor Benefits • Benefits in Retirement • Thrift Savings Plan Withdrawal Options • Online Resources 2
FERS RETIREMENT PLANNING Retirement Overview 3
FERS RETIREMENT PLANNING FERS: A Three-Tier Retirement Plan • Basic Benefit and FERS Annuity Supplement • Social Security • Thrift Savings Plan (TSP) 4
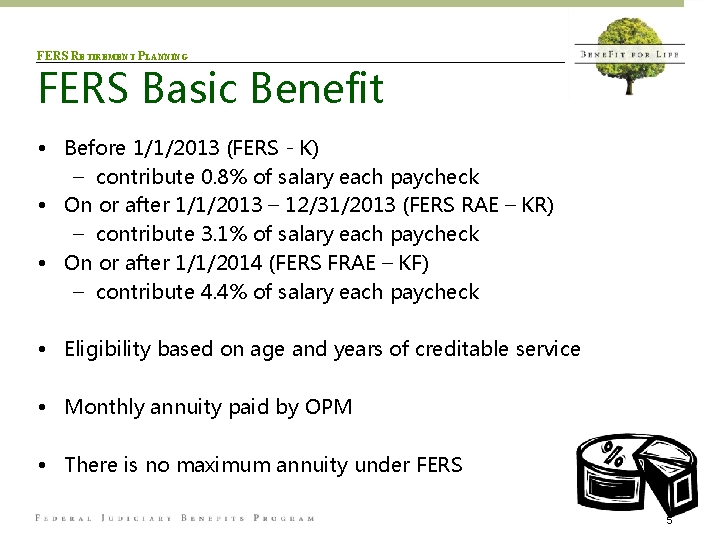
FERS RETIREMENT PLANNING FERS Basic Benefit • Before 1/1/2013 (FERS - K) – contribute 0. 8% of salary each paycheck • On or after 1/1/2013 – 12/31/2013 (FERS RAE – KR) – contribute 3. 1% of salary each paycheck • On or after 1/1/2014 (FERS FRAE – KF) – contribute 4. 4% of salary each paycheck • Eligibility based on age and years of creditable service • Monthly annuity paid by OPM • There is no maximum annuity under FERS 5
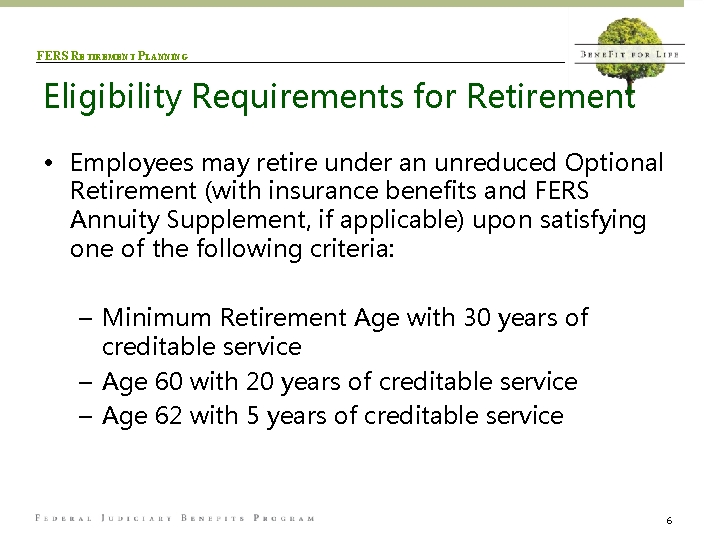
FERS RETIREMENT PLANNING Eligibility Requirements for Retirement • Employees may retire under an unreduced Optional Retirement (with insurance benefits and FERS Annuity Supplement, if applicable) upon satisfying one of the following criteria: – Minimum Retirement Age with 30 years of creditable service – Age 60 with 20 years of creditable service – Age 62 with 5 years of creditable service 6
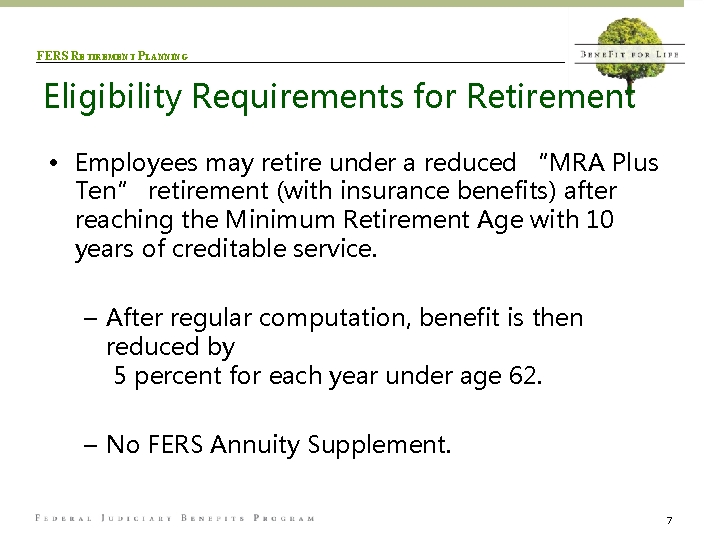
FERS RETIREMENT PLANNING Eligibility Requirements for Retirement • Employees may retire under a reduced “MRA Plus Ten” retirement (with insurance benefits) after reaching the Minimum Retirement Age with 10 years of creditable service. – After regular computation, benefit is then reduced by 5 percent for each year under age 62. – No FERS Annuity Supplement. 7

FERS RETIREMENT PLANNING FERS Minimum Retirement Ages If you were born in Your Minimum Retirement Age is 1947 or earlier 55 Years 1948 55 Years, 2 months 1949 55 Years, 4 months 1950 55 Years, 6 months 1951 55 Years, 8 months 1952 55 Years, 10 months 1953 to 1964 56 Years 1965 56 Years, 2 months 1966 56 Years, 4 months 1967 56 Years, 6 months 1968 56 Years, 8 months 1969 56 Years, 10 months 1970 or later 57 8

FERS RETIREMENT PLANNING Eligibility Requirements for Retirement Voluntary Early Retirement Must occupy a position covered by the approved agency plan Must retire by the agency-specified date Age 50 with 20 years of creditable service Any age with at least 25 year creditable Federal service CSRS – 1/6 per month or 2% per year permanent annuity reduction for each year under 55 FERS – No reduction Annuity estimates authorized only if employed notified of Early Retirement authorization 9

FERS RETIREMENT PLANNING Eligibility Requirements for Retirement • Employees may retire under Disability Retirement (with insurance benefits) at any age with 18 months of service – No FERS Annuity Supplement – 8 -10 month (on average) wait for OPM to render a decision – Separated for more than 31 days, submit disability retirement application directly to OPM – Application must be filed within 1 year of separation date 10

FERS RETIREMENT PLANNING Crediting Military Service • Employees can receive creditable service for active duty military service – Honorable or under honorable conditions • A deposit is required to receive credit for: – Any period of active duty service performed after 12/31/1956 – Deposit must be made before retirement – LWOP-US employee must make a deposit during the period when they were not receiving civilian pay 11

FERS RETIREMENT PLANNING Deposit Service • Employees can receive credit for civilian service performed before January 1, 1989 which was covered only by Social Security (FICA Only) • A deposit must be made to receive credit for FERS retirement eligibility and annuity calculation • No credit allowed for service performed after January 1, 1989 if retirement deductions were not withheld • Exception: Peace Corps or VISTA service 12

FERS RETIREMENT PLANNING Re-deposit Service • Re-deposits can be made for both CSRS and FERS refunds • Employee must make redeposit (plus interest) to receive credit in FERS annuity calculation for service that was previously refunded 13

FERS RETIREMENT PLANNING Sick Leave Credit – Now Under FERS • FERS employees now receive 100% of their sick leave balance as service credit time. • 2, 087 hours of unused sick leave equals a year of credit Key Points • Saving sick leave has advantages for FERS employees • Sick leave time is added to the actual service credit • Sick leave time is not used to determine eligibility 14

FERS RETIREMENT PLANNING FERS Annuity Supplement (“Bridge”) • Begins immediately upon retiring at MRA or older on regular voluntary retirement • Begins at MRA if retiring earlier under Early Optional Retirement or Discontinued Service Retirement • Subject to “earnings test” • Paid by US Office of Personnel Management, not by Social Security Administration • Approximates the portion of a full career Social Security benefit earned while under FERS • Ends at age 62 when Social Security benefits first become available 15

FERS RETIREMENT PLANNING Social Security • FERS & CSRS-Offset employees contribute 6. 2% of salary to Social Security taxes (OASDI or FICA) • Eligible to begin receiving benefits as early as age 62 or as late as age 70 – Full retirement age (FRA) – to receive full benefit – based on the year employee was born – Benefit is reduced if received prior to FRA • Benefit amount based on average earnings during lifetime of work contributing to Social Security 16

FERS RETIREMENT PLANNING Thrift Savings Plan (TSP) • Voluntary retirement benefit helps employee secure financial future • It’s up to you to maximize the TSP’s benefits to save for that “rainy day” • Similar to a 401(K) plan, employee chooses funds to invest – Five major funds: G, F, C, S, I – Life Cycle Funds: L 17

FERS RETIREMENT PLANNING TSP Tax Implications • IRS Deferral Limit – 2018: $18, 500 • Traditional – Contributions are deducted from your pay before your taxes are withheld. – Taxes are computed on your reduced salary. – Automatic tax break • Roth – Contributions are deducted from your pay after taxes – No taxes are taken on contributions when TSP is withdrawn 18

FERS RETIREMENT PLANNING TSP Agency Contributions • Agency Automatic 1% – The agency will contribute an amount equal to 1% of your basic pay – Do not need to participate in TSP contributions to receive – 3 year vesting period • Matching Contributions – Contributions matched dollar for dollar up to 3% – Contributions matched $. 50 for every dollar for 4% and 5% – No vesting period 19

FERS RETIREMENT PLANNING TSP Catch-up Contributions • You may make catch-up contributions if: – If you are age 50 or older or you will become age 50 during the calendar year; AND – You contribute the maximum IRS deferral limit • Separate annual limit set by IRS – Currently $6, 000 per year – In addition to regular contribution – No matching contributions 20

FERS RETIREMENT PLANNING Helping Employees Prepare for Retirement 21

FERS RETIREMENT PLANNING Forms Needed to Retire Once an employee has decided to retire, the next step is to complete the needed forms: • SF 3107 ‒ Application for Immediate Retirement, FERS • SF 2818 ‒ Continuation of Life Insurance • W-4 P ‒ Withholding Certification for Pension or Annuity Payments Retirement applications should be completed and mailed to at least 60 days prior to retirement date Submitting Your Retirement Application What to Expect in Retirement 22

FERS RETIREMENT PLANNING Annuity Estimate • Within 3 -5 years of first eligible retirement date üAO-74 üHow to Complete the AO-74 Request for Annuity Estimate • More than 5 years from first eligible retirement date üFed. Calc üFree tool which can be used to calculate retirement estimates with more than 5 years out from first retirement eligibility date ühttp: //www. fedcalc. com/fers. jsp 23

FERS RETIREMENT PLANNING Choosing a Retirement Date • The annuity effective date is the first day of the month after the retirement date – Example: Retire 10/15/2018, Annuity Effective: 11/1/2018 – Example: Retire 10/31/2018, Annuity Effective: 11/1/2018 – Example: (CSRS) Retire 11/1/2018, Annuity Effective 11/2/2018 • End of the month • End of the pay period – Leave accrual • End of the year – Leave accrual 24

FERS RETIREMENT PLANNING OPM and the Retirement Process • OPM receives application and enters retiree’s information into annuity system under “interim pay status” – CSA number assigned – Retiree receives up to approximately 85% of scheduled annuity payment • OPM reviews application for necessary documents, creditable service, and retirement deductions – Once finalized, retiree begins receiving full annuity payment • Percentage not paid during adjudication – First used to pay accumulated health and life insurance premiums – Any remaining amount is paid to retiree as “back annuity” 25

FERS RETIREMENT PLANNING Crunching the Numbers 26

FERS RETIREMENT PLANNING FERS Annuity Computation Basic Annuity Formula 1. 0% of the high-three average salary multiplied by length of creditable service Reduced by 5% for each year under age 62 only if retiring under MRA Plus Ten Basic Annuity Formula if retiring at age 62 with at least 20 years of creditable service 1. 1% of the high-three average salary multiplied by length of creditable service. 27

FERS RETIREMENT PLANNING “High-3”? • High-Three Average Salary – the average of basic pay during the consecutive three-year period when basic pay rates were the highest during an employee’s career. 28

FERS RETIREMENT PLANNING Part-Time Service • High-3 average salary is calculated the same as for a full-time employee • Annuity is calculated the same as for a full-time employee then multiplied by a part-time proration rate – Ratio between actual hours worked divided by total full-time hours possible to date of retirement. – The lower part-time proration rate, the greater reduction of annuity 29

FERS RETIREMENT PLANNING Cost-of-Living Adjustment (COLA) • Cost-of-Living Adjustments increase the amount of the retiree’s annuity each year • FERS Retirees begin receiving a COLA starting the year they turn age 62, or the year after they retire (if after age 62). • FERS Annuity Supplement (“Bridge”) is not increased by COLA • COLA based on percentage increase in Consumer Price Index (CPI) 30

FERS RETIREMENT PLANNING Taxes • The IRS taxes all Federal annuities • Tax treatment by states – Many states tax the full amount of the Federal annuity – Some states exclude the full amount of the annuity from taxes • States that do not have state income tax: – – – – – Alaska Florida Nevada New Hampshire South Dakota Tennessee Texas Washington State Wyoming 31

FERS RETIREMENT PLANNING Survivor Benefits 32

FERS RETIREMENT PLANNING FERS Survivor Annuity • Retiring employees may make one of three types of spousal survivor benefit elections at the time of retirement: – No survivor annuity (no survivor benefits) – Partial survivor annuity (25% of monthly annuity) • Monthly annuity reduced by 5% – Full survivor annuity (50% of monthly annuity) • Monthly annuity reduced by 10% • Employees must elect a Full or Partial survivor benefit in order for spouse to continue health benefits 33

FERS RETIREMENT PLANNING Keeping Benefits in Retirement 34

FERS RETIREMENT PLANNING Health Benefits (FEHB) • Continued Government premium contribution – Biweekly vs. monthly • Automatic deduction from annuity • Premiums are “after-tax” • Lifetime coverage • Making changes – Qualifying Life Events (QLEs) – Annual Open Season 35

FERS RETIREMENT PLANNING FEHB: The “Five-Year Rule” • You must be covered under the FEHB program for the last five years of service before you retire – You DON’T have to be in the same plan/option for all five years – Family members don’t have to meet this rule • Coverage under a spouse’s FEHB plan counts, even if for all five years • TRICARE coverage counts, if you’re in an FEHB plan on your last day • Plan for this --- OPM rarely grants waivers 36

FERS RETIREMENT PLANNING Dental and Vision Coverage (FEDVIP) • No five-year rule for continued coverage • Retirees eligible to newly enroll, or re-enroll before and after retirement • Administered by BENEFEDS under OPM authority • Can enroll for dental, vision, or both • Premiums are “after-tax” 37

FERS RETIREMENT PLANNING Life Insurance (FEGLI) • Must be covered (at least by Basic) for the five years of service immediately before retirement • Must meet this rule for each portion of FEGLI (options, multiples) to be carried into retirement • Elections made during 2016 FEGLI Open Season (eff. 2017) can’t be taken into retirement until 2022 38

FERS RETIREMENT PLANNING Basic Life Insurance • Salary rounded up to nearest $1, 000, plus an additional $2, 000 • No extra AD&D benefit after retirement • Decide at retirement what will happen at 65 – No Reduction: Full amount for life, BIG monthly premium for life – 50% Reduction: 1% reduction each month after age 65 to 50% level. Smaller monthly premium for life – 75% Reduction: 2% reduction each month after age 65 to 25% level. FREE after age 65!!! 39

FERS RETIREMENT PLANNING Option A Life Insurance • $10, 000 coverage amount until age 65 – Premium same as employee would pay • No extra AD&D benefit after retirement • At 65, 2% reduction each month to $2, 500 – FREE after age 65!!! 40

FERS RETIREMENT PLANNING Option B Life Insurance • Salary rounded up to nearest $1, 000 times the number of multiples (up to 5) • Amount of Option B remains the same until age 65 – Can cancel or reduce multiples • Decide at retirement what will happen at 65 – No Reduction: Full amount for life, BIG monthly premium for life. Can reduce multiples at any time. – Full Reduction: 2% reduction each month after age 65 until reaches zero. FREE after age 65!!! 41

FERS RETIREMENT PLANNING Option C Life Insurance • Family coverage – up to 5 multiples – Death of Spouse: $5, 000 per multiple – Death of Child (under age 22): $2, 500 per multiple • Amount of Option C remains the same until age 65 – Can cancel or reduce multiples • Decide at retirement what will happen at 65 – No Reduction: Full amount for life, moderate monthly premium for life. Can reduce multiples at any time. – Full Reduction: 2% reduction each month after age 65 until reaches zero. FREE after age 65!!! 42

FERS RETIREMENT PLANNING Long Term Care Insurance • Helps to pay for such long-term care services as: – nursing home care – home health care – assisted living care – adult day care – hospice care • These costs AREN’T paid by Medicare, FEHB, Tricare or other insurance plans! • Contact LTCFEDS after retirement (877) 888 -3337 – Premiums paid through deduction from annuity or – Premiums paid by check or automatic deduction from personal bank account 43

FERS RETIREMENT PLANNING Thrift Savings Plan (TSP) Withdrawal Options 44

FERS RETIREMENT PLANNING TSP Limitations in Retirement • Withdrawal of some, or all, of the TSP account balance must be made by April 1 of the year following the year in which retiree reaches age 70½ – Withdrawal can be single payment, monthly payments, or annuity ** changes are coming • Additional contributions to the TSP are not allowed – Transfers from an IRA or eligible employer plans are permitted • New loans cannot be initiated from the account 45

FERS RETIREMENT PLANNING Taxes on TSP Withdrawals • All TSP withdrawals are subject to Federal income taxes – Exception: A qualified distribution under TSP Roth • Key considerations – Different tax rules may apply to different TSP withdrawal options – Any outstanding loan at the time of separation must be repaid, or unpaid amount becomes fully taxable • For detailed information about TSP tax rules, refer to Important Tax Information About Payments from Your TSP Account 46

FERS RETIREMENT PLANNING TSP Withdrawal Options: A Closer Look • Series of monthly payments (life rate): Entire account balance paid over time in equal monthly payments – Uses IRS life expectancy tables – Spreads tax liability over time period of withdrawal • Series of monthly payments (fixed dollar amount): Account balance paid over time in requested dollar amounts – Spreads tax liability over time period of withdrawal – Can make changes to monthly amount • Life annuity: All or a portion of account balance used by TSP to purchase monthly benefit paid to the retiree for life – Spreads tax liability over time period annuity is received 47

FERS RETIREMENT PLANNING TSP Withdrawal Options: A Closer Look • Single payment: Entire account balance withdrawn at once – Fully taxable in year paid • Partial withdrawal: A lump sum payment withdrawn before request for “full” withdrawal is made • Transferring a withdrawal: Full or partial withdrawals transferred to an IRA or eligible employer plan in a single payment or in monthly payments – Monthly payment transfers are expected to last less than 10 years 48

Online Resources 49

FERS RETIREMENT PLANNING Online Resources • Retirement Lifeline: Building your retirement strategy starts with you. Your Retirement Lifeline puts much of the information you need to make informed decisions about your retirement right into your hands. http: //jnet. ao. dcn/human-resources/benefits/mid-careerresources/retirement-planning • Benefit For Life Hour: The Benefits Division provides live and on-demand recorded educational webinars regarding the Federal Judiciary Benefits Programs. http: //jnet. ao. dcn/human-resources/benefit-lifehour 50

FERS RETIREMENT PLANNING Online Resources • TSP Calculators: The TSP is one source of your retirement income. Use the calculators available to project future balances and retirement income. https: //www. tsp. gov/Planning. Tools/Calculators/index. ht ml • FEGLI Calculator: https: //www. opm. gov/retirementservices/calculators/fegli-calculator/ With this online calculator you can: − Determine the face value and premiums of various combinations of FEGLI coverage. − See how the life insurance carried into retirement will change over time. 51

FERS RETIREMENT PLANNING Have a Question? Contact the Retirement Processing Services Team Phone: (202) 502 -3110 Fax: (202) 502 -3599 Email: Retirement Branch/DCA/AO/USCOURTS or Contact the Benefits Advisory Team Phone: (202) 502 -1160 Fax: (202) 502 -2877 Email: Benefits Mailbox/DCA/AO/USCOURTS Benefits Division Contacts http: //jnet. ao. dcn/human-resources/benefits-contacts 52
- Slides: 52