
Federal Student Loan Repayment Plans and the Repayment
- Slides: 41
Federal Student Loan Repayment Plans and the Repayment Estimator June 2016
Today’s Topics Student Loan Basics • Repayment Options and Repayment Estimator • Postponing Payments, Default, and Discharge • Federal Student Aid Resources •
Student Loan Basics Types of Loans and Loan Servicers
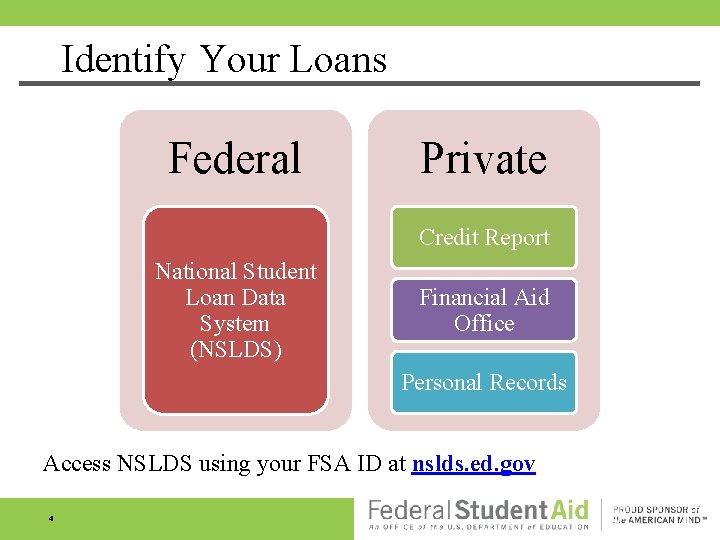
Identify Your Loans Federal Private Credit Report National Student Loan Data System (NSLDS) Financial Aid Office Personal Records Access NSLDS using your FSA ID at nslds. ed. gov 4
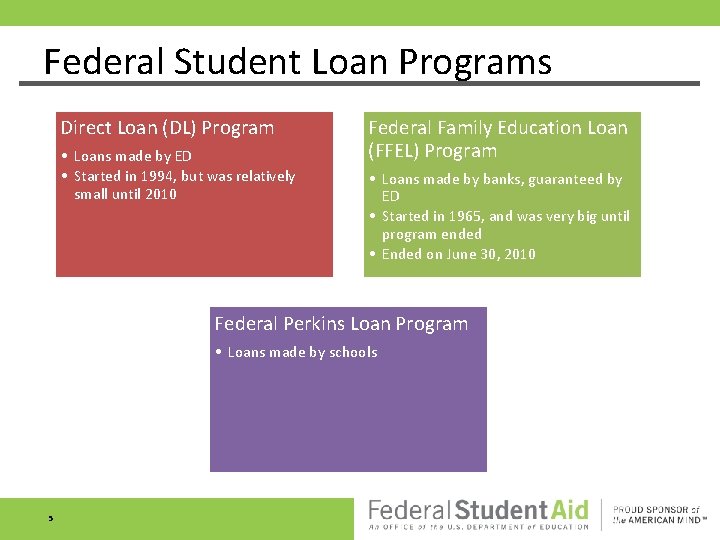
Federal Student Loan Programs Direct Loan (DL) Program • Loans made by ED • Started in 1994, but was relatively small until 2010 Federal Family Education Loan (FFEL) Program • Loans made by banks, guaranteed by ED • Started in 1965, and was very big until program ended • Ended on June 30, 2010 Federal Perkins Loan Program • Loans made by schools 5
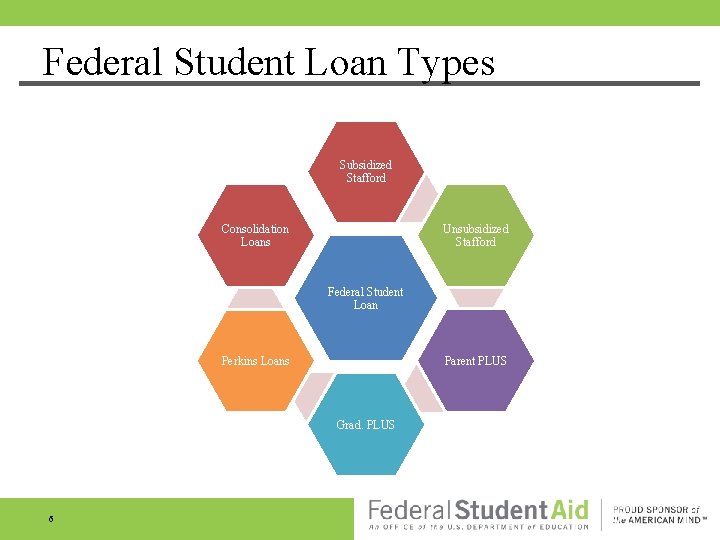
Federal Student Loan Types Subsidized Stafford Consolidation Loans Unsubsidized Stafford Federal Student Loan Parent PLUS Perkins Loans Grad. PLUS 6
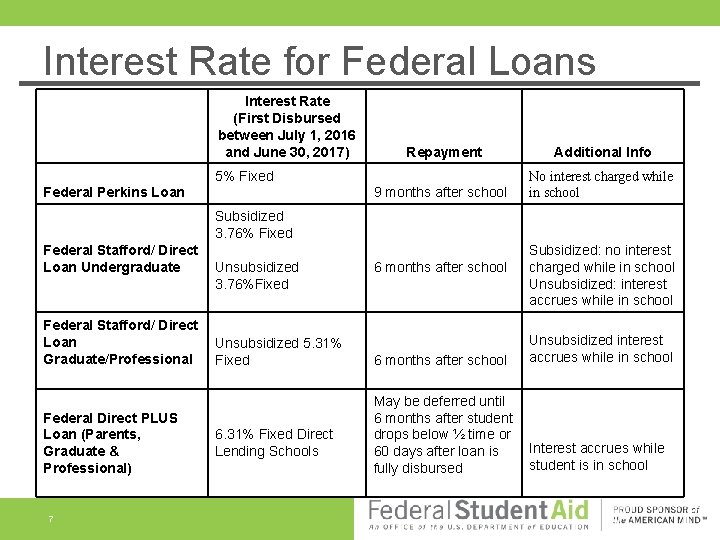
Interest Rate for Federal Loans Interest Rate (First Disbursed between July 1, 2016 and June 30, 2017) Repayment Additional Info 9 months after school No interest charged while in school 5% Fixed Federal Perkins Loan Subsidized 3. 76% Fixed Federal Stafford/ Direct Loan Undergraduate Federal Stafford/ Direct Loan Graduate/Professional Federal Direct PLUS Loan (Parents, Graduate & Professional) 7 Unsubsidized 3. 76%Fixed Unsubsidized 5. 31% Fixed 6. 31% Fixed Direct Lending Schools 6 months after school Subsidized: no interest charged while in school Unsubsidized: interest accrues while in school 6 months after school Unsubsidized interest accrues while in school May be deferred until 6 months after student drops below ½ time or 60 days after loan is fully disbursed Interest accrues while student is in school
8
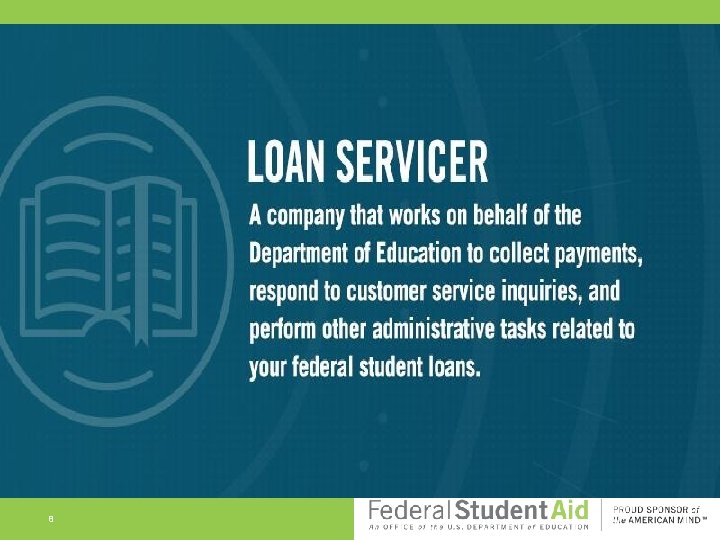
Loan Servicers The following are loan servicers for federally held loans made through the Direct Loan and (FFEL) Programs: • • • Corner. Stone ESA/Edfinancial Fed. Loan Servicing (PHEAA) Granite State – GSMR Great Lakes Educational Loan Services, Inc. MOHELA Navient Nelnet OSLA Servicing VSAC Federal Loans 9
Brookings and Perkins Repayment Heartland ECSI is the loan servicer for these two loans • They can be contacted at 888 -549 -3247 • Their Website is www. heartlandecsi. com • Little tip: your school code is W 30 and your account number is typically your social security number • 10
Repayment Options Repayment Plans and Consolidation 11
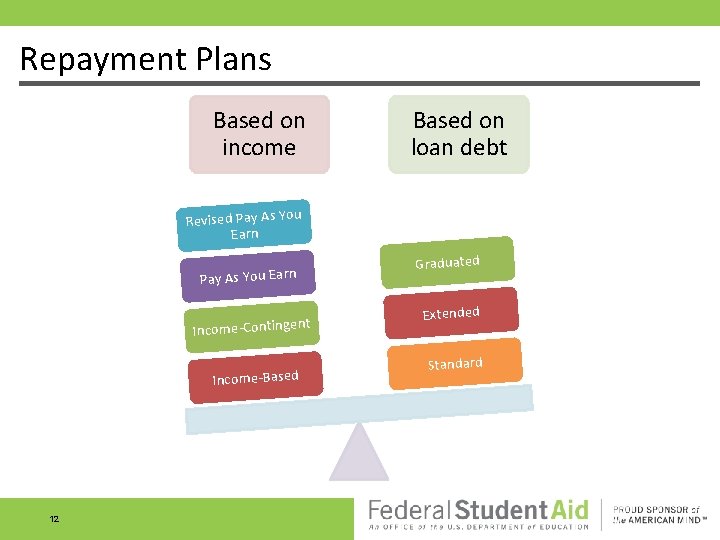
Repayment Plans Based on income Based on loan debt u Revised Pay As Yo Earn Pay As You Earn t Income-Contingen Income-Based 12 Graduated Extended Standard
Standard Repayment Plan Under this plan, the borrower will pay a fixed amount that ensures they pay their loan(s) in full within the repayment period. Payments will be at least $50 per month. For subsidized, unsubsidized, and PLUS loans, the repayment period is 10 years. For consolidation loans, the repayment period is 10 -30 years, depending on the borrower’s total educational indebtedness. For borrowers who do not have consolidation loans, this plan results in the lowest total interest paid because the repayment period is shorter than it would be under any of the other repayment plans. 13
Extended Repayment Plan Under this plan, the borrower will pay a fixed or graduated amount in an amount that will ensure that they pay their loans(s) in full within 25 years. Fixed payments will be at least $50 per month. Graduated payments will be at least the amount of interest that accrues in a month. A borrower may choose this plan if: • He or she did not have an outstanding balance on a FFEL Program or Direct Loan as of October 7, 1998 or on the date they obtained a student loan after that date and • He or she has more than $30, 000 in outstanding FFEL Program loans or more than $30, 000 in outstanding Direct Loans. 14
Graduated Repayment Plan Under this plan, the borrower will pay an amount that increases every two years and ensures that they pay their loan(s) in full within the repayment period. For subsidized, unsubsidized, and PLUS loans, the repayment period is 10 years. For consolidation loans, the repayment period is 10 -30 years, depending on the borrower’s total educational indebtedness. The minimum payment equals the amount of interest that accrues monthly. No one payment will be more than three times greater than any other payment. 15
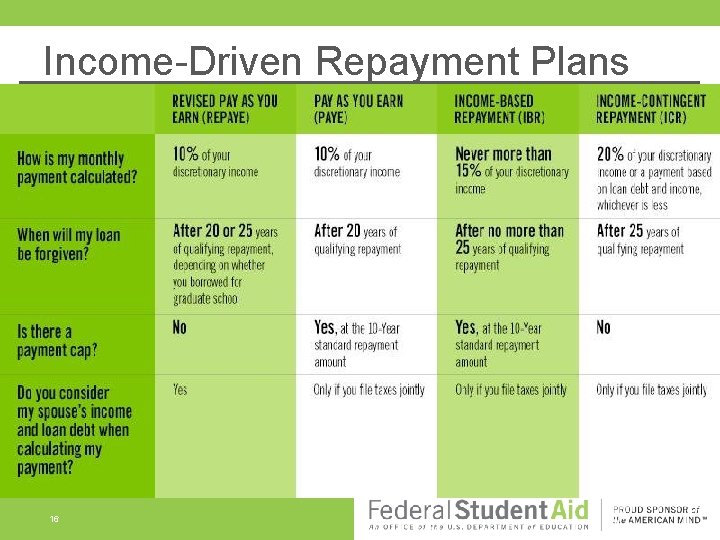
Income-Driven Repayment Plans 16
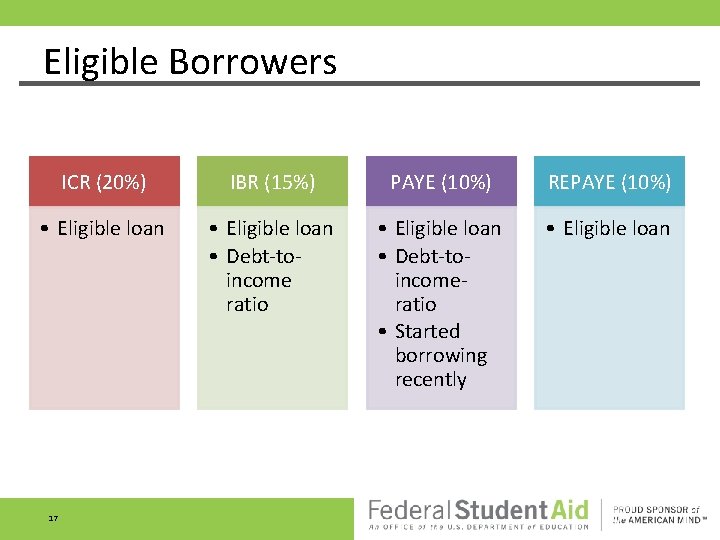
Eligible Borrowers ICR (20%) IBR (15%) PAYE (10%) REPAYE (10%) • Eligible loan • Debt-toincome ratio • Eligible loan • Debt-toincomeratio • Started borrowing recently • Eligible loan 17
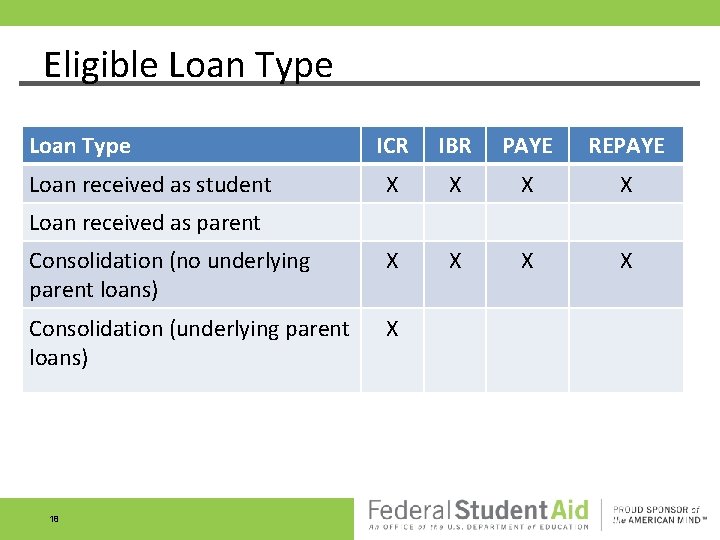
Eligible Loan Type ICR IBR PAYE REPAYE X X Consolidation (no underlying parent loans) X X Consolidation (underlying parent loans) X Loan received as student Loan received as parent 18
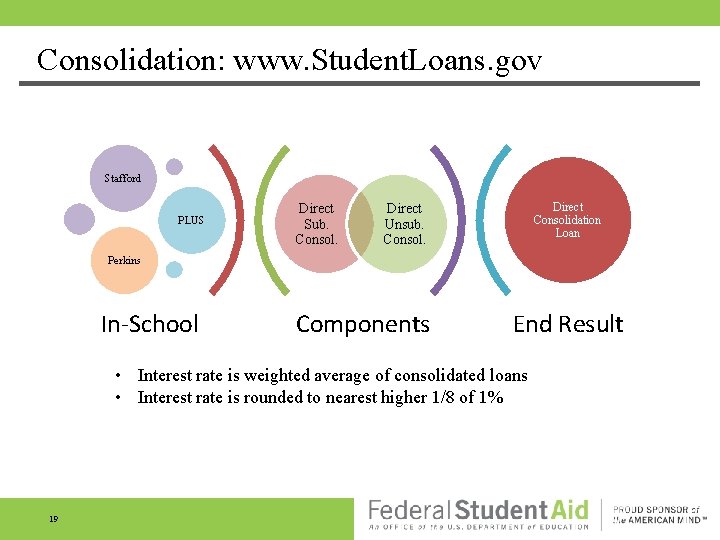
Consolidation: www. Student. Loans. gov Stafford PLUS Direct Sub. Consol. Direct Consolidation Loan Direct Unsub. Consol. Perkins In-School Components End Result • Interest rate is weighted average of consolidated loans • Interest rate is rounded to nearest higher 1/8 of 1% 19
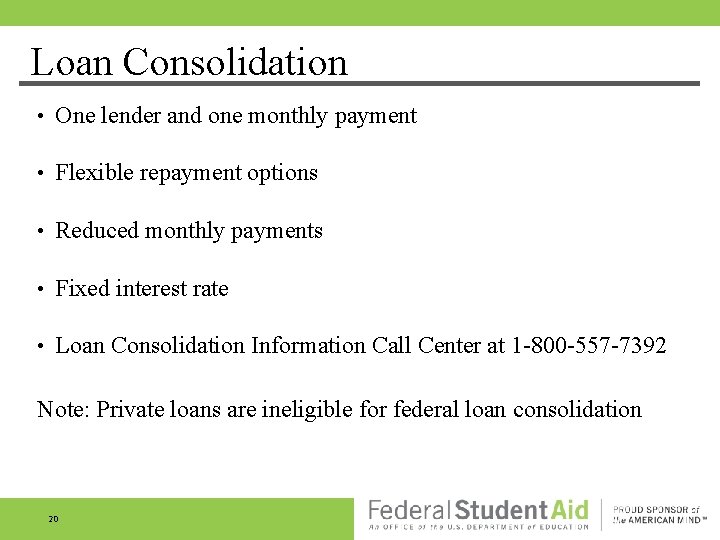
Loan Consolidation • One lender and one monthly payment • Flexible repayment options • Reduced monthly payments • Fixed interest rate • Loan Consolidation Information Call Center at 1 -800 -557 -7392 Note: Private loans are ineligible for federal loan consolidation 20
Income Sensitive Repayment Plan • Federal Family Education Loans (FFEL) • Low-income borrowers • Not applicable to those with Direct Loans • Payments increase or decrease based on income 21
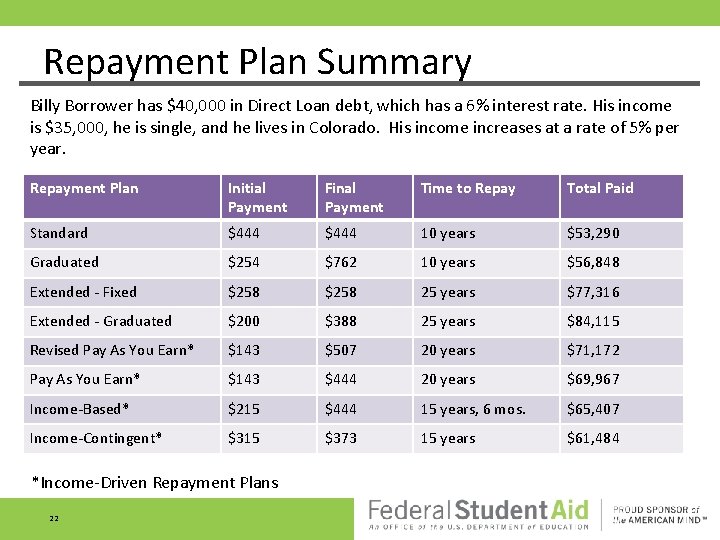
Repayment Plan Summary Billy Borrower has $40, 000 in Direct Loan debt, which has a 6% interest rate. His income is $35, 000, he is single, and he lives in Colorado. His income increases at a rate of 5% per year. Repayment Plan Initial Payment Final Payment Time to Repay Total Paid Standard $444 10 years $53, 290 Graduated $254 $762 10 years $56, 848 Extended - Fixed $258 25 years $77, 316 Extended - Graduated $200 $388 25 years $84, 115 Revised Pay As You Earn* $143 $507 20 years $71, 172 Pay As You Earn* $143 $444 20 years $69, 967 Income-Based* $215 $444 15 years, 6 mos. $65, 407 Income-Contingent* $315 $373 15 years $61, 484 *Income-Driven Repayment Plans 22
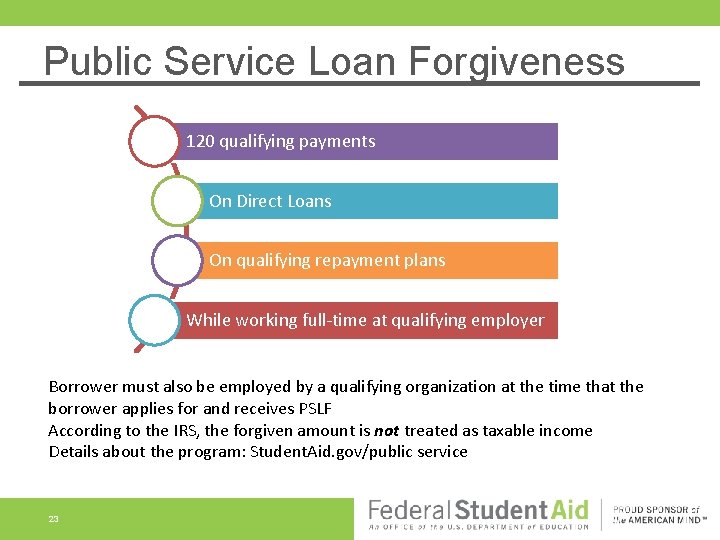
Public Service Loan Forgiveness 120 qualifying payments On Direct Loans On qualifying repayment plans While working full-time at qualifying employer Borrower must also be employed by a qualifying organization at the time that the borrower applies for and receives PSLF According to the IRS, the forgiven amount is not treated as taxable income Details about the program: Student. Aid. gov/public service 23
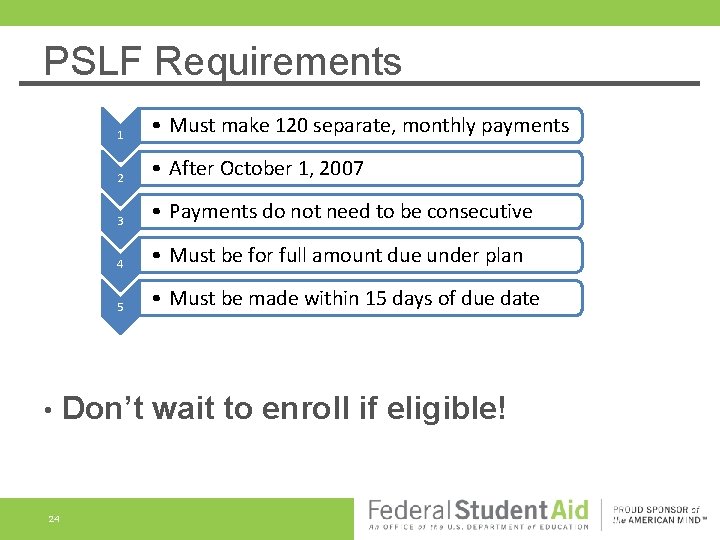
PSLF Requirements • 24 1 • Must make 120 separate, monthly payments 2 • After October 1, 2007 3 • Payments do not need to be consecutive 4 • Must be for full amount due under plan 5 • Must be made within 15 days of due date Don’t wait to enroll if eligible!
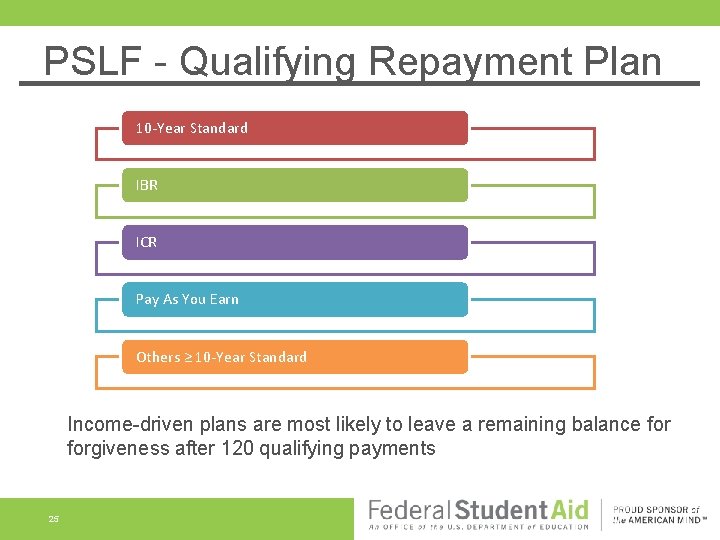
PSLF - Qualifying Repayment Plan 10 -Year Standard IBR ICR Pay As You Earn Others ≥ 10 -Year Standard Income-driven plans are most likely to leave a remaining balance forgiveness after 120 qualifying payments 25
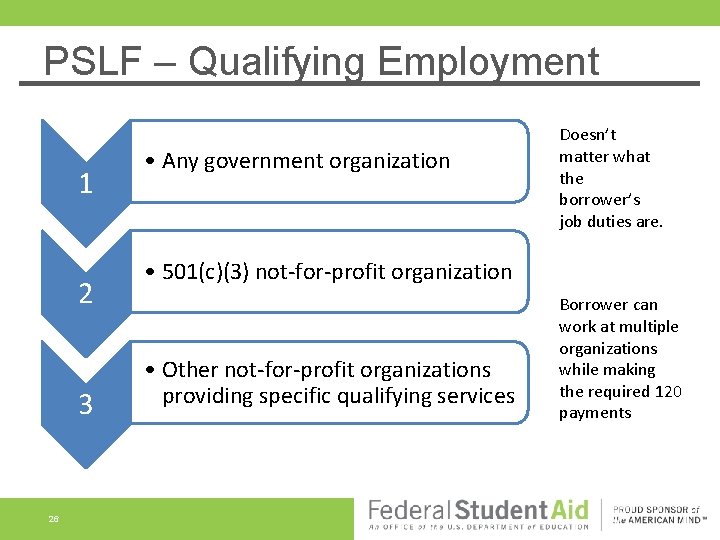
PSLF – Qualifying Employment 1 2 3 26 • Any government organization Doesn’t matter what the borrower’s job duties are. • 501(c)(3) not-for-profit organization • Other not-for-profit organizations providing specific qualifying services Borrower can work at multiple organizations while making the required 120 payments
www. studentloans. gov/repay 27
28
Repayment Estimator www. studentaid. gov/repay 29
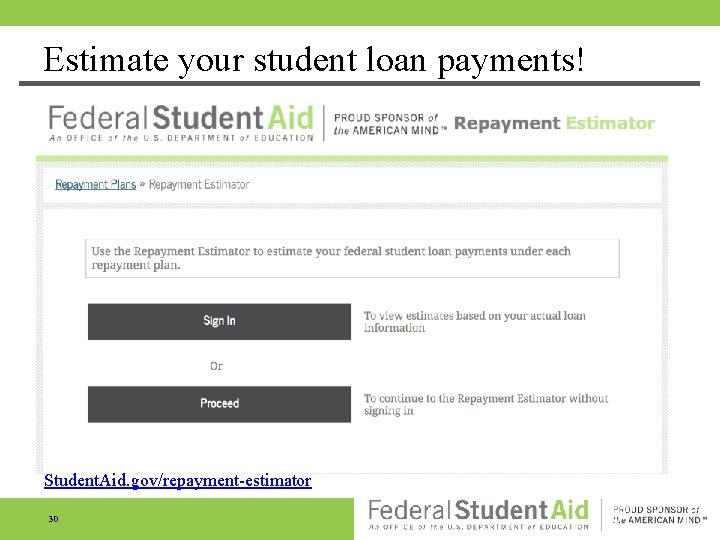
Estimate your student loan payments! Student. Aid. gov/repayment-estimator 30
Postponing Payment, Avoiding Default, Loan Discharge and Forgiveness
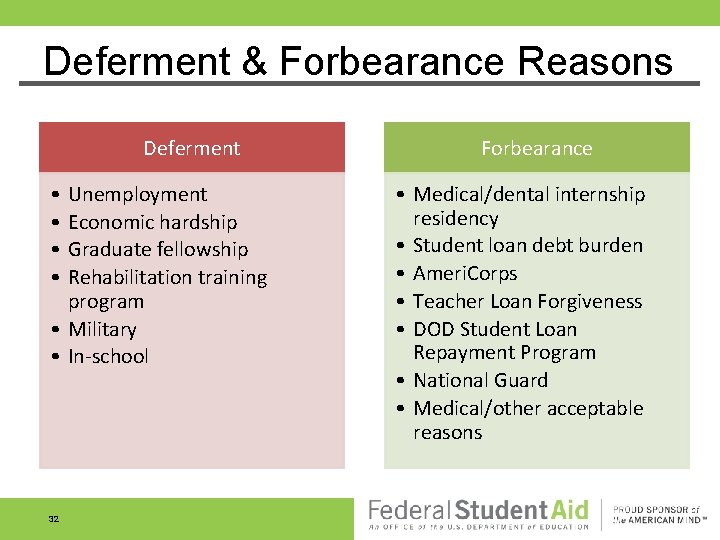
Deferment & Forbearance Reasons Deferment • • Unemployment Economic hardship Graduate fellowship Rehabilitation training program • Military • In-school 32 Forbearance • Medical/dental internship residency • Student loan debt burden • Ameri. Corps • Teacher Loan Forgiveness • DOD Student Loan Repayment Program • National Guard • Medical/other acceptable reasons
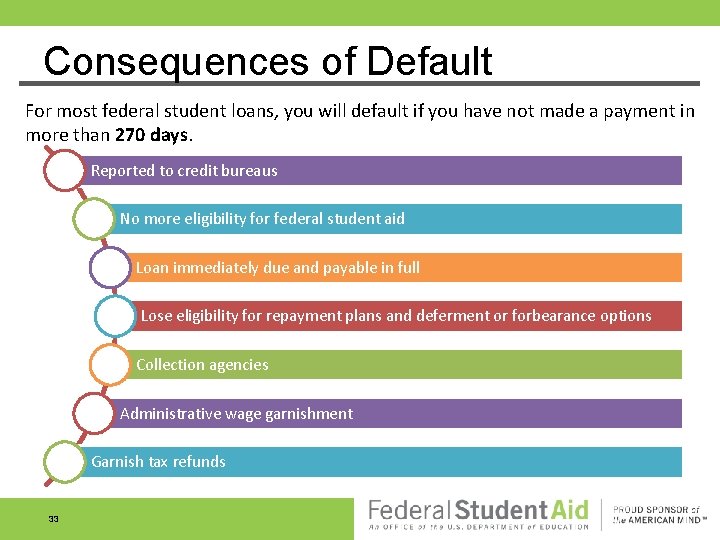
Consequences of Default For most federal student loans, you will default if you have not made a payment in more than 270 days. Reported to credit bureaus No more eligibility for federal student aid Loan immediately due and payable in full Lose eligibility for repayment plans and deferment or forbearance options Collection agencies Administrative wage garnishment Garnish tax refunds 33
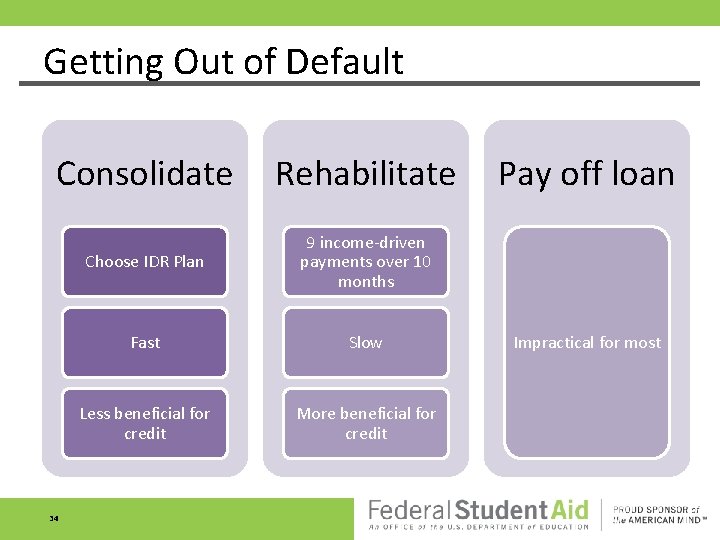
Getting Out of Default Consolidate Rehabilitate Choose IDR Plan 9 income-driven payments over 10 months Fast Slow Less beneficial for credit More beneficial for credit 34 Pay off loan Impractical for most
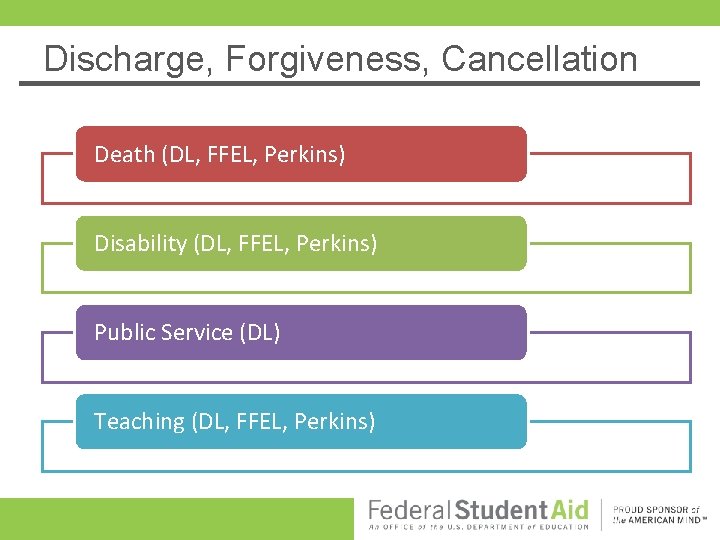
Discharge, Forgiveness, Cancellation Death (DL, FFEL, Perkins) Disability (DL, FFEL, Perkins) Public Service (DL) Teaching (DL, FFEL, Perkins)
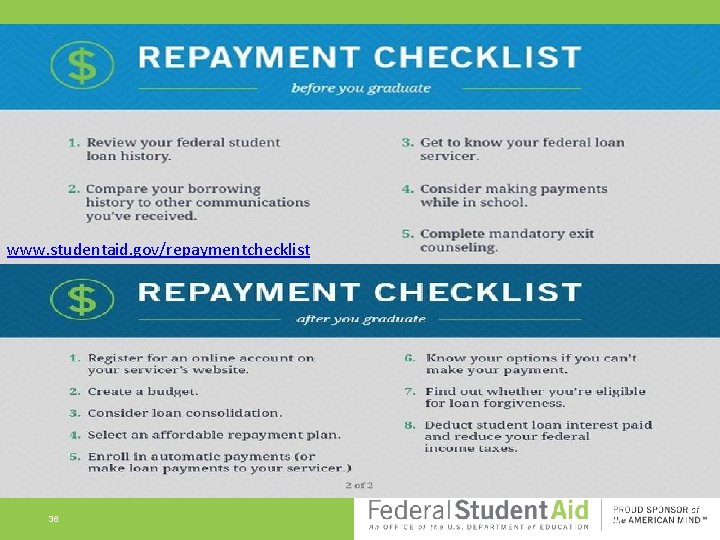
www. studentaid. gov/repaymentchecklist 36
Federal Student Aid Resources 37
Student. Aid. gov 38
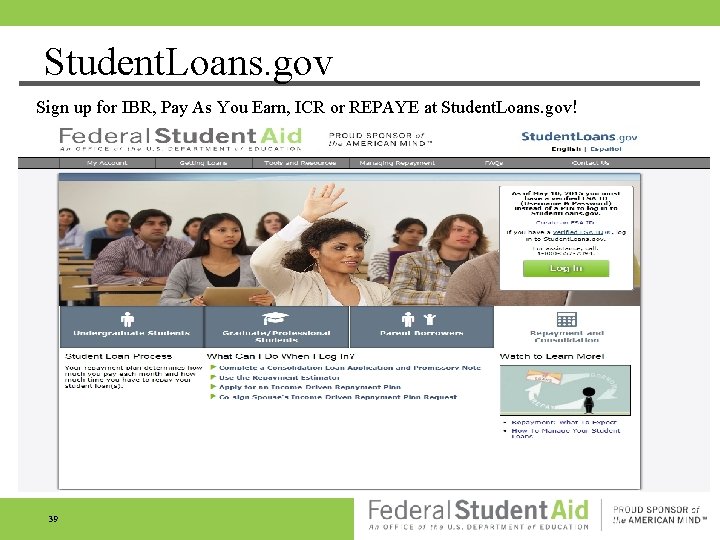
Student. Loans. gov Sign up for IBR, Pay As You Earn, ICR or REPAYE at Student. Loans. gov! 39
NSLDS. ed. gov
Questions? • Contact your loan servicer. • If you do not know who you loan servicer is, visit NSLDS at nslds. ed. gov Federal Student Aid Information Center (FSAIC) 1800 -4 -FEDAID (1 -800 -433 -3243) 41