
Everything You Always Wanted to Know About Business
Everything You Always Wanted to Know About Business Insurance and the Implications for Disaster Recovery But Were Afraid to Ask! September 9, 2014 Jim Gleaves Managing Director Wortham, L. L. C. , General Partner John L. Wortham & Son, L. P.
Father Guido Sarducci The Five Minute University 2
Agenda • Insurance Industry Landscape – Chips, Guacamole & Queso • Risk Management – The Whole Enchilada • Commercial Property / Casualty – Fajitas – but no Rice and Beans • Business Continuity and Insurance – The Tres Leches Cake 3
A Partnership That Works • Placing over $1 billion in premiums annually • Texas based since 1915 • Over 500 professionals • Wortham is the largest insurance agency headquartered in Texas, with offices in Houston, Fort Worth, Austin, San Antonio and Dallas • A Limited Partnership owned by 120 Managing Directors • Approximately half of our Managing Directors are technical staff 4
The Commercial P&C Insurance Industry • Insureds • Brokers or Agents – Retail – Wholesale – Bermuda and Lloyd’s • Insurance Carriers – – Stock Mutuals Captives Admitted vs. Non-Admitted 5
10 Largest U. S. Brokers 1. 2. 3. 4. 5. 6. 7. 8. 9. 10. Aon P. L. C. Marsh & Mc. Lennan Cos. Inc. Arthur J. Gallagher & Co. Willis Group Holdings P. L. C. BB&T Insurance Holdings, Inc. Brown & Brown Inc. Wells Fargo Insurance Services USA Inc. Lockton Cos. L. L. C. USI Holdings Corp. Hub International Ltd. Note: From Business Insurance, based on revenue. 6
10 Largest Property / Casualty Insurance Carriers • • • State Farm Berkshire Hathaway Allstate Liberty Mutual Travelers AIG Nationwide Progressive Farmers USAA Note: From National Underwriters, based on premium volume. 7
Risk Management • Having the policies and procedures in place and understood by all levels within the organization, that are necessary to minimize the probability of a loss • Having structures, such as insurance, hedges, or a plan, such as a crisis management plan, in place that will minimize the impact of a serious adverse incident, loss, or claim 8

Risk Management Why Do Businesses Fail? • Financial failure • Strategic inability to compete • Merger or takeover • Force majeure • Fraud • Loss of key supplier • Loss of key customer 9
Enterprise Risk Management – The Process • Step 1 – Identify risks • Step 2 – Measure and assess risks • Step 3 – Manage risks/response/control • Step 4 – Monitor risks/communication 10
Risk Categories • The world of risk funnels down into three major categories: – Strategic / business risks – Financial risks – Operational risks 11
Methods for Treating Risk • Avoid it • Reduce its likelihood • Reduce its impact • Transfer it 12
What Sets Great Apart From Good? • What risks are emerging? • Do you have the proper controls in place? • Are you well prepared for an event? • Do you have the right people with the right skills? • Are you tracking and measuring your risks with the right tools? • Are you achieving the desired return relative to the risks? 13
A Few Commercial Insurance Concepts • Cyclical business • Insurance carriers operate on thin margins • You pay for your losses over time – Frequency versus Severity • Complexity 14
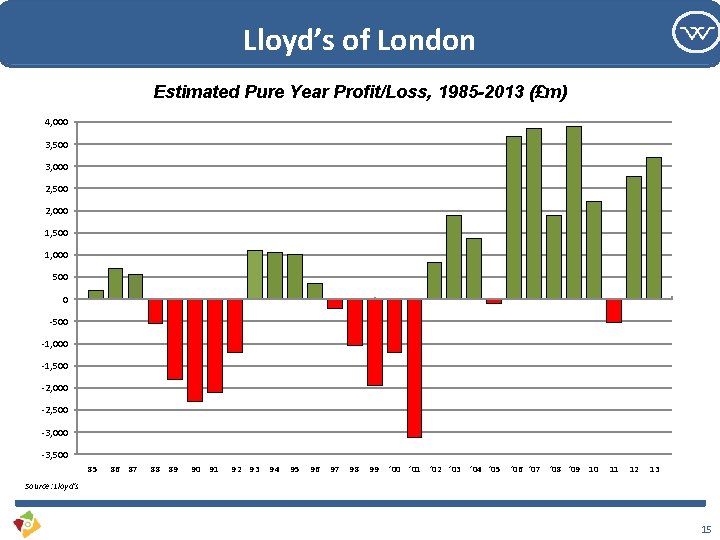
Lloyd’s of London Estimated Pure Year Profit/Loss, 1985 -2013 (£m) 4, 000 3, 500 3, 000 2, 500 2, 000 1, 500 1, 000 500 0 -500 -1, 000 -1, 500 -2, 000 -2, 500 -3, 000 -3, 500 85 86 87 88 89 90 91 92 93 94 95 96 97 98 99 ’ 00 ’ 01 ’ 02 ’ 03 ’ 04 ’ 05 ’ 06 ’ 07 ’ 08 ’ 09 10 11 12 13 Source: Lloyd’s 15
Commercial Insurance Categories - Property • Real Property / Business Personal Property • Boiler & Machinery • Builder’s Risk • Energy Package • Flood Insurance • Business Income / Extra Expense • Contingent Business Income 16
Commercial Insurance Categories - Casualty • General Liability • Auto Liability • Workers’ Compensation • Pollution / Aviation • Excess Liability / Umbrella 17
Commercial Insurance Categories – Professional Liability • Directors & Officers • Employment Practices • Crime / Fiduciary • Cyber • Other Professional 18
Other Commercial Insurance Categories • BOP – Business Owner Policies • Marine and Inland Marine • Farm & Ranch • Credit Insurance • Event Cancellation • Alternative / Financial 19
Four Important Coverage Parameters/Measurements • Exposure • Retention • Limits • The Total Cost of Risk 20
Exposure Evaluation • Probably the single most important task in risk management • Many exposures are obvious • The challenge – determine the less obvious exposures – Surveys and Questionnaires – Black Swan Theorizing 21
Retention Analysis Typically, three variables should be considered in developing retention levels: • Risk Appetite - Determine the financial strengths and operating philosophies unique to each company. • Loss Profile - Analyze loss trends and translate the analysis into projections. • Market Environment - Weigh the trade-off in premium cost against the potential liabilities associated with the retention level. 22
Property Loss Limits • Specific, Scheduled or Agreed limits Separate limits that apply to each type of property at each location based on a schedule of values supplied to underwriters or actually listed on the policy. • Blanket limit A single limit of insurance that applies over more than one location or more than one category of property coverage, or both. This is in contrast to specific or scheduled limits of insurance, which are separate limits that apply to each type of property at each location. The full blanket limit can be utilized for a single location loss. • Loss limit The maximum amount a carrier will pay in a single occurrence. This limit is typically lower than the total values reported and is normally tied back to values on the schedule provided to underwriters. 23
Limits Analysis Casualty and Professional Indemnity • Potential loss level • Industry experience / surveys • Benchmarking 24
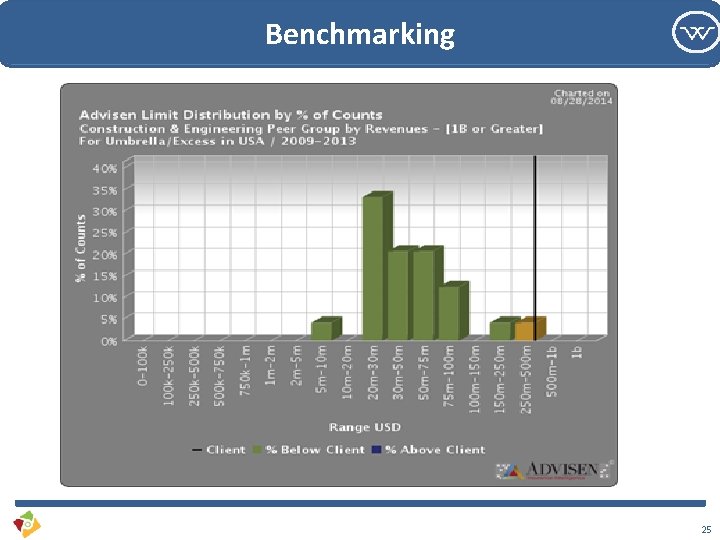
Benchmarking 25
The Total Cost of Risk The total cost of risk is one of the most important measurements in risk management. It is comprised of: • Retained losses • Cost of risk transfer (insurance) • Cost of insurance services 26
Duties in the Event of Loss or Damage • • Notify the police Give the insurer prompt notice Provide information Take all reasonable steps to protection the property from further loss Furnish the insurer with inventories of the damaged and undamaged property Submit to examination under oath Cooperate Send a signed, sworn proof of loss to the insurer within sixty days after the insurer requests one 27
Claims Handling • Small businesses - May have claims handled by the carrier’s in-house adjuster • Large businesses - Could have the benefit of a broker’s claims professionals • Very large or complex claims - third party adjusters or forensic accounting firms may be engaged 28
Business Continuity and Insurance STEP ONE: Identify Risks STEP TWO: Run Like Crazy! 29
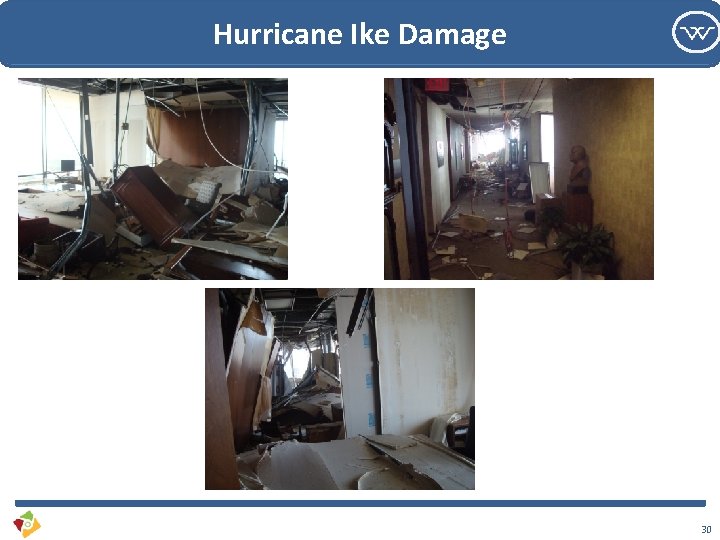
Hurricane Ike Damage 30
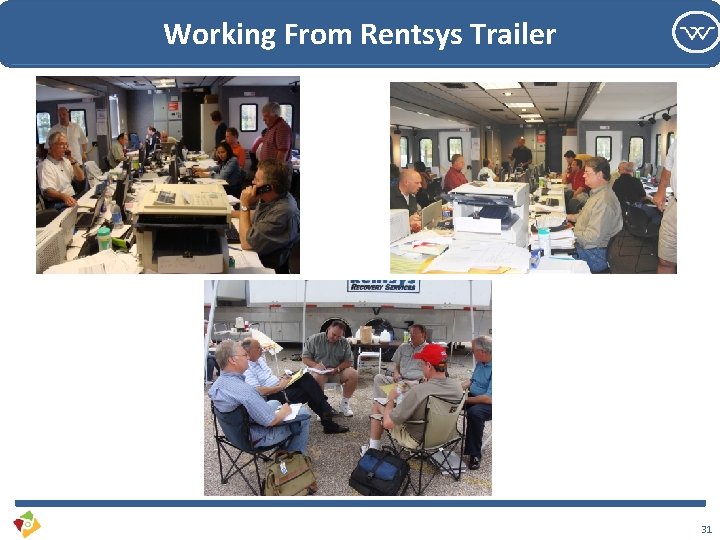
Working From Rentsys Trailer 31
Business Continuity and Insurance The Tres Leche Cake Remember Business Income/Extra Expense coverage? What did the Rentsys Mobile Recovery unit cost Wortham after Hurricane Ike? 32
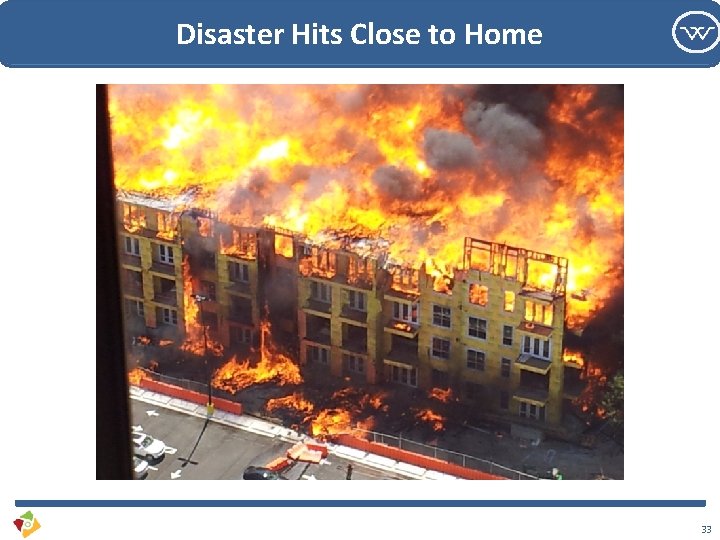
Disaster Hits Close to Home 33
- Slides: 33