
Evaluating Financial Institution Financial Condition NCLGIA Summer Conference
- Slides: 32
Evaluating Financial Institution Financial Condition NCLGIA Summer Conference 2014 The NC Capital Management Trust K. Lee Carter Gary Porter
Background • Government is making a loan to the depository • Insurance and collateralization are backup systems See discussion from Policies Manual Some risks of under-collateralization (although slight) Reputational risk May take time to fully recover insured and collateralized funds – government may have liquidity problems – Make sure that accounts are coded as public funds accounts – No brokered deposits – File INV-91 • – – –
Background (cont. ) • Government should select a sound financial institution as a depository – Should be evaluated during selection process – Ongoing evaluation of financial condition required – Note: see slide on continuous monitoring
Department of State Treasurer – Policy Manual for Local Governments Section 30: Cash and Investments Part II – Procurement of Banking Services b. Financial Criteria Periodically, concern is raised by units of government concerning the financial soundness of banks and savings institutions. This concern may arise because of changes in economic conditions or from unsound banking practices. It is important that the units assess the financial strength of the institutions with which they regularly transact business. To that end, the staff of the Department of State Treasurer has outlined various methods of analysis to help units obtain a better understanding of the financial position of banks and savings institutions. The areas that will be covered are merely guidelines and do not represent an all-inclusive analysis of a particular institution. These are presented in Exhibit D – Guidelines for Evaluation of the Soundness of a Financial Institution.
Department of State Treasurer – Policy Manual for Local Governments Section 30: Cash and Investments Part II – Procurement of Banking Services One may ask why a financial institution should be analyzed if the local government is properly insured or collateralized with respect to its deposits and investments. The staff of the Department of State Treasurer strongly urges units to place the soundness of a financial institution ahead of collateralization or insurance. Even when deposits of a unit are adequately protected by insurance or collateralization, a significant amount of time may be required before public funds are completely recovered; consequently, a unit may have liquidity problems if it needs immediate access to funds. This means that first level of protection for having funds available when needed is to place public funds only with financially-sound institutions. A unit is making a loan to a financial institution when it deposits funds and should ensure that all financial institutions utilized are financially sound.
Department of State Treasurer – Policy Manual for Local Governments Section 30: Cash and Investments Part II – Procurement of Banking Services 6. Continuous Monitoring of Safety and Soundness of Financial Partners After a bank is selected, the contract awarded and transition completed, it is important to continue to monitor both performance under the terms of the contract and the safety and soundness of banks and other financial institutions transacting business with the unit. An evaluation of the financial condition should be performed no less frequently than annually and quarterly evaluation is encouraged.
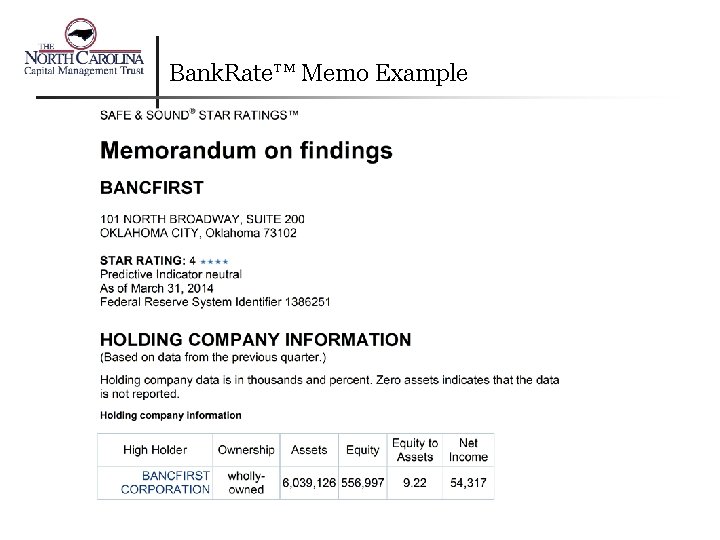
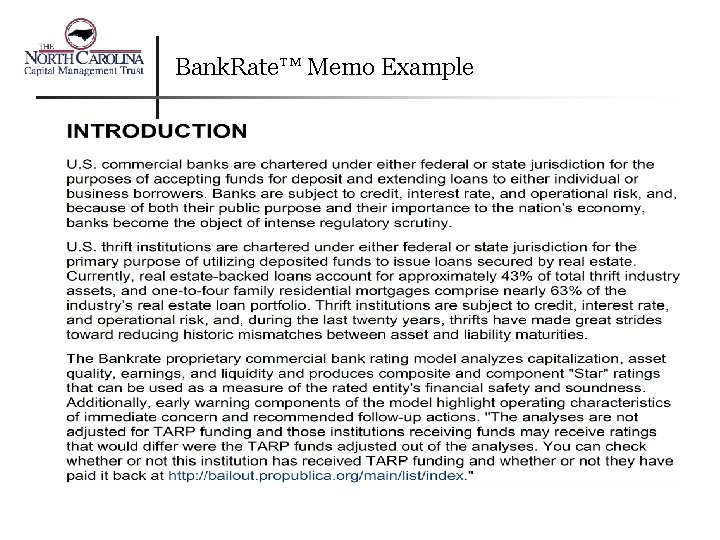
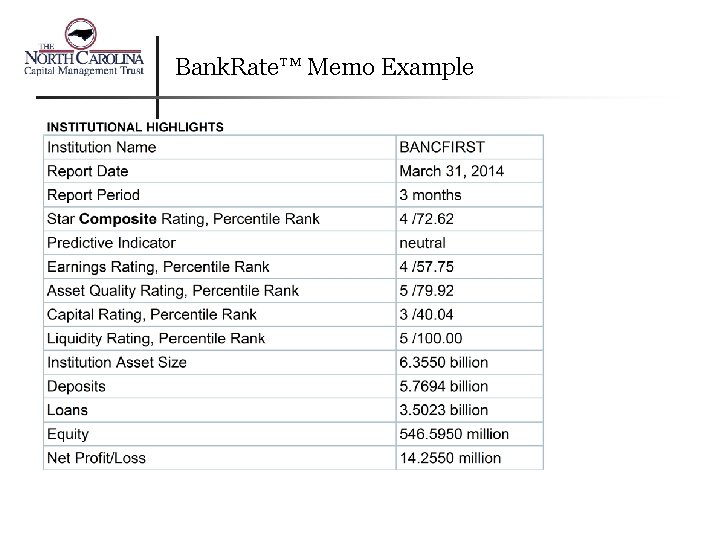
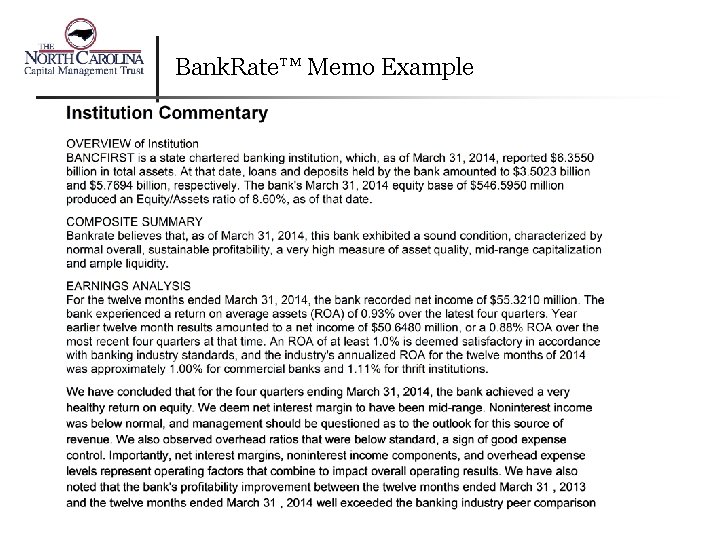
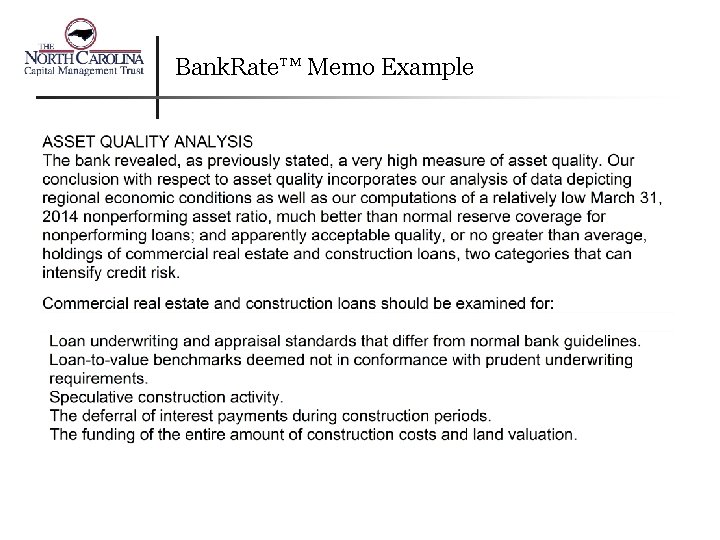
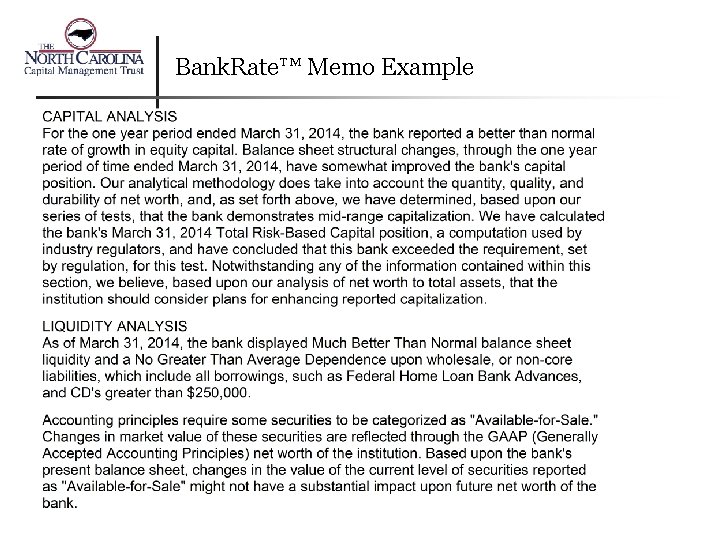
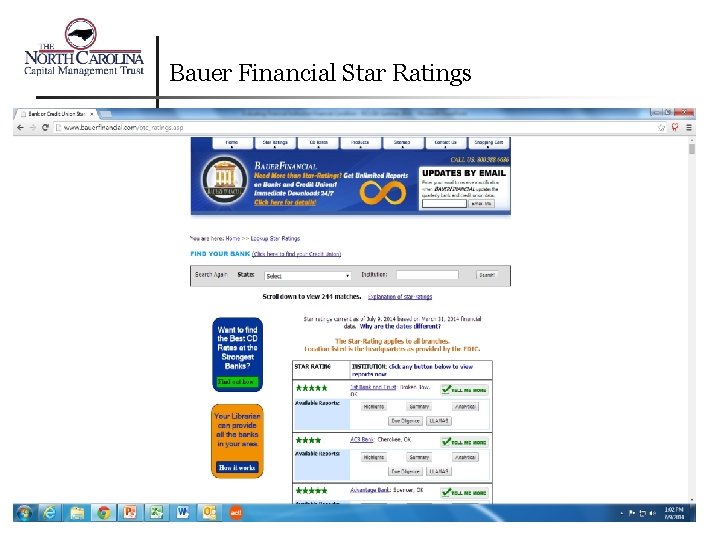
Sources of Information • FDIC (fdic. gov) – for individual credit analysis – Can access Uniform Bank Performance Reports from the Federal Financial Institutions Examinations Council (www. ffiec. gov) • Comptroller of the Currency, NC Commissioner of Banks, etc. • Rating agencies (Moody’s, S&P, Fitch) • Independent agencies – Bauer Financial • Star ratings – Bank Rate. com • Star ratings • Financial statement statistics • See Policies Manual for contact information
LGC’s Recommended Objectives • • Capital adequacy Earnings Problem loan experience Liquidity • Look at trend analysis over a multi-year period
Trend Analysis • • Growth in equity (hopefully from profit) Earnings growth Growth in problem loans Asset Growth
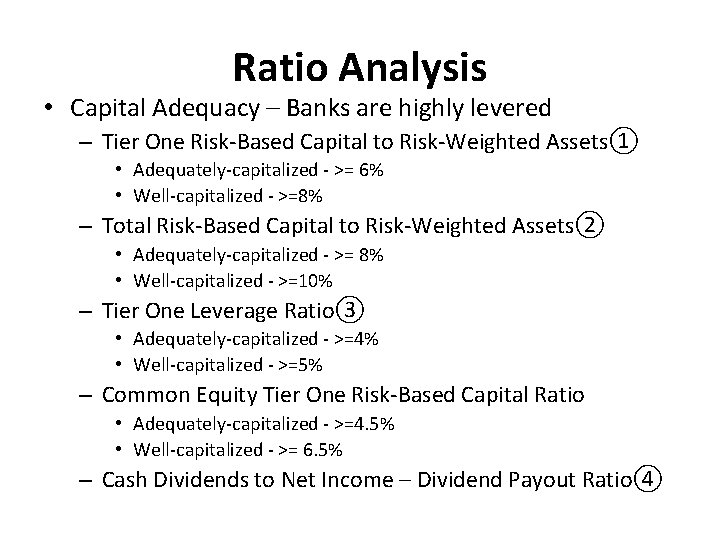
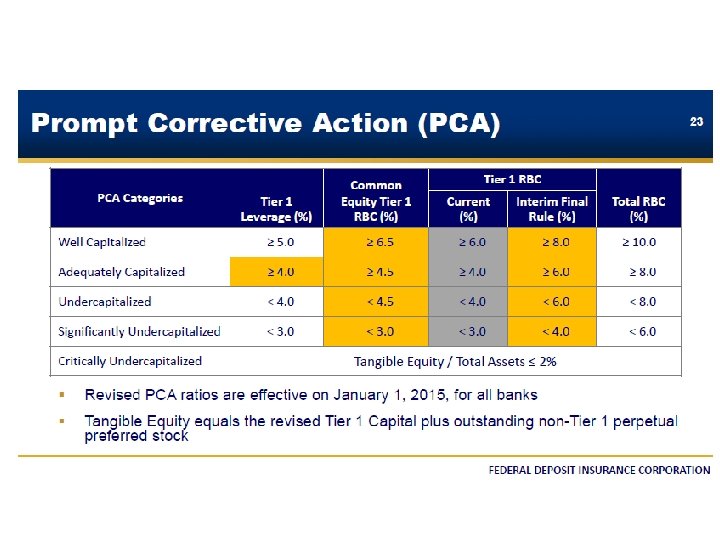
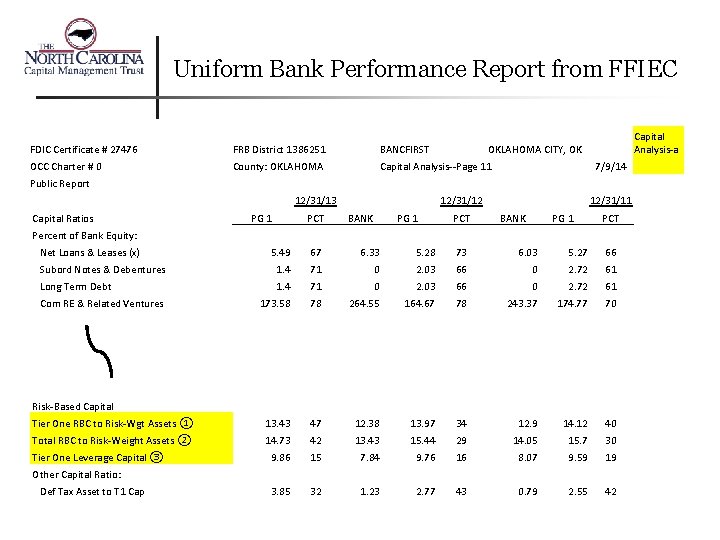
Ratio Analysis • Capital Adequacy – Banks are highly levered – Tier One Risk-Based Capital to Risk-Weighted Assets① • Adequately-capitalized - >= 6% • Well-capitalized - >=8% – Total Risk-Based Capital to Risk-Weighted Assets② • Adequately-capitalized - >= 8% • Well-capitalized - >=10% – Tier One Leverage Ratio③ • Adequately-capitalized - >=4% • Well-capitalized - >=5% – Common Equity Tier One Risk-Based Capital Ratio • Adequately-capitalized - >=4. 5% • Well-capitalized - >= 6. 5% – Cash Dividends to Net Income – Dividend Payout Ratio④
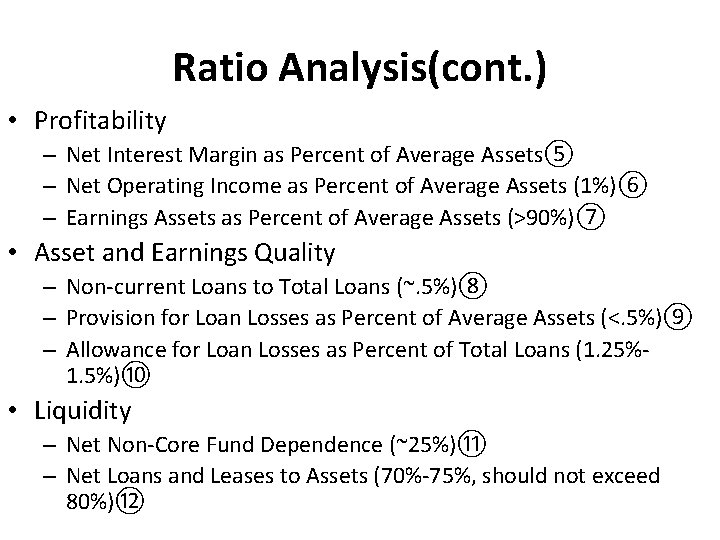
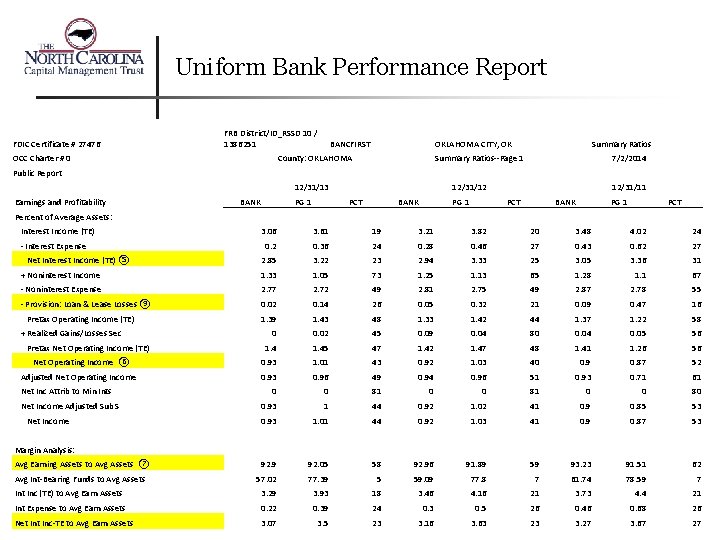
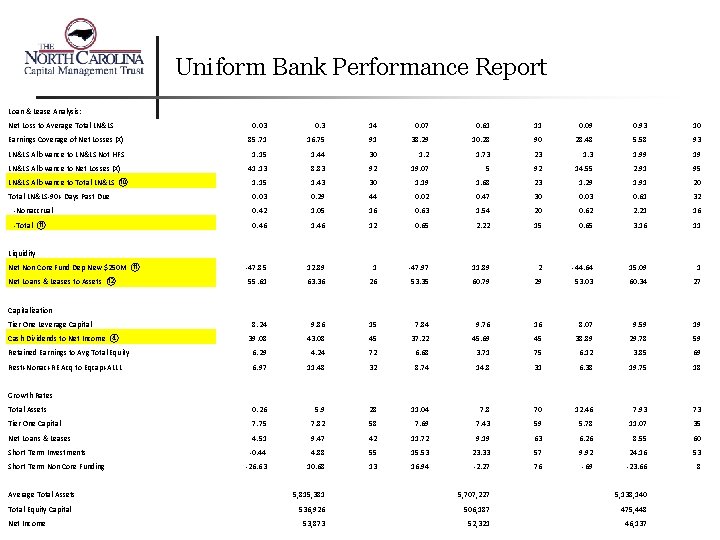
Ratio Analysis(cont. ) • Profitability – Net Interest Margin as Percent of Average Assets⑤ – Net Operating Income as Percent of Average Assets (1%)⑥ – Earnings Assets as Percent of Average Assets (>90%)⑦ • Asset and Earnings Quality – Non-current Loans to Total Loans (~. 5%)⑧ – Provision for Loan Losses as Percent of Average Assets (<. 5%)⑨ – Allowance for Loan Losses as Percent of Total Loans (1. 25%1. 5%)⑩ • Liquidity – Net Non-Core Fund Dependence (~25%)⑪ – Net Loans and Leases to Assets (70%-75%, should not exceed 80%)⑫
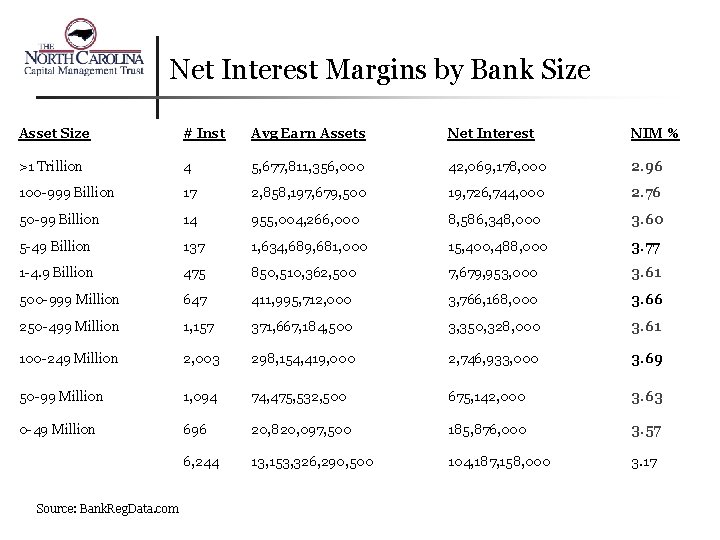
Net Interest Margins by Bank Size Asset Size # Inst Avg Earn Assets Net Interest NIM % >1 Trillion 4 5, 677, 811, 356, 000 42, 069, 178, 000 2. 96 100 -999 Billion 17 2, 858, 197, 679, 500 19, 726, 744, 000 2. 76 50 -99 Billion 14 955, 004, 266, 000 8, 586, 348, 000 3. 60 5 -49 Billion 137 1, 634, 689, 681, 000 15, 400, 488, 000 3. 77 1 -4. 9 Billion 475 850, 510, 362, 500 7, 679, 953, 000 3. 61 500 -999 Million 647 411, 995, 712, 000 3, 766, 168, 000 3. 66 250 -499 Million 1, 157 371, 667, 184, 500 3, 350, 328, 000 3. 61 100 -249 Million 2, 003 298, 154, 419, 000 2, 746, 933, 000 3. 69 50 -99 Million 1, 094 74, 475, 532, 500 675, 142, 000 3. 63 0 -49 Million 696 20, 820, 097, 500 185, 876, 000 3. 57 6, 244 13, 153, 326, 290, 500 104, 187, 158, 000 3. 17 Source: Bank. Reg. Data. com
Uniform Bank Performance Report from FFIEC FDIC Certificate # 27476 FRB District 1386251 BANCFIRST OCC Charter # 0 County: OKLAHOMA Capital Analysis--Page 11 Capital Analysis-a OKLAHOMA CITY, OK 7/9/14 Public Report 12/31/13 Capital Ratios PG 1 PCT 12/31/12 BANK PG 1 PCT 12/31/11 BANK PG 1 PCT Percent of Bank Equity: Net Loans & Leases (x) 5. 49 67 6. 33 5. 28 73 6. 03 5. 27 66 Subord Notes & Debentures 1. 4 71 0 2. 03 66 0 2. 72 61 Long Term Debt 1. 4 71 0 2. 03 66 0 2. 72 61 173. 58 78 264. 55 164. 67 78 243. 37 174. 77 70 Tier One RBC to Risk-Wgt Assets ① 13. 43 47 12. 38 13. 97 34 12. 9 14. 12 40 Total RBC to Risk-Weight Assets ② 14. 73 42 13. 43 15. 44 29 14. 05 15. 7 30 9. 86 15 7. 84 9. 76 16 8. 07 9. 59 19 3. 85 32 1. 23 2. 77 43 0. 79 2. 55 42 Com RE & Related Ventures Risk-Based Capital Tier One Leverage Capital ③ Other Capital Ratio: Def Tax Asset to T 1 Cap
Uniform Bank Performance Report FDIC Certificate # 27476 FRB District/ID_RSSD 10 / 1386251 OCC Charter # 0 BANCFIRST OKLAHOMA CITY, OK County: OKLAHOMA Summary Ratios--Page 1 7/2/2014 Public Report 12/31/13 Earnings and Profitability BANK PG 1 12/31/12 PCT BANK PG 1 12/31/11 PCT BANK PG 1 PCT Percent of Average Assets: Interest Income (TE) - Interest Expense 3. 06 3. 61 19 3. 21 3. 82 20 3. 48 4. 02 24 0. 2 0. 36 24 0. 28 0. 46 27 0. 43 0. 62 27 2. 85 3. 22 23 2. 94 3. 33 25 3. 05 3. 36 31 + Noninterest Income 1. 33 1. 05 73 1. 25 1. 13 65 1. 28 1. 1 67 - Noninterest Expense 2. 77 2. 72 49 2. 81 2. 75 49 2. 87 2. 78 55 - Provision: Loan & Lease Losses ⑨ 0. 02 0. 14 26 0. 05 0. 32 21 0. 09 0. 47 16 1. 39 1. 43 48 1. 33 1. 42 44 1. 37 1. 22 58 Net Interest Income (TE) ⑤ Pretax Operating Income (TE) + Realized Gains/Losses Sec 0 0. 02 45 0. 09 0. 04 80 0. 04 0. 05 56 1. 45 47 1. 42 1. 47 48 1. 41 1. 26 56 0. 93 1. 01 43 0. 92 1. 03 40 0. 9 0. 87 52 0. 93 0. 96 49 0. 94 0. 96 51 0. 93 0. 71 61 0 0 81 0 0 80 0. 93 1 44 0. 92 1. 02 41 0. 9 0. 85 53 0. 93 1. 01 44 0. 92 1. 03 41 0. 9 0. 87 53 Avg Earning Assets to Avg Assets ⑦ 92. 9 92. 05 58 92. 96 91. 89 59 93. 23 91. 51 62 Avg Int-Bearing Funds to Avg Assets 57. 02 77. 39 5 59. 09 77. 8 7 61. 74 78. 59 7 Int Inc (TE) to Avg Earn Assets 3. 29 3. 93 18 3. 46 4. 16 21 3. 73 4. 4 21 Int Expense to Avg Earn Assets 0. 22 0. 39 24 0. 3 0. 5 26 0. 46 0. 68 26 Net Inc-TE to Avg Earn Assets 3. 07 3. 5 23 3. 16 3. 63 23 3. 27 3. 67 27 Pretax Net Operating Income (TE) Net Operating Income ⑥ Adjusted Net Operating Income Net Inc Attrib to Min Ints Net Income Adjusted Sub S Net Income Margin Analysis:
Uniform Bank Performance Report Loan & Lease Analysis: Net Loss to Average Total LN&LS 0. 03 0. 3 14 0. 07 0. 61 11 0. 09 0. 93 10 85. 71 16. 75 91 38. 29 10. 28 90 28. 48 5. 58 93 LN&LS Allowance to LN&LS Not HFS 1. 15 1. 44 30 1. 2 1. 73 23 1. 99 19 LN&LS Allowance to Net Losses (X) 41. 13 8. 83 92 19. 07 5 92 14. 55 2. 91 95 LN&LS Allowance to Total LN&LS ⑩ 1. 15 1. 43 30 1. 19 1. 68 23 1. 29 1. 91 20 Total LN&LS-90+ Days Past Due 0. 03 0. 29 44 0. 02 0. 47 30 0. 03 0. 61 32 -Nonaccrual 0. 42 1. 05 16 0. 63 1. 54 20 0. 62 2. 21 16 -Total ⑪ 0. 46 12 0. 65 2. 22 15 0. 65 3. 16 11 -47. 85 12. 89 1 -47. 97 11. 89 2 -44. 64 15. 09 1 55. 61 63. 36 26 53. 35 60. 79 29 53. 03 60. 34 27 8. 24 9. 86 15 7. 84 9. 76 16 8. 07 9. 59 19 Earnings Coverage of Net Losses (X) Liquidity Net Non Core Fund Dep New $250 M ⑪ Net Loans & Leases to Assets ⑫ Capitalization Tier One Leverage Capital Cash Dividends to Net Income ④ 39. 08 43. 08 45 37. 22 45. 69 45 38. 89 29. 78 59 Retained Earnings to Avg Total Equity 6. 29 4. 24 72 6. 68 3. 71 75 6. 12 3. 85 69 Rest+Nonac+RE Acq to Eqcap+ALLL 6. 97 11. 48 32 8. 74 14. 8 31 6. 38 19. 75 18 Growth Rates Total Assets 0. 26 5. 9 28 11. 04 7. 8 70 12. 46 7. 93 73 Tier One Capital 7. 75 7. 82 58 7. 69 7. 43 59 5. 78 11. 07 35 Net Loans & Leases Short Term Investments Short Term Non Core Funding Average Total Assets Total Equity Capital Net Income 4. 51 9. 47 42 11. 72 9. 19 63 6. 26 8. 55 60 -0. 44 4. 88 55 15. 53 23. 33 57 9. 92 24. 16 53 -26. 63 10. 68 13 16. 94 -2. 27 76 -69 -23. 66 8 5, 815, 381 5, 707, 227 5, 138, 140 536, 926 506, 187 475, 448 53, 873 52, 321 46, 137
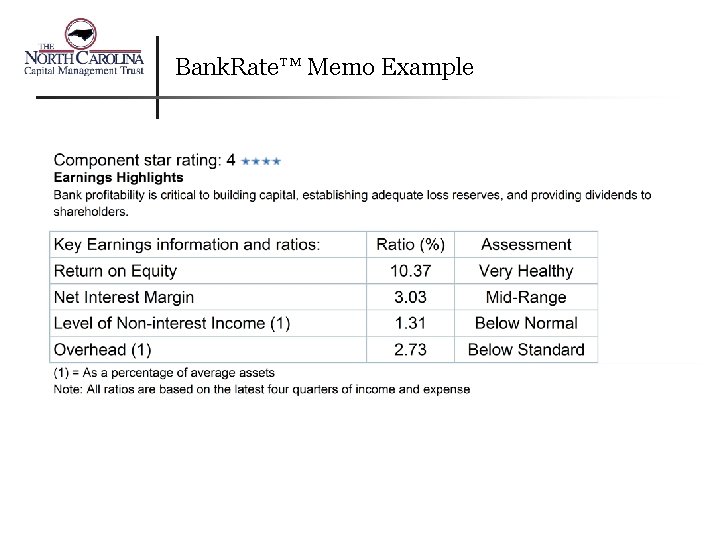
Bank. Rate™ Memo Example
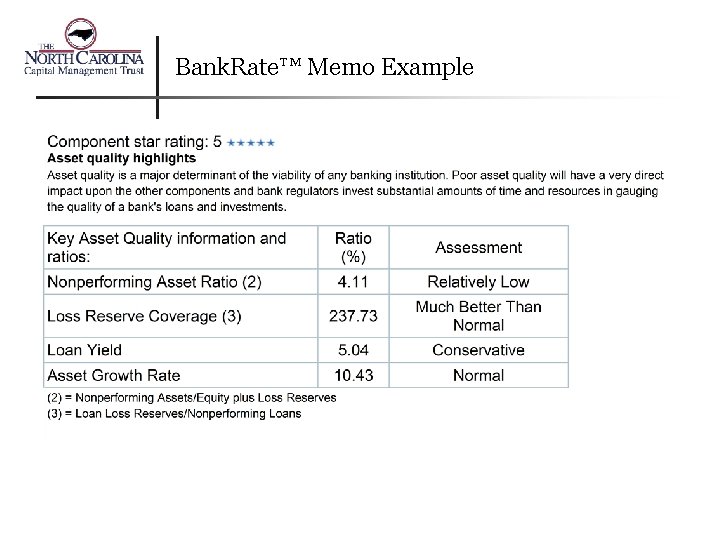
Bank. Rate™ Memo Example
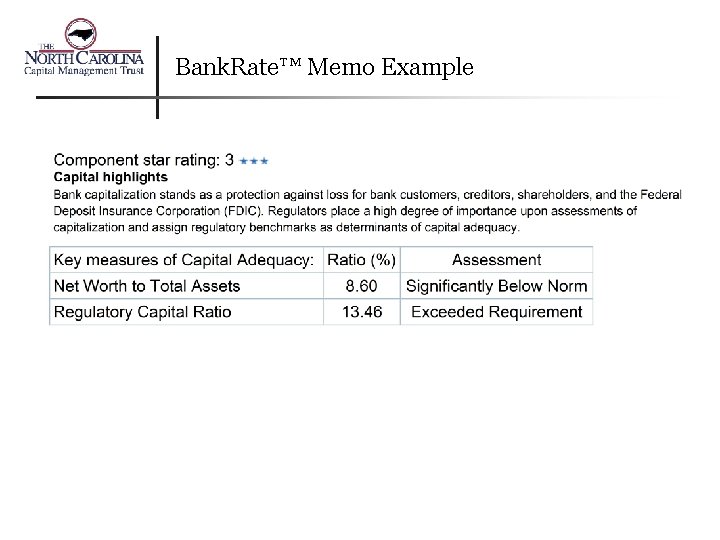
Bank. Rate™ Memo Example
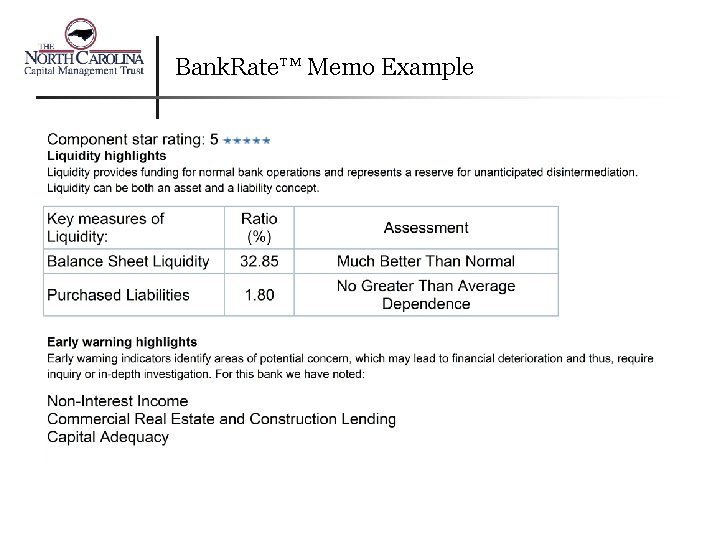
Bank. Rate™ Memo Example
Bank. Rate™ Memo Example
Bank. Rate™ Memo Example
Bank. Rate™ Memo Example
Bank. Rate™ Memo Example
Bank. Rate™ Memo Example
Bank. Rate™ Memo Example
Bauer Financial Star Ratings