
Discussion of Marco del Negro and Frank Schorfheide

- Slides: 25
Discussion of Marco del Negro and Frank Schorfheide’ “Monetary Policy Analysis with Potentially Misspecified Models” Ramon Marimon Universitat Pompeu Fabra & CREi, Barcelona (visiting Ente Einaudi and Luiss University, Rome) Monetary policy and imperfect knowledge ECB conference Würzburg, 14 -15 October 2004 1
A Discussion in honor of The 2004 Nobel Laureates in Economic Science! Finn E. Kydland & Edward C. Prescott 2
What “padre teorico della Banca Centrale Europea” (Sole 24 Ore, Ocotber 12, 2004) would say? 3
st The 1 that Ed would say is… 4
5
With probability. 73 the discussion would end here! Today the “efficient lottery” results in continuation… 6
The 2 nd Of course, 1995 Nobel Laureate Robert Lucas is right, but the issue [between DSGE models and VARs] is not the Lucas critique It’s, as 1975 Nobel Laureate Tjalling Koopmans’s, said “avoid measurement without theory” and [Ed adds] “constraint theory by data & facts” “the ‘minimal SVAR theory’ is not a beautiful theory (as RBC can be)” 7
“What is a beautiful theory? ” 1979 Physics Nobel Laureate Steven Weinberg asks, and says (proper Nobel Laureates only quote other Nobel Laureates!) “Simplicity is part of what I mean by beauty, but it is a simplicity of ideas. . . ” “We are on the track of something universal (…) We do not want to discover a theory that is capable of describing all imaginable kinds of force among particles of nature. Rather we hope for a theory that rigidly will allow us to describe only those forces – gravitational, electroweak, and strong– that actually, as it happens, do exist. This kind of rigidity in our physical theories is part of what we recognize as beauty. ” (Dreams of a Final Theory) 8
Are Del Negro & Schorfheilde building on a “beautiful theory”? 9
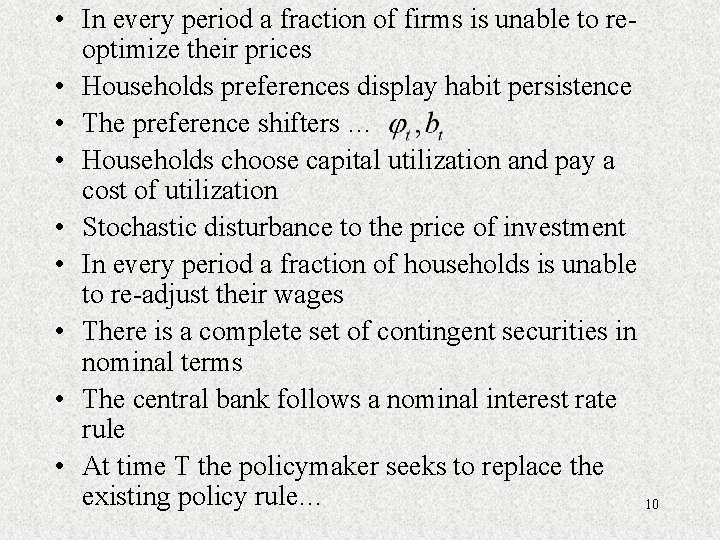
• In every period a fraction of firms is unable to reoptimize their prices • Households preferences display habit persistence • The preference shifters … • Households choose capital utilization and pay a cost of utilization • Stochastic disturbance to the price of investment • In every period a fraction of households is unable to re-adjust their wages • There is a complete set of contingent securities in nominal terms • The central bank follows a nominal interest rate rule • At time T the policymaker seeks to replace the existing policy rule… 10
rd The 3 : Progress, don’t disperse! 11
The 4 th : • Watch your language! • What do you mean by ‘complete markets’ here? • What is your commodity space? • What monetary/banking model do you have? 12
The 5 th : Set an explicit Recursive Dynamic Stochastic General Equilibrium Model! Derive agents and policy rules as functions of the state variables! Then, you can talk more properly of a misspecified model -are we missing a state variable? -are we constraining policy rules? -do agents’ Perceived Law of Motion differ from the Actual Law of Motion? [sorry, this is not Ed’s language!] 13
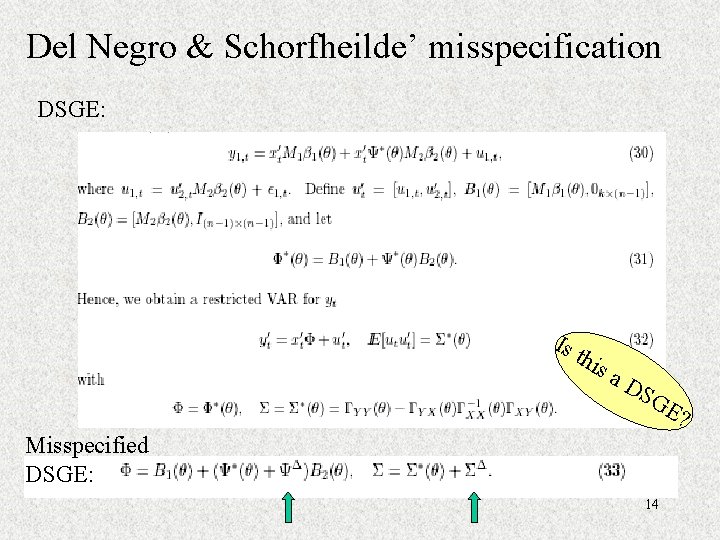
Del Negro & Schorfheilde’ misspecification DSGE: Is thi s a D SG Misspecified DSGE: 14 E?
Can we deconstruct? • Where is the misspecification in the original model? • Are we missing a state variable? • Does the AR representation of decision rules require long lags? “The hyperparameter , determining the length of the sample scales the variance of the discrepancy. Large values of , correspond to small model misspecification” with small you are likely to misspecify your decision rules! (Chari-Kehoe-Mc. Grattan dixit) 15
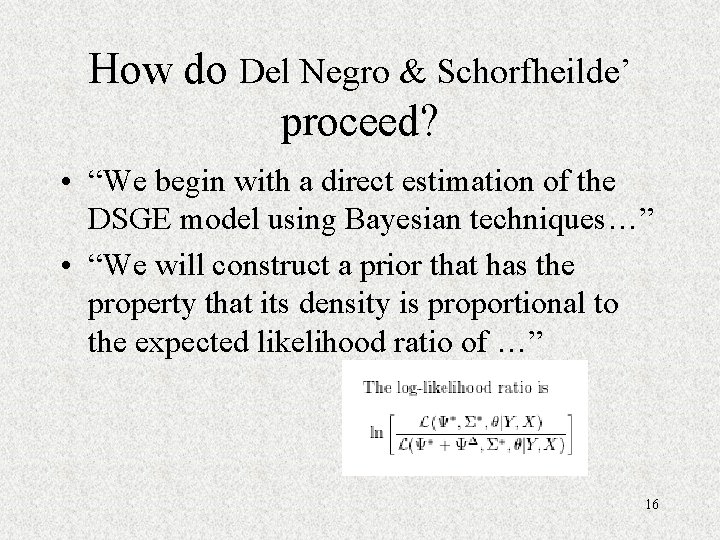
How do Del Negro & Schorfheilde’ proceed? • “We begin with a direct estimation of the DSGE model using Bayesian techniques…” • “We will construct a prior that has the property that its density is proportional to the expected likelihood ratio of …” 16
th The 6 Calibrate, don’t Bayess! a Minnesota discussion with will follow It will be: truly misspecified inarticulate and suddenly interrupted! 17
. . . only understood by 18
and Ed, looking would say th The 7 ! Don’t you have a problem with your Likelihood being too flat? 19
and Del Negro & Schorfheilde • “We conclude that over the range of historical sample the DSGE model is strongly dominated by the DSGE-VARs with intermediate values of indicating that the structural model is to some extent misspecified” 20
(from an Arizona Sunset) Ed would say: The 8 th Misspecified or Mesmerized? Why don’t you check first your DSGE-VARs with the data generated by the DSGE as those guys, still at Minnesota, do? 21
But Nobel Laureates must behave! (well, some appear in airline comercials, others write non-sense anti-G books!) The 9 th: What’s the point? (Lucas would say: Where is the meat? ) That while the DSGE may recommend a stronger response to inflation movements, the ‘better fit’ (optimal) misspecified DSGE-VAR will not recommend a strong response, when the ‘policymaker’ allows for more feedback from sample information (Scenarios 3 &4)? 22
23
Finally, being here, the “ padre teorico della Banca Centrale Europea” would conclude The 10 th : The ECB should • definitively use “rules rather than discretion” • follow the scientific method for policy design • support “economics science” research (as the Mpls FED!) 24
And Ed, the now proper Nobel Laureate, would say Thank you! 25