
Deductions from Gross Total Income Faiza Bhatti 09
Deductions from Gross Total Income
Faiza Bhatti- 09 Rez
Introduction Provided by the Income Tax Act, 1961. Contained in the form of deductions from section 80 C to 80 CCD. They are the permissible amount by which the gross total income is reduced to arrive at the total income liable to tax. They are intended to act as incentive to the assesses for achieving certain economic objectives.
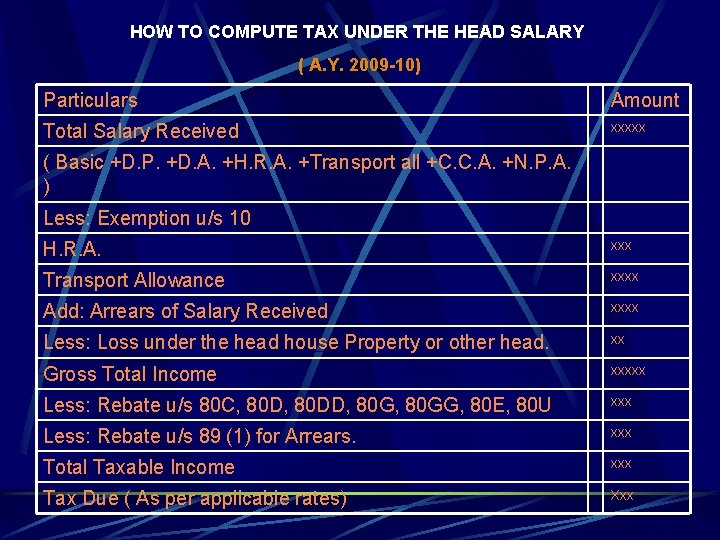
HOW TO COMPUTE TAX UNDER THE HEAD SALARY ( A. Y. 2009 -10) Particulars Amount Total Salary Received xxxxx ( Basic +D. P. +D. A. +H. R. A. +Transport all +C. C. A. +N. P. A. ) Less: Exemption u/s 10 H. R. A. xxx Transport Allowance xxxx Add: Arrears of Salary Received xxxx Less: Loss under the head house Property or other head. xx Gross Total Income xxxxx Less: Rebate u/s 80 C, 80 DD, 80 GG, 80 E, 80 U xxx Less: Rebate u/s 89 (1) for Arrears. xxx Total Taxable Income xxx Tax Due ( As per applicable rates) Xxx
Basic Rules Rule 1 The aggregate amount of deductions under sections 80 C to 80 U cannot exceed gross total income. Rule 2 These deductions are to be allowed only if the assesses claims these and gives the proof of such investments/ expenditure/ income.
Categories of Deductions 1. To encourage savings 2. For certain personal expenditure 3. For socially desirable activities 4. For physically disabled persons
Deduction u/s 80 C From AY 2007 -08 onwards. Applicable only to Individual & HUF. This section provides for deduction in respect of certain expenditure/ investments paid or deposited by the assesses in the previous year.
Computation of deduction u/s 80 C Step 1 - Gross qualifying amount Step 2 - Amount of deduction
The gross qualifying amount under this section refer to the payment/investment under some of the following schemes: Life Insurance Premium Paid. Deferred Annuity Contract. Statutory Provident Fund and Recognized Provident Fund. 15 Year Public Provident Fund. Approved Superannuation Fund. National Savings Certificates. Unit-linked Insurance Plan (Ulip). Dhanraksha Plan of LIC Mutual Fund. Jeevan Dhara, Jeevan Akshay, New Jeevan Dhara. Notified Units of Mutual Fund or UTI.
Amount of Deduction Gross qualifying amount; or Rs-100000 Whichever is lower ü It may be noted that the amount of deduction u/s 80 C, 80 CCC and 80 CCD cannot be exceed Rs. 100000
Deduction u/s 80 CCC Deduction in respect of Contribution to Certain Pension Funds. Individual Eligible Amount – amount paid/deposited under an annuity plan of the Life Insurance Corporation of India or any other insurer for receiving pension.
Conditions Taxable income. This must not be allowed as deduction u/s 80 C. Any amount withdrawn or pension received from the plan is taxable in the hands of the assessee or nominee in the year of receipt. Amount of Deduction Amount paid or Rs. 10, 000/- whichever is lower.
Deduction u/s 80 CCD Deduction in Respect of Contribution to Pension Scheme of Central Government. Individual who is an employee of Central Government on or after 1. 1. 2004. Eligible Amount – Deposit made under a pension scheme notified by the Central Government.
Conditions No deduction must have been claimed u/s 80 C. Any amount received from the scheme, is taxable in the hands of the assess in that year or receipt. Salary for the purpose of this section includes dearness allowance if under the terms of employment. Amount of Deduction Aggregate of amount deposited by the employee and the Central government, or 10% of the salary, whichever is lower.
The aggregate amount of deductions under 80 C, 80 CCC and 80 CCD put together cannot exceed Rs. 1, 000
Deduction u/s 80 G Deduction in respect to donation to certain funds Available to any taxpayer (Individual, Company, Firm or any other person)
Conditions Donation not necessarily come out of income chargeable to tax Donation made without any material return Cheques issued on 31 march 2006 for donation and realized in April are treated as relevant to A. Y-06 -07
Steps Gross qualifying amount Any Donation excluding made in kind Net qualifying amount 10% of the gross total income of assessee deducting following: 1) Amount deductable u/s 80 C to 80 U (but not u/s 80 G) 2) Long term capital gain 3) Short-term capital gain taxable u/s 11 A 4) such income on which income tax is not payable
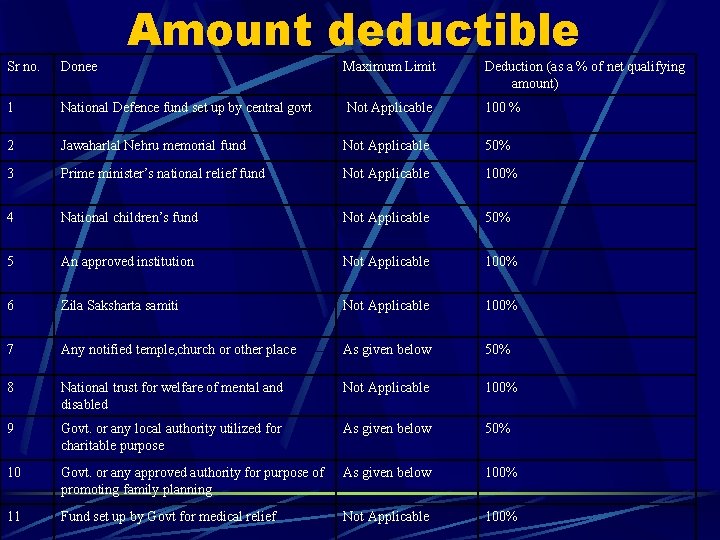
Amount deductible Sr no. Donee Maximum Limit Deduction (as a % of net qualifying amount) 1 National Defence fund set up by central govt Not Applicable 100 % 2 Jawaharlal Nehru memorial fund Not Applicable 50% 3 Prime minister’s national relief fund Not Applicable 100% 4 National children’s fund Not Applicable 50% 5 An approved institution Not Applicable 100% 6 Zila Saksharta samiti Not Applicable 100% 7 Any notified temple, church or other place As given below 50% 8 National trust for welfare of mental and disabled Not Applicable 100% 9 Govt. or any local authority utilized for charitable purpose As given below 50% 10 Govt. or any approved authority for purpose of promoting family planning As given below 100% 11 Fund set up by Govt for medical relief Not Applicable 100%
Calculation Amount of donation made 10% of adjusted gross total income calculated ü Which ever is lower
Conclusion Under the income tax act first of all income under each head is computed. The aggregate of income under each head is known as ‘Gross Total Income’. Out of this gross total income certain deductions are allowed. The income after such deductions is called ‘Total Income’ The total deductions from section 80 C - 80 U cannot exceed the total income.
- Slides: 22