
CPC marketing plan 2017 Kate Newell 2016 Envigo
- Slides: 92
CPC marketing plan 2017 Kate Newell © 2016 Envigo 1 envigo. com
Situational analysis 2
3
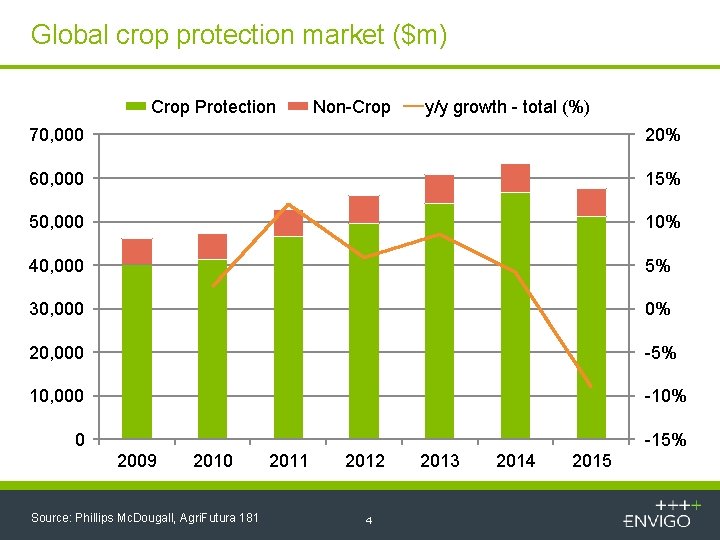
Global crop protection market ($m) Crop Protection Non-Crop y/y growth - total (%) 70, 000 20% 60, 000 15% 50, 000 10% 40, 000 5% 30, 000 0% 20, 000 -5% 10, 000 -10% 0 -15% 2009 2010 Source: Phillips Mc. Dougall, Agri. Futura 181 2012 4 2013 2014 2015
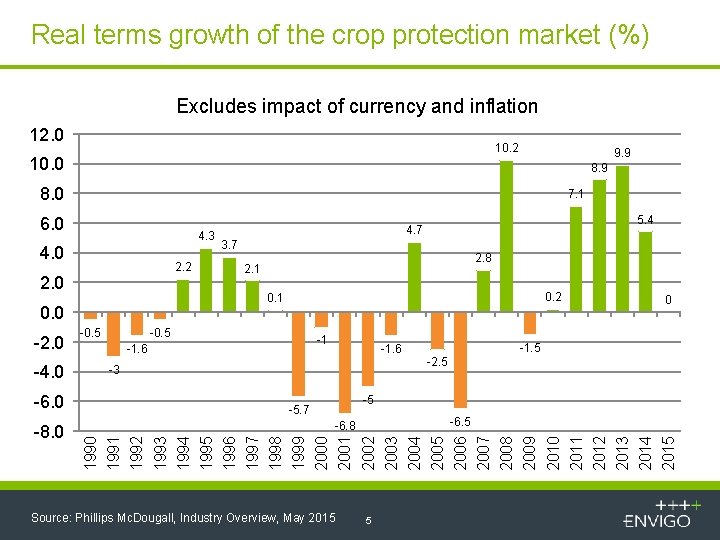
Real terms growth of the crop protection market (%) Excludes impact of currency and inflation 12. 0 10. 2 10. 0 9. 9 8. 0 7. 1 6. 0 4. 3 4. 0 2. 2 2. 0 -6. 0 -8. 0 2. 8 2. 1 0. 2 -0. 5 -1 -1. 6 -3 0 -1. 5 -2. 5 -5 -5. 7 -6. 5 -6. 8 1990 1991 1992 1993 1994 1995 1996 1997 1998 1999 2000 2001 2002 2003 2004 2005 2006 2007 2008 2009 2010 2011 2012 2013 2014 2015 -4. 0 3. 7 0. 1 0. 0 -2. 0 5. 4 4. 7 Source: Phillips Mc. Dougall, Industry Overview, May 2015 5
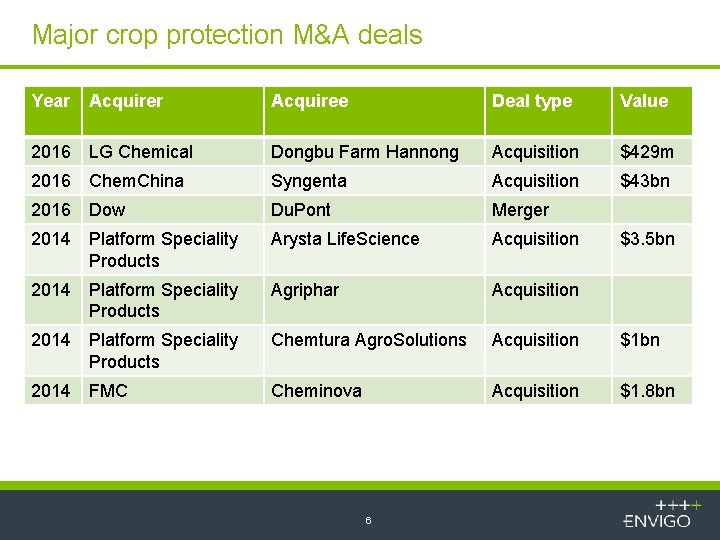
Major crop protection M&A deals Year Acquiree Deal type Value 2016 LG Chemical Dongbu Farm Hannong Acquisition $429 m 2016 Chem. China Syngenta Acquisition $43 bn 2016 Dow Du. Pont Merger 2014 Platform Speciality Products Arysta Life. Science Acquisition 2014 Platform Speciality Products Agriphar Acquisition 2014 Platform Speciality Products Chemtura Agro. Solutions Acquisition $1 bn 2014 FMC Cheminova Acquisition $1. 8 bn 6 $3. 5 bn
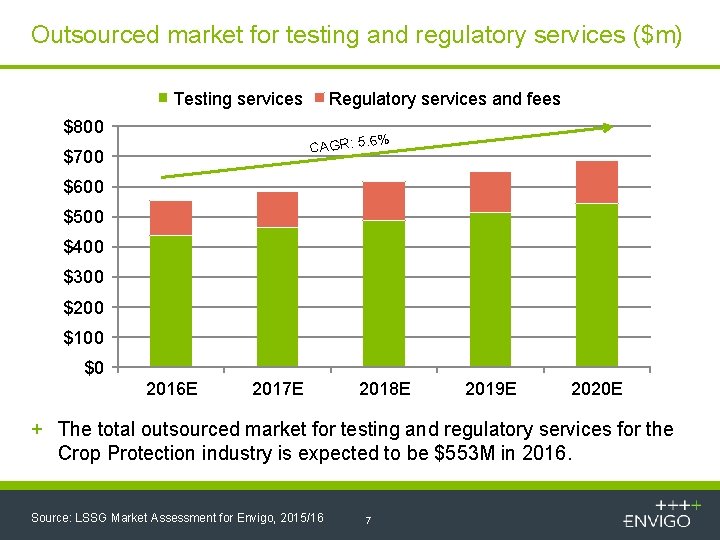
Outsourced market for testing and regulatory services ($m) Testing services $800 Regulatory services and fees CAGR: 5. 6 $700 % $600 $500 $400 $300 $200 $100 $0 2016 E 2017 E 2018 E 2019 E 2020 E + The total outsourced market for testing and regulatory services for the Crop Protection industry is expected to be $553 M in 2016. Source: LSSG Market Assessment for Envigo, 2015/16 7
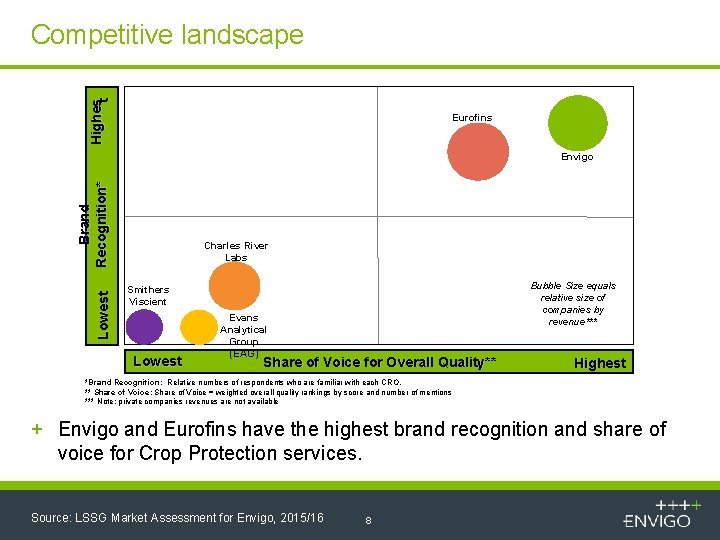
Highest Competitive landscape Eurofins Lowest Brand Recognition* Envigo Charles River Labs Bubble Size equals relative size of companies by revenue*** Smithers Viscient Lowest Evans Analytical Group (EAG) Share of Voice for Overall Quality** Highest *Brand Recognition: Relative numbers of respondents who are familiar with each CRO. ** Share of Voice: Share of Voice = weighted overall quality rankings by score and number of mentions *** Note: private companies revenues are not available + Envigo and Eurofins have the highest brand recognition and share of voice for Crop Protection services. Source: LSSG Market Assessment for Envigo, 2015/16 8
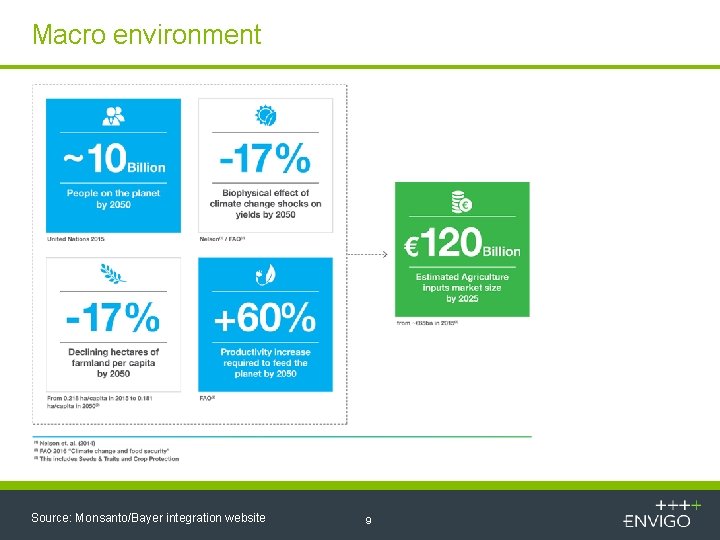
Macro environment Source: Monsanto/Bayer integration website 9
Macro environment “Monsanto prepares launch of digital services for agriculture in Brazil” Agropages 15 December 2016 The concept is that farmer should have reports, with maps and geographic coordinations of each property, indicating the performance of machines and productive potential of each area of the farm, to allow an evaluation of how to boost productivity. “The potential for increasing productivity is very high, ” said Rodrigo Santos, a Monsanto official in South America 10
Macro environment Consumer demands + Products that are highly nutritious + Look appetising + Stored for a long time An innovative new variety can mean the difference between market leading organisation and one that’s floundering. Lots rides on these innovations and developments. 11
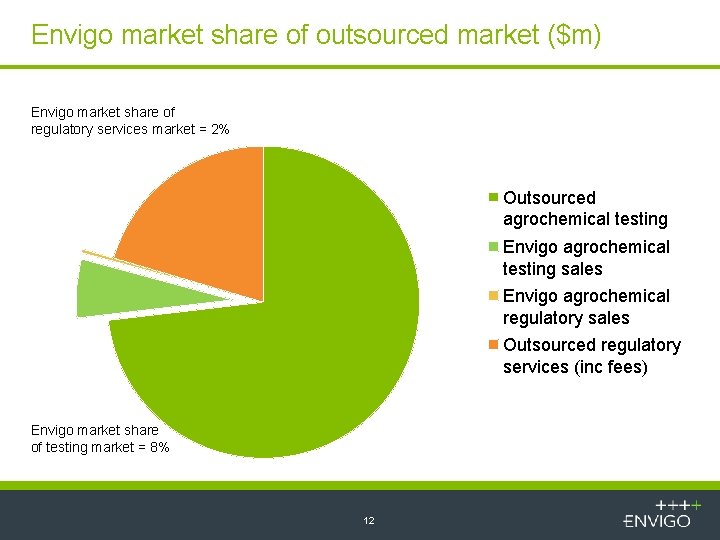
Envigo market share of outsourced market ($m) Envigo market share of regulatory services market = 2% Outsourced agrochemical testing Envigo agrochemical testing sales Envigo agrochemical regulatory sales Outsourced regulatory services (inc fees) Envigo market share of testing market = 8% 12
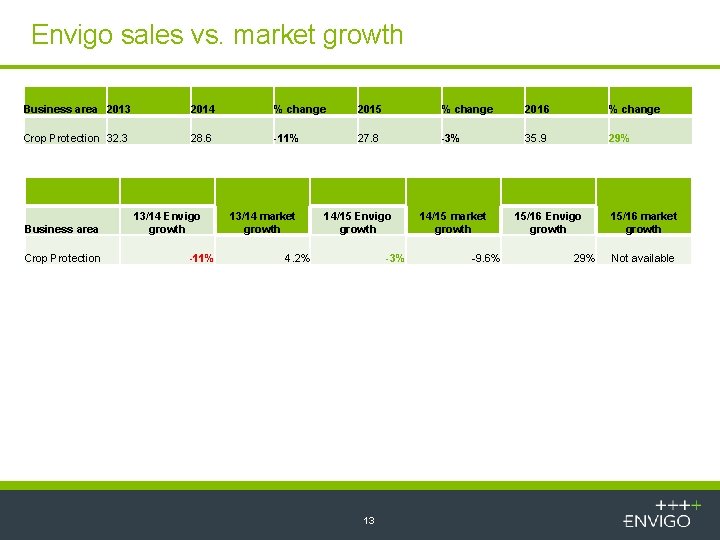
Envigo sales vs. market growth Business area 2013 2014 % change 2015 % change 2016 % change Crop Protection 32. 3 28. 6 -11% 27. 8 -3% 35. 9 29% Business area Crop Protection 13/14 Envigo growth -11% 13/14 market growth 14/15 Envigo growth 4. 2% -3% 13 14/15 market growth -9. 6% 15/16 Envigo growth 29% 15/16 market growth Not available
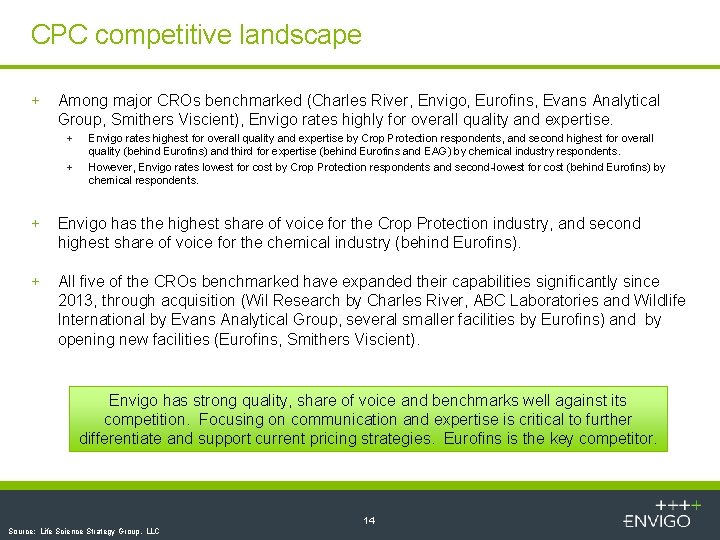
CPC competitive landscape + Among major CROs benchmarked (Charles River, Envigo, Eurofins, Evans Analytical Group, Smithers Viscient), Envigo rates highly for overall quality and expertise. + + Envigo rates highest for overall quality and expertise by Crop Protection respondents, and second highest for overall quality (behind Eurofins) and third for expertise (behind Eurofins and EAG) by chemical industry respondents. However, Envigo rates lowest for cost by Crop Protection respondents and second-lowest for cost (behind Eurofins) by chemical respondents. + Envigo has the highest share of voice for the Crop Protection industry, and second highest share of voice for the chemical industry (behind Eurofins). + All five of the CROs benchmarked have expanded their capabilities significantly since 2013, through acquisition (Wil Research by Charles River, ABC Laboratories and Wildlife International by Evans Analytical Group, several smaller facilities by Eurofins) and by opening new facilities (Eurofins, Smithers Viscient). Envigo has strong quality, share of voice and benchmarks well against its competition. Focusing on communication and expertise is critical to further differentiate and support current pricing strategies. Eurofins is the key competitor. 14 Source: Life Science Strategy Group, LLC
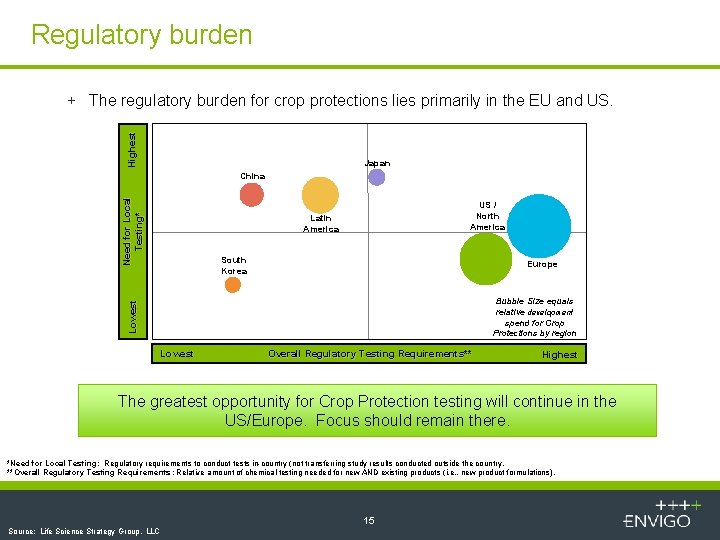
Regulatory burden Highest + The regulatory burden for crop protections lies primarily in the EU and US. Japan Need for Local Testing* China US / North America Latin America South Korea Europe Lowest Bubble Size equals relative development spend for Crop Protections by region Lowest Overall Regulatory Testing Requirements** Highest The greatest opportunity for Crop Protection testing will continue in the US/Europe. Focus should remain there. *Need for Local Testing: Regulatory requirements to conduct tests in-country (not transferring study results conducted outside the country. **Overall Regulatory Testing Requirements: Relative amount of chemical testing needed for new AND existing products (i. e. , new product formulations). 15 Source: Life Science Strategy Group, LLC
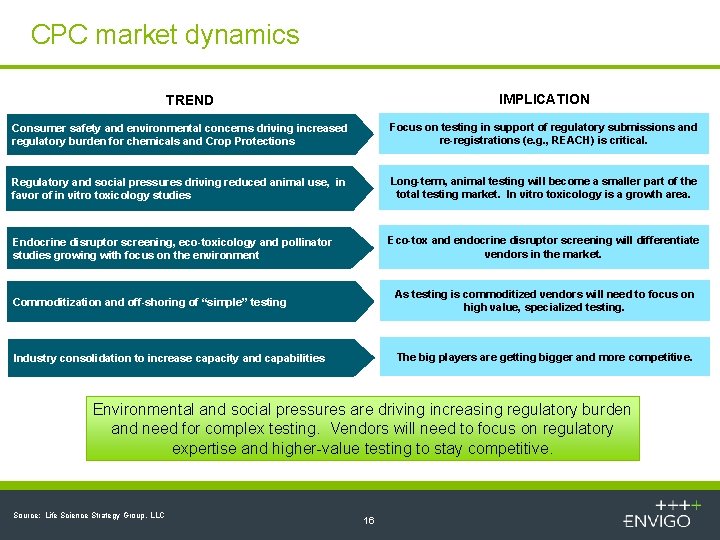
CPC market dynamics IMPLICATION TREND Consumer safety and environmental concerns driving increased regulatory burden for chemicals and Crop Protections Focus on testing in support of regulatory submissions and re-registrations (e. g. , REACH) is critical. Regulatory and social pressures driving reduced animal use, in favor of in vitro toxicology studies Long-term, animal testing will become a smaller part of the total testing market. In vitro toxicology is a growth area. Endocrine disruptor screening, eco-toxicology and pollinator studies growing with focus on the environment Eco-tox and endocrine disruptor screening will differentiate vendors in the market. Commoditization and off-shoring of “simple” testing As testing is commoditized vendors will need to focus on high value, specialized testing. Industry consolidation to increase capacity and capabilities The big players are getting bigger and more competitive. Environmental and social pressures are driving increasing regulatory burden and need for complex testing. Vendors will need to focus on regulatory expertise and higher-value testing to stay competitive. Source: Life Science Strategy Group, LLC 16
Situational analysis summary + Market growth has plateaued or declined in recent years + Sales have grown despite this + Growth is predicted for the future in both agrochemicals and seeds and traits + High levels of market consolidation + Patent applications declining – re-registrations prove to be a key area of focus + Geographically EU and US should be targeted + We can differentiate on specialist expertise and eco-tox, endocrine disruptors and communication 17
SWOT analysis 18
Crop Strengths + Market leading brand recognition and positioning + Full service offering – we wrap and bundle our services unlike our competitors + Our study directors really understand the context of the study they are managing within the regulatory requirements + Our employees are widely regarded as key opinion leaders + Regulatory guidance for customers 19
Crop Weaknesses + Capacity a perceived issue by customers – quality has suffered as a result. Particularly due to REACH requirements. + Perceived lack of CP services in the US and China + Loss of key personnel – retention has been an issue + Narrow relationships - difficult to penetrate market leaders outside core sales relationship 20
Crop Opportunities + Total market size for testing and regulatory services is $553 m + Majority of testing is outsourced + 50% of regulatory services are outsourced + Consolidation provides an opportunity to partner closely with strategic accounts (new and existing) to help achieve common goals + Alignment and targeting of consultants who act as intermediaries could be beneficial 21
Crop Opportunities + The crop protection regulatory burden is primarily in the EU and US – we’re strong in Europe but US has not been a focus to date + China could be a huge market for the future but there are currently no international registrations required – one to keep an eye on + High pressure on China to produce more with less due to ratio of agriculture output and population growth Macro environment + Brexit and change of leadership in US – could remove some regulations 22
Crop Opportunities + A focus on re-registrations + Non-animal alternatives + Endocrine disruptors will be a differentiator + Eco-toxicology and pollinator studies will be a differentiator + Biocides help to mitigate the seasonality of our income + Better communication strived for + Digital marketing channels favoured – our brand has strong foundations for success + Our experts aim for ‘regulatory-proof’ guidance for the future 23
Crop Threats Micro environment + + + Market declined in 2015 by 9% Flat or very slight growth predicted for 2016 -2018 Market consolidation More pressure for organic crop and GM Charles River and WIL Lack of CSR program Macro environment + Brexit + Change of leadership in US – could affect decision making 24
Crop - strategic focus 2017 Eco-toxicology and pollinator studies Re-registrations Consultant targeting Biocides In vitro Endocrine disruptors
26
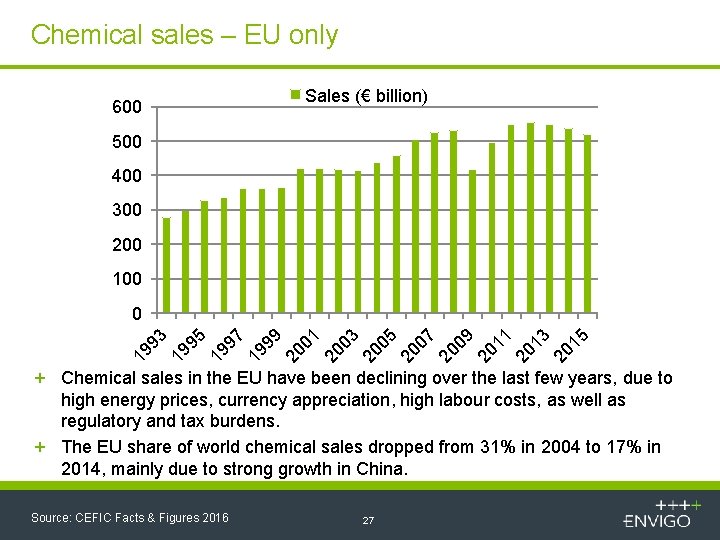
Chemical sales – EU only 600 Sales (€ billion) 500 400 300 200 19 93 19 95 19 97 19 99 20 01 20 03 20 05 20 07 20 09 20 11 20 13 20 15 0 + Chemical sales in the EU have been declining over the last few years, due to high energy prices, currency appreciation, high labour costs, as well as regulatory and tax burdens. + The EU share of world chemical sales dropped from 31% in 2004 to 17% in 2014, mainly due to strong growth in China. Source: CEFIC Facts & Figures 2016 27
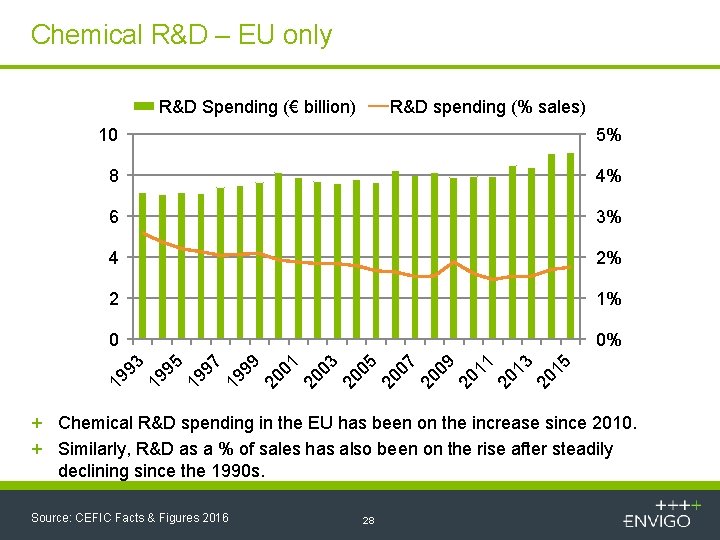
Chemical R&D – EU only R&D Spending (€ billion) R&D spending (% sales) 5% 8 4% 6 3% 4 2% 2 1% 0 0% 19 93 19 95 19 97 19 99 20 01 20 03 20 05 20 07 20 09 20 11 20 13 20 15 10 + Chemical R&D spending in the EU has been on the increase since 2010. + Similarly, R&D as a % of sales has also been on the rise after steadily declining since the 1990 s. Source: CEFIC Facts & Figures 2016 28
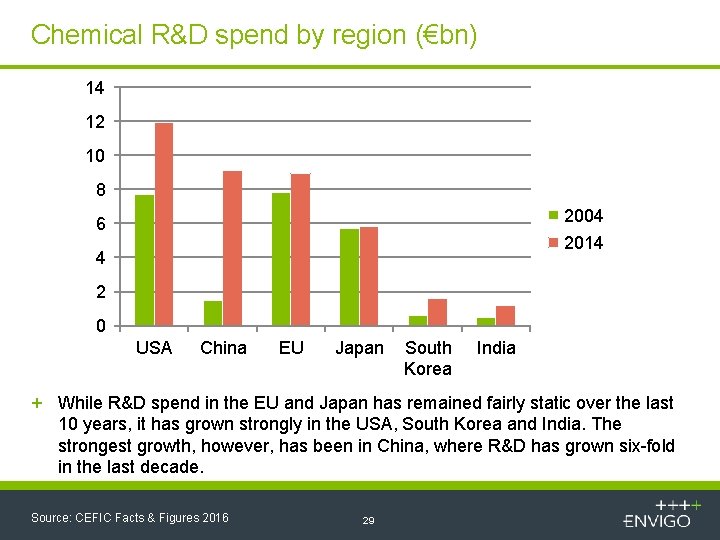
Chemical R&D spend by region (€bn) 14 12 10 8 2004 6 2014 4 2 0 USA China EU Japan South Korea India + While R&D spend in the EU and Japan has remained fairly static over the last 10 years, it has grown strongly in the USA, South Korea and India. The strongest growth, however, has been in China, where R&D has grown six-fold in the last decade. Source: CEFIC Facts & Figures 2016 29
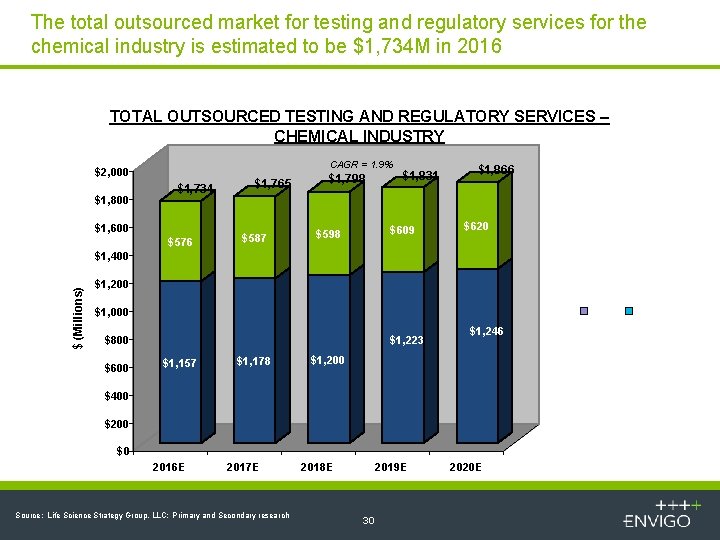
The total outsourced market for testing and regulatory services for the chemical industry is estimated to be $1, 734 M in 2016 TOTAL OUTSOURCED TESTING AND REGULATORY SERVICES – CHEMICAL INDUSTRY CAGR = 1. 9% $2, 000 $1, 800 $1, 734 $1, 600 $576 $1, 765 $587 $1, 798 $1, 831 $609 $598 $1, 866 $620 $ (Millions) $1, 400 $1, 200 $1, 000 $800 $600 $1, 223 $1, 157 $1, 178 $1, 246 $1, 200 $400 $200 $0 2016 E 2017 E Source: Life Science Strategy Group, LLC; Primary and Secondary research 2018 E 2019 E 30 2020 E
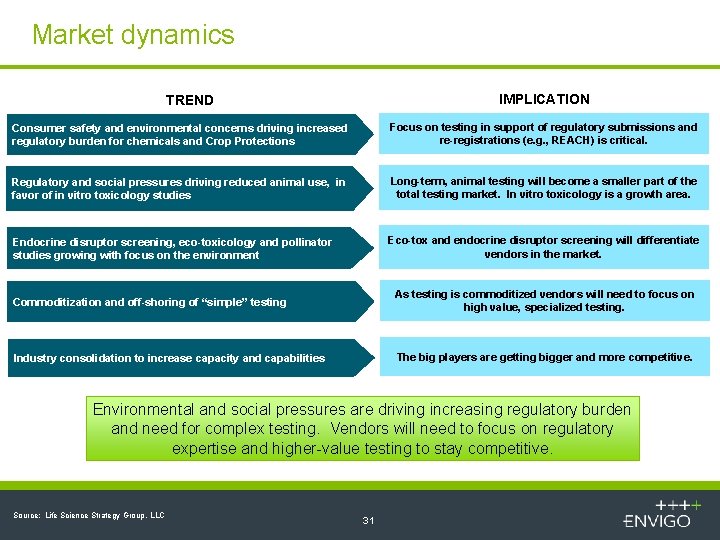
Market dynamics IMPLICATION TREND Consumer safety and environmental concerns driving increased regulatory burden for chemicals and Crop Protections Focus on testing in support of regulatory submissions and re-registrations (e. g. , REACH) is critical. Regulatory and social pressures driving reduced animal use, in favor of in vitro toxicology studies Long-term, animal testing will become a smaller part of the total testing market. In vitro toxicology is a growth area. Endocrine disruptor screening, eco-toxicology and pollinator studies growing with focus on the environment Eco-tox and endocrine disruptor screening will differentiate vendors in the market. Commoditization and off-shoring of “simple” testing As testing is commoditized vendors will need to focus on high value, specialized testing. Industry consolidation to increase capacity and capabilities The big players are getting bigger and more competitive. Environmental and social pressures are driving increasing regulatory burden and need for complex testing. Vendors will need to focus on regulatory expertise and higher-value testing to stay competitive. Source: Life Science Strategy Group, LLC 31
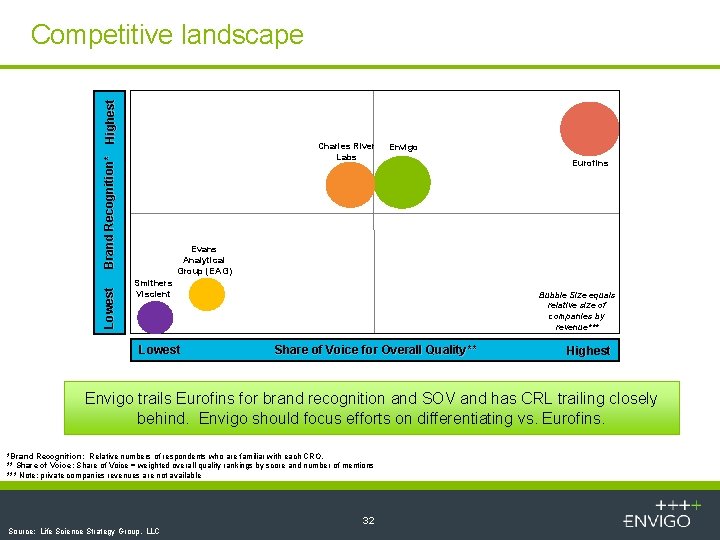
Lowest Brand Recognition* Highest Competitive landscape Charles River Labs Envigo Eurofins Evans Analytical Group (EAG) Smithers Viscient Lowest Bubble Size equals relative size of companies by revenue*** Share of Voice for Overall Quality** Highest Envigo trails Eurofins for brand recognition and SOV and has CRL trailing closely behind. Envigo should focus efforts on differentiating vs. Eurofins. *Brand Recognition: Relative numbers of respondents who are familiar with each CRO. ** Share of Voice: Share of Voice = weighted overall quality rankings by score and number of mentions *** Note: private companies revenues are not available 32 Source: Life Science Strategy Group, LLC
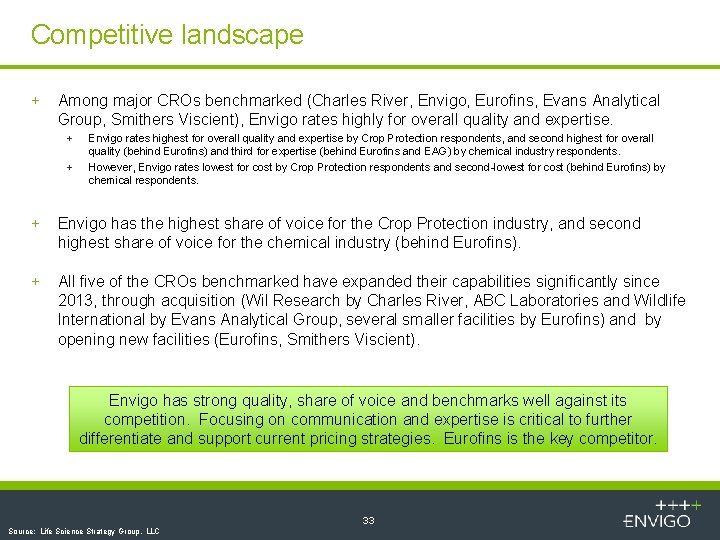
Competitive landscape + Among major CROs benchmarked (Charles River, Envigo, Eurofins, Evans Analytical Group, Smithers Viscient), Envigo rates highly for overall quality and expertise. + + Envigo rates highest for overall quality and expertise by Crop Protection respondents, and second highest for overall quality (behind Eurofins) and third for expertise (behind Eurofins and EAG) by chemical industry respondents. However, Envigo rates lowest for cost by Crop Protection respondents and second-lowest for cost (behind Eurofins) by chemical respondents. + Envigo has the highest share of voice for the Crop Protection industry, and second highest share of voice for the chemical industry (behind Eurofins). + All five of the CROs benchmarked have expanded their capabilities significantly since 2013, through acquisition (Wil Research by Charles River, ABC Laboratories and Wildlife International by Evans Analytical Group, several smaller facilities by Eurofins) and by opening new facilities (Eurofins, Smithers Viscient). Envigo has strong quality, share of voice and benchmarks well against its competition. Focusing on communication and expertise is critical to further differentiate and support current pricing strategies. Eurofins is the key competitor. 33 Source: Life Science Strategy Group, LLC
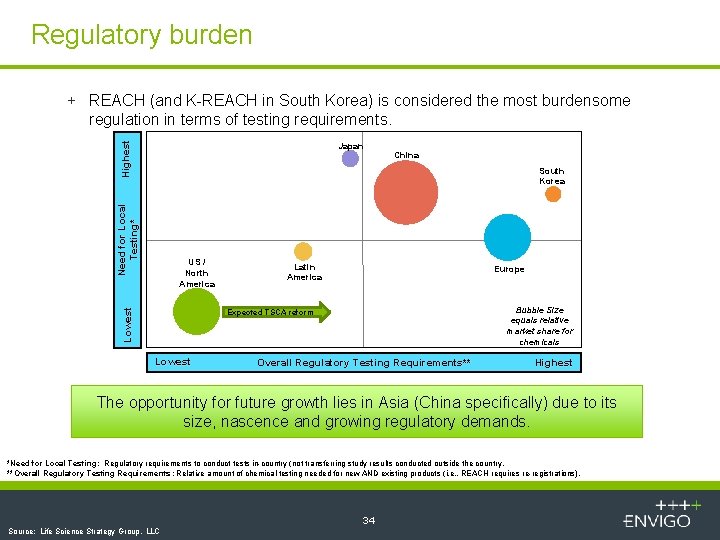
Regulatory burden + REACH (and K-REACH in South Korea) is considered the most burdensome Highest regulation in terms of testing requirements. Japan China Need for Local Testing* South Korea Lowest US / North America Latin America Europe Bubble Size equals relative market share for chemicals Expected TSCA reform Lowest Overall Regulatory Testing Requirements** Highest The opportunity for future growth lies in Asia (China specifically) due to its size, nascence and growing regulatory demands. *Need for Local Testing: Regulatory requirements to conduct tests in-country (not transferring study results conducted outside the country. **Overall Regulatory Testing Requirements: Relative amount of chemical testing needed for new AND existing products (i. e. , REACH requires re-registrations). 34 Source: Life Science Strategy Group, LLC
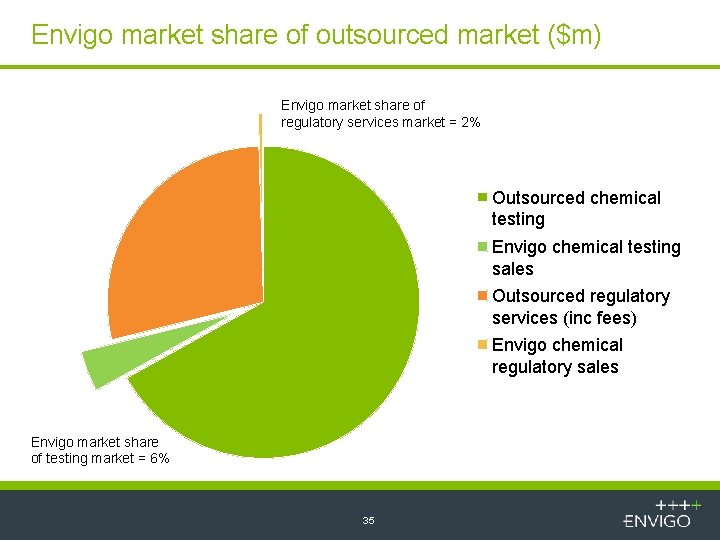
Envigo market share of outsourced market ($m) Envigo market share of regulatory services market = 2% Outsourced chemical testing Envigo chemical testing sales Outsourced regulatory services (inc fees) Envigo chemical regulatory sales Envigo market share of testing market = 6% 35
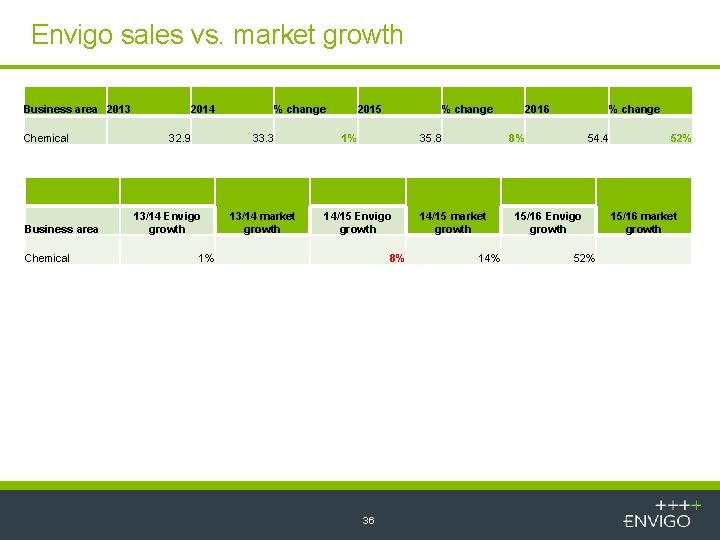
Envigo sales vs. market growth Business area 2013 Chemical Business area Chemical 2014 32. 9 % change 33. 3 13/14 Envigo growth 13/14 market growth 2015 % change 1% 35. 8 14/15 Envigo growth 1% 8% 36 2016 % change 8% 14/15 market growth 14% 54. 4 15/16 Envigo growth 52% 15/16 market growth
Situational analysis summary + Market growth has plateaued in recent years in the EU + However huge growth in the US, South Korea and China + Geographically EU, US and South Korea should be targeted + We can differentiate on specialist expertise and communication + Sales growth in 2016 has been strong 37
SWOT analysis 38
Chemical Strengths + Improving brand recognition and positioning + Full service offering + Our study directors really understand the context of the study they are managing within the regulatory requirements + Our employees are widely regarded as key opinion leaders 39
Chemical Weaknesses + Brand recognition not as strong as CP + Capacity a perceived issue by customers + Potential loss of key personnel + We’ve been behind on some key initiatives in 2016 40
Chemical Opportunities + Total market size for testing and regulatory services is $1. 73 bn + 50% of testing is outsourced + 40% of regulatory services are outsourced + Expertise in future planning ‘regulatory proof’ + REACH + What’s happening beyond 2018? Our teams are positioned for the future + EOGRTS + Some chemical companies are still dealing with REACH 2013 data requirements + TSCA reform definition 41
Chemical Opportunities + Non-animal alternatives identified as an area of interest for customers + Endochrine disruptors + (Biocides) + Better communication strived for 42
Chemical Opportunities Geographically: + China could be a huge market for the future but there are currently no international registrations required – one to keep an eye on 43
Chemical Threats + Market declined in 2015 by x% + Market consolidation + Reduced set of industry leaders through M&A – less opportunities for strategic relationships as incumbent suppliers better placed Macroenvironment + Brexit + Change of leadership in US – could affect decision making 44
Chemical - strategic focus 2017 REACH including: Beyond 2018 TSCA reform EOGRTS 2013 data requirements Targeting of consortia (Biocides) Consultant targeting Endocrine disruptors In vitro
Objectives 46
Crop protection + Actively increase enquiries for re-registrations by 5% annually by December 2017 + Contribute to the expansion our biocidal customer portfolio by 3% annually by December 2017 + Design and implement a comprehensive campaign for the targeting of consultants by June 2017 including: + Working closely with Sales to target those of most value + Development of an exclusive online offering for this segment + Keep top of mind with structured campaign deliverables + Construction of seasonal and targeted eco-tox campaign actively influencing orders by 3% for completion by March 2017 47
Chemical + Actively contribute to a 3% increase annually in pre. REACH 2018 testing enquiries by December 2017 + Actively contribute to a 5% increase annually in post. REACH 2018 regulatory enquiries by December 2017 + Design and implement a comprehensive campaign for the targeting of consultants by June 2017 including: + Working closely with Sales to target those of most value + Development of an exclusive offering for this segment + Keep top of mind with structured campaign deliverables 48
Key CRS goals + Increase visibility of Envigo brand in CRS market segment + Position Envigo’s CPC offerings as specialized in REACH, biocides, NATS and eco-tox arenas + Support CRS revenue target globally through a combination of standard marketing programs and account management-based approaches (for strategic accounts) + Provide lead generation efforts through marketing campaigns help makes customers and potential customers aware, engaged, and activated to work with Envigo
Strategy 50
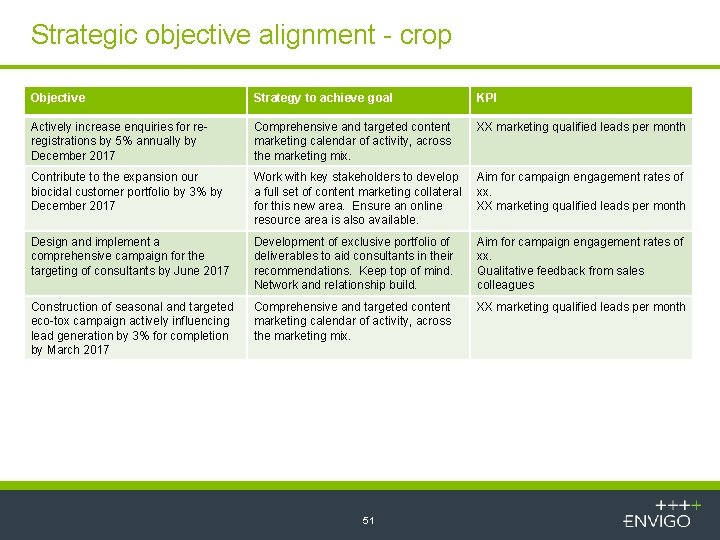
Strategic objective alignment - crop Objective Strategy to achieve goal KPI Actively increase enquiries for reregistrations by 5% annually by December 2017 Comprehensive and targeted content marketing calendar of activity, across the marketing mix. XX marketing qualified leads per month Contribute to the expansion our biocidal customer portfolio by 3% by December 2017 Work with key stakeholders to develop a full set of content marketing collateral for this new area. Ensure an online resource area is also available. Aim for campaign engagement rates of xx. XX marketing qualified leads per month Design and implement a comprehensive campaign for the targeting of consultants by June 2017 Development of exclusive portfolio of deliverables to aid consultants in their recommendations. Keep top of mind. Network and relationship build. Aim for campaign engagement rates of xx. Qualitative feedback from sales colleagues Construction of seasonal and targeted eco-tox campaign actively influencing lead generation by 3% for completion by March 2017 Comprehensive and targeted content marketing calendar of activity, across the marketing mix. XX marketing qualified leads per month 51
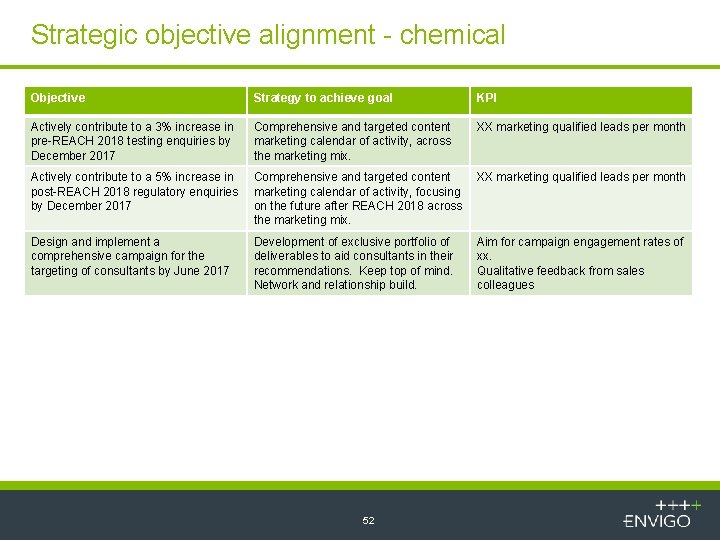
Strategic objective alignment - chemical Objective Strategy to achieve goal KPI Actively contribute to a 3% increase in pre-REACH 2018 testing enquiries by December 2017 Comprehensive and targeted content marketing calendar of activity, across the marketing mix. XX marketing qualified leads per month Actively contribute to a 5% increase in post-REACH 2018 regulatory enquiries by December 2017 Comprehensive and targeted content marketing calendar of activity, focusing on the future after REACH 2018 across the marketing mix. XX marketing qualified leads per month Design and implement a comprehensive campaign for the targeting of consultants by June 2017 Development of exclusive portfolio of deliverables to aid consultants in their recommendations. Keep top of mind. Network and relationship build. Aim for campaign engagement rates of xx. Qualitative feedback from sales colleagues 52
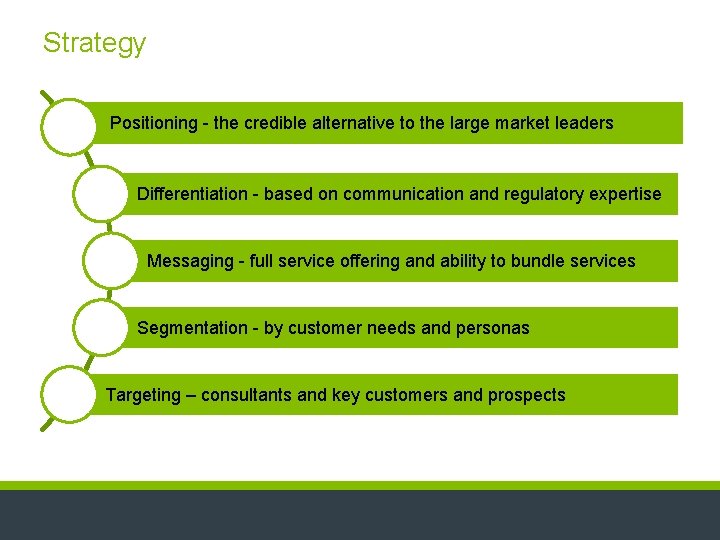
Strategy Positioning - the credible alternative to the large market leaders Differentiation - based on communication and regulatory expertise Messaging - full service offering and ability to bundle services Segmentation - by customer needs and personas Targeting – consultants and key customers and prospects
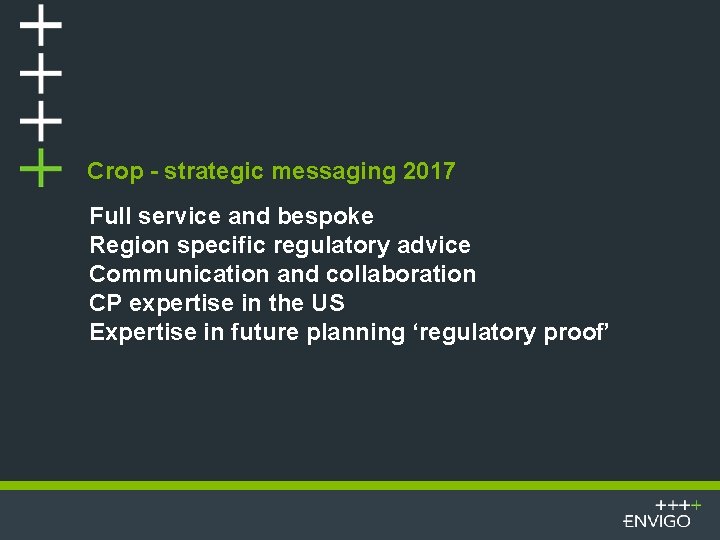
Crop - strategic messaging 2017 Full service and bespoke Region specific regulatory advice Communication and collaboration CP expertise in the US Expertise in future planning ‘regulatory proof’
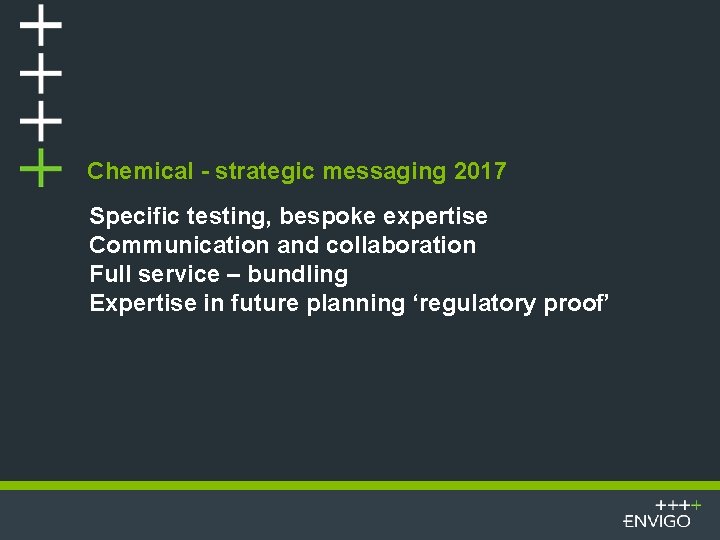
Chemical - strategic messaging 2017 Specific testing, bespoke expertise Communication and collaboration Full service – bundling Expertise in future planning ‘regulatory proof’
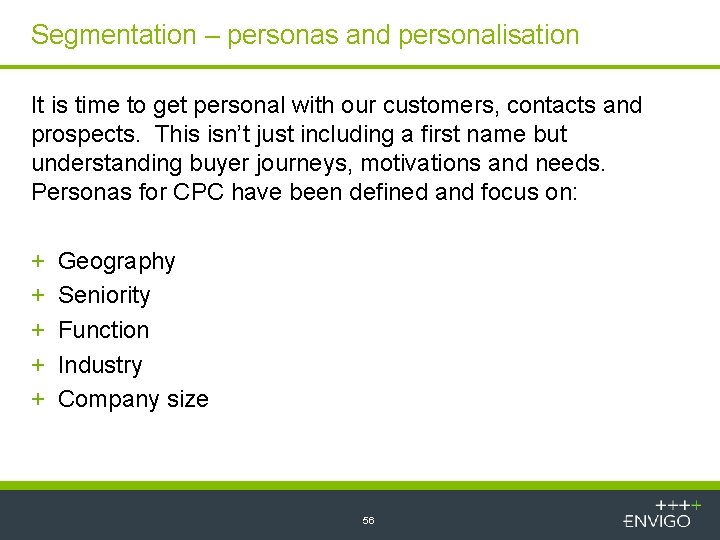
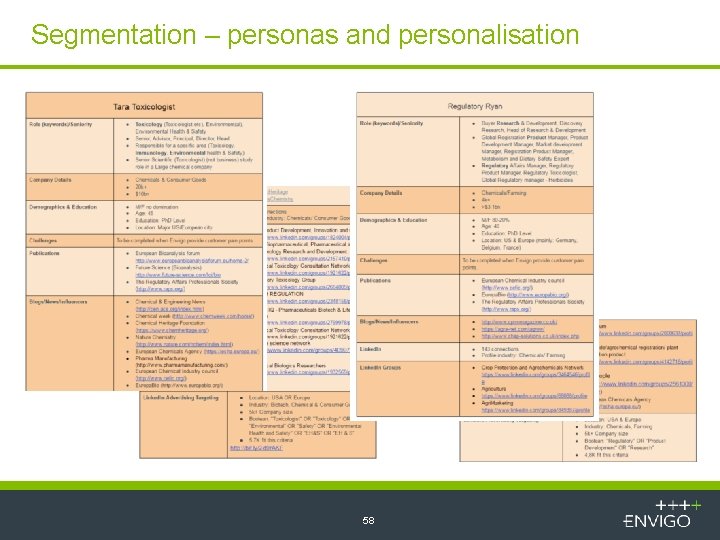
Segmentation – personas and personalisation It is time to get personal with our customers, contacts and prospects. This isn’t just including a first name but understanding buyer journeys, motivations and needs. Personas for CPC have been defined and focus on: + + + Geography Seniority Function Industry Company size 56
Segmentation – personas and personalisation Developed buyer personas: + + + Qualitative research on active buyers from SFDC Identified common attributes (i. e. job title, age, etc. ) Incorporated behaviour and digital footprint Additional personas to follow + + Procurement on each side Influencers Campaigns will exploit our marketing automation platforms and focus on nurturing contacts, prospects and customers through their own particular buyer journey. For 2017 we’ll focus on one key persona in each business area. 57
Segmentation – personas and personalisation 58
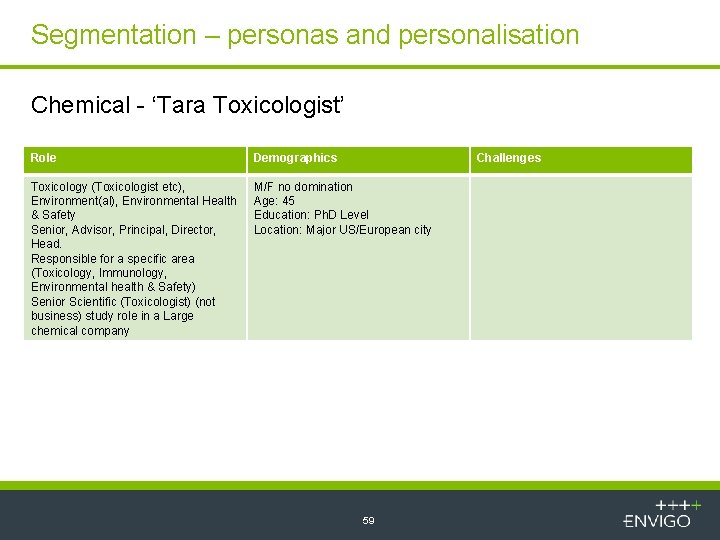
Segmentation – personas and personalisation Chemical - ‘Tara Toxicologist’ Role Demographics Challenges Toxicology (Toxicologist etc), Environment(al), Environmental Health & Safety Senior, Advisor, Principal, Director, Head. Responsible for a specific area (Toxicology, Immunology, Environmental health & Safety) Senior Scientific (Toxicologist) (not business) study role in a Large chemical company M/F no domination Age: 45 Education: Ph. D Level Location: Major US/European city 59
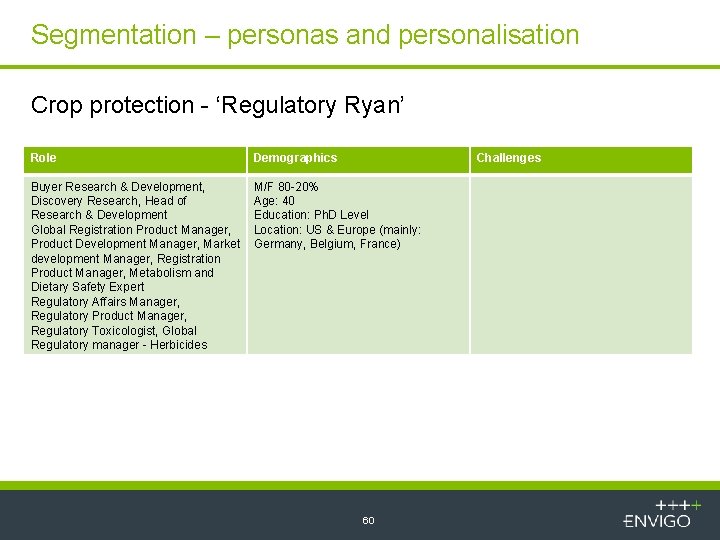
Segmentation – personas and personalisation Crop protection - ‘Regulatory Ryan’ Role Demographics Challenges Buyer Research & Development, Discovery Research, Head of Research & Development Global Registration Product Manager, Product Development Manager, Market development Manager, Registration Product Manager, Metabolism and Dietary Safety Expert Regulatory Affairs Manager, Regulatory Product Manager, Regulatory Toxicologist, Global Regulatory manager - Herbicides M/F 80 -20% Age: 40 Education: Ph. D Level Location: US & Europe (mainly: Germany, Belgium, France) 60
Account based focus “Account-based marketing (ABM), also known as key account marketing, is a strategic approach to business marketing in which an organization considers and communicates with individual prospect or customer accounts as markets of one. ” + Offers substantial advantages in consultancy industries, those with long sales cycles and where the market is becoming increasingly commoditised + By targeting to an individual account it's perceived as more relevant to the organisation. Extreme targeting! + It provides an incentive for customers to stay with existing suppliers. 61
Account based focus budget dependant + Set up pilot scheme with sales + Identify target accounts and set by serviceability, revenue potential and Envigo resource + Identify DMU or whole account (depending on size) + Identify key personas or overall persona (depending on size) + Highlight their objectives and plot service maps and areas of our expertise – pain points and areas to shine + Set goals + increase penetration and generate new contacts, + work existing contacts and maximise opportunities 62
STAG + Campaigns, actions and subsequent content should be aligned with and supported by STAG’s strategic objectives 63
Tactics 64
Campaigns Chemical + REACH 2018 and beyond Crop + Biocides + Eco-tox + Re-registrations CPC + NATS + Consultants 65
Budget $290, 000 split as follows: + + $40 k advertising $70 k events $155 k content production (inc. social and SEO) $25 k market research, new projects and innovation + 13% of total budget 66
Content marketing $135 k Aligned with seasonal calendar where appropriate and focussed on: + Webinars + Opinion leader profiles + E-books + Case studies + Infographics + Video + Posters + Digital sequences + White papers + Journal articles + Blogs Content to focus on stages of buyer journey and answer key challenges/obstacles 67
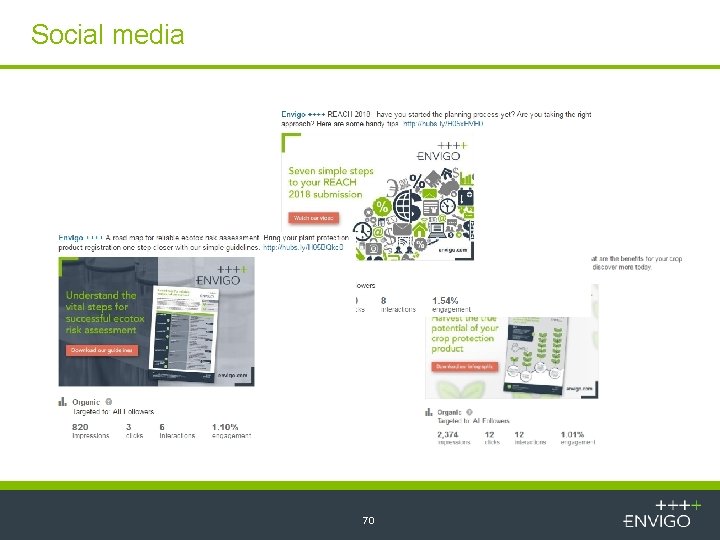
Social media $10 k + Social has evolved into a platform for conversations and engagement. Our main focus will remain on Linked. In, the most effective social media channel for building relationships and targeting, but will also include Twitter. + Social and search paid promotions focused on targeted persona and segments by: + Geography + Industry + Role + Function + Interests + Other relevant demographic/behavioral data 68
Social media Objectives for 2017 include: + Auto-posting for senior individuals + Sponsored updates + Interaction via groups, blogs and our insight pages + Linked. In engagement rate of 1 69
Social media 70
Blog – the new thang A typical blog combines text, digital images, and links to other blogs, web pages, and other media related to its topic. Gives a viewpoint or opinion on a specific topic. Benefits: + Engagement with audience + Increases SEO + An increase in indexed pages + Key to positioning 71
Video + + Virtual facility tours Interviews with scientists Educational shorts (e. g. videoscribe) Event recording (interviews/recaps at tradeshows) 72
SEO $10 k Work with digital team to define key words and phrases for general crop protection and chemical areas as well as specific Adword campaigns that tie into persona generated vocabulary and search terms. In addition: + Undertake Adwords campaigns to raise organic search results and page rankings + Regularly review with key stakeholders current web content to ensure fit for SEO purpose. 73
Advertising and media $40 k Focused around digital media. Working with publications to ensure our opportunities are valuable. Suggested routes: + Third party emails (TPE) + Round tables and featured or spotlight advertorial Press + Work more closely with our media agency to enhance our editorial opportunities Budget to be split 50% on straight advertising and 50% on third party emails and advertorial. 74
Advertising and media Key publications based on 2016 metrics: + + Agrowpages Chemical Industry Journal Speciality Chemical 75
Events $70 k The value of exhibiting at tradeshows has and should be questioned. + $40 k allocated for tradeshow exhibitions – a 75% reduction from 2016 + $30 k ear-marked for Envigo organized symposia: + Beyond REACH 2018 + In vitro 76
Events Key events agreed with senior management and aligned with plans + 2 nd Chem/Petrochem Prod Liab & Reg Reform + 5 th Annual European Regulatory Conference on Biocides + ECPA/ECCA Regulatory Conference 2017 + Society for Chemical Hazard Communication + SETAC + SOT (budgeted by brand) 77
Events + Flagship events will have a communications plan associated with them. Smaller events will be publicised by social media before and during the event. + Online symposia + Networking events where appropriate 78
Market research $25 k + Key account analysis + Pain points for personas + Content engagement measurement project + Internally driven (Survey Monkey) + Understand what types of content pieces our contacts appreciate consuming + Identify “wish list” from customers 79
Account based focus + Tactics to include multi point co-branded communications from/with sales and operations + Sales navigator contact + On site meet the scientist / webinars + Target company case studies highlighting work undertaken for same company + + + different area C level contact including direct mail and round tables Target account hashtag usage and support, share their positive news on key platforms Key event attendance and set meetings Set branded content and landing pages for downloads – exclude from general mailings and personalise to target accounts through email identification Micro website pages/online hub of content – target area specific if possible Sponsored ads on social direct to target accounts and retargeting based on IP addresses – eg Adwords Customer Match advertising 80
Actions 81
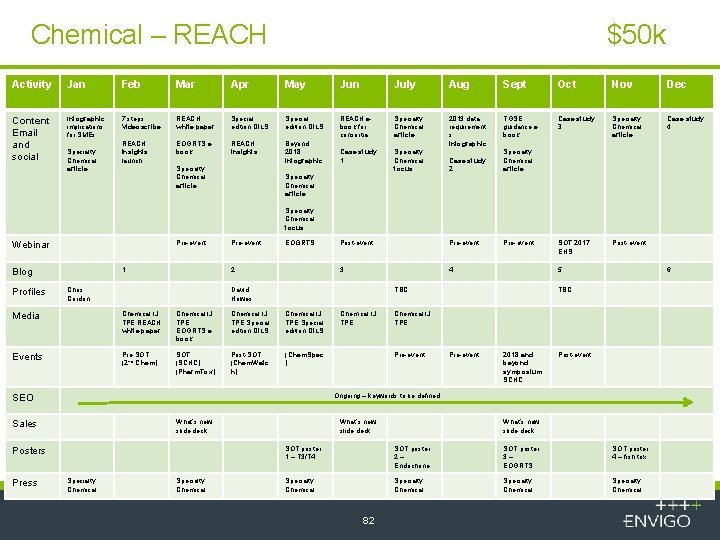
Chemical – REACH $50 k Activity Jan Feb Mar Apr May Jun July Aug Sept Oct Nov Dec Content Email and social Infographic implications for SMEs 7 steps Videoscribe REACH white paper Special edition Di. LS REACH ebook for consortia Specialty Chemical article TGSE guidance ebook Case study 3 Specialty Chemical article Case study 4 REACH insights launch EOGRTS ebook REACH insights Beyond 2018 infographic 2013 data requirement s infographic Case study 1 Specialty Chemical focus SOT 2017 EHS Post-event Specialty Chemical article Case study 2 Specialty Chemical article Post-event Pre-event 3 4 Specialty Chemical article Specialty Chemical focus Pre-event Webinar 1 Blog Profiles Pre-event EOGRTS 2 Chris Cordon David Howes TBC Media Chemical IJ TPE REACH white paper Chemical IJ TPE EOGRTS ebook Chemical IJ TPE Special edition Di. LS Events Pre-SOT (2 nd Chem) SOT (SCHC) (Pharm. Tox) Post-SOT (Chem. Watc h) (Chem. Spec ) Chemical IJ TPE 6 TBC Chemical IJ TPE Pre-event 2018 and beyond symposium SCHC Post-event Ongoing – keywords to be defined SEO What’s new slide deck Sales Posters Press 5 Specialty Chemical What’s new slide deck SOT poster 1 – T 3/T 4 SOT poster 2– Endochrine SOT poster 3– EOGRTS SOT poster 4 – fish tox Specialty Chemical 82
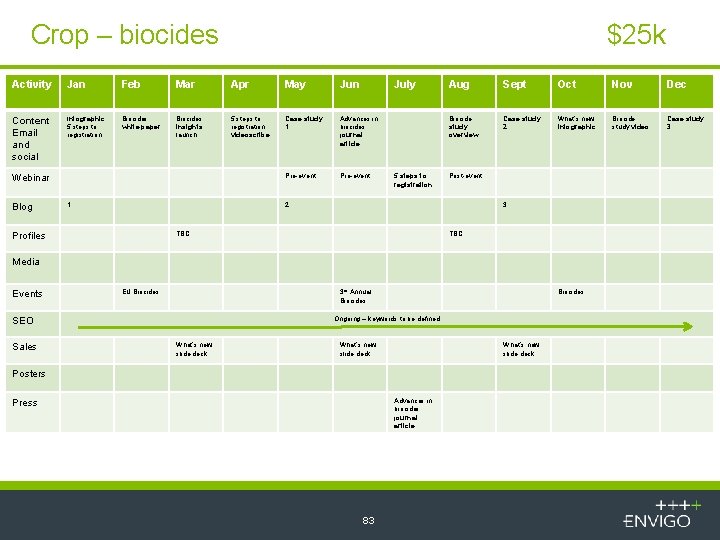
Crop – biocides $25 k Activity Jan Feb Mar Apr May Jun Content Email and social Infographic 5 steps to registration Biocides white paper Biocides insights launch 5 steps to registration videoscribe Case study 1 Advances in biocides journal article Pre-event Webinar Blog 1 July 5 steps to registration Aug Sept Oct Nov Dec Biocide study overview Case study 2 What’s new infographic Biocide study video Case study 3 Post-event 2 3 TBC Profiles TBC Media Events EU Biocides 3 rd Annual Biocides Ongoing – keywords to be defined SEO Sales Biocides What’s new slide deck Posters Advances in biocides journal article Press 83
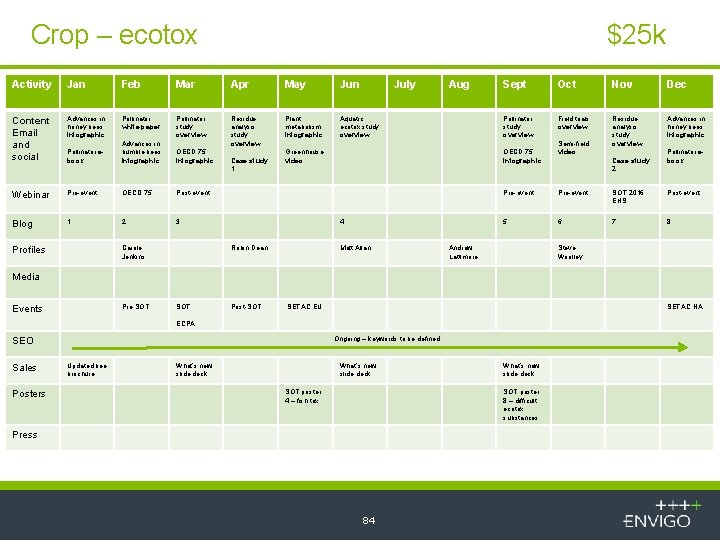
Crop – ecotox $25 k Activity Jan Feb Mar Apr May Jun Content Email and social Advances in honey bees infographic Pollinator white paper Pollinator study overview Plant metabolism infographic Aquatic ecotox study overview Pollinator ebook Advances in bumble bees infographic Residue analysis study overview OECD 75 infographic Webinar Pre-event OECD 75 Post-event Blog 1 2 3 Carole Jenkins Profiles Case study 1 July Aug Greenhouse video Oct Nov Dec Pollinator study overview Field trials overview Residue analysis study overview Advances in honey bees infographic OECD 75 infographic 4 Robin Dean Sept Matt Allan Semi-field video Case study 2 Pollinator ebook Pre-event SOT 2016 EHS Post-event 5 6 7 8 Andrew Lattimore Steve Woolley Media Pre-SOT Events SOT Post-SOT SETAC EU SETAC NA ECPA Ongoing – keywords to be defined SEO Sales Posters Updated bee brochure What’s new slide deck SOT poster 4 – fish tox What’s new slide deck SOT poster 8 – difficult ecotox substances Press 84
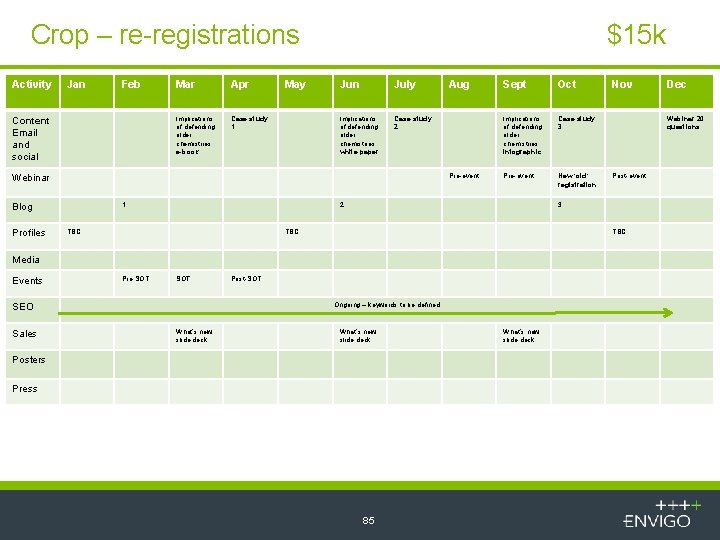
Crop – re-registrations Activity Jan Feb Content Email and social Mar Apr Implications of defending older chemistries e-book Case study 1 May $15 k Jun July Implications of defending older chemistries white paper Case study 2 Pre-event Webinar 1 Blog Profiles Aug Sept Oct Implications of defending older chemistries infographic Case study 3 Pre-event New ‘old’ registration 2 TBC Pre-SOT Ongoing – keywords to be defined SEO Sales What’s new slide deck Post-event TBC Post-SOT What’s new slide deck Posters Press 85 What’s new slide deck Dec Webinar 20 questions 3 Media Events Nov
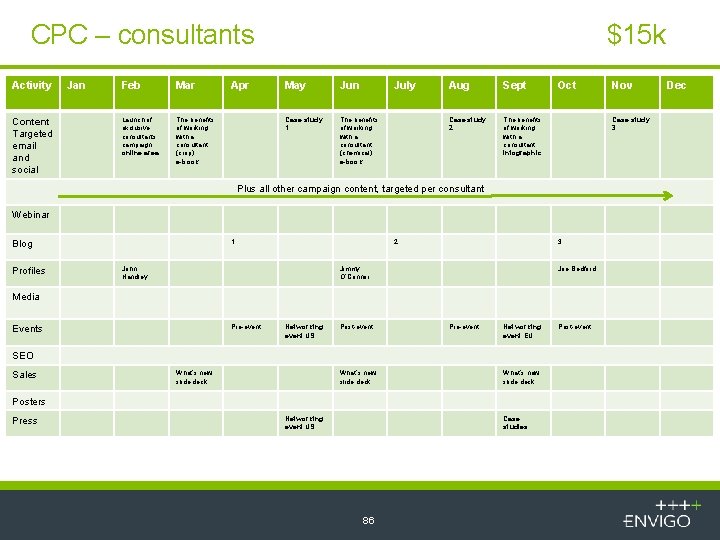
CPC – consultants Activity Content Targeted email and social Jan Feb Mar Launch of exclusive consultants campaign online area The benefits of working with a consultant (crop) e-book Apr $15 k May Jun July Case study 1 The benefits of working with a consultant (chemical) e-book Aug Sept Case study 2 The benefits of working with a consultant infographic Oct Case study 3 Plus all other campaign content, targeted per consultant Webinar 1 Blog Profiles 2 John Handley 3 Jimmy O’Connor Joe Bedford Media Pre-event Events Networking event US Post-event Pre-event Networking event EU SEO Sales What’s new slide deck Posters Press Networking event US Case studies 86 Nov Post-event Dec
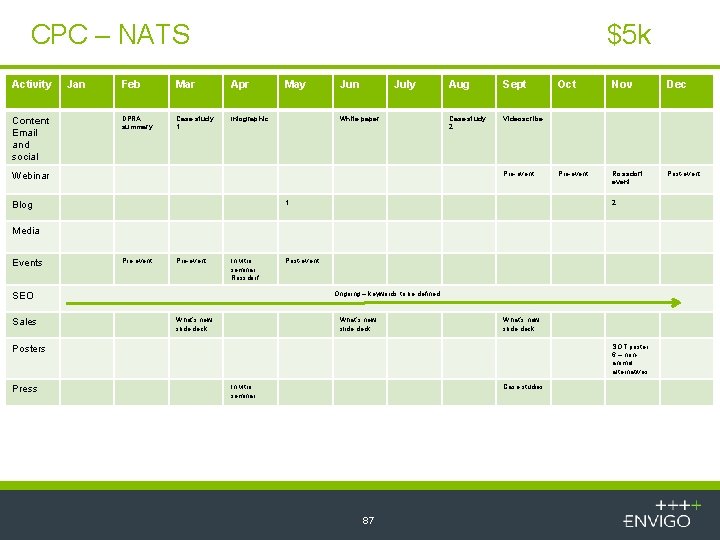
CPC – NATS Activity Content Email and social Jan $5 k Feb Mar Apr DPRA summary Case study 1 Infographic May Jun July White paper Aug Sept Case study 2 Videoscribe Pre-event Webinar 1 Blog Oct Nov Dec Pre-event Rossdorf event Post-event 2 Media Events Pre-event In-vitro seminar Rossdorf Ongoing – keywords to be defined SEO Sales Post-event What’s new slide deck SOT poster 6 – nonanimal alternatives Posters Press In-vitro seminar Case studies 87
Control 88
To be reported and evaluated per campaign By the business area marketing manager on a monthly basis + Email open, click through and deliverability including thank you emails + Landing page views and engagement rates, thank you page views, submission rate, the number of new contacts added + Total net new contacts (leads) generated + Total number of MQLS generated + Source report + Disruptor fly in stats + Database life cycle stage breakdown (subscriber, lead, mql, sql, opportunity, customer) + SFDC association report – opportunities/closed won and lost 89
To be reported and evaluated per tradeshow Quantitative + + + + Cost per lead Cost per contact No. of meetings arranged as a proportion of attendance Website traffic peaks? Social media engagement No. of delegates and % of our target audience Number of exhibitors and competitors present Number Envigo employees present and whether this was appropriate number Qualitative (rated as red, amber and green) + Comments made during event + Quality of delegates + Quality of interactions 90
To be reported per month + + Budgetary control Competitor analysis Tradeshows Customer feedback 91
Review and evaluation + Meet with CPC business lead on a monthly basis + Review and evaluate past month’s activity and confirm priorities for the following quarter 92