
Cost Management Accounting Lecture23 Main Ahmad Farhan Example
- Slides: 8
Cost & Management Accounting Lecture-23 Main Ahmad Farhan
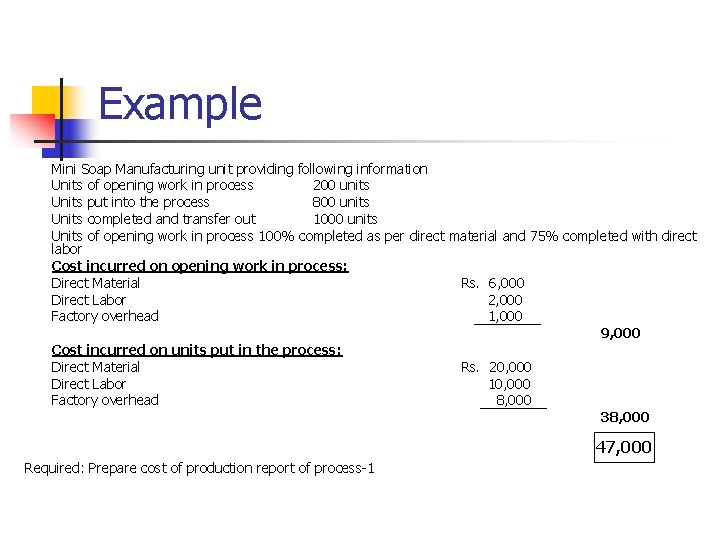
Example Mini Soap Manufacturing unit providing following information Units of opening work in process 200 units Units put into the process 800 units Units completed and transfer out 1000 units Units of opening work in process 100% completed as per direct material and 75% completed with direct labor Cost incurred on opening work in process: Direct Material Rs. 6, 000 Direct Labor 2, 000 Factory overhead 1, 000 9, 000 Cost incurred on units put in the process: Direct Material Rs. 20, 000 Direct Labor 10, 000 Factory overhead 8, 000 38, 000 47, 000 Required: Prepare cost of production report of process-1
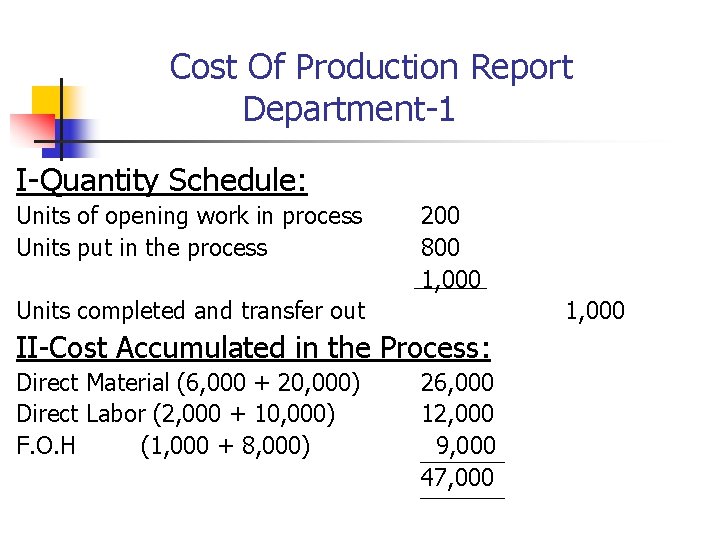
Cost Of Production Report Department-1 I-Quantity Schedule: Units of opening work in process Units put in the process 200 800 1, 000 Units completed and transfer out 1, 000 II-Cost Accumulated in the Process: Direct Material (6, 000 + 20, 000) Direct Labor (2, 000 + 10, 000) F. O. H (1, 000 + 8, 000) 26, 000 12, 000 9, 000 47, 000
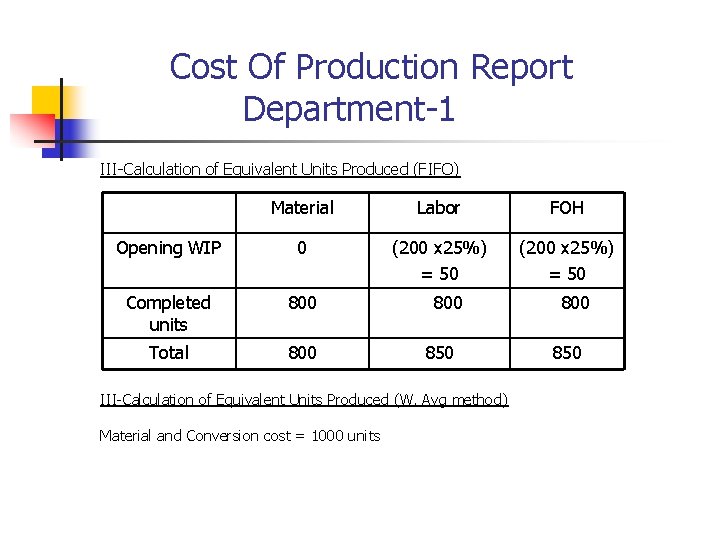
Cost Of Production Report Department-1 III-Calculation of Equivalent Units Produced (FIFO) Material Labor FOH Opening WIP 0 (200 x 25%) = 50 Completed units 800 Total 800 850 III-Calculation of Equivalent Units Produced (W. Avg method) Material and Conversion cost = 1000 units 800 850
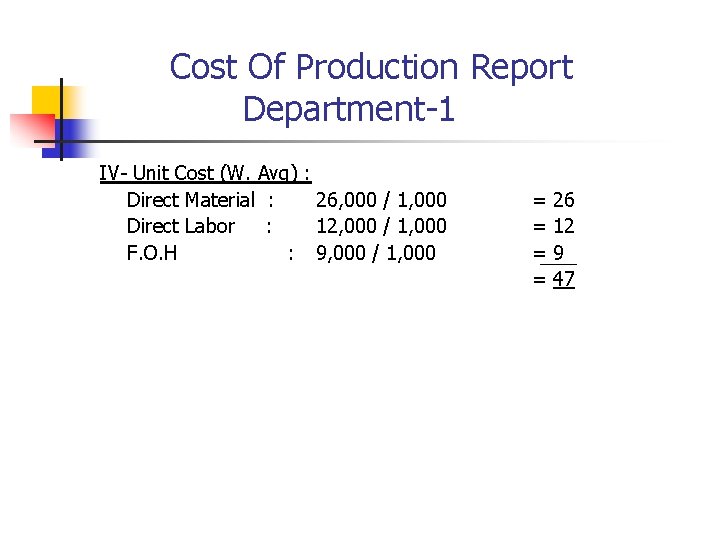
Cost Of Production Report Department-1 IV- Unit Cost (W. Avg) Direct Material : Direct Labor : F. O. H : : 26, 000 / 1, 000 12, 000 / 1, 000 9, 000 / 1, 000 = = 26 12 9 47
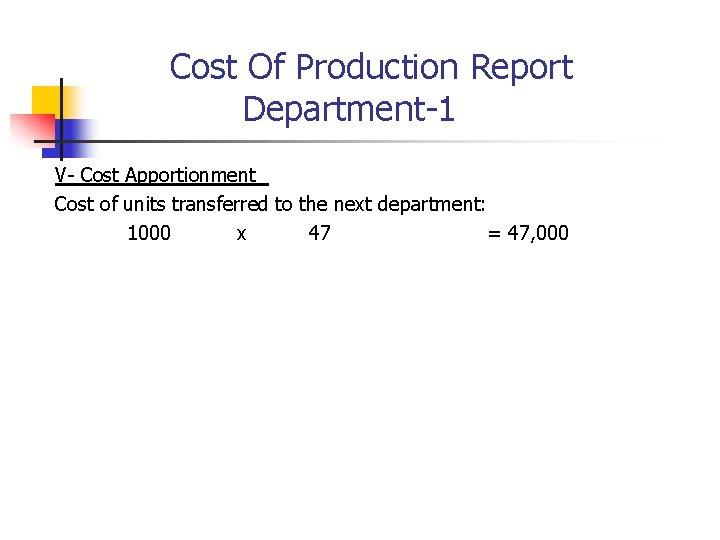
Cost Of Production Report Department-1 V- Cost Apportionment Cost of units transferred to the next department: 1000 x 47 = 47, 000
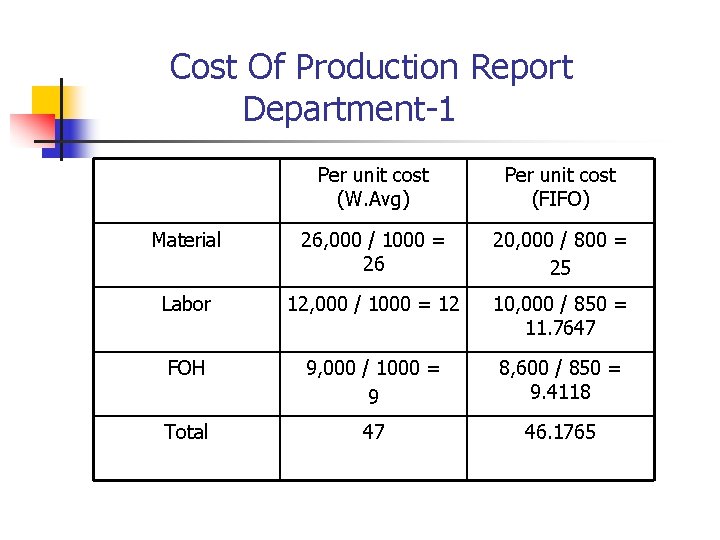
Cost Of Production Report Department-1 Per unit cost (W. Avg) Per unit cost (FIFO) Material 26, 000 / 1000 = 26 20, 000 / 800 = 25 Labor 12, 000 / 1000 = 12 10, 000 / 850 = 11. 7647 FOH 9, 000 / 1000 = 9 8, 600 / 850 = 9. 4118 Total 47 46. 1765
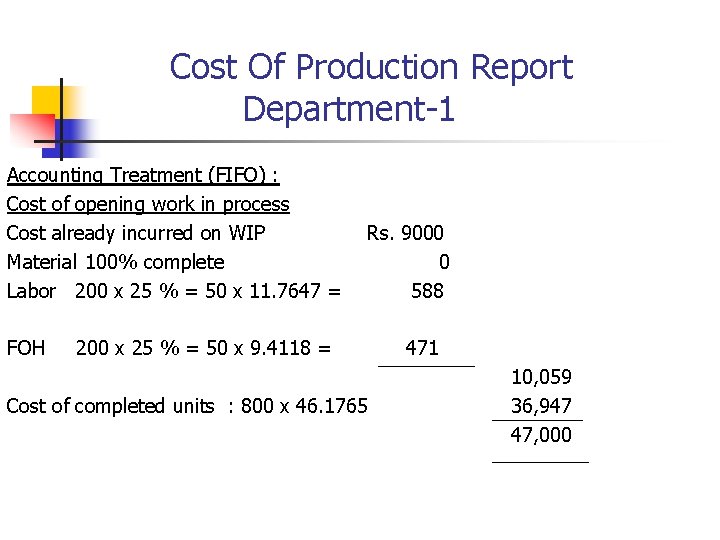
Cost Of Production Report Department-1 Accounting Treatment (FIFO) : Cost of opening work in process Cost already incurred on WIP Material 100% complete Labor 200 x 25 % = 50 x 11. 7647 = FOH Rs. 9000 0 588 200 x 25 % = 50 x 9. 4118 = Cost of completed units : 800 x 46. 1765 471 10, 059 36, 947 47, 000