
Cost Analysis and Estimating for Engineering and Management
- Slides: 71
Cost Analysis and Estimating for Engineering and Management Chapter 4 Accounting Analysis © 2004 Pearson Education, Inc. Pearson Prentice Hall, Pearson Education, Upper Saddle River, NJ 07458 Ostwald and Mc. Laren / Cost Analysis and Estimating for Engineering and Management Ch 4 -1
Overview l Accounting -Records, Transactions, Reports l Depreciation -What It Is, Uses, Calculations l Budgeting l Overhead -Calculations and Application l Variance © 2004 Pearson Education, Inc. Pearson Prentice Hall, Pearson Education, Upper Saddle River, NJ 07458 Ostwald and Mc. Laren / Cost Analysis and Estimating for Engineering and Management Ch 4 -2
Accounting l Analyzes Money Transactions l Multiple Disciplines l Cost Accounting -Cost of Using Productive Assets l Tax Accounting -Tax Consequences on Business © 2004 Pearson Education, Inc. Pearson Prentice Hall, Pearson Education, Upper Saddle River, NJ 07458 Ostwald and Mc. Laren / Cost Analysis and Estimating for Engineering and Management Ch 4 -3
Accounting & Engineering l Engineering -Looks Ahead -Cost Estimates BEFORE Things Happen l Accounting -Money Transactions That Have Happened -Historical Records -Incompatible Data Formats © 2004 Pearson Education, Inc. Pearson Prentice Hall, Pearson Education, Upper Saddle River, NJ 07458 Ostwald and Mc. Laren / Cost Analysis and Estimating for Engineering and Management Ch 4 -4
Transactions l Money (or Something of Value) Comes In or Goes Out of the Company l Recorded Twice (In 2 Accounts) l Double-Entry Bookkeeping l Accounts - Records of Like Transactions © 2004 Pearson Education, Inc. Pearson Prentice Hall, Pearson Education, Upper Saddle River, NJ 07458 Ostwald and Mc. Laren / Cost Analysis and Estimating for Engineering and Management Ch 4 -5
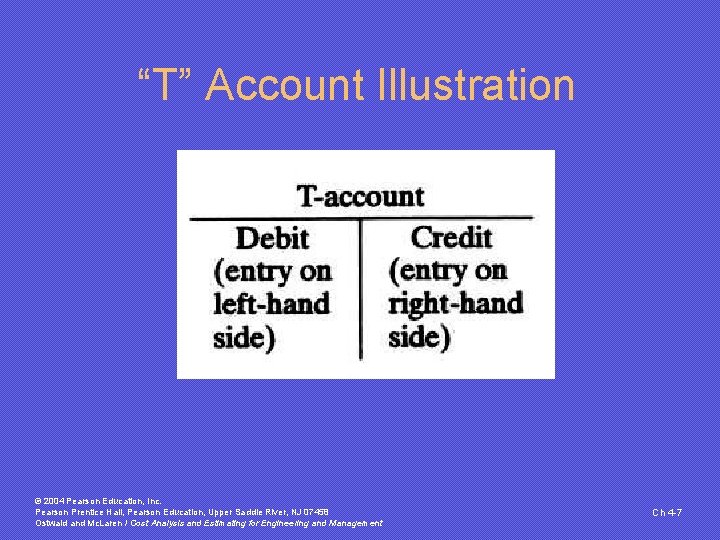
“T” Accounts l 2 Columns l Left Hand Column - Called “Debit” l Right Hand Column - Called “Credit” l Each Transaction Has a Debit In One Account and a Credit In Another l Note: Debit or Credit Have NO Value Meaning - Credit Is Not Always Good © 2004 Pearson Education, Inc. Pearson Prentice Hall, Pearson Education, Upper Saddle River, NJ 07458 Ostwald and Mc. Laren / Cost Analysis and Estimating for Engineering and Management Ch 4 -6
“T” Account Illustration © 2004 Pearson Education, Inc. Pearson Prentice Hall, Pearson Education, Upper Saddle River, NJ 07458 Ostwald and Mc. Laren / Cost Analysis and Estimating for Engineering and Management Ch 4 -7
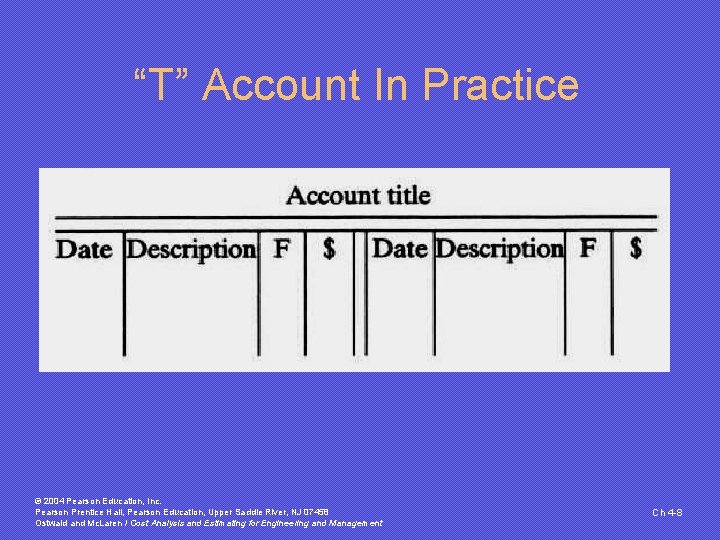
“T” Account In Practice © 2004 Pearson Education, Inc. Pearson Prentice Hall, Pearson Education, Upper Saddle River, NJ 07458 Ostwald and Mc. Laren / Cost Analysis and Estimating for Engineering and Management Ch 4 -8
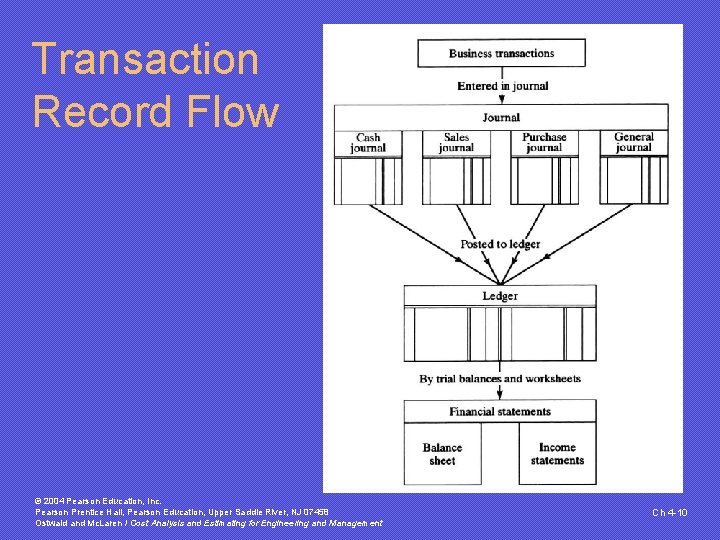
Records l Journals -Chronological Record of Transaction l Transaction “Posted” to Ledgers l Ledger -Group of Accounts © 2004 Pearson Education, Inc. Pearson Prentice Hall, Pearson Education, Upper Saddle River, NJ 07458 Ostwald and Mc. Laren / Cost Analysis and Estimating for Engineering and Management Ch 4 -9
Transaction Record Flow © 2004 Pearson Education, Inc. Pearson Prentice Hall, Pearson Education, Upper Saddle River, NJ 07458 Ostwald and Mc. Laren / Cost Analysis and Estimating for Engineering and Management Ch 4 -10
Accounting Conventions l Money Measurement -All Transactions Recorded in Money l Accounting Equivalence -Double Entry -Assets = Liabilities + Net Worth l Conservatism -Record the Lesser Value © 2004 Pearson Education, Inc. Pearson Prentice Hall, Pearson Education, Upper Saddle River, NJ 07458 Ostwald and Mc. Laren / Cost Analysis and Estimating for Engineering and Management Ch 4 -11
More Accounting Conventions l Consistency -Always Record Transactions the Same Way l Business Perspective -“Going Concern” -Transactions for the Sake of the Business l Use Cost Not Value © 2004 Pearson Education, Inc. Pearson Prentice Hall, Pearson Education, Upper Saddle River, NJ 07458 Ostwald and Mc. Laren / Cost Analysis and Estimating for Engineering and Management Ch 4 -12
Cash vs. Accrual l Cash -Transaction When Money Exchanged -Individuals and Very Small Businesses l Accrual -Transaction When Earned -Receipts at Shipment -Payables When Material Received © 2004 Pearson Education, Inc. Pearson Prentice Hall, Pearson Education, Upper Saddle River, NJ 07458 Ostwald and Mc. Laren / Cost Analysis and Estimating for Engineering and Management Ch 4 -13
Revenue vs. Expense l Revenue -Money Received -Increases to Net Worth l Expense -Costs Incurred -Decreases to Net Worth © 2004 Pearson Education, Inc. Pearson Prentice Hall, Pearson Education, Upper Saddle River, NJ 07458 Ostwald and Mc. Laren / Cost Analysis and Estimating for Engineering and Management Ch 4 -14
Account Categories l Asset l Liability l Net Worth l Revenue l Expense © 2004 Pearson Education, Inc. Pearson Prentice Hall, Pearson Education, Upper Saddle River, NJ 07458 Ostwald and Mc. Laren / Cost Analysis and Estimating for Engineering and Management Ch 4 -15
Assets l Things with Dollar Value l Company Owns l Current -For Short Period l Fixed -Longer Than 1 Year © 2004 Pearson Education, Inc. Pearson Prentice Hall, Pearson Education, Upper Saddle River, NJ 07458 Ostwald and Mc. Laren / Cost Analysis and Estimating for Engineering and Management Ch 4 -16
Liabilities l Debts the Company Owes l Short Term -Accounts Payable -Short Term Loans l Long Term -Over 1 Year -Mortgages, Long Term Loans © 2004 Pearson Education, Inc. Pearson Prentice Hall, Pearson Education, Upper Saddle River, NJ 07458 Ostwald and Mc. Laren / Cost Analysis and Estimating for Engineering and Management Ch 4 -17
Net Worth l Ownership Interest l Capital Stock -Portion Paid In By Owners l Retained Earnings -Accumulation of Profits and Losses © 2004 Pearson Education, Inc. Pearson Prentice Hall, Pearson Education, Upper Saddle River, NJ 07458 Ostwald and Mc. Laren / Cost Analysis and Estimating for Engineering and Management Ch 4 -18
Revenues & Expenses l Revenue -Sales Income Before Deduction of Costs l Expenses -Costs of Doing Business l Gross Income Revenue – Expense © 2004 Pearson Education, Inc. Pearson Prentice Hall, Pearson Education, Upper Saddle River, NJ 07458 Ostwald and Mc. Laren / Cost Analysis and Estimating for Engineering and Management Ch 4 -19
Profit l Gross Income – Taxes l Recorded on Profit and Loss Statement l Contributes to Net Worth © 2004 Pearson Education, Inc. Pearson Prentice Hall, Pearson Education, Upper Saddle River, NJ 07458 Ostwald and Mc. Laren / Cost Analysis and Estimating for Engineering and Management Ch 4 -20
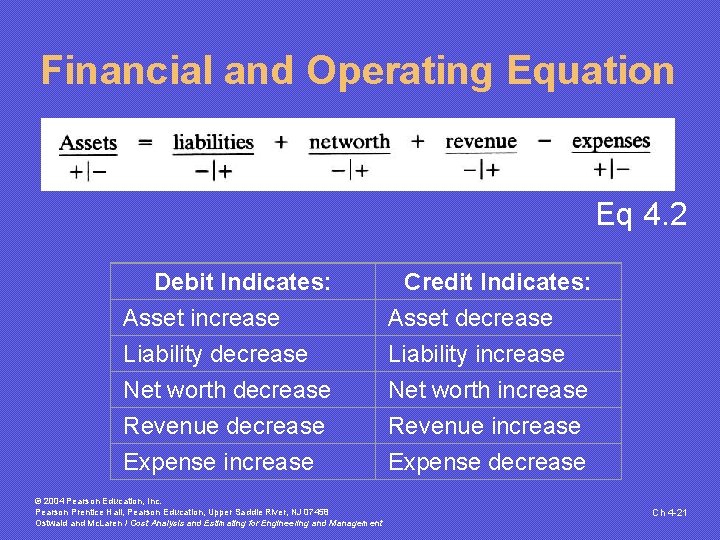
Financial and Operating Equation Eq 4. 2 Debit Indicates: Credit Indicates: Asset increase Asset decrease Liability increase Net worth decrease Net worth increase Revenue decrease Revenue increase Expense decrease © 2004 Pearson Education, Inc. Pearson Prentice Hall, Pearson Education, Upper Saddle River, NJ 07458 Ostwald and Mc. Laren / Cost Analysis and Estimating for Engineering and Management Ch 4 -21
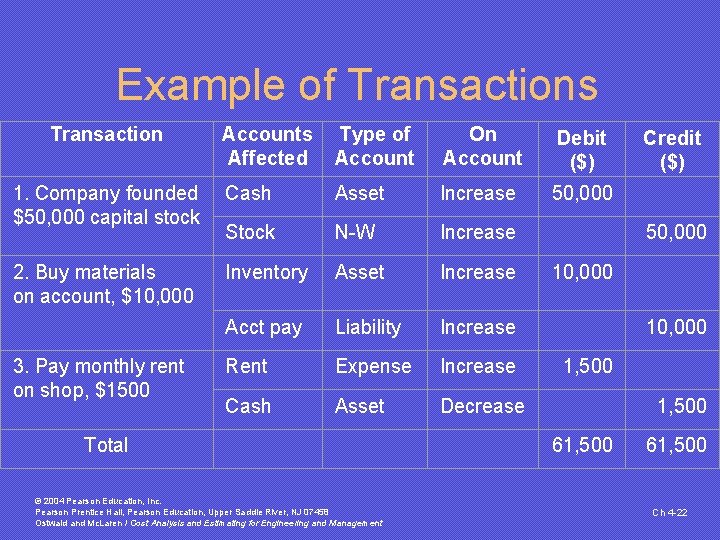
Example of Transactions Transaction Accounts Type of Affected Account On Account Debit ($) Credit ($) 1. Company founded $50, 000 capital stock Cash Asset Increase 50, 000 Stock N-W Increase 50, 000 2. Buy materials on account, $10, 000 Inventory Asset Increase 10, 000 Acct pay Liability Increase 10, 000 Rent Expense Increase 1, 500 Cash Asset Decrease 1, 500 61, 500 3. Pay monthly rent on shop, $1500 Total © 2004 Pearson Education, Inc. Pearson Prentice Hall, Pearson Education, Upper Saddle River, NJ 07458 Ostwald and Mc. Laren / Cost Analysis and Estimating for Engineering and Management Ch 4 -22
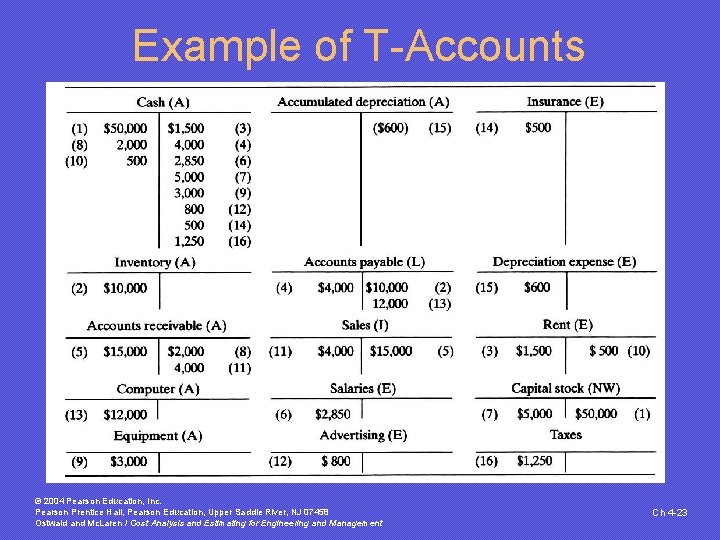
Example of T-Accounts © 2004 Pearson Education, Inc. Pearson Prentice Hall, Pearson Education, Upper Saddle River, NJ 07458 Ostwald and Mc. Laren / Cost Analysis and Estimating for Engineering and Management Ch 4 -23
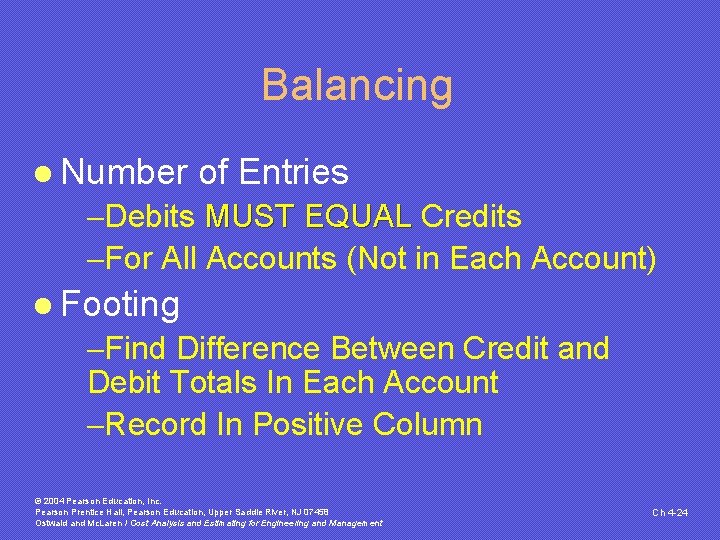
Balancing l Number of Entries -Debits MUST EQUAL Credits MUST EQUAL -For All Accounts (Not in Each Account) l Footing -Find Difference Between Credit and Debit Totals In Each Account -Record In Positive Column © 2004 Pearson Education, Inc. Pearson Prentice Hall, Pearson Education, Upper Saddle River, NJ 07458 Ostwald and Mc. Laren / Cost Analysis and Estimating for Engineering and Management Ch 4 -24
Finish Balancing l Balance In Each Account -Debit -Credit -“Closed” (Debit = Credit) l Balance the Books -Sum of All Debit Accounts MUST EQUAL Sum of All Credit Accounts © 2004 Pearson Education, Inc. Pearson Prentice Hall, Pearson Education, Upper Saddle River, NJ 07458 Ostwald and Mc. Laren / Cost Analysis and Estimating for Engineering and Management Ch 4 -25
Statements l Balance Sheet -“Snap Shot” at a Point in Time -Summary of Assets, Liabilities and NW l Profit and Loss Statement -Income and Expense Summary -Over a Specified Period of Time © 2004 Pearson Education, Inc. Pearson Prentice Hall, Pearson Education, Upper Saddle River, NJ 07458 Ostwald and Mc. Laren / Cost Analysis and Estimating for Engineering and Management Ch 4 -26
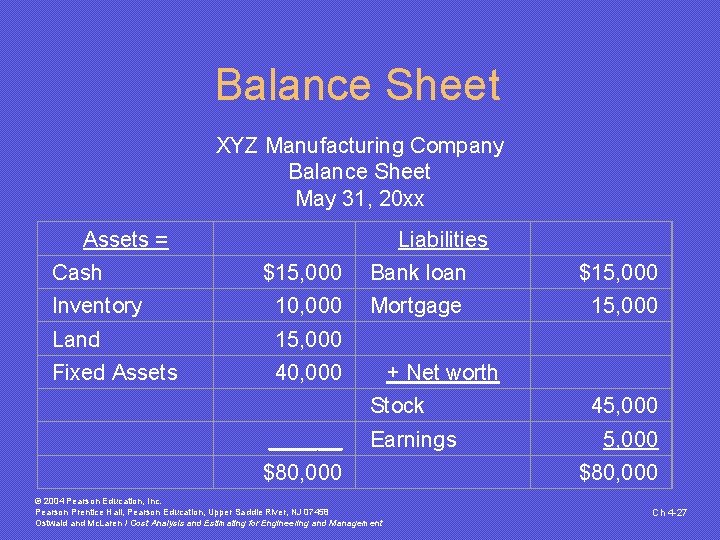
Balance Sheet XYZ Manufacturing Company Balance Sheet May 31, 20 xx Assets = Cash Liabilities $15, 000 Bank loan $15, 000 Inventory 10, 000 Mortgage 15, 000 Land 15, 000 Fixed Assets 40, 000 + Net worth Stock ______ $80, 000 Earnings © 2004 Pearson Education, Inc. Pearson Prentice Hall, Pearson Education, Upper Saddle River, NJ 07458 Ostwald and Mc. Laren / Cost Analysis and Estimating for Engineering and Management 45, 000 $80, 000 Ch 4 -27
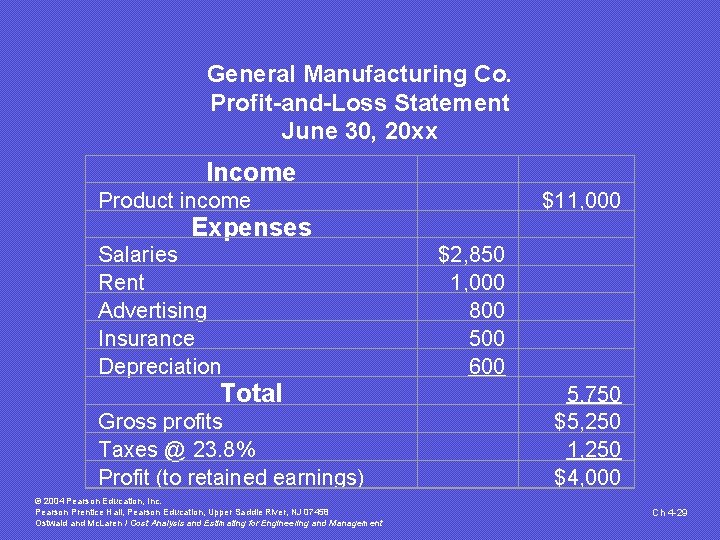
Profit and Loss Statement l Or Income and Expense Statement l Profit: Excess of Revenue Over Cost -Including Depreciation and Taxes l Loss: Excess of Cost Over Revenue -Including Depreciation -Taxes Are Not Owed In Loss Situation l Profit/Loss Included In Net Worth © 2004 Pearson Education, Inc. Pearson Prentice Hall, Pearson Education, Upper Saddle River, NJ 07458 Ostwald and Mc. Laren / Cost Analysis and Estimating for Engineering and Management Ch 4 -28
General Manufacturing Co. Profit-and-Loss Statement June 30, 20 xx Income Product income Expenses Salaries Rent Advertising Insurance Depreciation Total Gross profits Taxes @ 23. 8% Profit (to retained earnings) © 2004 Pearson Education, Inc. Pearson Prentice Hall, Pearson Education, Upper Saddle River, NJ 07458 Ostwald and Mc. Laren / Cost Analysis and Estimating for Engineering and Management $11, 000 $2, 850 1, 000 800 500 600 5, 750 $5, 250 1, 250 $4, 000 Ch 4 -29
Capital Assets l Money Spent -Larger Amounts -Long Period of Use l Decreasing Value Over Time -Physical Wear for Operation -Obsolescence -Regulations © 2004 Pearson Education, Inc. Pearson Prentice Hall, Pearson Education, Upper Saddle River, NJ 07458 Ostwald and Mc. Laren / Cost Analysis and Estimating for Engineering and Management Ch 4 -30
Depreciation l Accounting Charge -Provides for Recovery of Capital Costs -Over Time l NOT a Cash Expenditure (Transaction) -Money Spent for Initial Acquisition l Deduction to Income Statement -Largely for Tax Purposes © 2004 Pearson Education, Inc. Pearson Prentice Hall, Pearson Education, Upper Saddle River, NJ 07458 Ostwald and Mc. Laren / Cost Analysis and Estimating for Engineering and Management Ch 4 -31
Property (Assets) l Life -Longer Than One Year -Economic Life Physical Life l Tangible l Intangible l Real -Land Is Not Depreciated © 2004 Pearson Education, Inc. Pearson Prentice Hall, Pearson Education, Upper Saddle River, NJ 07458 Ostwald and Mc. Laren / Cost Analysis and Estimating for Engineering and Management Ch 4 -32
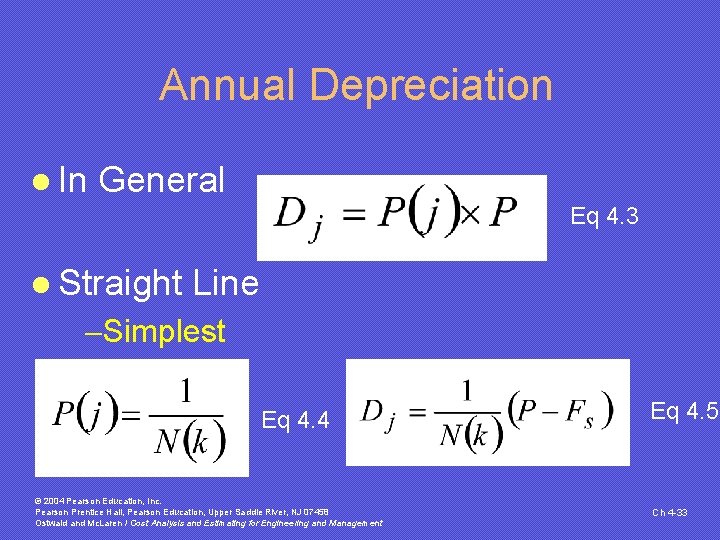
Annual Depreciation l In General Eq 4. 3 l Straight Line -Simplest Eq 4. 4 © 2004 Pearson Education, Inc. Pearson Prentice Hall, Pearson Education, Upper Saddle River, NJ 07458 Ostwald and Mc. Laren / Cost Analysis and Estimating for Engineering and Management Eq 4. 5 Ch 4 -33
Definitions l Salvage Value -Value Left at End of Depreciation Life -What Asset Could Be Sold for l Book Value Investment – Salvage – Depreciation © 2004 Pearson Education, Inc. Pearson Prentice Hall, Pearson Education, Upper Saddle River, NJ 07458 Ostwald and Mc. Laren / Cost Analysis and Estimating for Engineering and Management Ch 4 -34
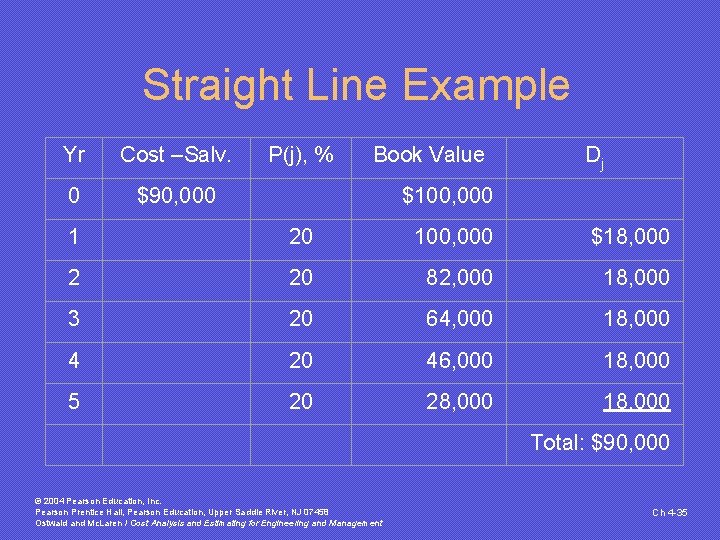
Straight Line Example Yr Cost –Salv. P(j), % 0 $90, 000 1 2 Book Value Dj $100, 000 20 100, 000 $18, 000 20 82, 000 18, 000 3 20 64, 000 18, 000 4 20 46, 000 18, 000 5 20 28, 000 18, 000 Total: $90, 000 © 2004 Pearson Education, Inc. Pearson Prentice Hall, Pearson Education, Upper Saddle River, NJ 07458 Ostwald and Mc. Laren / Cost Analysis and Estimating for Engineering and Management Ch 4 -35
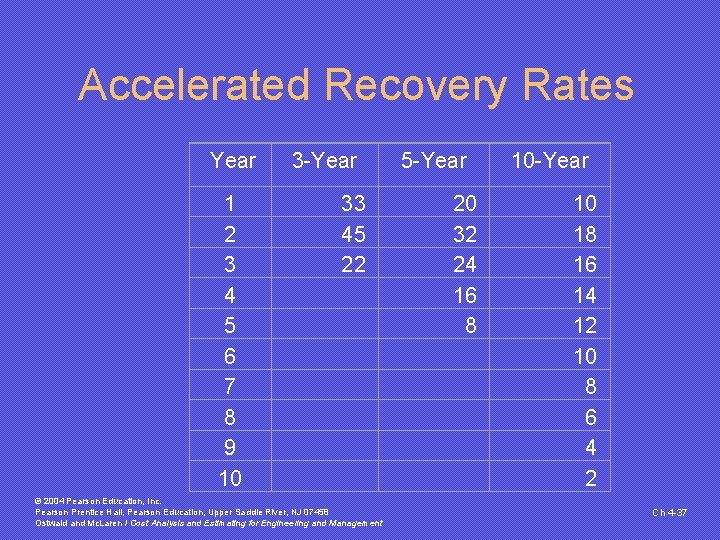
Accelerated Cost Recovery l Costs Recovered More Quickly l Allowed by Tax Laws -Certain Methods -MACRS l Better Approximates Actual Life Cycle l Helps Company Profits and Operations © 2004 Pearson Education, Inc. Pearson Prentice Hall, Pearson Education, Upper Saddle River, NJ 07458 Ostwald and Mc. Laren / Cost Analysis and Estimating for Engineering and Management Ch 4 -36
Accelerated Recovery Rates Year 1 2 3 4 5 6 7 8 9 10 3 -Year 5 -Year 33 45 22 10 -Year 20 32 24 16 8 © 2004 Pearson Education, Inc. Pearson Prentice Hall, Pearson Education, Upper Saddle River, NJ 07458 Ostwald and Mc. Laren / Cost Analysis and Estimating for Engineering and Management 10 18 16 14 12 10 8 6 4 2 Ch 4 -37
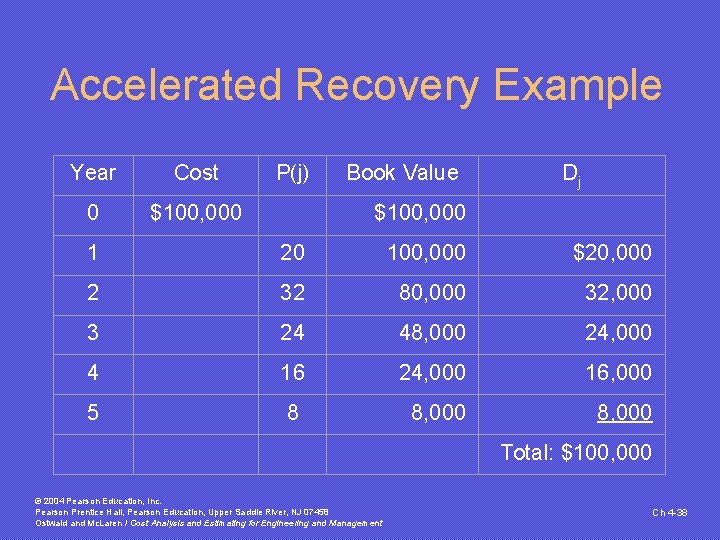
Accelerated Recovery Example Year Cost P(j) 0 $100, 000 1 2 Book Value Dj $100, 000 20 100, 000 $20, 000 32 80, 000 32, 000 3 24 48, 000 24, 000 4 16 24, 000 16, 000 5 8 8, 000 Total: $100, 000 © 2004 Pearson Education, Inc. Pearson Prentice Hall, Pearson Education, Upper Saddle River, NJ 07458 Ostwald and Mc. Laren / Cost Analysis and Estimating for Engineering and Management Ch 4 -38
Budgeting l Written Plan l For a Future Period l Based On: -Cost Estimating -Accounting Records -Conjectures of Future Activity © 2004 Pearson Education, Inc. Pearson Prentice Hall, Pearson Education, Upper Saddle River, NJ 07458 Ostwald and Mc. Laren / Cost Analysis and Estimating for Engineering and Management Ch 4 -39
Budget Types l Appropriation -Proposed Expenditures -Usually for Big Items (Building, Equip. ) l Fixed Budget -For Departments l Variable Budgets -Tied to Activity Levels -Highlights Variations from Planned © 2004 Pearson Education, Inc. Pearson Prentice Hall, Pearson Education, Upper Saddle River, NJ 07458 Ostwald and Mc. Laren / Cost Analysis and Estimating for Engineering and Management Ch 4 -40
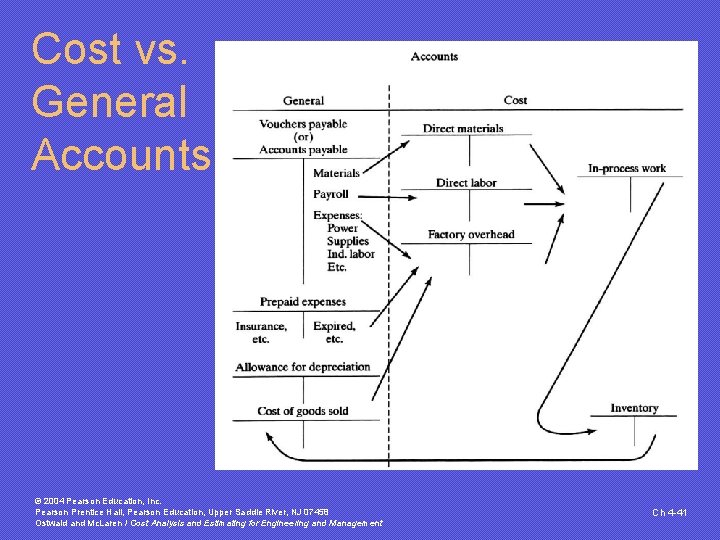
Cost vs. General Accounts © 2004 Pearson Education, Inc. Pearson Prentice Hall, Pearson Education, Upper Saddle River, NJ 07458 Ostwald and Mc. Laren / Cost Analysis and Estimating for Engineering and Management Ch 4 -41
Overhead l Collect Costs -Not Tied More Directly to Production -Obtained from Budgets l Distribute -Rational Apportioning to Products l Allow Accurate Estimates & Quotes -Along With Direct Costs © 2004 Pearson Education, Inc. Pearson Prentice Hall, Pearson Education, Upper Saddle River, NJ 07458 Ostwald and Mc. Laren / Cost Analysis and Estimating for Engineering and Management Ch 4 -42
About Costs l Direct Labor Costs -Uses Gross Hourly Cost Rate l Utilization -Attribute of Machines -Percent of Possible Time In Use ( 100%) l Efficiency -Attribute of Labor -Level and Amount of Effort © 2004 Pearson Education, Inc. Pearson Prentice Hall, Pearson Education, Upper Saddle River, NJ 07458 Ostwald and Mc. Laren / Cost Analysis and Estimating for Engineering and Management Ch 4 -43
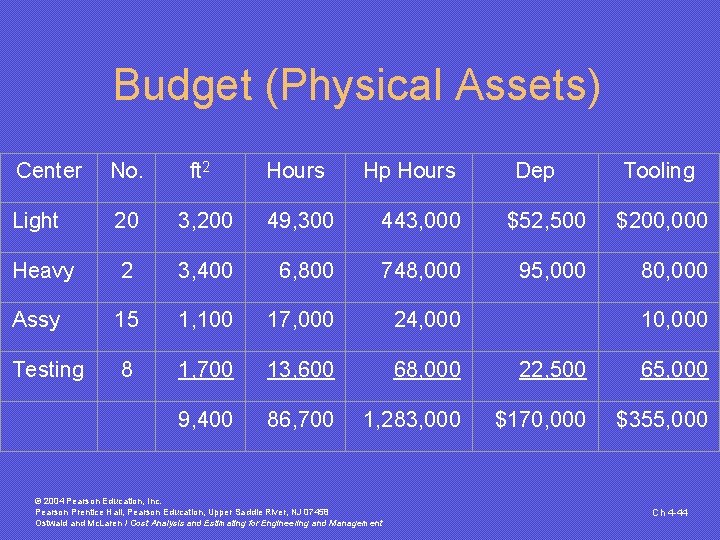
Budget (Physical Assets) Center No. ft 2 Hours Light 20 3, 200 49, 300 443, 000 $52, 500 $200, 000 Heavy 2 3, 400 6, 800 748, 000 95, 000 80, 000 Assy 15 1, 100 17, 000 24, 000 10, 000 Testing 8 1, 700 13, 600 68, 000 22, 500 65, 000 9, 400 86, 700 1, 283, 000 $170, 000 $355, 000 Hp Hours © 2004 Pearson Education, Inc. Pearson Prentice Hall, Pearson Education, Upper Saddle River, NJ 07458 Ostwald and Mc. Laren / Cost Analysis and Estimating for Engineering and Management Dep Tooling Ch 4 -44
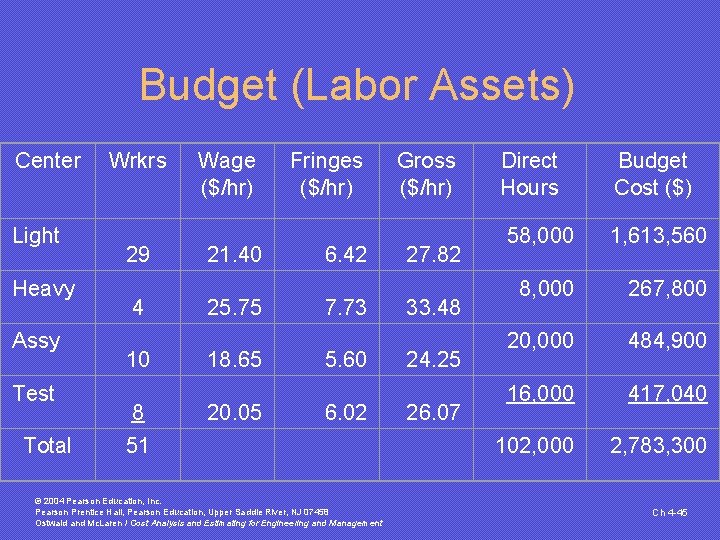
Budget (Labor Assets) Center Light Heavy Assy Test Total Wrkrs 29 4 10 8 51 Wage ($/hr) 21. 40 25. 75 18. 65 Fringes ($/hr) 6. 42 7. 73 5. 60 Gross ($/hr) 27. 82 33. 48 24. 25 20. 05 6. 02 26. 07 © 2004 Pearson Education, Inc. Pearson Prentice Hall, Pearson Education, Upper Saddle River, NJ 07458 Ostwald and Mc. Laren / Cost Analysis and Estimating for Engineering and Management Direct Hours Budget Cost ($) 58, 000 1, 613, 560 8, 000 267, 800 20, 000 484, 900 16, 000 417, 040 102, 000 2, 783, 300 Ch 4 -45
Collecting Overhead Costs l Costs Tied to Production -But Not to Specific Products l General Costs -Engineering -Management -Sales © 2004 Pearson Education, Inc. Pearson Prentice Hall, Pearson Education, Upper Saddle River, NJ 07458 Ostwald and Mc. Laren / Cost Analysis and Estimating for Engineering and Management Ch 4 -46
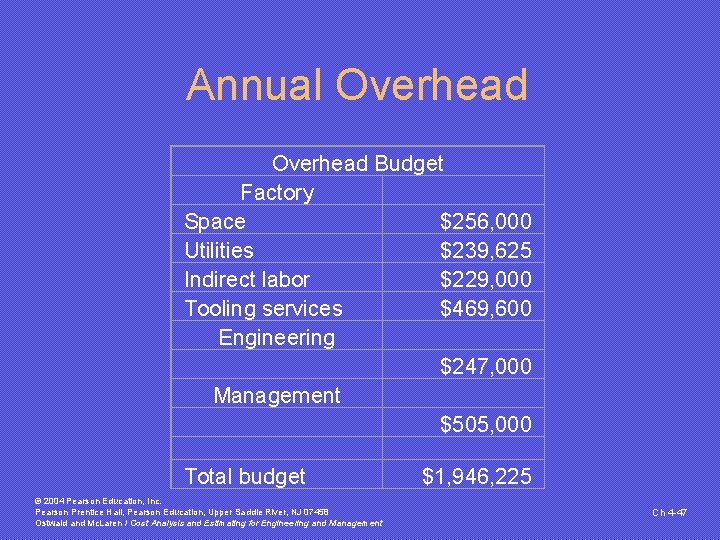
Annual Overhead Budget Factory Space $256, 000 Utilities $239, 625 Indirect labor $229, 000 Tooling services $469, 600 Engineering $247, 000 Management $505, 000 Total budget © 2004 Pearson Education, Inc. Pearson Prentice Hall, Pearson Education, Upper Saddle River, NJ 07458 Ostwald and Mc. Laren / Cost Analysis and Estimating for Engineering and Management $1, 946, 225 Ch 4 -47
Allocating Overhead Costs l Single Overhead Rate (Traditional) -Divide Total Overhead Over Some Measure of Production -e. g. Per Direct Labor Hour (Burden) -Misleading, Does Not Apportion Overhead as It Is Used © 2004 Pearson Education, Inc. Pearson Prentice Hall, Pearson Education, Upper Saddle River, NJ 07458 Ostwald and Mc. Laren / Cost Analysis and Estimating for Engineering and Management Ch 4 -48
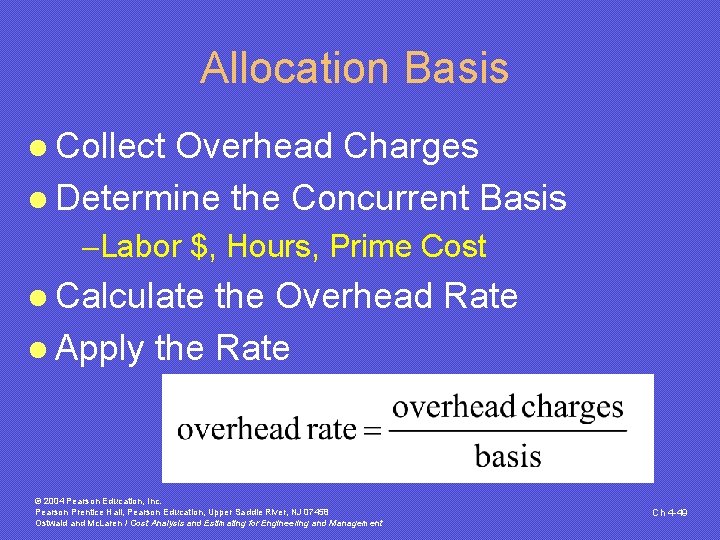
Allocation Basis l Collect Overhead Charges l Determine the Concurrent Basis -Labor $, Hours, Prime Cost l Calculate the Overhead Rate l Apply the Rate © 2004 Pearson Education, Inc. Pearson Prentice Hall, Pearson Education, Upper Saddle River, NJ 07458 Ostwald and Mc. Laren / Cost Analysis and Estimating for Engineering and Management Ch 4 -49
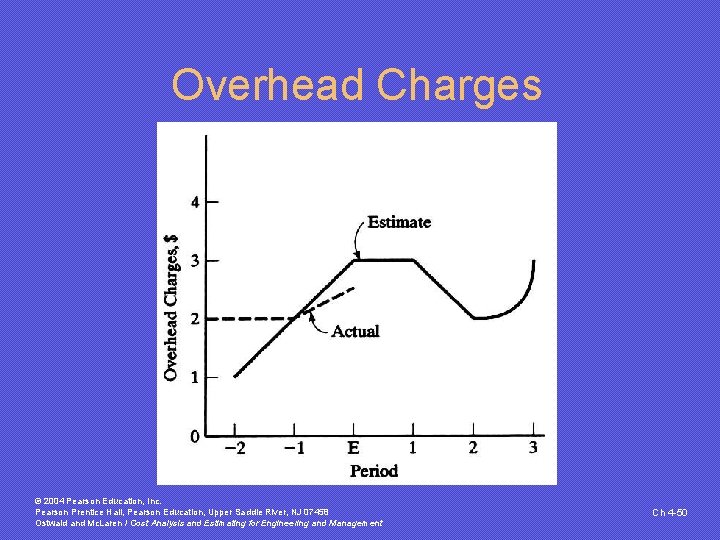
Overhead Charges © 2004 Pearson Education, Inc. Pearson Prentice Hall, Pearson Education, Upper Saddle River, NJ 07458 Ostwald and Mc. Laren / Cost Analysis and Estimating for Engineering and Management Ch 4 -50
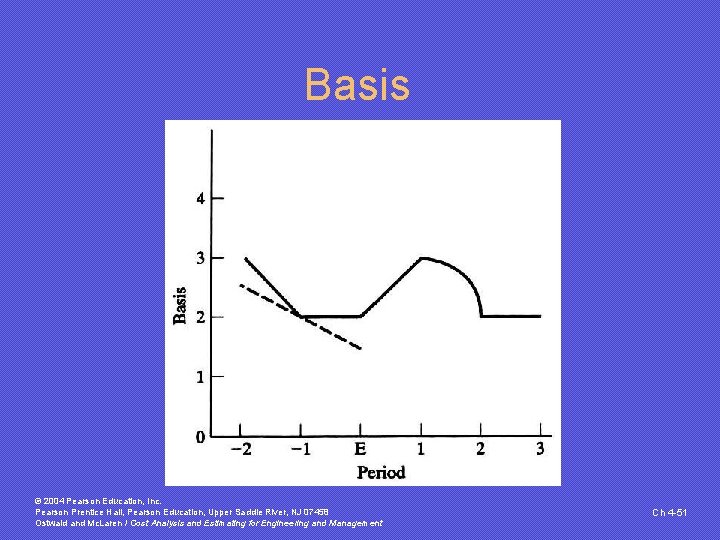
Basis © 2004 Pearson Education, Inc. Pearson Prentice Hall, Pearson Education, Upper Saddle River, NJ 07458 Ostwald and Mc. Laren / Cost Analysis and Estimating for Engineering and Management Ch 4 -51
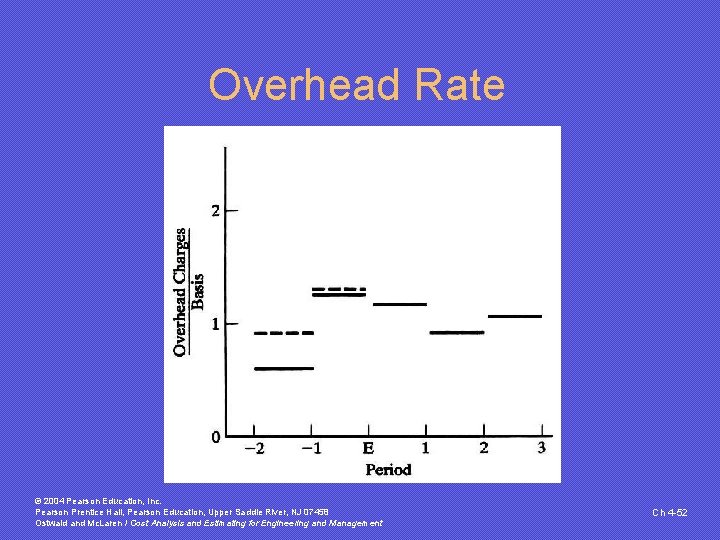
Overhead Rate © 2004 Pearson Education, Inc. Pearson Prentice Hall, Pearson Education, Upper Saddle River, NJ 07458 Ostwald and Mc. Laren / Cost Analysis and Estimating for Engineering and Management Ch 4 -52
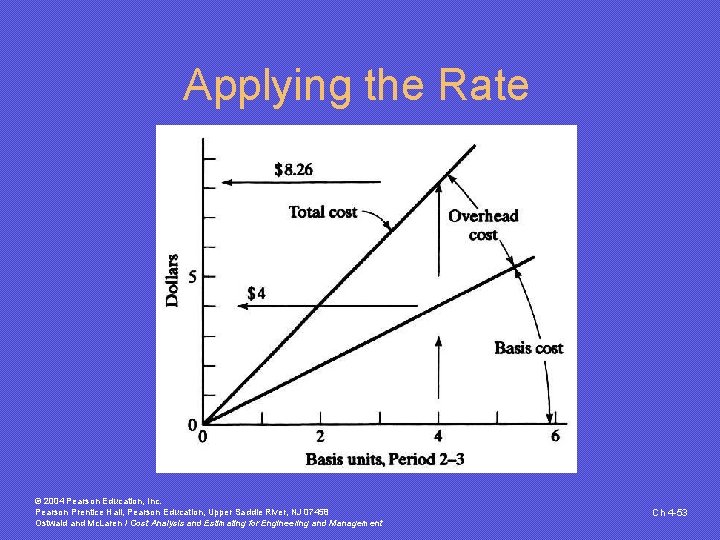
Applying the Rate © 2004 Pearson Education, Inc. Pearson Prentice Hall, Pearson Education, Upper Saddle River, NJ 07458 Ostwald and Mc. Laren / Cost Analysis and Estimating for Engineering and Management Ch 4 -53
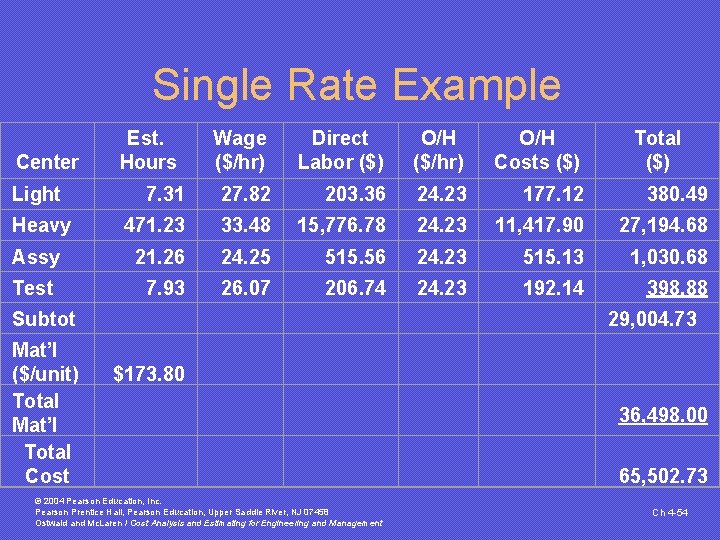
Single Rate Example Center Est. Hours Wage ($/hr) 7. 31 27. 82 Direct Labor ($) 203. 36 471. 23 33. 48 15, 776. 78 24. 23 11, 417. 90 27, 194. 68 Assy 21. 26 24. 25 515. 56 24. 23 515. 13 1, 030. 68 Test 7. 93 26. 07 206. 74 24. 23 192. 14 398. 88 Subtot Mat’l ($/unit) Total Mat’l Total Cost $173. 80 Light Heavy O/H ($/hr) O/H Costs ($) Total ($) 24. 23 177. 12 380. 49 29, 004. 73 36, 498. 00 65, 502. 73 © 2004 Pearson Education, Inc. Pearson Prentice Hall, Pearson Education, Upper Saddle River, NJ 07458 Ostwald and Mc. Laren / Cost Analysis and Estimating for Engineering and Management Ch 4 -54
Productive Hour Cost l Collect O/H Charges by Category l Apportion O/H Charges by Use l Examples -Maintenance to Equipment -Management to Labor © 2004 Pearson Education, Inc. Pearson Prentice Hall, Pearson Education, Upper Saddle River, NJ 07458 Ostwald and Mc. Laren / Cost Analysis and Estimating for Engineering and Management Ch 4 -55
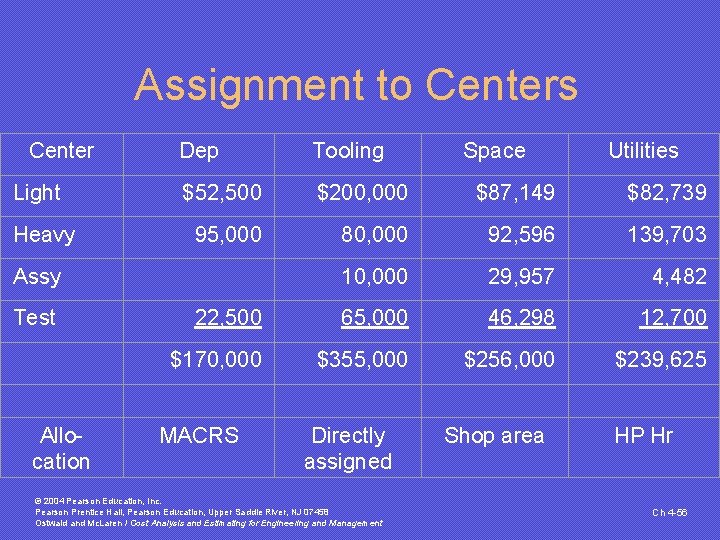
Assignment to Centers Center Light Heavy Dep Tooling $52, 500 $200, 000 $87, 149 $82, 739 95, 000 80, 000 92, 596 139, 703 10, 000 29, 957 4, 482 22, 500 65, 000 46, 298 12, 700 $170, 000 $355, 000 $256, 000 $239, 625 Assy Test Allocation MACRS Directly assigned © 2004 Pearson Education, Inc. Pearson Prentice Hall, Pearson Education, Upper Saddle River, NJ 07458 Ostwald and Mc. Laren / Cost Analysis and Estimating for Engineering and Management Space Shop area Utilities HP Hr Ch 4 -56
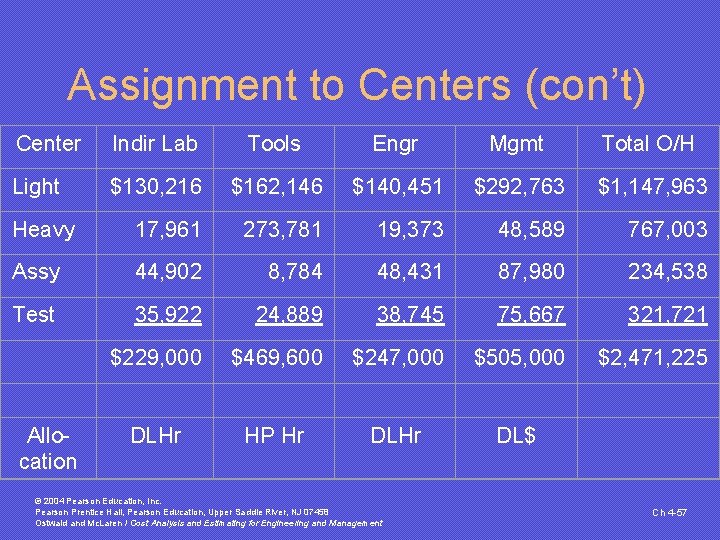
Assignment to Centers (con’t) Center Indir Lab Tools Engr Mgmt Total O/H Light $130, 216 $162, 146 $140, 451 $292, 763 $1, 147, 963 Heavy 17, 961 273, 781 19, 373 48, 589 767, 003 Assy 44, 902 8, 784 48, 431 87, 980 234, 538 Test 35, 922 24, 889 38, 745 75, 667 321, 721 $229, 000 $469, 600 $247, 000 $505, 000 $2, 471, 225 Allocation DLHr HP Hr DLHr © 2004 Pearson Education, Inc. Pearson Prentice Hall, Pearson Education, Upper Saddle River, NJ 07458 Ostwald and Mc. Laren / Cost Analysis and Estimating for Engineering and Management DL$ Ch 4 -57
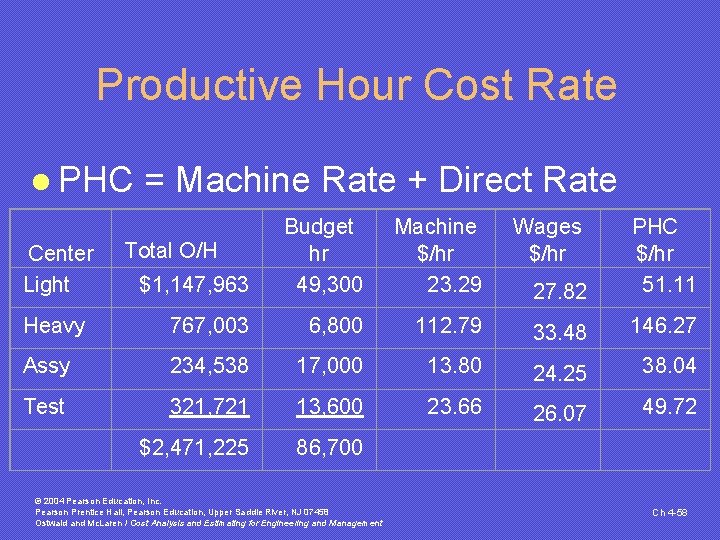
Productive Hour Cost Rate l PHC = Machine Rate + Direct Rate Center Light Machine $/hr 23. 29 Wages $/hr $1, 147, 963 Budget hr 49, 300 27. 82 PHC $/hr 51. 11 Heavy 767, 003 6, 800 112. 79 33. 48 146. 27 Assy 234, 538 17, 000 13. 80 24. 25 38. 04 Test 321, 721 13, 600 23. 66 26. 07 49. 72 $2, 471, 225 86, 700 Total O/H © 2004 Pearson Education, Inc. Pearson Prentice Hall, Pearson Education, Upper Saddle River, NJ 07458 Ostwald and Mc. Laren / Cost Analysis and Estimating for Engineering and Management Ch 4 -58
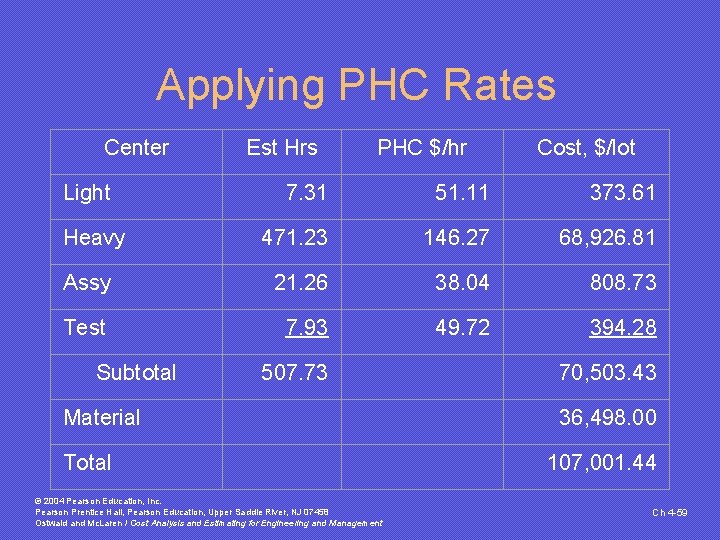
Applying PHC Rates Center Est Hrs Light PHC $/hr Cost, $/lot 7. 31 51. 11 373. 61 471. 23 146. 27 68, 926. 81 Assy 21. 26 38. 04 808. 73 Test 7. 93 49. 72 394. 28 Heavy Subtotal 507. 73 70, 503. 43 Material 36, 498. 00 Total 107, 001. 44 © 2004 Pearson Education, Inc. Pearson Prentice Hall, Pearson Education, Upper Saddle River, NJ 07458 Ostwald and Mc. Laren / Cost Analysis and Estimating for Engineering and Management Ch 4 -59
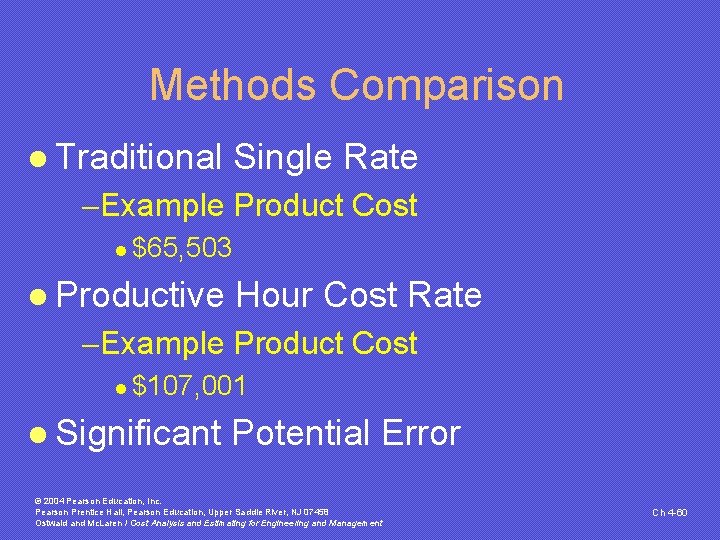
Methods Comparison l Traditional Single Rate -Example Product Cost l $65, 503 l Productive Hour Cost Rate -Example Product Cost l $107, 001 l Significant Potential Error © 2004 Pearson Education, Inc. Pearson Prentice Hall, Pearson Education, Upper Saddle River, NJ 07458 Ostwald and Mc. Laren / Cost Analysis and Estimating for Engineering and Management Ch 4 -60
Activity Based Costing (ABC) l Volume Related Cost Drivers -Number of Product Units Built Directly Effects Costs l Non-Volume Related Cost Drivers -Costs Not Effected by Number of Units -Can Be Determined By Various Factors -e. g. Engineering, Upper Management © 2004 Pearson Education, Inc. Pearson Prentice Hall, Pearson Education, Upper Saddle River, NJ 07458 Ostwald and Mc. Laren / Cost Analysis and Estimating for Engineering and Management Ch 4 -61
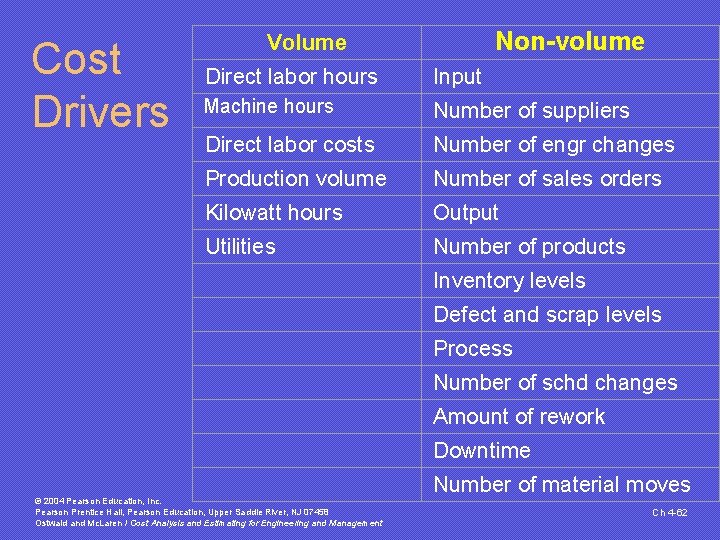
Cost Drivers Non-volume Volume Direct labor hours Machine hours Input Number of suppliers Direct labor costs Number of engr changes Production volume Number of sales orders Kilowatt hours Output Utilities Number of products Inventory levels Defect and scrap levels Process Number of schd changes Amount of rework Downtime Number of material moves © 2004 Pearson Education, Inc. Pearson Prentice Hall, Pearson Education, Upper Saddle River, NJ 07458 Ostwald and Mc. Laren / Cost Analysis and Estimating for Engineering and Management Ch 4 -62
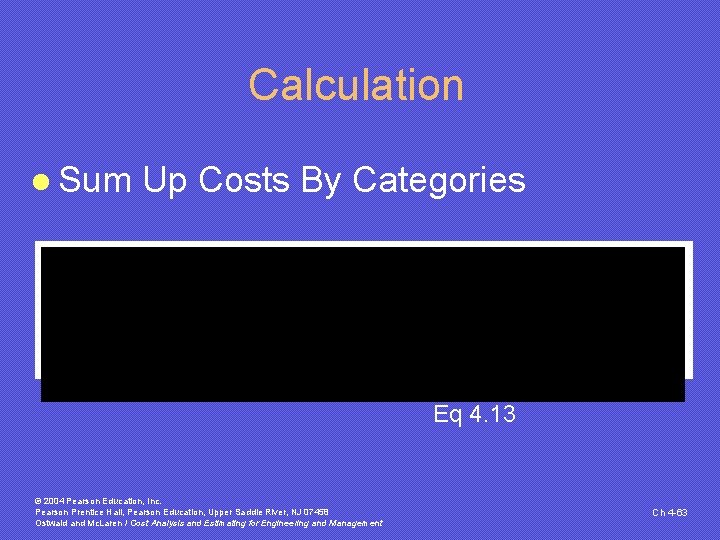
Calculation l Sum Up Costs By Categories Eq 4. 13 © 2004 Pearson Education, Inc. Pearson Prentice Hall, Pearson Education, Upper Saddle River, NJ 07458 Ostwald and Mc. Laren / Cost Analysis and Estimating for Engineering and Management Ch 4 -63
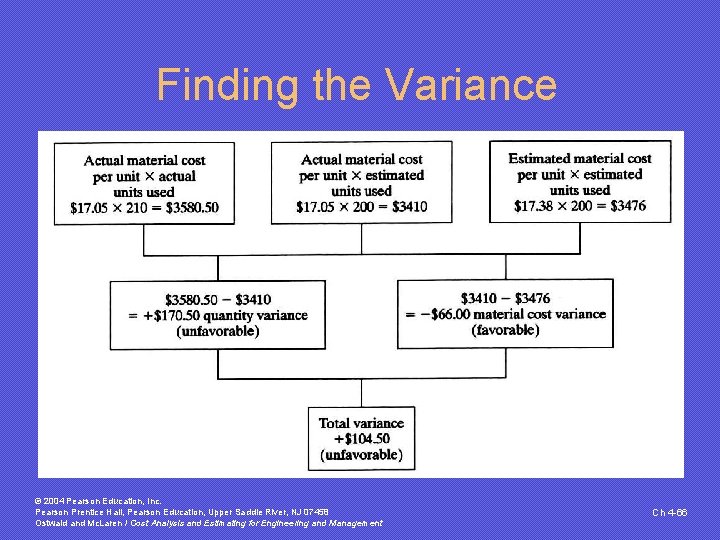
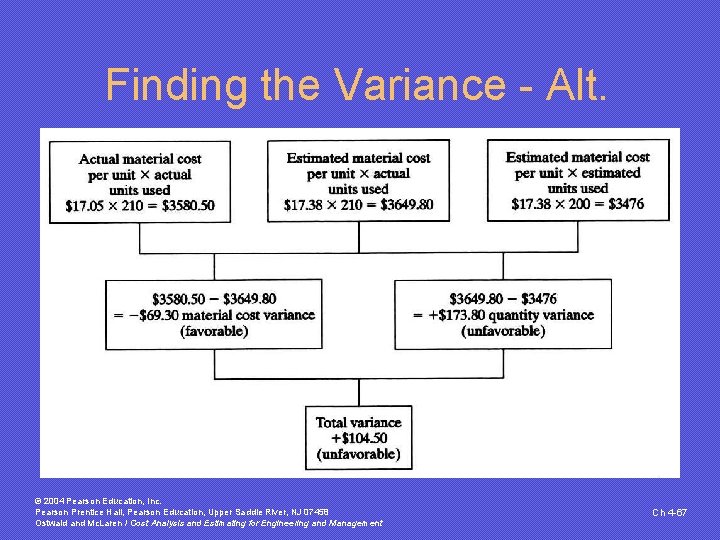
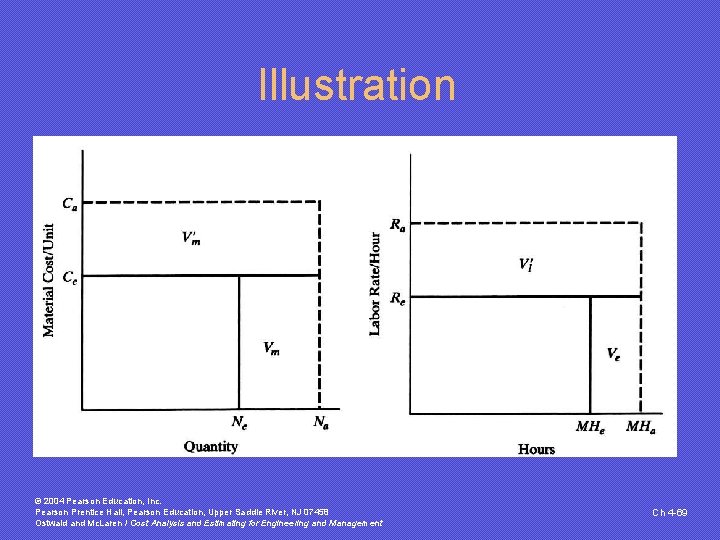
Variance l Compare Budget to Actual Costs l Variance Indicates Deviation from Plan l Unfavorable Variance -Actual Costs Exceed Standard Costs l Favorable Variance -Actual Costs Are Less Than Standard -Not Always Beneficial to the Company © 2004 Pearson Education, Inc. Pearson Prentice Hall, Pearson Education, Upper Saddle River, NJ 07458 Ostwald and Mc. Laren / Cost Analysis and Estimating for Engineering and Management Ch 4 -64
Evaluation of Variance l Unfavorable Variance -Example Increased Cost Due to Higher Production Than Planned -Probably Results in More Profit for the Company l Favorable Variance -Could Be from Lower Number of Orders © 2004 Pearson Education, Inc. Pearson Prentice Hall, Pearson Education, Upper Saddle River, NJ 07458 Ostwald and Mc. Laren / Cost Analysis and Estimating for Engineering and Management Ch 4 -65
Finding the Variance © 2004 Pearson Education, Inc. Pearson Prentice Hall, Pearson Education, Upper Saddle River, NJ 07458 Ostwald and Mc. Laren / Cost Analysis and Estimating for Engineering and Management Ch 4 -66
Finding the Variance - Alt. © 2004 Pearson Education, Inc. Pearson Prentice Hall, Pearson Education, Upper Saddle River, NJ 07458 Ostwald and Mc. Laren / Cost Analysis and Estimating for Engineering and Management Ch 4 -67
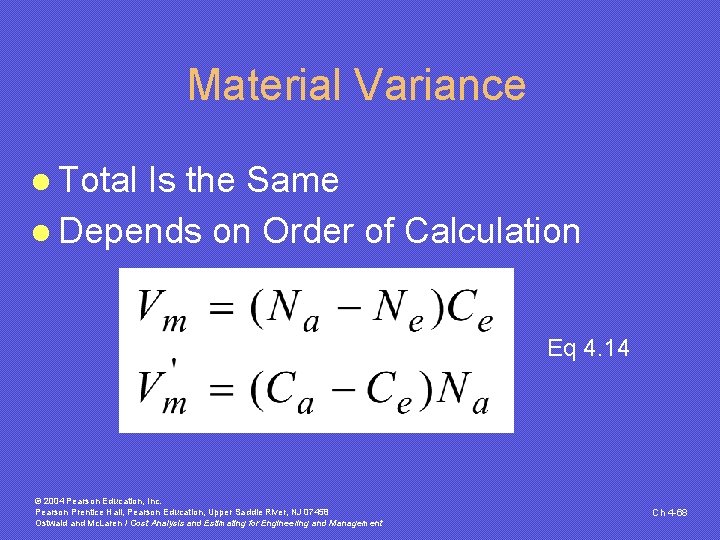
Material Variance l Total Is the Same l Depends on Order of Calculation Eq 4. 14 © 2004 Pearson Education, Inc. Pearson Prentice Hall, Pearson Education, Upper Saddle River, NJ 07458 Ostwald and Mc. Laren / Cost Analysis and Estimating for Engineering and Management Ch 4 -68
Illustration © 2004 Pearson Education, Inc. Pearson Prentice Hall, Pearson Education, Upper Saddle River, NJ 07458 Ostwald and Mc. Laren / Cost Analysis and Estimating for Engineering and Management Ch 4 -69
Use of Variances l Monitor and Control -Find Causes of Variance -Correct Causes or Budget Process l Example -Extra Production l Scrap or More Orders -Scrap is Production Problem -More Orders Is Sales Forecast Problem © 2004 Pearson Education, Inc. Pearson Prentice Hall, Pearson Education, Upper Saddle River, NJ 07458 Ostwald and Mc. Laren / Cost Analysis and Estimating for Engineering and Management Ch 4 -70
Summary l How Accounting Works and Fits l Working With and Impact of Depreciation l What a Budget Is, What It’s Used For l Determine and Apply Overhead Rates l Use Variance for Monitor and Control © 2004 Pearson Education, Inc. Pearson Prentice Hall, Pearson Education, Upper Saddle River, NJ 07458 Ostwald and Mc. Laren / Cost Analysis and Estimating for Engineering and Management Ch 4 -71