
Copyright 2005 Pearson Education Inc 1 Chapter 4
- Slides: 24
Copyright © 2005 Pearson Education, Inc. 1
Chapter 4 Copyright © 2005 Pearson Education, Inc.
4 -A Definitions n n n The principal in financial formulas is the balance upon which interest is paid. Simple interest is interest paid only on the original principal, an not on any interest added at later dates. Compound interest is interest paid on both the original principal and on all interest that has been added to the original principal. Copyright © 2005 Pearson Education, Inc. 3
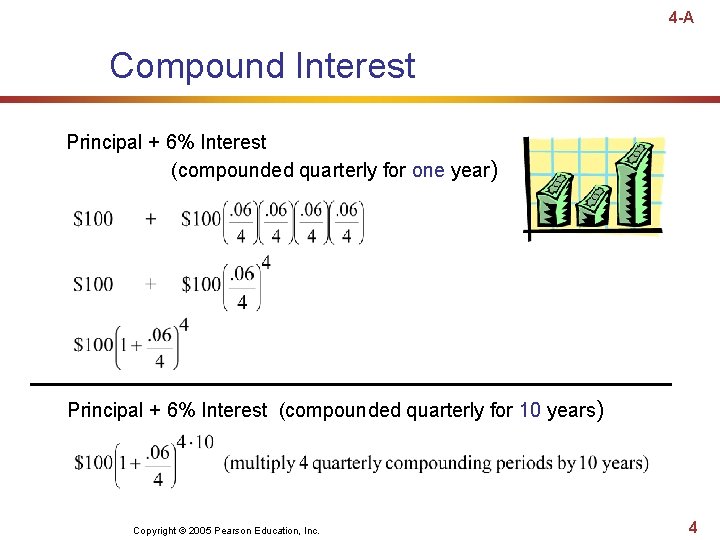
4 -A Compound Interest Principal + 6% Interest (compounded quarterly for one year) Principal + 6% Interest (compounded quarterly for 10 years) Copyright © 2005 Pearson Education, Inc. 4
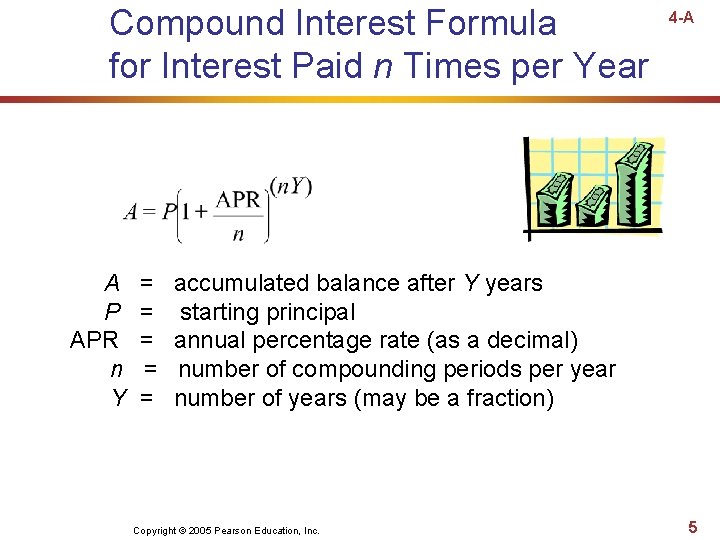
Compound Interest Formula for Interest Paid n Times per Year A P APR n Y = = = 4 -A accumulated balance after Y years starting principal annual percentage rate (as a decimal) number of compounding periods per year number of years (may be a fraction) Copyright © 2005 Pearson Education, Inc. 5
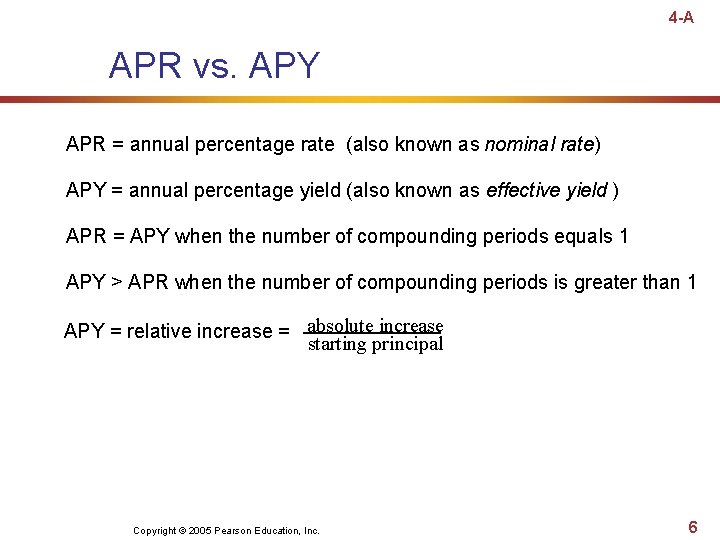
4 -A APR vs. APY APR = annual percentage rate (also known as nominal rate) APY = annual percentage yield (also known as effective yield ) APR = APY when the number of compounding periods equals 1 APY > APR when the number of compounding periods is greater than 1 APY = relative increase = absolute increase starting principal Copyright © 2005 Pearson Education, Inc. 6
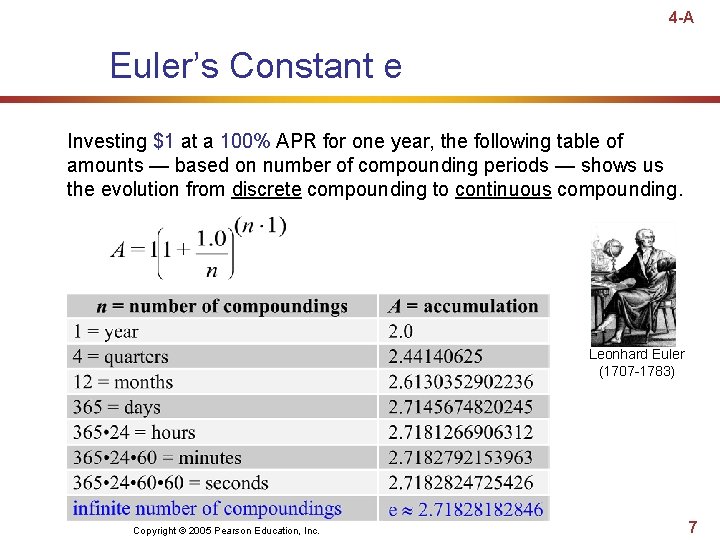
4 -A Euler’s Constant e Investing $1 at a 100% APR for one year, the following table of amounts — based on number of compounding periods — shows us the evolution from discrete compounding to continuous compounding. Leonhard Euler (1707 -1783) Copyright © 2005 Pearson Education, Inc. 7
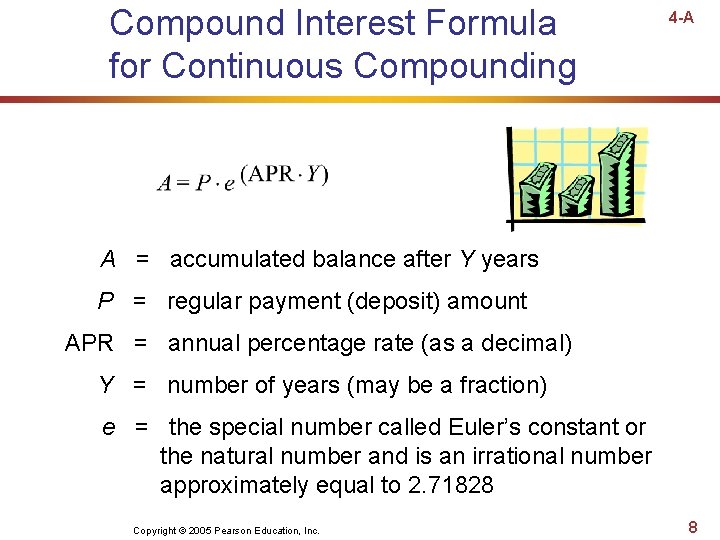
Compound Interest Formula for Continuous Compounding 4 -A A = accumulated balance after Y years P = regular payment (deposit) amount APR = annual percentage rate (as a decimal) Y = number of years (may be a fraction) e = the special number called Euler’s constant or the natural number and is an irrational number approximately equal to 2. 71828 Copyright © 2005 Pearson Education, Inc. 8
4 -B Social Security and Savings Plans “Social Security can furnish only a base upon which each one of our citizens may build his individual security through his own individual efforts. ” President Franklin D. Roosevelt The Franklin Delano Roosevelt Memorial in Washington D. C. Copyright © 2005 Pearson Education, Inc. 9
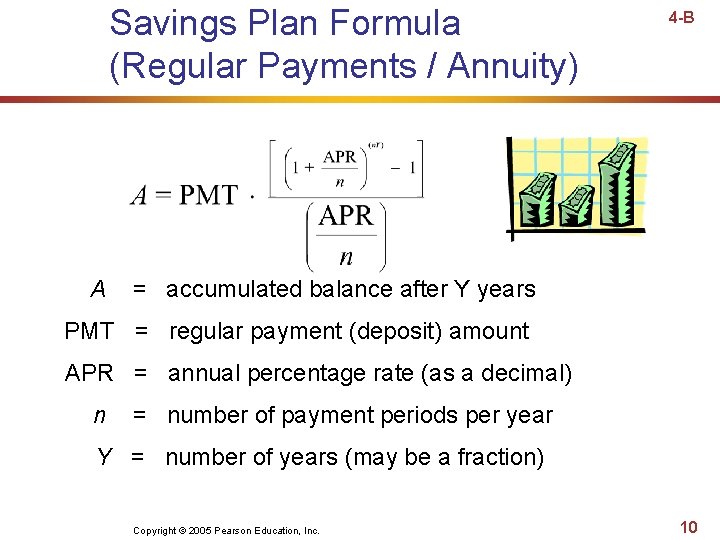
Savings Plan Formula (Regular Payments / Annuity) A 4 -B = accumulated balance after Y years PMT = regular payment (deposit) amount APR = annual percentage rate (as a decimal) n = number of payment periods per year Y = number of years (may be a fraction) Copyright © 2005 Pearson Education, Inc. 10
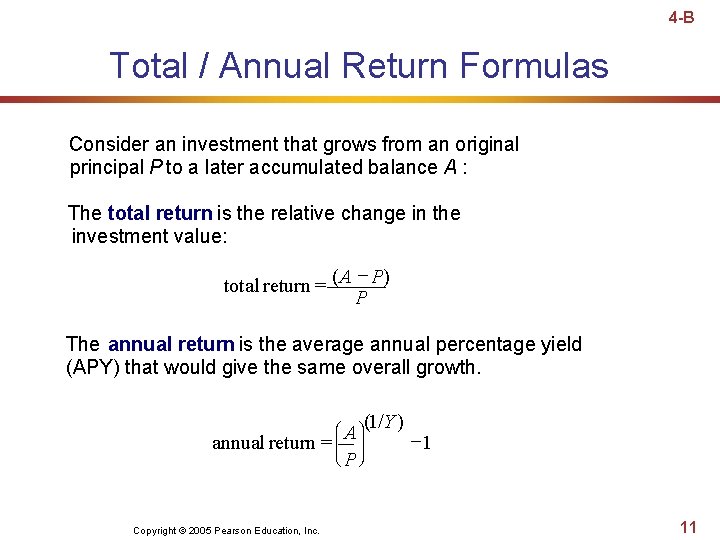
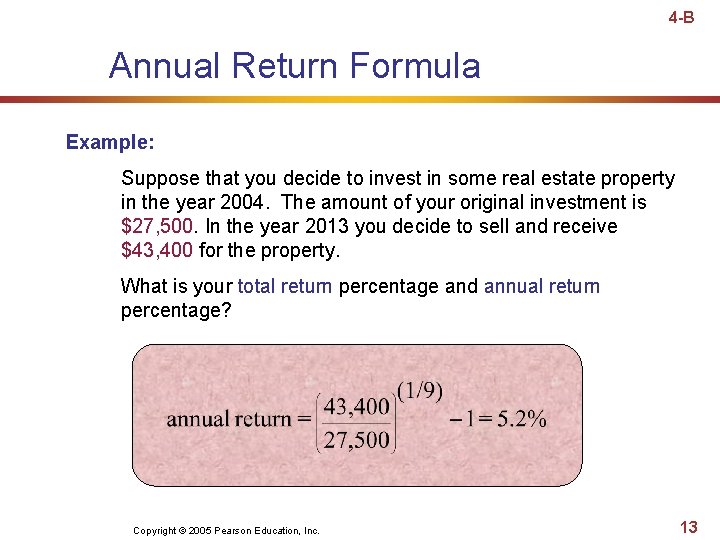
4 -B Total / Annual Return Formulas Consider an investment that grows from an original principal P to a later accumulated balance A : The total return is the relative change in the investment value: total return = ( A P) P The annual return is the average annual percentage yield (APY) that would give the same overall growth. æ ç ç ç è A ö÷ annual return = ÷÷ Pø Copyright © 2005 Pearson Education, Inc. (1/ Y ) -1 11
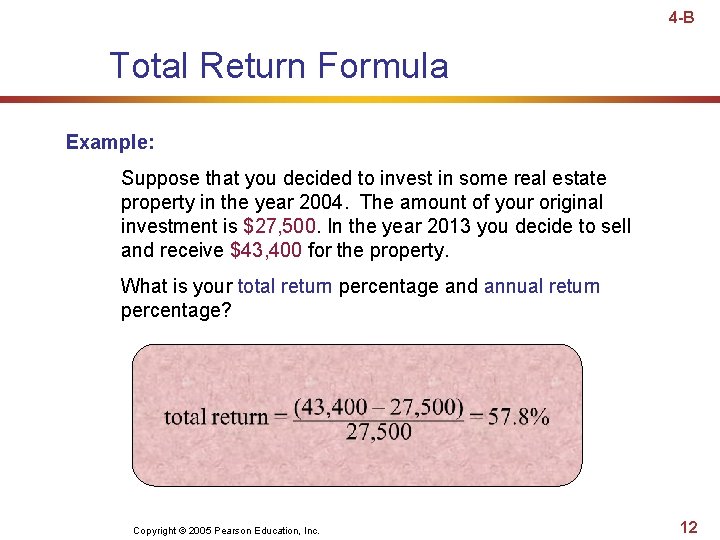
4 -B Total Return Formula Example: Suppose that you decided to invest in some real estate property in the year 2004. The amount of your original investment is $27, 500. In the year 2013 you decide to sell and receive $43, 400 for the property. What is your total return percentage and annual return percentage? Copyright © 2005 Pearson Education, Inc. 12
4 -B Annual Return Formula Example: Suppose that you decide to invest in some real estate property in the year 2004. The amount of your original investment is $27, 500. In the year 2013 you decide to sell and receive $43, 400 for the property. What is your total return percentage and annual return percentage? Copyright © 2005 Pearson Education, Inc. 13
4 -B Potential Retirement Sources 1. Pension 2. Personal Savings 3. Social Security Copyright © 2005 Pearson Education, Inc. 14
4 -B Types of Investments 1. Stocks 2. Bonds 3. Cash 4. Mutual Funds Copyright © 2005 Pearson Education, Inc. 15
4 -B Investment Considerations 1. Liquidity 2. Risk 3. Return Copyright © 2005 Pearson Education, Inc. 16
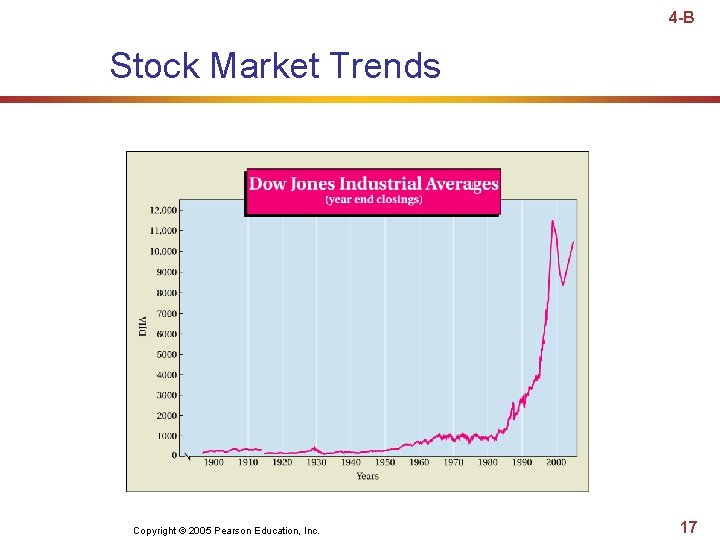
4 -B Stock Market Trends Copyright © 2005 Pearson Education, Inc. 17
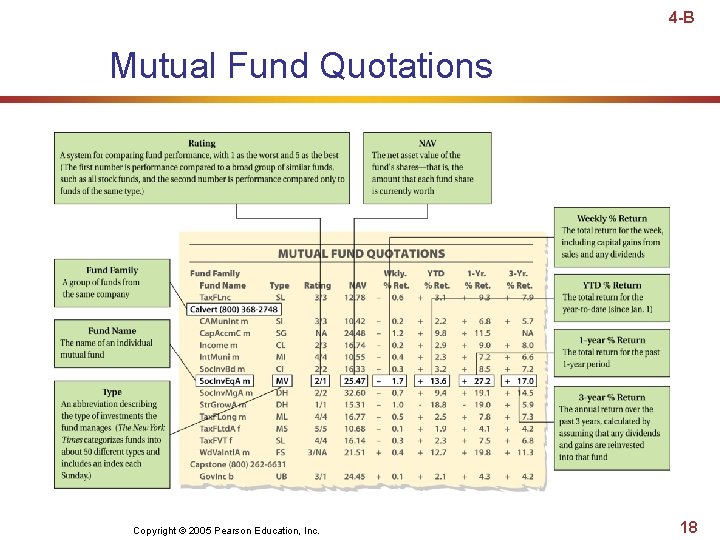
4 -B Mutual Fund Quotations Copyright © 2005 Pearson Education, Inc. 18
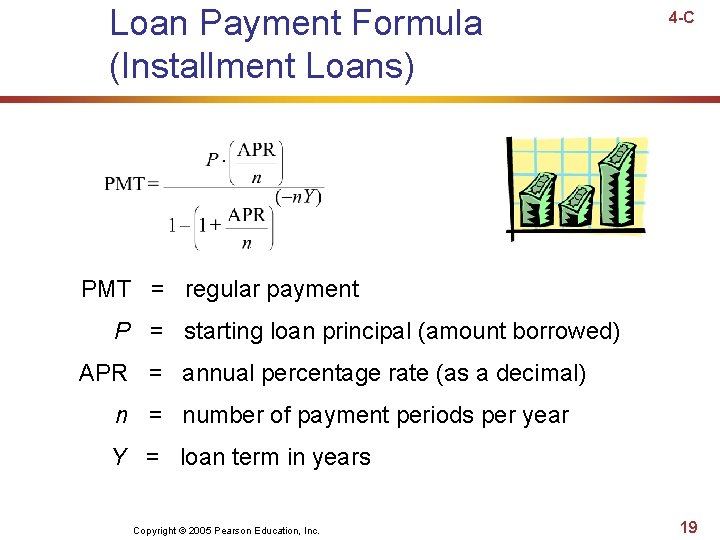
Loan Payment Formula (Installment Loans) 4 -C PMT = regular payment P = starting loan principal (amount borrowed) APR = annual percentage rate (as a decimal) n = number of payment periods per year Y = loan term in years Copyright © 2005 Pearson Education, Inc. 19
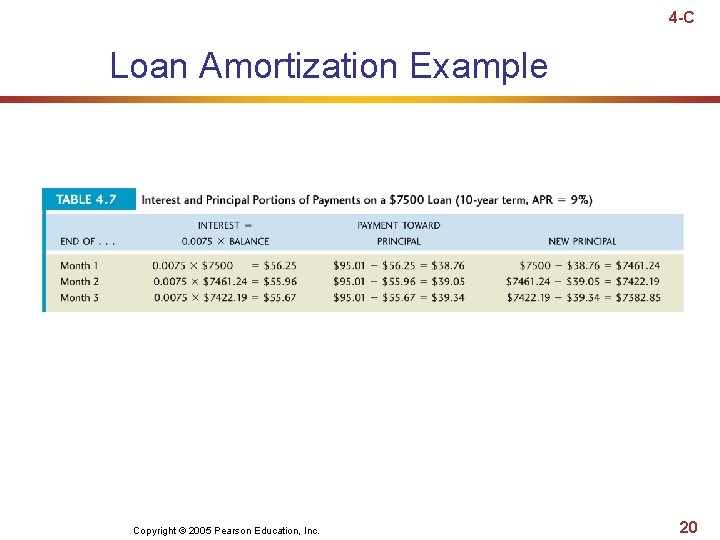
4 -C Loan Amortization Example Copyright © 2005 Pearson Education, Inc. 20
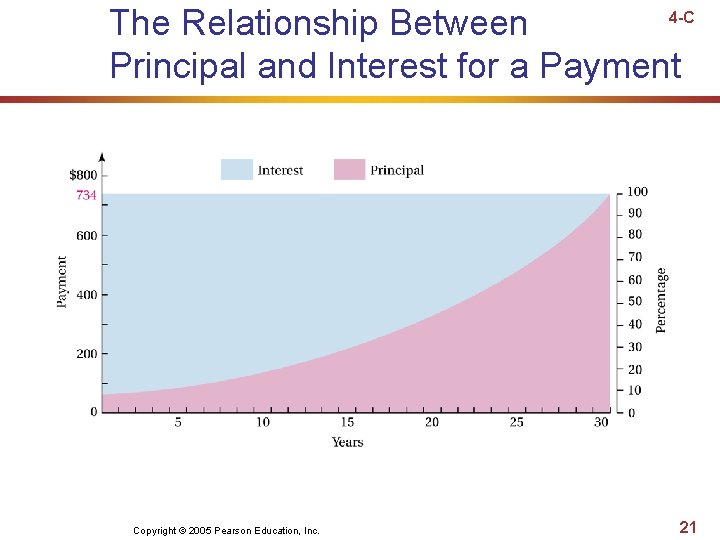
4 -C The Relationship Between Principal and Interest for a Payment Copyright © 2005 Pearson Education, Inc. 21
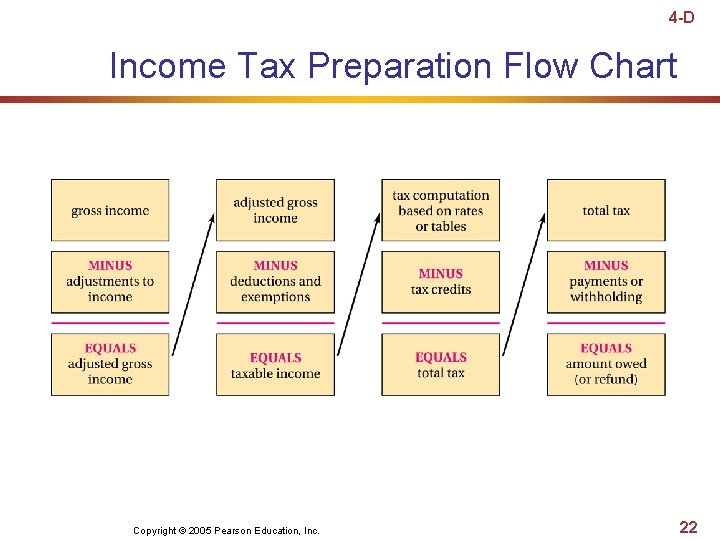
4 -D Income Tax Preparation Flow Chart Copyright © 2005 Pearson Education, Inc. 22
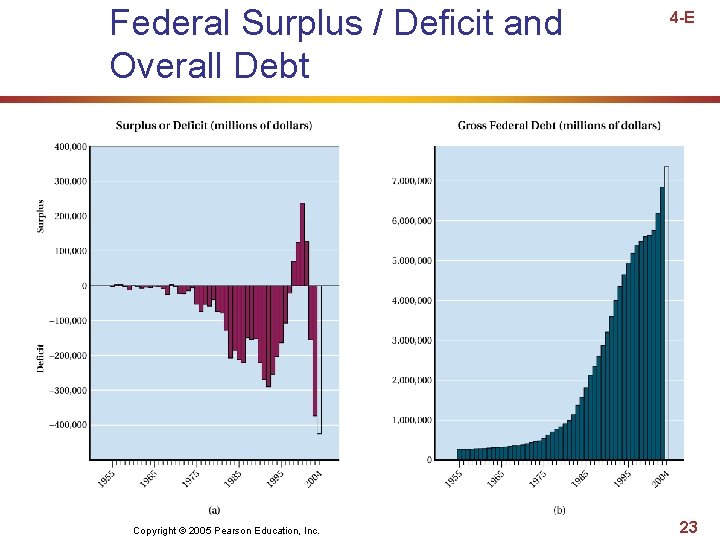
Federal Surplus / Deficit and Overall Debt Copyright © 2005 Pearson Education, Inc. 4 -E 23
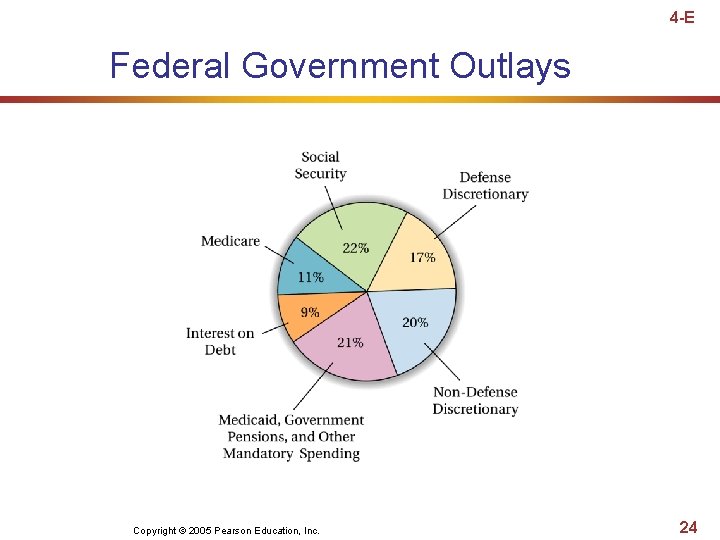
4 -E Federal Government Outlays Copyright © 2005 Pearson Education, Inc. 24