
COOK BYNUM CAPITAL MANAGEMENT LLC In the short
COOK &BYNUM CAPITAL MANAGEMENT, LLC “In the short run, the market is a voting machine, but in the long run it is a weighing machine. ” ─ Benjamin Graham
As the supporting scaffolding was removed following the completion of a Roman arch, the engineer responsible for its construction was required to stand beneath it. This approach ensured that the engineer had a fully vested interest in designing and building the arch with a substantial MARGIN OF SAFETY… 2
Who We Are § Cook & Bynum Capital Management was founded in 2001 – ~$315 million in assets under management – Two primary vehicles: (1) private partnership, (2) mutual fund § Global, concentrated, absolute value investing philosophy – We invest across regions, cap sizes and sectors based on in-depth, fundamental research – Circle of competence is our most important filter for ideas as we focus first on avoiding permanent impairments of capital § We believe in aligning our interests with those of our investors – We invest substantially all of our investable net worth in our funds – As a result, we manage our investors’ money exactly like our own 3
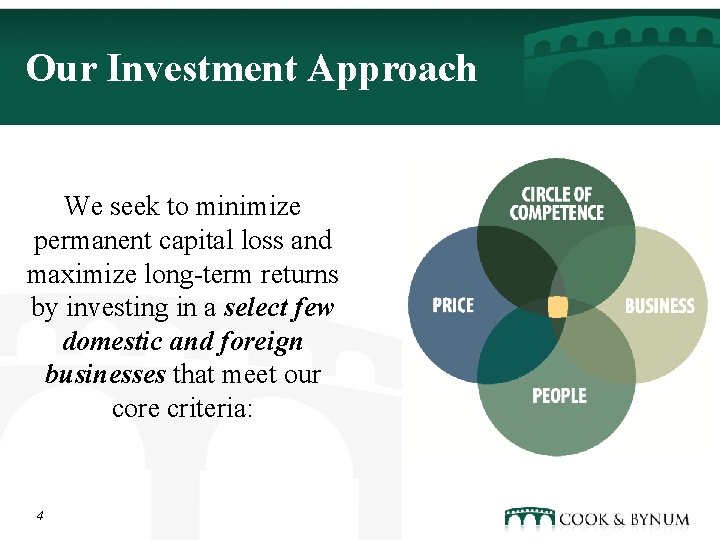
Our Investment Approach We seek to minimize permanent capital loss and maximize long-term returns by investing in a select few domestic and foreign businesses that meet our core criteria: 4
We Remain Strictly Within Our Circle of Competence § Only invest in businesses in which we are capable of understanding the core economics § Be disciplined about what we do and do not know, while working to prudently expand our circle of competence “It ain’t what you don’t know that gets you into trouble. It’s what you know for sure that just ain’t so. ” Mark Twain 5 § Only “compete” when we feel we have a competitive advantage § Always examine the psychological factors at work to avoid fooling ourselves
We Buy Businesses, Not Pieces of Paper § Use fundamental analysis to find good businesses – Only understandable and predictable businesses will be considered – Insist on a conservative balance sheet and accounting approach – Look for high returns on capital “A great business at a fair price is superior to a fair business at a great price. ” Charlie Munger 6 § Look for businesses with high barriers to entry (“moats”) § Insist upon real “owner-earnings, ” which we define as cash flow generated after all interest payments, taxes, working capital needs, and maintenance capital expenditures
We Thoroughly Investigate Management § Businesses must have trustworthy and capable management who think and act like owners – Find managers with whom we would want to be partners in a private endeavor – Prefer executives that invest a substantial portion of their own net worth in the company – An important indicator of management integrity is conservative, easily understood accounting “Associate yourselves only with those people you can be proud of whether they work for you work for them. ” S. Truett Cathy 7 § Evaluate capital allocation decisions by studying what management does with marginal free cash flow (dividends, stock buybacks, or expansion) § Carefully assess managements’ communications to ensure focus is on maximizing long-term shareholder returns rather than tangential issues like current stock price, next quarter’s earnings, growing revenues, etc.
Price Is Imperative: We Conservatively Value Businesses § Convert GAAP to “real” economics – Adjust for maintenance capital expenditures, working capital needs, interest, etc. – Account for stock options, off-balance sheet/pension liabilities, etc. “Confronted with a challenge to distill the secret of sound investment into three words, we venture the motto, ‘Margin of Safety. ’” Ben Graham 8 § Project real owner-earnings into the future and discount them to the present using a reasonable rate § Insist on a margin of safety by paying substantially less than a conservative appraisal
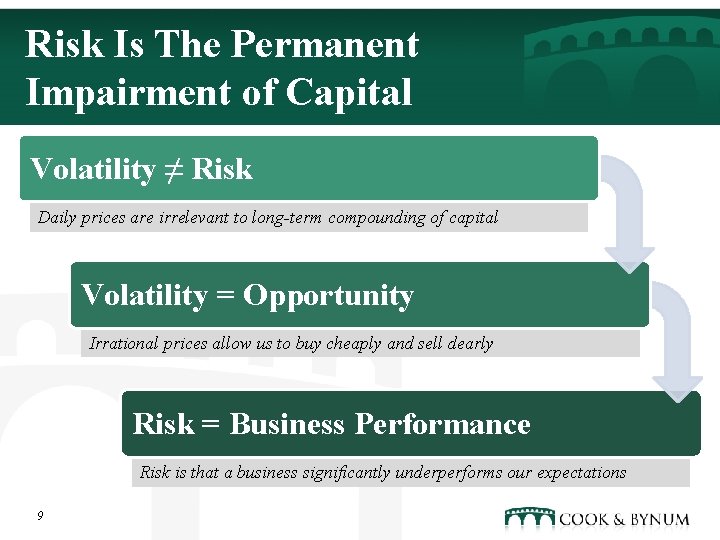
Risk Is The Permanent Impairment of Capital Volatility ≠ Risk Daily prices are irrelevant to long-term compounding of capital Volatility = Opportunity Irrational prices allow us to buy cheaply and sell dearly Risk = Business Performance Risk is that a business significantly underperforms our expectations 9
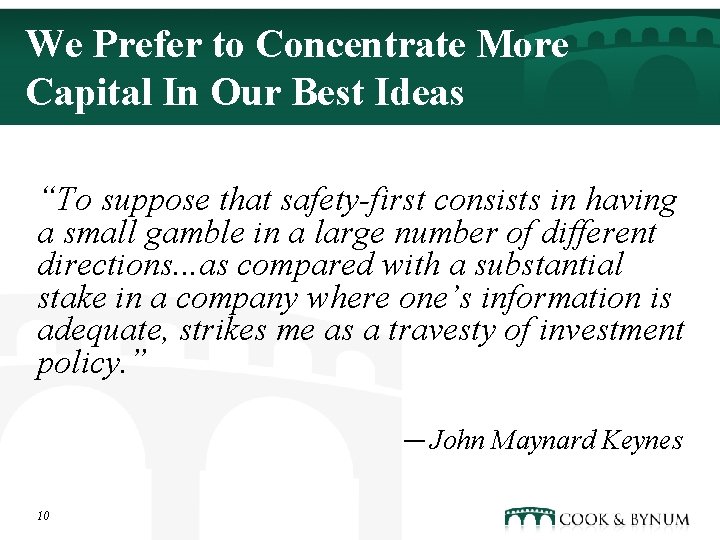
We Prefer to Concentrate More Capital In Our Best Ideas “To suppose that safety-first consists in having a small gamble in a large number of different directions. . . as compared with a substantial stake in a company where one’s information is adequate, strikes me as a travesty of investment policy. ” ─ John Maynard Keynes 10
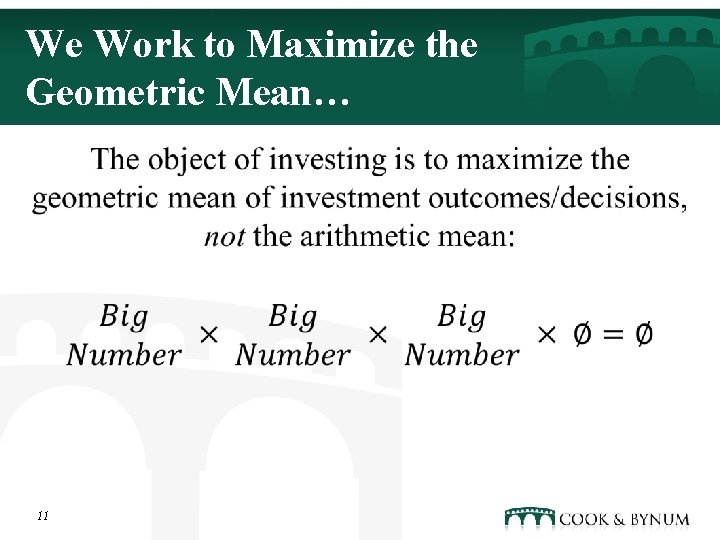
We Work to Maximize the Geometric Mean… § 11
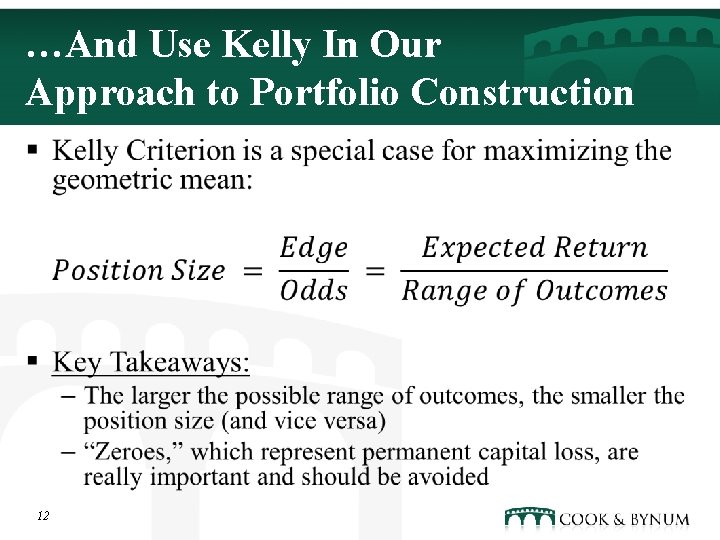
…And Use Kelly In Our Approach to Portfolio Construction § 12
Preference for Long-Term Holds with Clear Sell Discipline § While we favor holding long-term investments, situations arise where investments must and should be sold § A sell decision is based on one of two criteria: 1) We will begin to liquidate an investment when its price approaches our appraised value. An investment reaching our appraisal may have further upside potential, but it will no longer offer an appropriate margin of safety for putting capital at risk. 2) We will sell any investment that has experienced fundamental negative changes in business, management, or return prospects since we invested. Negative developments by themselves do not necessarily trigger the selling of a position, but should a negative event lower our appraisal enough or prevent us from appraising the investment at all, we will sell. 13
Our Approach Tends to Minimize Frictional Costs § Trading – Long-term strategy results in low turnover and consequently low commissions as a % of assets – Lower turnover also reduces the frictional costs of trading, such as execution costs § Operations – We do not pursue “soft dollar” arrangements – Long-term strategy tends to be tax efficient 14
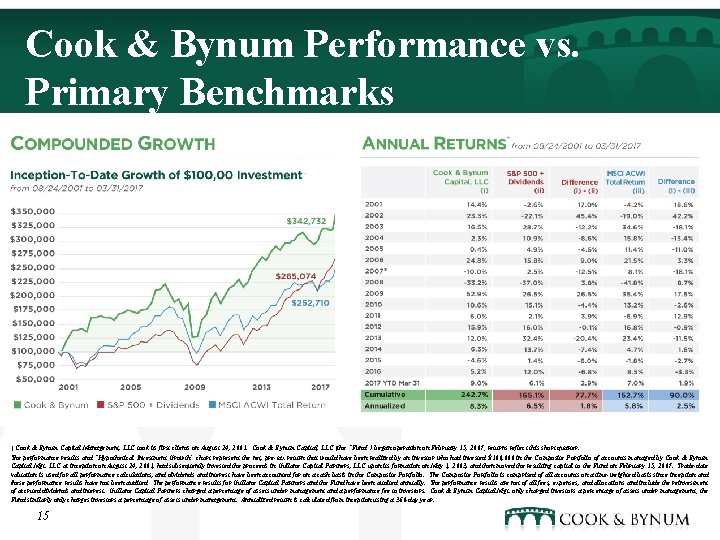
Cook & Bynum Performance vs. Primary Benchmarks † Cook & Bynum Capital Management, LLC took its first clients on August 24, 2001. Cook & Bynum Capital, LLC (the “Fund”) began operation on February 15, 2007; returns reflect this short quarter. The performance results and “Hypothetical Investment Growth” chart represent the net, pre-tax return that would have been realized by an investor who had invested $100, 000 in the Composite Portfolio of accounts managed by Cook & Bynum Capital Mgt. LLC at inception on August 24, 2001, had subsequently invested the proceeds in Gullane Capital Partners, LLC upon its formation on May 1, 2003, and then moved the resulting capital to the Fund on February 15, 2007. Trade-date valuation is used for all performance calculations, and dividends and interest have been accounted for on a cash basis in the Composite Portfolio. The Composite Portfolio is comprised of all accounts on a time-weighted basis sinception and these performance results have not been audited. The performance results for Gullane Capital Partners and the Fund have been audited annually. The performance results are net of all fees, expenses, and allocations and include the reinvestment of accrued dividends and interest. Gullane Capital Partners charged a percentage of assets under management and a performance fee to investors. Cook & Bynum Capital Mgt. only charged investors a percentage of assets under management; the Fund similarly only charges investors a percentage of assets under management. Annualized return is calculated from inception using a 360 -day year. 15
Concentrated, Global Value Investing Track Record of Outperformance Since Firm’s Founding in 2001 Concentrated Portfolio with Willingness to Hold Cash in the Absence of Compelling Investments 16 Consistent, Disciplined Application of Single, Absolute Value Strategy Opportunistic Mandate to Invest Across All Geographies, Cap Sizes and Industries Partners Are Fully Invested Only in Cook & Bynum Investment Vehicles
APPENDIX 17
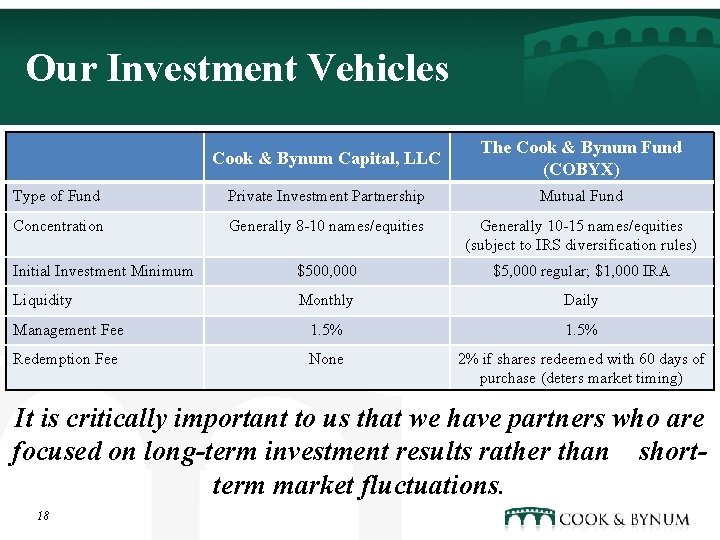
Our Investment Vehicles Cook & Bynum Capital, LLC The Cook & Bynum Fund (COBYX) Type of Fund Private Investment Partnership Mutual Fund Concentration Generally 8 -10 names/equities Generally 10 -15 names/equities (subject to IRS diversification rules) Initial Investment Minimum $500, 000 $5, 000 regular; $1, 000 IRA Liquidity Monthly Daily Management Fee 1. 5% Redemption Fee None 2% if shares redeemed with 60 days of purchase (deters market timing) It is critically important to us that we have partners who are focused on long-term investment results rather than shortterm market fluctuations. 18
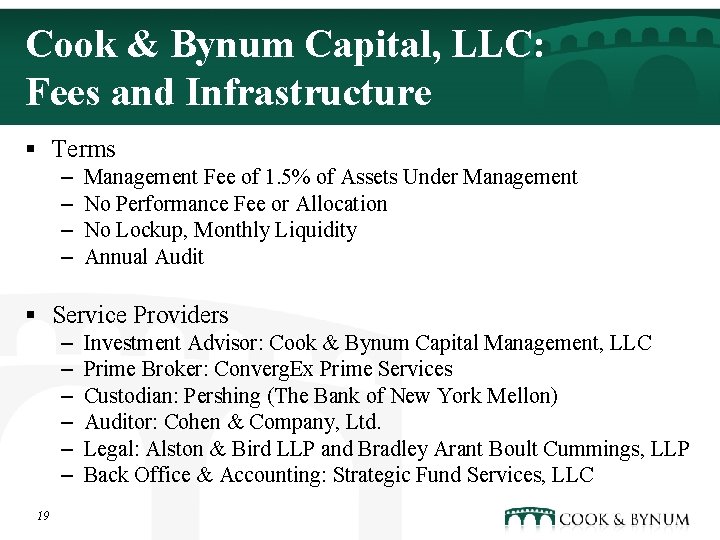
Cook & Bynum Capital, LLC: Fees and Infrastructure § Terms – – Management Fee of 1. 5% of Assets Under Management No Performance Fee or Allocation No Lockup, Monthly Liquidity Annual Audit § Service Providers – – – 19 Investment Advisor: Cook & Bynum Capital Management, LLC Prime Broker: Converg. Ex Prime Services Custodian: Pershing (The Bank of New York Mellon) Auditor: Cohen & Company, Ltd. Legal: Alston & Bird LLP and Bradley Arant Boult Cummings, LLP Back Office & Accounting: Strategic Fund Services, LLC
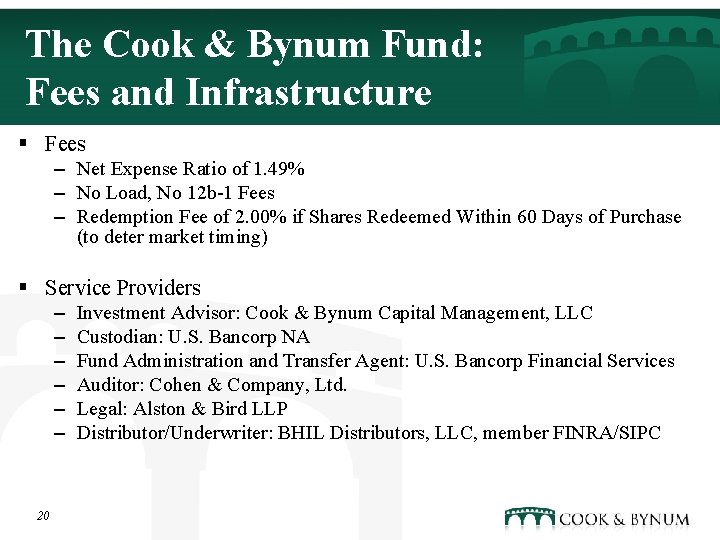
The Cook & Bynum Fund: Fees and Infrastructure § Fees – Net Expense Ratio of 1. 49% – No Load, No 12 b-1 Fees – Redemption Fee of 2. 00% if Shares Redeemed Within 60 Days of Purchase (to deter market timing) § Service Providers – – – 20 Investment Advisor: Cook & Bynum Capital Management, LLC Custodian: U. S. Bancorp NA Fund Administration and Transfer Agent: U. S. Bancorp Financial Services Auditor: Cohen & Company, Ltd. Legal: Alston & Bird LLP Distributor/Underwriter: BHIL Distributors, LLC, member FINRA/SIPC
Portfolio Managers § Richard P. Cook: Richard co-founded Cook & Bynum Capital Management in 2001. Before forming the firm, he worked for Tudor Investment Corporation in Greenwich, Connecticut. Richard attended Hampden-Sydney College where he graduated summa cum laude in three years with a B. S. in Mathematics, Applied Mathematics, and Economics and was a member of Phi Beta Kappa. § J. Dowe Bynum: Dowe co-founded Cook & Bynum Capital Management in 2001. Before forming the firm, he worked as an analyst in the Equities Division of Goldman, Sachs & Co. , Inc. in New York, New York. Dowe attended Princeton University where he graduated with a B. S. E. in Operations Research & Financial Engineering and a Certificate in Finance. Dowe serves on the Glenwood Board of Directors & Advisors and is also a member of the Mountain Brook City Schools Foundation Board. 21
Contact Information Cook & Bynum Capital Management, LLC 2830 Cahaba Road Birmingham, Alabama 35223 Tel: +1(205) 994 -2815 J. Dowe Bynum Principal/Portfolio Manager dowe@cookandbynum. com +1(205) 994 -6635 Direct Richard P. Cook David A. Hobbs Amanda Pridgen Principal/Portfolio Manager richard@cookandbynum. com +1(205) 994 -6611 Direct President david@cookandbynum. com +1(205) 533 -8400 Direct Fund Administration Associate amanda@cookandbynum. com +1(205) 623 -1432 Direct Lynne S. Owens Controller lynne@cookandbynum. com +1(205) 994 -6638 Direct 22 Allison Greenhalgh Office Manager allison@cookandbynum. com +1(205) 994 -6652 Direct
Disclaimer THIS PRESENTATION SHALL NOT CONSTITUTE AN OFFER TO SELL OR THE SOLICITATION OF ANY OFFER TO BUY ANY INTERESTS DESCRIBED HEREIN WHICH MAY BE MADE AT THE TIME A QUALIFIED OFFEREE RECEIVES A CONFIDENTIAL PRIVATE OFFERING MEMORANDUM DESCRIBING THE OFFERING. THESE SECURITIES SHALL NOT BE OFFERED OR SOLD IN ANY JURISDICTION IN WHICH SUCH OFFER, SOLICITATION OR SALE WOULD BE UNLAWFUL UNTIL THE REQUIREMENTS OF THE LAWS OF SUCH JURISDICTION HAVE BEEN SATISFIED. THIS PRESENTATION IS SOLELY FOR INFORMATION PURPOSES, IS CONFIDENTIAL AND MAY NOT BE REPRODUCED OR DISTRIBUTED WITHOUT THE PRIOR WRITTEN CONSENT OF COOK & BYNUM CAPITAL MANAGEMENT, LLC, A DELAWARE LIMITED LIABILITY COMPANY WHICH ACTS AS THE MANAGER OF COOK & BYNUM CAPITAL, LLC (THE “FUND”). THIS PRESENTATION IS QUALIFIED IN ITS ENTIRETY BY THE CONFIDENTIAL PRIVATE OFFERING MEMORANDUM OF THE FUND (THE “OFFERING MEMORANDUM”), WHICH SHOULD BE READ CAREFULLY PRIOR TO ANY INVESTMENT IN THE FUND. THE PURCHASE OF INTERESTS IN THE FUND MAY BE DEEMED TO BE SPECULATIVE INVESTMENT AND IS NOT INTENDED AS A COMPLETE INVESTMENT PROGRAM. INVESTMENT IN THE FUND IS DESIGNED ONLY FOR SOPHISTICATED PERSONS WHO ARE ABLE TO BEAR A SUBSTANTIAL LOSS OF THEIR INVESTMENT IN THE FUND. THERE IS NO ASSURANCE THAT THE FUND’S INVESTMENT OBJECTIVE WILL BE ACHIEVED, AND INVESTMENT RESULTS MAY VARY SUBSTANTIALLY FROM YEAR TO YEAR. AN INVESTMENT IN THE FUND INVOLVES SIGNIFICANT RISKS, WHICH SHOULD BE CAREFULLY EVALUATED BEFORE MAKING AN INVESTMENT IN THE FUND. FOR A DISCUSSION OF THE RISKS ASSOCIATED WITH AN INVESTMENT IN THE FUND, PLEASE REFER TO THE SECTION OF THE OFFERING MEMORANDUM ENTITLED “RISK FACTORS. ” 23
- Slides: 23