
Class 5 Dell Online Case Study NBC 1
Class 5: Dell Online Case Study NBC 1 2008, (c) 2008 Jay A. Smith 1
Region Goods/Service Promotion Project Review n n n n n Product/service: Company/brand: Customer target & size: Promotion message: Place: Channel: Competition: Price: Collaborators: NBC 1 2008, (c) 2008 Jay A. Smith + ADVERTISEMENT Sample 2
Homework: Dell Online Case Issues to Think About (Ps & Cs) Company History and Choices n Industry & Competition n Products n Customer/Market Segments n Pricing n Channel/Operations n Competitive Advantage n Case questions & decisions n NBC 1 2008, (c) 2008 Jay A. Smith 3
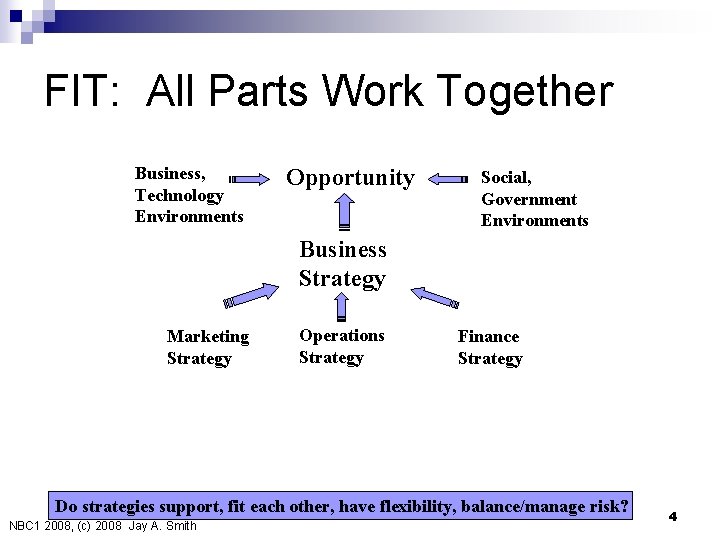
FIT: All Parts Work Together Business, Technology Environments Opportunity Social, Government Environments Business Strategy Marketing Strategy Operations Strategy Finance Strategy Do strategies support, fit each other, have flexibility, balance/manage risk? NBC 1 2008, (c) 2008 Jay A. Smith 4
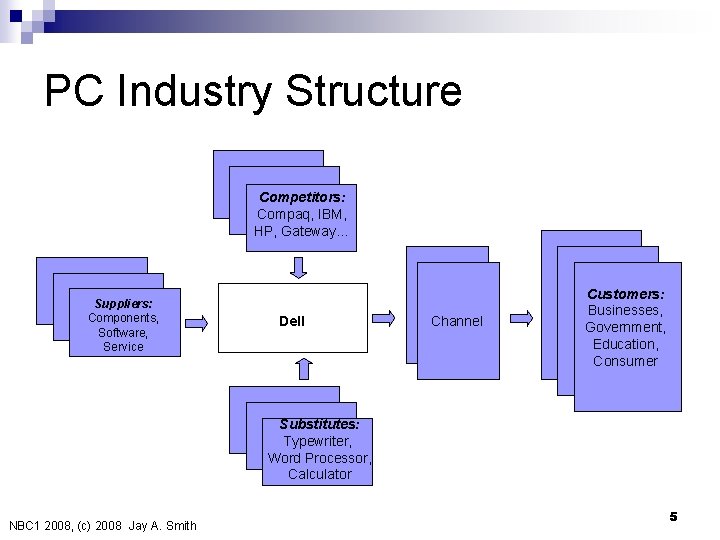
PC Industry Structure Competitors: Compaq, IBM, HP, Gateway… Suppliers: Components, Software, Service Dell Channel Customers: Businesses, Government, Education, Consumer Substitutes: Typewriter, Word Processor, Calculator NBC 1 2008, (c) 2008 Jay A. Smith 5
Dell History n 1983 Part-time Formatting Disks (Michael 18才, left college) ¨ ¨ n n n 1984 Sales $6 million upgrading IBM compatibles 1985 Dell Brand PCs = $70 million 1988 IPO 1990 Sales = $500+ million (IBM 386 delay gap) 1993 Sales = $2. 8 billion – But Net Loss ¨ ¨ n IBM / Apple / Dos. V/ NEC 98 DOS 1 4 GB i. Pod = 6. 2 650 MB CDs = 2, 777 1. 44 MB Floppy Quit the Retail Channel Stopped making laptops until quality improved 1996 Begins Online/Internet Sales NBC 1 2008, (c) 2008 Jay A. Smith 6
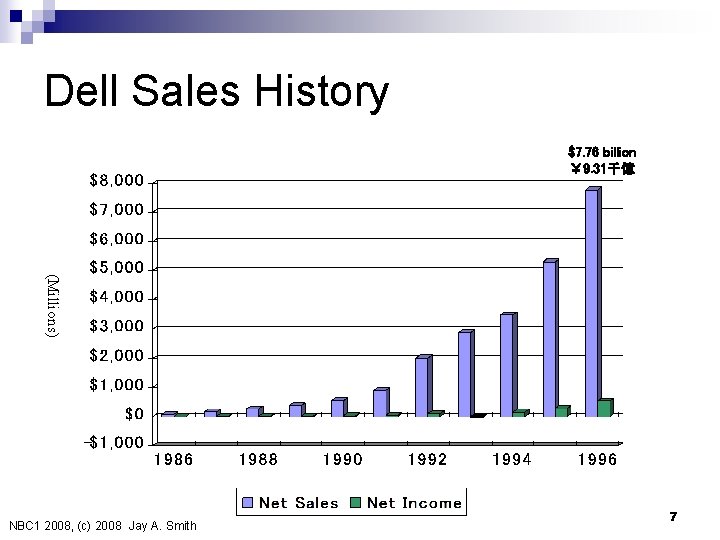
Dell Sales History $7. 76 billion ¥ 9. 31千億 (Millions) NBC 1 2008, (c) 2008 Jay A. Smith 7
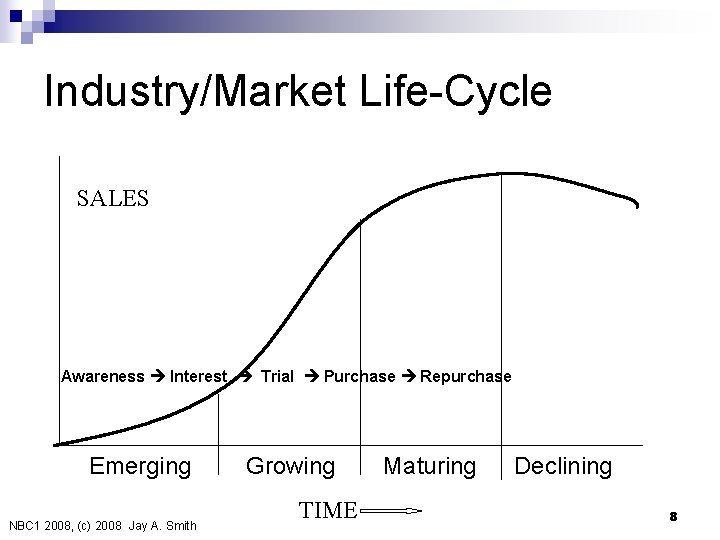
Industry/Market Life-Cycle SALES Awareness Interest Trial Purchase Repurchase Emerging NBC 1 2008, (c) 2008 Jay A. Smith Growing TIME Maturing Declining 8
PC Industry Growing, but Hard Business Highly competitive n Big companies compete at many levels n Pricing/Margin pressure n ¨ Commodity-like business– cost advantage is key ¨ Margins 35%-40% 1991 => 20% in 1996 Cyclical “Feast-or-famine” demand cycles n Strong power of dealers n NBC 1 2008, (c) 2008 Jay A. Smith 9
Signs of Maturing Markets n Home PC Market ¨ ¨ 49% to 32% first time buyers in ’ 95 -96 38 -40% household penetration of PCs Avg. selling price down from $2, 400 to $1, 500 in 9 months Market becoming “bi-polar” n n n Corporate Market Maturing ¨ ¨ ¨ n 33% below $1000 66% above $2, 000 1. 1 PCs per worker in U. S. 0. 8 PCs per worker in W. Europe & Asia But 75 -80% of corporate systems used slower-than-Pentium processors Becoming replacement business NBC 1 2008, (c) 2008 Jay A. Smith 10
1997 U. S. Market Share ($85 Billion) NBC 1 2008, (c) 2008 Jay A. Smith 11
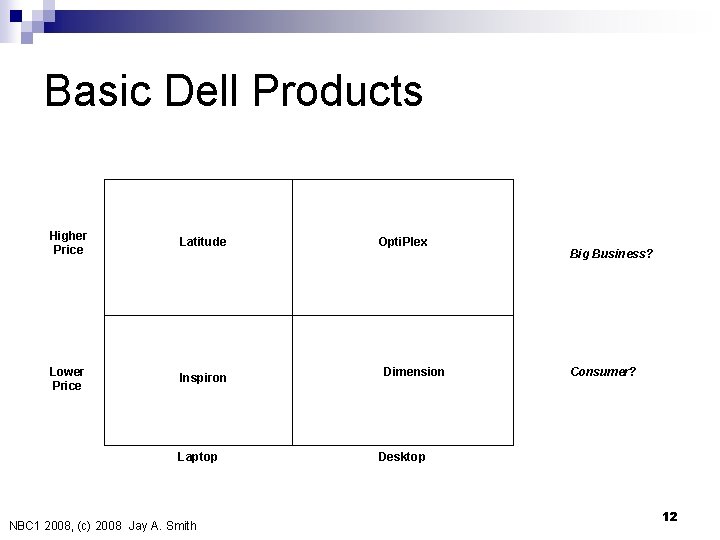
Basic Dell Products Higher Price Latitude Lower Price Inspiron Laptop NBC 1 2008, (c) 2008 Jay A. Smith Opti. Plex Dimension Big Business? Consumer? Desktop 12
A Manufacturer’s Disadvantages n Hardware Only? ¨ Software? ¨ Consulting/solutions provision? ¨ Peripherals? ¨ Service? n Perceived as Manufacturer NBC 1 2008, (c) 2008 Jay A. Smith 13
Dell Business Areas Dell. Direct, Dell. Online - computers n Dell. Plus – preinstall software n Dell. Ware – other software & hardware products n Dell Asset Management – leasing n 3 rd party support network n ¨ Use of Digital Equipment Corp. (DEC) ¨ (DEC acquired by Compaq 1998) NBC 1 2008, (c) 2008 Jay A. Smith 14
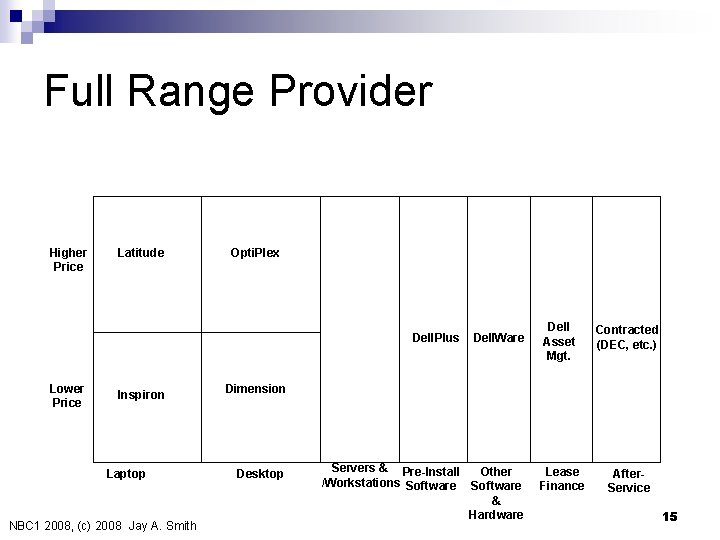
Full Range Provider Higher Price Latitude Opti. Plex Dell. Plus Lower Price Inspiron Laptop NBC 1 2008, (c) 2008 Jay A. Smith Dell. Ware Dell Asset Mgt. Contracted (DEC, etc. ) Lease Finance After. Service Dimension Desktop Servers & Pre-Install Other /Workstations Software & Hardware 15
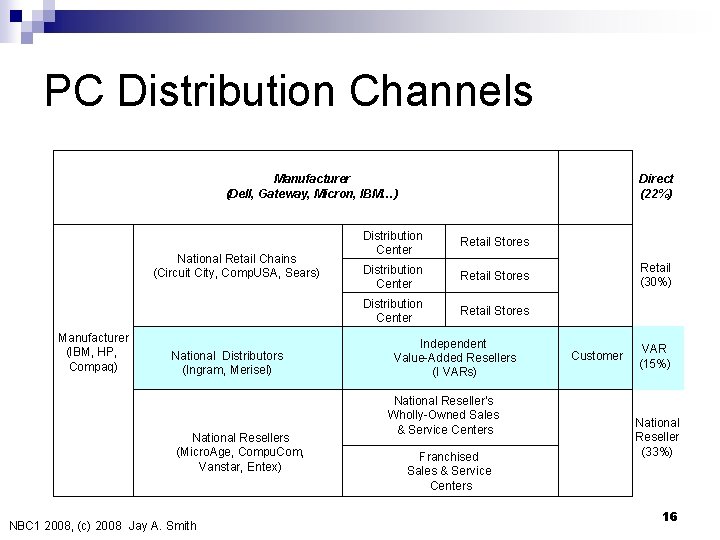
PC Distribution Channels Manufacturer (Dell, Gateway, Micron, IBM…) National Retail Chains (Circuit City, Comp. USA, Sears) Manufacturer (IBM, HP, Compaq) National Distributors (Ingram, Merisel) National Resellers (Micro. Age, Compu. Com, Vanstar, Entex) NBC 1 2008, (c) 2008 Jay A. Smith Direct (22%) Distribution Center Retail Stores Independent Value-Added Resellers (I VARs) National Reseller’s Wholly-Owned Sales & Service Centers Franchised Sales & Service Centers Retail (30%) Customer VAR (15%) National Reseller (33%) 16
Dell Direct Advantages n $150 million on marketing communications (1. 9% of 1996 n Control of channel / No Channel Conflict or Confusion Direct, real-time access to customers n sales) They know exactly the customer (and do market research) ¨ Forecasting and planning advantages sales = f (advertising $) ¨ n n Fresher computers (don’t sit on store shelves, warehouses) Better Cash Flow ¨ ¨ n Faster cash than via dealers Faster cash from transactional customers Manufacturing cost ¨ ¨ Short lead time lowers inventory costs and investment Short lead time lowers parts costs due to downward price trend NBC 1 2008, (c) 2008 Jay A. Smith 17
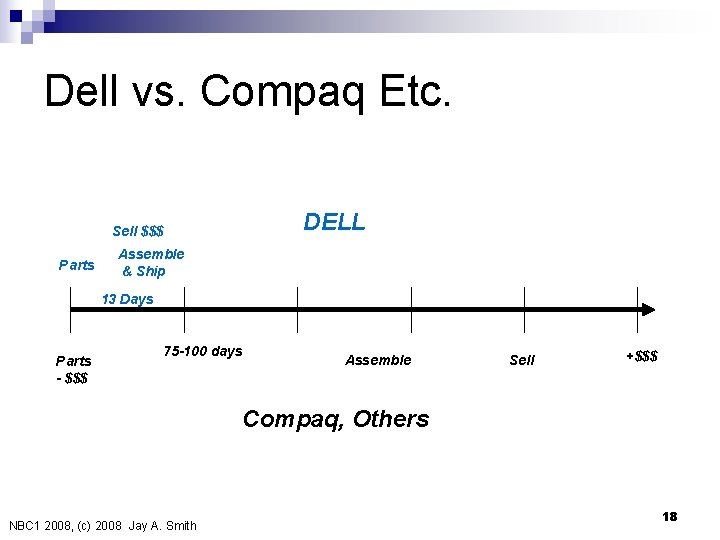
Dell vs. Compaq Etc. Sell $$$ Parts DELL Assemble & Ship 13 Days Parts - $$$ 75 -100 days Assemble Sell +$$$ Compaq, Others NBC 1 2008, (c) 2008 Jay A. Smith 18
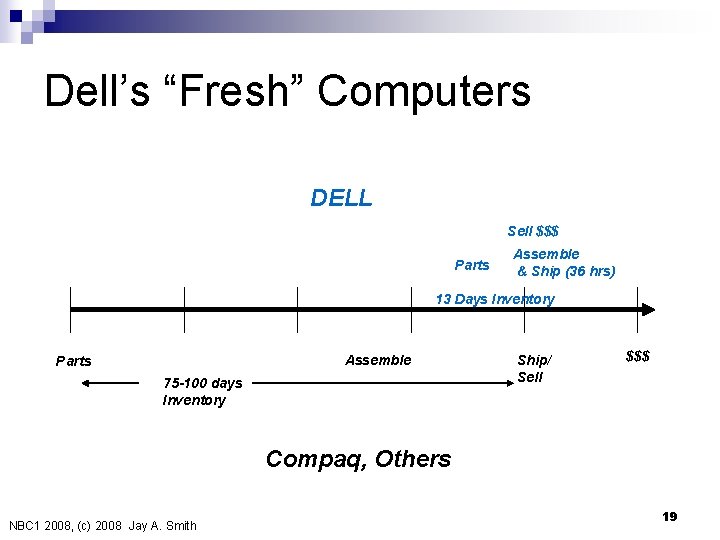
Dell’s “Fresh” Computers DELL Sell $$$ Parts Assemble & Ship (36 hrs) 13 Days Inventory Assemble Parts 75 -100 days Inventory Ship/ Sell $$$ Compaq, Others NBC 1 2008, (c) 2008 Jay A. Smith 19
Why Use Indirect Channels? Market “reach” n “can only reach 30%” VP of Compaq n ¨ Need indirect to reach entire market Is that true? n Does that change over time? n Do you want to reach the entire market? n NBC 1 2008, (c) 2008 Jay A. Smith 20
Dell Customer Segments n By Organization Type ¨ Business/Institutional Business n Government n Education n ¨ Consumer/Home/Individual Sell to “educated consumer” not only on price n With mature market more consumers are “educated” n NBC 1 2008, (c) 2008 Jay A. Smith 21
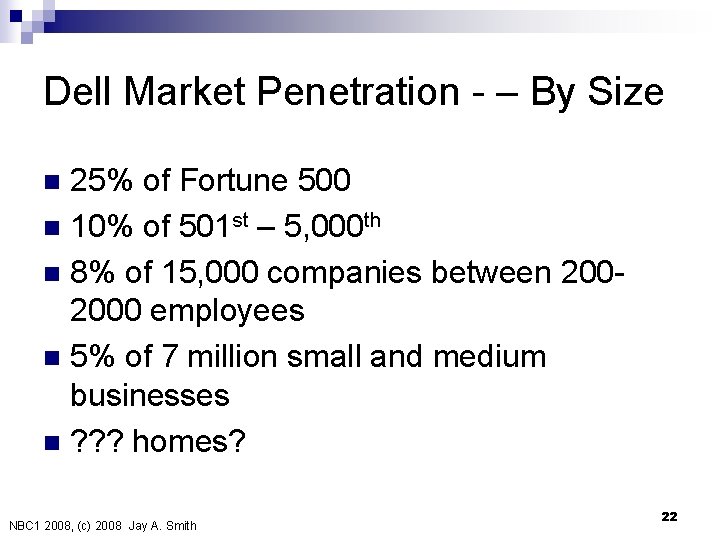
Dell Market Penetration - – By Size 25% of Fortune 500 n 10% of 501 st – 5, 000 th n 8% of 15, 000 companies between 2002000 employees n 5% of 7 million small and medium businesses n ? ? ? homes? n NBC 1 2008, (c) 2008 Jay A. Smith 22
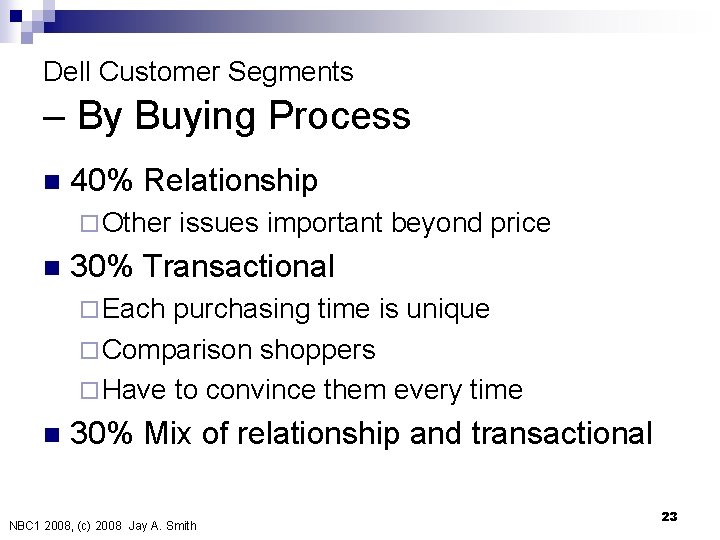
Dell Customer Segments – By Buying Process n 40% Relationship ¨ Other n issues important beyond price 30% Transactional ¨ Each purchasing time is unique ¨ Comparison shoppers ¨ Have to convince them every time n 30% Mix of relationship and transactional NBC 1 2008, (c) 2008 Jay A. Smith 23
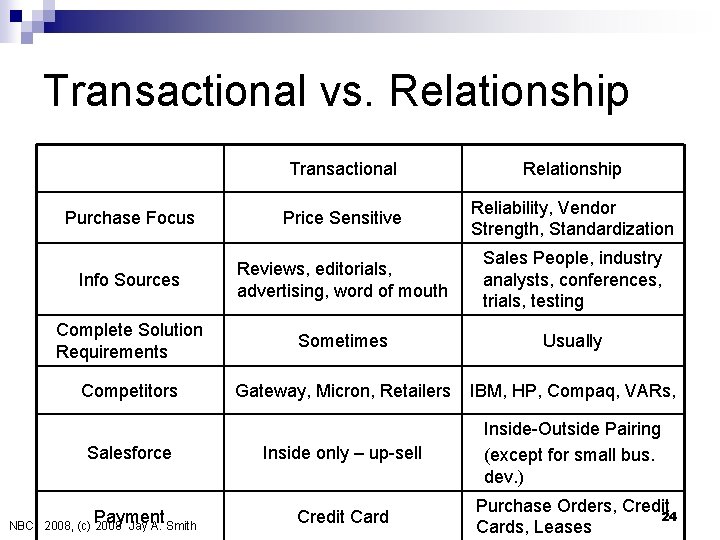
Transactional vs. Relationship Transactional Relationship Purchase Focus Price Sensitive Reliability, Vendor Strength, Standardization Info Sources Reviews, editorials, advertising, word of mouth Sales People, industry analysts, conferences, trials, testing Complete Solution Requirements Sometimes Usually Competitors Gateway, Micron, Retailers IBM, HP, Compaq, VARs, Inside only – up-sell Inside-Outside Pairing (except for small bus. dev. ) Credit Card Purchase Orders, Credit 24 Cards, Leases Salesforce Payment NBC 1 2008, (c) 2008 Jay A. Smith
Dell Sales Force n n Dell Direct – “phone & feet” - inside & outside sales reps Dell Sales force – U. S. 2, 000 in 1997 40% assigned to relationships (40% of business) ¨ 35% assigned to mixed (30% of business) ¨ 25% assigned to transactional (30% of business) ¨ n n Retail Shops --- exited this business Dell Online – Internet “Dell can migrate without upsetting existing channels” ¨ Premier Pages reinforce Relationship business ¨ n n Add value of purchasing control, customers’ procurement process costs in addition to ease-of-access NBC 1 2008, (c) 2008 Jay A. Smith 25
Internet Selling Benefits Self-service transaction (like ATM) n Information service n ¨ Menu n (can configure, select) Reduces number of phone calls NBC 1 2008, (c) 2008 Jay A. Smith 26
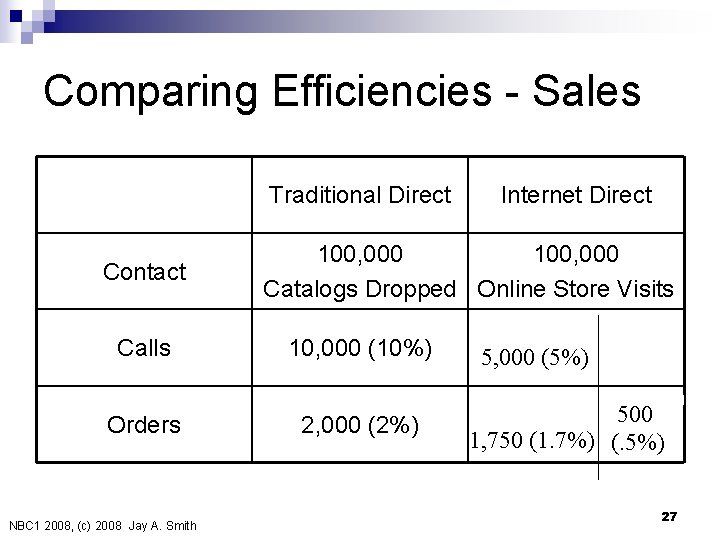
Comparing Efficiencies - Sales Traditional Direct Contact 100, 000 Catalogs Dropped Online Store Visits Calls 10, 000 (10%) Orders 2, 000 (2%) NBC 1 2008, (c) 2008 Jay A. Smith Internet Direct 5, 000 (5%) 500 1, 750 (1. 7%) (. 5%) 27
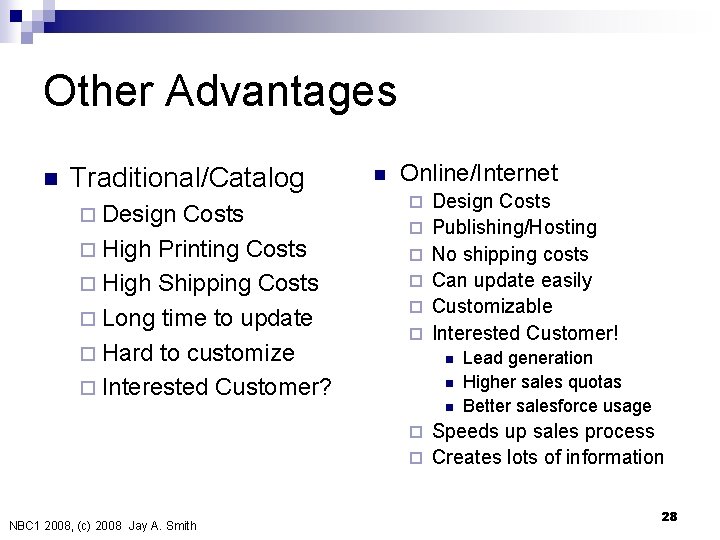
Other Advantages n Traditional/Catalog ¨ Design Costs ¨ High Printing Costs ¨ High Shipping Costs ¨ Long time to update ¨ Hard to customize ¨ Interested Customer? n Online/Internet ¨ ¨ ¨ Design Costs Publishing/Hosting No shipping costs Can update easily Customizable Interested Customer! n n n Lead generation Higher sales quotas Better salesforce usage Speeds up sales process ¨ Creates lots of information ¨ NBC 1 2008, (c) 2008 Jay A. Smith 28
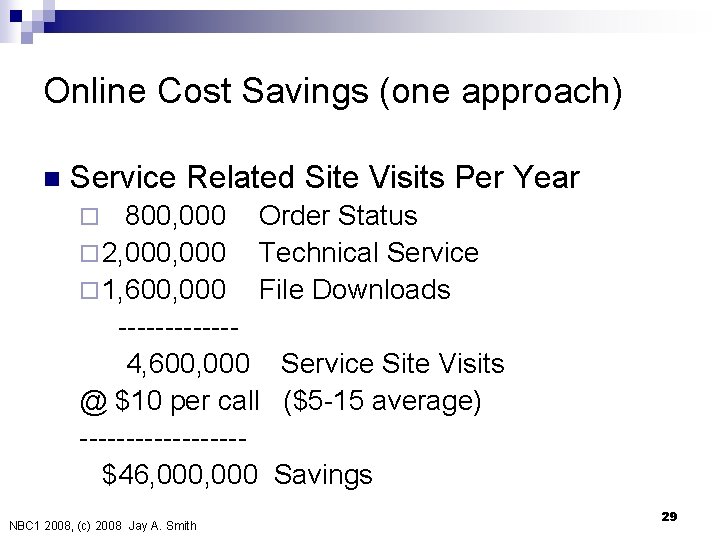
Online Cost Savings (one approach) n Service Related Site Visits Per Year 800, 000 Order Status ¨ 2, 000 Technical Service ¨ 1, 600, 000 File Downloads ------4, 600, 000 Service Site Visits @ $10 per call ($5 -15 average) ---------$46, 000 Savings ¨ NBC 1 2008, (c) 2008 Jay A. Smith 29
Does Online Really Save Costs? ¨ Would ¨ Are people still have called? (easability) tech and sales staff fired? ¨ Does it matter…what other medium saves costs? NBC 1 2008, (c) 2008 Jay A. Smith 30
Key Goals n 50% Online in Next Few Years (Michael Dell) ¨ 50% = $ OO Billion = $ OO Million/Day? ¨ Enough internet/ecommerce users? (reach) n Want to use Dell. com to get more customers, not just those who would buy Dell another way ¨ Table n C: 63 -75% likely would have bought anyway How to turn Dell Online into sustainable competitive advantage (p 1) ¨ Many companies trying to copy Dell model to survive in competitive market NBC 1 2008, (c) 2008 Jay A. Smith 31
Dell Online – Internet “Dell can migrate without upsetting existing channels” n Premier Pages reinforce Relationship business n Add value of purchasing control, customers’ procurement process costs n in addition to ease-of-access n n Does Online conflict with Salesforce? ¨ 56% utilized salesforce (37% +19%) ¨ Experienced reps better able to “upsell” (p 14) NBC 1 2008, (c) 2008 Jay A. Smith 32
Decisions n Should we promote our Internet channel (now) ¨ “will press coverage mean more/new sales? ” ¨ Are we enough ahead to do this yet? n Don’t competitors already know about this, so why worry ¨ PR had some negative internal reaction ¨ Dell. Online also “qualified lead” generator n Should we use Online to go after consumer market ¨ Will n this force down other prices? How to organize Dell Online to both: ¨ Be closer to business units ¨ Still reach 50% of revenues NBC 1 2008, (c) 2008 Jay A. Smith 33
Fit: Strategies & Methods Support Each Other n Direct sales ¨ Problems when n Lower margin n Long lead-time n tried to go through retail channels Manufacturing speed, cost, inventory advantages ¨ “Fresher” computers ¨ Virtual distribution of n Finance: Lowers Cash needs ¨ Cash n displays, software before assembling (made to order) PC market may be maturing, but e-commerce isn’t ¨ “We are now in the consumer market, with a channel consistent w/ Dell Direct” – Michael Dell ¨ (Internet will actually boost total demand…) NBC 1 2008, (c) 2008 Jay A. Smith 34
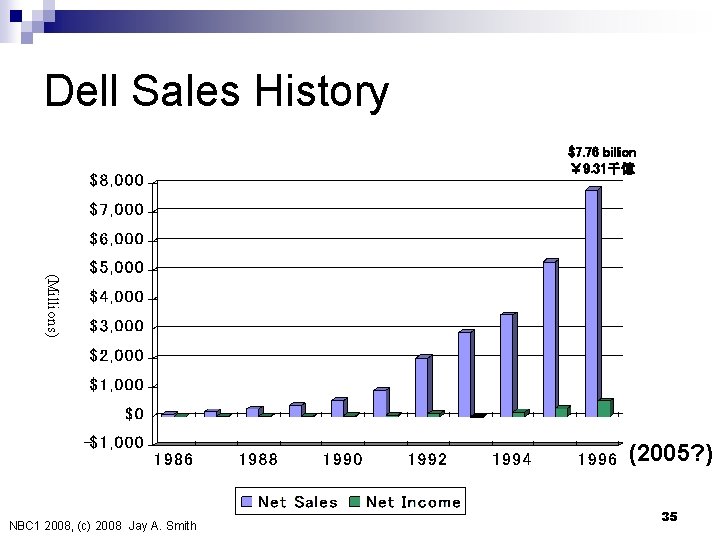
Dell Sales History $7. 76 billion ¥ 9. 31千億 (Millions) (2005? ) NBC 1 2008, (c) 2008 Jay A. Smith 35
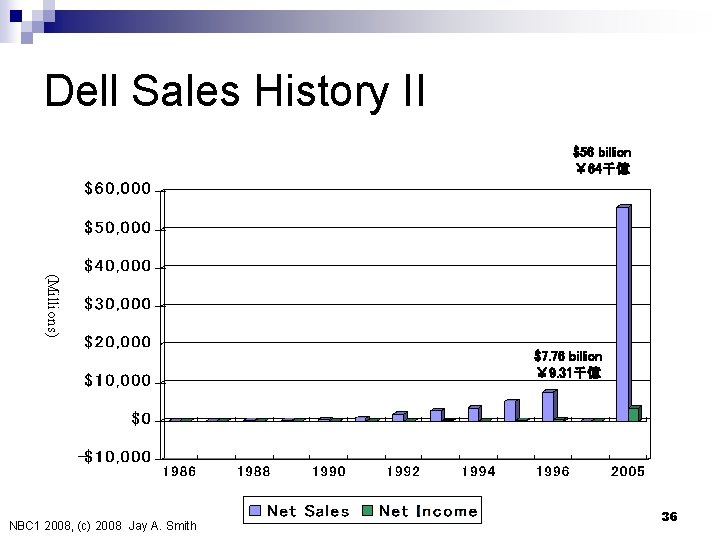
Dell Sales History II $56 billion ¥ 64千億 (Millions) $7. 76 billion ¥ 9. 31千億 NBC 1 2008, (c) 2008 Jay A. Smith 36
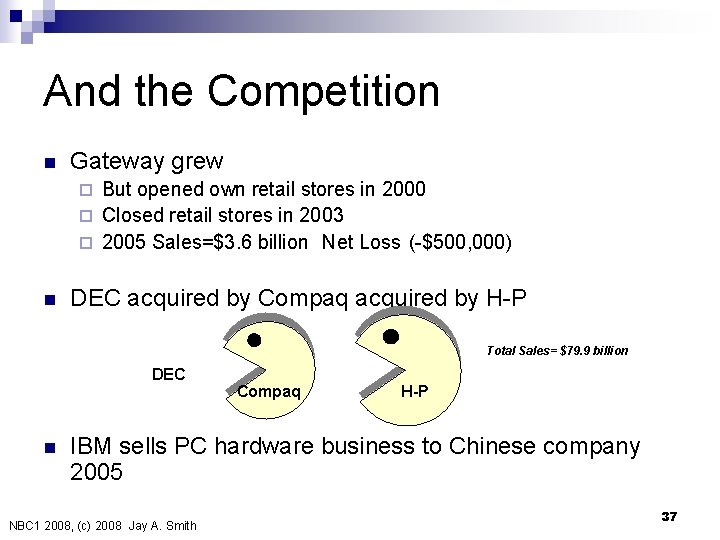
And the Competition n Gateway grew But opened own retail stores in 2000 ¨ Closed retail stores in 2003 ¨ 2005 Sales=$3. 6 billion Net Loss (-$500, 000) ¨ n DEC acquired by Compaq acquired by H-P Total Sales= $79. 9 billion DEC n Compaq H-P IBM sells PC hardware business to Chinese company 2005 NBC 1 2008, (c) 2008 Jay A. Smith 37
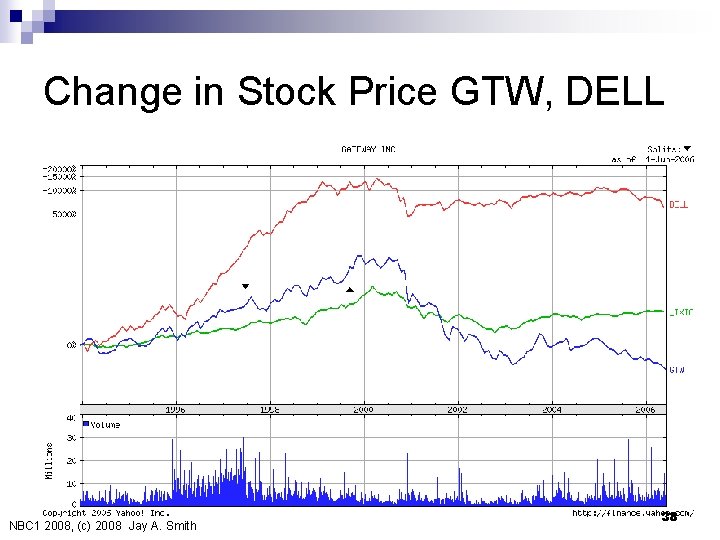
Change in Stock Price GTW, DELL NBC 1 2008, (c) 2008 Jay A. Smith 38
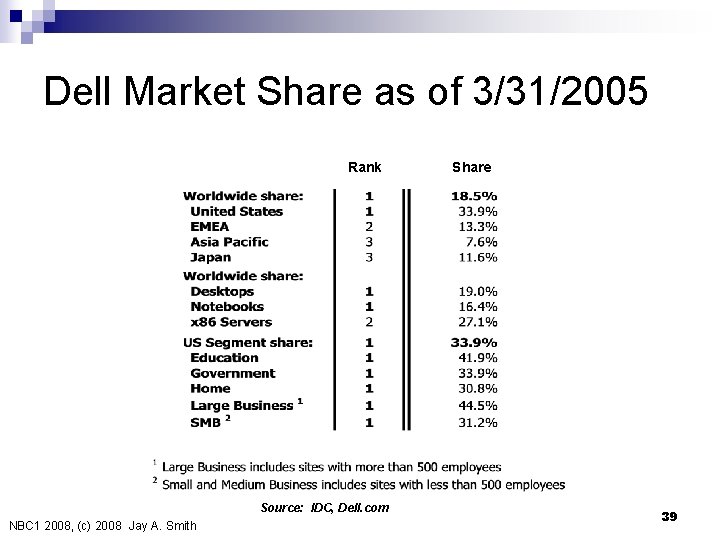
Dell Market Share as of 3/31/2005 Rank Source: IDC, Dell. com NBC 1 2008, (c) 2008 Jay A. Smith Share 39
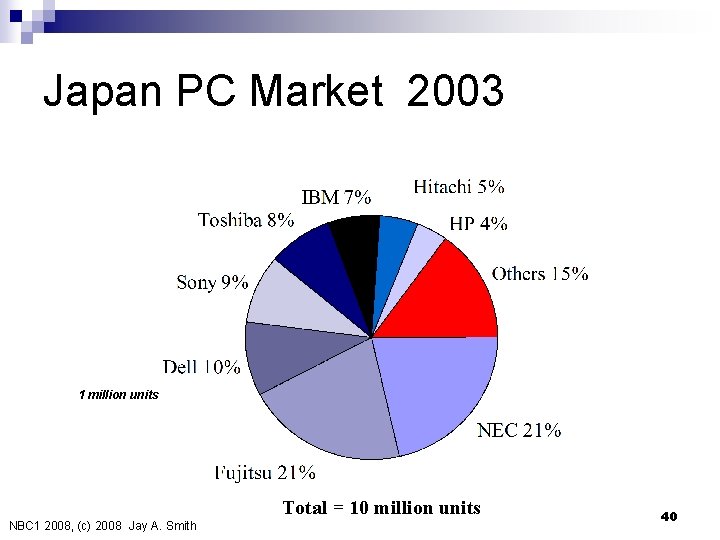
Japan PC Market 2003 1 million units Total = 10 million units NBC 1 2008, (c) 2008 Jay A. Smith 40
- Slides: 41